
 China Electric Vehicle Charging Infrastructure Market | 2026-2036
China Electric Vehicle Charging Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
China Electric Vehicle Charging Infrastructure Market Outlook
The China electric vehicle charging infrastructure landscape is restructuring around a sharp split between premium ultra-fast DC hubs and commodity AC installations. NIO Inc. leverages its battery swap network to anchor premium mobility services in tier-one cities. Star Charge competes on volume deployment across public parking assets. Wanbang New Energy differentiates through utility partnerships that secure grid-scale connection priority.
China electric vehicle charging infrastructure comprises hardware systems, software platforms, and grid integration assets that deliver electrical energy to battery-electric vehicles, with DC fast chargers typically delivering 60-350 kW through liquid-cooled cable assemblies. The primary purpose is to replenish vehicle energy stores while enabling fleet utilization rates and grid load balancing. DC fast chargers command the dominant share of capital deployment as operators prioritize highway corridor coverage and commercial complex penetration. Battery swap stations represent the fastest-growing installation category, driven by NIO's standardization push and taxi fleet adoption. Residential complexes remain the largest volume segment for AC charger installations, though per-unit margins compress amid hardware commoditization.
MIIT's GB/T connector standards and SAMR's quality certification protocols shape product entry requirements, while the National Development and Reform Commission's pricing directives govern electricity tariffs for charging services. Local grid companies under State Grid Corporation enforce interconnection technical reviews that determine project commissioning timelines. Stakeholders must monitor evolving peak-demand pricing mechanisms and battery swap standard harmonization as policy levers that will determine operator profitability and technology commitment paths.
Market Dynamics
China's dual carbon goals are compressing fleet electrification timelines, forcing charging operators to front-load capital deployment ahead of vehicle parc growth while MIIT tightens GB/T interoperability mandates that reshape hardware procurement specifications.
Growth Catalysts
- Fleet electrification mandates:Municipal taxi and logistics operators face binding decarbonization targets under provincial dual carbon implementation plans, accelerating hub deployment at depots and intercity corridors.
- MIIT connector standardization:Revised GB/T protocols for DC fast charging harmonize physical interfaces across domestic manufacturers, reducing stranded asset risk for public network investors.
- Yangtze River Delta density:Shanghai-Suzhou-Hangzhou megacity cluster concentrates passenger EV ownership and commercial fleet turnover, generating utilization rates that justify ultra-fast DC hub economics.
Market Restraints
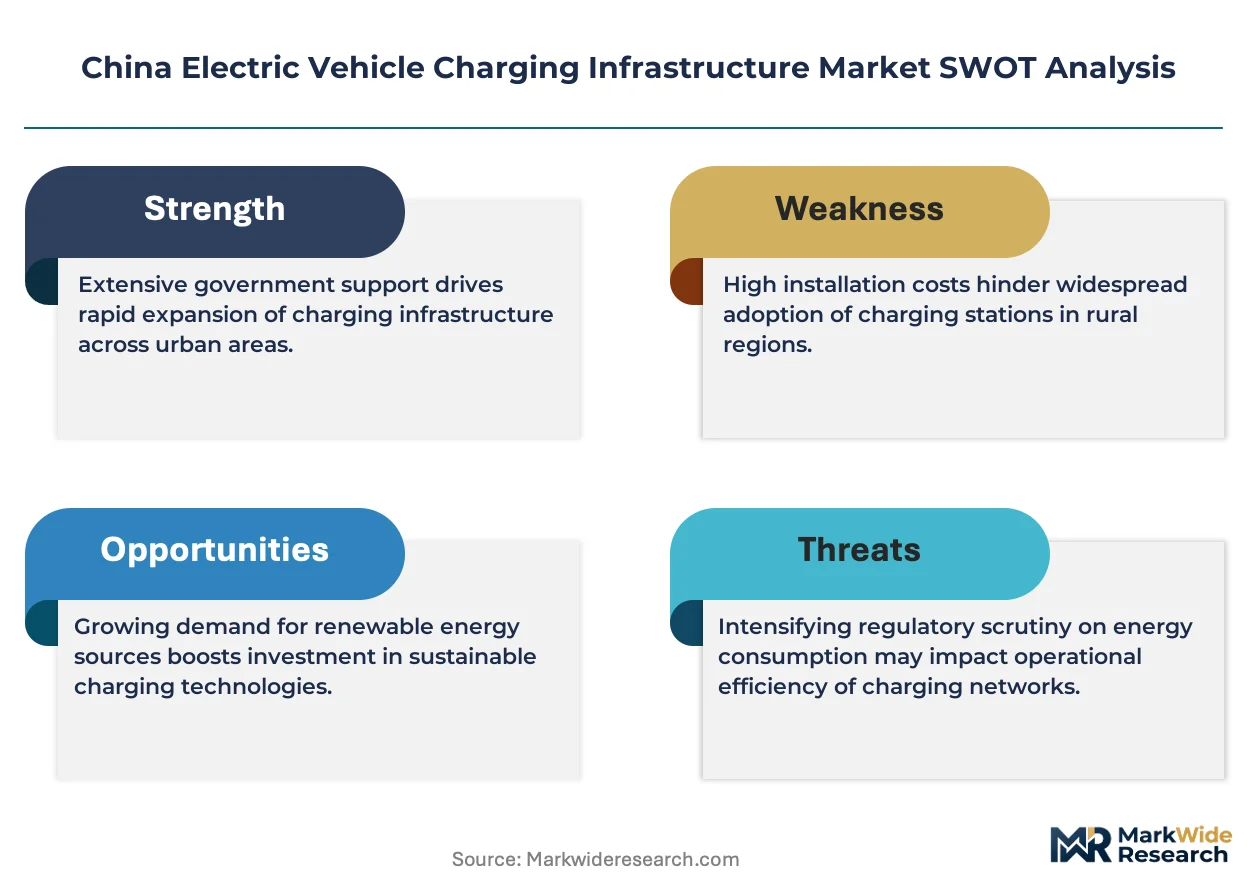
- Grid interconnection queues:State Grid Corporation technical reviews for 350kW+ installations extend commissioning timelines by 8-14 months in high-demand zones, throttling deployment velocity.
- Liquid-cooled cable supply concentration:Domestic specialty cable manufacturers hold captive positions on high-amperage assemblies, creating input cost volatility for DC fast charger integrators.
- Peak-demand tariff structures:National Development and Reform Commission time-of-use electricity pricing compresses operator margins during high-utilization evening windows when fleet charging concentrates.
Strategic Opportunities
- Western China corridor expansion:Chengdu-Chongqing-Guizhou triangle shows 40% lower charging point density per EV than eastern provinces, offering first-mover land-banking advantages for highway corridor operators.
- Battery swap-taxi integration:Shenzhen and Guangzhou municipal procurement specifications now prioritize swappable-battery taxi fleets, creating dedicated station deployment contracts with guaranteed utilization floors.
- V2G aggregation contracts:Grid-scale demand response pilots in Jiangsu province compensate charging hub operators for bi-directional power services, opening revenue stacking beyond per-kWh margins.
Industry Challenges
- Power electronics talent scarcity:Domestic universities produce insufficient SiC inverter and thermal management specialists to match deployment targets, forcing operators to poach from automotive OEM engineering centers.
- Residential AC certification delays:SAMR quality certification protocols for home charger installations require 90-120 day testing cycles that mismatch property developer construction timelines, creating installation backlogs in new build complexes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Electric Vehicle Charging Infrastructure Market |
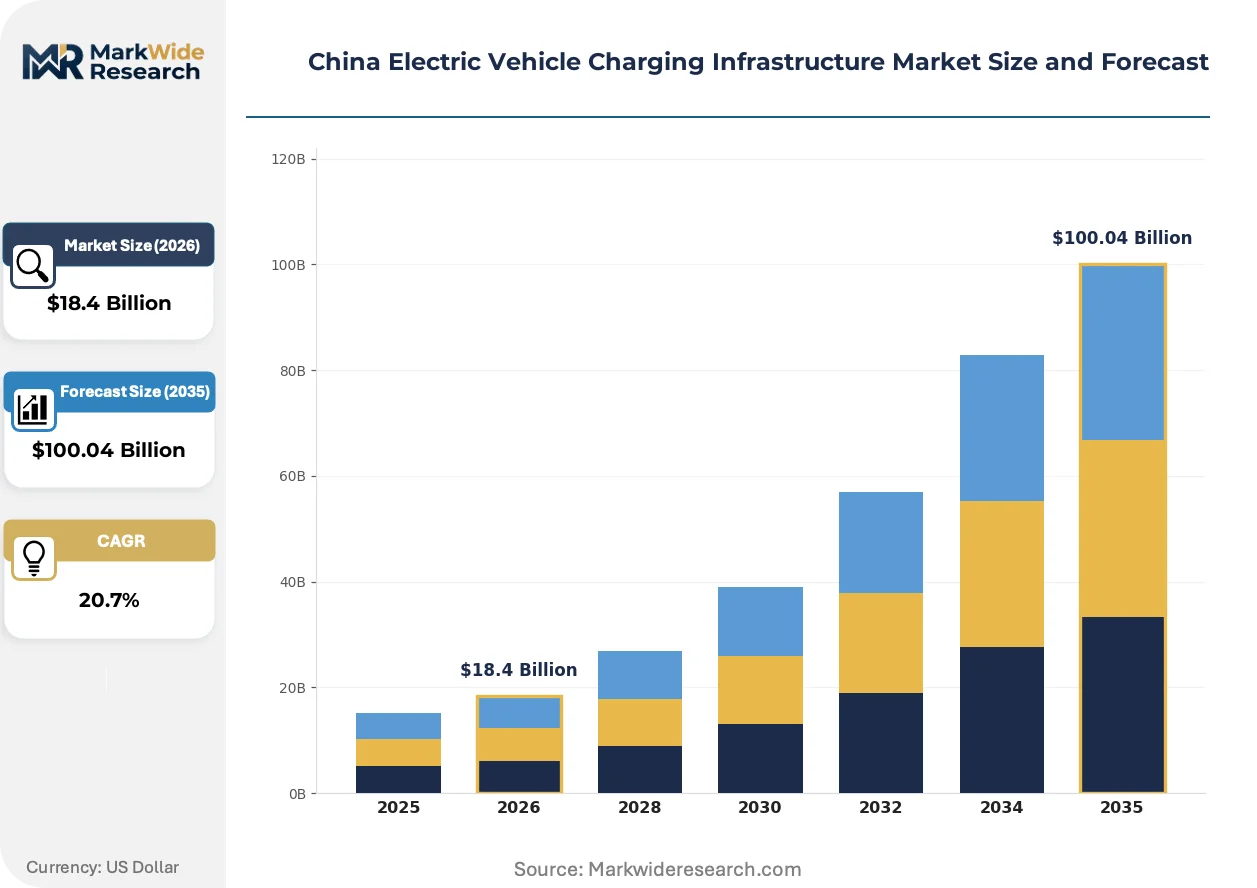
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $100.04 Billion |
| CAGR (2026 – 2036) | 20.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charger Type: AC Chargers, DC Fast Chargers, Wireless Chargers, Battery Swap Stations Installation Setting: Residential Complexes, Commercial Complexes, Public Parking, Fleet Depots, Highway Stations Operator Type: Utility Companies, Independent Service Providers, Automobile OEMs, Fleet Operators Payment Model: Subscription-based, Pay-per-use, Membership, Free Charging Zones |
| Companies Covered | NIO Inc., Anari, Star Charge, Qingdao TGOOD Electric, Wanbang New Energy, TGOOD, XCharge, Teltocharge, BYD Auto, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Electric Vehicle Charging Infrastructure Market Strategic Shifts
Liquid-cooled power electronics and dynamic load management software are converging to redefine charging asset economics, while regulatory pressure on grid integration tightens technical specifications across the installation base.
Silicon carbide (SiC) power modules are replacing IGBT assemblies in 350kW+ DC fast chargers, cutting conversion losses and enabling compact footprint designs. Tier-one charging hub operators are specifying SiC-based rectifiers for all new highway corridor installations. This semiconductor transition is modularizing charger architecture, allowing field-replaceable power blocks that extend asset life and reduce maintenance downtime.
MIIT's 2024 amendments to GB/T 18487.3 impose stricter electromagnetic compatibility testing and communication protocol verification for all new charging equipment certifications. The regulatory tightening is disqualifying smaller hardware assemblers lacking in-house EMC testing facilities. Premium charging network operators are responding by consolidating procurement around vertically integrated manufacturers with captive certification laboratories.
Fleet managers are unbundling charging infrastructure from vehicle procurement, shifting from captive depot builds to third-party hub access contracts with guaranteed uptime SLAs. Logistics operators in the Yangtze River Delta are leading this transition, trading capital ownership for operational flexibility. The procurement model evolution is most visible among express delivery fleets where route unpredictability makes fixed asset commitments uneconomical.
China Electric Vehicle Charging Infrastructure Market Segmentation
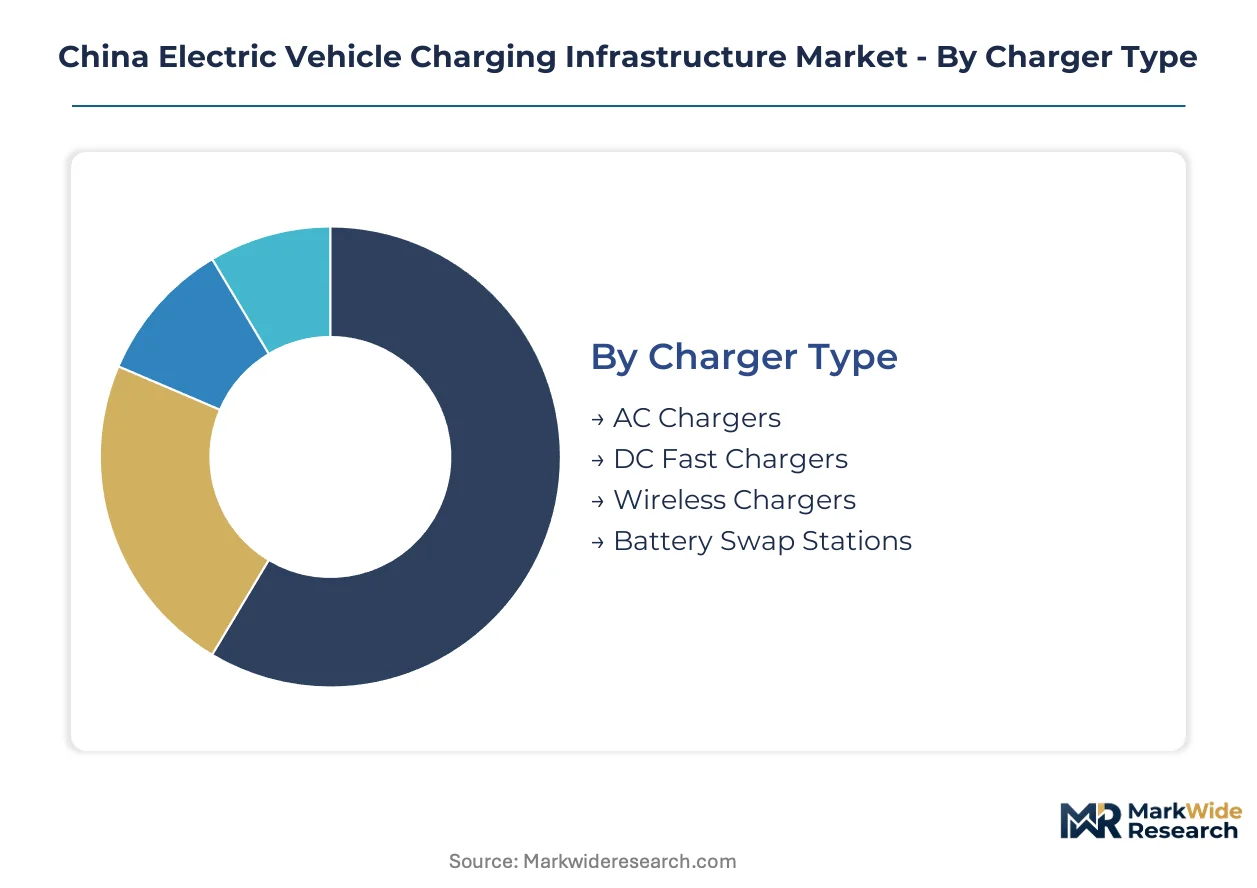
Segmentation reveals how capital allocation priorities split between hardware commoditization and service differentiation in China's charging infrastructure buildout. Charger type determines power electronics complexity, while installation setting dictates grid interconnection economics and utilization rate profiles.
Charger Type:
Standardization pressures from MIIT's GB/T protocols compress differentiation at the low-power end while ultra-fast specifications enable premium positioning.
- AC Chargers:These units deliver 7-22 kW through onboard vehicle rectifiers, dominating residential complex installations where overnight dwell times accommodate slower replenishment cycles. Demand concentrates in tier-two and tier-three city housing developments under municipal new-build EV-readiness mandates, though per-unit hardware margins collapse below 15% amid supplier fragmentation.
- DC Fast Chargers:Direct current systems bypass onboard converters to pump 60-350 kW through liquid-cooled cable assemblies, anchoring highway corridor networks and commercial hub strategies. The Yangtze River Delta megacity cluster absorbs the dominant share of 350kW+ deployments as fleet operators prioritize depot charging for electric logistics vehicles with high daily utilization requirements.
- Wireless Chargers:Inductive pad systems eliminate connector wear but suffer 10-15% efficiency losses that disqualify highway applications; limited deployment concentrates in premium residential valet parking and autonomous vehicle test zones.
- Battery Swap Stations:Automated exchange systems replace depleted packs with charged units in under five minutes, gaining traction in Shenzhen and Guangzhou taxi fleets where municipal procurement specifications now mandate swappable architectures.
Most installed capacity flows through DC Fast Chargers. Expansion is steepest in Battery Swap Stations.
Installation Setting:
Site selection determines grid connection priority queues and land-use permitting complexity across China's provincial regulatory patchwork.
- Residential Complexes:Underground parking retrofits and new-build pre-wiring dominate volume deployment under Ministry of Housing and Urban-Rural Development EV-readiness guidelines, though SAMR certification delays create 90-120 day installation backlogs that frustrate property developers.
- Commercial Complexes:Shopping mall and office tower installations leverage existing transformer capacity for 60-120 kW DC hubs that capture dwell-time charging revenue; State Grid Corporation interconnection reviews extend 8-14 months for 350kW+ upgrades in Shanghai and Suzhou high-demand zones.
- Public Parking:Municipal-owned surface lots and structured garages host commodity AC and mid-power DC assets with utilitarian uptime requirements; utilization rates struggle below 15% in tier-three cities with sparse EV penetration.
- Fleet Depots:Captive charging for logistics, taxi, and bus operators demands guaranteed power availability and dynamic load management software to avoid demand charge penalties; express delivery fleets in Hangzhou are unbundling from ownership to third-party hub access contracts.
- Highway Stations:Corridor coverage mandates from National Development and Reform Commission infrastructure plans prioritize 350kW+ liquid-cooled hubs at 50-kilometer intervals along G2 Beijing-Shanghai and G15 Shenyang-Haikou expressways.
Capital deployment concentrates in Commercial Complexes. Steepest expansion trajectory belongs to Fleet Depots.
Operator Type:
Market structure fragments across state-backed incumbents, private capital-backed specialists, and automotive manufacturer captive networks with divergent return hurdles.
- Utility Companies:State Grid Corporation and Southern Power Grid dominate interconnection infrastructure and direct-operated highway corridor assets, leveraging balance sheet capacity for 10-15 year payback horizons on ultra-fast hub investments.
- Independent Service Providers:Venture-funded operators like Star Charge compete on volume deployment across public parking assets, aggregating utilization across fragmented real estate relationships to justify hardware capital intensity.
- Automobile OEMs:NIO Inc. anchors premium mobility services through proprietary battery swap networks in tier-one cities, while BYD and Tesla deploy destination charging at dealerships and partner retail locations to reinforce vehicle purchase decisions.
- Fleet Operators:Logistics and taxi companies are retreating from captive depot builds, outsourcing charging infrastructure to third-party providers with guaranteed uptime SLAs that transfer utilization risk.
Utility Companies control interconnection gatekeeping. Independent Service Providers are gaining share fastest.
Payment Model:
Revenue capture mechanisms split between predictable subscription cash flows and transactional per-use pricing with volatile utilization exposure.
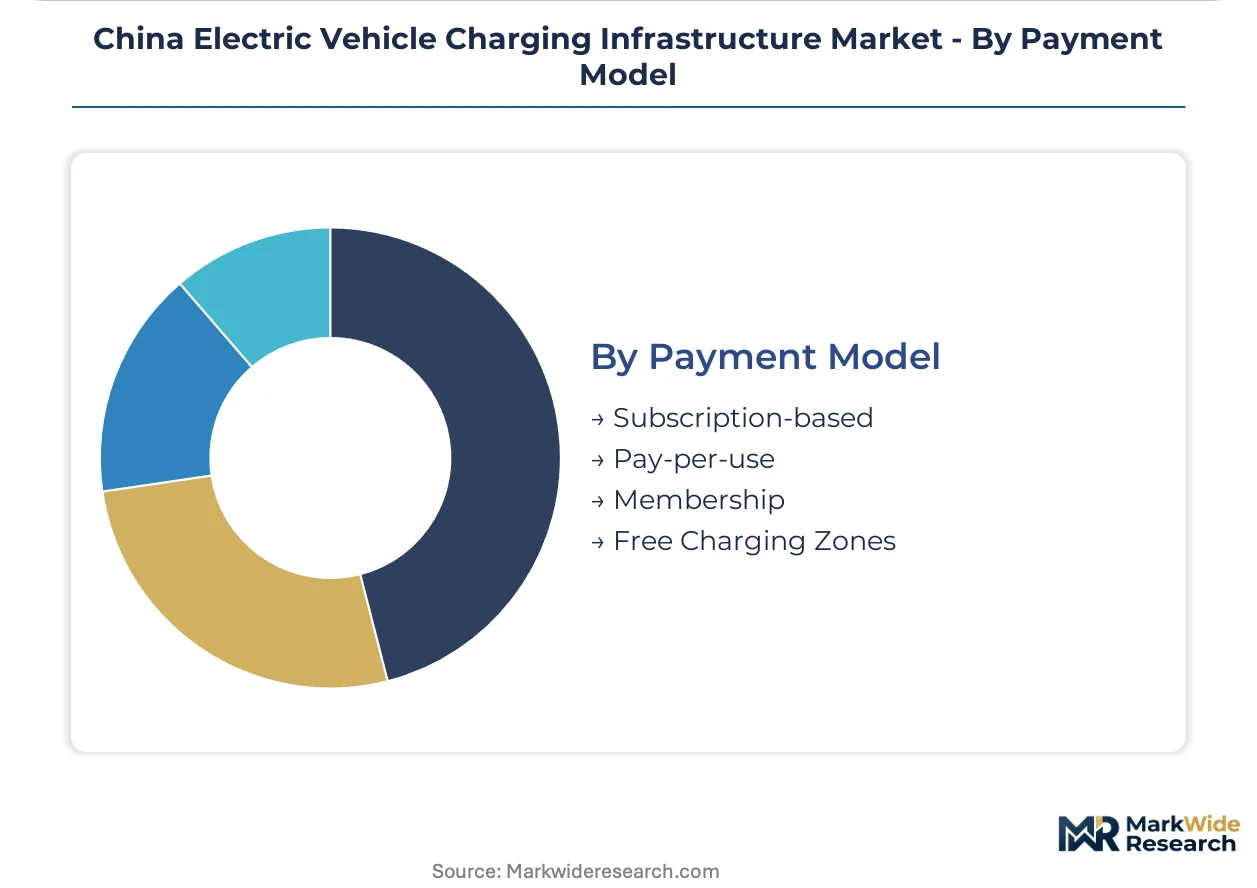
- Subscription-based:Monthly flat-rate plans with unlimited charging sessions attract high-mileage ride-hail and delivery drivers in Guangzhou and Shenzhen, transferring utilization volatility risk to operators.
- Pay-per-use:Per-kWh pricing with time-of-use adjustments dominates public network transactions, compressing margins during evening peak windows when National Development and Reform Commission tariff structures spike electricity costs.
- Membership:Annual fee models with discounted session rates lock in customer loyalty for charging hub operators competing against adjacent network density.
- Free Charging Zones:Complimentary charging bundled with retail purchases or vehicle leases absorbs customer acquisition costs into broader unit economics, prevalent in NIO's battery swap network and luxury mall partnerships.
Transaction volume concentrates in Pay-per-use. Subscription-based models are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power electronics engineering talent clusters anchor charging infrastructure deployment across China's provincial manufacturing belts. Grid interconnection priority queues and municipal dual carbon implementation timelines determine regional buildout velocity. Provincial regulators enforce divergent land-use permitting standards that fragment operator expansion strategies.
Yangtze River Delta
Shanghai-Suzhou-Hangzhou megacity cluster concentrates 350kW+ ultra-fast DC hub deployment for electric logistics fleets. MIIT's GB/T 18487.3 certification requirements tighten fastest in Jiangsu province testing facilities. State Grid Corporation technical reviews in Suzhou industrial zones extend 8-14 months for highway corridor upgrades.
Pearl River Delta
Shenzhen and Guangzhou municipal taxi procurement specifications mandate swappable-battery architectures, accelerating battery swap station contracts. SAMR quality certification protocols for residential AC installations create 90-120 day backlogs across Guangdong province. Dongguan electronics manufacturing corridors supply liquid-cooled cable assemblies for DC fast charger integrators.
Beijing-Tianjin-Hebei
Capital region fleet electrification mandates compress depot charging timelines for logistics operators under provincial dual carbon plans. National Development and Reform Commission highway corridor coverage mandates prioritize G2 Beijing-Shanghai expressway hub spacing at 50-kilometer intervals. Tianjin port electrification drives maritime fleet charging demand at container terminal depots.
Sichuan-Chongqing
Chengdu-Chongqing-Guizhou triangle exhibits 40% lower charging point density per EV than eastern provinces, offering land-banking advantages for first-mover highway operators. Western China grid interconnection queues move faster than coastal high-demand zones. Chongqing automotive manufacturing clusters generate captive fleet charging demand from local OEM vehicle output.
Shandong Peninsula
Qingdao and Jinan industrial zones host specialty cable manufacturers holding captive positions on high-amperage assemblies for DC fast charger production. Provincial grid companies under State Grid Corporation enforce divergent peak-demand tariff structures that compress operator margins during evening fleet charging windows. Yantai port logistics electrification drives intermodal depot hub deployment.
China Electric Vehicle Charging Infrastructure Market Competitive Environment
Top-tier vendors anchor ultra-fast DC highway corridor networks and proprietary battery swap ecosystems, while mid-tier operators compete on volume deployment across public parking assets. The market structure fragments across state-backed utility incumbents, venture-funded independent specialists, and automotive OEM captive networks with divergent capital return hurdles. Strategic archetypes include grid-interconnection gatekeepers, utilization-aggregating platform operators, and vertical mobility-service integrators. Dominant competitive moves encompass utility partnership negotiations for grid-scale connection priority and fleet operator SLA contracts that transfer utilization risk.
Within the premium mobility-service tier, NIO Inc. occupies a position exemplifying battery swap network standardization, while Star Charge and Wanbang New Energy represent contrasting archetypes of volume-focused public deployment versus utility-integrated grid priority access. These three entities illustrate the strategic divergence between proprietary ecosystem control and open-network aggregation models that defines competitive positioning in China's charging infrastructure buildout.
| Leading Market Players |
|---|
| NIO Inc. |
| Anari |
| Star Charge |
| Qingdao TGOOD Electric |
| Wanbang New Energy |
| TGOOD |
| XCharge |
| Teltocharge |
| BYD Auto |
| Others |
Value Chain & Pricing Dynamics
State Grid Corporation's balance-sheet-backed highway corridor investments anchor supply discipline while compressing third-party operator margins through interconnection priority queues. MIIT's GB/T certification mandates feed directly into procurement specifications that stratify hardware tiers across the charging infrastructure value chain.
Pricing Analysis
Bundled fleet depot contracts with guaranteed uptime SLAs command premium positioning against unbundled pay-per-use public network transactions. Pricing stratifies across premium, standard, and economy tiers based on power output certification and dynamic load management software inclusion. Cost compression in residential AC installations intensifies because SAMR certification cycles extend 90-120 days, forcing property developers toward commodity hardware. Municipal taxi fleets show least price sensitivity due to binding dual carbon procurement mandates, while tier-three public parking operators face acute margin pressure from sub-15% utilization rates.
Supply Chain Analysis
MIIT's GB/T 18487.3 electromagnetic compatibility testing requirements are disqualifying smaller hardware assemblers lacking captive certification laboratories. Power electronics manufacturing concentrates in China, South Korea, and Japan, with silicon carbide module production anchored in domestic foundries. Liquid-cooled cable assemblies draw from Dongguan specialty manufacturers holding captive positions on high-amperage inputs. Single-source vulnerability runs through domestic SiC inverter talent scarcity that forces operators to poach from automotive OEM engineering centers. Distribution runs through vertically integrated manufacturers with direct State Grid Corporation procurement channels and independent service provider aggregator platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's electric vehicle charging infrastructure functions as a regulatory compounder where MIIT's tightening GB/T interoperability mandates continuously reshape hardware procurement specifications and operator viability thresholds.
For Market Incumbents: Lock in grid-scale connection priority through utility partnership negotiations that secure 350kW+ interconnection queue advancement. Consolidate procurement around vertically integrated manufacturers with captive EMC testing facilities to neutralize smaller assembler price competition. Threat of battery swap standardization from NIO's ecosystem expansion demands defensive certification investment in dynamic load management software capabilities. For New Entrants and Emerging Players: The 40% charging point density gap between western provinces and eastern megacity clusters offers land-banking advantages for highway corridor operators targeting Chengdu-Chongqing-Guizhou triangle expansion. Battery swap-taxi integration contracts in Shenzhen and Guangzhou present the most penetrable segment given municipal procurement specification shifts. Go-to-market positioning should emphasize V2G aggregation pilots in Jiangsu province to access revenue stacking beyond per-kWh margins. For Investors and Strategic Acquirers: Valuations sit cheapest among independent service providers lacking utility partnership anchoring but demonstrating volume deployment scale across public parking assets. Long-term viability hinges on operator ability to secure guaranteed utilization floors through fleet SLA contracts rather than speculative public network density plays. Signal to watch is State Grid Corporation technical review queue length compression in high-demand zones as inflection indicator for deployment velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Utility Partnership Negotiation | State Grid Corporation interconnection priority secures 350kW+ highway corridor commissioning timelines. |
| Battery Swap Network Standardization | NIO's ecosystem expansion forces hardware procurement specification convergence across taxi fleet operators. |
| V2G Aggregation Pilot Participation | Jiangsu province demand response programs compensate operators for bi-directional power services. |
| SiC Power Module Transition | Silicon carbide rectifier adoption cuts conversion losses and enables compact 350kW+ hub footprints. |
| Western Corridor Land Banking | Chengdu-Chongqing-Guizhou triangle density gaps offer first-mover advantages for highway operators. |
Study Parameters
Bottom-up fleet operator demand modeling reconciled against top-down charging point installation tracking forms the analytical core of this study. Primary interviews with charging hub operators, State Grid Corporation interconnection planners, MIIT certification laboratory directors, and fleet procurement managers combined with secondary validation from MIIT GB standard filings, National Development and Reform Commission infrastructure plan disclosures, and provincial dual carbon implementation timelines. Top-down supply-side tracking draws from SAMR quality certification databases and State Grid Corporation capital expenditure disclosures.
Historical trendline analysis of charging point deployment velocity and utilization rate trajectories informed the projection framework across the analysis window. Segmentation dimensions modeled include charger type power tier, installation setting regulatory complexity, operator type capital structure, and payment model revenue stability. CAGRs derived from fitted growth curves applied to fleet electrification mandate timelines and vehicle parc expansion assumptions. Industry-specific forecast inputs incorporate MIIT standard amendment schedules and provincial grid interconnection queue dynamics.
Caveats apply where GB/T standard harmonization delays or battery swap architecture mandate reversals could materially shift the outlook. Forecasts reflect assumptions regarding State Grid Corporation technical review processing capacity and liquid-cooled cable supply elasticity. Deviation in peak-demand tariff restructuring would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Battery Swap Station Market
Electric Vehicle Charging
Smart EV Battery Charger Market
Electric Vehicle Charging
Electric Vehicle Charging Systems Testing Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
US Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Engineered Polymers in Electric Charging Infrastructure Market
Electric Vehicle Charging
Micro Mobility Charging Infrastructure Market
Electric Vehicle Charging
High Power Charger for Electric Vehicle Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station and Pile Operation and Management Market
Electric Vehicle Charging
Solar Carport Charging Station Market
Electric Vehicle Charging
Global EV Charging Piles Market
Electric Vehicle Charging
North America Wireless Charging Market
Electric Vehicle Charging
Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Safe Charging Inlet Market