
 Global Data Center Energy Storage Market | 2026-2036
Global Data Center Energy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Center Energy Storage Market Foresight
Aftermarket service revenue is fragmenting across battery management system upgrades, predictive maintenance contracts, and residual value recovery services. Schneider Electric leverages its integrated power distribution portfolio to capture recurring service income. Tesla anchors its position through proprietary battery chemistry and direct deployment at hyperscale campuses. Huawei Technologies competes on containerized system design with integrated thermal management.
Data center energy storage encompasses electrochemical and mechanical systems engineered to deliver instantaneous or short-duration power backup, typically rated between 1 MW and 100 MW per installation, with discharge durations from seconds to four hours depending on chemistry and architecture. These systems protect critical IT loads from grid instability and enable participation in ancillary power markets. Lithium-ion technology dominates installed capacity due to energy density advantages and declining cell costs, while flow battery systems gain traction in four-to-eight-hour duration applications where cycle life economics improve total cost of ownership. Hyperscale data centers represent the largest end-user segment by megawatt demand, though edge data centers constitute the fastest-growing deployment category as latency requirements push compute closer to population centers.
EPA emissions standards and FERC interconnection rules in the United States, alongside EU Green Deal carbon benchmarks and REACH chemical compliance in Europe, collectively shape product certification requirements and procurement criteria for storage system vendors. China's MIIT efficiency mandates and GB standards for battery safety add a third regulatory layer that manufacturers must navigate for market access. Stakeholders must monitor evolving duration requirements as grid operators revise ancillary service specifications and as data center operators evaluate hybrid storage architectures against standalone lithium-ion deployments.
Market Dynamics
Hyperscale cloud operators are consolidating procurement power and demanding four-hour discharge capabilities, compressing vendor margins while accelerating chemistry diversification beyond lithium-ion dominance.
Growth Catalysts
- FERC Order 2222:US grid operators now aggregate distributed energy resources, letting data center batteries earn ancillary service revenue. This dual-use economics justifies larger installations.
- AI training clusters:GPU-intensive workloads create power volatility that legacy UPS cannot manage. Operators deploy hybrid electrochemical-mechanical systems for ride-through.
- EU F-Gas Regulation:Phasedown of synthetic refrigerants in thermal management pushes adoption of liquid-cooled battery containers with natural coolant circuits.
Market Restraints
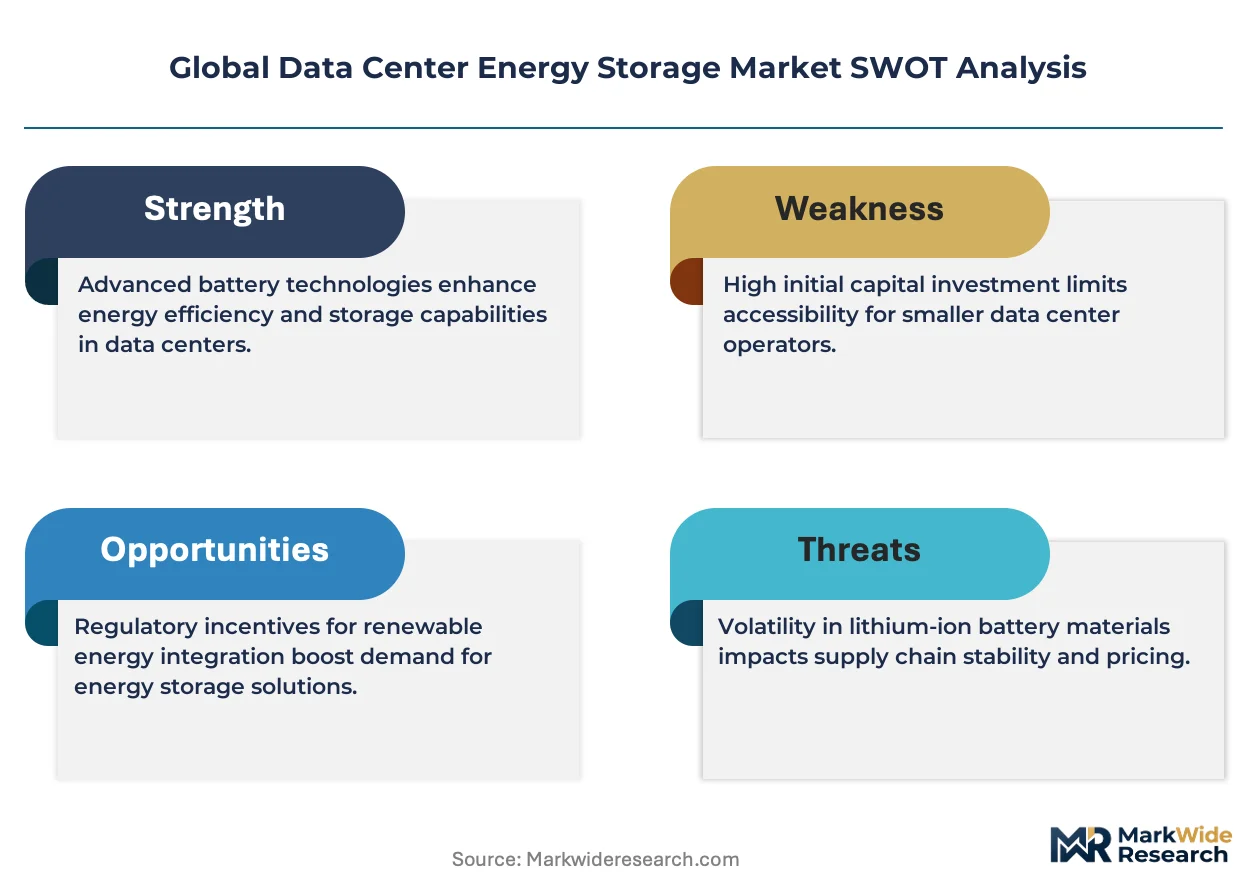
- Lithium carbonate volatility:Cell input costs swing with Chilean and Australian mining output, destabilizing project finance for multi-hundred-megawatt deployments.
- Single-source dependency:NMC cathode precursor refining concentrates in Chinese chemical parks, creating geopolitical supply risk for non-domestic integrators.
- Fire suppression retrofit burden:Existing facilities face sprinkler system upgrades to meet NFPA 855 standards, adding unbudgeted capex to brownfield installations.
Strategic Opportunities
- India's CEA storage mandate:Renewable purchase obligations now include co-located battery requirements, opening procurement channels for containerized systems at new data center parks near Chennai and Mumbai.
- Vanadium flow-lithium hybrid architectures:Pairing four-hour flow batteries with one-hour lithium buffers optimizes cycle life for daily peak-shaving versus emergency backup.
- Direct utility PPAs with storage riders:Bypassing traditional EPC channels, operators negotiate behind-the-meter installation ownership with municipal utilities in deregulated US states.
Industry Challenges
- Battery electrochemist shortage:System integrators compete with automotive OEMs for cell characterization talent, delaying product validation timelines.
- Multi-standard certification overlap:UL 9540A, IEC 62619, and UN 38.3 testing requirements lack mutual recognition, forcing redundant destructive testing for global deployments.
- Legacy DCIM integration:Proprietary battery management protocols fail to interface with existing infrastructure monitoring platforms, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Center Energy Storage Market |
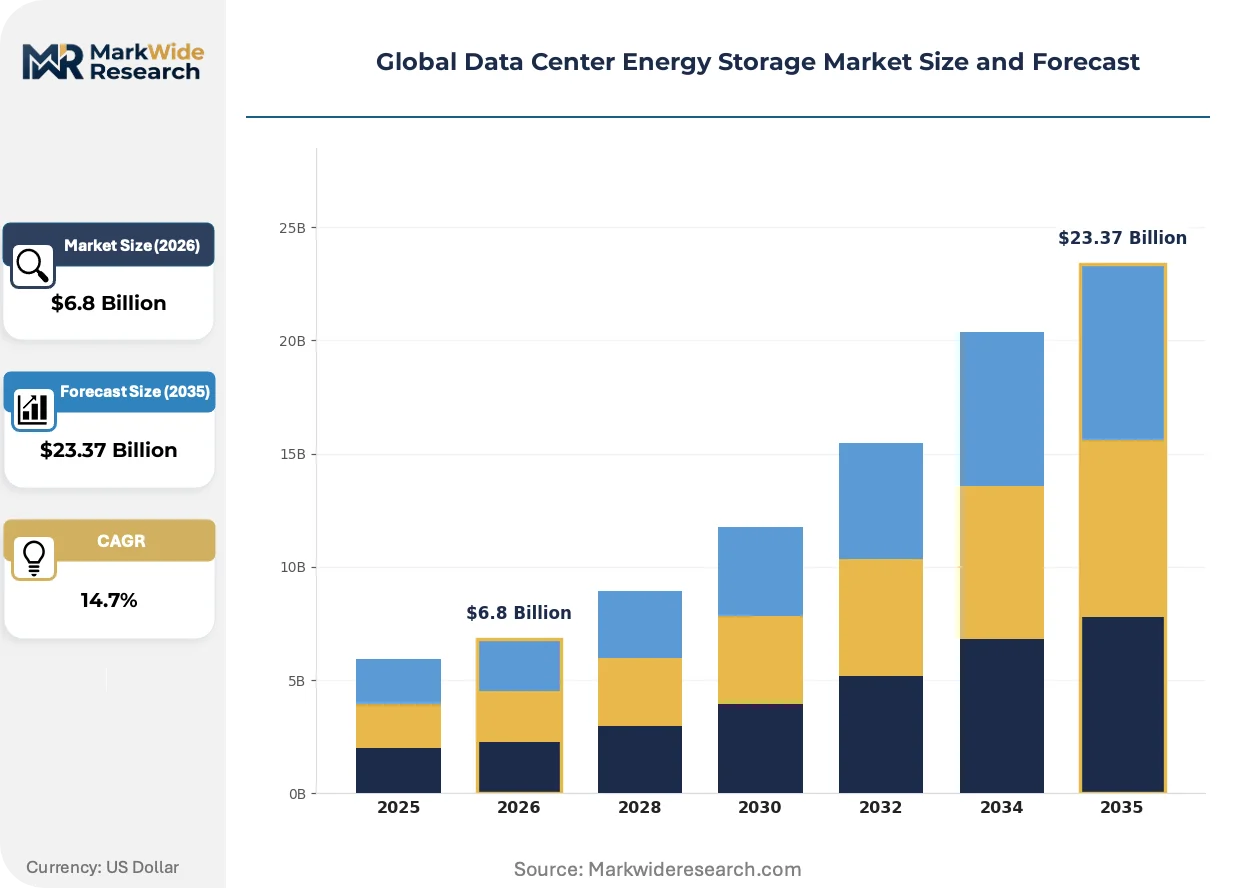
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.37 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lithium-ion, Lead-acid, Flow Battery, Sodium-ion, Nickel-Cadmium Application: Backup Power, Load Balancing, Peak Shaving, Frequency Regulation, Uninterruptible Power Supply End User: Hyperscale Data Centers, Colocation Facilities, Edge Data Centers, Managed Hosting Providers, Cloud Service Providers Deployment: On-premises, Cloud-integrated, Modular Units, Containerized Systems, Microgrid Connected |
| Companies Covered | Schneider Electric, Vertiv, ABB, Eaton Corporation, Huawei Technologies, Delta Electronics, Legrand, Mitsubishi Electric, Tesla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Center Energy Storage Market Shifts & Advancements
Digital twin architectures and solid-state cell chemistries are compressing the gap between design-phase simulation and operational performance, while regulatory pressure on embodied carbon forces supply chain visibility tools into procurement specifications.
Solid-state lithium-metal cells with sulfide electrolytes are digitizing thermal runaway prediction models by embedding distributed fiber-optic sensors throughout the cell stack. Early deployments at Singapore hyperscale campuses demonstrate 40% faster fault detection than conventional voltage-temperature monitoring. This sensor integration is digitizing how insurers underwrite battery fire risk, compressing premium spreads between Tier 1 and Tier 2 integrators.
REACH chemical restriction expansions are forcing disclosure of conflict minerals and fluorinated compounds across the full bill of materials. European data center operators now require full substance passports from storage vendors, with ECHA SCIP database registration mandatory for imported systems. German operators have responded by pre-qualifying only those suppliers with in-house recycling take-back programs.
Energy-as-a-service contracting is displacing traditional equipment ownership at edge data center deployments. Colocation providers in Brazil and Indonesia lease battery capacity by the kilowatt-hour rather than purchasing assets, transferring operational risk to specialized storage operators. This model concentrates most visibly in markets with currency volatility that deters dollar-denominated capex commitments.
Global Data Center Energy Storage Market Segmentation
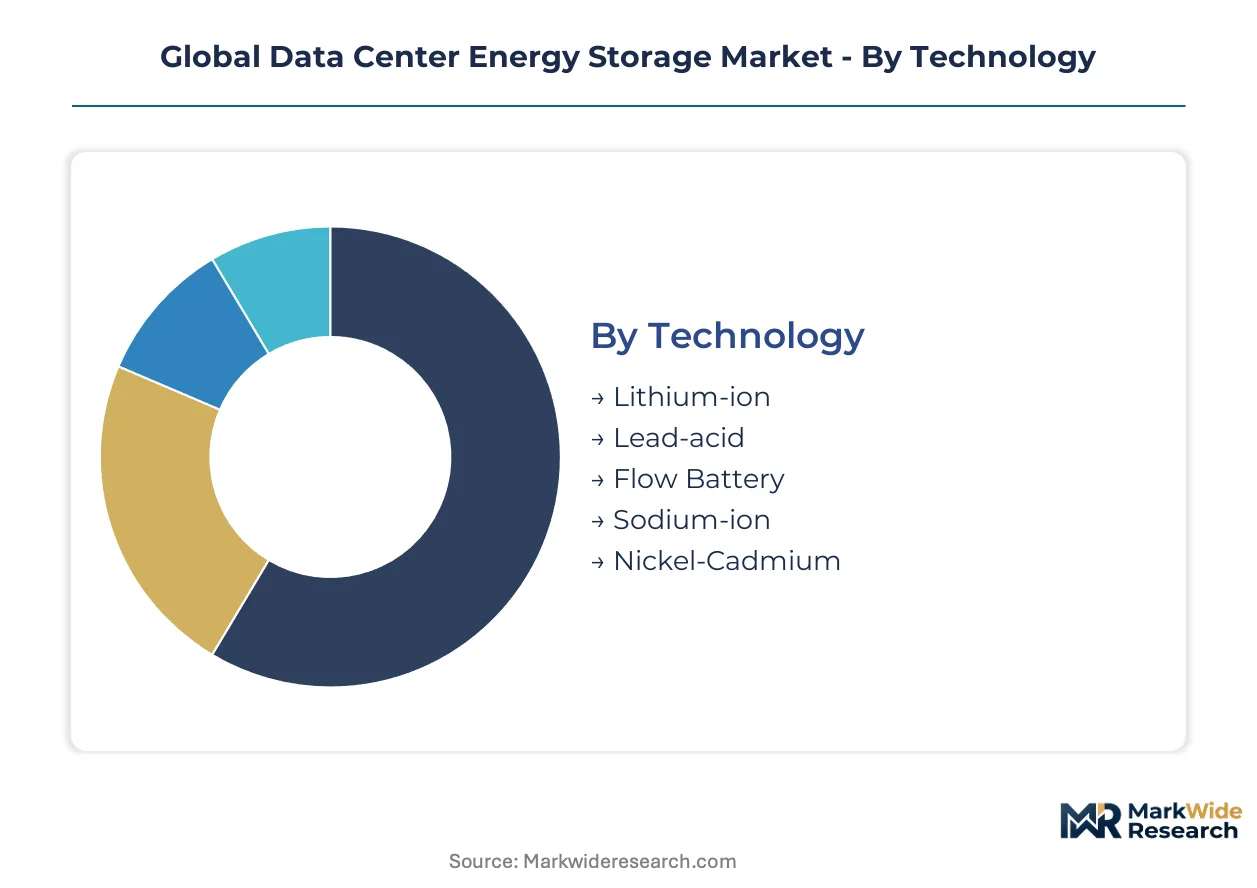
Segmentation in data center energy storage reveals divergent procurement cycles across chemistries and deployment architectures. Technology choices lock in operational characteristics for 10-15 year asset lifecycles, while application requirements shift with grid service revenue opportunities.
Technology:
Cycle times range from 3-5 years for emerging chemistries seeking certification to 12-15 years for mature battery systems with validated degradation curves.
- Lithium-ion:Dominant electrochemical architecture utilizing nickel-manganese-cobalt or lithium-iron-phosphate cathodes with energy densities exceeding 200 Wh/kg. Hyperscale operators in the United States specify lithium-ion for four-hour discharge requirements under FERC Order 2222 ancillary service participation.
- Flow Battery:Vanadium or zinc-bromine redox systems with electrolyte tanks decoupling power and energy ratings. Germany's grid operators favor these for daily cycling applications where 20,000+ cycle life amortizes higher upfront capital against lithium-ion replacement schedules.
- Lead-acid:Mature flooded or valve-regulated designs with established recycling infrastructure. Legacy installations in India persist where CEA mandates prioritize lowest first-cost procurement.
- Sodium-ion:Emerging chemistry using abundant raw materials with thermal stability advantages over lithium. CATL and BYD pilot deployments target price-sensitive Chinese data center clusters.
- Nickel-Cadmium:Aircraft-derived cells with extreme temperature tolerance. Arctic-region facilities in Norway specify these for outdoor containerized installations.
Lithium-ion dominates installed base. Sodium-ion is where expansion concentrates for supply security diversification.
Application:
Revenue models differentiate segments: backup power commands premium pricing for reliability guarantees, while grid services generate operational income streams.
- Backup Power:Emergency discharge systems rated for 15-30 minutes protecting critical IT loads during utility failure. Colocation providers in Singapore mandate 99.999% uptime contracts requiring redundant battery strings.
- Peak Shaving:Scheduled discharge reducing demand charges during utility peak pricing windows. Texas hyperscale campuses exploit ERCOT price volatility through automated dispatch algorithms.
- Load Balancing:Real-time power injection smoothing renewable generation intermittency. Ireland's data center operators deploy these to satisfy EirGrid connection constraints.
- Frequency Regulation:Sub-second response to grid frequency deviations per FERC Order 755 compensation rules. PJM Interconnection markets reward fastest-responding resources.
- Uninterruptible Power Supply:Double-conversion systems providing conditioned power with zero transfer time. Financial trading floors in London specify these for microsecond-sensitive transactions.
Backup Power anchors procurement budgets. Peak Shaving is climbing the fastest as electricity market liberalization spreads.
End User:
Scale economies concentrate purchasing power among operators exceeding 50 MW campus footprints, fragmenting vendor pricing power across smaller deployment categories.
- Hyperscale Data Centers:Single-tenant facilities exceeding 100 MW designed for cloud computing workloads. Amazon Web Services and Microsoft Azure negotiate multi-gigawatt supply agreements directly with cell manufacturers.
- Edge Data Centers:Distributed 1-10 MW facilities positioned within 10 milliseconds of population centers. Telefónica's Spanish deployments prioritize latency over energy cost optimization.
- Colocation Facilities:Multi-tenant data halls leasing space by the rack. Equinix standardizes battery specifications across 240+ global sites to simplify procurement.
- Cloud Service Providers:Software platforms operating leased infrastructure rather than owned assets. Google Cloud contracts storage-as-a-service from specialized operators.
- Managed Hosting Providers:Outsourced IT infrastructure operators serving enterprise clients. Rackspace maintains dedicated battery rooms for compliance-sensitive healthcare workloads.
Hyperscale Data Centers capture volume discounts. Edge Data Centers are gaining share fastest as 5G rollout accelerates.
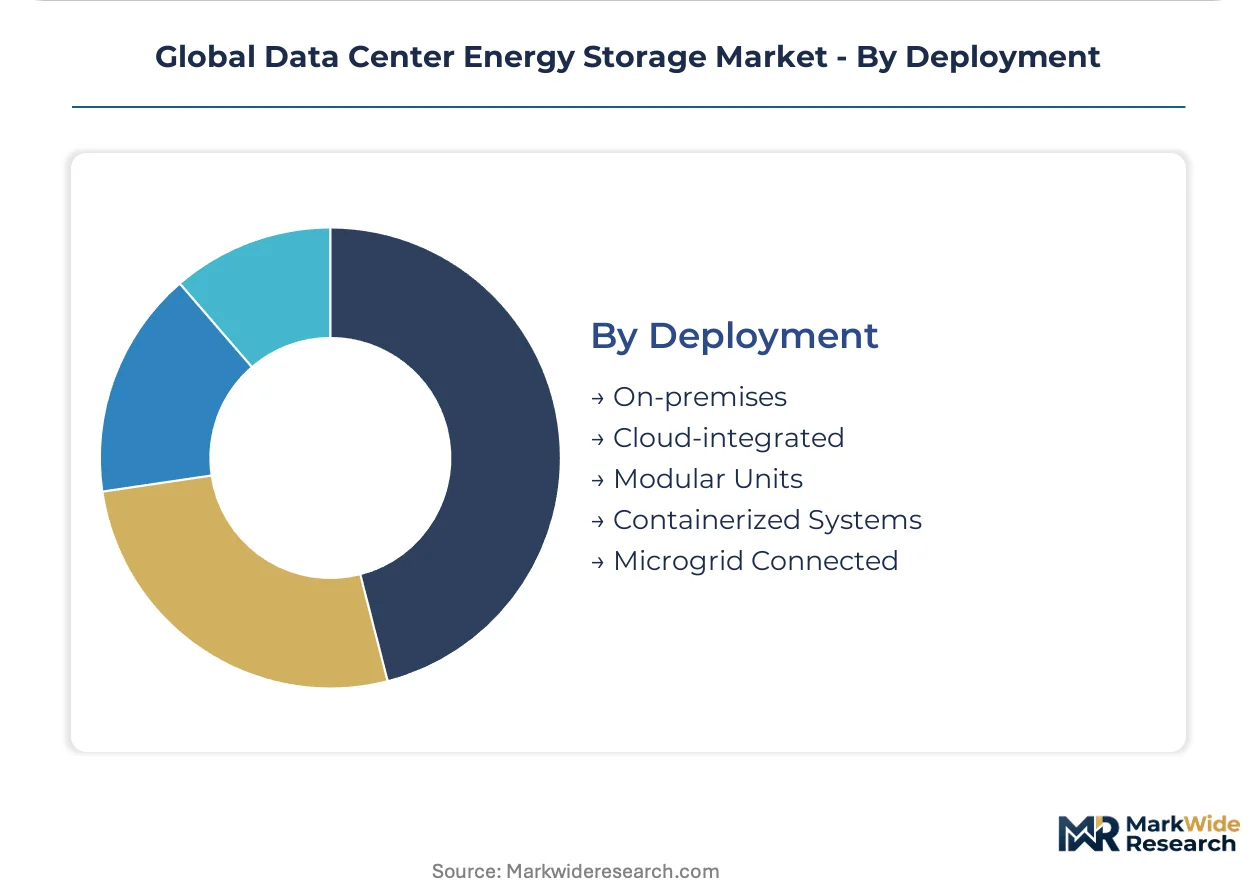
Deployment:
Capital efficiency favors factory-integrated systems over field-assembled architectures, compressing construction schedules and commissioning risk.
- Containerized Systems:Pre-engineered 40-foot modules with integrated thermal management and fire suppression. Schneider Electric's prefabricated units reduce Saudi Aramco's deployment timeline from 18 months to 8 weeks.
- Modular Units:Rack-mounted battery strings scaling in 100 kWh increments. NTT's Japanese facilities add capacity without facility shutdown.
- On-premises:Building-integrated installations with dedicated electrical rooms. Legacy enterprise data centers in Frankfurt maintain this architecture for insurance compliance.
- Cloud-integrated:Virtualized storage resources dispatched through software-defined power platforms. Virtual Power Plant aggregators pool distributed assets.
- Microgrid Connected:Island-capable systems with black-start capability. Microsoft's Wyoming campus operates independently during grid outages.
Containerized Systems lead new build specifications. Cloud-integrated architectures are expanding most quickly behind software-defined infrastructure adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity, prioritizing lowest first-cost procurement over lifecycle economics, while operators in Germany and Singapore absorb premium pricing for certified systems with validated degradation curves and full substance passports.
United States
Hyperscale cloud operators in Northern Virginia, Dallas-Fort Worth, and Phoenix drive multi-gigawatt procurement volumes. FERC Order 2222 and Order 755 enable battery participation in ancillary service markets, justifying four-hour discharge specifications. Texas hyperscale campuses exploit ERCOT price volatility through automated peak-shaving dispatch algorithms.
Germany
Grid operators favor vanadium flow batteries for daily cycling applications where 20,000-plus cycle life amortizes capital against lithium-ion replacement schedules. EU Green Deal carbon benchmarks and REACH chemical compliance mandate full substance passports and ECHA SCIP database registration. Frankfurt's data center cluster maintains building-integrated architectures for insurance compliance.
China
MIIT efficiency mandates and GB standards for battery safety create a dual regulatory layer for market access. CATL and BYD pilot sodium-ion deployments targeting price-sensitive domestic data center clusters. Yangtze River Delta and Pearl River Delta regions concentrate manufacturing and hyperscale demand.
Singapore
Colocation providers mandate 99.999 percent uptime contracts requiring redundant battery strings. Solid-state lithium-metal cells with embedded fiber-optic sensors demonstrate faster fault detection at hyperscale campuses. The city-state's tropical climate drives liquid-cooled container specifications with natural coolant circuits.
India
CEA storage mandates now include co-located battery requirements for renewable purchase obligations. Chennai and Mumbai data center parks open procurement channels for containerized systems. Legacy installations persist where mandates prioritize lowest first-cost lead-acid procurement over lifecycle optimization.
Global Data Center Energy Storage Market Competitive Landscape
Capability concentration sits with integrated power distribution specialists; scale advantage sits with direct cell manufacturers. The vendor base separates into three tiers: diversified electrical equipment conglomerates with captive service networks, pure-play battery system integrators with chemistry-specific expertise, and automotive cell suppliers forward-integrating into stationary applications. Consolidation pressures intensify as hyperscale operators consolidate procurement power and demand four-hour discharge capabilities. Dominant competitive moves include backward integration into cathode precursor refining and strategic partnerships with digital infrastructure monitoring platforms.
Among diversified electrical equipment conglomerates, Schneider Electric exemplifies the integrated power distribution archetype with recurring service income capture. Vertiv and Eaton Corporation represent North American-based specialists with established hyperscale relationships. Huawei Technologies anchors the containerized system design tier with integrated thermal management capabilities. Tesla occupies a distinct position through proprietary battery chemistry and direct hyperscale campus deployment.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv |
| ABB |
| Eaton Corporation |
| Huawei Technologies |
| Delta Electronics |
| Legrand |
| Mitsubishi Electric |
| Tesla |
| Others |
Supply & Pricing Matrix
Lithium carbonate volatility originating from Chilean and Australian mining corridors determines both pricing tier spreads and supply chain shape, compressing project finance terms for multi-hundred-megawatt deployments while forcing integrators toward chemistry diversification and long-term offtake contracting.
Pricing Analysis
Aftermarket service revenue tiers anchored by predictive maintenance contracts and residual value recovery services drive lifetime value capture. Three-tier pricing structure across premium, standard, and economy levels separates UL 9540A-certified systems with full substance passports from uncertified alternatives. Pricing pressure stems from hyperscale operators consolidating procurement power and demanding four-hour discharge capabilities. Edge data centers in Southeast Asia exhibit acute price sensitivity, while German operators absorb premium pricing for certified systems with validated degradation curves.
Supply Chain Analysis
Upstream feedstock concentration for NMC cathode precursor refining centers on Chinese chemical parks, creating geopolitical supply risk for non-domestic integrators. Cell manufacturing draws from South Korea and Japan for high-nickel chemistries, with raw material dependencies spanning lithium carbonate, cobalt hydroxide, and electrolyte salts. Single-source vulnerability in precursor refining amplifies tariff exposure. Distribution runs through direct utility PPAs with storage riders and specialized EPC contractors serving hyperscale campuses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FERC Order 2222 and parallel EU grid aggregation rules constitute a regulatory inflection that transforms battery assets from cost centers into revenue-generating infrastructure, positioning data center energy storage as a high-growth disruption.
For Market Incumbents: Pre-empt margin compression from hyperscale procurement consolidation by securing captive cathode precursor refining capacity and embedding predictive maintenance platforms into existing DCIM infrastructure. Threats from sodium-ion substitution and automotive OEM talent poaching demand chemistry-agnostic system architectures.
For New Entrants and Emerging Players: Establish a beachhead in India's CEA-mandated storage procurement at Chennai and Mumbai data center parks, where renewable purchase obligations create guaranteed demand. Target vanadium flow-lithium hybrid architectures for German daily cycling applications, leveraging 20,000-plus cycle life economics against incumbent lithium-ion replacement schedules.
For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors integrated power distribution specialists with recurring service income streams. Long-term viability hinges on backward integration into cell manufacturing and certification expertise. Signal to watch: FERC ancillary service specification revisions that extend duration requirements beyond four hours.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Refining | Reduces Chinese chemical park dependency for NMC supply security. |
| Predictive Maintenance Platform Deployment | Captures recurring service revenue from hyperscale operator contracts. |
| Vanadium Flow-Lithium Hybrid System Development | Optimizes cycle life economics for German daily peak-shaving applications. |
| Direct Utility PPA Negotiation with Storage Riders | Bypasses EPC channels in deregulated US states for margin retention. |
| Solid-State Cell Sensor Integration | Accelerates fault detection for Singapore tropical climate deployments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with data center infrastructure executives, battery system procurement leads, utility interconnection planners, EPC project developers, and thermal management engineers. Secondary validation drew from FERC filings, EIA project databases, EU ECHA SCIP registration records, and hyperscaler capex disclosures. Bottom-up installation capacity modeling and top-down regulatory scenario analysis were triangulated to produce segment-level outputs.
Calibration against historical deployment trajectories and announced project pipelines anchored volume and value estimates across the projection horizon. Segmentation dimensions modeled include electrochemical technology, discharge duration tier, deployment architecture, end-user scale category, and regional regulatory framework. CAGRs were derived from regression analysis of announced capacity additions against grid service revenue opportunity expansion, incorporating lithium carbonate price elasticity and FERC Order 2222 participation rate assumptions.
Stress conditions across lithium carbonate price bands, Chinese export restriction scenarios, and FERC ancillary service specification revisions were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against IEA stationary storage deployment benchmarks and hyperscaler disclosed sustainability targets is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Australia Energy Storage Systems (ESS) Market
Energy Storage
Power Bank Market
Energy Storage
Off-Grid Energy Storage Systems Market
Energy Storage
United Kingdom Energy Storage Systems Market
Energy Storage
Asia-Pacific Energy Storage Systems Market
Energy Storage
Hybrid Solar Wind Energy Storage Market
Energy Storage
Supercapacitor Market
Energy Storage
Gravity Energy Storage Market
Energy Storage
Sodium Sulfur (Nas) Battery for Energy Storage Market
Energy Storage
Water Electrolysis Machine Market
Energy Storage
Super Capacitor Energy Storage System Market
Energy Storage
Double Layer Super-Capacitor Market
Energy Storage
Vessel Energy Storage Systems Market
Energy Storage
Flywheel Energy Storage (FES) Systems Market
Energy Storage
Ultracapacitors Market
Energy Storage
Natural Gas Storage Market