
 India Solar Energy Market | 2026-2036
India Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
India Solar Energy Market Outlook
Polysilicon supply from domestic sources is hardening module cost structures for Indian manufacturers. Waaree Energies leverages vertical integration into cell manufacturing to protect margin pools. Tata Power Solar anchors utility-scale project development through its nationwide execution footprint. Adani Green Energy dominates the renewable energy park model with gigawatt-scale land banking in Gujarat and Rajasthan.
India solar energy encompasses photovoltaic systems that convert sunlight into direct current electricity through semiconductor junctions, typically operating at 15-22% conversion efficiency depending on cell architecture, then feeding power through string or central inverters for grid synchronization or battery storage. The technology segment shows monocrystalline modules commanding premium pricing due to higher efficiency ratings, while thin-film retains niche appeal in building-integrated applications where weight constraints matter. Ground-mounted installations occupy the largest share of capacity additions, though rooftop systems are accelerating in the commercial end-user category as DISCOM net-metering frameworks mature across Maharashtra and Tamil Nadu.
India's Ministry of New and Renewable Energy shapes project allocation through the National Solar Mission, while BIS certification mandates enforce module quality standards for domestic procurement. The PLI scheme administered by the Department of Expenditure redirects capital toward polysilicon-to-module integration, tightening eligibility for imported component reliance. CEA grid connectivity regulations determine evacuation infrastructure sequencing for solar parks. Stakeholders must weigh domestic content requirements against technology cost curves when siting manufacturing capacity.
Market Dynamics
India's solar sector is restructuring around domestic manufacturing mandates as the PLI scheme tightens eligibility criteria for imported components, forcing project developers to requalify suppliers and manufacturers to absorb polysilicon cost volatility.
Growth Catalysts
- PLI Scheme Incentives:The Department of Expenditure's production-linked incentive framework redirects capital toward polysilicon-to-module integration, tightening eligibility for imported component reliance and accelerating domestic cell and wafer capacity buildout.
- Rajasthan Desert Solar Parks:Industrial buyers are expanding procurement of large-scale photovoltaic installations concentrated in Rajasthan's desert solar parks, where land availability and irradiance levels support gigawatt-scale project economics.
- Monocrystalline Technology:Higher-efficiency monocrystalline modules command premium pricing due to superior conversion ratings, displacing polycrystalline alternatives in utility-scale tenders where land-use efficiency determines project viability.
Market Restraints
- Polysilicon Supply Concentration:Domestic polysilicon supply remains insufficient, hardening module cost structures for Indian manufacturers dependent on imported feedstock from concentrated East Asian suppliers.
- BIS Certification Friction:Bureau of Indian Standards certification mandates enforce module quality standards that extend procurement timelines and disqualify lower-cost imported alternatives lacking domestic testing documentation.
- Grid Evacuation Bottlenecks:Central Electricity Authority regulations determine evacuation infrastructure sequencing, creating interconnection queues that delay commercial operation dates for solar parks in Gujarat and Rajasthan.
Strategic Opportunities
- Commercial Rooftop Acceleration:DISCOM net-metering frameworks are maturing across Maharashtra and Tamil Nadu, unlocking distributed generation opportunities in the commercial end-user category as tariff parity improves.
- Thin-Film Building Integration:Thin-film photovoltaic retains niche appeal in building-integrated applications where weight constraints matter, particularly in urban commercial retrofits across Delhi and Bangalore.
- Battery Storage Convergence:String and central inverter manufacturers are integrating battery storage interfaces, enabling hybrid solar-plus-storage configurations that address evening peak demand for industrial offtakers.
Industry Challenges
- Wafer Processing Skill Gap:Domestic cell and wafer manufacturing expansion faces acute shortages of semiconductor process engineers and crystallization specialists, constraining yield optimization at new facilities.
- Land Aggregation Complexity:Gigawatt-scale land banking in Gujarat and Rajasthan requires navigating fragmented landownership patterns and state-level revenue department clearances, extending project development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Solar Energy Market |
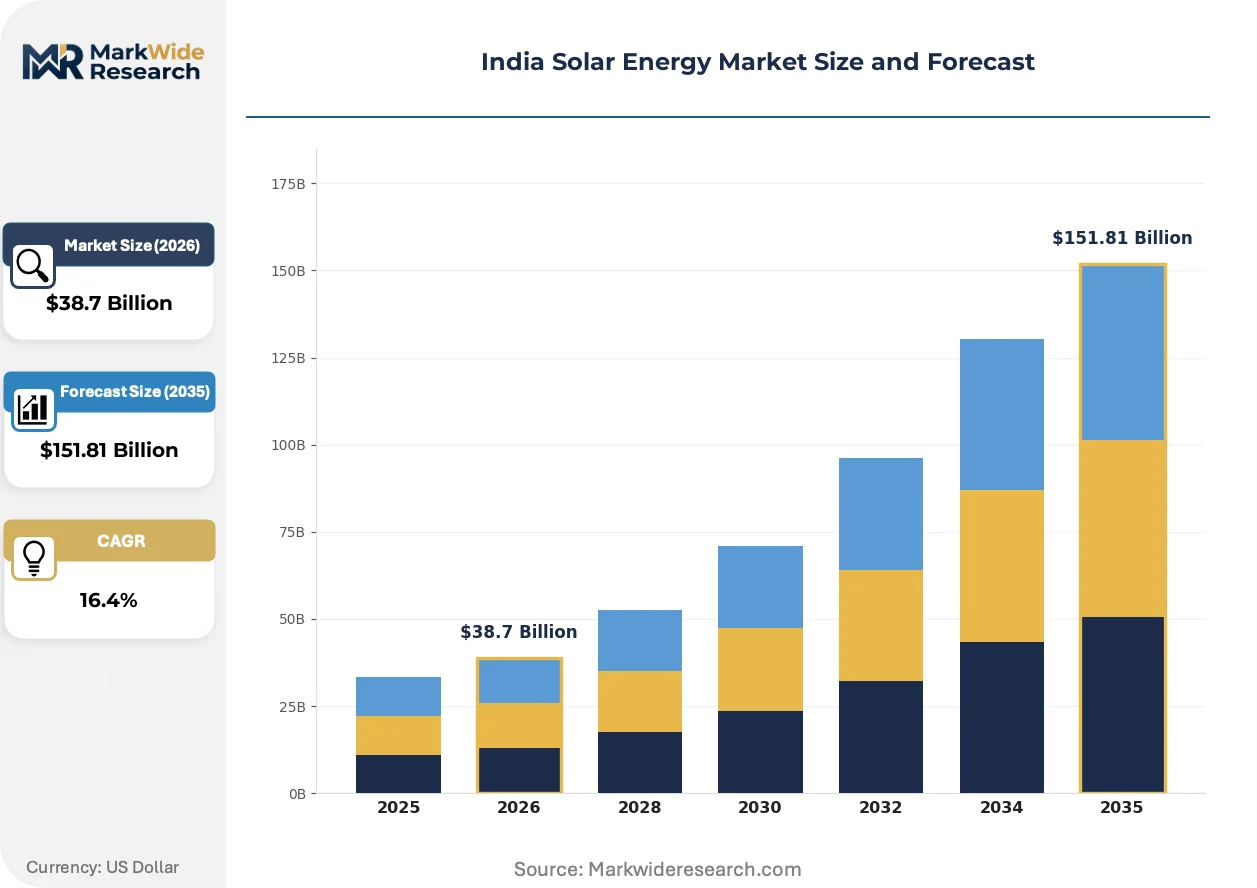
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Monocrystalline, Polycrystalline, Thin-Film, BIPV End User: Residential, Commercial, Industrial, Utilities Installation Type: Rooftop, Ground-Mounted, Off-Grid, Hybrid Component: Inverters, Batteries, Racking Systems, Charge Controllers |
| Companies Covered | Tata Power Solar, Vikram Solar, Waaree Energies, KPI Green Energy, Premier Energies, Adani Green Energy, NHPC, JSW Energy, NTPC Green Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Solar Energy Market Strategic Shifts
Technology evolution and procurement restructuring are compressing project development cycles while regulatory mandates force supply chain reconfiguration across the photovoltaic value chain.
Topcon cell architecture is electrifying module efficiency benchmarks in the Indian market. This tunnel oxide passivated contact technology reduces recombination losses at the semiconductor junction, enabling conversion efficiencies exceeding 22% in mass production. Industrial buyers in Rajasthan's desert solar parks are specifying Topcon modules for new tenders, accepting 8-12% module cost premiums to reduce land requirements and balance-of-system expenses. The technology is electrifying competitive positioning among domestic manufacturers racing to license production equipment before PLI scheme windows close.
CEA technical standards for grid-connected solar systems are mandating stricter fault ride-through and reactive power capabilities. These regulations require inverter manufacturers to upgrade firmware and hardware designs, increasing certification costs but improving grid stability during voltage disturbances. Utility-scale project developers in Gujarat's Charanka cluster are absorbing these compliance costs to secure long-term power purchase agreements with state distribution companies.
Corporate renewable energy procurement is consolidating through open access mechanisms and group captive structures. Large manufacturing consumers in Tamil Nadu and Karnataka are bypassing DISCOM intermediaries to contract directly with solar park developers, securing fixed tariffs over 15-20 year tenors. This direct contracting model is compressing developer margins but expanding addressable demand beyond utility-managed procurement channels.
India Solar Energy Market Segmentation
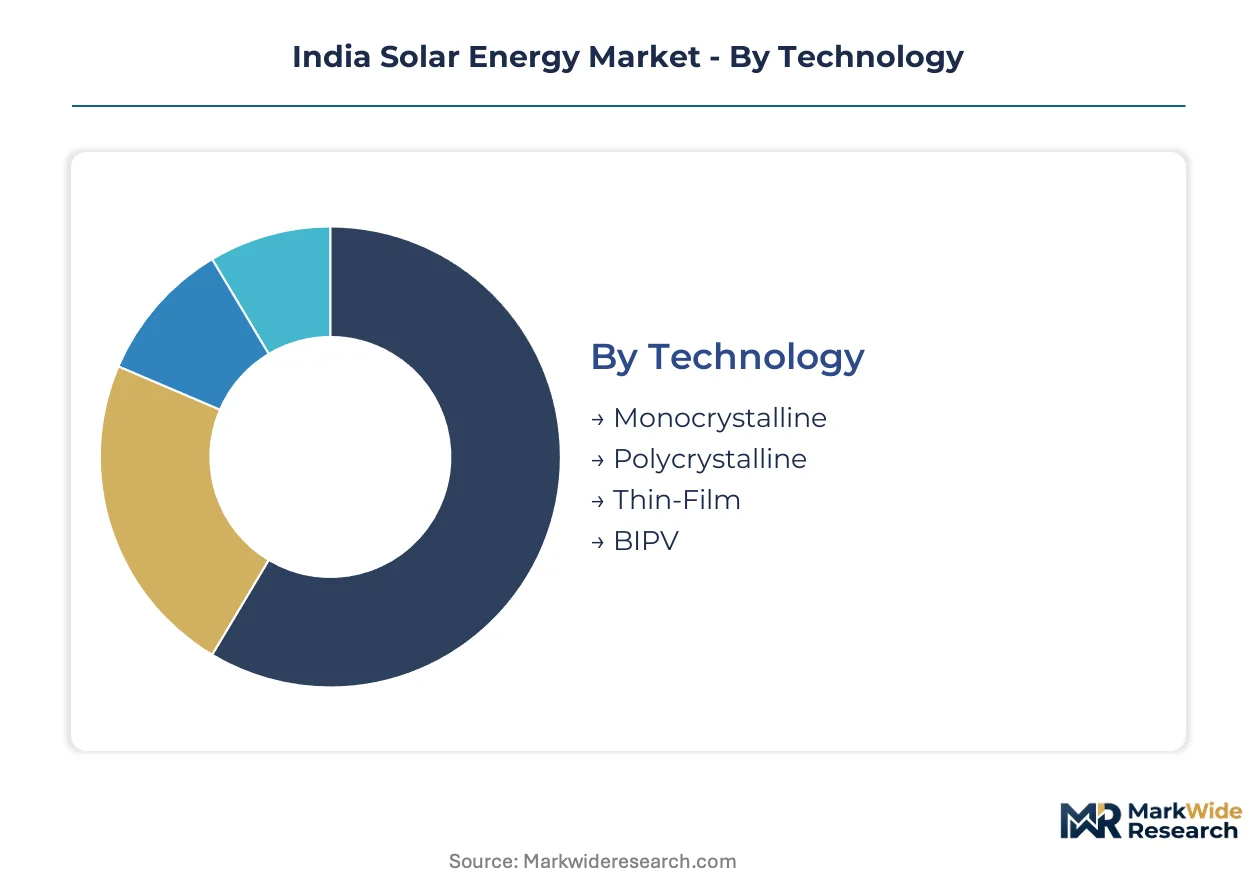
Segmentation in the India solar market reveals how procurement priorities diverge across technology generations, installation scales, and grid-integration requirements. Each dimension carries distinct margin structures and regulatory exposure that shape supplier selection and project economics.
Technology:
Supply concentration in high-efficiency cell architectures is compressing margins for legacy technology tiers while rewarding manufacturers with advanced production equipment.
- Monocrystalline:Single-crystal silicon ingots cut into wafers deliver 20-22% conversion efficiency through uniform electron mobility. Demand concentrates in Rajasthan's desert solar parks where land scarcity rewards higher wattage-per-square-meter economics and PLI scheme incentives favor domestic cell production.
- Polycrystalline:Multi-crystal silicon formed through directional solidification offers lower manufacturing energy intensity but 16-18% peak efficiency. Procurement is retreating to price-sensitive distributed installations in rural Maharashtra where capital constraints outweigh land optimization.
- Thin-Film:Cadmium-telluride or CIGS deposition on glass substrates enables flexible, lightweight modules for weight-constrained structures.
- BIPV:Building-integrated photovoltaic replaces conventional facade and roofing materials with electricity-generating surfaces in urban commercial retrofits.
Today's leader: Monocrystalline. Tomorrow's challenger: BIPV.
End User:
Cost tier differentiation separates procurement volumes, contract tenors, and offtake risk profiles across customer categories.
- Utilities:State distribution companies and central public sector undertakings tender gigawatt-scale capacity through SECI and NTPC Vidyut Vyapar Nigam. Procurement concentrates in Gujarat's Charanka cluster and Rajasthan's Bhadla park where land aggregation and transmission infrastructure align.
- Industrial:Manufacturing consumers in Tamil Nadu and Karnataka execute open-access and group captive arrangements to bypass DISCOM tariffs. Demand is climbing fastest as corporate renewable energy targets harden and banking regulations ease.
- Commercial:Office complexes, retail chains, and educational institutions deploy rooftop systems under net-metering frameworks maturing across Maharashtra and Delhi NCR.
- Residential:Individual households access subsidized rooftop programs through state nodal agencies with MNRE capital cost support.
Industrial offtake is expanding most quickly as direct contracting displaces utility intermediation.
Installation Type:
Application requirements dictate racking complexity, inverter sizing, and grid interconnection protocols.
- Ground-Mounted:Fixed-tilt or tracking structures on dedicated land parcels dominate utility-scale deployment in Rajasthan's solar parks where irradiance exceeds 1,800 kWh/m² annually and evacuation corridors are pre-planned under CEA sequencing.
- Rooftop:Distributed generation on commercial and residential buildings accelerates in Tamil Nadu as TANGEDCO net-metering settlement periods shorten and DISCOMs clear interconnection backlogs.
- Off-Grid:Standalone systems with battery storage serve unelectrified habitations in remote Himalayan and Northeastern districts beyond central grid reach.
- Hybrid:Solar-plus-storage configurations integrate string inverters with lithium-ion battery interfaces to address evening peak demand for industrial consumers.
Ground-mounted capacity retains volume leadership. Hybrid installations are gaining share fastest as storage costs decline.
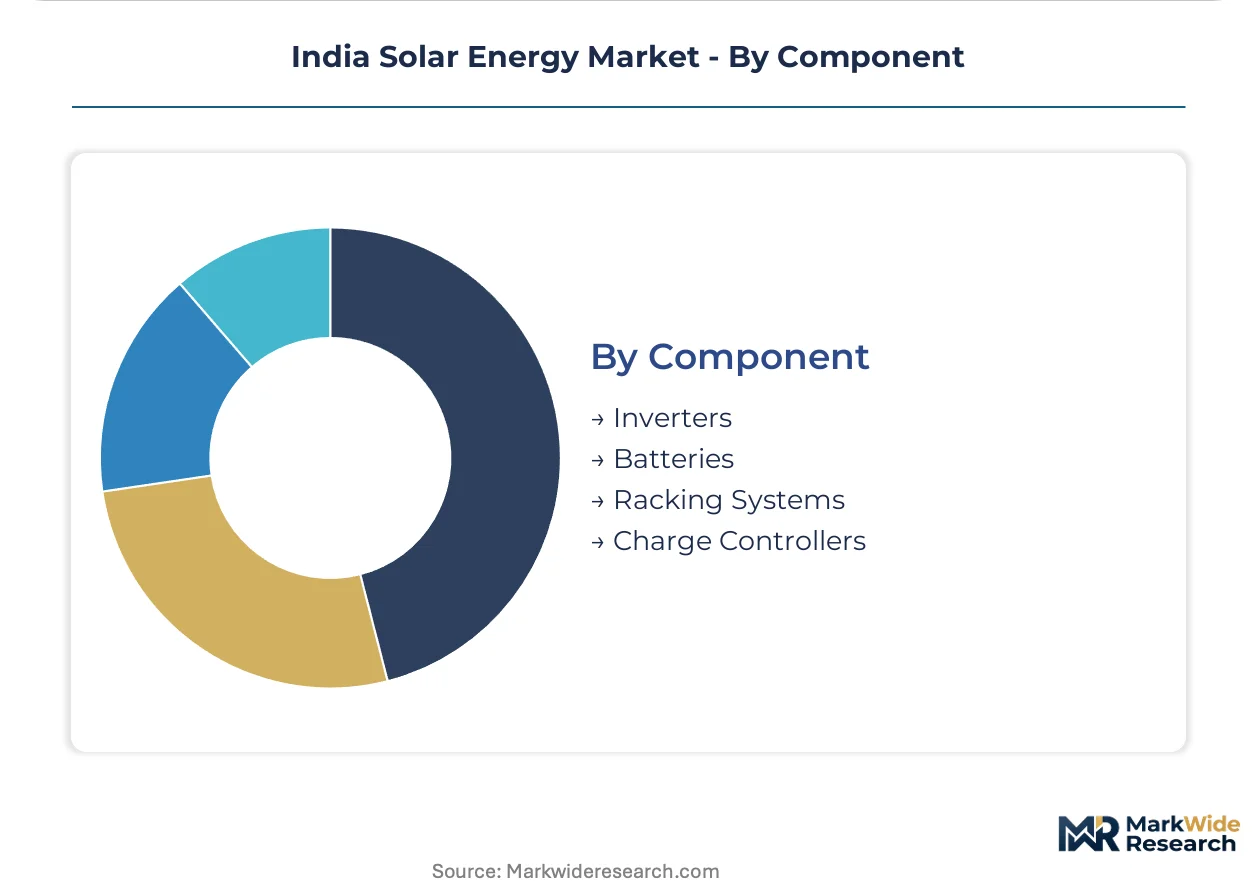
Component:
Margin capture varies sharply across the balance-of-system value chain, with power electronics and energy storage commanding pricing power.
- Inverters:String and central power conversion equipment must meet CEA technical standards for fault ride-through and reactive power capability, with firmware upgrades increasing certification costs for grid-connected projects in Gujarat.
- Batteries:Lithium-ion storage systems enable time-shifted dispatch and frequency regulation services, with demand concentrating in industrial hybrid configurations where peak shaving improves tariff economics.
- Racking Systems:Galvanized steel or aluminum mounting structures support module orientation and wind load resistance across fixed-tilt and single-axis tracking designs.
- Charge Controllers:Maximum power point tracking devices regulate battery charging in off-grid and hybrid DC-coupled architectures.
Inverters anchor component revenue today. Battery systems represent the steepest expansion trajectory as storage mandates emerge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rajasthan's desert solar parks anchor national capacity deployment, with Gujarat's Charanka cluster and Tamil Nadu's industrial corridors forming secondary concentration nodes. State-level policy variation and DISCOM reform progress determine regional investment velocity.
Rajasthan
Bhadla and Phased Solar Parks attract gigawatt-scale tenders from central public sector undertakings. The state's solar policy offers land aggregation support and single-window clearance for projects above 250 MW. Jodhpur and Jaisalmer districts host the densest module installation clusters where irradiance exceeds 1,800 kWh/m² annually.
Gujarat
Charanka Solar Park anchors utility-scale procurement through NTPC Vidyut Vyapar Nigam tenders. The state's renewable energy policy mandates renewable purchase obligations for industrial consumers. Kutch and Patan districts concentrate manufacturing capacity where PLI scheme beneficiaries are locating cell and wafer facilities.
Tamil Nadu
Open-access regulations enable direct corporate procurement from solar park developers. TANGEDCO net-metering settlement periods have shortened to monthly cycles, accelerating commercial rooftop deployment. Coimbatore and Tiruppur industrial belts host the fastest-growing group captive installations for textile and engineering consumers.
Karnataka
Engineering and automotive manufacturers execute group captive arrangements under eased banking regulations. The state's renewable energy policy exempts transmission charges for solar projects commissioned before 2025. Bengaluru's commercial real estate stock drives BIPV pilot programs in urban retrofit applications.
Maharashtra
MSEDCL net-metering frameworks mature across Mumbai and Pune metropolitan regions. The state's solar policy targets 40 GW capacity by 2030 through utility-scale and distributed generation pathways. Nagpur and Aurangabad industrial zones concentrate open-access demand from cement and steel consumers.
India Solar Energy Market Competitive Environment
Global majors compete with regional champions across module technology and project development capabilities. The market structures around three tiers: integrated manufacturers with captive cell capacity, pure-play project developers with land banking advantages, and state-owned utilities with preferential transmission access. Strategic moves concentrate on backward integration into wafer processing and gigawatt-scale land aggregation in Rajasthan and Gujarat.
Among domestic integrated manufacturers, Waaree Energies and Vikram Solar exemplify the captive cell production archetype, while Adani Green Energy occupies the renewable energy park development tier. Tata Power Solar anchors the utility-scale EPC and project ownership segment. These three entities represent distinct competitive positions shaped by PLI scheme eligibility and land banking tenure in western Indian solar corridors.
| Leading Market Players |
|---|
| Tata Power Solar |
| Vikram Solar |
| Waaree Energies |
| KPI Green Energy |
| Premier Energies |
| Adani Green Energy |
| NHPC |
| JSW Energy |
| NTPC Green Energy |
| Others |
Value Chain & Pricing Dynamics
Captive polysilicon-to-module integration anchors both supply security and pricing power for Indian manufacturers navigating the PLI scheme's domestic content mandates. This backward integration choice hardens cost structures against imported feedstock volatility while compressing margins for competitors reliant on East Asian wafer suppliers.
Pricing Analysis
Imported polysilicon cost pass-through dominates module pricing dynamics, with domestic manufacturers absorbing volatility from concentrated East Asian suppliers. Pricing stratifies across PLI-compliant domestic tiers, BIS-certified import alternatives, and uncertified economy options. Cost compression in polycrystalline modules is intensifying as monocrystalline technology displaces legacy capacity. Industrial offtakers in Rajasthan's solar parks exhibit lowest price sensitivity, prioritizing land-use efficiency over capital cost.
Supply Chain Analysis
Direct-to-utility procurement channels handle gigawatt-scale project demand from NTPC Vidyut Vyapar Nigam and SECI tenders. Geographic supply concentration centers on China, South Korea, and domestic Indian facilities for polysilicon, wafers, and cell processing. Raw material dependencies include metallurgical-grade silicon, silver paste for metallization, and aluminum frames. Single-source vulnerability in polysilicon ingot supply creates tariff exposure under DGFT import duty structures. Distribution runs through EPC contractors with nationwide execution footprints for utility-scale deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India solar market functions as a regulatory compounder where PLI scheme eligibility windows and BIS certification mandates continuously reshape competitive access. MNRE's National Solar Mission capacity targets drive demand visibility across the projection horizon.
For Market Incumbents: Acquire land banking portfolios in Gujarat and Rajasthan to lock in gigawatt-scale project development rights before state revenue department clearances tighten. Secure captive wafer processing equipment under PLI scheme windows to defend margin pools against pure-play module assemblers. Prioritize backward integration into cell manufacturing to reduce polysilicon price volatility exposure.
For New Entrants and Emerging Players: Commercial rooftop installers in Maharashtra and Tamil Nadu represent the most penetrable buyer archetype as DISCOM net-metering frameworks mature. Target group captive structures for textile and engineering consumers in Coimbatore and Tiruppur industrial belts. Deploy distributed generation offerings through TANGEDCO interconnection pathways to bypass utility-scale land aggregation complexity.
For Investors and Strategic Acquirers: Roll-up economics work for regional EPC specialists with established state-level regulatory relationships because fragmented project development capabilities command scarcity premiums. Long-term viability hinges on manufacturing assets with PLI scheme approval and secured polysilicon offtake agreements. Watch CEA grid connectivity sequencing announcements as inflection indicators for commercial operation date realization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wafer Processing | PLI scheme eligibility hardens cost structures against imported polysilicon volatility for domestic manufacturers. |
| Gigawatt-Scale Land Banking | Rajasthan and Gujarat solar park development rights anchor utility-scale project pipelines for NTPC tenders. |
| BIS Certification Investment | Quality standard compliance unlocks domestic procurement channels while disqualifying lower-cost import alternatives. |
| Hybrid Solar-Plus-Storage Deployment | String inverter battery interfaces address evening peak demand for industrial open-access consumers in Tamil Nadu. |
| Commercial Rooftop Channel Expansion | Net-metering framework maturation across Maharashtra accelerates distributed generation for retail and office segments. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both installed capacity trajectories and regulatory implementation dynamics. Primary discussions with MNRE policy officers, NTPC project developers, EPC contractors, and DISCOM planning executives informed PLI scheme impact assessment. Secondary validation drew from CEA grid connectivity databases, SECI tender documentation, BIS certification registries, and MNRE capacity addition reports. Bottom-up project pipeline analysis and top-down policy target reconciliation provided cross-verification.
Comparable historical periods anchored the forecast window to pre-PLI and post-PLI implementation phases across the analysis window. Segmentation modeling incorporated technology architecture, installation scale, end-user category, and state-level regulatory framework dimensions. CAGRs derived from capacity addition run-rates and project commissioning timelines. Forecast inputs included polysilicon price trajectories, land availability constraints, and CEA evacuation infrastructure sequencing.
Inputs from MNRE policy circulars and SECI tender awards were available through the study window; gaps in DISCOM net-metering settlement data introduce uncertainty bands for distributed generation forecasts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Smart Solar Solutions Market
Solar Power Systems
Solar Power Market
Solar Power Systems
Non-Concentrating Solar Collector Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
Thin Film Photovoltaic Modules Market
Solar Power Systems
Building Integrated Photovoltaics Module Market
Solar Power Systems
Global Rooftop Solar Photovoltaic Market
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
Biohybrid Solar Cell Market
Solar Power Systems
UV Solar Simulators Market
Solar Power Systems
Middle East and Africa Solar PV Inverters Market
Solar Power Systems
Graphene Solar Cell Market
Solar Power Systems
Iran Solar Energy Market
Solar Power Systems
Home Solar System Market
Solar Power Systems
Tubular Solar Collector Market