
 Thermal Power Valve Market | 2026-2036
Thermal Power Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Power Valve Market Insights
Utility procurement consolidation among independent power producers is restructuring long-term valve supply agreements across emerging markets. Emerson Electric Co. leverages its digital valve positioning systems to capture predictive maintenance contracts. Flowserve Corporation anchors its position through captive foundry capacity for superalloy castings. KSB SE & Co. KGaA competes on large-diameter gate valve engineering for ultra-supercritical steam conditions.
Thermal power valves regulate high-temperature, high-pressure steam and feedwater circuits in fossil-fuel and concentrated solar thermal plants, typically rated for service above 540 degrees Celsius and pressure classes exceeding ASME 2500. Globe valves dominate supercritical steam throttling applications where precise flow modulation prevents thermal fatigue in turbine inlet piping. Alloy steel constructions represent the fastest-growing material category as plants shift from carbon steel to chromium-molybdenum grades for creep resistance at elevated temperatures. The power generation end user segment commands the deepest margin pool due to extended qualification cycles and OEM-specified spare parts protocols.
ASME Boiler and Pressure Vessel Code Section I governs valve design for thermal power service in the United States, while the EU Pressure Equipment Directive and ISO 10434 shape market access across Europe and global export channels. China's SAMR enforces GB standards for domestic power plant equipment, creating parallel certification requirements for foreign suppliers. Stakeholders must monitor regulatory divergence between national pressure equipment codes and emerging hydrogen co-firing compatibility standards.
Market Dynamics
Superalloy material upgrades are restructuring supplier economics as thermal power operators face creep-resistance thresholds beyond chromium-molybdenum grades. Foundry capacity constraints and ASME qualification cycles are compressing vendor margins while extending procurement timelines for critical steam circuit components.
Growth Catalysts
- Ultra-supercritical steam conditions:Power plants operating above 600 degrees Celsius require valve constructions with enhanced creep rupture strength. Alloy steel demand accelerates as operators replace carbon steel installations.
- China's SAMR certification mandates:Domestic GB standards enforcement creates captive demand for locally qualified valve suppliers. Foreign manufacturers must establish parallel certification pathways.
- India's CEA refurbishment directives:Aging coal-fired infrastructure triggers replacement cycles for high-pressure steam valves. State electricity boards consolidate procurement under technical specifications.
Market Restraints
- Nickel superalloy input volatility:Inconel and Hastelloy feedstock price swings compress foundry margins. Long-term supply agreements lock in material costs eighteen months ahead of delivery.
- European foundry concentration:Superalloy casting capability clusters in Germany and Italy. Geographic supply density creates vulnerability to energy cost shocks and logistics disruptions.
- Hydrogen embrittlement limitations:Existing valve sealing technologies face compatibility gaps with hydrogen co-firing blends. Material science lag delays retrofit deployment timelines.
Strategic Opportunities
- Saudi Arabia's gas turbine expansion:Greenfield combined-cycle plants require large-diameter gate valves for steam bypass systems. Local content rules favor joint ventures with established European suppliers.
- Digital valve positioning convergence:Integration of edge computing with pneumatic actuators enables real-time cavitation monitoring. Predictive maintenance contracts displace traditional spare parts revenue models.
- US IRA clean hydrogen incentives:Tax credits for hydrogen-ready power plants accelerate valve specification reviews. OEMs embed hydrogen compatibility into new turbine inlet designs.
Industry Challenges
- ASME Section I welder certification scarcity:Qualified technicians for high-pressure steam valve repair retire faster than training programs replenish. Field service capacity constraints extend outage durations.
- Legacy DCS integration complexity:Modern digital positioners require protocol translation for 1990s-era distributed control systems. Retrofit engineering consumes project margins.
- Dual carbon goal compliance timelines:China's MEE enforcement compresses plant upgrade windows. Valve procurement must synchronize with turbine overhaul schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Power Valve Market |
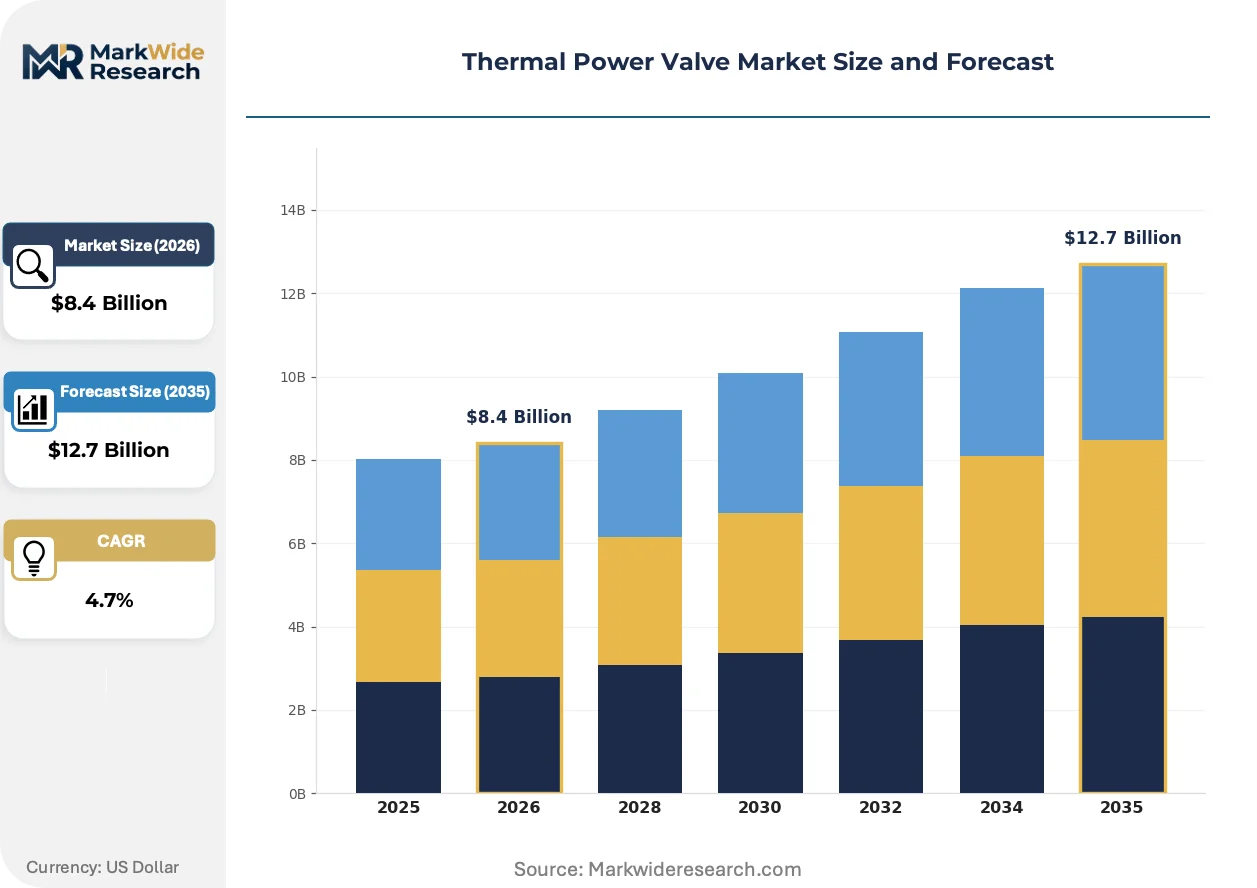
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.7 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Valve Type: Globe Valve, Gate Valve, Ball Valve, Check Valve Material: Carbon Steel, Stainless Steel, Alloy Steel, Bronze End User: Power Generation, Oil & Gas, Industrial, Marine Size: Low Size, Medium Size, Large Size, Extra Large |
| Companies Covered | Emerson Electric Co., Flowserve Corporation, Crane Company, KITZ Corporation, IMI plc, Schlumberger Limited, Curtiss-Wright Corporation, Valmet Oyj, KSB SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Power Valve Market Trends and Innovations
Additive manufacturing is penetrating superalloy valve component production, enabling geometries impossible through conventional investment casting. Foundries and power plant operators are recalibrating spare parts strategies around this capability.
Directed energy deposition is decentralizing repair workflows for turbine inlet valve seats. Maintenance contractors at coal-fired plants in India and China are adopting mobile metal deposition units. Field refurbishment cycles compress from weeks to days, reducing turbine outage penalties.
The EU F-Gas Regulation is accelerating pneumatic actuator replacement with electromechanical alternatives. Valve positioners using synthetic refrigerants face phase-out deadlines by 2030. European power utilities are specifying all-electric control packages for new ultra-supercritical installations.
Independent power producers are unbundling valve maintenance from OEM service contracts. Third-party specialists with SAMR and ASME dual qualifications are capturing refurbishment volume. This pattern concentrates in China's provincial generation companies seeking cost arbitrage against foreign OEM rates.
Thermal Power Valve Market Segmentation
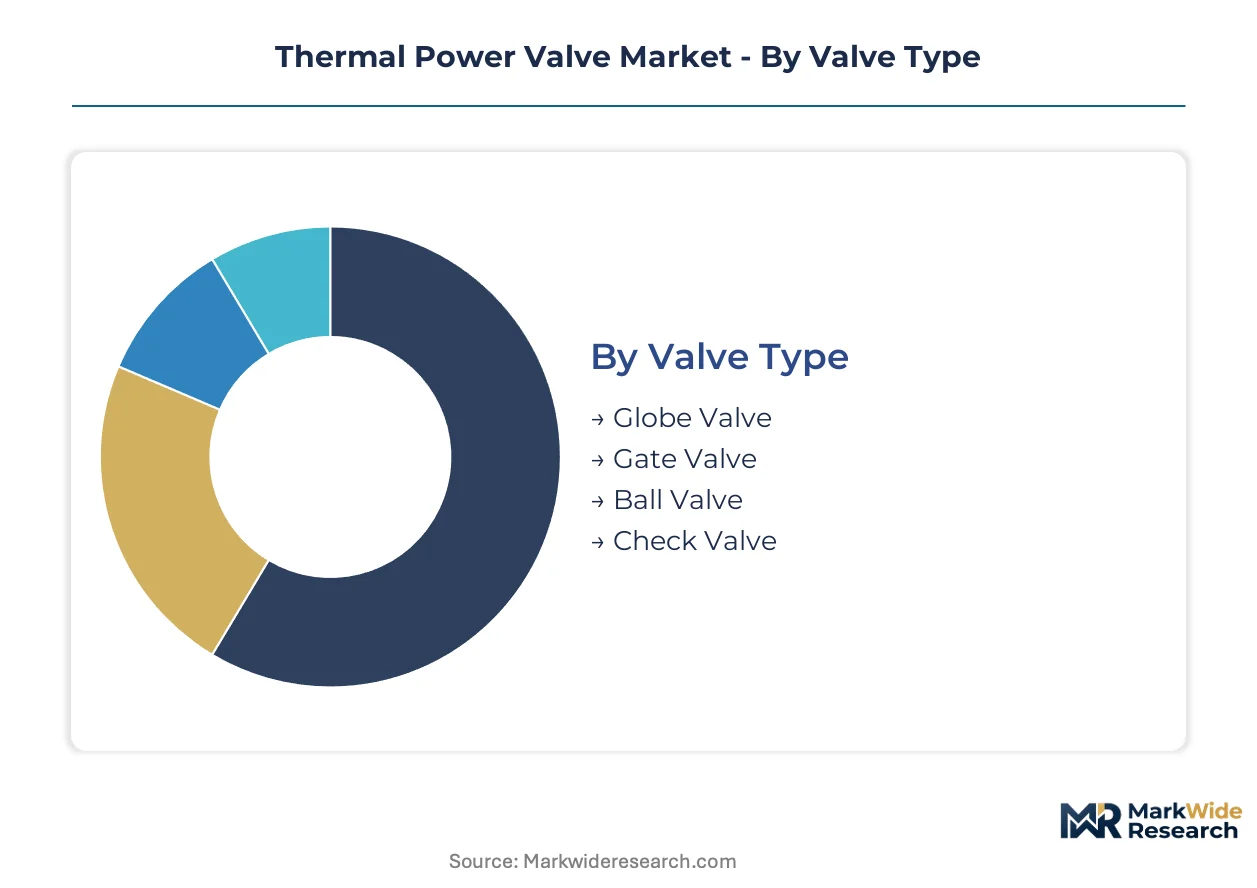
Thermal power valve procurement patterns diverge sharply across valve type, material grade, and end-use application. Equipment replacement cycles and technology upgrades create distinct demand pockets that suppliers must map precisely to capture margin.
Valve Type:
Upgrade cycles for high-pressure steam service are reshaping valve type demand, with precise flow control requirements driving specification changes across plant vintages.
- Globe Valve:Engineered for throttling service in supercritical steam lines where precise flow modulation prevents thermal fatigue damage. Demand concentrates in turbine inlet piping retrofits across China's provincial power companies as SAMR-enforced GB standards mandate creep-resistant constructions.
- Gate Valve:Designed for full-flow isolation in steam bypass and feedwater systems with minimal pressure drop. Large-diameter specifications dominate procurement for Saudi Arabia's greenfield combined-cycle plants where local content rules favor joint venture supply structures.
- Ball Valve:Quarter-turn operation suits auxiliary steam and drain applications with rapid cycling requirements.
- Check Valve:Passive flow prevention protects pumps and turbines from reverse flow damage in feedwater circuits.
Globe valves sit at the top of the volume ranking, with gate valves climbing the fastest.
Material:
Material specification decisions hinge on temperature-pressure thresholds, with creep resistance requirements accelerating grade migration across installed base refurbishment.
- Alloy Steel:Chromium-molybdenum grades deliver creep rupture strength for service above 540 degrees Celsius in ultra-supercritical conditions. India's CEA refurbishment directives are accelerating replacement of carbon steel installations at aging state electricity board plants.
- Carbon Steel:Baseline material for low-pressure auxiliary services and pre-2000 plant installations now facing upgrade pressure.
- Stainless Steel:Corrosion resistance suits feedwater and condensate applications where oxygen scavenging is incomplete.
- Bronze:Seawater cooling and low-pressure marine applications leverage galling resistance and machinability.
Alloy steel commands the deepest margin pool, with carbon steel losing share fastest to upgrade-driven replacement.
End User:
End-user procurement sophistication varies dramatically, with qualification cycles and spare parts protocols creating divergent competitive dynamics.
- Power Generation:Fossil-fuel and concentrated solar thermal plants specify ASME Section I or GB-compliant valves for high-pressure steam service. Extended OEM qualification cycles and captive spare parts agreements protect incumbent supplier positions.
- Oil & Gas:Refinery and petrochemical steam systems require API 600/602 specifications with sour service NACE compliance.
- Industrial:Pulp, paper, and chemical process plants prioritize delivery speed over extended qualification for non-critical steam services.
- Marine:Naval and commercial vessel propulsion systems demand compact, vibration-resistant constructions with classification society approval.
Power generation anchors absolute demand value, with oil & gas expanding most quickly on petrochemical capacity additions.
Size:
Size classification maps directly to manufacturing capability requirements, with foundry capacity constraints concentrating supply for the largest pressure classes.
- Large Size:ASME 1500-2500 pressure class valves for main steam lines require captive superalloy foundry capacity. Flowserve Corporation's integrated casting operations anchor supply for this segment where European foundry concentration creates geographic vulnerability.
- Extra Large:Custom-engineered turbine bypass valves exceed standard catalog dimensions and demand project-specific forging partnerships.
- Medium Size:Standard catalog pressure classes dominate volume production for feedwater and auxiliary services.
- Low Size:Instrument and sampling valves leverage distributed machining capacity with minimal foundry dependence.
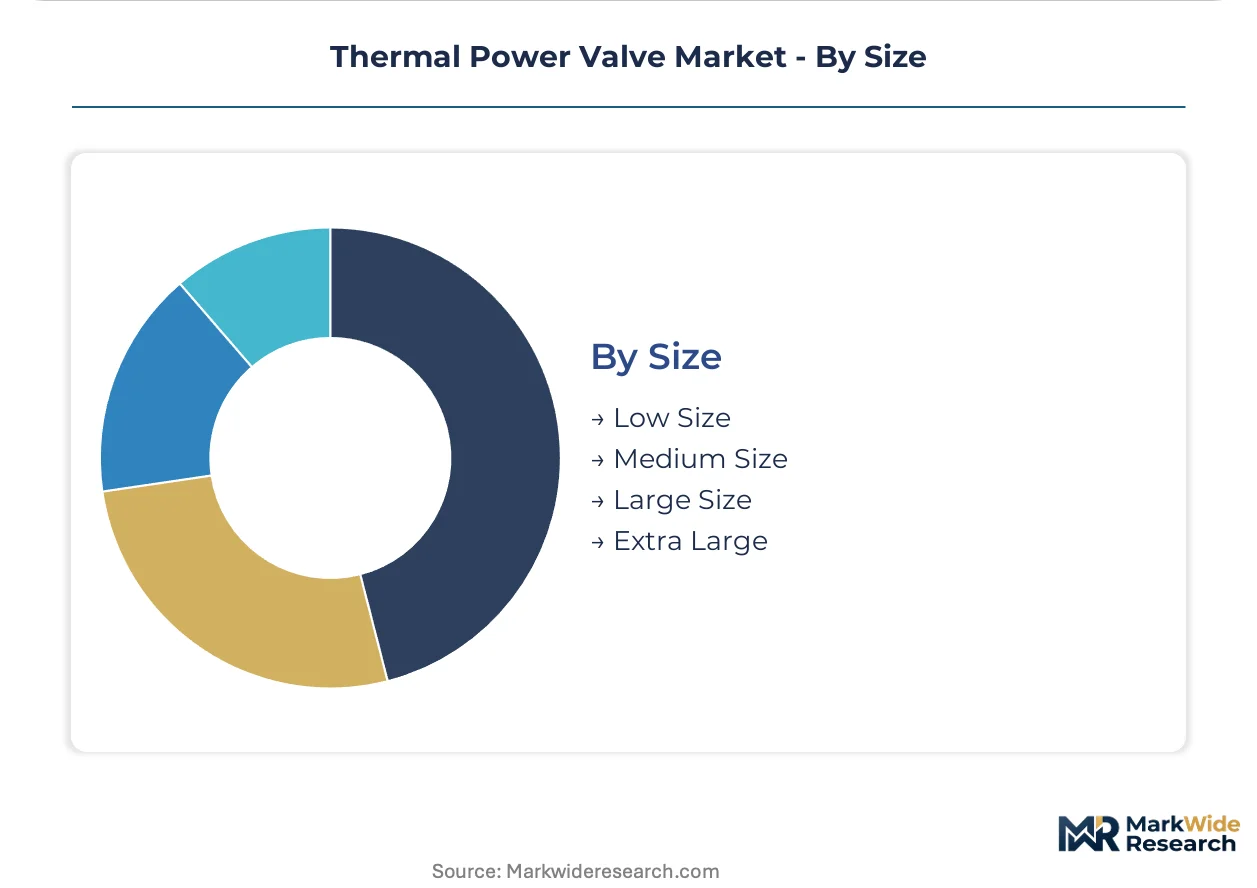
Medium size captures the widest unit volume, with large size gaining share fastest on ultra-supercritical plant commissioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's provincial power companies outpace India's state electricity boards in ultra-supercritical valve procurement, though both markets face parallel SAMR and CEA certification pressures. The United States leverages IRA incentives for hydrogen-ready retrofits while Saudi Arabia's combined-cycle expansion attracts joint venture suppliers. Germany's foundry concentration anchors European superalloy casting capacity.
China
Provincial generation companies in Shandong and Jiangsu drive globe valve demand for turbine inlet piping retrofits. SAMR-enforced GB standards mandate creep-resistant alloy steel constructions for plants operating above 540 degrees Celsius. Shanghai and Tianjin host captive foundry operations supplying chromium-molybdenum castings to domestic valve fabricators.
India
State electricity boards in Maharashtra and Tamil Nadu trigger replacement cycles for aging high-pressure steam valves at coal-fired installations. CEA refurbishment directives compress procurement timelines for critical feedwater circuit components. The Mundra and Mundra-Ultra Mega Power clusters concentrate maintenance contractor activity for field valve refurbishment.
United States
Independent power producers in Texas and the PJM interconnection specify hydrogen-compatible valve constructions for turbine inlet designs. IRA clean hydrogen tax credits accelerate specification reviews for hydrogen-ready power plant retrofits. Houston anchors aftermarket service capacity for ASME Section I-qualified valve repair and welder certification programs.
Saudi Arabia
Greenfield combined-cycle plants in the Eastern Province require large-diameter gate valves for steam bypass systems. Local content rules under Vision 2030 favor joint ventures between European suppliers and Saudi fabrication partners. Jubail Industrial City concentrates turbine maintenance infrastructure serving the Kingdom's gas turbine expansion pipeline.
Germany
Ultra-supercritical plant operators in North Rhine-Westphalia and Bavaria specify electromechanical actuator packages to comply with EU F-Gas Regulation phase-out deadlines. Foundry capacity for Inconel and Hastelloy castings clusters in the Ruhr region and southern industrial belt. Essen and Mannheim anchor captive superalloy casting operations supplying valve OEMs across Europe.
Thermal Power Valve Market Competitive Landscape
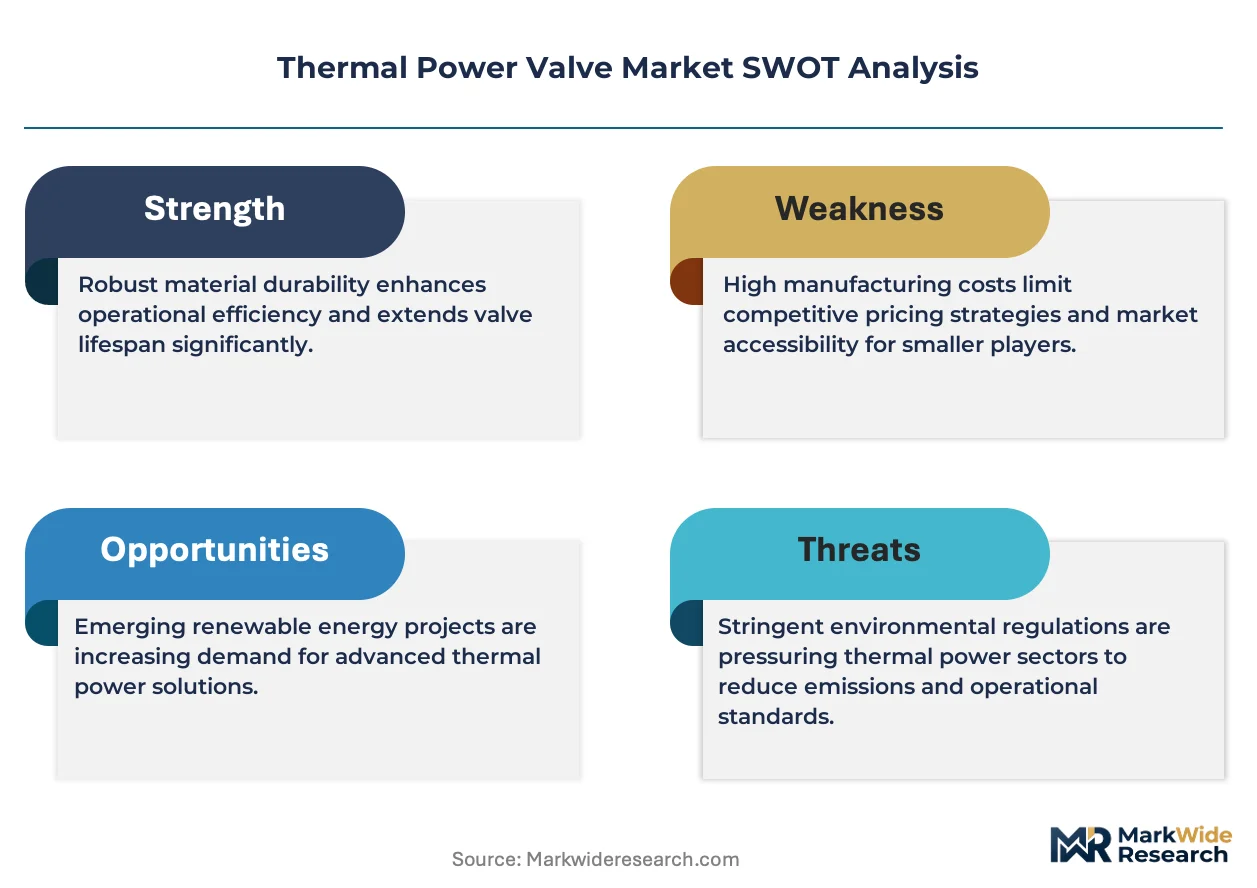
Diversified conglomerates compete with focused pure-play specialists across material grade and pressure class segments. The market structure exhibits tiered concentration: integrated multinationals with captive foundry capacity anchor large-size superalloy supply, while regional fabricators capture medium-pressure catalog volume. Strategic archetypes include backward-integrated casting specialists, digital positioning system developers, and third-party refurbishment contractors. Competitive moves center on predictive maintenance contract capture and SAMR/ASME dual qualification acquisition.
Among diversified industrial conglomerates, Emerson Electric Co. and Flowserve Corporation exemplify contrasting approaches to valve supply chain configuration. Emerson's positioning within digital valve technologies represents the predictive maintenance archetype, while Flowserve's captive foundry operations anchor the backward-integrated casting specialist model. KSB SE & Co. KGaA occupies a position within the large-diameter gate valve engineering tier for ultra-supercritical steam conditions.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Flowserve Corporation |
| Crane Company |
| KITZ Corporation |
| IMI plc |
| Schlumberger Limited |
| Curtiss-Wright Corporation |
| Valmet Oyj |
| KSB SE & Co. KGaA |
| Others |
Pricing and Supply Chain Analysis
ASME Section I certification tiers bifurcate the thermal power valve landscape into qualified and non-qualified supply pools, with this divergence manifesting in both pricing premiums for certified fabricators and geographic concentration of backward-integrated foundries. Superalloy material grades command margin structures that reflect captive chromium-molybdenum casting capacity, while carbon steel alternatives face procurement compression from India's CEA-mandated refurbishment cycles.
Pricing Analysis
Capacity additions in China's Shandong and Jiangsu provinces are reshaping price floors for globe valve retrofits as provincial generation companies consolidate procurement under SAMR-enforced GB standards. Three-tier pricing structure across premium, standard, and economy levels reflects ASME qualification status, superalloy grade specification, and aftermarket service bundling. Cost compression in economy-grade carbon steel installations is intensifying because India's state electricity boards accelerate replacement timelines. Independent power producers exhibit highest price sensitivity due to unbundled maintenance contracts, while ultra-supercritical plant operators accept premium positioning for creep-resistant alloy steel constructions.
Supply Chain Analysis
Single-source vulnerability sits with Germany's Ruhr region and southern industrial belt for Inconel and Hastelloy superalloy castings. Supply draws from foundry clusters in Germany, Italy, and captive operations in Shanghai and Tianjin. Nickel superalloy feedstock, chromium-molybdenum bar stock, and ASME-qualified welder labor pools represent critical input dependencies. Geographic supply density creates exposure to energy cost shocks and logistics disruptions across European casting capacity. Distribution runs through OEM-specified spare parts protocols for power generation end users, with third-party refurbishment contractors capturing volume in China's provincial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in thermal power valves rests on superalloy grade migration and predictive maintenance contract capture, with additive manufacturing compressing spare parts production costs for qualified fabricators.
For Market Incumbents: Cement ASME Section I welder certification programs in Houston and Essen to defend field service margins against third-party refurbishment contractors. Lock in eighteen-month nickel superalloy supply agreements to buffer Inconel feedstock volatility. Prioritize digital valve positioning integration with legacy DCS systems to capture predictive maintenance contracts displacing traditional spare parts revenue.
For New Entrants and Emerging Players: The premium-economy price gap in SAMR-qualified alloy steel globe valves opens procurement access for domestic Chinese fabricators with captive foundry capacity. Target India's Maharashtra and Tamil Nadu state electricity boards for high-pressure steam valve refurbishment where CEA directives compress replacement timelines. Pursue joint venture structures with Saudi fabrication partners under Vision 2030 local content rules for Eastern Province combined-cycle projects.
For Investors and Strategic Acquirers: Asymmetric upside sits with additive manufacturing specialists enabling directed energy deposition repair workflows for turbine inlet valve seats. Long-term viability favors dual ASME-GB qualified fabricators with captive superalloy casting capacity across the analysis window. Monitor hydrogen embrittlement material science breakthroughs as inflection indicator for hydrogen-ready valve specification cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Superalloy Foundry Investment | Backward integration into Inconel casting secures margin control for ASME 2500 pressure class supply. |
| Digital Valve Positioner Platform Launch | Edge computing integration with pneumatic actuators enables real-time cavitation monitoring for predictive contracts. |
| ASME-GB Dual Certification Acquisition | Parallel qualification pathways unlock procurement access to China's provincial generation companies. |
| Directed Energy Deposition Repair Deployment | Mobile metal deposition units compress turbine outage penalties from weeks to days at Indian coal plants. |
| Electromechanical Actuator Transition | EU F-Gas Regulation compliance positions suppliers for European ultra-supercritical installations. |
Research Methodology
Coverage spans China, India, the United States, Saudi Arabia, and Germany, with primary inputs from each market's power plant maintenance directors, valve procurement officers at independent power producers, ASME-qualified welder training program administrators, and superalloy foundry operations managers. Secondary validation draws from SAMR GB standard filings, CEA refurbishment directives, ASME Boiler and Pressure Vessel Code Section I documentation, and IRA clean hydrogen incentive program disclosures. Bottom-up unit demand modeling triangulates against top-down capacity installation forecasts across ultra-supercritical and combined-cycle plant categories.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions include valve type, material grade, end-user procurement sophistication, and pressure class tier. CAGRs derive from plant commissioning pipelines, regulatory enforcement timelines, and replacement cycle analysis. Forecast inputs incorporate SAMR certification mandate compliance rates and hydrogen co-firing retrofit specification reviews.
Caveats apply where nickel superalloy input volatility, ASME welder certification scarcity, or hydrogen embrittlement material science delays could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Solenoid Valves Market
Valves
Penstock Market
Valves
Steel Cylinder Market
Valves
Deluge Valve Market
Valves
Axial and Radial Seals Market
Valves
Ball Valves Market
Valves
Valve Seat Inserts Market
Valves
Explosion Vents Market
Valves
Flow Computer Market
Valves
Pipeline Pigging Equipment Market
Valves
Manual Control Valve Market
Valves
Sandblast Valves Market
Valves
Float Traps Market
Valves
Global Gate Valve Market
Valves
Pipeline Pigging Valves Market
Valves
Reciprocating Compressor Components Market