
 Europe Vacuum Insulated Pipe Market | 2026-2036
Europe Vacuum Insulated Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Vacuum Insulated Pipe Market Analysis
Multi-source procurement among cryogenic engineering contractors is broadening the vendor base for vacuum-insulated pipe systems across European industrial gas projects. Cryotherm GmbH and Co. KG leverages its German manufacturing footprint to anchor supply relationships with regional LNG terminal developers. CoreDux competes through specialized corrugated hose integration within VIP assemblies for space-constrained installations. Demaco Holland BV sustains its position via deep expertise in liquid helium transfer systems for scientific research facilities.
Europe vacuum insulated pipe consists of concentric pipe walls separated by a vacuum annulus, typically achieving thermal conductivity below 0.005 W/m·K through multi-layer insulation and getter materials, engineered to minimize heat ingress during transport of cryogenic fluids such as liquid nitrogen, oxygen, or hydrogen. Custom pipe configurations command premium positioning due to project-specific dimensional requirements in nuclear fusion research and space launch infrastructure. Stainless steel material grades dominate structural segments for corrosion resistance in marine LNG bunkering applications, while composite material variants represent the fastest-growing category as weight reduction becomes critical in aerospace fueling systems.
CE marking under the EU Pressure Equipment Directive governs market access, with ECHA REACH compliance additionally restricting certain insulation chemistries in vacuum spaces. The EU Green Deal hydrogen backbone initiative channels investment toward large-diameter VIP corridors connecting Iberian hydrogen hubs to Central European offtakers. Stakeholders must monitor whether the EU AI Act inspection protocols extend to automated welding quality systems used in VIP fabrication.
Market Dynamics
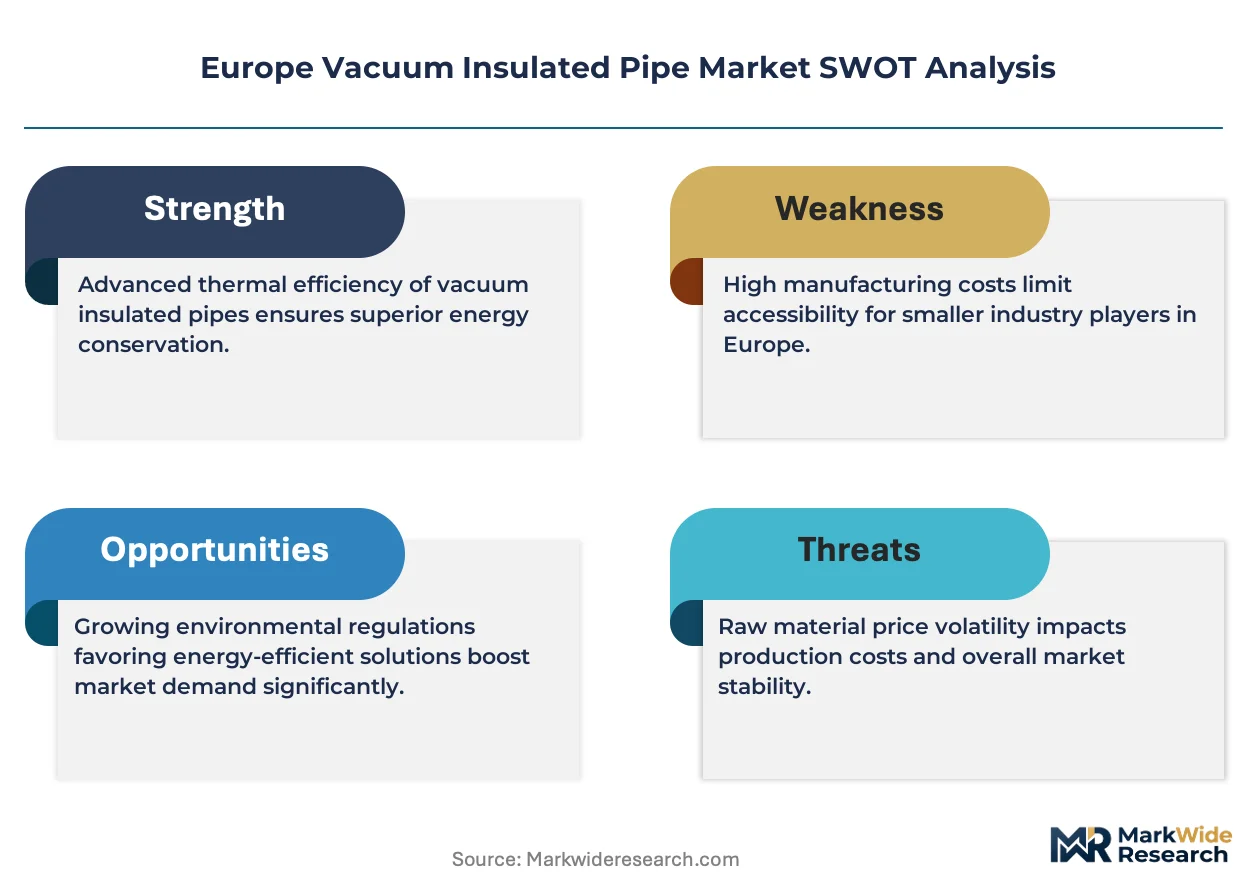
The EU F-Gas Regulation is compressing deployment timelines for legacy foam-insulated cryogenic lines while accelerating specification switches toward vacuum-insulated alternatives across LNG bunkering and hydrogen liquefaction infrastructure.
Growth Catalysts
- Hydrogen liquefaction pilots:German industrial clusters are installing large-diameter VIP corridors to connect hydrogen hubs to Central European offtakers, creating anchor demand for specialized fabrication capacity.
- EU Green Deal hydrogen backbone:The initiative channels public investment toward cross-border cryogenic transport networks, mandating thermal performance standards that favor vacuum insulation over conventional alternatives.
- Stainless steel corrosion resistance:Marine LNG bunkering operators specify 316L-grade VIP assemblies for saltwater exposure, expanding addressable demand in North Sea and Mediterranean port infrastructure.
Market Restraints
- Specialized welding labor scarcity:Automated orbital welding for vacuum-tight joints requires certified technicians concentrated in Germany and the Netherlands, constraining project ramp rates.
- Multi-layer insulation material costs:Aluminum-polyester laminate and glass paper composites face price volatility tied to aerospace sector demand cycles, compressing fabricator margins on fixed-price contracts.
- CE marking timeline under PED:The EU Pressure Equipment Directive certification process extends lead times by 4-6 months for custom VIP configurations, delaying revenue recognition on nuclear fusion research orders.
Strategic Opportunities
- Spain-Portugal hydrogen corridor underdevelopment:Iberian hydrogen hub projects lack established VIP supplier relationships, creating first-mover positioning for contractors with large-diameter fabrication capability.
- Scientific research liquid helium systems:Nuclear fusion facilities and particle accelerators require ultra-low heat ingress specifications that command premium pricing and long-term service contracts.
- Composite material weight reduction:Aerospace fueling system integrators are qualifying carbon-fiber-reinforced VIP variants for space launch infrastructure, opening a faster-growing material segment.
Industry Challenges
- Getter material activation protocols:Vacuum maintenance during field installation requires specialized technician training that outpaces current certification program throughput in Eastern Europe.
- Legacy LNG terminal retrofit integration:Aging transfer infrastructure uses incompatible flange standards and support spacing, forcing costly custom engineering on brownfield VIP deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Vacuum Insulated Pipe Market |
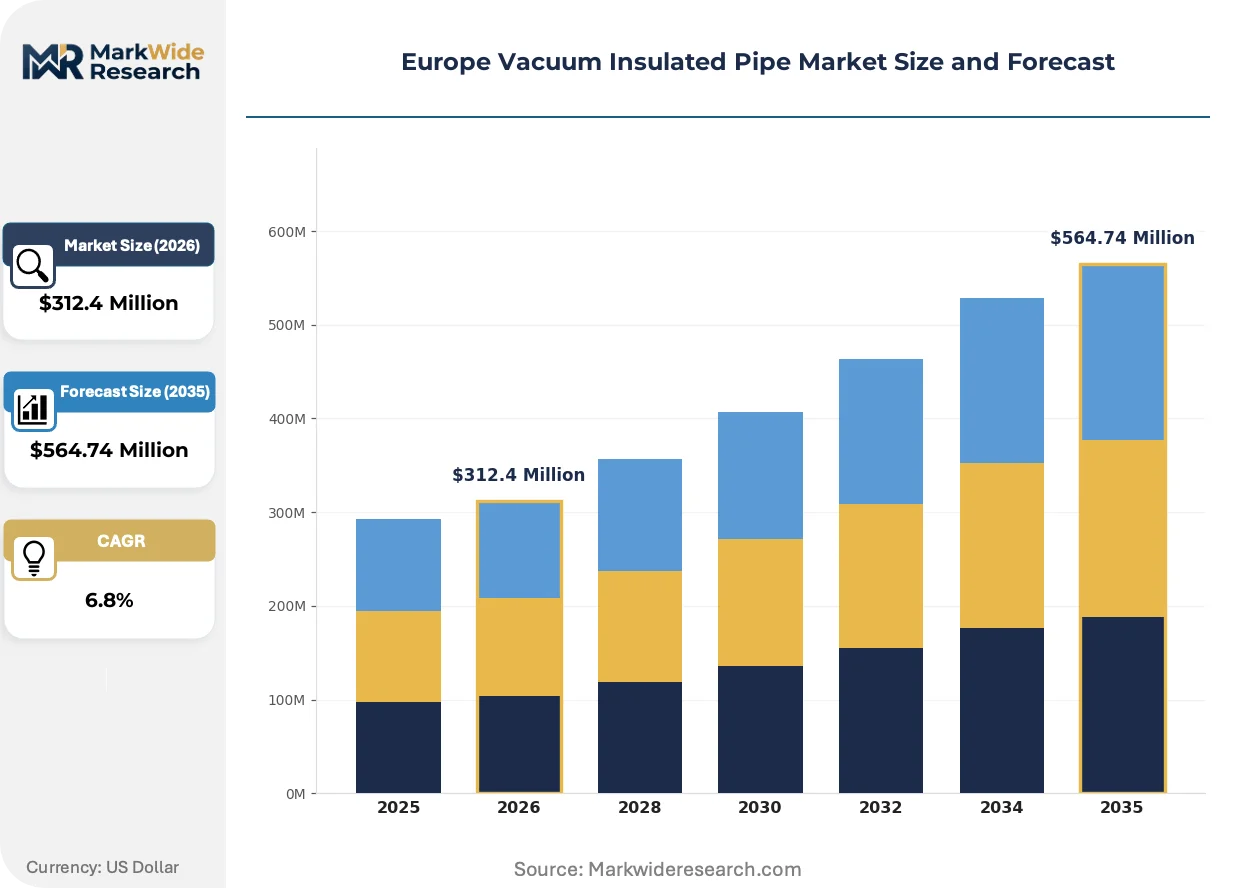
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pipe, Custom Pipe, Pre-Insulated Pipe, Specialty Pipe Material: Stainless Steel, Carbon Steel, Copper, Composite Application: Industrial Heating, Cryogenic Systems, District Heating, Refrigeration End User: Food & Beverage, Oil & Gas, Chemical Processing, Power Generation |
| Companies Covered | CRIOTEC Impianti srl, CoreDux, Air Liquide, Demaco Holland BV, TMK, Taylor-Wharton, KrioSystem, Cryotherm GmbH and Co. KG, CRYOTHERM, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Vacuum Insulated Pipe Market Emerging Trajectories
Modular fabrication methods are compressing on-site installation timelines while automated quality inspection systems are reshaping certification workflows for cryogenic pressure equipment.
Corrugated stainless steel bellows with integrated vacuum annulus are modularizing field assembly for space-constrained installations. Nuclear fusion research facilities and urban hydrogen fueling stations specify these pre-fabricated segments to minimize welding in restricted access zones. The approach is modularizing project delivery timelines from 18-month cycles toward 6-8 month deployments.
The EU AI Act inspection protocol proposals are extending toward automated welding quality systems used in VIP fabrication. Machine vision defect detection during orbital welding is gaining regulatory attention as a candidate for mandatory third-party validation. German fabricators with existing robotic welding cells face adaptation costs to document algorithmic decision trails for notified body review.
Engineering-procurement-construction contractors are consolidating cryogenic system sourcing under single-responsibility contracts. Industrial gas majors now specify VIP supply as part of integrated liquefaction-skid packages, displacing standalone pipe procurement. This bundling is most visible in Dutch and Belgian port hydrogen projects where terminal operators lack in-house cryogenic engineering expertise.
Europe Vacuum Insulated Pipe Market Segmentation
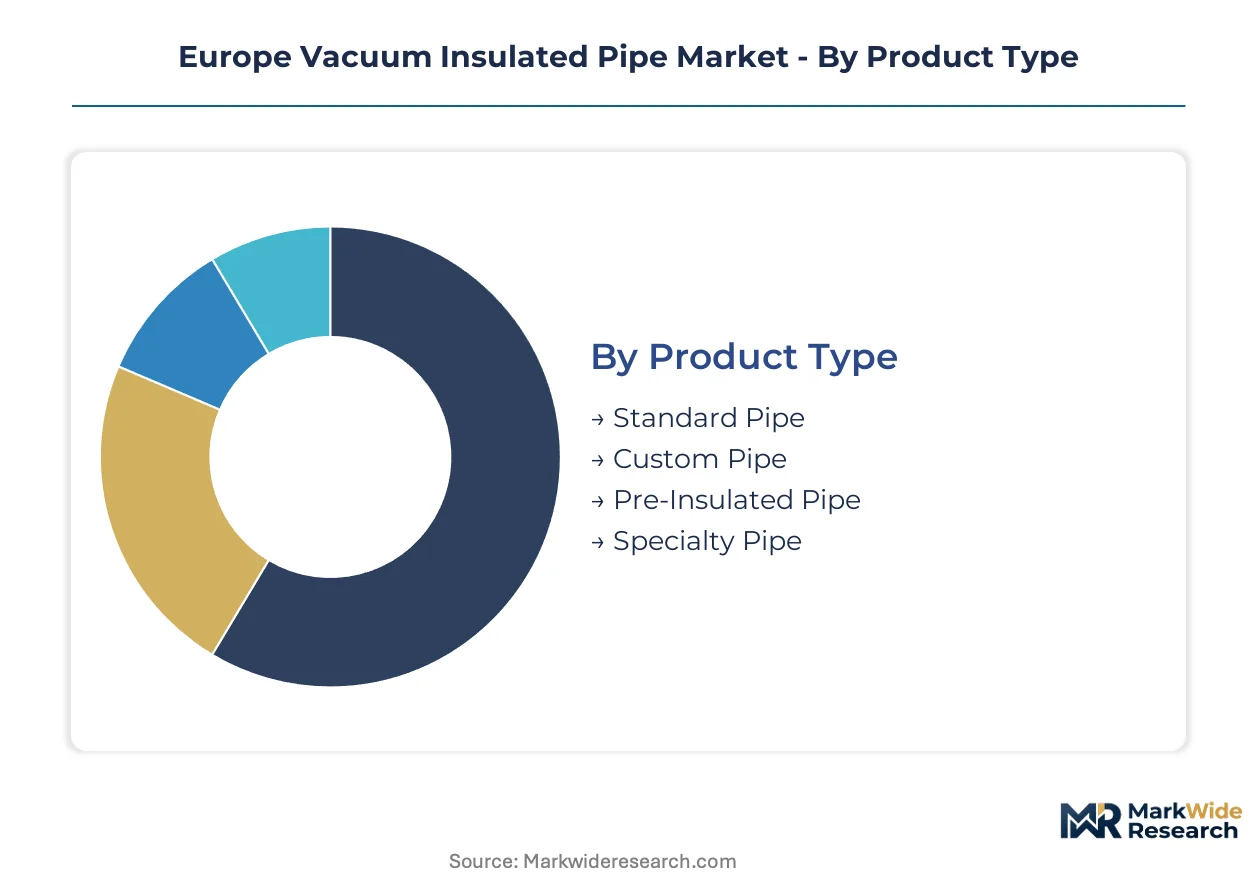
Vacuum insulated pipe procurement patterns diverge sharply across European industrial clusters. Specification requirements in German hydrogen liquefaction pilots differ fundamentally from Mediterranean LNG bunkering contracts or CERN helium transfer systems.
Product Type:
Cost tier separates project winners from commodity bidders in European cryogenic infrastructure tenders.
- Standard Pipe:Fixed-dimension VIP assemblies with pre-engineered vacuum annulus geometry serve high-volume industrial gas distribution. German chemical parks in Ludwigshafen and Leuna specify these for liquid nitrogen feedstock lines where routing follows established corridors.
- Custom Pipe:Project-specific dimensional configurations with tailored multi-layer insulation density address nuclear fusion research and space launch infrastructure. ITER in southern France and ArianeGroup facilities in French Guiana drive specification complexity that commands fabrication premiums.
- Pre-Insulated Pipe:Factory-sealed vacuum assemblies reduce field welding requirements for urban hydrogen fueling stations.
- Specialty Pipe:Corrugated geometries with integrated expansion joints serve seismic zones and shipboard LNG bunkering.
Standard pipe leads volumes today; custom pipe is gaining share fastest.
Material:
Application environment dictates corrosion resistance requirements across marine, aerospace, and terrestrial installations.
- Stainless Steel:316L-grade austenitic alloys dominate saltwater-exposed LNG bunkering infrastructure. Rotterdam and Barcelona terminal operators mandate this specification for jetty transfer lines where chloride exposure exceeds 10,000 ppm annually.
- Composite:Carbon-fiber-reinforced polymers achieve 60% weight reduction versus metallic equivalents. ArianeGroup and ESA launch facilities in Kourou drive qualification programs for aerospace fueling systems where payload mass directly determines mission economics.
- Carbon Steel:Cost-sensitive district heating retrofits in Eastern Europe specify epoxy-coated variants for above-ground routing.
- Copper:High thermal conductivity suits small-diameter instrumentation lines in scientific research cryostats.
Stainless steel anchors current procurement volumes; composite materials show the steepest expansion trajectory.
Application:
Thermal performance thresholds separate specification winners from commodity alternatives in European energy transition infrastructure.
- Cryogenic Systems:Liquid hydrogen at 20 Kelvin and liquid helium at 4 Kelvin demand thermal conductivity below 0.005 W/m·K. German hydrogen backbone corridors and ITER tokamak cooling loops specify vacuum insulation exclusively where foam alternatives fail performance thresholds.
- District Heating:Fourth-generation low-temperature networks in Denmark and Sweden deploy VIP for seasonal thermal storage transfer. Aarhus and Copenhagen municipal utilities specify these for 70°C supply lines where conventional insulation bulk constrains urban routing.
- Industrial Heating:High-temperature process integration remains limited by vacuum envelope materials.
- Refrigeration:Cold chain logistics in Netherlands food processing clusters specify modular VIP for flexible layout reconfiguration.
Cryogenic systems dominate revenue concentration; district heating climbs fastest as Nordic cities retrofit networks.
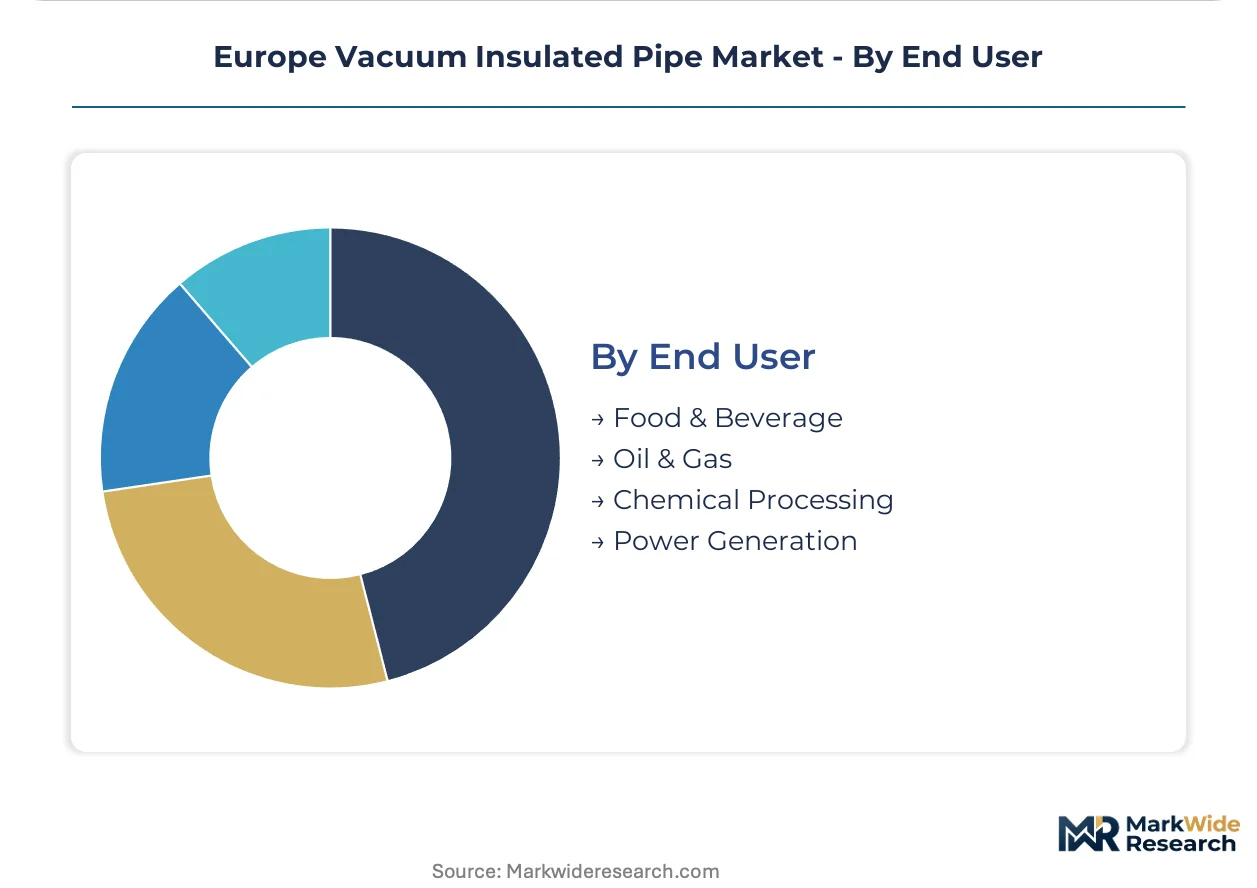
End User:
Project scale and technical capability determine whether buyers self-specify or delegate to EPC contractors.
- Oil & Gas:LNG terminal operators in Zeebrugge, Dunkirk, and Revithoussa possess in-house cryogenic engineering teams that draft detailed VIP specifications. These buyers negotiate directly with fabricators rather than delegating to system integrators.
- Food & Beverage:Industrial gas majors supply packaged liquefaction skids where VIP is bundled rather than procured standalone. Air Liquide and Linde specify integrated transfer lines for European carbonated beverage bottlers lacking cryogenic expertise.
- Chemical Processing:German BASF and Bayer sites in Ludwigshafen and Leverkusen maintain captive specification teams for olefin plant cryogenic separation units.
- Power Generation:Nuclear fusion research facilities represent concentrated demand for ultra-low heat ingress specifications.
Oil and gas commands the largest contract values; power generation shows the most rapid specification growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial clusters along the Rhine and Ruhr corridors generate the densest concentration of vacuum insulated pipe procurement in Europe. Hydrogen liquefaction pilots and chemical park retrofits anchor demand across multiple federal states. CE marking under the EU Pressure Equipment Directive governs cross-border equipment flows, while the EU F-Gas Regulation accelerates specification shifts away from foam-insulated alternatives.
Germany
Ludwigshafen and Leuna chemical parks specify standard-dimension VIP assemblies for liquid nitrogen feedstock distribution. The EU Green Deal hydrogen backbone channels federal funding toward large-diameter corridors connecting North Sea ports to Bavarian industrial zones. Bavarian hydrogen liquefaction pilots in Ingolstadt and Burghausen create anchor demand for specialized fabrication capacity serving Central European offtakers.
Netherlands
Rotterdam terminal operators mandate 316L-grade stainless VIP for jetty transfer lines exposed to North Sea chloride concentrations. The Dutch national hydrogen strategy aligns with EU Green Deal targets, prioritizing low-emission thermal insulation in port infrastructure retrofits. Eindhoven-region engineering contractors bundle VIP procurement within integrated liquefaction-skid packages for hydrogen fueling station deployments.
France
ITER tokamak cooling loops in southern France command custom VIP configurations with ultra-low heat ingress specifications below 0.005 W/m·K. ECHA REACH compliance restricts certain insulation chemistries in vacuum spaces, affecting multi-layer insulation material selection. ArianeGroup facilities in French Guiana drive qualification programs for carbon-fiber-reinforced VIP variants in aerospace fueling systems.
Spain
Barcelona LNG terminal operators specify corrosion-resistant VIP assemblies for Mediterranean saltwater exposure exceeding 10,000 ppm annual chloride levels. Iberian hydrogen hub projects under the EU Green Deal framework lack established supplier relationships, creating first-mover positioning opportunities. Valencia and Algeciras port authorities evaluate large-diameter VIP corridors for hydrogen export infrastructure to Central European markets.
Belgium
Zeebrugge LNG terminal operators maintain in-house cryogenic engineering teams that draft detailed VIP specifications for direct fabricator negotiation. The EU F-Gas Regulation compresses deployment timelines for legacy foam-insulated transfer lines in coastal infrastructure. Antwerp chemical cluster demand concentrates on standard pipe configurations for established liquid nitrogen and oxygen distribution corridors.
Europe Vacuum Insulated Pipe Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized corrugated geometries and composite material variants. The vendor base stratifies across German manufacturing anchors, Dutch engineering specialists, and Italian system integrators. Three archetypes dominate: integrated industrial gas majors bundling VIP within liquefaction skids, dedicated cryogenic fabricators with captive welding certification capacity, and corrugated hose specialists addressing space-constrained installations. Capacity expansion and strategic partnerships represent the dominant competitive vectors as hydrogen infrastructure timelines compress.
Among Germany-based fabricators, Cryotherm GmbH and Co. KG anchors supply relationships with regional LNG terminal developers through its manufacturing footprint in the southwestern industrial belt. Dutch specialist Demaco Holland BV exemplifies the scientific research tier, occupying a position tied to liquid helium transfer systems for nuclear fusion and particle accelerator facilities. CoreDux represents the corrugated integration archetype, sitting within the space-constrained installation segment through specialized hose assemblies. These three entities illustrate the geographic and technical stratification shaping procurement decisions across European cryogenic infrastructure projects.
| Leading Market Players |
|---|
| CRIOTEC Impianti srl |
| CoreDux |
| Air Liquide |
| Demaco Holland BV |
| TMK |
| Taylor-Wharton |
| KrioSystem |
| Cryotherm GmbH and Co. KG |
| CRYOTHERM |
| Others |
Supply Flow & Price Mechanics
Modular fabrication methods are compressing project delivery timelines from 18-month cycles toward 6-8 month deployments while simultaneously concentrating supply relationships among German and Dutch fabricators with certified orbital welding capacity. This production-method transition simultaneously reshapes cost economics and supply concentration, as EPC contractors consolidate cryogenic system sourcing under single-responsibility contracts that favor integrated suppliers over standalone pipe vendors.
Pricing Analysis
Input-cost pass-through from aluminum-polyester laminate and glass paper composites drives pricing volatility in multi-layer insulation materials, compressing fabricator margins on fixed-price contracts. Three-tier pricing structure across premium, standard, and economy levels separates custom nuclear fusion configurations from standard chemical park assemblies. Price differentiation hinges on CE marking tier under the EU Pressure Equipment Directive and volume scale of hydrogen corridor deployments. Cost compression in standard pipe tiers is intensifying because aerospace sector demand cycles for MLI materials create supply competition. Food and beverage buyers bundled within liquefaction skids show lowest price sensitivity; Eastern European district heating retrofits exhibit highest.
Supply Chain Analysis
Stainless steel 316L-grade supply rests on German, Italian, and Swedish specialty metal producers serving marine LNG bunkering specifications. Carbon-fiber-reinforced polymer feedstock draws from aerospace-qualified suppliers in France and Germany. Getter materials for vacuum maintenance hinge on Japanese and US specialty chemical producers. Single-source vulnerability concentrates in certified orbital welding technicians concentrated in Germany and the Netherlands. Distribution runs through EPC contractors bundling VIP within integrated liquefaction-skid packages for hydrogen infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation operates as a regulatory compounder, compressing deployment timelines for legacy foam-insulated cryogenic lines while mandating thermal performance standards that favor vacuum insulation alternatives.
For Market Incumbents: To counter specialized welding labor scarcity constraining project ramp rates, anchor capacity expansion in German and Dutch certification clusters while securing captive supply relationships for aluminum-polyester laminate MLI materials. Backward integration into getter material activation training programs addresses Eastern European technician certification gaps threatening field installation quality. For New Entrants and Emerging Players: Iberian hydrogen hub projects lacking established VIP supplier relationships represent the most penetrable buyer archetype for first-mover positioning. Carbon-fiber-reinforced composite variants for aerospace fueling systems open white-space in weight-critical applications. Scientific research liquid helium systems command premium pricing with long-term service contract attach rates. Partner with EPC contractors bundling cryogenic systems under single-responsibility contracts to bypass direct specification barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among corrugated hose specialists with space-constrained installation expertise rather than integrated industrial gas majors. Long-term viability over a 5-10 year window favors fabricators with CE marking certification capacity and hydrogen corridor project visibility. Mid-cap Dutch and German specialists with robotic welding cells face adaptation costs from EU AI Act inspection protocol proposals, creating entry windows. Watch EU AI Act final rules on automated welding quality systems as the inflection indicator for compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MLI Material Supply | Secures aluminum-polyester laminate feedstock against aerospace demand cycle volatility. |
| Robotic Welding Cell Certification Investment | Positions German fabricators for EU AI Act algorithmic decision trail requirements. |
| Iberian Hydrogen Corridor Partnership | Captures first-mover positioning in Spain-Portugal projects lacking supplier relationships. |
| Composite Material Qualification Program | Opens ArianeGroup and ESA launch facility specifications for carbon-fiber VIP variants. |
| Getter Activation Training Certification | Addresses Eastern European technician throughput gaps threatening field installation quality. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cryogenic engineering contractors, EPC procurement leads, industrial gas project developers, and scientific research facility engineering directors with secondary validation through EU Pressure Equipment Directive certification databases, ECHA REACH compliance filings, and hydrogen infrastructure project development registries. Bottom-up fabrication capacity assessments and top-down hydrogen corridor investment flows were triangulated to anchor market sizing.
Segment-weighting approaches modeled product type, material grade, application thermal threshold, and end-user technical capability across the projection horizon. CAGRs were derived from installation volume trajectories tied to EU Green Deal hydrogen backbone funding disbursements and F-Gas Regulation compliance deadlines. Nuclear fusion research facility order pipelines and aerospace fueling system qualification timelines served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; standard pipe configurations for established chemical park corridors carry tighter precision than custom nuclear fusion research orders with extended CE marking timelines. Forecasts reflect assumptions around EU AI Act implementation timing and hydrogen liquefaction pilot scale-up rates. Regulatory enforcement intensity on F-Gas Regulation compliance and MLI material supply disruptions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Naval Actuators and Valves Market
Valves
Flare Stack Monitoring Systems Market
Valves
Air Jet Ejectors Market
Valves
Safety Valve Test Benches Market
Valves
Sliding Sleeves Market
Valves
Three Way Ball Valve Market
Valves
Pressure Gauge Market
Valves
One-Way Valve Market
Valves
Bend Restrictors and Stiffeners Market
Valves
Pneumatic Positioner Market
Valves
Pipeline Pigging Equipment Market
Valves
Actuators and Valves Market
Valves
Europe Medium Voltage Switchgear Market
Valves
US Water & Wastewater Valves Market
Valves
Thermal Power Valve Market
Valves
Rising Stem Ball Valve Market