
 Tank Hydrogen Valve Market | 2026-2036
Tank Hydrogen Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Tank Hydrogen Valve Market Insights
Heavy-duty transport is recalibrating the buyer landscape for tank hydrogen valves as fleet operators replace diesel with hydrogen fuel cell systems. Baker Hughes Company leverages its cryogenic expertise to anchor positions in high-pressure storage applications. Swagelok Company sustains channel control through specialized distribution for laboratory and aerospace qualification programs. Parker Hannifin Corp competes on manufacturing scale across multiple pressure tiers.
A tank hydrogen valve is a pressure-containment device engineered from stainless steel or aluminum alloys with metallic or polymer seals, designed to regulate, isolate, or protect gaseous hydrogen stored at pressures ranging from low-pressure buffer tanks to ultra-high-pressure composite cylinders exceeding 700 bar. Its primary industrial purpose is to prevent leakage, enable controlled discharge, and maintain structural integrity across thermal cycling in mobile and stationary hydrogen systems. Automatic valves are capturing margin pools as refueling automation eliminates human intervention, while safety valves remain mature with stable replacement cycles. High-pressure configurations are expanding fastest alongside composite tank adoption in automotive and energy storage deployments.
The EPA and NHTSA in the United States, ECHA through REACH in Europe, and METI in Japan each enforce material compatibility and pressure-equipment standards that dictate seal specifications and testing protocols for hydrogen service. These frameworks raise compliance costs but also consolidate market access around certified suppliers capable of documenting traceability. Stakeholders must monitor evolving harmonization between regional pressure-equipment codes as hydrogen trade corridors mature.
Market Dynamics
Composite tank adoption above 700 bar is compressing valve specification cycles as fleet operators demand lighter, higher-pressure storage systems for long-haul hydrogen trucking routes.
Growth Catalysts
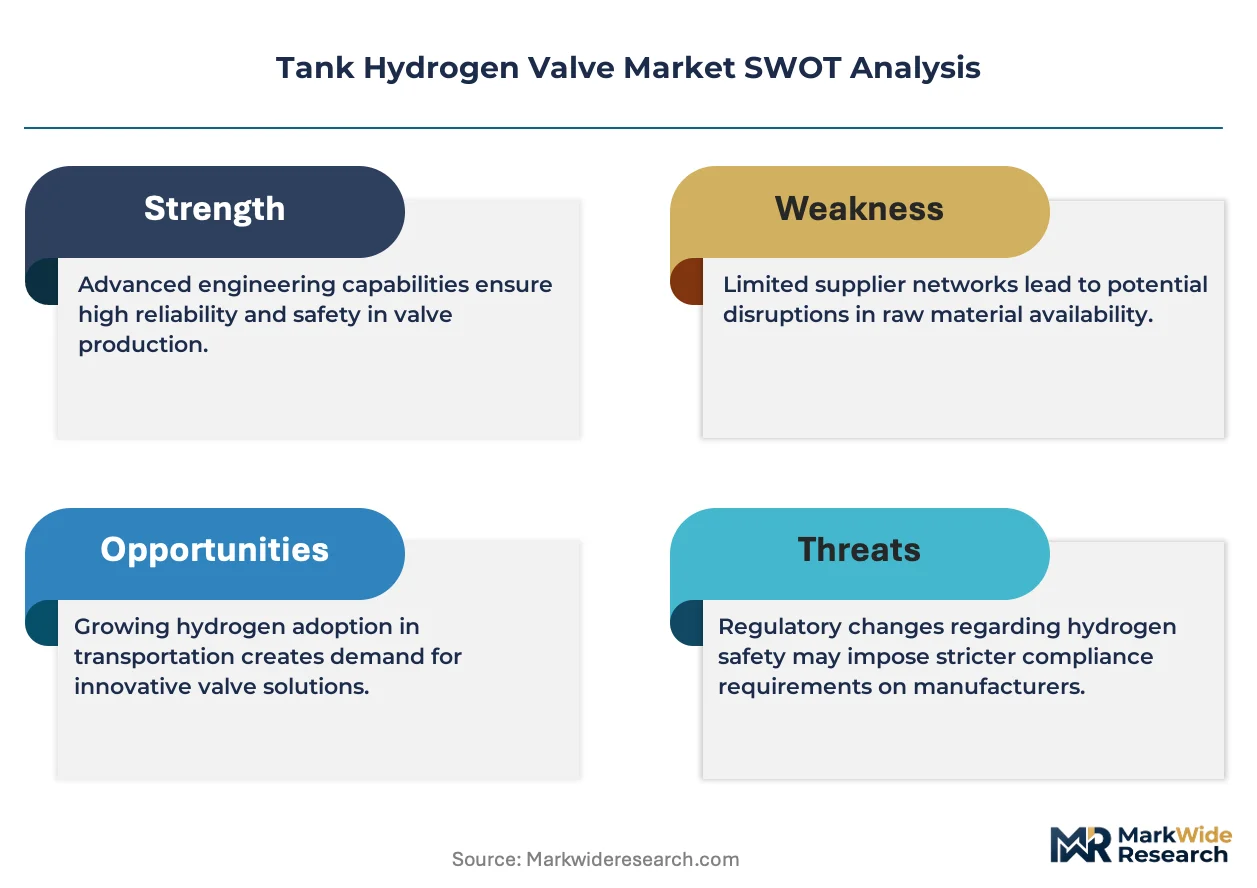
- EU F-Gas Regulation:Tightening seal-material requirements for hydrogen service are filtering supplier bases toward certified manufacturers with documented polymer compatibility testing.
- Heavy-duty trucking fleets:Diesel replacement programs in Germany and California are accelerating demand for high-pressure automatic valves in refueling infrastructure buildouts.
- Composite cylinder technology:Type IV tank adoption in automotive applications is expanding addressable volume for ultra-high-pressure valve configurations.
Market Restraints
- Stainless steel input volatility:Aerospace-grade alloy pricing swings compress margin predictability for valve manufacturers serving price-sensitive buffer tank segments.
- Certified supplier concentration:Hydrogen-specific seal qualification programs limit viable polymer compound sources to Japanese and German specialty chemical producers.
- Pressure-equipment code fragmentation:Divergent testing protocols between ASME standards and EU Pressure Equipment Directive create redundant certification costs for cross-border suppliers.
Strategic Opportunities
- South Korean hydrogen corridors:Government-backed H2City initiatives are creating dedicated demand pockets for smart valve systems with integrated pressure telemetry.
- Aerospace qualification channel:Laboratory certification programs are opening premium pricing tiers for valves meeting JIS hydrogen embrittlement standards.
- Automatic valve-meets-IoT convergence:Refueling station automation is creating integrated system procurement opportunities beyond discrete component sales.
Industry Challenges
- Hydrogen embrittlement metallurgy expertise:Shortage of materials engineers with pressure-vessel failure-mode analysis experience delays product qualification timelines.
- Multi-jurisdiction certification backlog:Sequential approvals from METI, KBA, and EPA pressure-equipment divisions extend time-to-revenue for new valve designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tank Hydrogen Valve Market |
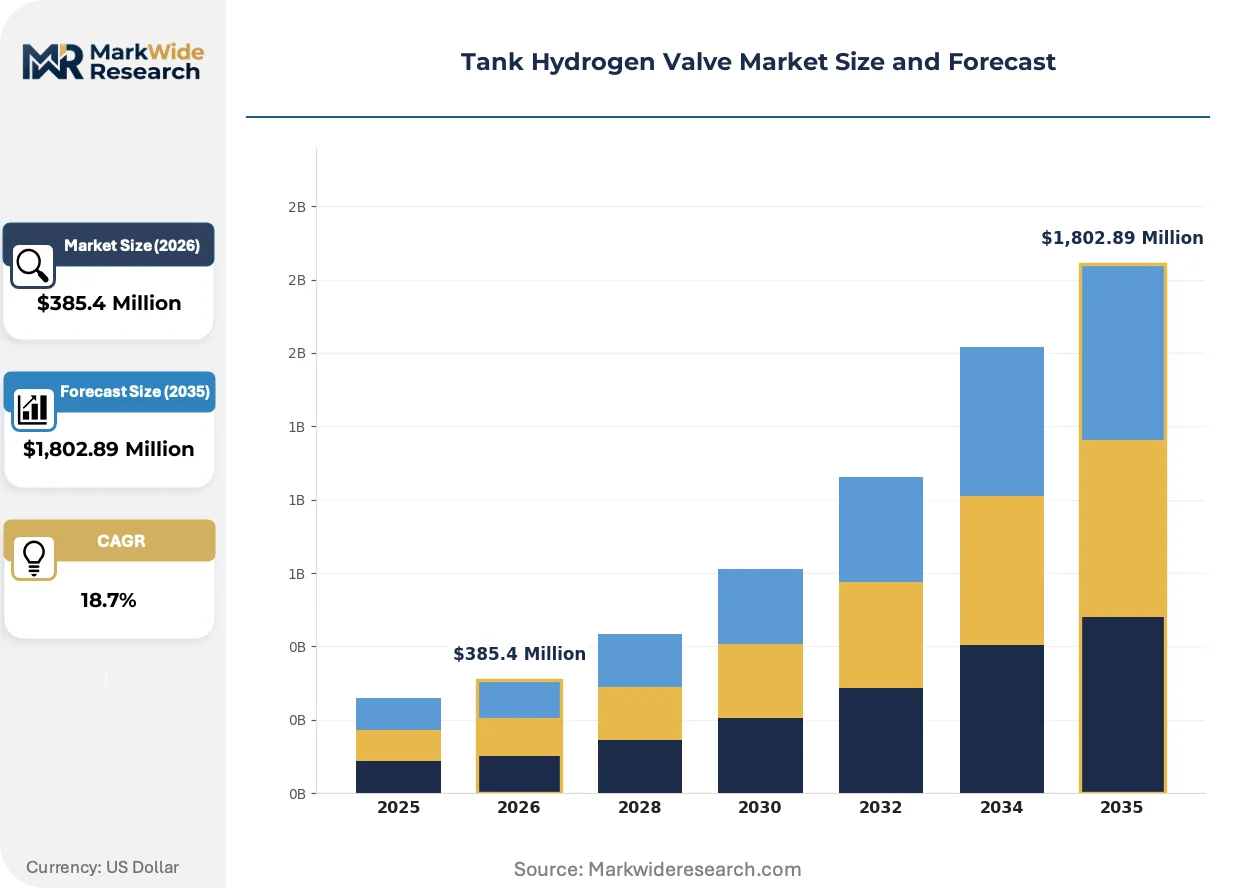
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,802.89 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Valves, Automatic Valves, Safety Valves, Check Valves End Use Industry: Aerospace, Automotive, Energy, Research Material: Stainless Steel, Aluminum, Brass, Polymer Operating Pressure: Low Pressure, Medium Pressure, High Pressure, Ultra High Pressure |
| Companies Covered | Crane Company, Baker Hughes Company, Emerson Electric Co., Rotarex, KITZ Corporation, Swagelok Company, Westport Fuel Systems Inc., Quantum Fuel Systems LLC., Parker Hannifin Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tank Hydrogen Valve Market Trends and Innovations
Valve intelligence and materials science are converging to redefine performance benchmarks as stationary and mobile hydrogen systems diverge in specification requirements.
Automatic shutoff valve technology is automating refueling sequences by replacing manual isolation procedures with pressure-triggered actuation systems. Fleet operators in California and Germany are specifying these configurations for unattended heavy-duty truck refueling. The shift is automating procurement decisions toward integrated valve-controller packages and away from discrete mechanical components.
REACH material compliance deadlines are forcing reformulation of legacy polymer seal compounds used in hydrogen service. ECHA substance restrictions on fluorinated materials are accelerating qualification of hydrogen-compatible thermoplastic elastomers. European valve suppliers are responding by verticalizing polymer development partnerships to secure supply continuity.
After-sales service unbundling is fragmenting traditional valve procurement relationships as fleet operators separate hardware acquisition from maintenance contracts. Third-party certification houses in Japan and South Korea are capturing calibration and recertification revenue streams previously retained by original manufacturers. This pattern is most pronounced in high-frequency refueling station deployments where replacement cycles compress below five years.
Tank Hydrogen Valve Market Segmentation
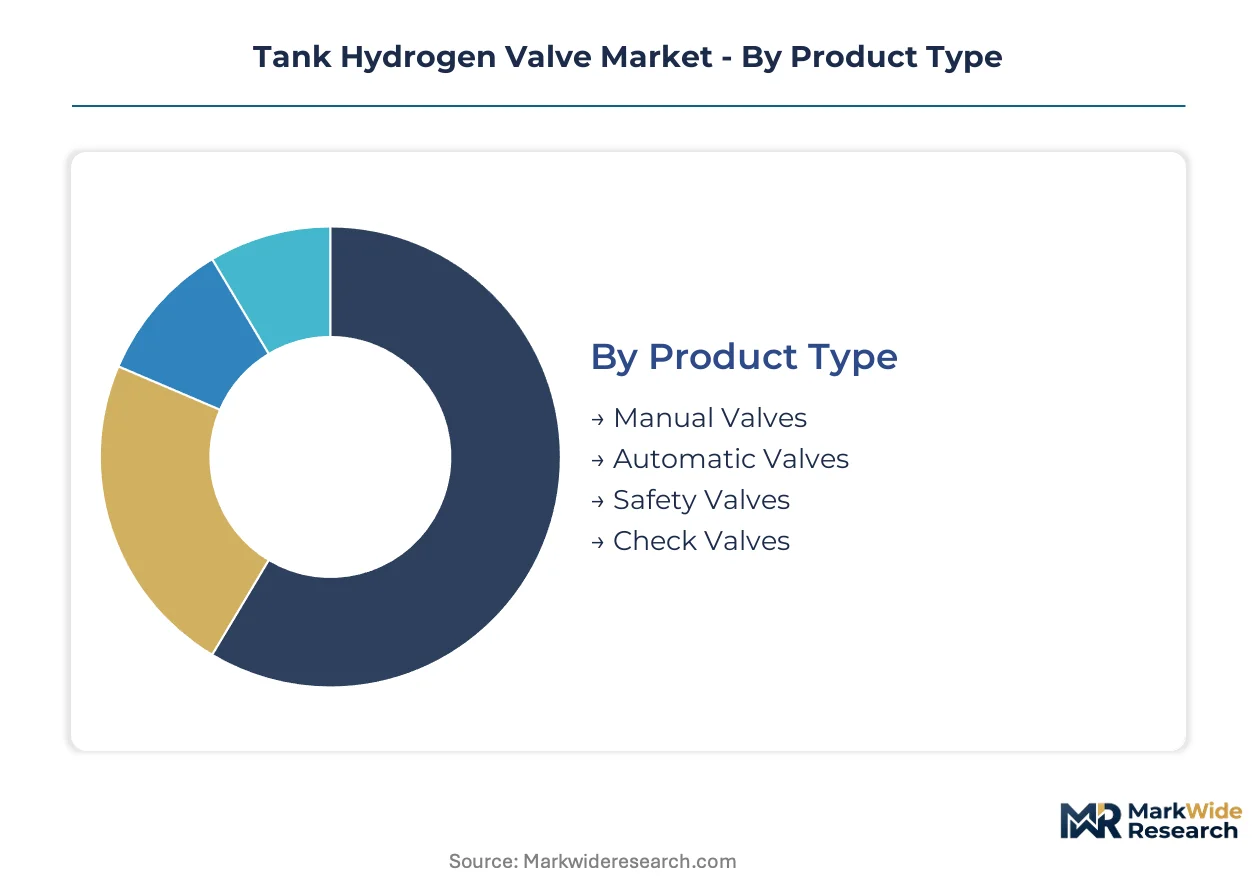
Tank hydrogen valve segmentation reveals how specification requirements diverge between mass-production automotive applications and low-volume aerospace qualification programs. Each dimension—product function, end-use, material, and pressure rating—carries distinct margin profiles and certification burdens that reshape supplier positioning.
Product Type:
The customization-vs-standardization spectrum spans from commodity manual isolation valves to application-engineered automatic systems with integrated telemetry.
- Automatic Valves:Electromechanical actuation systems with pressure-triggered shutoff sequences dominate refueling infrastructure procurement in California and Germany. Fleet operators specify these configurations for unattended heavy-duty truck refueling, compressing specification cycles as automation eliminates manual intervention.
- Safety Valves:Pressure-relief devices engineered for thermal excursion protection maintain stable replacement cycles across stationary storage installations. Demand concentrates in buffer tank applications where regulatory mandates dictate periodic recertification intervals.
- Manual Valves:Hand-actuated isolation devices serve laboratory and maintenance access points with lower automation requirements.
- Check Valves:Unidirectional flow prevention components protect compressor systems from backflow contamination during refueling sequences.
Leading the category by volume: Safety Valves. Growing fastest: Automatic Valves.
End Use Industry:
Cost tier stratification separates premium aerospace qualification programs from price-sensitive energy storage deployments.
- Automotive:Composite cylinder integration in fuel cell electric vehicles drives demand for ultra-high-pressure configurations above 700 bar. Type IV tank adoption across German and Japanese OEM platforms expands addressable volume for lightweight valve assemblies with polymer seal compatibility.
- Aerospace:Laboratory certification programs for satellite propulsion and ground support equipment command premium pricing tiers. JIS hydrogen embrittlement standards and extended thermal cycling protocols filter supplier bases toward metallurgical specialists with documented failure-mode analysis capabilities.
- Energy:Stationary storage and grid-buffer applications prioritize cost efficiency in high-volume procurement of medium-pressure stainless steel configurations.
- Research:University and national laboratory installations sustain niche demand for precision-manual valves with specialized port geometries.
Dominating procurement value: Automotive. Expanding most quickly: Aerospace qualification channels.
Material:
Supply concentration for certified polymer compounds creates sourcing bottlenecks that reshape procurement strategies across pressure tiers.
- Stainless Steel:Aerospace-grade austenitic and precipitation-hardened alloys provide hydrogen embrittlement resistance for high-cycle refueling applications. REACH compliance and ECHA substance restrictions on fluorinated seal materials force reformulation partnerships with German and Japanese specialty chemical producers.
- Aluminum:Lightweight alloys enable mass reduction in automotive composite tank assemblies, though thermal expansion coefficients limit high-temperature service ranges.
- Brass:Cost-effective copper-zinc formulations serve low-pressure buffer tank segments with reduced cycling frequency.
- Polymer:Thermoplastic elastomers and high-performance fluoropolymers function as dynamic seals and valve seat inserts, with qualification programs limiting viable compound sources.
Capturing highest unit margins: Stainless Steel. Gaining share fastest: Polymer seal components.
Operating Pressure:
Volume-maturity dynamics concentrate replacement demand in established low-pressure segments while technology investment flows toward ultra-high-pressure frontiers.
- Ultra High Pressure:Configurations exceeding 700 bar serve long-haul hydrogen trucking routes and automotive fuel cell systems where composite cylinder technology enables mass reduction. Fleet operators in South Korea's H2City corridors specify these valves with integrated pressure telemetry for smart refueling networks.
- High Pressure:350-700 bar ranges balance performance and certification accessibility for medium-duty commercial vehicle deployments.
- Medium Pressure:Industrial buffer tank and stationary storage applications sustain predictable replacement cycles with standardized ASME and EU Pressure Equipment Directive compliance pathways.
- Low Pressure:Laboratory and maintenance bypass systems face price compression from commodity stainless steel input volatility.
Generating steepest expansion trajectory: Ultra High Pressure. Maintaining largest installed base: Medium Pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial free zones and hydrogen-specialized economic corridors are concentrating tank hydrogen valve procurement. Germany's H2Global auction mechanism, South Korea's H2City clusters, and California's HVIP voucher zones each create localized demand pockets with distinct certification requirements.
Germany
Heavy-duty trucking corridors along the Rhine-Alpine freight axis drive valve demand for 700-bar refueling stations. The KBA enforces pressure-equipment standards that filter supplier bases toward documented hydrogen embrittlement testing. Industrial clusters in North Rhine-Westphalia and Baden-Württemberg host OEM qualification programs for composite tank-integrated valve assemblies.
Japan
Fuel cell passenger vehicle fleets sustain replacement cycles for ultra-high-pressure configurations. METI's hydrogen roadmap mandates JIS-compliant seal materials that limit polymer compound sourcing to domestic specialty chemical producers. The Chubu region around Nagoya anchors manufacturing for automotive-qualified valve systems with integrated pressure telemetry.
South Korea
Government-backed H2City initiatives in Ulsan and Changwon create dedicated demand for smart valve systems. The MFDS and national hydrogen safety agency enforce dual certification pathways that extend time-to-market for imported components. Busan-Ulsan industrial complexes concentrate domestic valve assembly capacity for export-oriented fuel cell vehicle programs.
United States
California HVIP incentives compress procurement timelines for heavy-duty fleet conversions. The EPA and NHTSA coordinate pressure-equipment standards that diverge from EU testing protocols, creating redundant certification costs. The San Joaquin Valley and Port of Long Beach anchor refueling infrastructure buildouts with automated valve specifications.
China
State-backed hydrogen corridor investments in the Yangtze River Delta and Pearl River Delta expand addressable volume for medium-pressure buffer tank valves. GB standards and MIIT hydrogen equipment regulations mandate domestic content ratios that reshape supply chain configurations. Shanghai and Foshan industrial zones concentrate assembly capacity for cost-optimized stainless steel configurations.
Tank Hydrogen Valve Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with certified suppliers capturing premium tiers while commodity fabricators serve price-sensitive buffer tank applications. The supplier base concentrates around metallurgical specialists with documented hydrogen embrittlement testing capabilities and polymer compound developers with REACH-compliant seal formulations. Three archetypes dominate: cryogenic heritage industrial conglomerates, precision fluid control specialists, and regional stainless steel fabricators with pressure-equipment certifications. Competitive dynamics center on backward integration into polymer seal development and geographic expansion through local certification partnerships.
Among diversified industrial conglomerates, Baker Hughes Company and Parker Hannifin Corp exemplify scale-driven positioning across multiple pressure tiers. Precision fluid control specialists include Swagelok Company, which occupies a position in laboratory and aerospace qualification channels. Regional fabricators and fuel system integrators such as Westport Fuel Systems Inc. and Quantum Fuel Systems LLC. represent the automotive-integrated tier, anchoring positions in composite tank-assembly supply chains.
| Leading Market Players |
|---|
| Crane Company |
| Baker Hughes Company |
| Emerson Electric Co. |
| Rotarex |
| KITZ Corporation |
| Swagelok Company |
| Westport Fuel Systems Inc. |
| Quantum Fuel Systems LLC. |
| Parker Hannifin Corp |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between aerospace-qualified metallurgical specialists and commodity stainless steel fabricators manifests in both pricing power and supply chain configurations. EU F-Gas Regulation compliance costs filter procurement toward German and Japanese specialty chemical producers with documented polymer compatibility testing, compressing margin pools for uncertified competitors while consolidating upstream supply relationships around REACH-compliant seal compound developers.
Pricing Analysis
Short lead-time premiums for JIS hydrogen embrittlement-certified valves command pricing advantages in Japanese aerospace qualification channels, while spot inventory of medium-pressure stainless steel configurations faces discount pressure from fleet operator consolidation. Three-tier pricing structure across premium aerospace certification, standard automotive integration, and economy buffer tank tiers differentiates on seal qualification depth and pressure-equipment documentation. Pricing pressure stems from aerospace-grade alloy input volatility compressing predictability for commodity fabricators serving price-sensitive energy storage deployments. Fleet operators in heavy-duty trucking segments exhibit highest price sensitivity due to total-cost-of-ownership calculations, while laboratory certification programs show lowest sensitivity given failure-mode liability exposure.
Supply Chain Analysis
Refurbishment flows for safety valve recertification create reverse-logistics revenue streams that third-party calibration houses in Japan and South Korea are capturing from original manufacturers. Manufacturing concentration in Germany, Japan, and South Korea anchors production of high-pressure automatic valve systems, with domestic content ratios in China's GB-standard corridor reshaping regional assembly configurations. Raw material dependencies on aerospace-grade austenitic alloys, hydrogen-compatible thermoplastic elastomers, and precipitation-hardened stainless steel feed from specialized metallurgical suppliers with documented embrittlement testing. Single-source vulnerability concentrates in Japanese specialty chemical producers holding JIS-compliant polymer compound formulations. Distribution runs through OEM-integrated fuel system assemblers and refueling infrastructure EPC contractors with specification control over valve-controller packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU F-Gas Regulation seal-material requirements erect barrier-to-entry moats that consolidate procurement around certified manufacturers with documented polymer compatibility testing capabilities.
For Market Incumbents: Hedge against margin compression in commodity buffer tank segments by backward integration into polymer seal development partnerships with German and Japanese specialty chemical producers. Capacity addition in South Korea's H2City corridors captures government-backed smart valve demand, while defending aerospace qualification channel control through JIS hydrogen embrittlement testing documentation that emerging metallurgical competitors cannot rapidly replicate. For New Entrants and Emerging Players: Begin with aftermarket service unbundling opportunities in high-frequency refueling station deployments where replacement cycles compress below five years and third-party calibration houses are capturing recertification revenue. South Korean hydrogen corridors present the most penetrable geography given MFDS dual certification pathways that favor local assembly partnerships. Go-to-market positioning as integrated valve-controller system suppliers rather than discrete component fabricators aligns with refueling automation procurement shifts. For Investors and Strategic Acquirers: Re-rating potential sits with metallurgical specialists possessing documented hydrogen embrittlement failure-mode analysis capabilities given composite tank adoption above 700 bar compressing specification cycles. Long-term viability hinges on backward integration into REACH-compliant seal formulations that survive ECHA substance restriction evolution. Monitor harmonization progress between ASME standards and EU Pressure Equipment Directive as inflection indicator for cross-border supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Seal Development | REACH-compliant compound control secures supply continuity against ECHA fluorinated material restrictions. |
| Smart Valve-Controller System Launch | Integrated telemetry packages capture H2City corridor procurement specifications in South Korea. |
| JIS Hydrogen Embrittlement Certification Investment | Aerospace qualification channel access commands premium pricing tiers from satellite propulsion programs. |
| Aftermarket Service Unbundling | Third-party calibration revenue streams in high-frequency refueling deployments offset hardware margin pressure. |
| South Korean Manufacturing Footprint Expansion | Local assembly capacity satisfies MFDS domestic content ratios for government-backed hydrogen corridor buildouts. |
Research Methodology
Independent corroboration across valve manufacturer technical directors, refueling infrastructure EPC procurement leads, and aerospace qualification program managers underwrites the qualitative findings. Primary interviews with fleet operator maintenance directors, polymer compound R&D specialists, and national hydrogen safety agency officials combined with secondary validation from KBA pressure-equipment filings, METI hydrogen roadmap disclosures, and ECHA REACH substance restriction databases. Bottom-up triangulation across product-type shipment estimates and top-down cross-checks against refueling station deployment pipelines anchored volume assessments.
Comparable-period anchoring to historical composite tank adoption curves and diesel replacement program timelines structured the projection horizon across the analysis window. Segmentation modeling spanned product function, end-use industry, material grade, and operating pressure tier alongside geographic regulatory cluster differentiation. CAGRs derived from pressure-equipment installation trajectories and fleet conversion voucher program uptake curves, with hydrogen embrittlement metallurgy expertise scarcity and multi-jurisdiction certification backlog timelines informing adoption rate constraints.
Underlying measurement precision varies by segment; ultra-high-pressure automatic valve configurations carry tighter precision than commodity manual valve categories given concentrated OEM qualification program visibility. Forecasts reflect assumptions regarding EU-Japan hydrogen trade corridor maturation and harmonization between regional pressure-equipment codes. Practitioners should monitor KBA-METI reciprocal certification agreement progress and aerospace-grade alloy pricing volatility for early signals of supply chain restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Flare Stack Monitoring Systems Market
Valves
Industrial Safety Valves Market
Valves
Leak Detection Market
Valves
Steam Safety Valve Market
Valves
United States Valves Market
Valves
Cryogenic Valve Market
Valves
Global Valve Positioners Market
Valves
Pipeline Integrity Management (PIM) Market
Valves
Europe Vacuum Insulated Pipe Market
Valves
Construction Valve Seat Insert Market
Valves
Thermal Power Valve Market
Valves
Pulsation Dampeners Market
Valves
Dense Phase Vessels Market
Valves
Global Pressure Relief Valves Market
Valves
Pneumatic Positioner Market
Valves
China Explosion-Proof Equipment Market