
 Global Gate Valve Market | 2026-2036
Global Gate Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gate Valve Market Foresight
A shift from single-source to multi-source procurement is repositioning how downstream operators manage valve supply chains. Emerson leverages its automation-integrated valve portfolio to anchor long-term service contracts with major energy producers. Flowserve sustains manufacturing scale across forged and cast product lines. Neway Valve competes on cost-engineered carbon steel variants for municipal water utilities in Asia.
A gate valve employs a flat or wedge-shaped disc that moves perpendicular to fluid flow to achieve full shutoff with minimal pressure drop, typically rated for ANSI Class 150 through 2500 pressure-temperature conditions. Rising stem designs dominate upstream oil and gas applications where visual position indication matters, while knife gate configurations occupy pulp and paper slurry lines where bi-directional sealing against fibrous media proves critical. Stainless steel material grades capture premium margin pools in chemical manufacturing corrosive service, whereas ductile iron remains the volume workhorse for water treatment plants.
API 6D pipeline valve standards in the United States, PED 2014/68/EU pressure equipment directives in Europe, and GB/T 12234 national standards in China collectively shape design validation, testing protocols, and market access requirements. ISO 5208 pressure testing specifications further harmonize leakage-rate acceptance criteria for cross-border project specifications. Stakeholders must monitor evolving methane-emission regulations and their downstream implications for fugitive-emission-tested packing systems.
Market Dynamics
Offshore platform operators are consolidating valve specifications around API 6D-certified products, compressing supplier qualification timelines and redistributing procurement leverage toward integrated automation vendors.
Growth Catalysts
- API 6D Pipeline Standards:US operators now mandate full-bore, through-conduit designs for critical isolation service, elevating certified manufacturers above uncertified competitors in bid evaluations.
- Bohai Rim Petrochemical Expansion:China's coastal refining corridor requires thousands of Class 2500 gate valves for hydrogen cracking units and ethylene crackers under construction.
- Stainless Steel Casting Advances:Investment casting improvements in CF8M grades now achieve 0.5% wall thickness tolerance, opening sour gas service applications previously reserved for forged bodies.
Market Restraints
- Chromium-Nickel Alloy Volatility:Stainless steel scrap prices fluctuate 15-30% quarterly, compressing margin predictability for foundries serving chemical processing end-uses.
- Forging Capacity Concentration:Seventy percent of large-diameter forged bodies originate from three integrated mills in Germany and Japan, creating bottleneck risk for urgent project timelines.
- Ball Valve Substitution:Trunnion-mounted ball designs with metal-seated technology now achieve zero-leakage isolation in pipeline service, displacing traditional gate valves in new-build specifications.
Strategic Opportunities
- Saudi Aramco Megaprojects:The Kingdom's Jafurah unconventional gas development and Red Sea coastal refineries specify super-duplex gate valves for high-H2S service, creating premium product demand.
- Digital Twin Integration:Valve positioners with HART-IP connectivity enable predictive maintenance contracts, bundling hardware with recurring software revenue streams.
- India's PLI Scheme for Capital Goods:Domestic manufacturing incentives for precision castings support local valve production for municipal water infrastructure at 20% lower landed cost than imports.
Industry Challenges
- Welding Inspector Certification Backlog:ASME Section IX-qualified radiographic interpreters face 6-month queue times, delaying final acceptance testing for critical path project schedules.
- Legacy DCS Integration Complexity:New smart valve positioners require protocol gateways to communicate with 1990s-era distributed control systems common in established refineries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gate Valve Market |
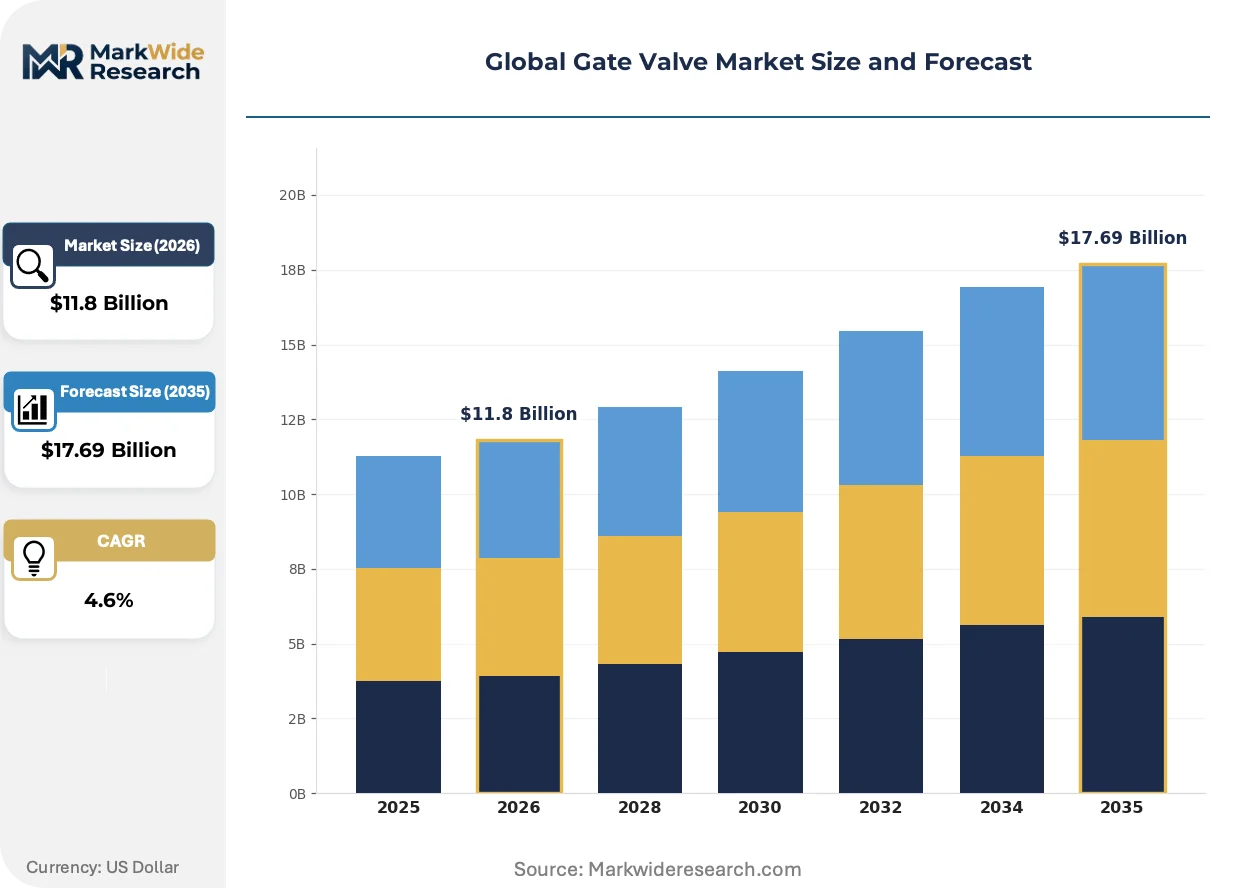
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rising Stem, Non-Rising Stem, Knife Gate, Expanding Gate, Parallel Slide Material: Carbon Steel, Stainless Steel, Bronze, Alloy Steel, Ductile Iron Application: Oil & Gas Processing, Power Generation Facilities, Water Treatment Plants, Chemical Manufacturing, Pulp & Paper Production End User Industry: Refineries, Energy Producers, Municipal Water Utilities, Chemical Plants, Paper Mills |
| Companies Covered | Neway Valve, Kosen Valve, Emerson, Flowserve, AVK Group, SLB, Yuanda Valve Group, Baker Hughes, Crane, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gate Valve Market Shifts & Advancements
Automation convergence and materials science advances are redefining performance benchmarks for isolation valves across energy and process industries.
Metal-seated knife gate configurations are expanding into mining tailings and biomass processing applications previously served by resilient-seated designs. Rio Tinto and Vale have standardized these for abrasive slurry service in iron ore concentration plants. The technology is expanding into municipal wastewater grit chambers, displacing plug valves in facilities requiring bi-directional sealing without elastomer degradation.
EPA methane emission regulations under the Inflation Reduction Act now mandate quarterly LDAR surveys on valve packing in production, processing, and transmission facilities. Fugitive emission-tested graphite packing systems with live-loading qualify for reduced inspection frequencies. US onshore shale operators are retrofitting existing rising-stem gate valves with EPA-certified low-e packing to avoid penalty exposure.
Integrated procurement platforms now consolidate valve specifications, inspection reports, and maintenance histories in cloud-based asset registries. EPC contractors on Middle Eastern megaprojects require suppliers to upload mill test reports and NDE documentation directly into client ERP systems before shipment release. This behavior is most visible in UAE and Qatar LNG expansion projects, where operator engineering standards now exclude vendors without API Q1-certified quality management systems.
Global Gate Valve Market Segmentation
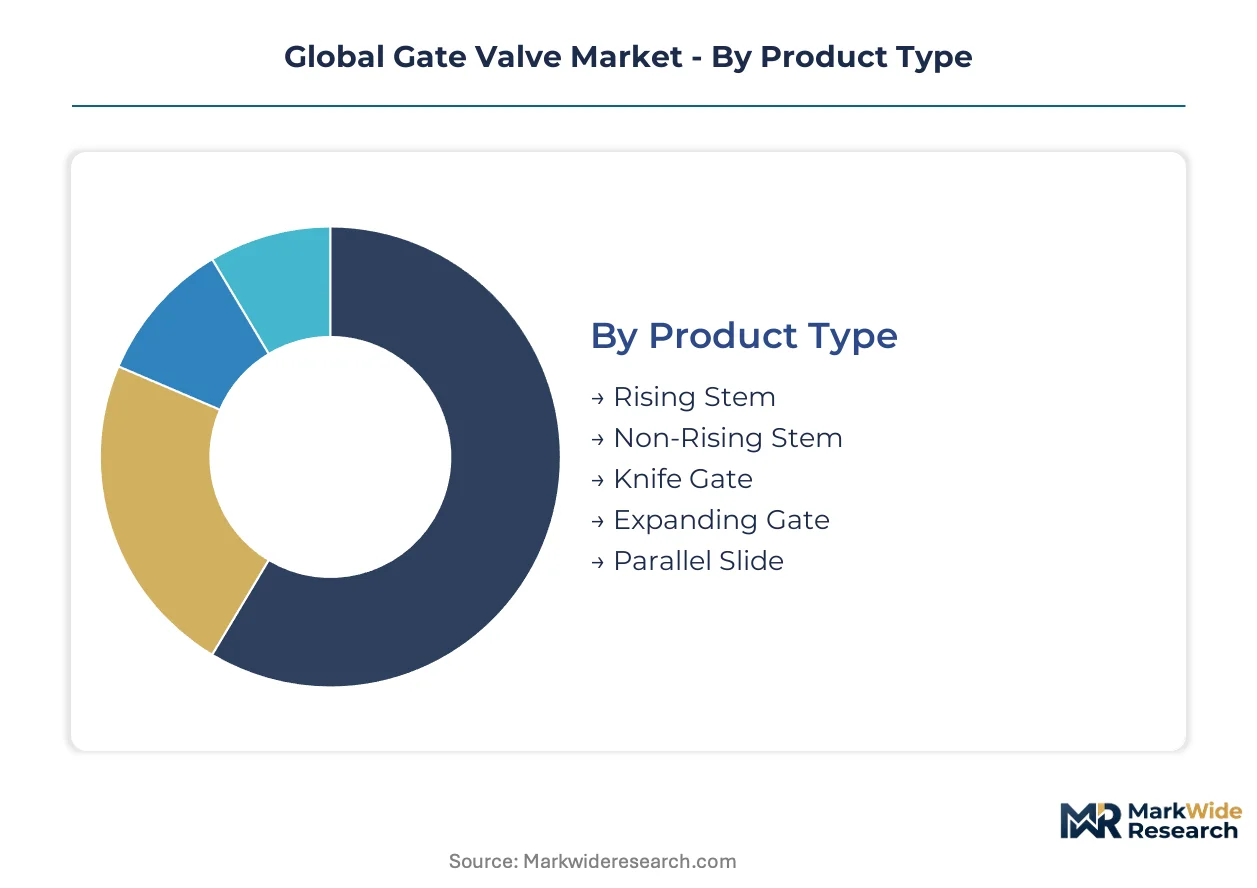
Gate valve procurement decisions pivot on pressure-temperature ratings, corrosion resistance, and stem visibility requirements. Each segmentation dimension carries distinct margin profiles and certification burdens that reshape supplier positioning.
Product Type:
Application environment dictates stem configuration and sealing geometry, with visibility requirements and space constraints driving specification splits.
- Rising Stem:External thread engagement provides immediate visual position confirmation for operators. Upstream oil and gas facilities across the Permian Basin and North Sea platforms specify these for critical isolation points where manual verification overrides automation trust.
- Knife Gate:Thin profile gate geometry shears through fibrous slurries and tailings without jamming. Rio Tinto's Western Australia iron ore operations and Vale's Carajás complex have standardized these for abrasive media handling, displacing resilient-seated alternatives in mining concentrate lines.
- Non-Rising Stem:Compact vertical footprint suits buried service and limited-headroom installations. Municipal water distribution networks in Tokyo and Seoul deploy these for underground valve chambers where stem extension is impractical.
- Expanding Gate:Mechanical wedge expansion achieves dual-seat sealing against differential pressure. LNG liquefaction trains in Qatar and Australia specify these for cryogenic isolation where thermal contraction risks single-seat leakage.
- Parallel Slide:Twin-disc spring-loaded design maintains seal independent of pipeline pressure. Combined cycle power plants in Germany and South Korea favor these for steam isolation where thermal cycling degrades wedge-style alternatives.
Rising Stem leads on scale; Knife Gate leads on momentum.
Material:
Corrosivity of process fluid and capital intensity of replacement cycles determine alloy selection, with sour service and chlorine-bearing environments commanding premium grades.
- Carbon Steel:A216 WCB castings dominate high-volume, low-corrosivity applications. India's municipal water infrastructure expansion under the Jal Jeevan Mission sources these domestically at cost points 20% below imported stainless alternatives.
- Stainless Steel:CF8M austenitic grades resist chloride stress corrosion in offshore and chemical service. Saudi Aramco's Jafurah unconventional gas development specifies super-duplex variants for high-H2S production headers, creating concentrated demand for foundries with NORSOK M-650 certification.
- Bronze:C95800 aluminum bronze resists seawater galvanic corrosion. Desalination plants in the UAE and Kuwait specify these for intake and brine discharge lines where carbon steel fails within 18 months.
- Alloy Steel:WC6 and WC9 chrome-moly grades sustain elevated temperatures in refinery hydrocracking and coking units. US Gulf Coast upgrading projects require these for hydrogen service above 260°C.
- Ductile Iron:A536 65-45-12 grade delivers pressure containment at carbon steel's 60% material cost. French and Italian water treatment authorities specify these for filtration and disinfection skids where corrosion rates remain manageable.
Carbon Steel dominates installed base; Stainless Steel captures value expansion.
Application:
Process criticality and safety classification determine specification stringency, with hydrocarbon containment and nuclear isolation commanding the tightest validation protocols.
- Oil & Gas Processing:Full-bore through-conduit designs eliminate flow restriction and pigging interference. API 6D certification is now mandatory for US pipeline operators, compressing supplier pools to manufacturers with third-party witnessed testing capabilities.
- Water Treatment Plants:Ductile iron and epoxy-coated carbon steel variants prioritize lifecycle cost over alloy performance. China's Bohai Rim municipal expansion drives volume for resilient-seated configurations in filtration and backwash isolation.
- Power Generation Facilities:Parallel slide and pressure-seal bonnet designs tolerate thermal transients in steam circuits. India's Ultra Mega Power Projects and Saudi combined-cycle expansions specify these for turbine isolation and boiler feedwater regulation.
- Chemical Manufacturing:Alloy selection tracks process fluid corrosivity, with PTFE-lined and hastelloy-trimmed variants for chlor-alkali and acid service. German and Belgian chemical clusters maintain specification libraries exceeding 200 distinct material combinations.
- Pulp & Paper Production:Knife gate configurations handle high-consistency stock and black liquor with minimal erosion. Brazilian and Indonesian integrated mills specify these for digester discharge and recovery boiler feed lines.
Oil & Gas anchors revenue concentration; Water Treatment drives volume velocity.
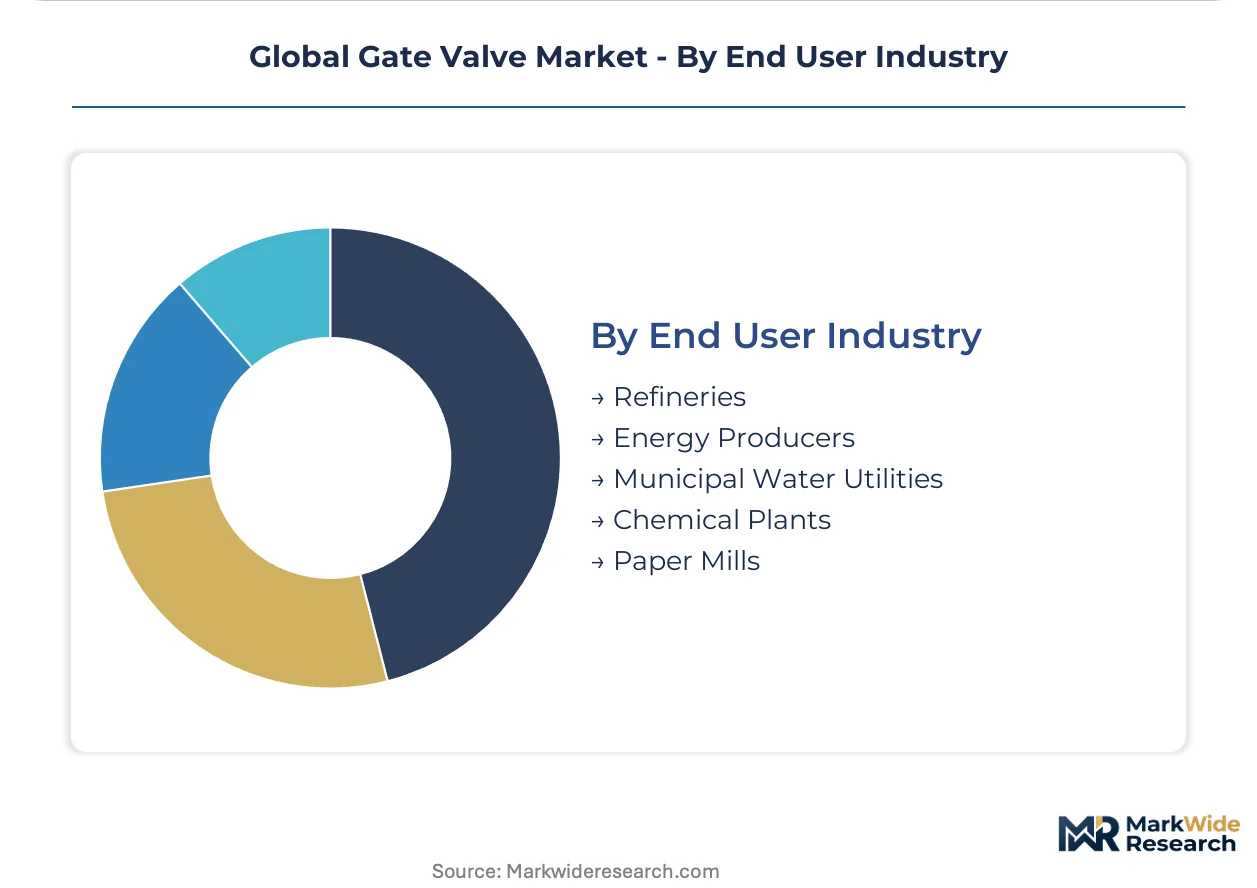
End User Industry:
Procurement sophistication and technical staffing depth vary sharply, with international oil companies imposing qualification barriers that exclude regional fabricators.
- Refineries:Turnaround-driven replacement cycles and process hazard analysis requirements favor established suppliers with API 6A and 6D dual certification. US and European refiners now mandate digital position feedback for all isolation valves in LOPA-identified scenarios.
- Energy Producers:Upstream operators prioritize delivery certainty over unit cost for remote platform and shale pad installations. Brazilian pre-salt developments and Norwegian North Sea tiebacks specify forged bodies with full material traceability to ingot source.
- Municipal Water Utilities:Public procurement rules emphasize lowest compliant bid, compressing margins for standardized ductile iron products. India's AMRUT scheme and Indonesia's PAM Jaya expansion create concentrated demand for resilient-seated configurations in distribution networks.
- Chemical Plants:Process safety management regulations in the EU and US require documented valve integrity programs. BASF's Ludwigshafen complex and Dow's Texas Operations maintain approved manufacturer lists with 3-year qualification renewal cycles.
- Paper Mills:Capital constraints and commodity pricing pressure favor repair-over-replace strategies. Scandinavian and Canadian integrated producers maintain in-house valve shops for knife gate refurbishment, limiting new equipment demand to greenfield capacity additions.
Refineries command specification authority; Municipal Water Utilities determine aggregate volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as foundries migrate toward jurisdictions with streamlined pressure-equipment certification. Cost-of-compliance gaps between the United States, Germany, and China now exceed 40% for API 6D witness testing, redirecting investment toward Asian casting clusters.
United States
EPA methane regulations under the Inflation Reduction Act now mandate quarterly LDAR surveys on valve packing across production and transmission facilities. Fugitive-emission-tested graphite packing systems with live-loading qualify for reduced inspection frequencies. US Gulf Coast upgrading projects require WC6 and WC9 chrome-moly grades for hydrogen service above 260°C.
Germany
Combined cycle power plants favor parallel slide designs for steam isolation where thermal cycling degrades wedge-style alternatives. PED 2014/68/EU pressure equipment directives shape design validation and testing protocols for cross-border project specifications. The Ruhr industrial corridor maintains specification libraries exceeding 200 distinct material combinations for chemical processing applications.
China
GB/T 12234 national standards govern domestic market access requirements alongside evolving dual carbon goals from MEE. The Bohai Rim petrochemical corridor requires thousands of Class 2500 gate valves for hydrogen cracking units and ethylene crackers under construction. Investment casting improvements in CF8M grades now achieve 0.5% wall thickness tolerance for sour gas service.
Saudi Arabia
The Jafurah unconventional gas development and Red Sea coastal refineries specify super-duplex gate valves for high-H2S service. SFDA-equivalent pressure equipment oversight applies to hydrocarbon containment systems in upstream installations. Eastern Province industrial cities anchor demand for forged bodies with full material traceability to ingot source.
India
The PLI scheme for capital goods supports domestic manufacturing incentives for precision castings. Jal Jeevan Mission and AMRUT scheme expansions create concentrated demand for resilient-seated configurations in municipal water distribution networks. Gujarat and Maharashtra foundries now deliver ductile iron variants at 20% lower landed cost than imported alternatives.
Global Gate Valve Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue automation-integrated portfolios and specialty alloy niches. The vendor base stratifies across three maturity tiers: integrated automation vendors with service contract anchoring, scale-driven forged and cast product specialists, and cost-engineered carbon steel fabricators for municipal utilities. Strategic archetypes include certification-heavy full-line suppliers, regional foundry clusters leveraging domestic content incentives, and digital-positioner bundlers capturing recurring software revenue. Consolidation pressure favors M&A among mid-tier European foundries; capacity expansion concentrates in Indian and Chinese casting corridors.
Within the integrated automation tier, Emerson and Flowserve exemplify the service-contract anchoring model. Among Asian cost-engineered specialists, Neway Valve occupies a position representing the municipal utility volume play. Baker Hughes and SLB sit within the energy-producer qualification tier where forged-body traceability commands premium positioning.
| Leading Market Players |
|---|
| Neway Valve |
| Kosen Valve |
| Emerson |
| Flowserve |
| AVK Group |
| SLB |
| Yuanda Valve Group |
| Baker Hughes |
| Crane |
| Others |
Supply & Pricing Matrix
Offshore platform operators and municipal water utilities anchor opposite ends of gate valve procurement, with specification stringency determining whether pricing follows project-based engineering premiums or lowest-compliant-bid commodity mechanics. API 6D-certified forged bodies command substantial premiums over carbon steel cast variants, yet foundry capacity constraints in Germany and Japan limit volume elasticity at the top tier.
Pricing Analysis
Distributor margins compress standard-tier carbon steel variants while direct-to-EPC contracts preserve pricing power for super-duplex and alloy steel grades. Three-tier pricing structure across premium, standard, and economy levels separates API 6D-certified forged products from GB/T-compliant cast bodies and unmarked municipal-grade fabrications. Pricing pressure stems from ball valve substitution in pipeline specifications and chromium-nickel alloy volatility squeezing foundry margins. Municipal water utilities exhibit highest price sensitivity, while Saudi Aramco megaprojects and North Sea operators prioritize delivery certainty over unit cost.
Supply Chain Analysis
Regional distribution centers in Houston, Rotterdam, and Singapore anchor hub-and-spoke patterns for urgent project spares and turnaround inventory. Manufacturing concentrates in China, India, and Germany, with seventy percent of large-diameter forged bodies originating from three integrated mills in Germany and Japan. Raw material dependencies include nickel-chromium scrap, molybdenum feedstock, and graphite packing systems. Single-source vulnerability around ASME-qualified welding inspector certification creates six-month bottlenecks for final acceptance testing. Distribution runs through EPC contractor procurement platforms with cloud-based asset registry integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
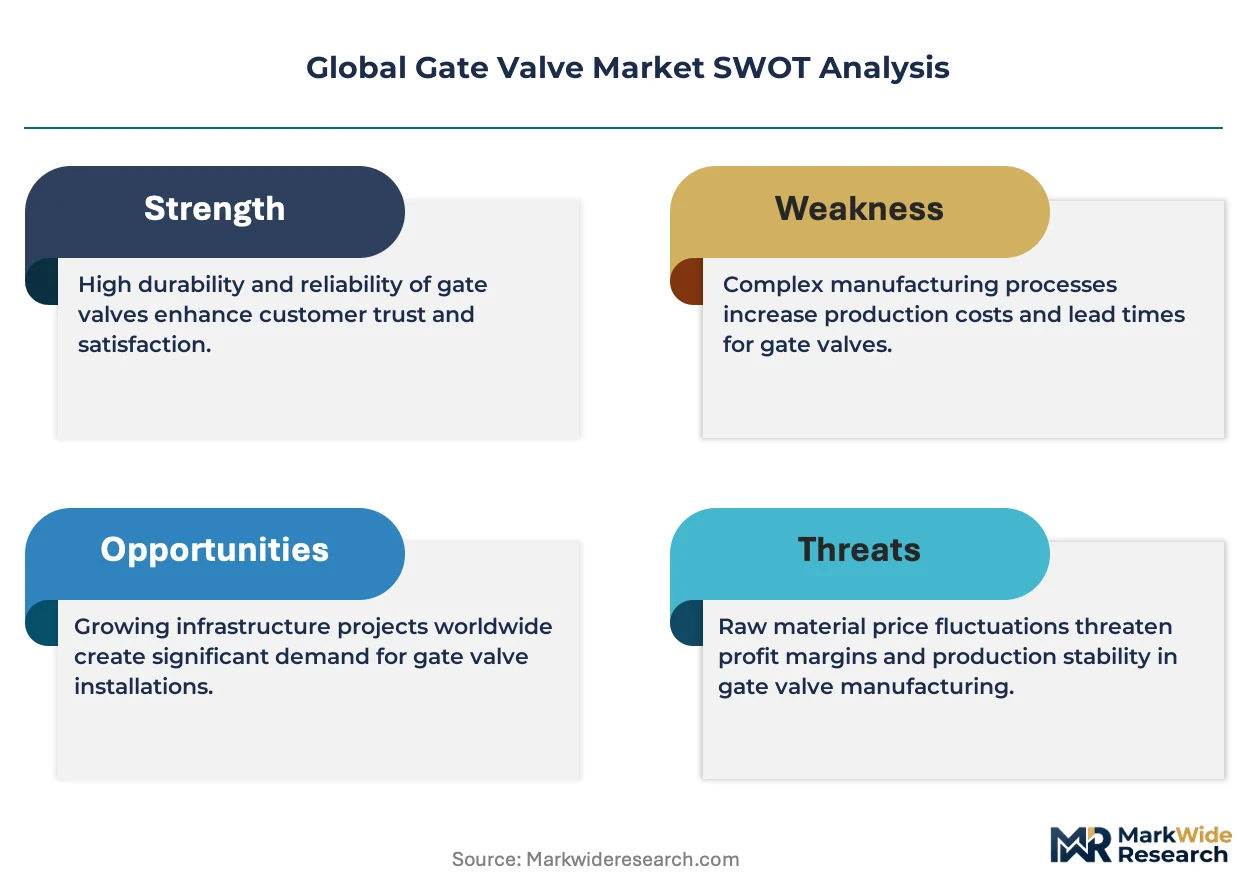
Gate valve procurement has shifted toward premium specifications as methane emission regulations and digital twin integration reshape buyer priorities. API 6D certification and HART-IP connectivity now separate viable suppliers from commodity fabricators.
For Market Incumbents: Acquire specialist foundries with NORSOK M-650 certification to secure super-duplex capacity for sour gas service. Backward integration into investment casting for CF8M grades defends margin position against stainless steel scrap volatility. Ball valve substitution in pipeline specifications and emerging automation-integrated competitors threaten traditional isolation valve positioning. For New Entrants and Emerging Players: Begin with India's PLI scheme for capital goods to capture Jal Jeevan Mission municipal water volume at twenty percent below import parity. Target resilient-seated ductile iron configurations where specification barriers remain lowest. Partner with Gujarat and Maharashtra foundries for domestic casting capacity rather than competing on forged-body certifications. For Investors and Strategic Acquirers: Integrated automation vendors with service contract anchoring are the most active acquirer in this space, seeking valve positioner technology to bundle recurring software revenue. Mid-tier European foundries facing consolidation pressure represent acquisition targets with certification assets. Watch EPA methane enforcement intensity as inflection indicator for fugitive-emission packing retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| API 6D Certification Investment | Opens bid eligibility for US pipeline operators under tightened qualification timelines. |
| Backward Integration into Forging | Secures material traceability for Saudi Aramco and Norwegian North Sea specifications. |
| Digital Positioner Development | Enables predictive maintenance contracts with HART-IP connectivity for refinery automation. |
| Super-Duplex Foundry Capacity | Captures Jafurah unconventional gas demand for high-H2S service valves. |
| Cloud-Based Asset Registry Integration | Meets UAE and Qatar LNG project requirements for mill test report upload protocols. |
Research Methodology
Bottom-up oil and gas processing modeling reconciled against top-down foundry capacity tracking forms the analytical core. Primary interviews with maintenance directors at refineries, EPC contractor procurement leads, foundry operations managers, and aftermarket service heads combine with secondary validation from API certification databases, customs trade records, SEC filings of listed valve manufacturers, and pressure equipment directive compliance registries. Triangulation against ISO 5208 testing specifications and GB/T 12234 national standards ensures cross-border specification alignment.
Historical trendline analysis of rising stem, knife gate, and expanding gate shipment patterns informs the projection framework across the analysis window. Segmentation dimensions include product type, material grade, application environment, and end-user industry procurement sophistication. CAGRs derive from fitted growth curves adjusted for API 6D adoption trajectories and stainless steel casting yield improvements. Forecast inputs incorporate Bohai Rim petrochemical construction timelines and India's municipal infrastructure scheme allocations.
Several conditions sit outside the modeled scope, including geopolitical disruption to German and Japanese forging capacity, abrupt EPA methane regulation enforcement changes, and breakthrough metal-seated ball valve cost reductions. Forecasts reflect documented assumptions about certification timeline compression and alloy price stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Pup Joint Market
Valves
Oil Drain Valves Market
Valves
North America Irrigation Valves Market
Valves
Asia-Pacific Industrial Valves Market
Valves
Safety Valve Market
Valves
HVAC Valves Market
Valves
Explosion Proof Solenoid Valves Market
Valves
Explosion Isolation Valves Market
Valves
Fluid Power Cylinder Market
Valves
Sandblast Valves Market
Valves
Global Marine Actuators and Valves Market
Valves
Middle East and Africa Industrial Valves Market
Valves
Expansion Valves Market
Valves
Industrial Valves Market
Valves
Supply Stop Valves Market
Valves
Global Gas Pressure Regulator Market