
 Valve Driver Market | 2026-2036
Valve Driver Market Size, Share, and Industry Trends Forecast 2026-2036
Valve Driver Market Intelligence
A shift from single-source to multi-source procurement is decoupling customer loyalty from legacy component suppliers. Large industrial conglomerates like Emerson Electric Co. leverage extensive distribution networks to maintain market presence. Parker Hannifin Corporation specializes in high-performance hydraulic and pneumatic systems for mobile and industrial applications. Danfoss competes on energy efficiency and system integration, particularly within the HVAC and refrigeration sectors.
A valve driver is an electronic module that translates low-power logic signals into the high-current or high-voltage output needed to actuate an industrial valve. Its primary function is to provide precise, repeatable control over fluid or gas flow in automated processes. Electromechanical and electrohydraulic product types command a significant share due to their robustness in heavy industries. Demand from water management and chemical processing applications continues to expand, driven by the need for process automation and safety compliance.
Product design and market access are shaped by standards for electrical safety and electromagnetic compatibility, such as CE marking in Europe. In hazardous environments like petrochemical plants, certifications including ATEX and IECEx are mandatory. Future competitiveness depends on aligning product development with the accelerating shift toward intelligent, network-connected valve control systems.
Market Dynamics
The integration of digital communication protocols like HART and Fieldbus is the central force shaping the valve driver market. This shift moves the product's function from simple actuation to an intelligent node in automated process control networks.
Growth Catalysts
- Building Automation:Upgrades to advanced HVAC systems in commercial and public buildings to improve energy efficiency rely on precise valve control.
- Digital Protocols:The adoption of HART and Fieldbus in chemical processing enables remote diagnostics and more accurate flow regulation, boosting safety.
- Infrastructure Investment:New water management projects in China require large volumes of automated valves and their associated drivers.
Market Restraints
- Component Volatility:Unpredictable supply chains for essential microcontrollers and power semiconductors create production bottlenecks and increase lead times.
- Legacy System Integration:The high cost of retrofitting older industrial plants with modern, digitally-enabled valve drivers inhibits widespread adoption.
- Low-Cost Substitutes:Simple solenoid valves or manual controls remain a viable, cheaper alternative for non-critical applications, capping market potential.
Strategic Opportunities
- Hazardous Environment Compliance:Developing drivers with advanced intrinsic safety features to meet stricter ATEX and IECEx certifications opens premium segments in oil and gas.
- Smart Water Grids:Expansion into smart water networks in markets like India creates demand for networked valve controls for leak detection.
- Refrigerant Regulation:EU F-Gas regulations create opportunities for drivers that enable precise refrigerant flow control in next-generation HVAC-R systems.
Industry Challenges
- Cybersecurity Threats:Securing network-connected valve drivers against malicious attacks is a critical challenge for operators of infrastructure like power plants.
- Certification Delays:The lengthy and expensive process for obtaining mandatory CE marking and IECEx certifications can stall new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Valve Driver Market |
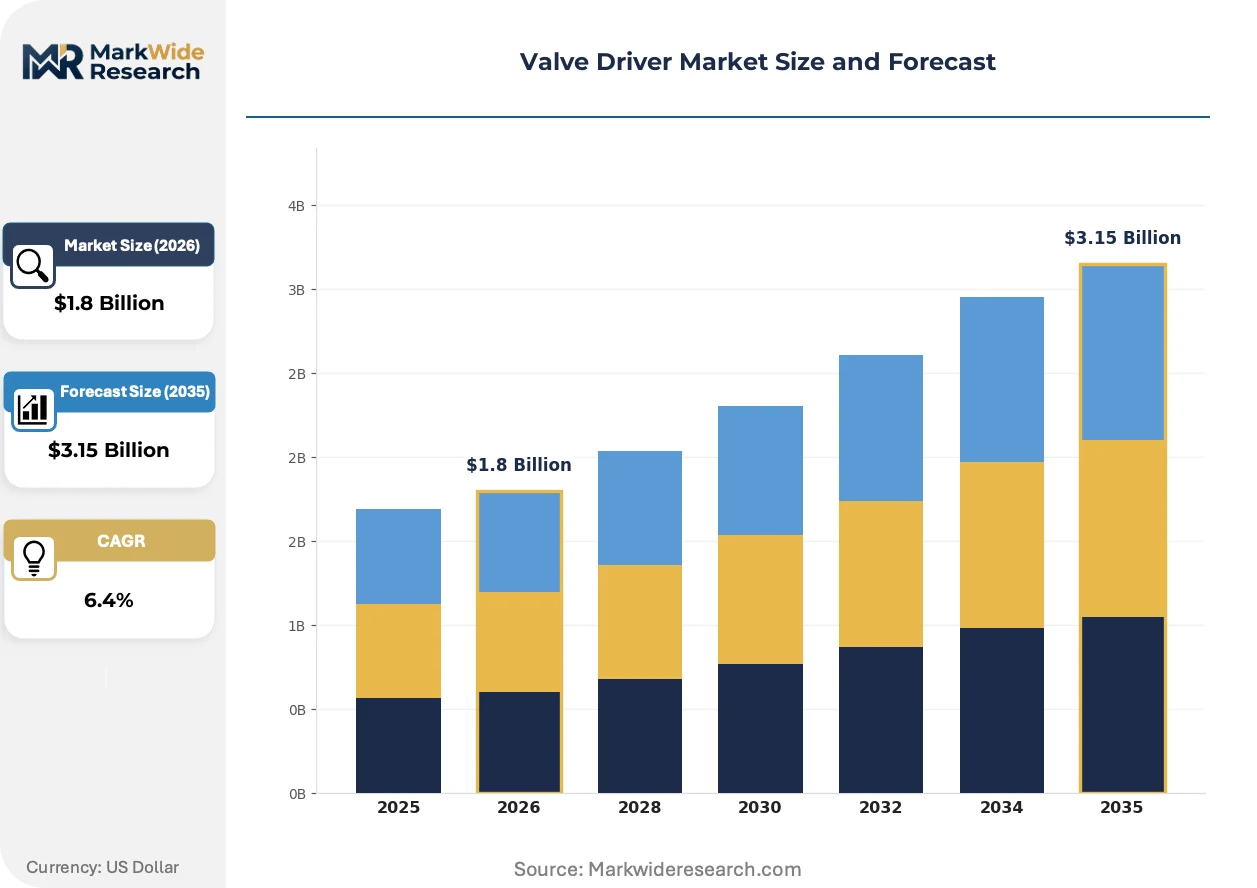
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Piezoelectric, Pneumatic, Hydraulic, Electrohydraulic Technology: Analog, Digital, Pulse Width Modulation, Linear, Rotary Application: Oilfield Equipment, Chemical Processing, Power Generation, HVAC Systems, Water Management End User: Petrochemical Plants, Manufacturing Units, Utilities, Building Automation, Agriculture |
| Companies Covered | Emerson Electric Co., Parker Hannifin Corporation, Danfoss, Carel Industries S.p.A., Flowserve Corporation, Honeywell International Inc., Hydraforce Inc., Sanhua International, Inc., Fujikoki Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Valve Driver Market Strategic Shifts & Innovations
The fusion of operational technology with information technology is redefining the valve driver's role within industrial ecosystems. Value is migrating from basic electromechanical actuation toward intelligent, data-rich control and diagnostics integrated directly at the valve.
Predictive maintenance algorithms embedded within driver firmware represent a key product evolution. These systems analyze operational data like cycle counts to forecast valve degradation. The oil and gas industry adopts this technology to minimize failures, as it is automating maintenance scheduling and preventing costly unplanned downtime.
European Union directives like the Corporate Sustainability Reporting Directive (CSRD) create new compliance burdens. The regulation compels large industrial operators to disclose detailed energy consumption and process efficiency metrics. This affects the chemical sector, which seeks intelligent valve drivers that provide auditable performance data for reporting.
A behavioral change toward system-level procurement is evident among large industrial end-users. This model favors integrated packages comprising the valve, actuator, and driver from a single source, disrupting specialist component suppliers. The trend is most pronounced in new petrochemical plant construction across the Middle East.
Valve Driver Market Segmentation
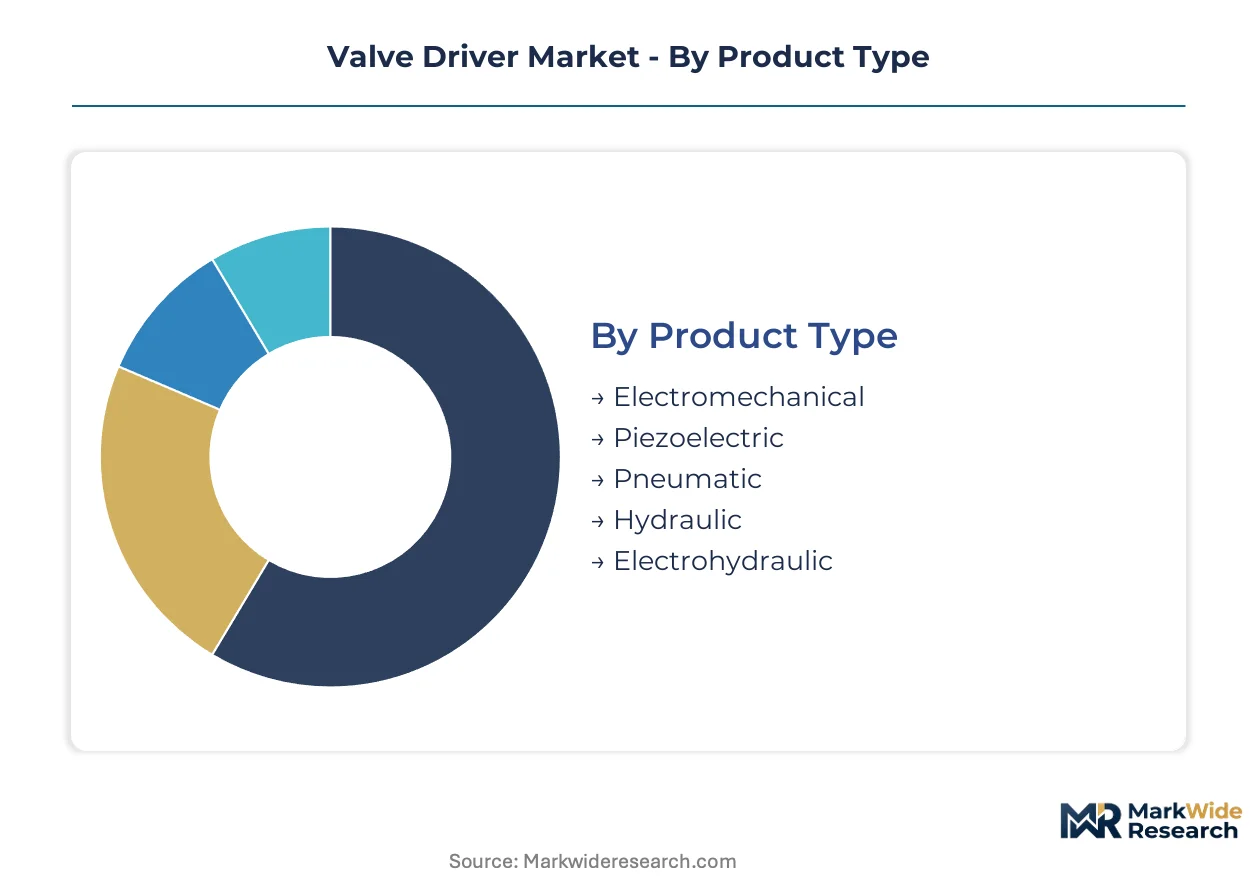
The valve driver market segments based on fundamental technical specifications and diverse end-use requirements. Understanding these distinctions clarifies the competitive landscape and highlights areas of concentrated demand across industrial sectors.
Product Type:
Valve driver product types are differentiated by their core actuation mechanism and power delivery specifications.
- Electromechanical:Electromechanical valve drivers utilize electric motors or solenoids to convert electrical energy into mechanical motion, offering robust and reliable actuation. Their demand concentrates in heavy industrial sectors like power generation, driven by the need for proven, durable control solutions.
- Piezoelectric:Piezoelectric drivers employ ceramic materials that change shape in response to an electric field, providing extremely fine, rapid positioning for microfluidic and precision applications.
- Pneumatic:Pneumatic valve drivers use compressed air to generate linear or rotary motion, offering inherent safety in explosive atmospheres and simple operation.
- Hydraulic:Hydraulic drivers harness pressurized fluid to deliver high force and torque, suitable for large valves and heavy-duty industrial machinery.
- Electrohydraulic:Electrohydraulic drivers combine electrical control with hydraulic power, delivering high force and precise positioning for demanding applications. The oil and gas industry shows significant demand for these systems, especially in hazardous environments requiring powerful, fail-safe operation.
Electromechanical drivers lead on scale; Electrohydraulic systems lead on momentum.
Technology:
The technological maturity and control sophistication define distinct segments within valve driver functionality.
- Analog:Analog valve drivers receive and process continuous electrical signals, providing proportional control based on voltage or current levels.
- Digital:Digital valve drivers process signals using microcontrollers, enabling advanced diagnostics and integration with industrial communication networks. Their adoption is accelerating in chemical processing plants across Europe, driven by stringent process control and data reporting requirements from regulations like CSRD.
- Pulse Width Modulation:Pulse Width Modulation (PWM) drivers control valve position by varying the duration of electrical pulses, achieving fine resolution and energy efficiency. HVAC systems increasingly utilize PWM drivers to optimize energy consumption in commercial buildings, responding to global energy efficiency mandates.
- Linear:Linear drivers produce straight-line motion to actuate globe or gate valves, essential for applications requiring precise flow regulation.
- Rotary:Rotary drivers generate rotational motion for ball, butterfly, or plug valves, commonly used for on/off or throttling control.
Digital technologies demonstrate the steepest expansion trajectory, while Analog systems maintain a foundational installed base.
Application:
Demand for valve drivers varies significantly across different industrial applications, reflecting diverse operational requirements and environmental conditions.
- Oilfield Equipment:Oilfield equipment applications require robust valve drivers capable of withstanding extreme pressures and temperatures in drilling and extraction processes.
- Chemical Processing:Chemical processing applications require valve drivers capable of precise flow control and material compatibility, often operating in corrosive or high-temperature environments. The need for enhanced safety and regulatory compliance in plants across Germany drives demand for advanced, digitally-enabled drivers.
- Power Generation:Power generation facilities deploy valve drivers for steam, water, and fuel control, demanding high reliability and fast response times for critical systems.
- HVAC Systems:HVAC systems integrate valve drivers to manage the flow of heating and cooling fluids, optimizing indoor climate control and energy usage. Building automation projects in China are significantly increasing demand for these components, supporting new infrastructure developments.
- Water Management:Water management applications use valve drivers for controlling water flow in municipal networks, treatment plants, and irrigation systems, focusing on efficiency and leak detection.
Chemical Processing applications exhibit substantial demand, with HVAC Systems showing consistent growth.
End User:
The end-user landscape for valve drivers reflects specific operational scales and regulatory environments that shape product requirements.
- Petrochemical Plants:Petrochemical plants deploy valve drivers in critical processes for refining and chemical production, demanding high reliability and hazardous area certifications. Middle Eastern new plant construction projects are a primary source of demand, requiring integrated valve, actuator, and driver packages.
- Manufacturing Units:Manufacturing units utilize valve drivers for process automation in diverse industries, including automotive, food and beverage, and pharmaceuticals.
- Utilities:Utilities, including water, gas, and electricity providers, integrate valve drivers into their infrastructure for distribution, safety, and operational control.
- Building Automation:Building automation systems utilize valve drivers to manage HVAC, water, and fire suppression systems within commercial and public structures. Public sector infrastructure upgrades in India are driving significant procurement, focusing on energy efficiency and smart building integration.
- Agriculture:Agriculture employs valve drivers in irrigation systems and climate-controlled greenhouses, enabling automated water and nutrient delivery.
Petrochemical Plants represent high-value deployments, while Building Automation drives volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global valve driver market exhibits regional variations influenced by diverse regulatory frameworks and compliance costs. These disparities create a landscape where production and market focus can shift based on national requirements. Such regulatory arbitrage impacts investment decisions and product development priorities.
China
China's robust infrastructure investment and industrial upgrades drive substantial demand for valve drivers, particularly in advanced HVAC systems. The country's dual carbon goals necessitate energy-efficient solutions, influencing product development. Manufacturing hubs like the Yangtze River Delta are seeing significant deployment in new commercial buildings.
Germany
Germany's advanced chemical processing sector requires sophisticated valve drivers for precise control and data reporting, aligning with stringent process control needs. EU directives like CSRD compel industrial operators to disclose detailed efficiency metrics, boosting demand for intelligent drivers. Industrial clusters in North Rhine-Westphalia are implementing digitally-enabled drivers for enhanced safety and compliance.
India
India's expanding smart water networks and public sector infrastructure upgrades create significant demand for networked valve controls, particularly for leak detection. Government initiatives like the PLI scheme support domestic manufacturing, impacting supply chain dynamics. Major urban centers in Maharashtra are integrating smart building solutions that rely on advanced valve drivers.
United States
United States demand for valve drivers remains strong in oil and gas and power generation sectors, requiring robust and reliable control solutions. OSHA regulations drive the adoption of advanced safety features in industrial equipment, including valve drivers for hazardous environments. The Gulf Coast region, particularly Texas, sees continuous investment in petrochemical plants needing high-performance actuation.
United Arab Emirates
The United Arab Emirates is investing heavily in new petrochemical plant construction and critical infrastructure, driving demand for integrated valve, actuator, and driver packages. Safety standards mandated by MOHAP ensure compliance for equipment deployed in hazardous industrial zones. Major industrial developments in Abu Dhabi prioritize advanced valve control systems for efficient and secure operations.
Valve Driver Market Key Industry Players
Established producers occupy the standard tier of the valve driver market, while emerging entrants pursue intelligent, network-connected valve control systems. The market structure is tiered, with large industrial conglomerates leveraging extensive distribution networks. Specialized firms focus on high-performance hydraulic and pneumatic systems, and others compete on energy efficiency and system integration. Dominant competitive moves include strategic partnerships for system integration and continuous product development to align with digital communication protocols.
Within the segment of large industrial conglomerates leveraging broad market reach, Emerson Electric Co. represents a significant presence through its extensive distribution networks, maintaining market presence across various industrial applications. Parker Hannifin Corporation exemplifies specialization in high-performance hydraulic and pneumatic systems, catering to demanding mobile and industrial applications requiring precise control. Danfoss occupies a position as a key competitor focused on energy efficiency and system integration, particularly within the HVAC and refrigeration sectors, aligning with system-level procurement trends.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Parker Hannifin Corporation |
| Danfoss |
| Carel Industries S.p.A. |
| Flowserve Corporation |
| Honeywell International Inc. |
| Hydraforce Inc. |
| Sanhua International, Inc. |
| Fujikoki Corporation |
| Others |
Cost & Logistics Intelligence
The certification ladder, ranging from standard CE marking to stringent ATEX and IECEx, creates a pronounced tier divergence in the valve driver market. This distinction heavily influences both pricing structures and supply chain configurations, especially for hazardous environment applications.
Pricing Analysis
Distributor margins often reflect the technical complexity and required certifications of valve drivers. The dominant pricing model is per-unit transactional, though large-scale industrial projects often utilize contract-based long-term offtake agreements. Price differentiation stems from the certification level, such as IECEx for explosion-proof environments, and the degree of customization for specific industrial processes. Pricing softness runs through standard electromechanical drivers due to component volatility and the availability of low-cost substitutes. General manufacturing units demonstrate the highest price sensitivity, while petrochemical plants show the least for critical, compliant systems.
Supply Chain Analysis
Direct-to-OEM channels manage integrated valve driver packages for large petrochemical projects, while value-added distributors serve broader industrial clients. Geographic supply concentration for valve drivers primarily resides in China, Germany, and the United States. The market draws from critical raw material dependencies including microcontrollers, power semiconductors, and specialized alloys. A structural risk is single-source vulnerability for advanced microcontrollers, creating production bottlenecks. The dominant downstream structure is a hybrid model, combining direct sales for large-scale system integrators with extensive distributor networks for aftermarket and smaller OEM requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The valve driver market is evolving into a late-cycle quality story, driven by a pronounced demand-shift toward intelligent, network-connected valve control systems.
For Market Incumbents:
Cement long-term customer relationships by investing in advanced digital communication protocols like HART and Fieldbus. This counters the threat of new entrants specializing in smart control systems. Pursue strategic partnerships for comprehensive system integration, leveraging extensive distribution networks to maintain market presence against specialist component suppliers. Prioritize R&D in robust cybersecurity features for network-connected valve drivers.
For New Entrants and Emerging Players:
Advanced intrinsic safety features represent a technology-first wedge into premium segments like oil and gas. Target hazardous environments in the Middle East with IECEx certified drivers for powerful, fail-safe operation. The most penetrable segment is smart water grids in India, offering opportunities for networked valve controls. A go-to-market angle focusing on predictive maintenance algorithms embedded in firmware can capture early adopters seeking operational efficiency.
For Investors and Strategic Acquirers:
Consolidation pressure builds where specialized expertise in digital integration and hazardous environment compliance is scarce. The market demonstrates long-term viability, particularly in segments driven by infrastructure upgrades and energy efficiency mandates. Acquisition targets include agile firms with proprietary intelligent valve control software or unique certification portfolios. Watch for increased M&A activity among mid-tier players as a signal of market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-powered predictive maintenance | This extends product lifespan and reduces unplanned downtime for industrial operators. |
| Expand ATEX/IECEx certified product lines | This unlocks high-value opportunities in the stringent oil and gas sector. |
| Form system integration alliances | These partnerships offer comprehensive solutions to end-users seeking full automation packages. |
| Invest in secure digital communication modules | This addresses cybersecurity threats in critical infrastructure like power plants. |
| Localize manufacturing in key growth regions | This mitigates supply chain volatility and improves market access in China and India. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core for this valve driver market study. Primary interviews with plant engineers, procurement leads, and system integrators provided granular insights. This was validated against secondary data from industry association reports, patent databases, and company financial filings. The approach ensures robust triangulation of market sizing and growth projections.
An input-output matrix underpins the quantitative forecast, mapping component demand to end-use application growth across the analysis window. Segmentation dimensions include product type, technology, application, and end-user, with a specific focus on hazardous environment certifications. Compound annual growth rates were derived from historical data trends and projected industry shifts. Key forecast inputs included infrastructure investment rates and regulatory compliance timelines.
The model holds under prevailing macroeconomic conditions and current regulatory frameworks; deviation in global trade policies or component supply stability would shift projections. Forecasts reflect assumptions regarding technological adoption rates and end-user investment priorities. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Vacuum Insulated Pipe Market
Valves
Europe Industrial Valves Market
Valves
Chemical Injection Skid Market
Valves
Float Traps Market
Valves
Pipeline Integrity Management (PIM) Market
Valves
Europe Medium Voltage Switchgear Market
Valves
Hot Blast Valves Market
Valves
Emergency Venting System Market
Valves
3-Way Pilot Operated Directional Control Valves Market
Valves
North America Irrigation Valves Market
Valves
Pipeline Pigging System Market
Valves
Degassing Valves Market
Valves
Air Heated Vaporizer Market
Valves
Steam Trap Valve Market
Valves
Air Jet Ejectors Market
Valves
Explosion Isolation Valves Market