
 Valve Remote Control System Market | 2026-2036
Valve Remote Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Valve Remote Control System Market Intelligence
The Valve Remote Control System market is restructuring around a widening gap between SIL-certified premium systems for hazardous environments and basic electric actuators serving non-critical water applications. Emerson Electric leverages its DeltaV integration platform to dominate upstream oil and gas projects requiring fail-safe redundancy. Rotork anchors its position through in-house production of both electric and hydraulic actuator lines, reducing lead times for large-scale power utility contracts. KSB differentiates via specialized marine-grade coatings that extend service life in corrosive offshore environments.
A valve remote control system comprises electromechanical, pneumatic, or hydraulic actuators coupled to centralized control interfaces, typically operating within pressure ratings of 150 to 2500 psi and temperature ranges from -60°C to 200°C depending on seal material selection. Electric valve controllers lead installed base volumes across chemical processing facilities where precise modulating control proves essential. Wireless technology represents the fastest-expanding connectivity segment as operators eliminate cabling costs on sprawling refinery complexes. Energy producers constitute the deepest margin pool among end users due to their specification of redundant control architectures and long-term service contracts.
FDA oversight of pharmaceutical manufacturing processes shapes sanitary valve control specifications in the United States, while EPA emissions mandates accelerate pneumatic system retrofits across petrochemical corridors along the Gulf Coast. The EU's ATEX directives and IEC 61508 functional safety standards constrain market access for uncertified suppliers across European chemical processing hubs. Stakeholders must weigh the capital cost of full wireless migration against the operational resilience of hybrid wired-wireless architectures as facility footprints expand and cybersecurity frameworks tighten.
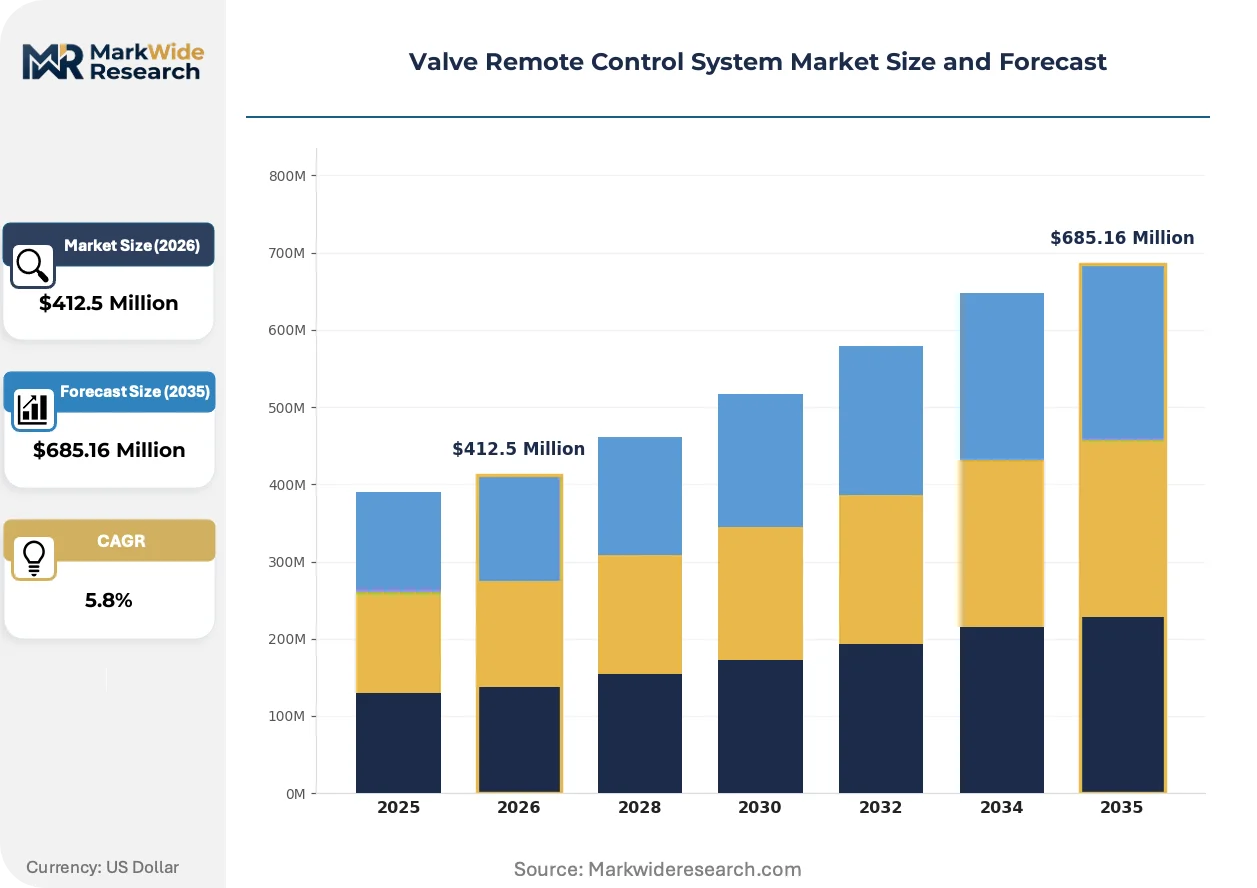
Market Dynamics
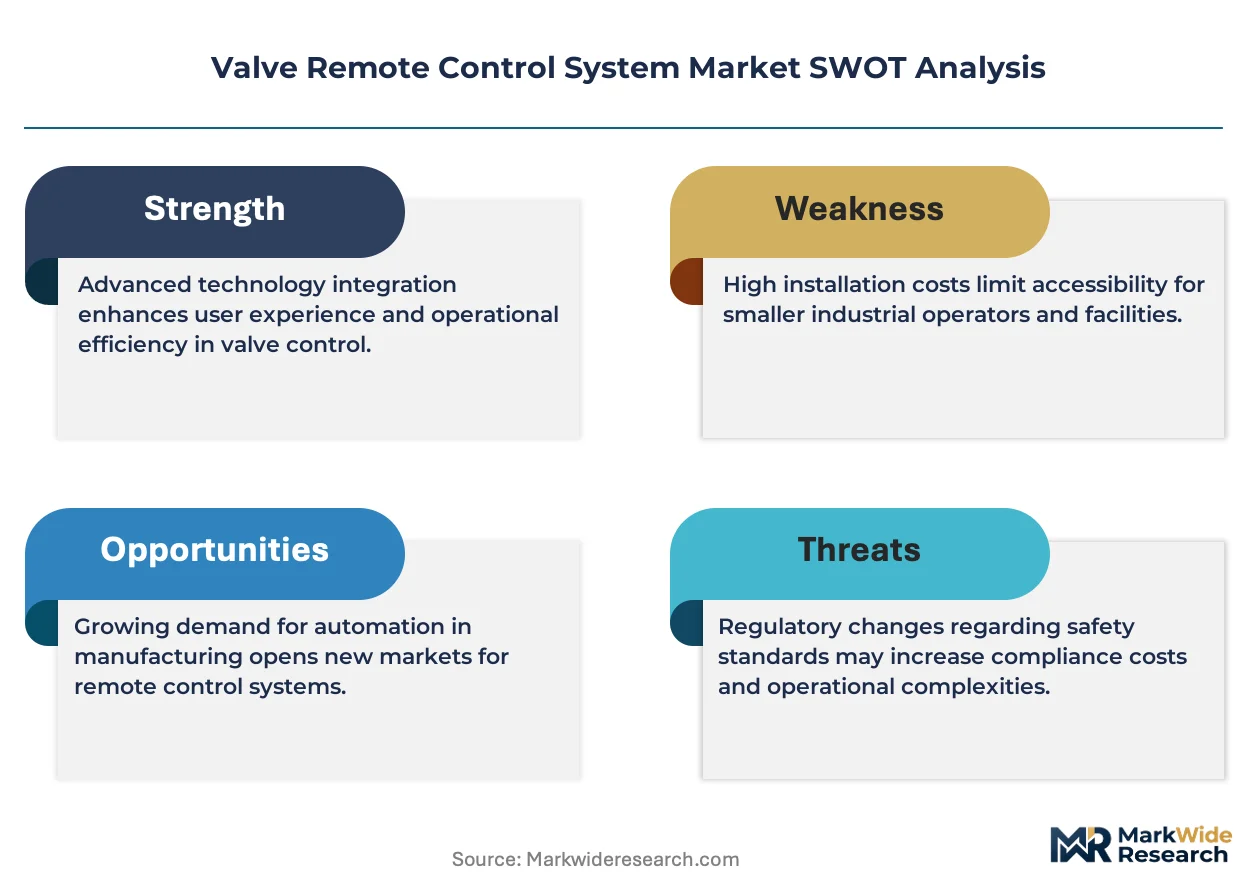
Retrofit cycles on aging North Sea platforms are compressing replacement timelines, forcing operators to choose between full platform electrification and modular pneumatic upgrades before regulatory deadlines hit.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for hydrofluorocarbon-based pneumatic systems push operators toward nitrogen-actuated alternatives with negligible global warming potential.
- Subsea infrastructure expansion:Norway's Equinor and Aker BP maintain extensive brownfield modification programs requiring SIL-certified valve control architectures.
- Wireless connectivity:Elimination of multi-kilometer cable runs on sprawling refinery complexes cuts installation costs and commissioning timelines by half.
Market Restraints
- Stainless steel price volatility:Marine-grade 316L and super-duplex alloys constitute 35-40% of actuator housing costs, exposing margins to nickel and molybdenum commodity swings.
- Hydraulic fluid supply concentration:Biodegradable synthetic ester production clusters in German and Belgian chemical corridors, creating single-source vulnerability for offshore hydraulic systems.
- Substitution by manual override systems:Non-critical water treatment facilities in municipal sectors bypass automation entirely, capping addressable market depth.
Strategic Opportunities
- Floating offshore wind:Dynamic cable-connected platforms off Scotland and France require subsea valve control for ballast and mooring tensioning systems.
- Carbon capture injection:High-pressure CO2 transport networks need corrosion-resistant actuators rated for dense-phase operation at 2000+ psi.
- India's PLI scheme:Domestic manufacturing incentives for process equipment create localized assembly opportunities for pneumatic actuator lines.
Industry Challenges
- Cybersecurity certification backlog:IEC 62443 compliance testing for wireless valve controllers faces 14-18 month queue times at accredited laboratories.
- SIL validation complexity:Third-party functional safety assessments for redundant architectures extend project timelines and strain engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Valve Remote Control System Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Valve Controllers, Pneumatic Valve Controllers, Hydraulic Valve Controllers, Manual Override Systems Technology: Wireless, Wired, Bluetooth, Infrared, Radio Frequency Application: Oil Exploration, Water Treatment, Chemical Processing, Power Generation, Waste Management End User: Energy Producers, Municipal Water Authorities, Chemical Manufacturers, Power Utilities |
| Companies Covered | Flowserve, Honeywell International, Emerson Electric, Valmet, Nordic Group Limited, Rotork, KSB, Scana Skarpenord, Wärtsilä, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Valve Remote Control System Market Strategic Shifts & Innovations
Digital twin deployment is compressing commissioning cycles and enabling predictive maintenance models that shift service revenue from reactive repairs to subscription-based uptime guarantees.
Edge computing hardware is integrating directly into electric actuator enclosures, enabling localized loop control without round-trip latency to distributed control systems. Offshore operators in the North Sea are piloting these architectures on unmanned platform retrofits. The technology is integrating machine-learning-based seal degradation models that trigger maintenance windows before failure.
The EPA's methane emissions rules for new and modified oil and gas facilities mandate pneumatic controller replacement or vapor capture systems across Gulf Coast petrochemical corridors. Compressor stations and gathering lines face the steepest compliance costs. Midstream operators are responding by consolidating valve control procurement under single-source automation integrators to streamline certification documentation.
Service contract unbundling is fragmenting the traditional bundled actuator-plus-maintenance model into separate hardware, software, and field service line items. Refinery operators in Rotterdam and Antwerp now benchmark actuator suppliers on spare parts availability metrics rather than total cost of ownership. This shift favors vendors with regional stocking depots over those relying on centralized European distribution.
Valve Remote Control System Market Segmentation
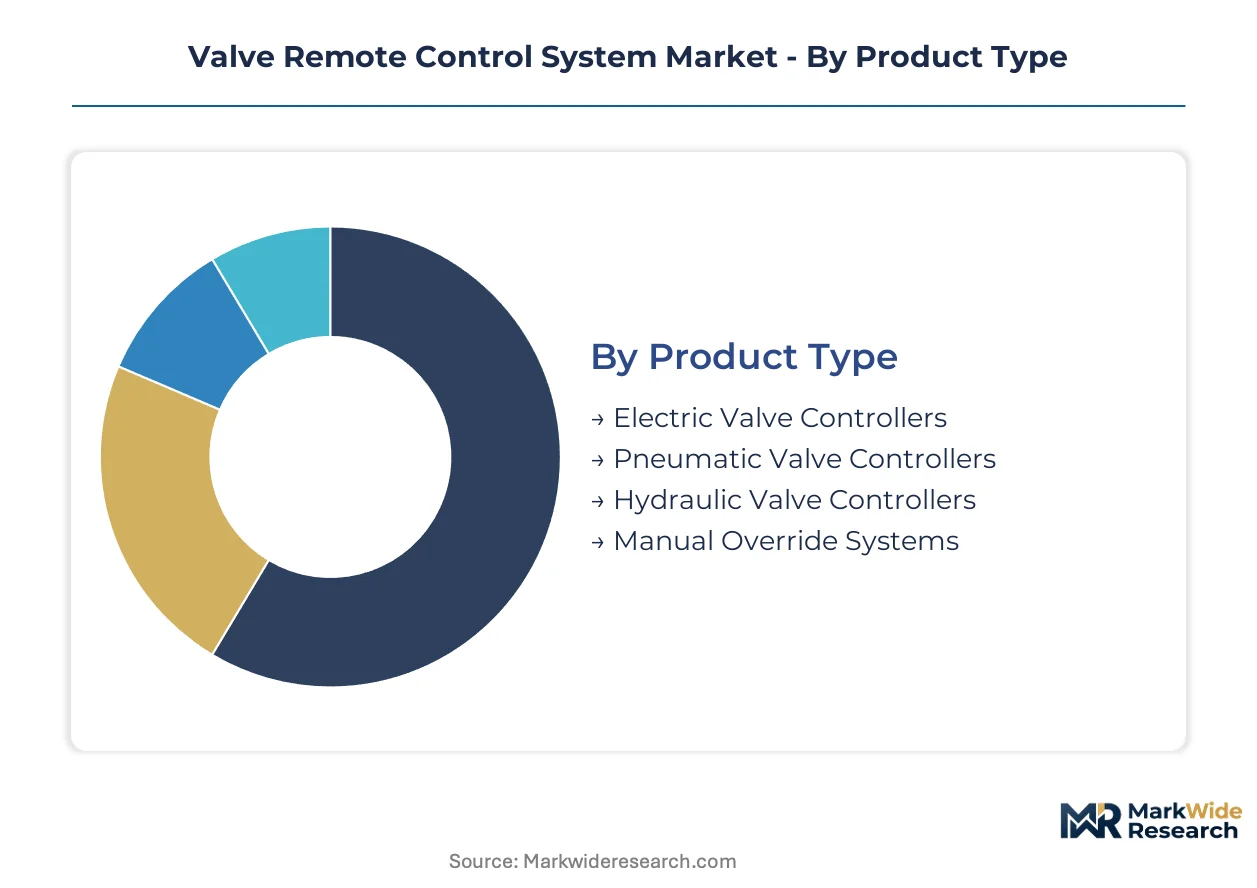
Segmentation in valve remote control systems tracks a fundamental divergence between standalone retrofit units and deeply embedded automation architectures. Procurement patterns differ sharply across these integration depths, with energy sector buyers favoring unified control platforms while municipal operators prioritize modular, interoperable components.
Product Type:
Integration depth varies substantially across actuator technologies, with some categories designed for standalone retrofit deployment and others engineered for seamless DCS integration.
- Electric Valve Controllers:These units combine brushless DC motors with position feedback encoders, delivering precise modulating control for throttling applications. Chemical processing facilities in Germany's Ludwigshafen cluster specify these for reactor feed regulation, driven by IEC 61508 SIL requirements for safety loops.
- Pneumatic Valve Controllers:Compressed air-driven actuators with spring-return fail-safe configurations dominate hazardous area installations. Norway's North Sea platform retrofits favor nitrogen-actuated variants to comply with EU F-Gas Regulation phase-down mandates for hydrofluorocarbon systems.
- Hydraulic Valve Controllers:High-force output systems for large-bore isolation valves in subsea manifolds.
- Manual Override Systems:Handwheel or lever-actuated backups specified for non-critical municipal water distribution nodes.
Electric controllers lead volumes today; pneumatic alternatives are gaining share fastest in offshore electrification programs.
Technology:
Connectivity architecture selection directly shapes commissioning complexity and long-term cybersecurity exposure for facility operators.
- Wireless:ISA100.11a and WirelessHART protocols eliminate multi-kilometer cable runs across sprawling refinery complexes. Rotterdam-Antwerp petrochemical corridor operators are expanding these networks for tank farm valve clusters, cutting installation timelines substantially.
- Wired:Hardwired 4-20 mA and fieldbus connections maintain dominance in safety-critical loops where electromagnetic interference resilience is paramount. Power utilities in France's nuclear fleet mandate these for primary containment isolation.
- Bluetooth:Short-range commissioning and diagnostics access for maintenance technicians.
- Infrared:Line-of-sight local configuration in hazardous areas where radio emissions are restricted.
- Radio Frequency:Proprietary long-range links for geographically dispersed pipeline compressor stations.
Wired infrastructure retains the largest installed base; wireless deployment is expanding most quickly in greenfield refinery construction.
Application:
End-use environment severity dictates material specifications, with corrosive media and extreme pressure ratings segmenting demand sharply.
- Oil Exploration:Subsea and topside production systems require actuators rated for 15,000 psi wellhead pressures and sour service H2S exposure. Brazil's pre-salt developments drive specification of super-duplex stainless constructions with 25-year design lives.
- Water Treatment:Potable and wastewater facilities utilize epoxy-coated ductile iron actuators with IP68 submersion ratings. India's Smart Cities Mission is accelerating automated valve deployment across metropolitan distribution networks.
- Chemical Processing:Aggressive media handling with PTFE-lined or Hastelloy trim options.
- Power Generation:Steam cycle isolation and turbine bypass systems requiring high-temperature seal materials.
- Waste Management:Landfill gas collection and leachate control with explosion-proof enclosures.
Water treatment applications represent the broadest volume base; oil exploration commands the steepest per-unit pricing tier.
End User:
Procurement sophistication and service contract structures diverge markedly across buyer categories, from integrated energy majors to fragmented municipal authorities.
- Energy Producers:Integrated oil companies and independents specify redundant control architectures with comprehensive spare parts agreements. Saudi Aramco's long-term service contracts with automation integrators bundle valve control maintenance into platform-wide uptime guarantees.
- Municipal Water Authorities:Public sector procurement emphasizes interoperable open protocols and lowest lifecycle cost evaluation. Dutch water boards benchmark suppliers on 20-year total cost models including energy consumption and predictive maintenance enablement.
- Chemical Manufacturers:Batch and continuous process operators with ATEX zone classification requirements.
- Power Utilities:Grid-connected generators with turbine governor valve control needs.
Energy producers dominate premium segment revenue; municipal authorities are expanding procurement most quickly in emerging economy infrastructure programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized engineering talent clusters in Norway's subsea automation sector anchor European demand, while Gulf Coast petrochemical corridors concentrate North American procurement expertise. Asian manufacturing hubs in India and South Korea are building actuator assembly capacity for export markets.
Norway
Equinor and Aker BP drive brownfield platform retrofits requiring SIL-certified valve architectures. The EU F-Gas Regulation accelerates nitrogen-actuated system adoption across North Sea installations. Stavanger's subsea engineering cluster houses specialized commissioning teams for unmanned platform automation.
United States
EPA methane emissions rules force pneumatic controller replacements across Texas and Louisiana petrochemical corridors. Midstream operators consolidate procurement under automation integrators to streamline compliance documentation. Houston's energy automation sector specializes in redundant control architectures for compressor stations.
Germany
Chemical processing facilities in Ludwigshafen specify electric valve controllers for reactor feed regulation under IEC 61508 requirements. ECHA chemical safety frameworks shape actuator material specifications for aggressive media handling. The Ruhr industrial basin maintains demand for high-temperature steam cycle isolation systems.
India
The PLI scheme for process equipment creates localized assembly opportunities for pneumatic actuator lines. Municipal water authorities in Delhi and Mumbai deploy automated valves under Smart Cities Mission infrastructure programs. Gujarat's chemical manufacturing belt drives specification of corrosion-resistant actuator coatings.
South Korea
Shipbuilders in Ulsan and Busan specify marine-grade valve control systems for LNG carrier and offshore vessel newbuilds. MFDS oversight of pharmaceutical manufacturing shapes sanitary valve specifications for domestic biotech facilities. The country's industrial automation sector is integrating valve control into smart factory platforms.
Valve Remote Control System Market Key Industry Players
Top-tier vendors anchor premium SIL-certified segments, while mid-tier specialists compete on lead times for standard industrial applications. The market structure reflects a bifurcation between integrated automation platforms and standalone actuator suppliers. Two strategic archetypes dominate: diversified industrial conglomerates with control system integration capabilities, and focused actuator manufacturers with in-house production of multiple drive technologies. Competitive moves center on geographic expansion into emerging economy infrastructure programs and technology licensing for wireless connectivity modules.
Among diversified industrial conglomerates, Emerson Electric and Honeywell International exemplify the integrated automation platform archetype, bundling valve control within distributed control system offerings. Flowserve occupies a position as a dedicated flow control specialist with broad actuator portfolio coverage. Rotork represents the focused actuator manufacturer model, with in-house production spanning electric and hydraulic drive lines. These three companies collectively illustrate the competitive tension between full-platform integration and component specialization strategies.
| Leading Market Players |
|---|
| Flowserve |
| Honeywell International |
| Emerson Electric |
| Valmet |
| Nordic Group Limited |
| Rotork |
| KSB |
| Scana Skarpenord |
| Wärtsilä |
| Others |
Cost & Logistics Intelligence
Family-owned German actuator specialists and private-equity-consolidated mid-caps anchor supply-side discipline, translating captive forging capacity into pricing power for super-duplex housings while resisting margin erosion on standard electric lines. This ownership concentration feeds directly into procurement behavior, with long-tenured supplier relationships shielding premium tiers from commodity volatility that compresses spot-market pricing for unbundled hardware.
Pricing Analysis
The bundled-versus-unbundled service split now defines transaction structures across the valve remote control system market. Pricing stratifies across SIL-certified premium architectures, standard industrial electric actuators, and economy-grade pneumatic units for non-critical water applications, with differentiation driven by certification grade and geographic delivery cost. Cost compression in the standard tier is intensifying because municipal buyers benchmark spare parts availability against total cost of ownership, while energy producers show lowest price sensitivity due to uptime guarantee requirements. Subscription-based predictive maintenance contracts are displacing traditional hardware-plus-service bundles in offshore retrofits.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore anchor hub-and-spoke fulfillment patterns for actuator assemblies and spare parts. Manufacturing concentrates in Germany, Norway, and South Korea, with super-duplex stainless and specialized synthetic hydraulic fluids drawing from Belgian chemical corridors and Nordic metallurgical clusters. Single-source vulnerability in biodegradable ester production creates supply chain risk for offshore hydraulic systems. Distribution runs through authorized integrator networks rather than direct OEM-to-end-user channels, with Rotterdam-Antwerp petrochemical corridor operators consolidating procurement under automation specialists to streamline compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The valve remote control system market offers margin expansion through service contract unbundling and predictive maintenance subscription conversion, with digital twin deployment reducing field service costs while locking in recurring revenue streams.
For Market Incumbents: Anchor defensive positioning through backward integration into seal manufacturing and captive forging capacity for super-duplex housings, insulating margins from nickel and molybdenum commodity swings. Deepen regional stocking depot networks in Norway's North Sea cluster and the US Gulf Coast to defend against lead-time-based competitive threats from mid-tier specialists. Prioritize IEC 62443 cybersecurity certification investment to capture wireless retrofit cycles ahead of 14-18 month laboratory queue times. For New Entrants and Emerging Players: The price-point gap between premium SIL-certified systems and basic municipal water actuators creates white-space opportunity for mid-tier specialists with modular, interoperable architectures. Target India's PLI scheme-enabled domestic assembly opportunities for pneumatic lines, where localized production escapes import duty exposure. Pursue floating offshore wind ballast control applications off Scotland and France as the most penetrable emerging segment, leveraging standard industrial electric platforms adapted for marine-grade coatings. For Investors and Strategic Acquirers: Valuations sit cheapest among focused actuator manufacturers with in-house electric and hydraulic production lines but limited control system integration capabilities. Long-term viability hinges on 5-10 year conversion of hardware revenue to subscription-based uptime guarantees. Watch for inflection where cybersecurity certification backlog clears and wireless valve controller deployment accelerates in greenfield refinery construction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal Manufacturing | Captive PTFE and elastomer production shields margins from specialty polymer supply concentration in German chemical corridors. |
| Regional Distribution Center Expansion | Stavanger and Aberdeen stocking depots capture North Sea platform retrofit demand with 48-hour spare parts availability. |
| Digital Twin Platform Deployment | Emerson Electric and Honeywell integrate valve control data into predictive maintenance subscriptions for Rotterdam refinery operators. |
| Wireless Connectivity Module Licensing | ISA100.11a protocol adoption eliminates multi-kilometer cabling costs across sprawling Antwerp petrochemical complexes. |
| Marine-Grade Coating Specialization | KSB's corrosion-resistant actuator finishes extend service life in Equinor's subsea infrastructure, commanding premium pricing tiers. |
Research Approach
Bottom-up energy sector and municipal water authority modeling reconciled against top-down actuator production tracking forms the analytical core of this study. Primary interviews with maintenance directors at offshore platform operators, automation procurement leads at integrated oil companies, plant engineers in Germany's Ludwigshafen chemical cluster, and aftermarket service heads at regional stocking depots combined with secondary validation from SEC filings of listed automation conglomerates, EIA energy infrastructure databases, EU F-Gas Regulation compliance filings, and Norwegian Petroleum Directorate platform modification records. This triangulation anchors volume and value estimates against actual procurement patterns and documented retrofit timelines.
Historical trendline analysis of installed base replacement cycles and technology substitution patterns informs the projection framework across the analysis window. Segmentation dimensions modeled include actuator technology type, connectivity architecture, application severity, and end-user procurement sophistication, with CAGRs derived from regression against capital expenditure disclosures by major energy producers and municipal infrastructure budget trajectories. Industry-specific forecast inputs incorporate documented SIL certification adoption rates and wireless valve controller pilot deployment metrics from North Sea unmanned platform programs.
Caveats apply where stainless steel commodity volatility, IEC 62443 certification queue extensions, or regulatory deadline shifts for EU F-Gas phase-down mandates could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Pressure Gauge Market
Valves
Asia-Pacific Medium Voltage Switchgear Market
Valves
Valve Seat Inserts Market
Valves
HVAC Valves Market
Valves
Asia Pacific Pipeline Maintenance Market
Valves
Reciprocating Compressor Components Market
Valves
Industrial Valves and Actuators Market
Valves
Vaneometer Market
Valves
North America Irrigation Valves Market
Valves
Pneumatic Needle Valves Market
Valves
Subsea Control System Market
Valves
Sliding Sleeves Market
Valves
Hybrid Valve Market
Valves
Actuators and Valves Market
Valves
Global Valves Market
Valves
US Water & Wastewater Valves Market