
 Global Control Valves Market | 2026-2036
Global Control Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Global Control Valves Market Analysis
Skilled valve technician availability is collapsing across North American and European energy hubs, forcing OEMs to redesign service architectures. Emerson Electric Co. leverages its global service network to embed predictive maintenance contracts directly at refinery sites. Flowserve Corporation anchors its position through backward integration into specialized alloy casting for severe-service trims. SLB competes by extending digital twin capabilities across its control valve portfolio for subsea installations.
Control valves regulate fluid flow, pressure, temperature, and liquid level by varying the size of the flow passage in response to signals from controllers, with typical specifications spanning ANSI pressure classes from 150 to 4500 and temperature ratings from cryogenic to over 800 degrees Celsius. Their primary industrial purpose centers on process stability, safety interlocking, and efficiency optimization across continuous-flow operations. Electric actuation segments are capturing margin pools as plants electrify valve fleets to eliminate instrument air infrastructure, while chemical processing applications demand titanium and super-austenitic stainless steel constructions to survive acid service and chloride cracking environments. Pneumatic variants still dominate installed-base volumes in legacy oil and gas facilities where compressed air systems remain entrenched.
The EPA enforces methane emission thresholds that compel valve packing upgrades and low-leakage stem seal specifications across US petroleum infrastructure. EMA medical device standards and EU F-Gas Regulation phase-down schedules shape material selection and sealing technology in European pharmaceutical and refrigeration-adjacent process lines. China's NMPA and GB standards impose localized testing protocols that condition market access for imported severe-service designs. Stakeholders must monitor how divergent regional certification burdens reshape sourcing geography and whether digital valve positioners become mandatory under evolving cybersecurity frameworks.
Market Dynamics
The EPA methane emission thresholds and EU F-Gas Regulation revisions are forcing simultaneous material upgrades across installed valve bases and new procurement specifications, compressing design cycles while expanding testing burdens for OEMs and end-users alike.
Growth Catalysts
- Upstream automation procurement:Oil and gas operators across Gulf Coast petrochemical corridors are expanding control valve orders for wellhead digitalization and remote monitoring infrastructure.
- EPA methane rules:The EPA enforces low-leakage stem seal specifications that compel packing upgrades across US petroleum infrastructure, generating replacement demand.
- Electric actuation conversion:Process plants are electrifying valve fleets to eliminate instrument air infrastructure, with titanium and super-austenitic stainless steel constructions penetrating acid service environments.
Market Restraints
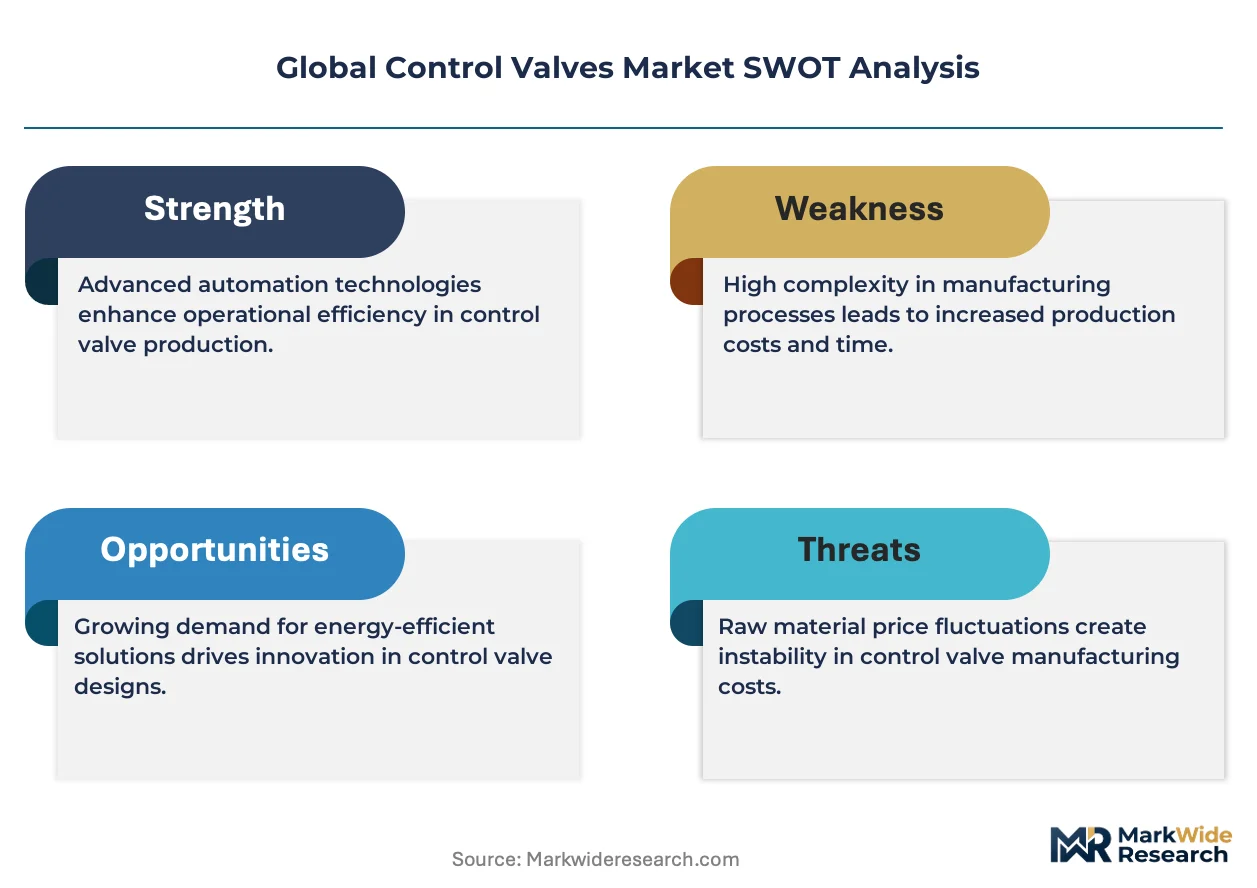
- Specialized alloy input costs:Nickel and cobalt price volatility in super-austenitic grades compresses margins for severe-service trim manufacturers.
- Technician supply collapse:Skilled valve technician availability is contracting across North American and European energy hubs, extending service response times.
- Pneumatic installed-base lock-in:Legacy oil and gas facilities with entrenched compressed air systems resist full electrification conversions due to capital replacement cycles.
Strategic Opportunities
- Chinese state-owned refinery expansions:NMPA and GB standards create localized testing protocols that favor suppliers establishing domestic certification capabilities.
- Digital twin convergence:Subsea installations are integrating valve positioners with predictive analytics platforms, opening premium service contract structures.
- Cybersecurity framework preparation:Evolving digital valve positioner mandates under emerging industrial cybersecurity standards favor early-compliant OEMs.
Industry Challenges
- Certification timeline compression:China's NMPA localized testing protocols extend market access timelines for imported severe-service designs.
- Legacy system integration friction:Electric actuation retrofits face compatibility constraints with existing distributed control system architectures.
- Skill pipeline gaps:Predictive maintenance contract fulfillment requires technicians trained in both mechanical valve service and data analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Control Valves Market |
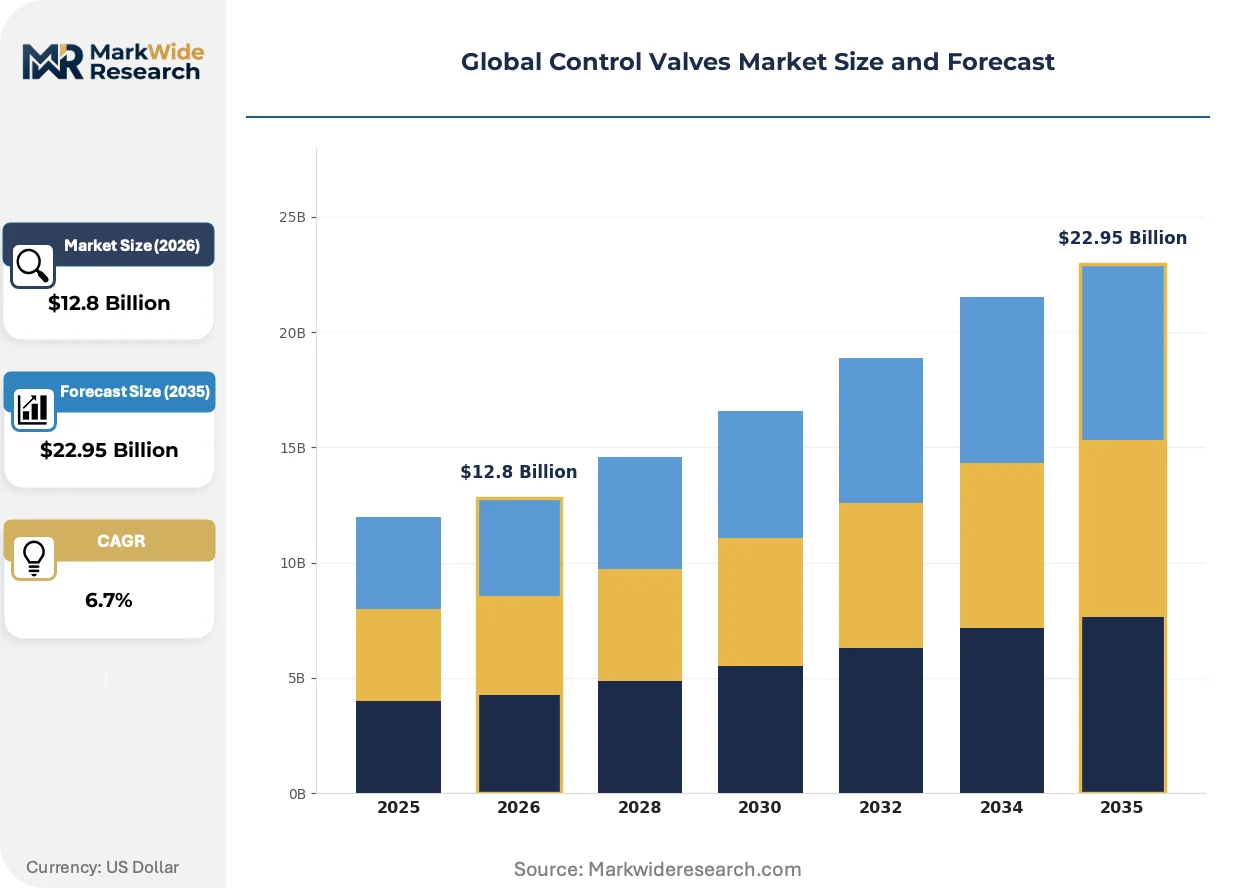
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Pneumatic, Hydraulic, Manual Application: Oil & Gas, Water Treatment, Power Generation, Chemical Processing End User: Energy, Manufacturing, Construction, Pharmaceuticals Material: Stainless Steel, Brass, Plastic, Titanium |
| Companies Covered | Emerson Electric Co., Flowserve Corporation, IMI plc, Curtiss-Wright Corporation, Christian Bürkert GmbH & Co. KG, Valmet, SLB, KITZ Corporation, Crane Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Control Valves Market Emerging Trajectories
Control valve architecture is fragmenting across three simultaneous vectors: component-level digitalization, material science advances for extreme service, and procurement model restructuring that unbundles hardware from lifecycle services.
Digital valve positioners with embedded edge computing capabilities are decomposing traditional maintenance schedules by enabling continuous diagnostic feedback. Refinery operators in German industrial clusters are adopting these units at accelerated pace. The technology is decomposing the historical separation between valve hardware vendors and process control system integrators.
The EU F-Gas Regulation phase-down schedules are compressing refrigerant-adjacent process line specifications, forcing sealing technology upgrades across pharmaceutical manufacturing. EMA medical device standards simultaneously shape material selection for clean steam and WFI applications. European pharmaceutical valve suppliers are responding by consolidating dual-certification capabilities under single product platforms.
Service contract unbundling is accelerating as end-users separate valve procurement from predictive maintenance agreements. Refinery operators along the US Gulf Coast now source hardware through traditional channels while negotiating performance-based service directly with OEM field networks. This bifurcation is most visible in continuous-flow chemical processing where uptime guarantees dominate vendor selection criteria.
Global Control Valves Market Segmentation
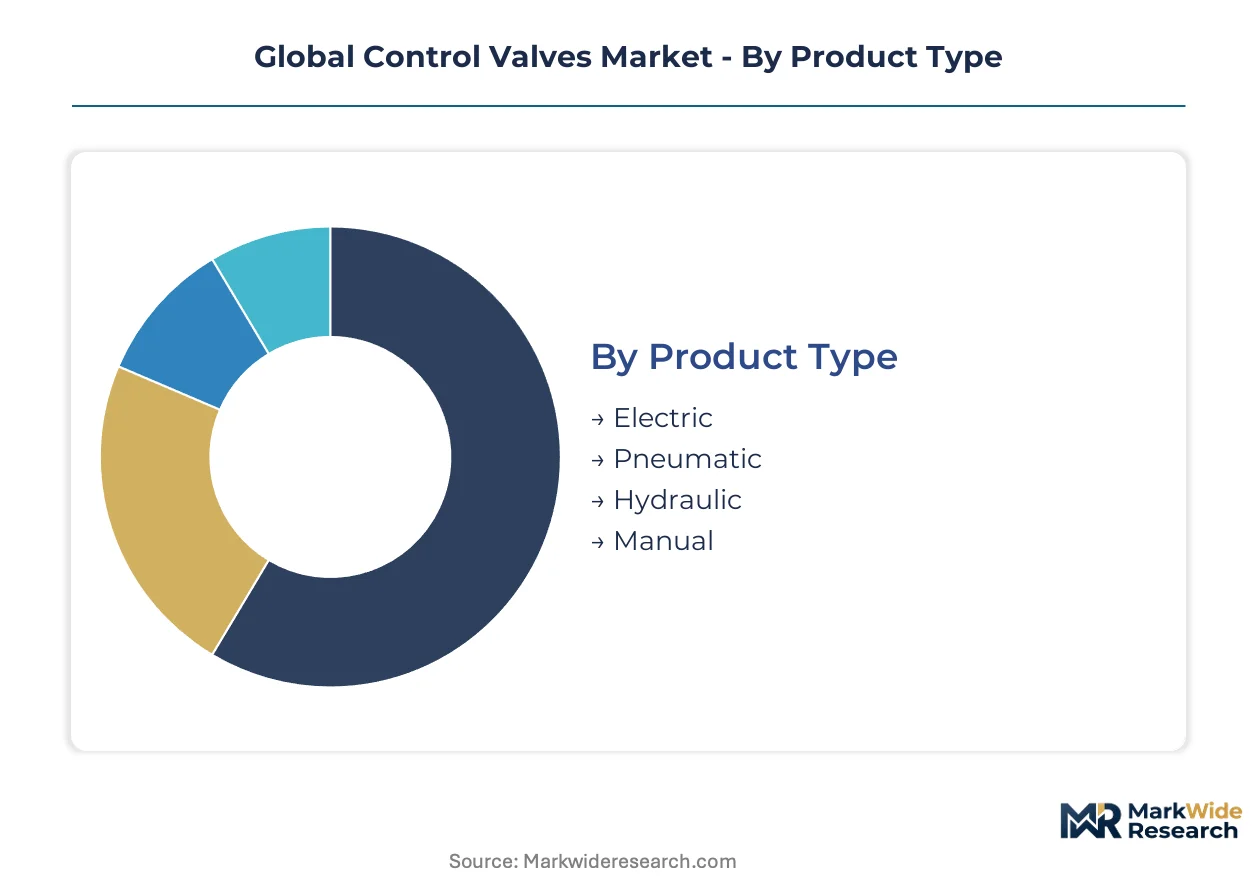
Control valve procurement patterns diverge sharply across actuation technology, material specification, and end-use severity. Understanding these fault lines reveals where specification premiums concentrate and where commoditization pressures erode margins.
Product Type:
Pneumatic variants face the most acute substitution pressure as electrification eliminates instrument air infrastructure across greenfield installations.
- Electric:Brushless DC and servo motor actuators deliver precise positioning without compressed air dependency. Gulf Coast petrochemical operators specify these for wellhead automation projects driven by EPA methane monitoring mandates.
- Pneumatic:Diaphragm and piston-actuated designs retain dominance across legacy oil and gas facilities where instrument air systems remain entrenched. Technician scarcity and extended service response times now constrain their expansion trajectory.
- Hydraulic:High-force actuation for subsea and severe-service environments requiring fail-safe positioning under extreme pressure differentials.
- Manual:Handwheel and lever operators persist in isolation valve applications and backup safety positions where automated response is unnecessary.
Pneumatic variants anchor the volume base while electric configurations gain share at the steepest rate.
Application:
Cost tier stratification separates projects demanding severe-service metallurgy from standard commodity specifications.
- Oil & Gas:Upstream wellhead control, pipeline regulation, and refinery process loops require ANSI Class 600-2500 ratings with fire-safe certification. Chinese state-owned refinery expansions concentrate procurement for hydrogenation and cracking units.
- Chemical Processing:Acid service and chloride-rich environments mandate titanium and super-austenitic stainless steel trims. German industrial clusters drive specification for digital positioners with predictive diagnostic capabilities.
- Power Generation:Steam conditioning and feedwater regulation across combined-cycle and nuclear facilities.
- Water Treatment:Municipal and industrial desalination plants specify corrosion-resistant materials for membrane process control.
Oil & Gas commands the premium specification tier while Chemical Processing shows the steepest specification upgrade trajectory.
End User:
Customer type determines whether procurement prioritizes lifecycle cost optimization or upfront capital minimization.
- Energy:Integrated oil companies and utilities negotiate performance-based service contracts tied to uptime guarantees. Predictive maintenance integration shapes vendor selection criteria across subsea and remote installations.
- Manufacturing:Continuous-process chemical and food plants balance specification compliance against total cost of ownership metrics.
- Construction:Project-based procurement with compressed timelines favors standardized specifications and rapid fulfillment.
- Pharmaceuticals:EMA clean steam and WFI standards impose surface finish and material traceability requirements that filter supplier pools.
Energy sector procurement anchors the service contract premium tier while Pharmaceuticals imposes the most stringent certification burden expansion.
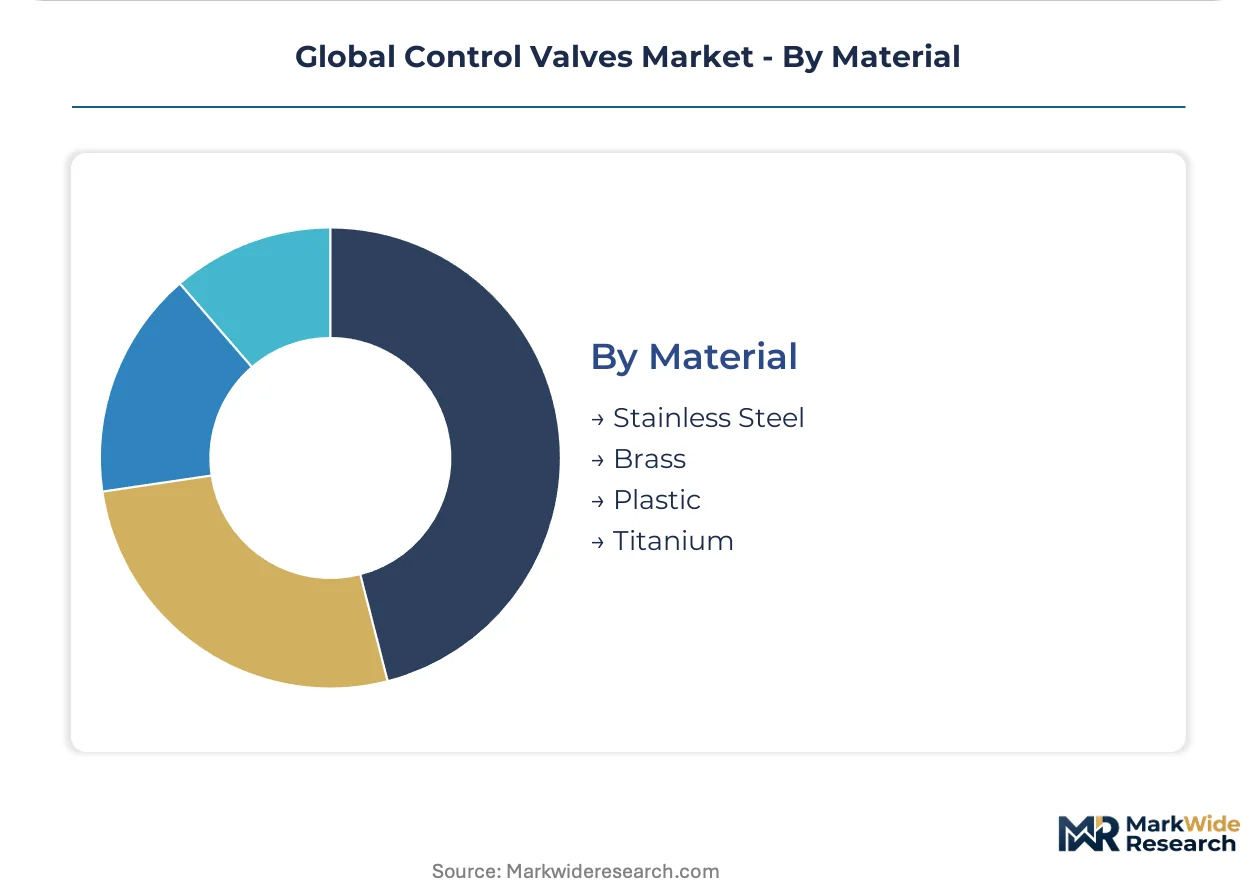
Material:
Supply concentration for specialized alloys creates margin pressure differentiation across specification grades.
- Stainless Steel:Austenitic and duplex grades dominate general service applications across water treatment and standard chemical processing. Nickel price volatility compresses margins for severe-service super-austenitic variants.
- Titanium:Unmatched corrosion resistance in acid chloride environments justifies unit cost premiums. Seawater desalination and pharmaceutical reactor applications concentrate demand in coastal manufacturing clusters.
- Brass:Lead-free formulations for potable water and low-pressure steam applications where cost sensitivity dominates.
- Plastic:PTFE and PVDF linings for ultra-pure water and aggressive chemical environments below elevated temperature thresholds.
Stainless Steel anchors the installed base volume while Titanium expands most quickly in severe-service specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA methane emission thresholds anchor procurement dynamics in the United States, while divergent regulatory pressures across Germany, China, Saudi Arabia, and India reshape material specifications and certification timelines for valve suppliers.
United States
Gulf Coast petrochemical corridors drive upstream automation procurement for wellhead digitalization. EPA enforcement of low-leakage stem seal specifications compels packing upgrades across petroleum infrastructure. Houston and Corpus Christi clusters concentrate demand for ANSI Class 600-2500 rated valves with fire-safe certification.
Germany
Industrial clusters in the Ruhr and Bavaria specify digital valve positioners with predictive diagnostic capabilities. EU F-Gas Regulation phase-down schedules compress refrigerant-adjacent process line specifications. Frankfurt-Rhine-Main pharmaceutical manufacturing demands EMA-compliant surface finish and material traceability standards.
China
State-owned refinery expansions concentrate procurement for hydrogenation and cracking units. NMPA and GB standards impose localized testing protocols that condition market access for imported severe-service designs. Shandong and Jiangsu coastal provinces anchor titanium and super-austenitic stainless steel demand for acid service environments.
Saudi Arabia
Eastern Province hydrocarbon processing drives severe-service valve procurement for high-pressure differentials. The country's national petroleum regulator enforces material certification protocols for subsea installations. Jubail Industrial City clusters demand hydraulic actuation systems for fail-safe positioning in extreme service conditions.
India
Maharashtra and Gujarat chemical processing corridors specify corrosion-resistant materials for chloride-rich environments. BIS standards and PLI scheme incentives shape domestic manufacturing capacity expansion. Mumbai-Pune industrial belt concentrates demand for electric actuation retrofits in continuous-flow operations.
Global Control Valves Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the control valve market. The vendor base consolidates around integrated industrial conglomerates with captive service networks, specialized severe-service metallurgy specialists, and regional fabrication houses serving localized certification requirements. Three archetypes dominate: predictive maintenance integrators, backward-integrated alloy casters, and digital twin platform providers. Competitive moves center on service contract unbundling and predictive analytics platform licensing.
Within the integrated conglomerate tier, Emerson Electric Co. and Flowserve Corporation exemplify archetypes combining hardware manufacturing with embedded field service networks. SLB occupies a position representing digital twin convergence for subsea installations. Christian Bürkert GmbH & Co. KG anchors the specialized fluid control segment among European precision engineering houses. KITZ Corporation and IMI plc sit within the severe-service metallurgy specialist tier, with geographic origins in Japan and the United Kingdom respectively informing their certification capabilities.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Flowserve Corporation |
| IMI plc |
| Curtiss-Wright Corporation |
| Christian Bürkert GmbH & Co. KG |
| Valmet |
| SLB |
| KITZ Corporation |
| Crane Company |
| Others |
Supply Flow & Price Mechanics
Long-term performance-based service contracts lock in supply access for severe-service alloy castings while anchoring price visibility across volatile nickel and cobalt input cycles. Gulf Coast petrochemical operators and German industrial clusters negotiate these arrangements to insulate procurement from spot market swings in super-austenitic grades.
Pricing Analysis
Price spreads between US Gulf Coast and Jiangsu Province suppliers compress during nickel price spikes but widen when EPA methane rules trigger premium certification tiers. Three-tier pricing structure across severe-service, standard-process, and commodity-grade levels dominates procurement, with certification grade and volume scale as primary differentiation drivers. Cost compression in super-austenitic trims intensifies because nickel price volatility feeds directly into trim manufacturing economics. Project-based construction buyers exhibit highest price sensitivity, while integrated energy operators prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites titanium sponge flows from East Asian reduction facilities to European and North American valve foundries. Supply concentration centers on China for super-austenitic castings, Japan for precision titanium components, and Germany for digital positioner electronics. Raw material dependencies span nickel cathodes, cobalt metal, and rare-earth magnets for electric actuation systems. Single-source vulnerability in specialized alloy melting capacity threatens severe-service trim availability. Distribution runs through OEM-authorized service networks that embed field technicians directly at refinery sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Control valve incumbents face substitution pressure from integrated process control platforms that bundle valve hardware with distributed control system architectures. Defense requires embedding deeper into plant automation stacks before platform vendors capture specification authority.
For Market Incumbents: Compound predictive maintenance capabilities into subscription service offerings that extend beyond hardware replacement cycles. Backward integration into captive alloy casting secures margin control against nickel price volatility. Digital twin platform vendors threaten specification authority by offering valve-agnostic optimization layers. For New Entrants and Emerging Players: Differentiate on NMPA certification velocity to capture share in Chinese state-owned refinery expansions where localized testing protocols filter imported competitors. White-space concentrates in electric actuation retrofits for legacy pneumatic installations across Indian chemical processing corridors. Go-to-market through EPC contractor partnerships accelerates project-based procurement access. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors service-network scale over pure manufacturing capacity. Long-term viability hinges on predictive analytics platform ownership rather than commodity valve production. Acquisition targets with embedded field service networks in Gulf Coast or German industrial clusters offer defensive positioning. Watch for EPA cybersecurity framework drafts that could mandate digital positioner compliance as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Casting | Captive supply of super-austenitic trims insulates margins from nickel price volatility. |
| Predictive Maintenance Platform Launch | Emerson-style service contracts embed OEMs at refinery sites through uptime guarantees. |
| NMPA Certification Investment | Localized testing capabilities unlock Chinese state-owned refinery procurement channels. |
| Electric Actuation Retrofit Program | Eliminates instrument air infrastructure for Gulf Coast methane monitoring compliance. |
| Digital Twin Integration Partnership | SLB-modeled subsea capabilities extend valve positioners into predictive analytics stacks. |
Methodological Framework
The analysis maps pneumatic-to-electric actuation substitution patterns, severe-service material grade specifications, and predictive maintenance contract structures, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary interviews with valve technicians and refinery reliability engineers combined with secondary validation from customs trade data, SEC 10-K filings, and API equipment certification records. Bottom-up unit economics triangulate against top-down energy sector capex forecasts.
Consistency checks against EIA refinery utilization data and German chemical industry association production indices validated volume assumptions across the projection horizon. Segmentation dimensions span actuation technology, material specification tier, end-use severity, and regional regulatory cluster. CAGRs derive from installed-base replacement cycles and greenfield automation intensity curves. Forecast inputs incorporate EPA methane rule enforcement timelines and EU F-Gas Regulation phase-down schedules.
The analysis sits within stated boundaries; outcomes outside current EPA and EU regulatory trajectories would require recalibration. Forecasts reflect assumptions about technician supply recovery and nickel price mean-reversion. Practitioners should keep alternative scenarios live as Chinese NMPA testing protocol timelines and cybersecurity framework drafts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Industrial Thermostatic Control Valves Market
Valves
Global Level Gauge Market
Valves
Water Draw Off Valves Market
Valves
Global Valves in Chemical Market
Valves
Europe Industrial Valves Market
Valves
Manual Control Valve Market
Valves
India Industrial Valves Market
Valves
Portable Valve Actuator Market
Valves
Gas Equipment Market
Valves
North America Irrigation Valves Market
Valves
Lined Valves Market
Valves
Construction Valve Seat Insert Market
Valves
Subsea Valves Market
Valves
Fluid Power Cylinder Market
Valves
Sandblast Valves Market
Valves
Air Vent Heads Market