
 Sliding Sleeves Market | 2026-2036
Sliding Sleeves Market Size, Share, and Industry Trends Forecast 2026-2036
Sliding Sleeves Market Outlook
Asset-light leasing models for high-pressure completion tools is tilting competitive dynamics toward service companies with balance-sheet flexibility. Halliburton leverages its integrated well construction platform to bundle sliding sleeve deployments with directional drilling services. Schlumberger anchors its position through proprietary downhole actuation technology that reduces rig time. National Oilwell Varco competes by manufacturing sleeves in-house alongside wellbore intervention systems, controlling cost structures across the supply chain.
A sliding sleeve is a downhole completion device, typically machined from corrosion-resistant alloys with pressure ratings exceeding 10,000 psi, that opens or closes ports to control fluid communication between the wellbore and reservoir. Its primary purpose is enabling staged fracturing and selective zone isolation without intervention. Hydraulic sliding sleeves dominate installed base due to reliability in high-pressure shale environments, while dual-activated sliding sleeves represent the fastest-growing category as operators seek redundancy in extended-reach laterals. Well completion applications capture the deepest margin pools because sleeve performance directly determines stage count and hydrocarbon recovery efficiency.
The EPA regulates hydraulic fracturing chemical disclosure under state-level programs, while the Texas Railroad Commission enforces well integrity standards that mandate pressure testing of all downhole tools. API 19OH and ISO 13628-7 set material qualification and functional testing benchmarks that shape procurement specifications for operators. Stakeholders must monitor how methane emissions rules from the EPA and state regulators affect completion design choices, as tighter venting standards could accelerate demand for sleeves that enable more precise zone targeting.
Market Dynamics
The sliding sleeves market is experiencing structural pressure from API 19OH standards tightening material qualification requirements, forcing operators to retool procurement specifications and manufacturers to recertify corrosion-resistant alloy portfolios.
Growth Catalysts
- Multi-stage completion proliferation:Unconventional shale operators in the Permian Basin of Texas and New Mexico are expanding lateral lengths beyond 15,000 feet, requiring more sleeve stages per wellbore.
- EPA methane venting rules:Tighter emissions standards are accelerating demand for sleeves that enable precise zone targeting and reduce non-productive flaring during completions.
- Dual-activation technology maturation:Hydraulic-mechanical hybrid actuation systems are penetrating extended-reach laterals where single-point failure risks previously limited stage counts.
Market Restraints
- Corrosion-resistant alloy supply concentration:Premium nickel-based alloy feedstock for 10,000+ psi sleeves concentrates among a limited supplier base in Western Europe, exposing lead times to geopolitical friction.
- ISO 13628-7 testing burden:Functional qualification protocols for high-pressure cycling add six to nine months to product commercialization timelines.
- Coiled tubing intervention substitutes:Some operators in mature basins are reverting to plug-and-perf methods where sleeve redundancy does not justify capital deployment.
Strategic Opportunities
- Argentina Vaca Muerta underpenetration:The Neuquén Basin holds substantial untapped unconventional reserves where multi-stage completion infrastructure remains underdeveloped relative to North American benchmarks.
- Digital twin integration:Convergence of downhole sensor telemetry with sleeve actuation systems enables real-time pressure monitoring and predictive maintenance.
- Texas Railroad Commission well integrity mandates:Stricter pressure testing requirements are creating procurement preference for sleeves with embedded verification ports.
Industry Challenges
- API 19OH metallurgical expertise gap:Manufacturers face shortages of engineers qualified to interpret updated corrosion testing protocols for sour gas environments.
- Legacy wellbore interoperability:Operators struggle to integrate new sleeve designs with existing completion strings in refracturing campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sliding Sleeves Market |
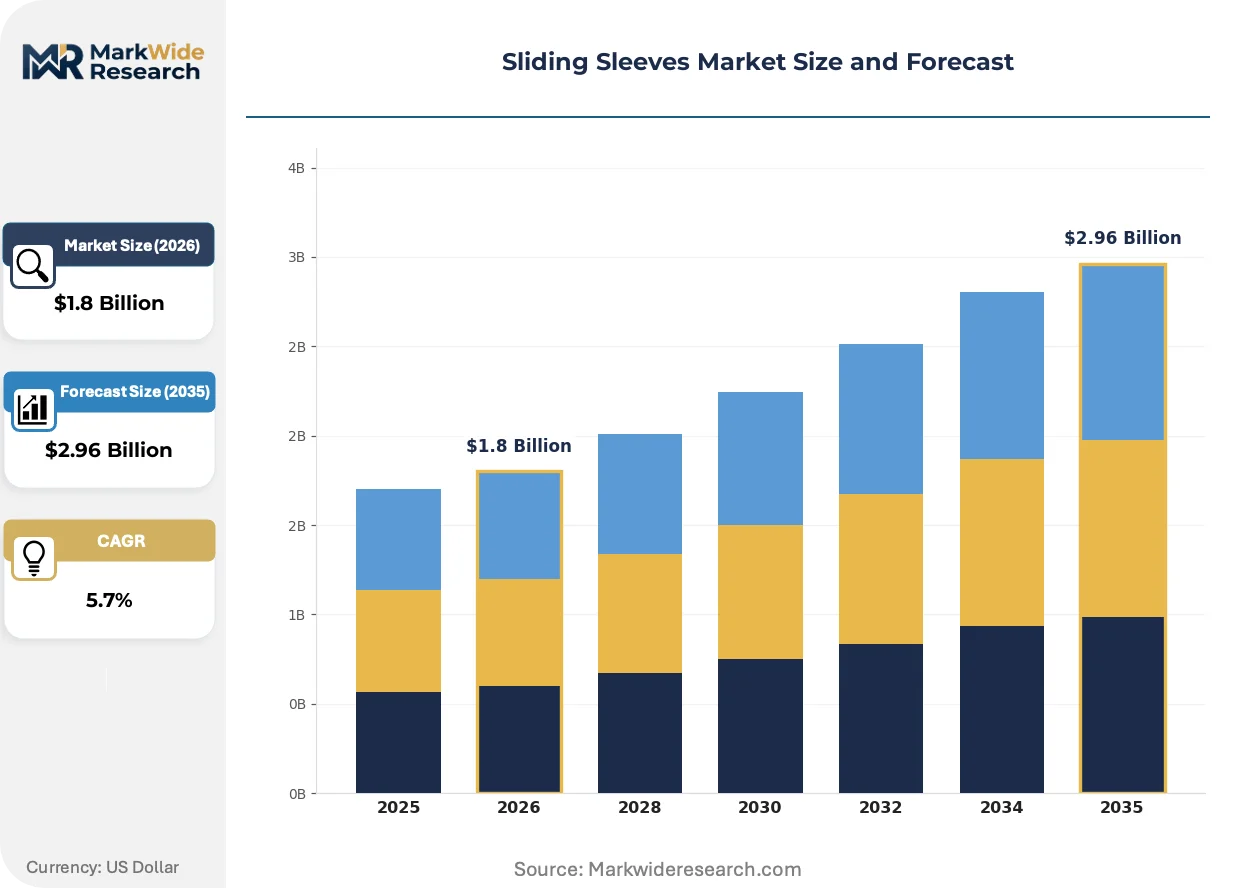
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Sliding Sleeves, Mechanical Sliding Sleeves, Dual-Activated Sliding Sleeves, Single-Activated Sliding Sleeves Application: Well Completion, Oil Recovery, Gas Production, Water Injection End User: Oil & Gas Operators, Service Companies, Drilling Contractors, Energy Producers Technology: Vapour Recovery, Downhole Tools, Multi-Phase Flow, Reservoir Management |
| Companies Covered | Halliburton, NCS Multistage, Schlumberger, Dynamic Oilfield Technology, Packers Plus Energy Services, National Oilwell Varco, Baker Hughes Company, Magnum Oil Tools International, Weatherford, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sliding Sleeves Market Strategic Shifts
Downhole completion architecture is migrating toward redundancy-centric designs as operators push lateral lengths into geomechanically challenging formations. Three intersecting developments are reshaping sleeve specification and deployment patterns.
Electromechanical sliding sleeve actuation is migrating from niche deepwater applications into onshore unconventional basins. These systems eliminate hydraulic control lines, reducing installation complexity in extended-reach laterals. Operators in the Permian Basin are piloting battery-powered sleeves that enable stage-by-stage wireless communication, compressing rig time per stage by eliminating surface pumping for actuation.
The EPA's methane emissions reduction framework is tightening completion design standards across US shale plays. New source performance standards require operators to minimize venting during flowback operations. This regulatory pressure is accelerating sleeve specification for pinpoint zone isolation, allowing operators to shut in non-producing intervals rather than venting entire wellbore volumes.
Leasing models for high-pressure completion tools are displacing outright purchase arrangements among mid-size exploration and production companies. Service providers with balance-sheet capacity are capturing recurring revenue streams through tool-as-a-service offerings. This shift is most visible in the Delaware Basin sub-region of the Permian, where capital discipline has compressed upfront completion budgets.
Sliding Sleeves Market Segmentation
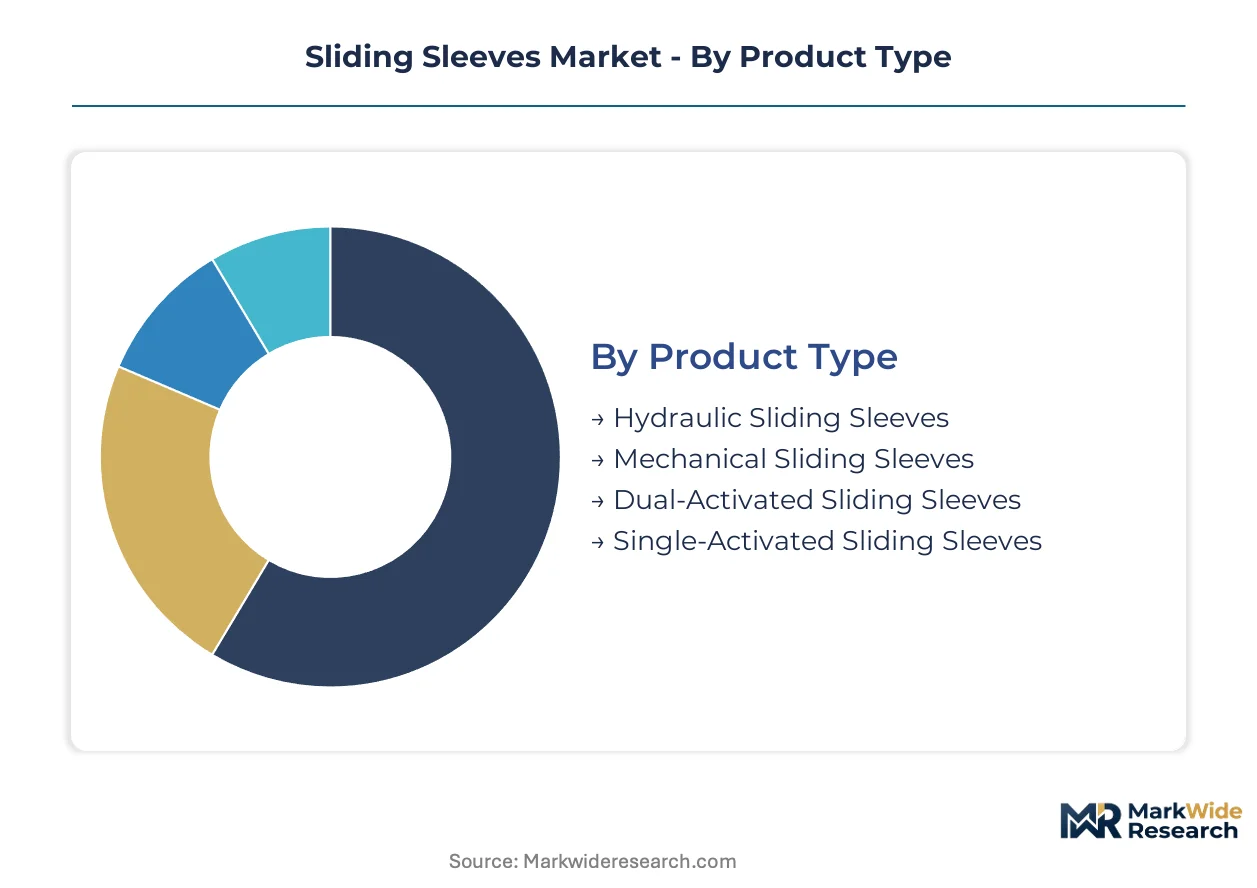
Sliding sleeve specification varies sharply across pressure ratings, actuation mechanisms, and reservoir conditions. Procurement patterns diverge between shale operators prioritizing stage density and offshore developers demanding fail-safe redundancy. Understanding these segment boundaries clarifies where margin pools concentrate and which technical specifications command pricing premiums.
Product Type:
Actuation mechanism determines installation complexity, pressure tolerance, and failure-mode redundancy in downhole deployments.
- Hydraulic Sliding Sleeves:Pressure-fluid actuation through dedicated control lines delivers proven reliability in 10,000+ psi shale environments. Permian Basin operators specify these for standard lateral programs where single-point actuation risk remains manageable within 12,000-foot wellbores.
- Dual-Activated Sliding Sleeves:Hybrid hydraulic-mechanical systems provide redundant actuation pathways critical for extended-reach laterals beyond 15,000 feet. The Neuquén Basin and other geomechanically challenging formations are driving specification shifts toward this architecture as stage counts per wellbore climb.
- Mechanical Sliding Sleeves:Ball-drop or collet-based actuation eliminates surface pumping requirements. These sleeves suit remote locations where hydraulic infrastructure proves logistically prohibitive.
- Single-Activated Sliding Sleeves:Simplified one-way actuation delivers cost efficiency in mature basin recompletions. Operators in the Delaware Basin deploy these for refracturing campaigns where capital discipline compresses tool budgets.
Hydraulic systems command the established base. The steepest expansion runs through dual-activated architectures.
Application:
Functional deployment context shapes material specifications, pressure cycling requirements, and aftermarket service intensity.
- Well Completion:Multi-stage fracturing applications demand corrosion-resistant alloys rated for repeated pressure cycling between 8,000 and 15,000 psi. Sleeve performance here directly determines stage count achievable per lateral, making this the deepest margin pool in the value chain.
- Oil Recovery:Artificial lift integration and selective zone production require sleeves with embedded sensor ports for real-time monitoring. North Sea operators specify these for brownfield redevelopment where reservoir pressure has depleted.
- Gas Production:Sour gas environments impose hydrogen sulfide compatibility requirements under API 19OH protocols. Nickel-based alloy selections dominate procurement specifications for these applications.
- Water Injection:Disposal and pressure maintenance operations utilize lower-specification sleeves where corrosion tolerance exceeds pressure cycling demands. Permian operators deploy these extensively for produced water reinjection.
Well completion captures dominant revenue share. Oil recovery applications are expanding most quickly as brownfield redevelopment accelerates.
End User:
Customer scale and technical capability determine procurement modality, from capital purchase to tool-as-a-service leasing.
- Oil & Gas Operators:Integrated majors and large independents wield specification authority through direct procurement of completion strings. These buyers prioritize API 19OH certification and embedded verification ports for regulatory compliance.
- Service Companies:Halliburton, Schlumberger, and similar providers bundle sleeve deployment with directional drilling and fracturing services. Balance-sheet capacity enables asset-light leasing models that displace outright purchase among mid-size explorers.
- Drilling Contractors:Rig operators specify sleeves compatible with automated pipe-handling systems and rapid trip speeds. Time-per-stage economics drive their procurement criteria.
- Energy Producers:Diversified utilities and renewable-hybrid operators entering shale plays lack deep completion expertise, creating demand for fully integrated sleeve-plus-service packages.
Service companies intermediate the largest volume flows. Direct operator procurement is gaining share fastest as technical capabilities internalize.
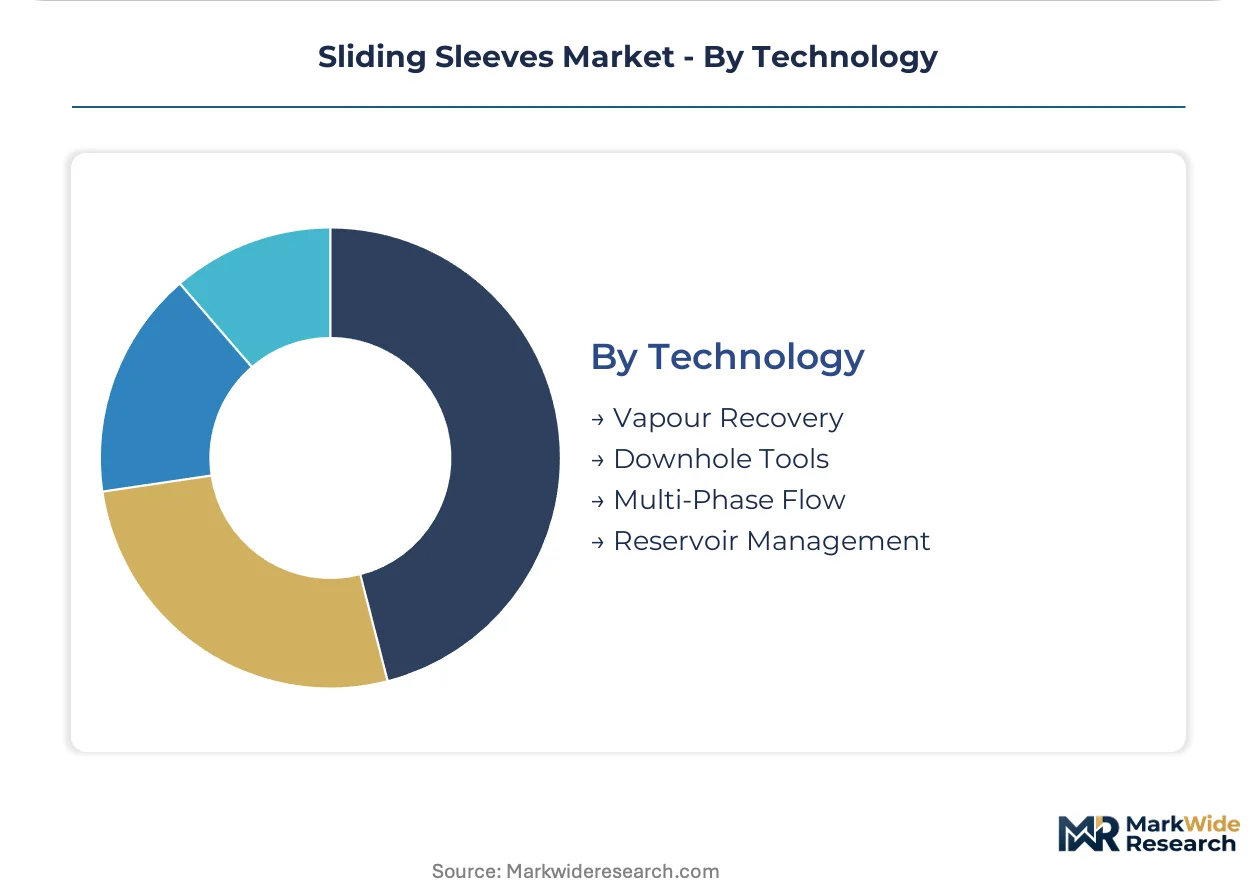
Technology:
Adjacent system integration determines data capture, actuation precision, and predictive maintenance potential.
- Downhole Tools:Sleeves engineered for integration with packers, anchors, and isolation valves form the core completion architecture. These systems dominate unconventional shale specifications where stage isolation integrity determines recovery efficiency.
- Reservoir Management:Real-time pressure and temperature telemetry through sleeve-embedded sensors enables dynamic production optimization. Vaca Muerta operators are piloting these systems to manage heterogeneous reservoir properties.
- Vapour Recovery:Methane capture integration aligns with EPA emissions standards by minimizing venting during flowback operations. Sleeve specifications increasingly incorporate sealing verification for regulatory compliance.
- Multi-Phase Flow:Handles simultaneous oil, gas, and water production without erosion degradation. These sleeves suit high-water-cut mature fields where production chemistry has shifted.
Downhole tool integration anchors current deployment patterns. Reservoir management connectivity is climbing the fastest as digital oilfield investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal methane regulations in the United States are accelerating specification shifts toward precision-actuated completion tools. Argentina's Vaca Muerta unconventional development is attracting capital deployment for multi-stage infrastructure. China's shale gas push under the national energy security mandate is expanding domestic manufacturing capacity for high-pressure downhole equipment.
United States
Permian Basin operators in Texas and New Mexico are extending lateral lengths beyond 15,000 feet, requiring denser sleeve stage spacing per wellbore. The EPA's methane emissions reduction framework mandates minimized venting during flowback, favoring sleeves with embedded sealing verification. Midland-Odessa service clusters are deploying dual-activated systems for geomechanically challenging Delaware Basin formations.
Argentina
Neuquén Basin unconventional reserves are driving import substitution policies for completion hardware to reduce North American supply dependence. The national hydrocarbons regulator enforces well integrity standards adapted from API protocols for sour gas environments. YPF-operated Vaca Muerta blocks are piloting wireless electromechanical sleeves to compress rig time in remote locations lacking hydraulic infrastructure.
China
Sichuan Basin shale gas targets under the 14th Five-Year Plan are expanding domestic demand for 10,000+ psi-rated completion tools. The Ministry of Ecology and Environment is tightening methane venting standards for onshore production operations. Zigong manufacturing clusters are scaling corrosion-resistant alloy foundry capacity to supply national oil company procurement programs.
Canada
Montney and Duvernay formation operators are specifying sleeves compatible with sub-zero operating temperatures and high-pressure cycling. Alberta's energy regulator mandates pressure testing documentation for all downhole tools under well license requirements. Calgary-based service providers are bundling sleeve deployment with automated fracturing fleets to reduce per-stage labor intensity.
Saudi Arabia
Unconventional gas development in the Jafurah Basin is creating demand for sour-gas-compatible completion systems under Aramco procurement standards. The national hydrocarbons regulator applies API 19OH material qualification protocols for high-H2S environments. Dhahran-based engineering centers are qualifying domestic manufacturing partners for sleeve components to localize supply chains.
Sliding Sleeves Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure that concentrates specification authority among integrated service providers. The vendor base organizes into three tiers: full-line well construction platforms, completion-tool specialists, and component fabricators. Strategic archetypes include balance-sheet-enabled lessors capturing recurring revenue, technology licensors monetizing proprietary actuation systems, and vertically integrated manufacturers controlling alloy supply chains. Dominant competitive moves encompass asset-light leasing model expansion and in-house corrosion-resistant alloy production.
Among Houston-based energy service conglomerates, Halliburton, Schlumberger, and Baker Hughes Company exemplify the full-line platform archetype that bundles sleeve deployment with directional drilling and hydraulic fracturing operations. These entities leverage integrated well construction workflows to compress stage timing and capture specification authority through operator relationships. Completion-tool specialists including NCS Multistage and Packers Plus Energy Services occupy positions focused on multi-stage system architecture without the capital intensity of full drilling service portfolios. National Oilwell Varco represents the manufacturing-integrated archetype, controlling cost structures through captive production of sleeves alongside wellbore intervention systems.
| Leading Market Players |
|---|
| Halliburton |
| NCS Multistage |
| Schlumberger |
| Dynamic Oilfield Technology |
| Packers Plus Energy Services |
| National Oilwell Varco |
| Baker Hughes Company |
| Magnum Oil Tools International |
| Weatherford |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Western European nickel-based alloy suppliers determines both pricing tier spreads and supply chain shape for high-pressure sliding sleeves. Procurement officers face extended lead time exposure that compresses margin pools for manufacturers lacking captive metallurgical capacity or pre-negotiated feedstock positions.
Pricing Analysis
Certification level under API 19OH creates the primary spread between premium and standard sleeve tiers. Three-tier pricing structure across premium, standard, and economy levels reflects material qualification burden, with sour-gas-rated nickel alloys commanding substantial premiums over carbon steel alternatives. Cost compression in the economy tier is intensifying because mid-size operators are migrating toward tool-as-a-service leasing models. Service companies exhibit the least price sensitivity due to balance-sheet capacity for asset-light deployment, while independent drilling contractors remain most exposed to per-unit procurement volatility.
Supply Chain Analysis
Extended payment terms from integrated service providers are restructuring supplier-financing relationships across the tiered vendor base. Geographic supply concentration centers on Germany, France, and Belgium for corrosion-resistant alloy feedstock, with secondary machining and assembly clustering in Houston and Calgary. Raw material sourcing draws from nickel laterite deposits in Indonesia, refined cobalt from the Democratic Republic of Congo, and specialty chromium alloys from South Africa. Single-source vulnerability in premium nickel-based alloy qualification creates structural risk for manufacturers without dual-certified supplier relationships. Distribution runs through service company warehouses proximate to Permian Basin and Appalachian Basin drilling clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plug-and-perf completion methods pose a credible substitution threat that sleeve incumbents must navigate through performance differentiation and total-cost economics.
For Market Incumbents: Entrench specification authority by embedding verification ports for Texas Railroad Commission pressure testing mandates and securing backward integration into corrosion-resistant alloy foundry capacity. Captive metallurgical production insulates margin structures from Western European feedstock concentration. Dual-activated sleeve architectures defend against plug-and-perf substitution in extended-reach laterals beyond 15,000 feet.
For New Entrants and Emerging Players: Pursue white-space opportunity in Argentina's Neuquén Basin where multi-stage completion infrastructure remains underdeveloped relative to North American benchmarks. Wireless electromechanical actuation systems offer a penetrable technology entry point for remote locations lacking hydraulic infrastructure. Go-to-market positioning should emphasize integrated sleeve-plus-telemetry packages for operators without deep completion expertise.
For Investors and Strategic Acquirers: EPA methane venting rule implementation reshapes the acquisition landscape toward sleeve manufacturers with embedded sealing verification and zone-targeting precision. Long-term viability favors asset-light lessors with recurring revenue streams over capital-intensive manufacturers exposed to cyclical tool replacement demand. The signal to watch is regulatory adoption of real-time emissions monitoring mandates that would accelerate digital twin integration premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| API 19OH Certification Investment | Qualification under tightened metallurgical protocols secures procurement preference from Permian Basin operators. |
| Dual-Activated Sleeve Development | Redundant actuation architectures penetrate extended-reach laterals where single-point failure risks previously limited adoption. |
| Tool-as-a-Service Leasing Expansion | Asset-light models capture recurring revenue from mid-size explorers compressing upfront completion budgets. |
| Wireless Electromechanical Actuation | Battery-powered sleeves eliminate hydraulic infrastructure requirements in remote Vaca Muerta development blocks. |
| Corrosion-Resistant Alloy Backward Integration | Captive foundry capacity insulates margin structures from Western European feedstock supply concentration. |
Study Parameters
A standing panel of completion engineering directors, procurement managers at independent operators, regulatory affairs specialists, and aftermarket service heads provided ongoing calibration throughout the study period. Primary interview insights combined with secondary validation from API certification databases, Texas Railroad Commission well integrity filings, EPA emissions compliance records, and SEC 10-K disclosures from publicly traded service companies. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing around regulatory adoption timelines and shale drilling intensity variations shaped the analytical framework. Segmentation modeling incorporated actuation mechanism, pressure rating tier, application context, and regional regulatory cluster dimensions throughout the projection horizon. CAGRs derived from historical deployment trajectories adjusted for stage-count density trends in unconventional basins and dual-activation technology penetration curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-backed Chinese manufacturers or accelerated electromechanical substitution would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Insulation Flanges Market
Valves
North America Butterfly Valve Market
Valves
Middle East and Africa Machined Seals Market
Valves
Battery Safety Valve Market
Valves
Emergency Shutdown Valves Market
Valves
Off-Highway Hydraulic Valve Actuator Systems Market
Valves
Fluid Handling Systems Market
Valves
Christmas Tree Valves Market
Valves
Middle East and Africa Electro Hydraulic Servo Valve Market
Valves
Wind Energy Fasteners Market
Valves
Pipeline Integrity Management (PIM) Market
Valves
Global Pressure Relief Valves Market
Valves
Leak Detection Market
Valves
Global Plug Valve Market
Valves
Deluge Valve Market
Valves
Europe Butterfly Valve Market