
 HVAC Valves Market | 2026-2036
HVAC Valves Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC Valves Market Intelligence
The CE marking requirement for pressure equipment sold in the European Union is collapsing the distinction between regional and global component suppliers, forcing manufacturers to design for compliance across multiple jurisdictions. Belimo Holding AG specializes in actuator-driven valve solutions for building automation systems. Siemens AG leverages its broad industrial automation portfolio to offer integrated HVAC control solutions, while Johnson Controls International plc competes through its extensive distribution network and building management platforms.
HVAC valves are mechanical devices that regulate the flow of fluids like water or refrigerant within heating and cooling systems. They are specified by flow coefficient (Cv) and pressure ratings to manage energy and maintain comfort. Ball valves and butterfly valves dominate the product landscape due to their operational reliability and cost-effectiveness. The commercial buildings sector represents the largest end-user base, where demand for electronically actuated valves is driven by energy efficiency retrofits and smart building integrations.
Regulatory frameworks are pivotal in shaping product development and market access. The EU's F-Gas Regulation and the US EPA's AIM Act mandate the phase-down of high-GWP refrigerants, compelling valve manufacturers to ensure material compatibility with newer, low-GWP alternatives. Building energy codes, such as ASHRAE Standard 90.1, also influence the specification of high-performance, low-leakage valves. Component suppliers must now decide whether to specialize in valves for natural refrigerants or develop broader portfolios compatible with a fragmented landscape of synthetic alternatives.
Market Dynamics
The transition toward low-GWP refrigerants, mandated by frameworks like the EU's F-Gas Regulation and the US AIM Act, is the central force shaping the HVAC valve market. This shift compels material science innovation and product requalification across the entire supply chain.
Growth Catalysts
- Data Center Expansion:The proliferation of high-density data centers requires precise thermal management systems, driving demand for electronically actuated valves that offer superior flow control and integration with building automation systems.
- Building Energy Codes:Stricter energy efficiency standards, such as ASHRAE Standard 90.1, compel the use of high-performance, low-leakage valves in new construction and retrofits to minimize energy waste in commercial buildings.
- Infrastructure Investment:Massive public and commercial infrastructure development, particularly in China, creates sustained demand for a wide range of HVAC components, including valves for new airports, rail stations, and commercial complexes.
Market Restraints
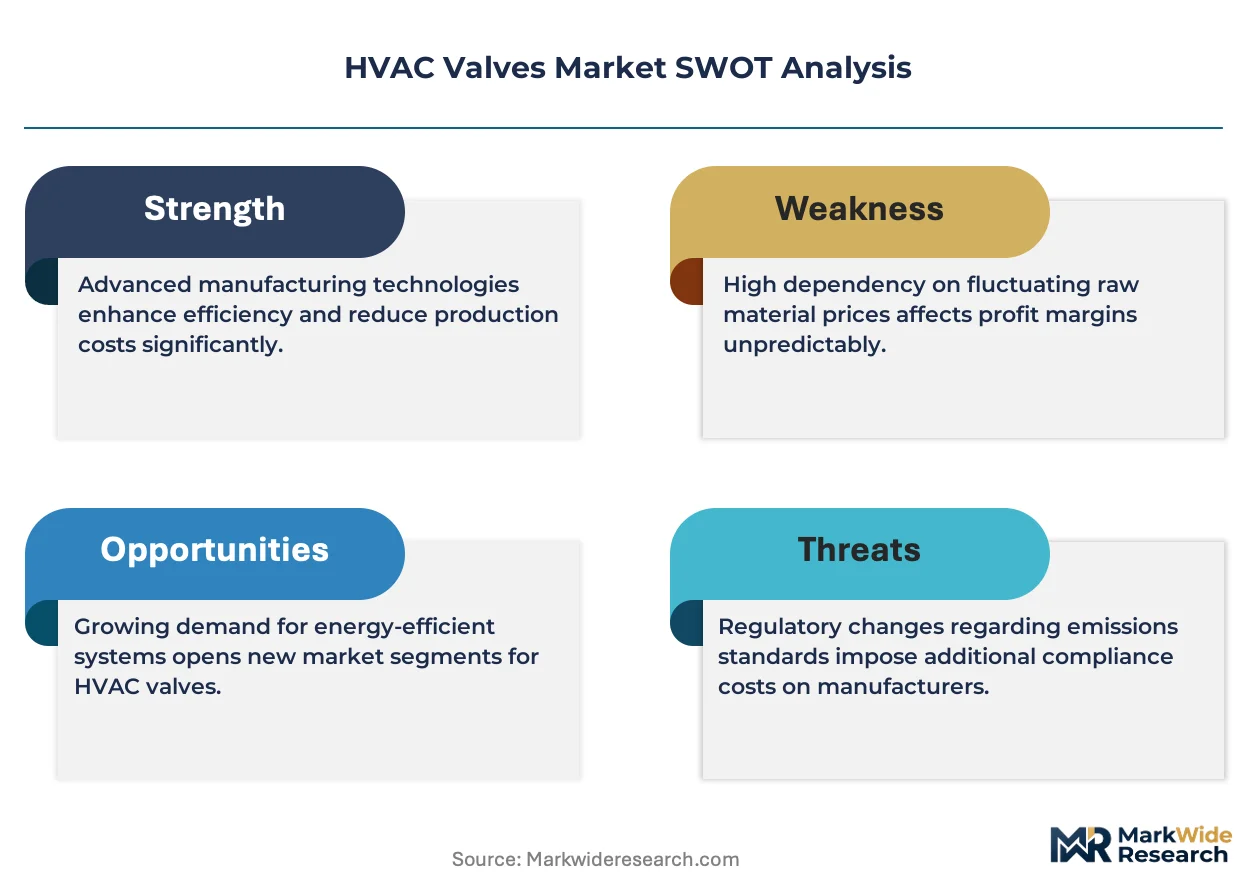
- Input Cost Volatility:The price of raw materials like brass, copper, and stainless steel, which are essential for valve bodies and components, is subject to significant fluctuation on commodity markets, creating margin pressure for manufacturers.
- Material Compatibility Hurdles:Newer low-GWP refrigerants, including A2L variants and natural refrigerants like CO2, can be more corrosive or operate at higher pressures, posing significant material science and engineering challenges for valve design.
- Regulatory Fragmentation:Divergent timelines and technical requirements between major regulatory regimes, such as the EU F-Gas Regulation and the US EPA's AIM Act, complicate product development and create inventory management challenges for global suppliers.
Strategic Opportunities
- Smart Valve Development:Integrating IoT sensors and onboard diagnostics directly into valve actuators offers a significant opportunity to create value-added products that provide predictive maintenance data and enhance system-level energy efficiency.
- Natural Refrigerant Systems:Specializing in high-pressure valves designed for natural refrigerant systems, such as transcritical CO2, allows manufacturers to capture a high-margin niche market driven by sustainability-focused end-users in food retail and industrial refrigeration.
- Energy Retrofit Programs:Government-backed initiatives promoting energy efficiency in existing buildings, like the EU's Renovation Wave, create a dedicated market for advanced, electronically controlled valves to replace outdated manual or pneumatic components.
Industry Challenges
- Technician Skill Gaps:A shortage of field technicians proficient in both mechanical HVAC systems and the IT networking protocols used in modern building automation creates a bottleneck for the installation and maintenance of advanced smart valve systems.
- Certification Delays:The extensive testing and certification process required to validate valve materials and designs for use with each new flammable or high-pressure refrigerant creates a significant time-to-market delay for component suppliers.
- Legacy System Integration:Ensuring seamless interoperability and communication between new, intelligent valves and the diverse array of older, proprietary Building Management Systems (BMS) installed in existing buildings remains a persistent operational challenge.
Report Scope
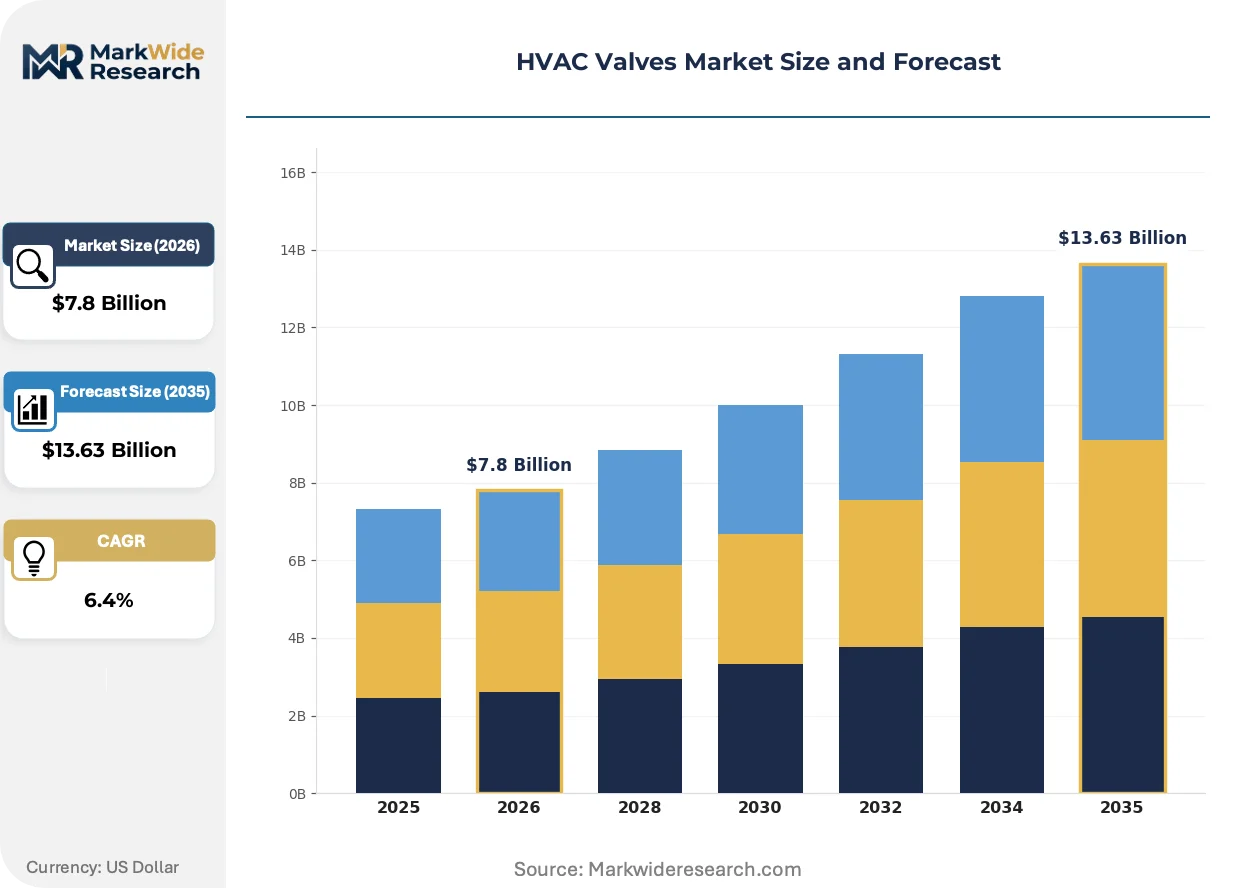
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC Valves Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valves, Butterfly Valves, Globe Valves, Gate Valves, Check Valves, Diaphragm Valves Material: Brass, Stainless Steel, Cast Iron, PVC, Bronze, Carbon Steel End User Industry: Commercial Buildings, Residential Complexes, Data Centers, Educational Facilities, Hospitality Venues, Government Establishments Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesalers, System Integrators, Specialized Dealers |
| Companies Covered | Siemens AG, Emerson Electric Co., Honeywell International Inc., Flowserve Corporation, Schneider Electric SE, Danfoss A/S, Belimo Holding AG, Pentair plc, Johnson Controls International plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC Valves Market Strategic Shifts & Innovations
Product development is pivoting from purely mechanical flow control to creating intelligent, networked endpoints within a building's digital ecosystem. This evolution reflects a broader shift where HVAC components are becoming active participants in energy management and building operational intelligence.
Pressure-independent control valves (PICVs) integrate balancing, control, and differential pressure regulation into a single component. These devices are seeing rapid adoption in new commercial projects like hospitals and laboratories that demand precise environmental control. The adoption of PICVs is bifurcating the market between high-performance, integrated solutions for smart buildings and commodity valves for less demanding applications.
The US EPA's AIM Act mandates a steep phase-down of high-GWP hydrofluorocarbons, directly impacting system design. This regulatory action compels equipment manufacturers to adopt alternatives like mildly flammable A2L refrigerants or high-pressure natural refrigerants. Valve suppliers are the most affected segment, facing urgent requirements to re-engineer products with compatible materials and higher pressure ratings to ensure system safety and reliability.
A notable behavioral shift is altering how components are specified for large-scale commercial projects. Instead of selecting valves based on brand or upfront cost, engineers and building owners are increasingly using performance-based specifications that define required energy savings or temperature stability outcomes. This trend is most visible in North America and Europe, where ESG metrics influence procurement decisions for commercial real estate portfolios.
HVAC Valves Market Segmentation
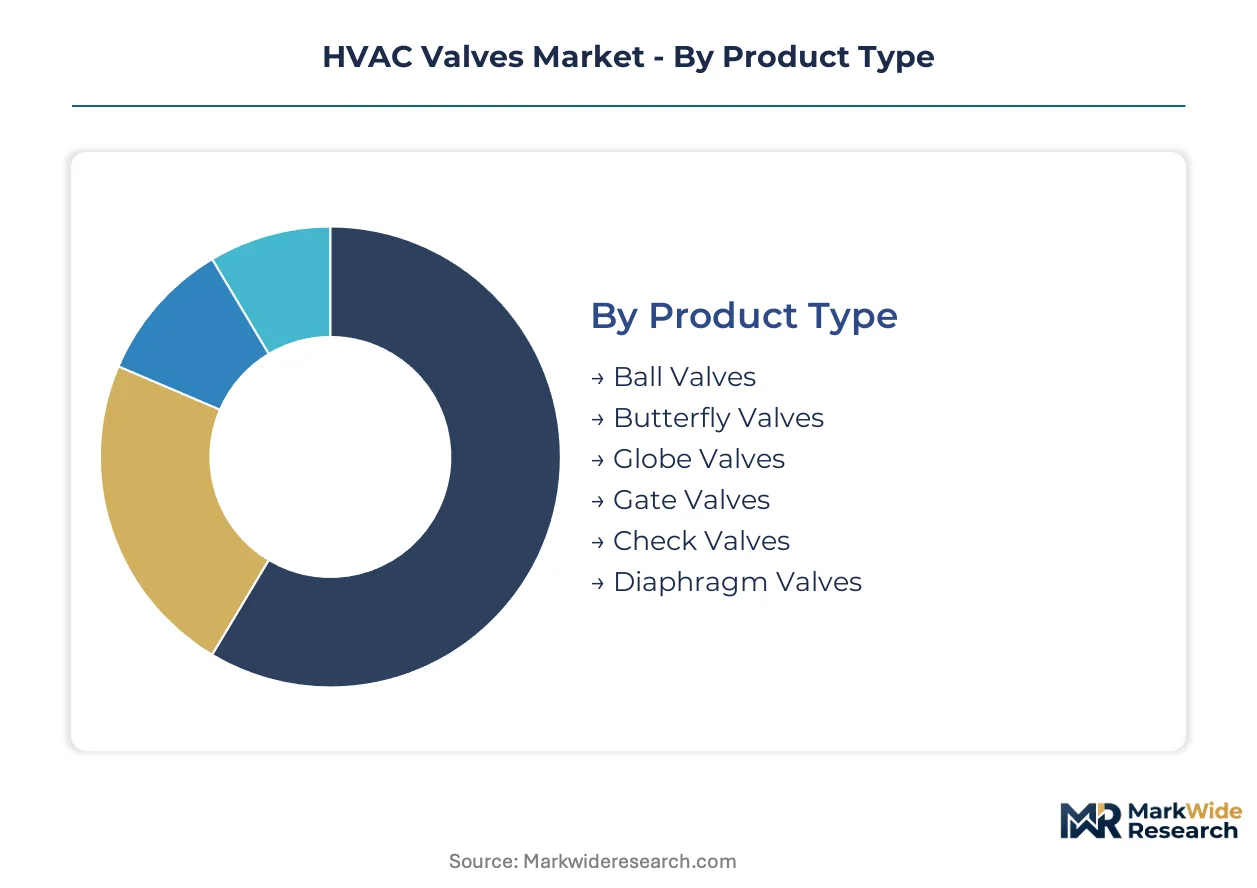
The HVAC valves market is disaggregated across several dimensions, reflecting diverse technical requirements and operational contexts within heating, ventilation, and air conditioning systems. Understanding these distinct segments reveals varying technological demands and commercial pathways for market participants. Each segment responds to unique drivers, from material science advancements to evolving end-user expectations.
Product Type:
Regional construction practices and regulatory preferences often dictate the geographic prevalence of specific valve types, influencing their global adoption.
- Ball Valves:Rotary ball devices for flow control, widely adopted in North American commercial HVAC systems due to tight shut-off and reliable operation.
- Butterfly Valves:Quarter-turn valves using a disc for flow control. Their compact design and cost-effectiveness are prevalent in European district cooling networks.
- Globe Valves:Linear motion valves regulating flow with a movable disk.
- Gate Valves:Provide full flow or complete shut-off, common in industrial and large commercial water lines.
- Check Valves:Permit flow in one direction, preventing backflow in critical HVAC applications.
- Diaphragm Valves:Utilize a flexible diaphragm for flow control, specified for corrosive fluid services.
Ball Valves hold the largest share of the product type segment; momentum sits with Butterfly Valves due to their use in large-scale commercial projects.
Material:
Material selection for HVAC valves is dictated by fluid handled, operating pressures, temperature ranges, and required corrosion resistance.
- Stainless Steel:This alloy offers excellent corrosion resistance and high-pressure capabilities, essential for aggressive refrigerants or demanding industrial settings. Demand concentrates in data centers.
- Brass:Copper-zinc alloy, brass valves are common for water-based HVAC systems due to good machinability and corrosion resistance. Cost-effectiveness drives adoption in residential applications.
- Cast Iron:Provides strength and durability for large-diameter, low-pressure applications, especially in older commercial building retrofits.
- PVC:Lightweight, corrosion-resistant polyvinyl chloride valves suit non-critical, low-pressure water systems.
- Bronze:Bronze valves offer good corrosion resistance and strength for potable water systems in commercial buildings.
- Carbon Steel:Robust carbon steel valves handle high pressures, primarily in industrial HVAC systems.
Stainless Steel valves exhibit the steepest expansion trajectory due to compatibility with new refrigerants and high-pressure systems.
End User Industry:
Demand concentration across end-user industries varies, driven by infrastructure development scale and specific environmental control requirements.
- Commercial Buildings:This sector is the largest end-user, encompassing offices, retail, and mixed-use. Demand for electronically actuated valves is driven by energy efficiency retrofits.
- Data Centers:High-density data centers require precise thermal management and uninterrupted cooling, driving demand for high-performance actuated valves globally.
- Residential Complexes:Utilize standard HVAC valves, focusing on cost-effectiveness and reliability.
- Educational Facilities:Require robust and quiet HVAC systems, influencing valve specifications for optimal learning.
- Hospitality Venues:Prioritize occupant comfort and energy efficiency, driving demand for quiet, precise control valves.
- Government Establishments:Require durable, secure HVAC systems, often with long service life specifications.
Commercial Buildings consistently account for the largest volume; Data Centers exhibit the most rapid growth in demand.
Distribution Channel:
Procurement patterns for HVAC valves are influenced by project scale, technical complexity, and need for specialized installation or support.
- Distributors:Serve as intermediaries, stocking HVAC valves and providing local availability to contractors and smaller businesses. Their networks facilitate broad market reach.
- System Integrators:Combine HVAC components into complete building automation solutions for complex projects. They offer value-added services like design and commissioning.
- Direct Sales:Manufacturers sell directly to large original equipment manufacturers or major project developers.
- Online Retailers:Provide convenient access to standardized HVAC valves, catering to smaller contractors and DIY markets.
- Wholesalers:Supply bulk quantities of HVAC valves to smaller distributors and large contractors, focusing on volume and logistics.
- Specialized Dealers:Offer niche valve solutions and technical expertise for specific applications, such as natural refrigerant systems.
Distributors maintain the broadest market penetration, while System Integrators are critical for high-value, integrated solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global HVAC valves market is significantly influenced by stringent energy efficiency mandates and the phase-down of high-GWP refrigerants. These regulatory pressures compel manufacturers and system integrators to adopt advanced valve technologies compatible with new refrigerants and capable of precise flow control.
China
Massive public and commercial infrastructure development, alongside the proliferation of high-density data centers, drives substantial demand for HVAC valves in China. The country's dual carbon goals and national GB standards promote energy-efficient building practices. The Yangtze River Delta region, with its extensive manufacturing base and commercial projects, remains a significant hub for HVAC system deployment.
United States
Energy efficiency retrofits in commercial buildings and continued data center expansion generate consistent demand for high-performance HVAC valves across the United States. The US EPA's AIM Act mandates the phase-down of high-GWP refrigerants, while ASHRAE Standard 90.1 influences valve specifications. Major technology and data center clusters in Silicon Valley and Northern Virginia require advanced thermal management solutions.
Germany
Smart building integrations and ongoing energy efficiency retrofits within the commercial sector underpin demand for HVAC valves in Germany. The EU F-Gas Regulation directly impacts product development, alongside national energy efficiency directives. Cities like Munich and Frankfurt are at the forefront of advanced building automation and green building project implementations.
India
Rapid urbanization, extensive commercial infrastructure projects, and a burgeoning data center build-out contribute to a rising demand for HVAC valves in India. National building codes increasingly promote energy efficiency, while BIS standards guide product quality. Bengaluru and Hyderabad are key IT and data center hubs driving the adoption of modern HVAC systems.
United Arab Emirates
Large-scale commercial, hospitality, and mixed-use developments, combined with significant data center investments, fuel demand for advanced HVAC valves in the United Arab Emirates. Local green building regulations and ambitious sustainability initiatives shape system specifications. Dubai and Abu Dhabi are prominent for smart city developments that integrate high-performance HVAC solutions.
HVAC Valves Market Key Industry Players
Listed leaders compete with private specialists across technology integration and geographic reach within the HVAC valves market. The market structure exhibits a tiered consolidation, where global industrial conglomerates coexist with specialized building automation providers and regional component manufacturers. Strategic partnerships for integrated solutions and portfolio diversification into smart valve technologies represent dominant competitive moves.
Among the global industrial automation providers, Siemens AG exemplifies broad industrial automation capabilities across diverse sectors. Belimo Holding AG represents specialized actuator-driven valve solutions tailored for building automation systems. Johnson Controls International plc anchors building management platforms and extensive distribution networks for comprehensive HVAC solutions.
| Leading Market Players |
|---|
| Siemens AG |
| Emerson Electric Co. |
| Honeywell International Inc. |
| Flowserve Corporation |
| Schneider Electric SE |
| Danfoss A/S |
| Belimo Holding AG |
| Pentair plc |
| Johnson Controls International plc |
| Others |
Cost & Logistics Intelligence
Extended lead times for specialized components, particularly those compatible with low-GWP refrigerants, reflect a concentrated manufacturing base and enable manufacturers to exert greater pricing power. This dynamic influences procurement strategies across commercial and industrial end-users.
Pricing Analysis
CE marking compliance creates the primary pricing spread, differentiating certified European products from standard offerings. Transactional pricing dominates, with project-based contracts for large commercial and data center installations. Price differentiation stems from material compatibility with low-GWP refrigerants and precise flow control capabilities. Pricing pressure affects commodity brass valves, while specialized stainless steel units for high-pressure systems command a premium.
Supply Chain Analysis
Inventory levels for common valve types are generally stable, but specialized electronic actuators face longer procurement cycles. The global supply chain draws from manufacturing hubs in China, Germany, and the United States for various components. Raw material dependencies include brass, copper, and stainless steel, whose prices are subject to commodity market volatility. Distribution runs through a network of distributors and specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HVAC valves market presents a significant opportunity for players who can bridge the current skill gap in integrating advanced IT networking protocols with mechanical HVAC systems. This scarcity of specialized expertise creates distinct competitive advantages.
For Market Incumbents: Secure material science expertise for compatibility with A2L and natural refrigerants to counter disruptive smart valve technologies. Incumbents must invest in certification for high-pressure applications and integrate advanced diagnostics into their electronically actuated valves. Deepening channel relationships with system integrators also reinforces market position against emerging tech-focused entrants.
For New Entrants and Emerging Players: Lead with specialized valve solutions for natural refrigerant systems, targeting the high-pressure transcritical CO2 niche in food retail. Focus on energy retrofit programs in Europe, leveraging government-backed initiatives like the EU's Renovation Wave. Partnering with building automation specialists provides a direct go-to-market channel for advanced, electronically controlled valves.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates seeking to divest non-core HVAC valve divisions lacking specialized digital or refrigerant capabilities. The market demonstrates strong long-term viability over the next 5-10 years, driven by decarbonization mandates. Acquiring mid-sized specialists in smart valve development or natural refrigerant systems offers strategic value. The signal to watch is the accelerating adoption rate of A2L refrigerants in new commercial construction projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop A2L/Natural Refrigerant Valve Line | This initiative ensures compliance with EU F-Gas Regulation and US AIM Act, capturing demand for compatible components. |
| Acquire Building Automation Software Firm | This move enhances integration capabilities for smart building systems, strengthening Johnson Controls' comprehensive offerings. |
| Expand Smart Valve IoT Integration | Integrating IoT sensors into valves provides predictive maintenance data, creating value-added products for data centers. |
| Target EU Renovation Wave Projects | Focusing on Europe's energy efficiency retrofits drives demand for advanced, electronically controlled valves in commercial buildings. |
| Invest in Advanced Material Science R&D | This investment addresses material compatibility hurdles with new, corrosive low-GWP refrigerants, crucial for future product development. |
Research Approach
A spread of perspectives from HVAC engineers, building automation specialists, data center procurement managers, and regulatory affairs experts converged on the working assumptions. Primary interviews validated market dynamics, complemented by extensive secondary research from ASHRAE standards, EU F-Gas Regulation documents, and company financial reports. This approach ensured robust bottom-up and top-down triangulation of market data.
Product type, material, end-user industry, distribution channel, and regional regulatory compliance formed the core segmentation dimensions modeled. An analytical framework integrated historical trends with future projections across the analysis window to derive compound annual growth rates. Data center expansion rates and commercial building retrofit budgets served as key industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU F-Gas and US AIM Act regimes; material policy shifts would require re-modeling. Unforeseen raw material price shocks or rapid technological disruptions could alter market trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Europe Butterfly Valve Market
Valves
Reciprocating Compressor Components Market
Valves
Flare Stack Monitoring Systems Market
Valves
Europe Electro Hydraulic Servo Valve Market
Valves
Pinch Valve Market
Valves
China Explosion-Proof Equipment Market
Valves
Global Plug Valve Market
Valves
Manual Control Valve Market
Valves
Valve Sack Market
Valves
Portable Valve Actuator Market
Valves
Industrial Valves and Actuators Market
Valves
Europe Valves Market
Valves
GCC and MENA Valves Market
Valves
Industrial Safety Valves Market
Valves
Steam Trap Market
Valves
Hot Blast Valves Market