
 Australia Renewable Energy Market | 2026-2036
Australia Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Renewable Energy Market Analysis
Utility-scale battery co-location with solar and wind farms is tilting the technology stack toward dispatchable renewable generation rather than intermittent output alone. AGL Energy leverages its retail customer base to anchor long-term power purchase agreements for new storage-backed projects. Origin Energy competes through integrated gas-to-renewables transition pathways, while Neoen specializes in large-scale battery construction alongside its solar and wind portfolio. Iberdrola Australia controls a growing pipeline of offshore wind developments in Bass Strait waters.
Australia renewable energy encompasses electricity generation from solar photovoltaic, wind turbine, biomass combustion, and hydropower systems, typically feeding voltages from 415V distributed generation up to 330kV transmission connections through grid-following or grid-forming inverters. Its primary commercial purpose is displacing fossil-fuel baseload with low-emission capacity while maintaining frequency control and voltage stability across the National Electricity Market. Solar photovoltaic dominates new capacity additions due to declining module costs and high irradiance across the continent, while wind turbines capture stronger margin pools in coastal regions with consistent resource profiles. Off-grid applications in remote mining operations represent the fastest-growing application segment as diesel displacement economics improve.
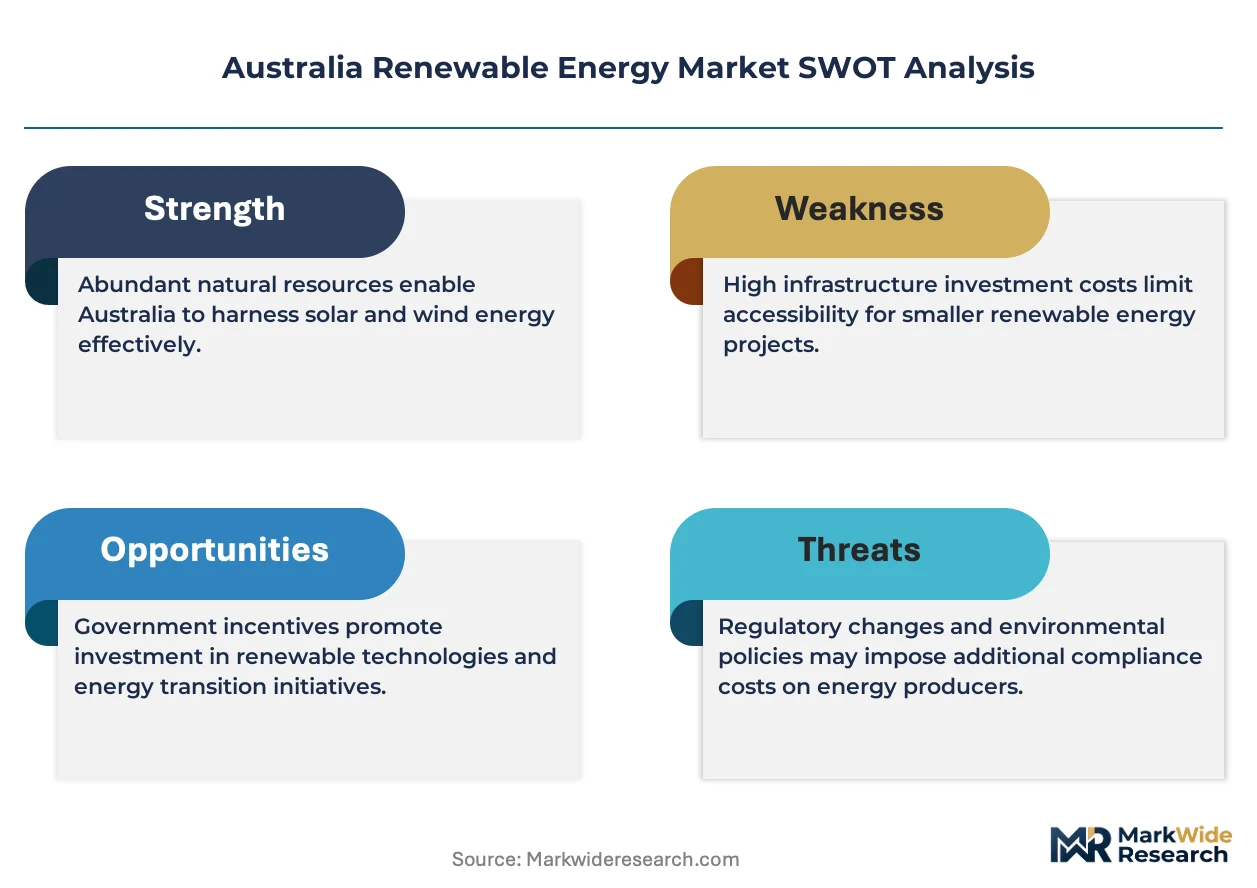
The Clean Energy Regulator administers the Renewable Energy Target scheme, creating certificate-based revenue streams that shape project finance structures, while the Australian Energy Market Commission revises grid connection standards to accommodate inverter-dominated generation profiles. The Australian Competition and Consumer Commission monitors wholesale market bidding behavior as concentration rises among vertically integrated gentailers. Stakeholders must track how the Capacity Investment Mechanism's underwriting design affects merchant revenue exposure for new projects entering construction.
Market Dynamics
Utility-scale battery co-location with solar and wind farms is fundamentally restructuring dispatch economics in the National Electricity Market, shifting revenue models from energy-only to capacity-plus-ancillary services as inverter-dominated generation displaces synchronous baseload.
Growth Catalysts
- Renewable Energy Target scheme:The Clean Energy Regulator's certificate-based mechanism creates bankable revenue streams that de-risk project finance for new solar and wind developments.
- Mining sector diesel displacement:Remote Pilbara operations are accelerating procurement of off-grid renewable systems as fuel logistics costs and carbon exposure intensify.
- Grid-forming inverter standards:The Australian Energy Market Commission's revised connection codes enable higher renewable penetration while maintaining system stability services.
Market Restraints
- Critical mineral supply concentration:Lithium and rare earth processing capacity concentrates in China, exposing battery supply chains to geopolitical friction and input cost volatility.
- Transmission access queuing:Connection approval timelines from the Australian Energy Market Operator stretch 3-5 years for remote renewable zones, freezing capital deployment.
- Gas peaker displacement limits:Current battery duration economics cap substitution of firming capacity beyond four-hour storage, preserving fossil fuel backup roles.
Strategic Opportunities
- Western Australia hydrogen offtake:Renewable hydrogen pilot projects in the Pilbara create anchor demand for dedicated renewable generation capacity with long-term contracts.
- Offshore wind development:Bass Strait waters offer consistent resource profiles untapped by existing infrastructure, with streamlined permitting under emerging state marine planning frameworks.
- Behind-the-meter C&I aggregation:Commercial and industrial solar-plus-storage systems can stack value streams through virtual power plant participation in frequency control markets.
Industry Challenges
- Grid integration engineering shortage:Power systems specialists capable of modeling inverter-based resource dynamics are in acute deficit across project development and network planning functions.
- Certificate market liquidity fragmentation:Large-scale generation certificate price volatility complicates long-term revenue forecasting for merchant-exposed projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Renewable Energy Market |
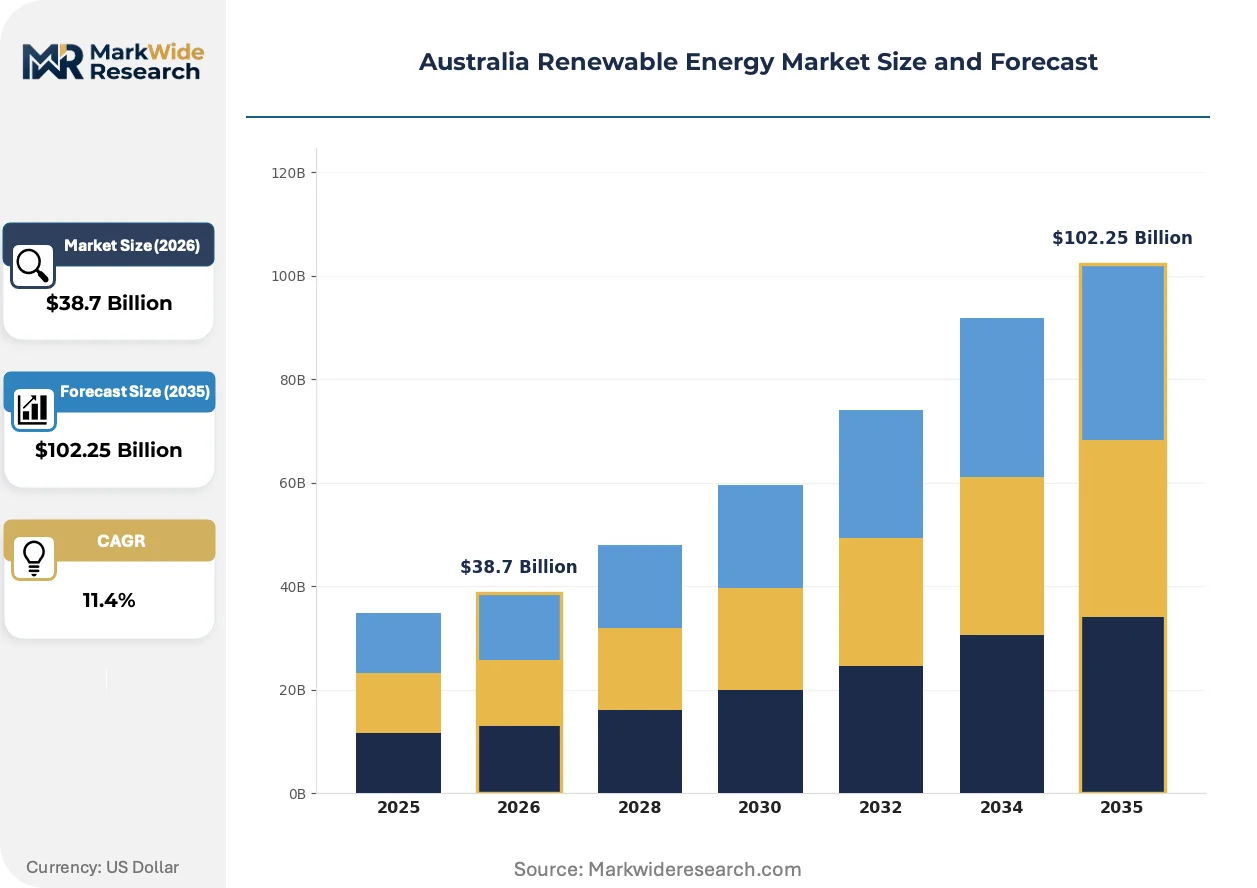
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar Photovoltaic, Wind Turbines, Biomass, Hydropower Application: Grid Connected, Off Grid, Distributed Generation, Microgrid End User: Utilities, Residential, Commercial, Industrial Service Type: Consulting, Installation, Maintenance, Operation |
| Companies Covered | Iberdrola Australia, Tilt Renewables, AGL Energy, ACEN Australia, Snowy Hydro, Origin Energy, Acciona Energia, EnergyAustralia, Neoen, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Renewable Energy Market Emerging Trajectories
Digitization of asset management and predictive maintenance is compressing operational expenditure profiles across renewable portfolios. Software layers now extract value from hardware through performance optimization and market dispatch automation.
Grid-scale battery energy storage systems are virtualizing firming capacity in the National Electricity Market. Mining operators in Queensland and Western Australia are deploying 100MWh-plus systems at remote sites. This virtualization collapses the distinction between generation and load-side resources, enabling synthetic inertia provision from battery inverters.
The Capacity Investment Mechanism's underwriting design is reshaping merchant revenue exposure for new projects entering construction. The Australian Energy Market Operator's auction structure transfers volume risk to government counterparties. Developers in Victoria and New South Wales are restructuring power purchase agreement tenors to align with mechanism timelines.
Corporate renewable procurement is migrating from bundled certificates to physical power purchase agreements with firming obligations. Large energy users in smelting and data center verticals now require dispatchable supply rather than intermittent output. This behavioral shift concentrates in South Australia and Queensland where grid congestion forces location-specific sourcing strategies.
Australia Renewable Energy Market Segmentation
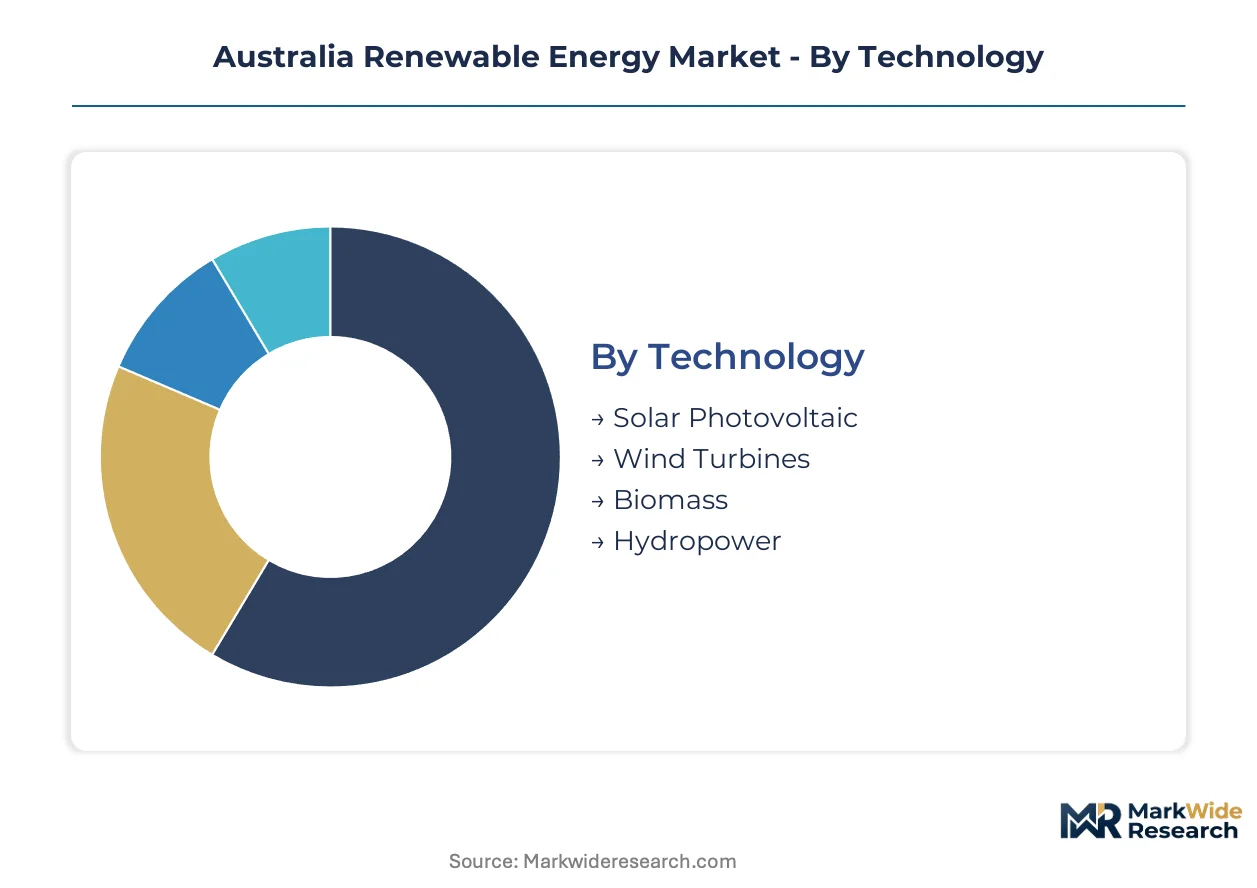
Technology choice dictates capital intensity and revenue stability across Australia's renewable buildout. Application architecture determines grid integration complexity and offtake contract structures. End user concentration shapes procurement scale and payment security profiles.
Technology:
Cost tier stratification separates mature, capital-efficient options from emerging, premium-priced alternatives in the Australian context.
- Solar Photovoltaic:Silicon wafer-based modules convert direct and diffuse irradiance into DC electricity, with utility-scale single-axis tracking systems dominating new capacity. Queensland and Victoria utility-scale installations concentrate procurement volumes as the Clean Energy Finance Corporation de-risks project finance through concessional debt structures.
- Wind Turbines:Horizontal-axis machines with doubly-fed induction generators or full-power converters capture coastal and inland wind resources. Bass Strait offshore developments and South Australian onshore zones command developer attention as the Australian Energy Market Operator identifies these corridors for priority transmission augmentation.
- Biomass:Agricultural residue and forestry waste combustion systems provide dispatchable baseload with synchronous generation characteristics. Sugar mill cogeneration facilities in Queensland represent the primary installed base.
- Hydropower:Run-of-river and pumped storage configurations leverage established water infrastructure. Tasmania's existing reservoir systems and Snowy 2.0 expansion anchor national firming capacity.
Solar Photovoltaic commands the established base. The steepest expansion trajectory runs through Wind Turbines.
Application:
Volume concentration varies sharply between centralized, transmission-connected assets and distributed, behind-the-meter systems.
- Grid Connected:Utility-scale solar and wind farms connect at 66kV to 330kV transmission voltages, dispatching through the National Electricity Market spot price mechanism. Queensland and New South Wales renewable energy zones concentrate development pipelines as the Australian Energy Market Commission streamlines generator registration protocols.
- Off Grid:Standalone diesel displacement systems serve remote mining operations and indigenous communities across Western Australia's Pilbara and Kimberley regions. Rio Tinto and Fortescue Metals Group procurement programs are accelerating battery-hybrid configurations.
- Distributed Generation:Commercial rooftop solar and small-scale wind feed directly into low-voltage distribution networks. South Australia's high residential penetration rates create network voltage management challenges requiring inverter reconfiguration.
- Microgrid:Islanded or semi-islanded systems combine generation, storage, and control for single-site or community-level energy security. Resources sector camps and remote towns in the Northern Territory deploy these architectures.
Grid Connected assets absorb the majority of capital deployment. Off Grid applications are climbing the fastest as mining sector decarbonization timelines compress.
End User:
Customer type determines contract tenor, creditworthiness, and technical specification requirements.
- Utilities:Vertically integrated gentailers and pure-play generators procure long-duration assets to meet renewable portfolio obligations. AGL Energy and Origin Energy power purchase agreement pipelines shape developer project finance structures.
- Residential:Small-scale rooftop solar installations under 100kW capacity dominate household-level decarbonization. New South Wales and Queensland certificate schemes subsidize upfront capital costs through the Small-scale Renewable Energy Scheme.
- Commercial:Mid-sized energy users in retail, hospitality, and light manufacturing deploy behind-the-meter solar-plus-storage. Virtual power plant aggregation programs in Victoria enable frequency control ancillary service revenue stacking.
- Industrial:Smelters, data centers, and hydrogen production facilities require firm, dispatchable supply with high load factors. Western Australia's Pilbara hydrogen hub and Queensland's Gladstone industrial cluster anchor offtake demand.
Utilities command the established base. The steepest expansion runs through Industrial offtakers as physical power purchase agreements displace bundled certificate procurement.
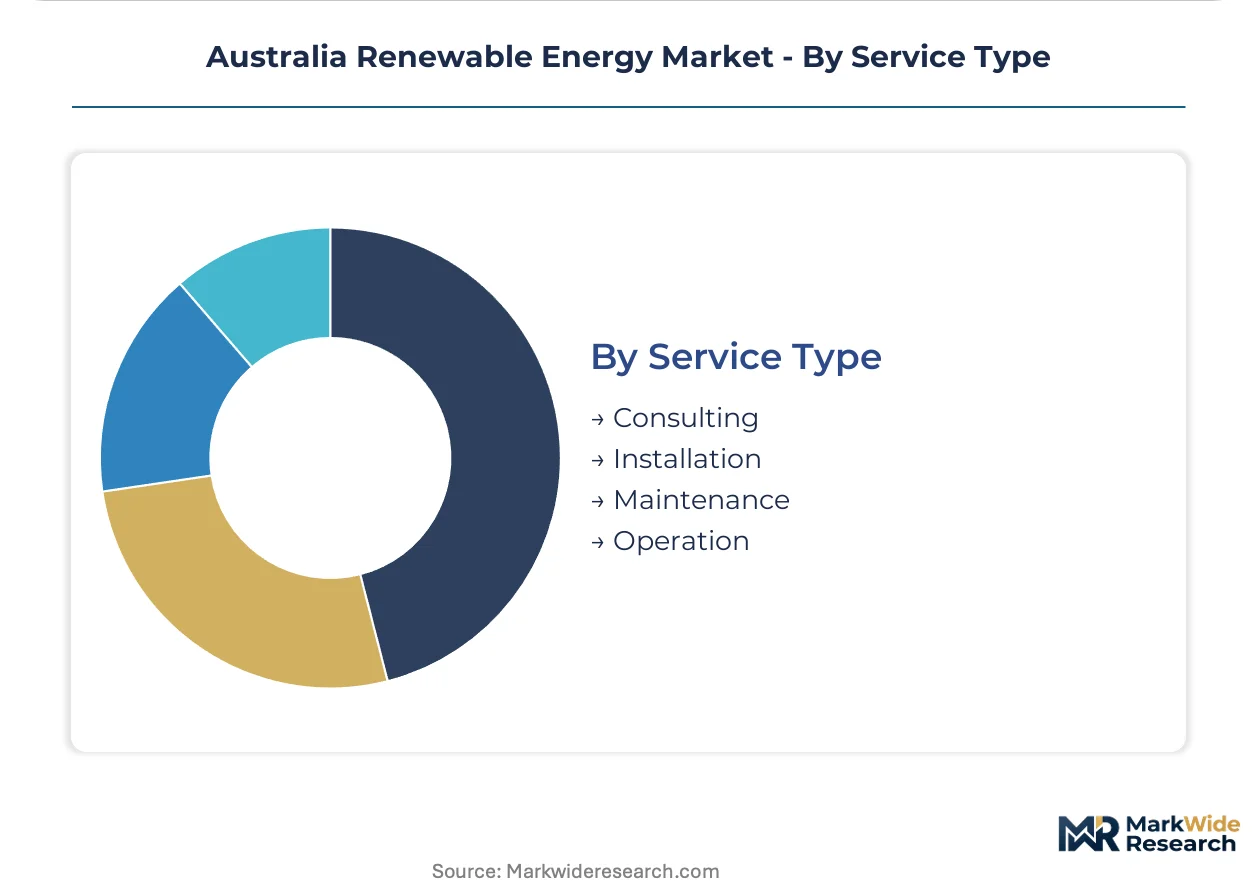
Service Type:
Margin structure varies across the project lifecycle from advisory through operational phases.
- Consulting:Feasibility studies, grid connection applications, and environmental permitting support early-stage development. Specialist power systems engineering firms face acute talent shortages for inverter-dominated resource modeling.
- Installation:EPC contractors deliver turnkey construction with fixed-price risk transfer. Queensland and Victoria utility-scale solar farms concentrate construction activity and skilled labor demand.
- Maintenance:Preventive and corrective servicing maximizes capacity factors and warranty compliance. Drone-based thermographic inspection and predictive analytics are compressing operational expenditure profiles.
- Operation:Asset management and market dispatch optimization extract value from generation and storage portfolios. Algorithmic bidding into the National Electricity Market requires continuous regulatory adaptation.
Installation commands the established base. The steepest expansion runs through Operation as portfolio scale justifies in-house capability buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial off-takers in mining and smelting sectors concentrate procurement in Western Australia's Pilbara and Queensland's Gladstone corridor, while utility-scale developers anchor project pipelines in New South Wales and Victoria renewable energy zones.
New South Wales
Data center operators and hydrogen production facilities drive firm power demand in the Hunter-Central Coast region. The state's Electricity Infrastructure Roadmap designates five renewable energy zones with coordinated transmission investment. Developers concentrate grid-scale solar and wind construction in the Central-West Orana zone, where the Australian Energy Market Operator has streamlined generator registration protocols.
Victoria
Commercial and industrial solar-plus-storage aggregation programs expand frequency control market participation. The Victorian Renewable Energy Target mandates procurement thresholds that reshape gentailer power purchase agreement structures. Latrobe Valley transition projects repurpose existing transmission infrastructure for offshore wind feed-in from Bass Strait developments.
Queensland
Sugar mill cogeneration facilities and utility-scale solar farms dominate the existing installed base. The Clean Energy Finance Corporation's concessional debt structures de-risk project finance for single-axis tracking installations in the state's northern renewable energy zones. Rio Tinto and Fortescue Metals Group procurement programs accelerate battery-hybrid configurations at remote Pilbara operations.
Western Australia
Renewable hydrogen pilot projects in the Pilbara create anchor demand for dedicated generation capacity with long-term offtake contracts. The state's Wholesale Electricity Market operates outside the National Electricity Market, requiring separate grid connection standards from the Australian Energy Market Commission. Remote mining camps and indigenous communities in the Kimberley region deploy microgrid architectures with diesel displacement economics.
South Australia
High residential rooftop solar penetration creates network voltage management challenges requiring inverter reconfiguration. The state's grid-scale battery fleet provides synthetic inertia and frequency control ancillary services. Virtual power plant aggregation programs enable commercial and industrial behind-the-meter systems to stack value streams through market dispatch automation.
Australia Renewable Energy Market Vendor Landscape
Channel-controlling players compete with product-specialist players across Australia's renewable buildout. Vertically integrated gentailers leverage retail customer bases to anchor long-term power purchase agreements, while pure-play developers concentrate on construction and asset management capabilities. Three archetypes dominate: integrated energy retailers with generation portfolios, specialist renewable developers with storage construction expertise, and international utilities with offshore wind pipelines. Competitive moves center on power purchase agreement tenor restructuring and transmission access queue positioning.
Among Spain-based utilities with Australian operations, Iberdrola Australia occupies a position in offshore wind development through Bass Strait pipeline control. French specialists in large-scale battery construction, Neoen, exemplify the storage-backed solar and wind archetype. AGL Energy and Origin Energy represent integrated gentailer positioning, with retail bases anchoring procurement structures for new capacity. These players illustrate how geographic origin and corporate structure shape strategic archetype alignment without dictating specific market actions.
| Leading Market Players |
|---|
| Iberdrola Australia |
| Tilt Renewables |
| AGL Energy |
| ACEN Australia |
| Snowy Hydro |
| Origin Energy |
| Acciona Energia |
| EnergyAustralia |
| Neoen |
| Others |
Supply Flow & Price Mechanics
Chinese lithium hydroxide and rare earth processing capacity concentrates upstream, capturing margin pools that Australian project developers and battery integrators struggle to reclaim through downstream integration. The Clean Energy Finance Corporation's concessional debt structures partially offset this squeeze by lowering weighted average cost of capital for domestic developers, yet module and cell import dependency leaves pricing power concentrated with East Asian suppliers.
Pricing Analysis
Cost-plus contracts with quarterly indexation to polysilicon and lithium carbonate spot benchmarks dominate utility-scale project procurement. Price differentiation separates N-type TOPCon modules with enhanced degradation warranties from legacy PERC technology and unbranded Tier-2 imports. Cost compression in the residential rooftop segment is intensifying because certificate scheme subsidy reductions are shifting payment risk onto installers. Mining sector offtakers exhibit lowest price sensitivity due to diesel displacement economics, while commercial aggregators face acute margin pressure from virtual power plant revenue uncertainty.
Supply Chain Analysis
Contract manufacturing for battery cells concentrates with CATL, BYD, and LG Energy Solution facilities in China and South Korea. Polysilicon ingots and wafers draw from Xinjiang and Yunnan provinces, while wind turbine nacelles source from Vestas factories in Tianjin and Goldwind operations in Urumqi. Single-source vulnerability in lithium spodumene concentrate exposes Australian developers to Pilbara Minerals and Mineral Resources offtake allocation decisions. Distribution runs through AEMO-registered generators and retailer-backed virtual power plants into National Electricity Market dispatch.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward vertically integrated mining houses as Rio Tinto and Fortescue Metals Group consolidate renewable procurement decisions under single sustainability mandates. This concentration fragments developer negotiating leverage across the Pilbara and Queensland industrial corridors.
For Market Incumbents: Entrench transmission access queue positions in the Central-West Orana and Northern Queensland renewable energy zones before connection timelines extend further. Acquire grid-forming inverter engineering capabilities to differentiate from commodity solar and wind developers facing margin erosion. The Australian Energy Market Commission's revised connection standards threaten laggards with technical disqualification from priority dispatch. For New Entrants and Emerging Players: Western Australia's Kimberley region presents underpenetrated off-grid microgrid demand from indigenous communities and remote resource camps. Bass Strait offshore wind permitting offers a second white-space entry point with streamlined Victorian marine planning frameworks and repurposed Latrobe Valley transmission infrastructure. Anchor initial projects through hydrogen offtake agreements with Pilbara pilot facilities rather than competing for saturated utility-scale solar queues. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed developers holding 2018-2021 vintage solar farms facing merchant revenue exposure as large-scale generation certificate prices soften. Long-term viability across the analysis window hinges on storage co-location retrofit economics and power purchase agreement recontracting spreads. Watch the Capacity Investment Mechanism auction clearing prices as the inflection signal for merchant project refinancing stress.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement | AGL Energy and Origin Energy retail bases anchor long-term procurement structures for new capacity. |
| Vertical Integration into Storage | Neoen's battery construction expertise captures ancillary service revenue streams alongside solar generation. |
| Capacity Buildout | Queensland and Victoria utility-scale zones concentrate Clean Energy Finance Corporation de-risked deployment. |
| Technology Licensing | Grid-forming inverter standards from the Australian Energy Market Commission enable higher renewable penetration. |
| Green Certification Program | Clean Energy Regulator certificate schemes create bankable revenue streams shaping project finance structures. |
Methodological Framework
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators and refined through secondary validation. The analysis combined structured interviews with Australian Energy Market Operator dispatch specialists and Clean Energy Finance Corporation investment leads against project development databases, IEA renewable deployment reports, AEMO integrated system plan filings, and customs import records for module and cell shipments. Bottom-up capacity addition tracking and top-down National Electricity Market demand forecasting were triangulated to anchor segment sizing.
Demand-supply balance modeling across the projection horizon incorporated technology segmentation by solar photovoltaic, wind turbine, and battery storage systems; application architecture across grid-connected, off-grid, and distributed generation; and end-user concentration among utilities, industrial offtakers, and commercial aggregators. CAGRs were derived from regression-adjusted capacity deployment curves and merchant revenue sensitivity to certificate price trajectories. Forecast inputs included AEMO transmission augmentation timelines and the Capacity Investment Mechanism auction design parameters.
Practitioners should monitor lithium carbonate price volatility, grid connection approval delays, and large-scale generation certificate market liquidity for early signals of forecast revision. Forecasts reflect assumptions regarding the Australian Energy Market Commission's inverter standards implementation pace and mining sector diesel displacement acceleration. Quarterly review of AEMO generator registration queues and Clean Energy Regulator certificate surrender data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Green Renewable Energy Market
Renewable Energy
South Asia Renewable Energy Market
Renewable Energy
Marine Energy Market
Renewable Energy
Finland Renewable Energy Market
Renewable Energy
New Zealand Renewable Energy Market
Renewable Energy
Ethiopia Renewable Energy Market
Renewable Energy
South America Renewable Energy Market
Renewable Energy
Europe Biomethane Market
Renewable Energy
Republic of Ireland Renewable Energy Market
Renewable Energy
LAMEA Wave and Tidal Energy Market
Renewable Energy
East Europe Renewable Energy Market
Renewable Energy
Renewable Energy Cable Market
Renewable Energy
Green Energy Lighting Market
Renewable Energy
Europe Ocean Power Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
Solar Showers Market