
 Laparotomy Sponges Market | 2026-2036
Laparotomy Sponges Market Size, Share, and Industry Trends Forecast 2026-2036
Laparotomy Sponges Market Intelligence
The shift toward radiopaque sponges with integrated radio-frequency identification (RFID) tracking systems is redrawing the standards for patient safety and inventory management. Cardinal Health leverages its extensive distribution network to supply these advanced products to major hospital systems. Medtronic specializes in integrating such technologies within its broader surgical solutions portfolio. B. Braun Melsungen AG competes on the basis of its manufacturing excellence and material science innovations in sponge composition.
Laparotomy sponges are highly absorbent pads used during surgical procedures to absorb excess fluids, protect organs, and assist in blunt tissue dissection. These medical devices are typically manufactured from 100% cotton and feature an x-ray detectable thread to prevent retention in the body post-surgery. Radiopaque sponges command the market due to safety mandates and hospital protocols. While hospitals remain the dominant end-user segment, Ambulatory Surgical Centers represent a significant growth area.
Regulatory frameworks, including the U.S. FDA's requirements for Class II medical devices and Europe's Medical Device Regulation (MDR), impose strict quality and traceability standards. Compliance with directives from bodies like Japan's PMDA is essential for market access in key Asian geographies. The key decision for manufacturers now centers on balancing the cost of advanced features like antimicrobial coatings against the procurement budgets of healthcare providers.
Market Dynamics
The central structural force shaping the laparotomy sponges market is the tension between the adoption of advanced, high-cost safety technologies like RFID and the intense cost-containment pressures exerted by healthcare providers and reimbursement systems globally.
Growth Catalysts
- RFID Integration:The incorporation of radio-frequency identification chips into sponges to automate surgical counting processes is a significant catalyst, directly addressing the critical patient safety issue of retained surgical items.
- Surgical Volume Growth:A consistent rise in the number of surgical procedures performed in Ambulatory Surgical Centers, particularly in developed economies, expands the core consumer base for these essential medical supplies.
- Regulatory Mandates:Stringent patient safety protocols and device traceability requirements, such as those enforced by the U.S. FDA and under Europe's Medical Device Regulation (MDR), compel healthcare facilities to adopt safer, radiopaque sponges.
Market Restraints
- Raw Material Volatility:The market is sensitive to price fluctuations in 100% cotton, the primary raw material, which can compress manufacturer margins or lead to price increases for healthcare providers.
- Substitution Threats:In specific surgical contexts, alternative solutions like advanced hemostatic agents and novel wound closure technologies can reduce the required volume of traditional laparotomy sponges.
- Cost-Containment Pressures:Budget constraints within public and private healthcare systems, especially in Europe, can slow the adoption of premium-priced sponges with advanced features like antimicrobial coatings or RFID tracking.
Strategic Opportunities
- Emerging Market Penetration:Manufacturers have a significant opportunity to expand into markets across Latin America and Southeast Asia, where improving healthcare infrastructure and rising surgical volumes create new demand.
- Biodegradable Materials:Developing sponges from sustainable, biodegradable materials presents a white-space opportunity to appeal to healthcare systems focused on reducing their environmental footprint and medical waste.
- Antimicrobial Coatings:The integration of antimicrobial agents into sponge fibers offers a clear value proposition by helping to reduce the incidence of surgical site infections, a major focus for hospitals worldwide.
Industry Challenges
- Supply Chain Integrity:Ensuring the sterility and traceability of sponges from manufacturing to the operating room requires a complex and resilient supply chain, which remains vulnerable to global logistics disruptions.
- User Training and Adoption:The effective implementation of RFID-enabled sponge counting systems requires significant investment in training operating room personnel, posing an operational challenge for hospitals.
- Standardization Hurdles:A lack of globally harmonized standards for sponge counting and tracking protocols complicates product design and marketing for manufacturers operating in multiple international markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laparotomy Sponges Market |
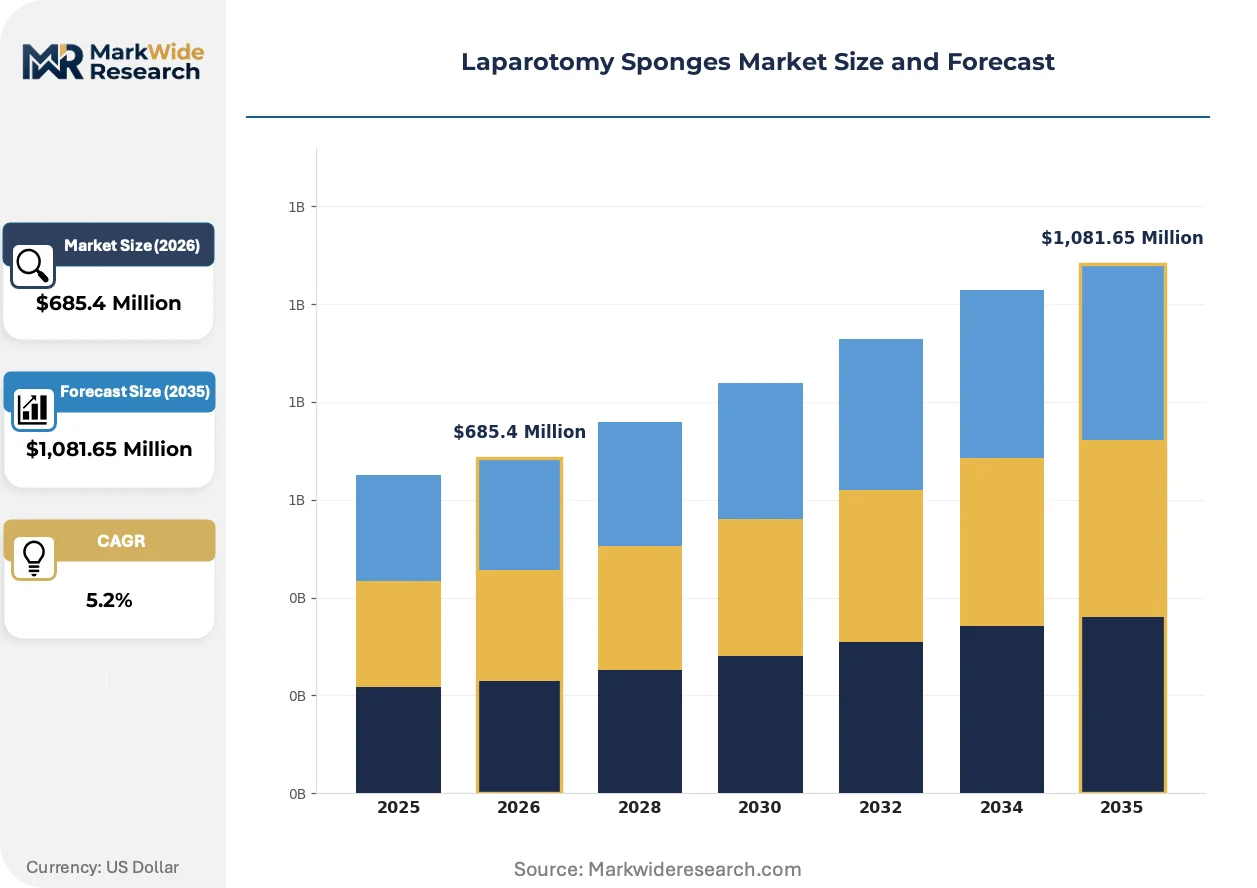
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Sponges, Radiopaque Sponges, Specialty Sponges, Antimicrobial Sponges End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialty Surgical Centers Material: Cotton, Non-woven Fabric, Rayon, Composite Materials Application: General Surgery, Obstetrics, Orthopedic Surgery, Trauma Surgery |
| Companies Covered | Cardinal Health, Integra LifeSciences, Stryker, Medtronic, Owens & Minor, B. Braun Melsungen AG, Medline Industries, Dynarex, DeRoyal Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laparotomy Sponges Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of material science innovation and digital tracking technologies. This combination is establishing new benchmarks for patient safety, inventory control, and operational efficiency within surgical environments.
Radio-frequency identification technology integrated into sponges provides a non-invasive method for real-time tracking, aiming to eliminate retained surgical items. Major hospital systems, particularly in the United States and Germany, are leading the adoption curve, driven by stringent patient safety goals. This technology is bifurcating the market into a premium segment defined by digital safety systems and a standard tier relying on traditional X-ray detection and manual counts.
Europe's Medical Device Regulation (MDR) imposes significantly stricter requirements for clinical evaluation, traceability, and post-market surveillance on manufacturers. This has increased the compliance burden and associated costs across the medical device industry. The radiopaque sponges category is particularly affected, as producers must now generate more robust data to maintain their CE marking for market access within the European Union.
A notable behavioral change is the consolidation of purchasing decisions within large healthcare networks. Group Purchasing Organizations (GPOs) and Integrated Delivery Networks (IDNs) are increasingly centralizing procurement, displacing transactional, per-unit sales with long-term, volume-based contracts. This trend is most visible within the United States healthcare system, where large hospital groups leverage their significant purchasing power to negotiate favorable pricing and integrated supply agreements.
Laparotomy Sponges Market Segmentation
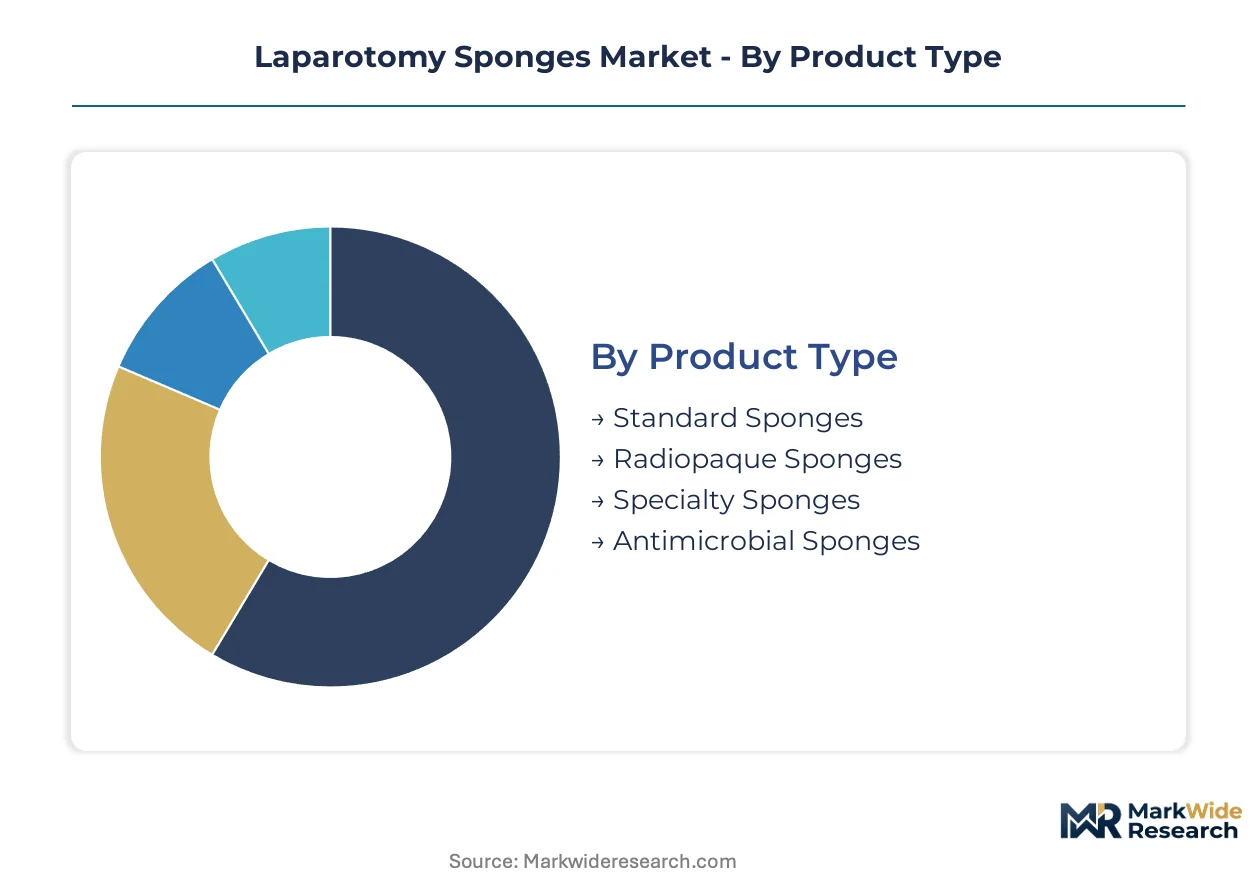
The segmentation of the laparotomy sponges market reveals how product innovation, end-user requirements, and material science collectively shape demand and supply dynamics. Understanding these distinct segments assists manufacturers in tailoring product development and market strategies to specific healthcare needs.
Product Type:
The distribution of laparotomy sponges often dictates the type of product available to healthcare providers, reflecting varied procurement channels and safety requirements.
- Radiopaque Sponges:These sponges incorporate an x-ray detectable thread, crucial for post-surgical verification and preventing retained surgical items. Demand concentrates in advanced healthcare systems like those in the United States and Germany, driven by stringent patient safety mandates.
- Antimicrobial Sponges:Integrating antimicrobial agents into their fibers, these sponges aim to reduce surgical site infections, a significant concern for hospitals globally. Procurement budgets heavily influence their adoption, particularly in cost-sensitive healthcare environments.
- Standard Sponges:These basic absorbent pads are used for fluid management during less complex surgical procedures.
- Specialty Sponges:Designed for specific surgical needs, these sponges offer unique shapes or enhanced absorbency for intricate operations.
By volume, Radiopaque Sponges lead due to safety mandates. By growth pace, Antimicrobial Sponges are gaining share fastest as infection control becomes paramount.
End User:
The varied types of healthcare facilities performing surgical procedures directly influence the volume and specification of laparotomy sponges procured.
- Hospitals:These institutions represent the dominant end-user segment for laparotomy sponges, handling a wide array of complex surgical cases. Their purchasing decisions are often centralized through Group Purchasing Organizations, influencing volume-based contracts.
- Ambulatory Surgical Centers:These facilities are experiencing significant growth in surgical volumes, particularly for outpatient procedures, expanding the core consumer base for essential medical supplies. Cost-effectiveness and efficient inventory management are critical for these centers.
- Clinics:Smaller medical facilities utilize laparotomy sponges for minor surgical interventions and diagnostic procedures.
- Specialty Surgical Centers:These centers focus on particular surgical disciplines, requiring specific types and sizes of sponges for their specialized operations.
Hospitals maintain the largest market share for sponge consumption. Ambulatory Surgical Centers demonstrate the most rapid expansion in adoption.
Material:
The foundational material composition of laparotomy sponges directly impacts their absorbency, cost, and environmental footprint, influencing procurement decisions.
- Cotton:Comprising 100% cotton, these sponges are the traditional and most widely used material due to their high absorbency and biocompatibility. Raw material price volatility significantly affects manufacturing costs and market pricing.
- Composite Materials:These advanced materials combine different fibers, such as cellulose and synthetics, to achieve enhanced absorbency or durability. Development in this area presents opportunities for sustainable and biodegradable options.
- Non-woven Fabric:These materials offer an alternative to traditional cotton, sometimes providing cost efficiencies or specific fluid handling properties.
- Rayon:Known for its softness and absorbency, rayon is occasionally blended or used as a primary material in certain sponge formulations.
Surgeons widely prefer cotton for its natural properties. Innovation is concentrated in composite materials for future advancements.
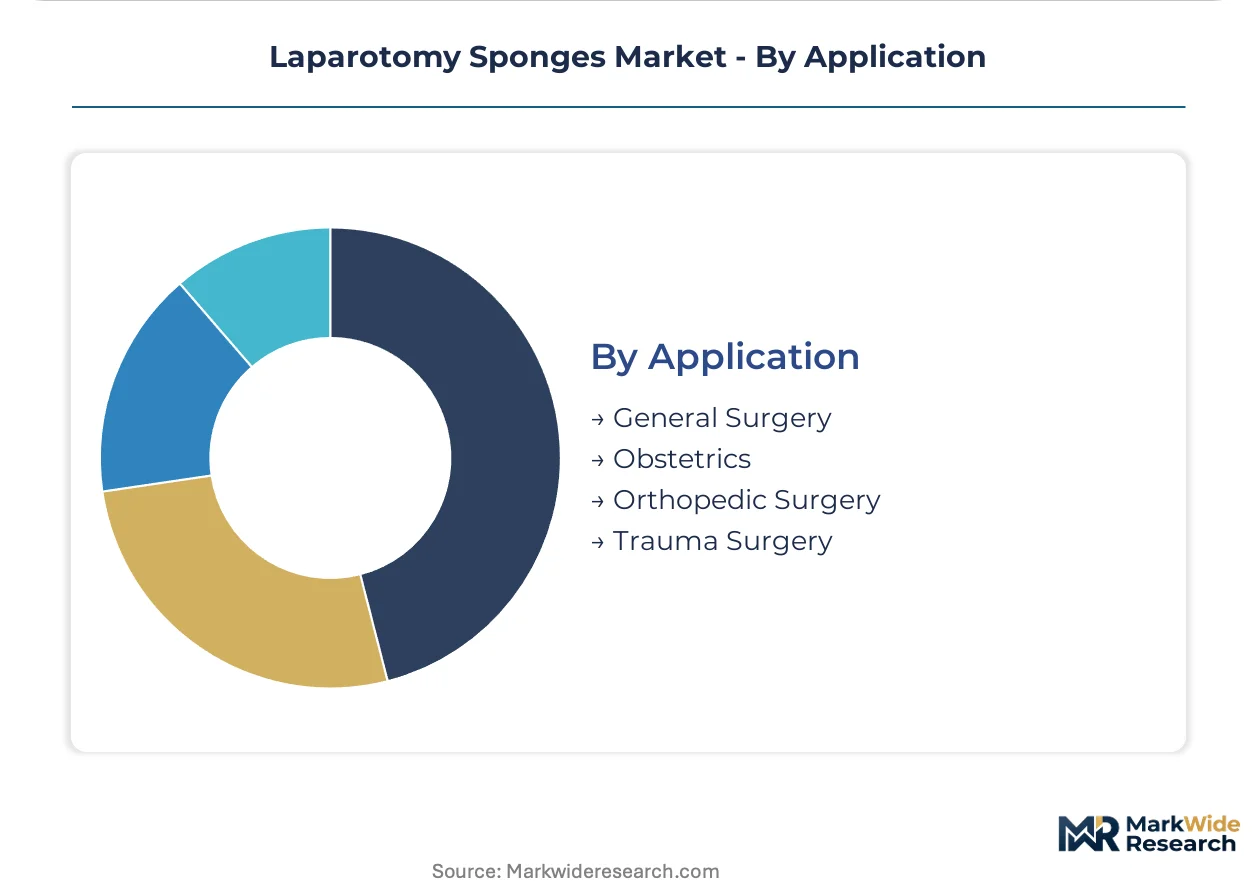
Application:
The specific surgical discipline dictates the type, size, and quantity of laparotomy sponges required, reflecting procedural demands and patient needs.
- General Surgery:This broad category encompasses a vast range of procedures, making it the largest application segment for laparotomy sponges. High procedural volumes drive consistent demand for various sponge types.
- Trauma Surgery:Urgent and often extensive, trauma surgeries require significant quantities of highly absorbent sponges for fluid management and hemostasis. Patient safety initiatives are particularly critical in these emergency settings.
- Obstetrics:Laparotomy sponges are essential in obstetric procedures such as C-sections for fluid absorption and tissue protection.
- Orthopedic Surgery:While not always the primary focus, sponges are used in orthopedic operations for fluid control and maintaining a clear surgical field.
General Surgery procedures generate the highest demand volume. Trauma Surgery applications emphasize rapid availability and critical performance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global laparotomy sponges market exhibits diverse regional demands and regulatory landscapes, driven by varying healthcare infrastructure and patient safety priorities. Strong trade flows exist, with advanced medical device manufacturers in Germany often supplying specialized surgical consumables to markets worldwide. This influences product availability and technology adoption across different healthcare systems.
United States
Rising surgical volumes in Ambulatory Surgical Centers drive demand for radiopaque sponges in the United States. U.S. FDA requirements for Class II medical devices mandate stringent safety and traceability standards for these products. Boston's MedTech hub focuses on surgical device innovation, integrating advanced features into medical consumables.
Germany
Advanced surgical practices and patient safety initiatives underpin demand for high-quality sponges throughout Germany. Europe's Medical Device Regulation (MDR) imposes strict compliance burdens on manufacturers operating within the EU. The 'Medical Valley' in Erlangen serves as a key center for medical technology development, fostering innovation in surgical supplies.
Japan
Stringent safety standards and an aging population requiring more surgical interventions propel the Japanese market. PMDA directives are essential for market access, ensuring product efficacy and patient safety. Tokyo's medical device industry integrates advanced materials into surgical tools, enhancing functional performance.
India
Improving healthcare infrastructure and rising surgical volumes create new demand for laparotomy sponges across India. CDSCO regulations govern medical device imports and manufacturing, impacting product availability and quality. Bengaluru's burgeoning MedTech sector sees increasing local production of medical consumables, catering to domestic needs.
China
Expanding hospital networks and increasing access to surgical care fuel consumption of medical sponges in China. NMPA oversight ensures medical device quality and safety for both domestically produced and imported goods. Shanghai's medical device industry concentrates on advanced surgical supply chain development, supporting broader healthcare goals.
Laparotomy Sponges Market Key Industry Players
Listed leaders compete with private specialists across product innovation and distribution networks within the laparotomy sponges market. The market exhibits a moderately consolidated structure, with a few global entities holding significant shares, alongside numerous regional and niche players. Strategic archetypes include large-scale diversified medical device conglomerates, specialized surgical consumable providers, and regional distributors focusing on cost-effectiveness. Companies frequently engage in strategic partnerships to expand geographic reach and integrate new technologies like RFID into their offerings, enhancing patient safety.
On the global scale, companies like Cardinal Health and Medtronic exemplify broad portfolio strategies, leveraging extensive distribution networks to supply advanced surgical products. Cardinal Health (an Ohio-based corporation) occupies a position as a major distributor of medical supplies, including radiopaque sponges with RFID technology. Medtronic (an Irish-domiciled company) integrates such technologies within its broader surgical solutions portfolio, focusing on comprehensive operating room offerings. B. Braun Melsungen AG (a German-based private company) anchors its competitive position on manufacturing excellence and material science innovations in sponge composition, serving diverse healthcare systems globally.
| Leading Market Players |
|---|
| Cardinal Health |
| Integra LifeSciences |
| Stryker |
| Medtronic |
| Owens & Minor |
| B. Braun Melsungen AG |
| Medline Industries |
| Dynarex |
| DeRoyal Industries |
| Others |
Cost & Logistics Intelligence
Europe's Medical Device Regulation (MDR) compliance gates both supply qualification and price differentiation for advanced laparotomy sponges. Manufacturers must navigate stringent quality standards, directly impacting product costs and market access. This regulatory environment fosters a market where premium features command higher prices.
Pricing Analysis
Healthcare system buyers anchor pricing structures through long-term, volume-based contracts, particularly with Group Purchasing Organizations. Price differentiation stems from certification levels, such as U.S. FDA Class II clearance, and the inclusion of advanced features like RFID technology. Pricing softness runs through the standard sponge segment due to intense cost-containment pressures from Ambulatory Surgical Centers. Hospitals, prioritizing patient safety, demonstrate lower price sensitivity for radiopaque and RFID-enabled products.
Supply Chain Analysis
Volatility in 100% cotton prices underwrites a significant supply chain risk for laparotomy sponge manufacturers. Geographic supply concentration for raw cotton centers in countries like India and China, while advanced component manufacturing often occurs in Germany and the United States. Single-source vulnerability for specialized components, such as RFID chips, poses a structural risk. Distribution runs through major medical device distributors like Cardinal Health and Owens & Minor, reaching healthcare systems globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents an early-cycle expansion story, primarily driven by the increasing penetration of patient safety technologies like RFID in surgical settings.
For Market Incumbents: Consolidate market share by acquiring niche technology providers specializing in RFID integration or antimicrobial coatings. Deepen strategic partnerships with major Group Purchasing Organizations to secure long-term, volume-based contracts, mitigating substitution threats from advanced hemostatic agents. Invest in R&D for next-generation biodegradable materials to align with evolving sustainability mandates.
For New Entrants and Emerging Players: PMDA approval fast-track offers a strategic entry point into the Japanese market for specialized sponges. Target Ambulatory Surgical Centers with cost-effective, radiopaque sponge solutions that meet essential safety standards without premium RFID features. A value-based go-to-market angle, emphasizing core safety and absorbency, allows penetration in price-sensitive healthcare environments across Latin America and Southeast Asia.
For Investors and Strategic Acquirers: Europe's Medical Device Regulation (MDR) reshapes the acquisition landscape, favoring companies with robust compliance frameworks and proven product efficacy. The long-term viability of essential surgical consumables remains strong over the next 5-10 years, driven by consistent surgical volumes and patient safety mandates. Target specialized manufacturers with patented RFID or antimicrobial technologies, or those with strong distribution networks in high-growth emerging markets. Increased M&A activity in sustainable medical consumables is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| RFID Technology Acquisition | Securing advanced tracking capabilities enhances patient safety and inventory management for surgical teams. |
| Biodegradable Material R&D | Developing sustainable sponge alternatives addresses environmental concerns and aligns with green procurement policies. |
| Hospital System Partnership | Establishing long-term agreements ensures stable demand and deepens integration within major healthcare networks. |
| CE Marking Pathway Investment | Obtaining European regulatory approval facilitates market access and broadens distribution across the EU. |
| Supply Chain Digitalization | Implementing digital tools improves traceability, reduces waste, and strengthens resilience against disruptions. |
Research Approach
The analysis maps product types, end-user segments, and material compositions, each validated through primary interviews with hospital procurement managers, surgical nurses, medical device engineers, and GPO contract specialists. Secondary validation leverages U.S. FDA filings, Europe's MDR guidance documents, PMDA directives, and medical device association reports. This approach integrates bottom-up data collection with top-down market sizing for comprehensive insights.
Outputs underwent consistency checks against external benchmarks and industry reports across the analysis window. The analytical framework incorporates segmentation dimensions including product type, end user, material, application, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical trends and projected market shifts, with key forecast inputs including surgical procedure volumes and healthcare expenditure trends.
Decision-makers should treat outputs as directional under stable regulatory environments and consistent raw material supply; material deviation would warrant model refresh. Forecasts reflect these base assumptions. Revision becomes warranted when significant changes in patient safety mandates or raw material costs cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
US Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Global Surgical Retractor Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
United States Minimally Invasive Surgery Market
Surgical Instruments
Global Veterinary Surgical Instruments Market
Surgical Instruments
Resectoscopes Market
Surgical Instruments
India Surgical Sutures Market
Surgical Instruments
Global Electromagnetic Surgical Navigation System Market
Surgical Instruments
Surgical Equipment Market
Surgical Instruments
Surgical Suction Pumps Market
Surgical Instruments
Global Minimally Invasive Surgery (MIS) Market
Surgical Instruments
Robotic Surgery Market
Surgical Instruments
Global Surgical Lasers Market
Surgical Instruments
Spain General Surgical Devices Market
Surgical Instruments
United States General Surgical Devices Market
Surgical Instruments
Europe Biosurgery Market