
 Global Surgical Lasers Market | 2026-2036
Global Surgical Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Lasers Market Foresight
A capital-intensity divergence between integrated manufacturers and component assemblers is bifurcating competitive returns in surgical lasers. Lumenis Be Ltd leverages in-house fiber and solid-state fabrication to sustain premium positioning across ophthalmology and dermatology platforms. Alma Lasers competes through aggressive geographic expansion into ambulatory settings across Latin America and Southeast Asia. IPG Photonics Corporation anchors its position via captive diode and fiber laser supply chains that lower unit costs for OEM partners.
Surgical lasers are instruments that generate coherent, monochromatic light beams at precise wavelengths and power densities to cut, coagulate, vaporize, or ablate tissue with minimal thermal spread to adjacent structures. Solid-state Nd:YAG and Er:YAG platforms dominate neurosurgery and dentistry respectively due to their specific absorption peaks in water and hemoglobin. Gas-based CO2 lasers retain entrenched positions in ENT and gynecological procedures where shallow penetration depths reduce collateral tissue damage. Diode and semiconductor technologies are capturing share in dermatology applications as portable, lower-cost alternatives to legacy platforms.
FDA 510(k) clearance pathways and the EU Medical Device Regulation shape product development timelines and clinical evidence requirements for manufacturers seeking market access. ISO 13485 quality management standards and IEC 60601-1-22 laser-specific safety protocols further constrain design choices and manufacturing compliance burdens. Stakeholders must monitor evolving reimbursement decisions by CMS and national health technology assessment bodies that determine whether laser procedures qualify for procedure code coverage in outpatient settings.
Market Dynamics
The surgical lasers sector faces a structural squeeze between escalating EU MDR clinical evidence mandates and ambulatory centers' procurement pressure for lower per-procedure costs. This tension compresses margins for equipment makers while accelerating technology refresh cycles.
Growth Catalysts
- Outpatient Migration:Ambulatory surgical centers in the United States are expanding laser procedure volumes as CMS reimbursement pathways mature across ophthalmology and dermatology specialties.
- EU MDR Compliance Upgrades:Manufacturers are capturing replacement demand as hospitals retire legacy devices that cannot meet tightened pre-market clinical evidence requirements for laser surgical equipment.
- Solid-State Platform Refinement:Nd:YAG and Er:YAG systems are penetrating neurosurgery and dentistry applications through specific absorption optimization in water and hemoglobin.
Market Restraints
- Diode Supply Concentration:Captive diode fabrication at IPG Photonics and limited qualified suppliers in Germany and Japan create input bottlenecks for OEM partners.
- CO2 Laser Entrenchment:Gas-based platforms retain installed base dominance in ENT and gynecology, slowing solid-state substitution despite superior thermal profiles.
- FDA 510(k) Timeline Compression:Predicate device disputes and substantive review backlogs extend product development timelines for novel wavelength platforms.
Strategic Opportunities
- Southeast Asia Ambulatory Expansion:Alma Lasers' geographic playbook demonstrates latent demand in Vietnam and Indonesia where private clinic infrastructure is scaling.
- Photonics-AI Convergence:Real-time tissue feedback systems integrating spectral analysis with laser delivery are enabling precision improvements in oncology resections.
- IRReimbursement Tailwinds:India's PLI scheme for medical device manufacturing offers duty and tax incentives for domestic laser assembly operations.
Industry Challenges
- Clinical Specialist Scarcity:Laser safety certification programs through AORN and specialty societies cannot match training demand across expanding ambulatory networks.
- ISO 13485 Audit Burden:Multi-site quality management recertification consumes 14-18 month cycles, delaying product line extensions.
- Legacy System Integration:EMR connectivity protocols for older CO2 and Nd:YAG platforms require costly middleware development for hospital IT compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Lasers Market |
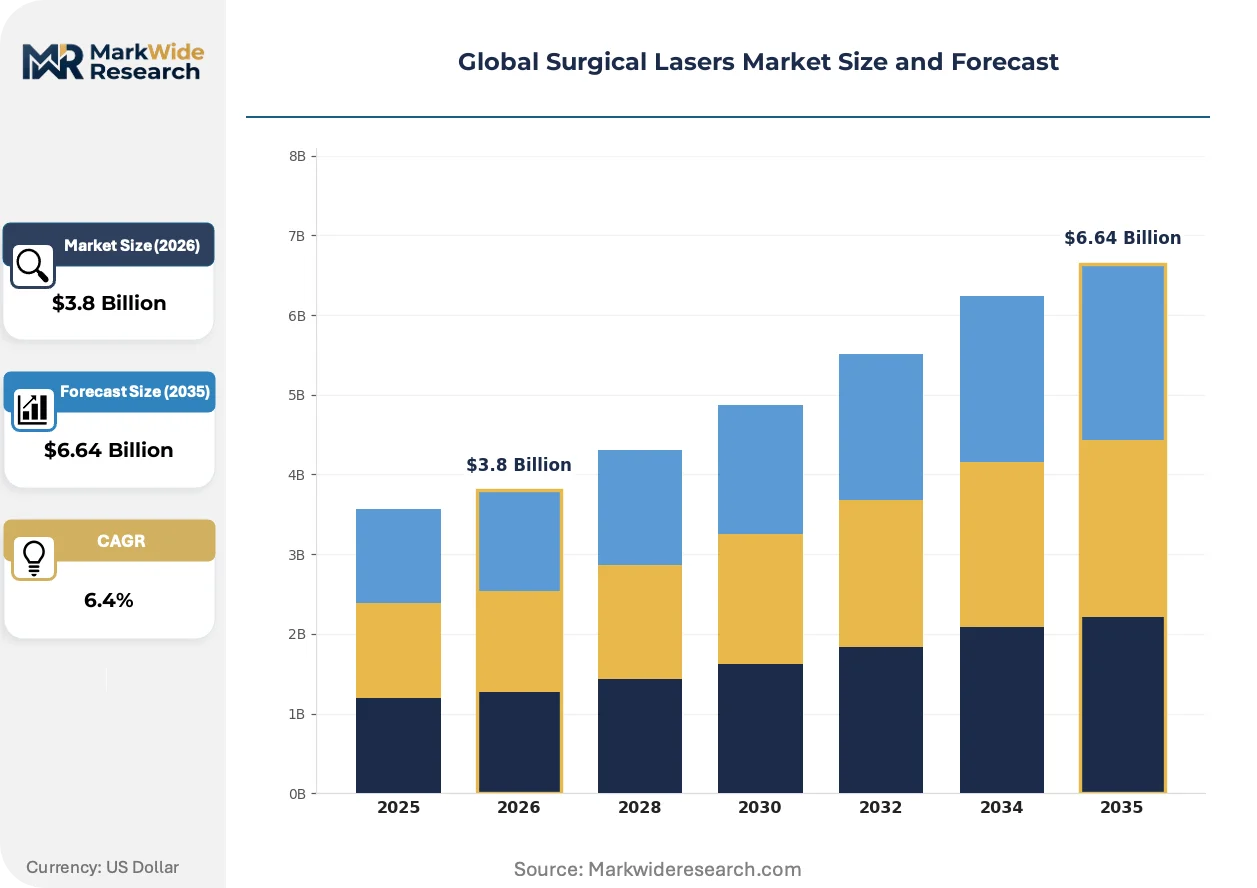
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CO2 Laser, Nd:YAG Laser, Erbium Laser, Diode Laser, Alexandrite Laser, Dye Laser Application: Dermatology, Ophthalmology, ENT Procedures, Dentistry, Gynecology, Neurosurgery End User: Specialty Clinics, Ambulatory Surgical Centers, Academic Research Facilities, Dental Offices, Eye Care Centers, Cosmetic Surgery Clinics Technology: Solid-State, Gas, Semiconductor, Fiber, Dye, Free Electron |
| Companies Covered | Lumenis Be Ltd, Cynosure, Alma Lasers, Candela Corporation, IPG Photonics Corporation, KLS Martin Group, Fotona, BIOLASE, Inc., El.En., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Lasers Market Shifts & Advancements
Waveguide and fiber delivery architectures are fragmenting established platform economics while regulatory harmonization efforts stall. These shifts compress hardware margins and elevate software-enabled service contracts as differentiation vectors.
Semiconductor diode arrays are fragmenting the dermatology segment where portable, lower-cost alternatives displace legacy solid-state systems in private practice settings. Aesthetic clinics in Brazil and Mexico are adopting these platforms at twice the replacement rate of hospital systems. The technology is fragmenting price architecture across the mid-market tier, forcing incumbents to unbundle service contracts from hardware sales.
EU MDR Article 10 post-market surveillance requirements are extending clinical follow-up obligations from two to five years for active implantable and high-risk devices. Manufacturers must now maintain registry data or face notified body suspension. Ophthalmology platforms with predicate clearances predating 2017 are experiencing the steepest compliance cost escalation.
Hospital procurement committees are consolidating vendor relationships through single-source agreements that bundle capital equipment, disposables, and training. This behavior concentrates purchasing power among IDN networks in Texas and Florida while squeezing independent distributors. The shift is most visible in gynecology suites where laser hysteroscopy volumes justify dedicated service contracts over transactional equipment sales.
Global Surgical Lasers Market Segmentation
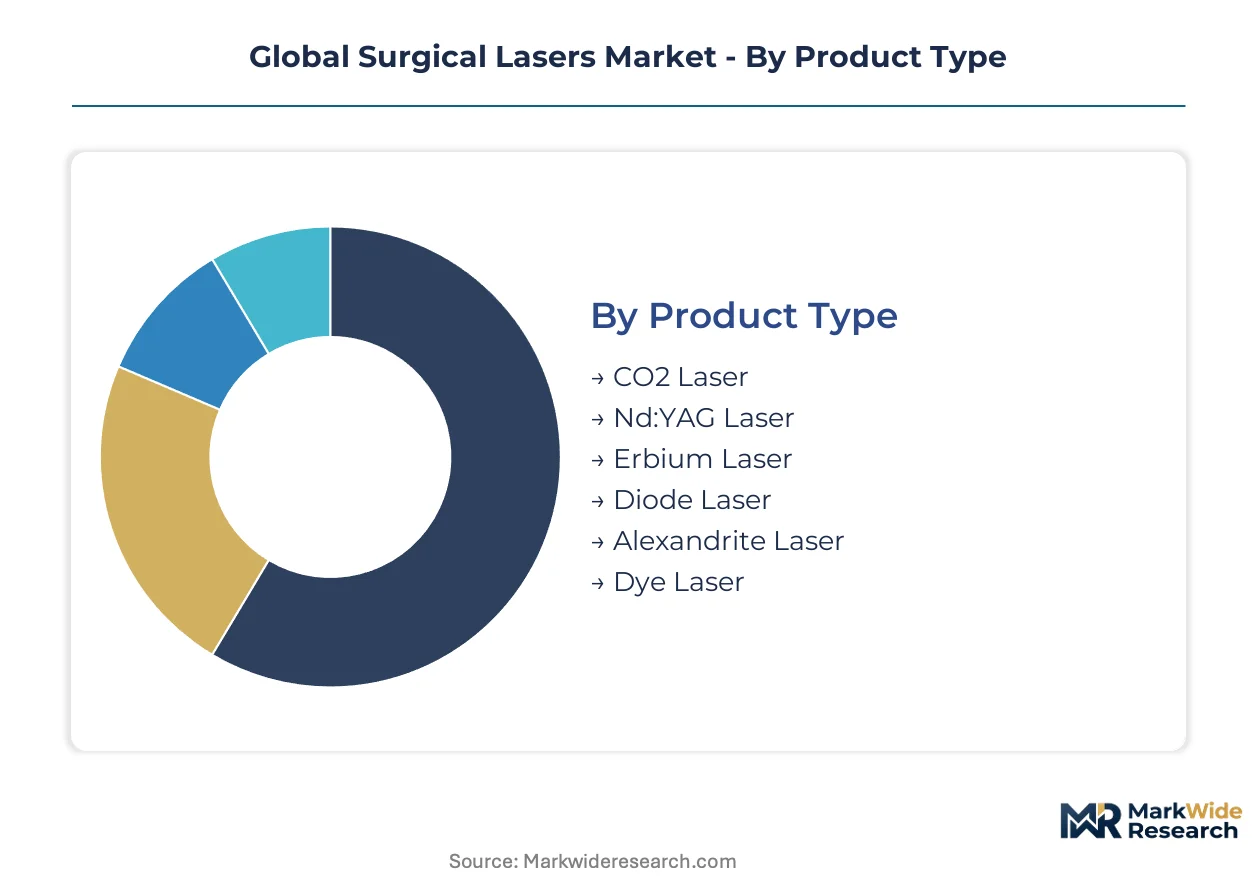
Surgical laser segmentation reveals divergent margin profiles across wavelength platforms and care delivery settings. Product type and application splits determine pricing power, while end-user concentration shapes procurement leverage and service contract economics.
Product Type:
Margin pools concentrate in solid-state and gas laser platforms where proprietary resonator designs sustain premium positioning against commoditized diode alternatives.
- CO2 Laser:Gas-based systems generate infrared emission at 10,600 nm with minimal collateral thermal spread. Demand clusters in United States ENT suites and German gynecology wards where shallow penetration profiles reduce adjacent tissue damage during vocal cord and cervical procedures.
- Nd:YAG Laser:Neodymium-doped yttrium aluminum garnet crystals produce 1,064 nm wavelengths with deep tissue penetration capabilities. Neurosurgery departments in Japanese university hospitals and Indian metropolitan medical centers are expanding installed bases for coagulation and tumor ablation applications.
- Erbium Laser:Er:YAG variants emit at 2,940 nm with high water absorption coefficients suited for precise hard tissue ablation. Dental practices across Italy and Spain favor these platforms for cavity preparation and bone sculpting.
- Diode Laser:Compact semiconductor arrays at 800-980 nm wavelengths enable portable, lower-cost alternatives to legacy systems. Brazilian and Mexican aesthetic clinics are adopting these units at accelerated replacement cycles.
- Alexandrite Laser:Chromium-doped chrysoberyl crystals deliver 755 nm pulses optimized for melanin targeting in dermatological applications.
- Dye Laser:Organic dye solutions enable tunable wavelength output across 400-700 nm ranges for specialized vascular lesion treatments.
The dominant share belongs to CO2 and Nd:YAG platforms, while diode systems are gaining share fastest through ambulatory penetration.
Application:
Procedure volumes concentrate in outpatient settings where reimbursement clarity determines technology refresh rates and capital allocation priorities.
- Dermatology:Aesthetic and medical skin procedures utilize fractional and full-field ablative modalities for lesion removal and resurfacing. Private clinics in São Paulo and Seoul are driving replacement demand for multi-wavelength platforms that consolidate treatment capabilities.
- Ophthalmology:Corneal sculpting and retinal photocoagulation require sub-micron precision with real-time tracking systems. United States ASC networks are expanding femtosecond and excimer laser volumes as CMS procedure codes mature for refractive corrections.
- ENT Procedures:Tonsillectomy, stapedectomy, and laryngeal surgery employ CO2 and KTP wavelengths for hemostatic cutting. United Kingdom NHS trusts are consolidating vendor relationships through single-source agreements covering capital equipment and disposables.
- Dentistry:Hard and soft tissue oral surgery leverages erbium and diode wavelengths for caries removal and periodontal therapy.
- Gynecology:Laser hysteroscopy and laparoscopy procedures target fibroids and endometrial pathologies with controlled thermal profiles.
- Neurosurgery:Brain and spinal tumor resections integrate Nd:YAG and CO2 systems with navigation platforms for margin control.
Dermatology and ophthalmology command the largest revenue pools, though ENT applications are expanding most quickly through ambulatory migration.
End User:
Procurement authority is fragmenting as hospital networks lose volume to independent specialty operators with faster capital deployment cycles.
- Specialty Clinics:Focused dermatology and ophthalmology practices prioritize multi-modality platforms with rapid ROI profiles. Clinics in Dubai and Singapore are investing in premium solid-state systems to differentiate against hospital competitors.
- Ambulatory Surgical Centers:United States ASCs in Texas and Florida are capturing ophthalmology and pain management volumes through dedicated laser suites and bundled service contracts.
- Academic Research Facilities:University medical centers in Switzerland and Sweden maintain experimental free-electron and dye laser programs for translational studies.
- Dental Offices:Solo and group practices favor compact erbium and diode units with minimal footprint requirements.
- Eye Care Centers:Refractive surgery chains in Australia and Canada are standardizing on excimer and femtosecond platforms across multi-site networks.
- Cosmetic Surgery Clinics:Med-spa operators in Thailand and Turkey leverage diode and alexandrite systems for hair removal and vascular treatments.
ASCs and specialty clinics together account for the dominant procurement volume, with cosmetic surgery clinics climbing the fastest as medical tourism infrastructure scales.
Technology:
Platform economics diverge sharply between capital-intensive resonator fabrication and outsourced component assembly models.
- Solid-State:Crystalline gain media in Nd:YAG, Er:YAG, and alexandrite configurations deliver high peak powers with thermal stability. Manufacturers with captive crystal growth capabilities in Israel and Germany command pricing premiums through supply security.
- Gas:CO2 and excimer discharge tubes require precision optical cavity engineering and gas handling infrastructure. Legacy installed bases in United States and Japanese hospitals create replacement demand as EU MDR compliance deadlines approach.
- Semiconductor:Diode bar and VCSEL architectures enable compact, air-cooled designs with reduced maintenance burdens. Chinese and South Korean foundries are expanding wafer capacity for medical-grade emitters.
- Fiber:Doped silica waveguides integrate directly with endoscopic delivery systems for flexible tissue access.
- Dye:Liquid gain media permit wavelength tuning for specialized vascular and pigmented lesion applications.
- Free Electron:Synchrotron-derived radiation supports experimental intraoperative radiation therapy protocols at select research institutions.
Solid-state and gas technologies retain the dominant revenue position, while semiconductor platforms are expanding most quickly through dermatology and dental market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across geographies. United States buyers prioritize reimbursement clarity over unit cost, while emerging markets in Southeast Asia and Latin America exhibit acute price sensitivity that favors diode platforms over solid-state systems.
United States
CMS reimbursement maturation for laser-assisted ophthalmology and dermatology procedures drives ambulatory surgical center expansion in Texas and Florida. FDA 510(k) clearance pathways shape product development timelines for manufacturers seeking market access. Dallas-Fort Worth and Miami metropolitan clusters concentrate purchasing power among integrated delivery networks bundling capital equipment with service contracts.
Germany
University hospital procurement committees in Bavaria and North Rhine-Westphalia maintain preference for premium solid-state platforms with EU MDR compliance certification. The EU Medical Device Regulation's tightened pre-market clinical evidence requirements accelerate replacement cycles for legacy gas laser systems. Stuttgart and Munich industrial corridors host precision optics fabricators supplying resonator components to domestic OEMs.
Japan
Neurosurgery departments in Tokyo and Osaka metropolitan medical centers expand Nd:YAG installed bases for tumor ablation applications. METI industrial policy supports domestic photonics supply chain security through targeted R&D subsidies. Yokohama and Nagoya manufacturing clusters produce crystalline gain media for captive use by integrated laser manufacturers.
Brazil
Aesthetic clinics in São Paulo and Rio de Janeiro adopt diode laser systems at twice the replacement rate of hospital systems, driven by private-pay dermatology demand. ANVISA regulatory pathways for Class III medical devices extend approval timelines for novel wavelength platforms. The São Paulo state medical device distribution hub channels imported equipment to southeastern private clinic networks.
India
Metropolitan medical centers in Maharashtra and Karnataka expand laser surgery volumes as private health insurance penetration deepens. The PLI scheme for medical device manufacturing offers duty and tax incentives for domestic laser assembly operations. Hyderabad and Bengaluru technology corridors attract contract manufacturing investments from multinational OEMs seeking cost-competitive production bases.
Global Surgical Lasers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Integrated manufacturers with captive crystal growth and fiber fabrication capabilities command premium positioning through supply security, while component assemblers compete on price through outsourced supply chains. The market organizes around three strategic archetypes: vertically integrated photonics specialists, geographic expansion-focused platform marketers, and captive suppliers serving OEM partnerships. Dominant competitive moves include backward integration into diode and fiber laser supply chains, plus aggressive geographic expansion into ambulatory settings across Latin America and Southeast Asia.
Among Israel-based integrated manufacturers, Lumenis Be Ltd and Alma Lasers occupy distinct positioning vectors. Lumenis exemplifies the captive fabrication archetype through in-house fiber and solid-state production, while Alma Lasers represents geographic expansion-focused competition targeting ambulatory penetration in emerging markets. IPG Photonics Corporation anchors the captive supplier tier, providing diode and fiber laser components that lower unit costs for downstream OEM partners. These three companies collectively illustrate the competitive tension between integrated technology control and distributed cost optimization across the surgical lasers sector.
| Leading Market Players |
|---|
| Lumenis Be Ltd |
| Cynosure |
| Alma Lasers |
| Candela Corporation |
| IPG Photonics Corporation |
| KLS Martin Group |
| Fotona |
| BIOLASE, Inc. |
| El.En. |
| Others |
Supply & Pricing Matrix
Multi-year service bundling agreements lock in diode and fiber laser supply access while flattening procurement cost visibility for ambulatory surgical centers negotiating against integrated manufacturers. These contracts tether pricing to ISO 13485 audit cycles and EU MDR compliance milestones, embedding regulatory risk into lifetime value calculations across United States and German hospital networks.
Pricing Analysis
After-sales service contracts and consumable disposables drive lifetime value beyond initial hardware placement, with three-tier pricing structure across premium, standard, and economy levels separating integrated manufacturers from component assemblers. Premium tiers command positioning through captive crystal growth and FDA 510(k) predicate lineage, while diode-based economy tiers face cost compression from Chinese wafer foundry expansion. Price differentiation hinges on EU MDR certification status and geographic service density. Ambulatory surgical centers in Texas and Florida exhibit highest price sensitivity, whereas Japanese university hospitals prioritize supply security over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for crystalline gain media sourced from Yokohama manufacturing clusters. German and Israeli facilities anchor solid-state resonator fabrication, drawing from rare-earth mineral concentrates processed in Chinese separation facilities. Japanese and South Korean foundries supply medical-grade diode arrays, creating single-source vulnerability for OEM partners lacking backward integration. Distribution runs through São Paulo and Dubai medical device hubs serving private clinic networks across Latin America and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crystalline gain media fabrication expertise and EU MDR notified body relationships constitute scarce capabilities that constrain competitive entry, with fewer than twelve qualified suppliers globally capable of medical-grade Nd:YAG crystal production.
For Market Incumbents: Secure captive diode supply through long-term offtake agreements with Japanese or South Korean foundries before capacity allocation tightens. Deepen clinical specialist training infrastructure to defend against ambulatory center procurement committees consolidating vendor relationships through single-source agreements. Reinforce ISO 13485 multi-site recertification capabilities to accelerate product line extensions ahead of EU MDR Article 10 surveillance deadline compression. For New Entrants and Emerging Players: FDA 510(k) predicate pathway acceleration offers fastest market access for solid-state platforms targeting underpenetrated neurosurgery applications in Indian metropolitan medical centers. White-space concentration exists in compact erbium systems for dental group practices in Italy and Spain seeking footprint-minimal alternatives. Photonics-AI convergence for real-time tissue feedback represents unclaimed differentiation vector in oncology resection suites. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with captive fiber fabrication and established notified body relationships across the analysis window. Acquisition targets should demonstrate EU MDR technical documentation completion and installed base concentration in United States ASC networks. Watch for IPG Photonics Corporation capacity expansion signals as inflection indicator for downstream OEM pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | Notified body certification unlocks German and French hospital procurement committees previously blocked to legacy devices. |
| Captive Diode Array Fabrication | In-house wafer production at IPG Photonics lowers unit costs for OEM partners competing on diode platform economics. |
| Photonics-AI Convergence Development | Spectral analysis integration with laser delivery enables precision improvements in oncology resections at Swiss university hospitals. |
| Southeast Asia Distribution Partnership | Alma Lasers' Vietnam and Indonesia clinic networks demonstrate latent demand for portable diode platforms in private settings. |
| Clinical Specialist Certification Program | AORN-aligned training infrastructure addresses scarcity constraining ambulatory network expansion across United States ASCs. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and ambulatory surgical center administrators and refined through secondary validation against FDA 510(k) clearance databases, EU MDR notified body technical documentation, CMS procedure code reimbursement filings, and ISO 13485 audit registries. Bottom-up procedure volume estimates across ophthalmology, dermatology, and ENT applications were triangulated with top-down capital equipment shipment data from German and Japanese industrial clusters.
Variance decomposition across wavelength platform, application specialty, and end-user setting dimensions shaped analytical framework development over the projection horizon. CAGRs were derived from installed base replacement cycles, reimbursement pathway maturation trajectories, and ambulatory center expansion rates. Modeled inputs included EU MDR compliance deadline acceleration effects, diode supply concentration at qualified foundries, and CMS procedure code coverage decisions for laser-assisted interventions.
Underlying assumptions cover reimbursement stability in United States outpatient settings, EU MDR notified body capacity availability, and rare-earth mineral supply continuity from Chinese separation facilities, with deviation risk concentrated in FDA 510(k) predicate device disputes and substantive review backlogs extending product development timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Surgical Stents Market
Surgical Instruments
Handheld Arthroscopic Instruments Market
Surgical Instruments
Electrocautery Enhanced Delivery System Market
Surgical Instruments
Surgical Clips Market
Surgical Instruments
Surgical Broaches Market
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Huber Needles Market
Surgical Instruments
Global Arthroscopy Instruments Market
Surgical Instruments
Disposable Ophthalmic Surgical Products Market
Surgical Instruments
United States Minimally Invasive Surgery Market
Surgical Instruments
Hydrosurgery Systems Market
Surgical Instruments
US Surgical Sutures Market
Surgical Instruments
Surgical Pliers Market
Surgical Instruments
Global Powered Surgical Instruments Market
Surgical Instruments
Spain General Surgical Devices Market