
 United States Face Mask Market | 2026-2036
United States Face Mask Market Size, Share, and Industry Trends Forecast 2026-2036
United States Face Mask Market Analytics
Buyer concentration among hospital systems is restructuring procurement patterns across the United States face mask landscape. 3M Company leverages its NIOSH-certified manufacturing infrastructure to sustain dominant positioning in industrial respirators. Kimberly-Clark Corporation anchors healthcare channel relationships through private-label and branded surgical mask portfolios. Honeywell International Inc. competes on dual-use technology migration from aerospace filtration into medical-grade respiratory protection.
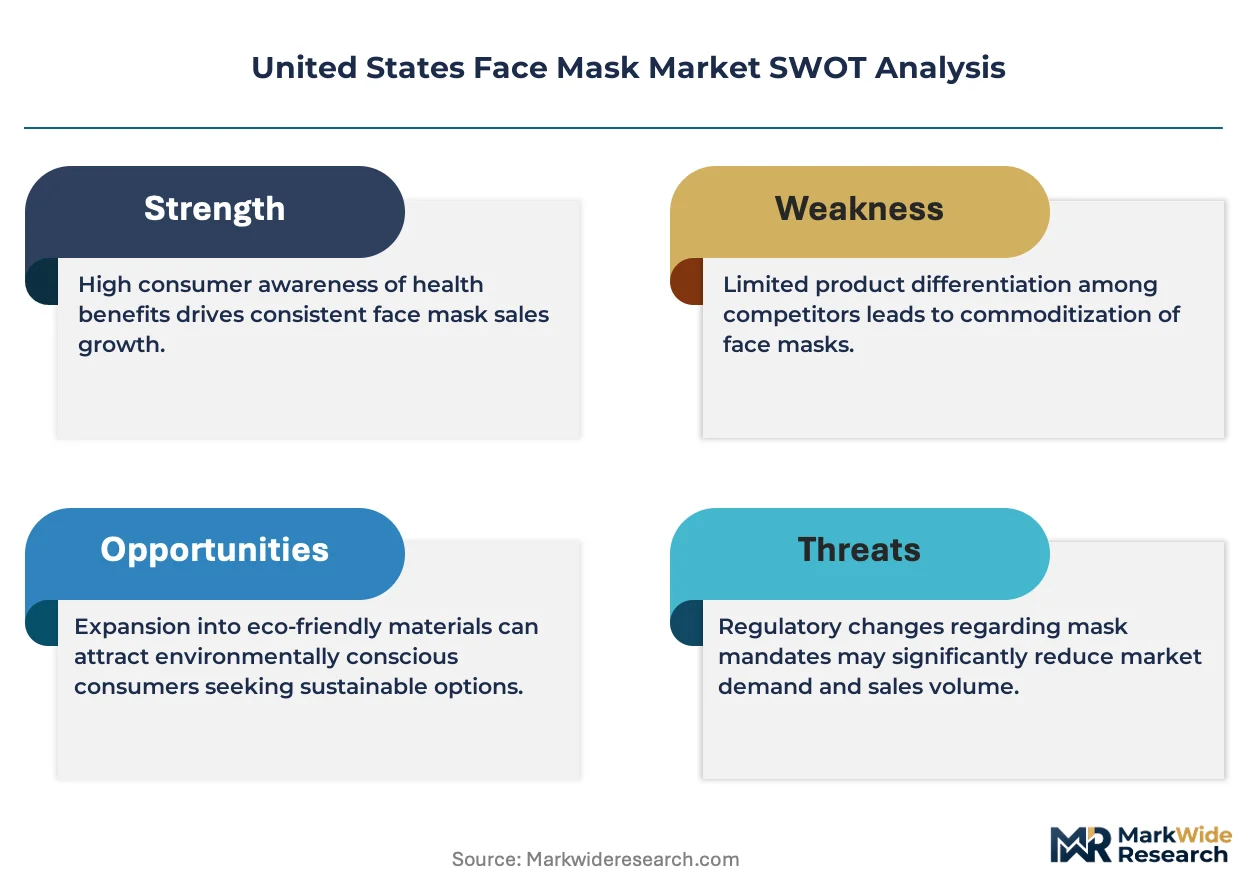
Face masks in the United States encompass disposable and reusable barrier devices engineered from melt-blown polypropylene layers with bacterial filtration efficiency ratings typically exceeding 95 percent, designed to reduce airborne pathogen transmission in clinical, occupational, and public settings. The N95 respirator segment commands premium positioning due to NIOSH compliance burdens and limited domestic melt-blown capacity, while cloth masks face margin compression from commoditized cotton sourcing and waning institutional demand. Industrial application channels retain structural importance as OSHA respiratory protection standards mandate fit-tested protection across manufacturing, construction, and chemical processing workplaces.
FDA oversight of surgical masks as Class II medical devices and NIOSH certification under 42 CFR Part 84 create dual regulatory gateways that constrain market entry for offshore manufacturers lacking United States-based testing relationships. The EPA occasionally intervenes on antimicrobial claims attached to treated mask surfaces, adding another compliance vector for material innovators. Stakeholders must monitor evolving CDC guidance on respiratory protection tiers and preemptive capacity investments in domestic melt-blown polypropylene production.
Market Dynamics
Hospital procurement consolidation across integrated delivery networks is compressing supplier margins and favoring manufacturers with NIOSH-certified domestic production capacity. This buyer-side concentration is restructuring competitive positioning toward scale and compliance depth.
Growth Catalysts
- NIOSH 42 CFR Part 84 enforcement:Certification requirements filter non-compliant imports, creating protected market space for domestic manufacturers with established testing relationships.
- California healthcare corridor demand:Concentrated hospital procurement from San Francisco to Los Angeles sustains volume commitments for surgical mask suppliers.
- OSHA respiratory protection mandates:Fit-testing requirements across manufacturing and chemical processing workplaces lock in recurring industrial respirator demand.
Market Restraints
- Domestic melt-blown polypropylene scarcity:Limited United States-based spunbond capacity constrains N95 respirator production expansion regardless of demand signals.
- FDA Class II device pathway:Surgical mask clearance timelines and quality system requirements create multi-year barriers for new market entrants.
- Commoditized cotton sourcing:Cloth mask margins face compression from undifferentiated textile supply and declining institutional procurement.
Strategic Opportunities
- Antimicrobial surface treatments:EPA-registered claims differentiation offers premium positioning for material innovators beyond basic filtration.
- Integrated delivery network direct contracting:Bypassing distributor markups through hospital system private-label partnerships captures margin from consolidated procurement.
- Aerospace filtration technology migration:Dual-use respiratory protection leveraging Honeywell's aerospace expertise opens industrial-medical crossover segments.
Industry Challenges
- NIOSH certification queue management:Testing backlog delays product launches and strains working capital for manufacturers scaling capacity.
- Fit-testing infrastructure scaling:OSHA-mandated respirator protection programs require trained personnel that industrial distributors struggle to field.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Face Mask Market |
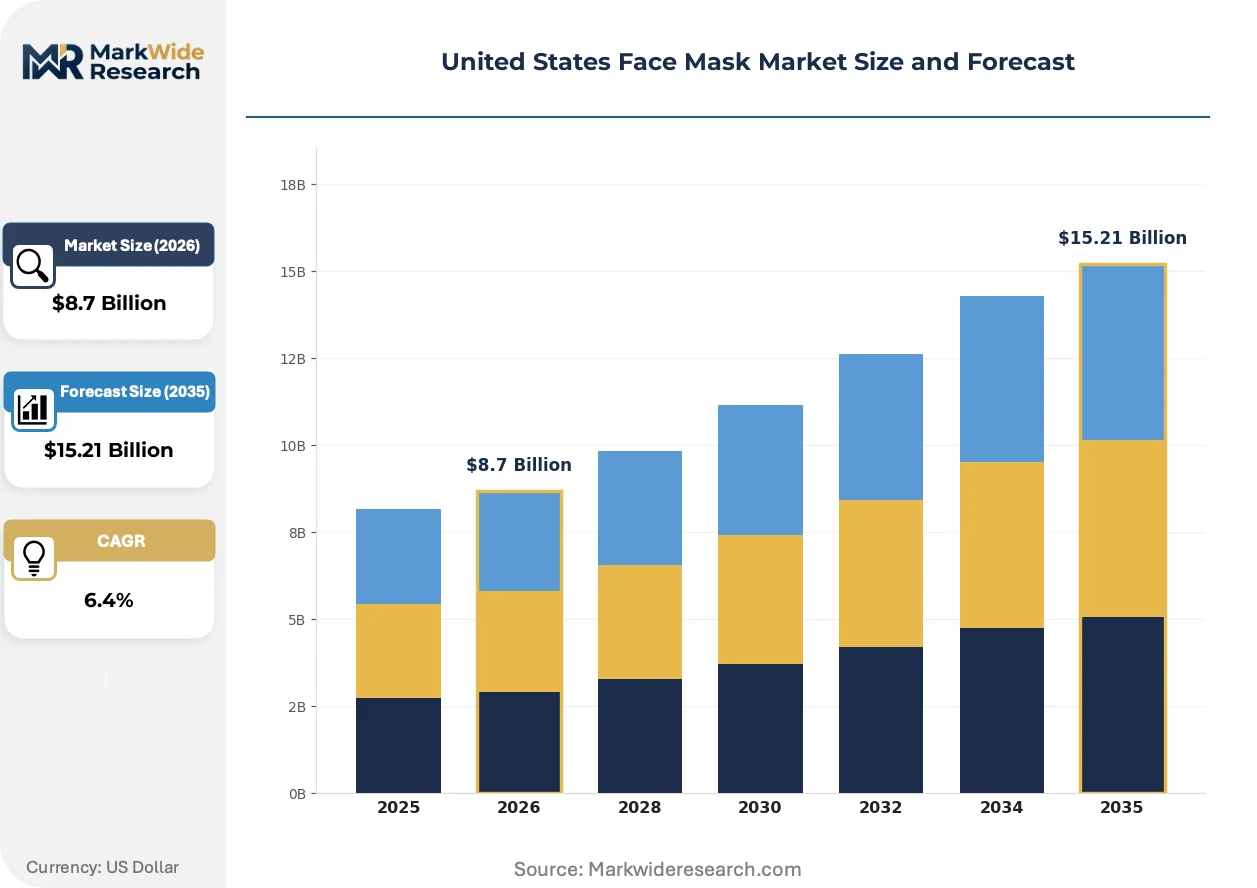
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Masks, N95 Respirators, Cloth Masks, KN95 Masks End User: Hospitals, Clinics, Individuals, Corporations Material: Polypropylene, Cotton, Non-woven Fabric, Polyester Application: Healthcare, General Public Use, Industrial, Travel |
| Companies Covered | 3M Company, Kimberly-Clark Corporation, Honeywell International Inc., Moldex-Metric, Procter & Gamble Company, L'Oréal SA, The Estée Lauder Companies Inc., Unilever Plc, Kenvue Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Face Mask Market Evolving Landscape
Active filtration materials and domestic supply chain reconfiguration are reshaping product architecture and sourcing strategy across United States face mask manufacturing. These shifts favor integrated producers with captive melt-blown capacity.
Electrostatic melt-blown polypropylene is consolidating market share in medical-grade respirators by delivering sub-micron particle capture without the breathing resistance of denser mechanical media. Hospital systems in the Northeast and Midwest are specifying charged fiber construction in N95 tenders. This material transition is compressing demand for standard mechanical filtration layers and rewarding suppliers with in-house electrostatic charging lines.
EPA scrutiny of antimicrobial additive claims is tightening substantiation requirements for treated mask surfaces under Federal Insecticide, Fungicide, and Rodenticide Act provisions. Manufacturers must now generate efficacy data against specific pathogen panels rather than relying on generic metal-ion marketing. Surgical mask innovators with registered copper or silver treatments are gaining shelf space in infection control procurement while untreated competitors face delisting risk.
Hospital system consortium purchasing is displacing independent distributor relationships as integrated delivery networks centralize respiratory protection contracts under single-source agreements. Group purchasing organizations are extracting price concessions in exchange for multi-year volume commitments. This consolidation is most visible in Texas and Florida health systems, where Catholic and for-profit chains have unified procurement under shared services organizations.
United States Face Mask Market Segmentation
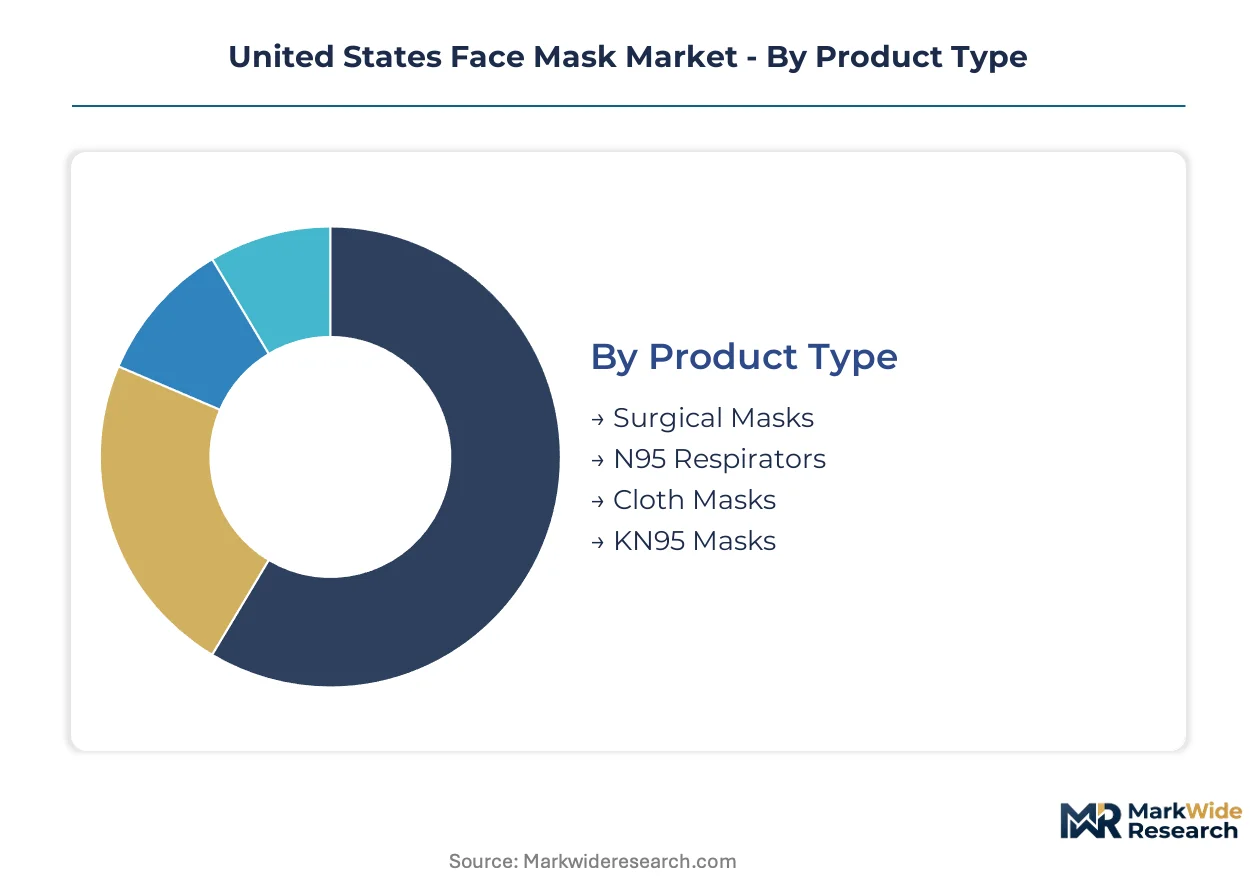
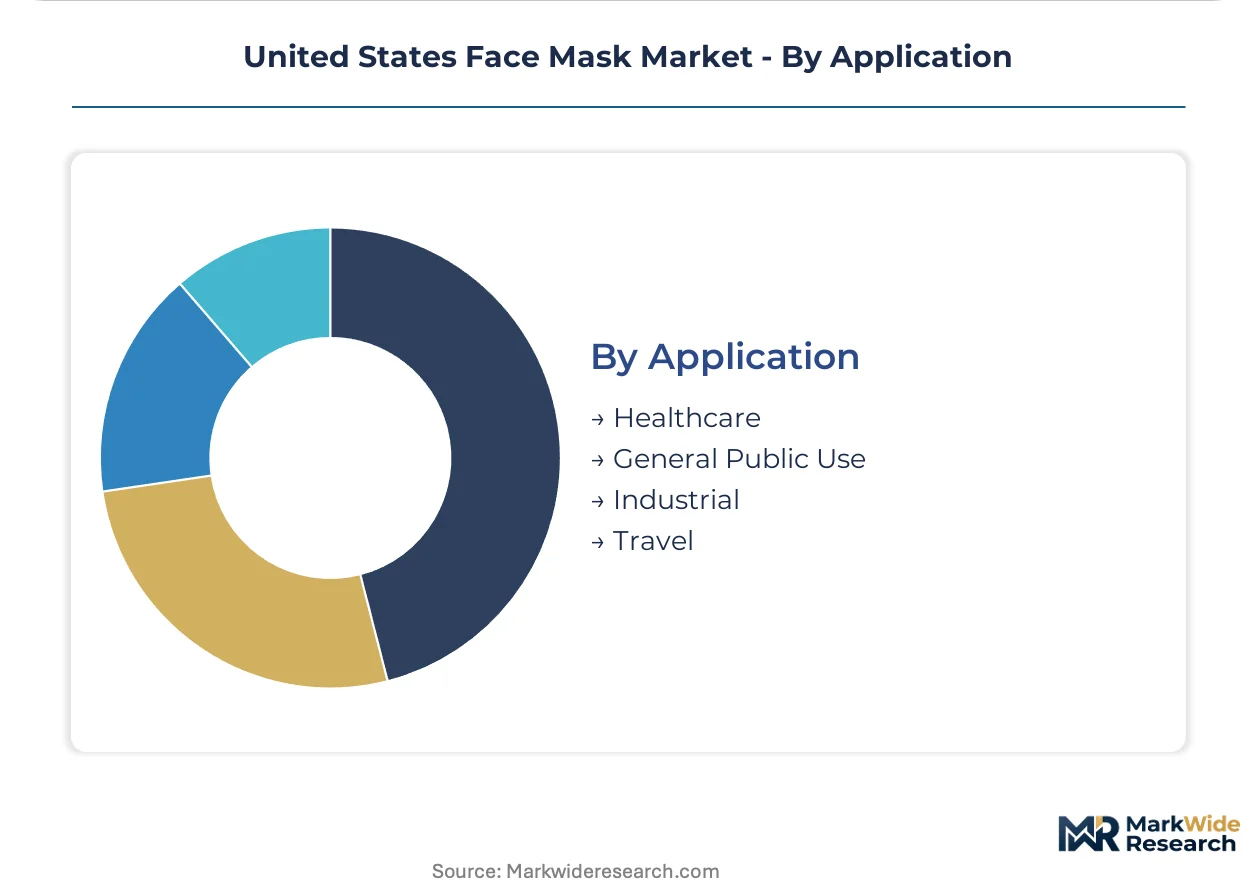
Segmentation in the United States face mask market reveals how regulatory certification, material sourcing, and procurement channel concentration create divergent margin profiles across product tiers. Understanding these divides enables manufacturers to align capacity investments with structurally advantaged segments.
Product Type:
Standalone respiratory protection dominates hospital procurement, while embedded filtration systems serve industrial OEM channels with different margin dynamics.
- Surgical Masks:Three-ply melt-blown polypropylene barriers with bacterial filtration efficiency ratings above 95 percent serve routine clinical procedures. California's healthcare corridor from San Francisco to Los Angeles sustains the heaviest volume commitments as integrated delivery networks consolidate purchasing.
- N95 Respirators:NIOSH-certified under 42 CFR Part 84, these electrostatically charged respirators capture sub-micron particles through mechanical and electrostatic filtration. Domestic melt-blown capacity scarcity constrains production expansion regardless of demand signals from hospital systems.
- Cloth Masks:Cotton and blended fabric barriers without standardized filtration certification serve residual consumer demand and institutional uniform programs.
- KN95 Masks:Chinese-manufactured respirators meeting GB 2626 standards face FDA enforcement variability and customs scrutiny at U.S. ports.
Volume placements concentrate in surgical masks; the faster expansion belongs to N95 respirators as hospital systems upgrade respiratory protection tiers.
End User:
Customer type determines pricing power, with institutional buyers extracting concessions through multi-year contracts while individual purchasers absorb retail markups.
- Hospitals:Integrated delivery networks centralize procurement across multi-hospital systems, demanding NIOSH-certified supply chains and documented quality systems. OSHA respiratory protection mandates lock in recurring fit-testing programs alongside product purchases.
- Clinics:Outpatient facilities source surgical masks through distributor relationships with less volume leverage than hospital consortiums.
- Individuals:Consumer channel demand has compressed toward commodity cloth masks as pandemic-era stockpiling behavior normalized.
- Corporations:Industrial employers maintain OSHA-mandated respiratory protection programs across manufacturing, construction, and chemical processing workplaces.
Procurement gravity centers on hospital systems; corporate industrial programs deliver the most stable recurring revenue streams.
Material:
Supply chain control over raw inputs separates integrated producers from converters dependent on spot market sourcing.
- Polypropylene:Melt-blown and spunbond non-woven grades constitute the technical core of medical-grade filtration media. Limited domestic electrostatic charging capacity constrains N95 expansion regardless of resin availability.
- Cotton:Commoditized textile sourcing from domestic and international gin operations serves cloth mask production with minimal barrier to entry.
- Non-woven Fabric:Spunlace and needle-punch constructions serve lower-filtration applications where breathability outweighs particle capture requirements.
- Polyester:Synthetic fiber blends offer durability for reusable mask platforms targeting industrial and travel applications.
Margin capture concentrates in polypropylene; polyester applications are climbing the fastest as reusable industrial platforms gain specification.
Application:
Use environment dictates certification burden and replacement frequency, with healthcare settings demanding the highest compliance investment.
- Healthcare:FDA Class II device classification and CDC guidance tiers create multi-layered procurement specifications. Hospital infection control committees validate supplier quality systems before contract award.
- General Public Use:Unregulated consumer demand has normalized toward fashion-oriented and comfort-driven purchasing with minimal technical specification.
- Industrial:OSHA 29 CFR 1910.134 mandates fit-tested respiratory protection across manufacturing and chemical processing, sustaining qualified distributor relationships.
- Travel:Aviation and hospitality sector procurement has consolidated toward disposable surgical masks for crew and passenger distribution.
Revenue concentration sits with healthcare applications; industrial channels are gaining share fastest as manufacturing reshoring intensifies respiratory protection compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consolidation across integrated delivery networks concentrates demand in specific metropolitan corridors, with California's healthcare infrastructure anchoring the heaviest volume commitments for surgical mask suppliers.
California
The San Francisco-to-Los Angeles healthcare corridor sustains the nation's densest concentration of hospital system procurement, with Kaiser Permanente and Sutter Health centralizing respiratory protection contracts under single-source agreements. California's Division of Occupational Safety and Health (Cal/OSHA) enforces respiratory protection standards exceeding federal OSHA baselines, mandating fit-testing documentation for industrial employers across the Central Valley manufacturing belt. Los Angeles County's garment manufacturing infrastructure has partially converted to melt-blown polypropylene production, though electrostatic charging capacity remains constrained.
Texas
The Dallas-Fort Worth and Houston metropolitan areas host expanding hospital networks consolidating procurement through Catholic health system shared services organizations. Texas does not operate a state-plan OSHA program, deferring to federal enforcement of 29 CFR 1910.134 respiratory protection mandates across the Gulf Coast petrochemical corridor. Houston's medical center complex generates sustained surgical mask demand from outpatient surgery centers and research institutions.
New York
The New York metropolitan area's hospital systems maintain strategic stockpiles of N95 respirators following pandemic-era supply disruptions, with Northwell Health and NYU Langone anchoring procurement volume. New York State Department of Health regulations require healthcare facilities to maintain minimum inventory levels of personal protective equipment, creating predictable replacement demand. Buffalo's polymer research corridor supports limited domestic melt-blown development initiatives.
Illinois
Chicago's integrated delivery networks, including Advocate Aurora and Northwestern Medicine, centralize procurement for surgical masks across the upper Midwest. Illinois operates a state-plan OSHA program with respiratory protection enforcement parity to federal standards across the Rockford manufacturing belt. The city's logistics infrastructure positions distributors to serve secondary markets throughout the Great Lakes region.
Florida
Florida's hospital consolidation accelerates through for-profit chain shared services organizations, with HCA and Tenet facilities unifying respiratory protection procurement across the peninsula. The state defers to federal OSHA enforcement without state-plan modifications, maintaining standard respiratory protection requirements for construction and hospitality sector employers. Miami's import logistics infrastructure processes residual KN95 shipments facing FDA enforcement variability at U.S. ports.
United States Face Mask Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue antimicrobial differentiation and direct hospital contracting. The market structure concentrates around manufacturers with NIOSH-certified domestic production capacity, with three to four entities capturing disproportionate share in hospital procurement channels. Strategic archetypes include diversified conglomerates with aerospace-to-medical technology migration, hygiene-focused consumer goods multinationals, and specialized respiratory protection fabricators. Competitive moves center on capacity expansion in domestic melt-blown polypropylene and private-label partnerships with consolidated hospital systems.
Among diversified industrial conglomerates, 3M Company and Honeywell International Inc. represent the technology-migration archetype, leveraging established NIOSH certification relationships and cross-sector filtration expertise. Kimberly-Clark Corporation exemplifies the hygiene-specialist position, anchoring healthcare channel relationships through surgical mask portfolios. Moldex-Metric occupies the dedicated respiratory protection fabricator tier, focusing exclusively on industrial and medical-grade respirators without consumer diversification.
| Leading Market Players |
|---|
| 3M Company |
| Kimberly-Clark Corporation |
| Honeywell International Inc. |
| Moldex-Metric |
| Procter & Gamble Company |
| L'Oréal SA |
| The Estée Lauder Companies Inc. |
| Unilever Plc |
| Kenvue Inc. |
| Others |
Value Network & Pricing Analysis
NIOSH-certified N95 respirators and commodity surgical masks occupy divergent pricing strata, with the certification gap translating into three-to-five-fold unit cost differentials and captive melt-blown supply chains for premium tiers versus spot-market polypropylene sourcing for standard barriers. Hospital procurement consolidation extracts volume discounts from surgical mask suppliers while N95 manufacturers defend pricing power through domestic electrostatic charging capacity scarcity.
Pricing Analysis
Volume placements in surgical masks generate thin margins at high throughput, while N95 respirators retain pricing power through NIOSH certification scarcity and limited domestic melt-blown capacity. Price differentiation hinges on bacterial filtration efficiency certification tiers and fit-testing service bundling. Cost compression in cloth masks is intensifying because undifferentiated cotton sourcing eliminates technical moats. Individual consumers exhibit the highest price sensitivity, while hospital integrated delivery networks leverage multi-year contracts for concession extraction.
Supply Chain Analysis
Direct-to-hospital channels handle integrated delivery network procurement, with distributor relationships serving smaller clinics and industrial employers. Raw material sourcing draws from domestic melt-blown polypropylene producers, imported spunbond non-wovens, and commodity cotton gin operations. Supply chain risk centers on single-source vulnerability in electrostatic charging equipment, where German and Japanese machinery suppliers dominate. Distribution runs through medical-surgical distributors, industrial safety suppliers, and residual retail pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA Class II device pathways and NIOSH 42 CFR Part 84 certification create barrier-to-entry moats rewarding established domestic manufacturers with testing relationships and quality systems already validated.
For Market Incumbents: Cement NIOSH certification queue positions through expanded domestic melt-blown capacity additions in Texas and Ohio, defending against emerging entrants with antimicrobial surface treatments. Prioritize backward integration into electrostatic charging equipment to reduce German machinery dependency. Lock in multi-year private-label contracts with Catholic and for-profit hospital chains before procurement consolidation peaks. For New Entrants and Emerging Players: Outpatient surgery centers represent the most penetrable buyer archetype, as these facilities lack hospital system volume leverage and source through distributor relationships with less stringent quality system documentation. Target industrial employers in reshoring manufacturing corridors with dual-use respirators bridging medical and occupational applications. Lead with EPA-registered antimicrobial claims to differentiate from commoditized surgical mask suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with domestic melt-blown specialists given NIOSH certification backlog and hospital procurement mandates for United States-based supply chains. Long-term viability favors producers with captive electrostatic charging capacity and established FDA quality systems. Monitor NIOSH testing queue clearance rates as the inflection indicator for capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| NIOSH Certification Investment | 42 CFR Part 84 compliance unlocks hospital procurement channels and industrial respirator specifications. |
| Domestic Melt-Blown Capacity Expansion | Captive polypropylene supply insulates against import scrutiny and raw material scarcity. |
| Antimicrobial Surface Treatment Registration | EPA-registered claims differentiate premium tiers from undifferentiated surgical mask competition. |
| Hospital System Direct Contracting | Private-label partnerships bypass distributor markups and capture margin from consolidated procurement. |
| Aerospace Filtration Technology Migration | Honeywell's dual-use respiratory platforms open industrial-medical crossover segments with premium positioning. |
Research Methodology
Independent corroboration across hospital procurement executives, industrial safety distributors, and NIOSH certification consultants underwrites the qualitative findings in this analysis. Primary interviews with biomedical engineers, GPO contracts managers, and melt-blown production facility operators combined with secondary validation from FDA 510(k) filings, OSHA enforcement data, and hospital supply chain databases. Bottom-up demand modeling from end-user segments triangulates against top-down market sizing from trade flow analysis.
Comparable-period anchoring to pandemic-era demand spikes and subsequent normalization patterns structured the forecast window across the projection horizon. Segmentation dimensions modeled include product type, end-user category, material composition, and application environment. CAGRs were derived from regression analysis of historical procurement volume trends and hospital capital expenditure cycles. Industry-specific inputs incorporated NIOSH certification queue dynamics and integrated delivery network consolidation trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CDC guidance revisions, OSHA enforcement intensity, and domestic melt-blown capacity buildout timing. Periodic stress-testing of base assumptions is recommended given regulatory pathway variability and hospital procurement centralization momentum.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Asia-Pacific Ostomy Drainage Bags Market
Medical Supplies
Cryotubes Market
Medical Supplies
Catgut Sutures Market
Medical Supplies
Anti Venom Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
Specimen Retrieval Bags Market
Medical Supplies
Global Disposable Blood Bags Market
Medical Supplies
Surgical Gloves Market
Medical Supplies
Global Dried Blood Spot Collection Cards Market
Medical Supplies
Colon Decompression Kits Market
Medical Supplies
Venipuncture Needles and Syringes Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
Global Hospital Supplies Market
Medical Supplies
North America Surgical Glue Market
Medical Supplies
Safety Pen Needles Market
Medical Supplies
Global Lancet and Pen Needles Market