
 Surgical Equipment Market | 2026-2036
Surgical Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Equipment Market Intelligence
The divergence between integrated robotic platforms and single-use commodity instruments is repositioning the surgical equipment value chain. High-end systems require significant R&D investment and direct sales channels, creating a high-margin, specialized tier. Intuitive Surgical dominates the robotic-assisted surgery space with its integrated hardware and software ecosystem. In contrast, companies like B. Braun Melsungen AG compete across a broader portfolio, including traditional surgical instruments and electrosurgical devices.
Surgical equipment encompasses a range of devices, from handheld instruments to complex robotic systems, designed for performing operative procedures. These products are often manufactured from medical-grade materials like 316L stainless steel or biocompatible polymers to ensure sterility and durability. The primary purpose is to enable precise tissue manipulation, incision, and closure during surgery. While traditional surgical instruments maintain the largest volume, the robotic surgery technology segment is expanding rapidly, driven by demand for minimally invasive procedures in hospitals and specialty centers.
Market access is governed by stringent regulatory frameworks enforced by bodies such as the US Food and Drug Administration (FDA) and the European Union's Medical Device Regulation (MDR). In China, the National Medical Products Administration (NMPA) oversees approvals, creating distinct compliance pathways for market entry. These regulations mandate rigorous clinical data and quality management systems. Stakeholders must decide whether to focus on developing advanced digital surgery platforms or on optimizing manufacturing for high-volume, cost-sensitive product lines.
Market Dynamics
The central structural force shaping the surgical equipment market is the bifurcation between capital-intensive robotic systems and high-volume, single-use instruments. This divergence pressures manufacturers to commit to either high-margin, specialized digital ecosystems or cost-optimized, broad-portfolio commodity production.
Growth Catalysts
- Healthcare Infrastructure Expansion:Significant government-led investment in new hospital construction and healthcare modernization, particularly in China, creates sustained demand for a full spectrum of surgical equipment.
- Shift to Outpatient Settings:The expansion of Ambulatory Surgical Centers (ASCs) generates new demand for equipment specifically designed for efficiency, smaller footprints, and faster turnaround in outpatient procedures.
- Global Demographic Aging:An aging worldwide population is increasing the prevalence of chronic conditions that require surgical intervention, such as orthopedic and cardiovascular procedures, sustaining baseline volume growth.
Market Restraints
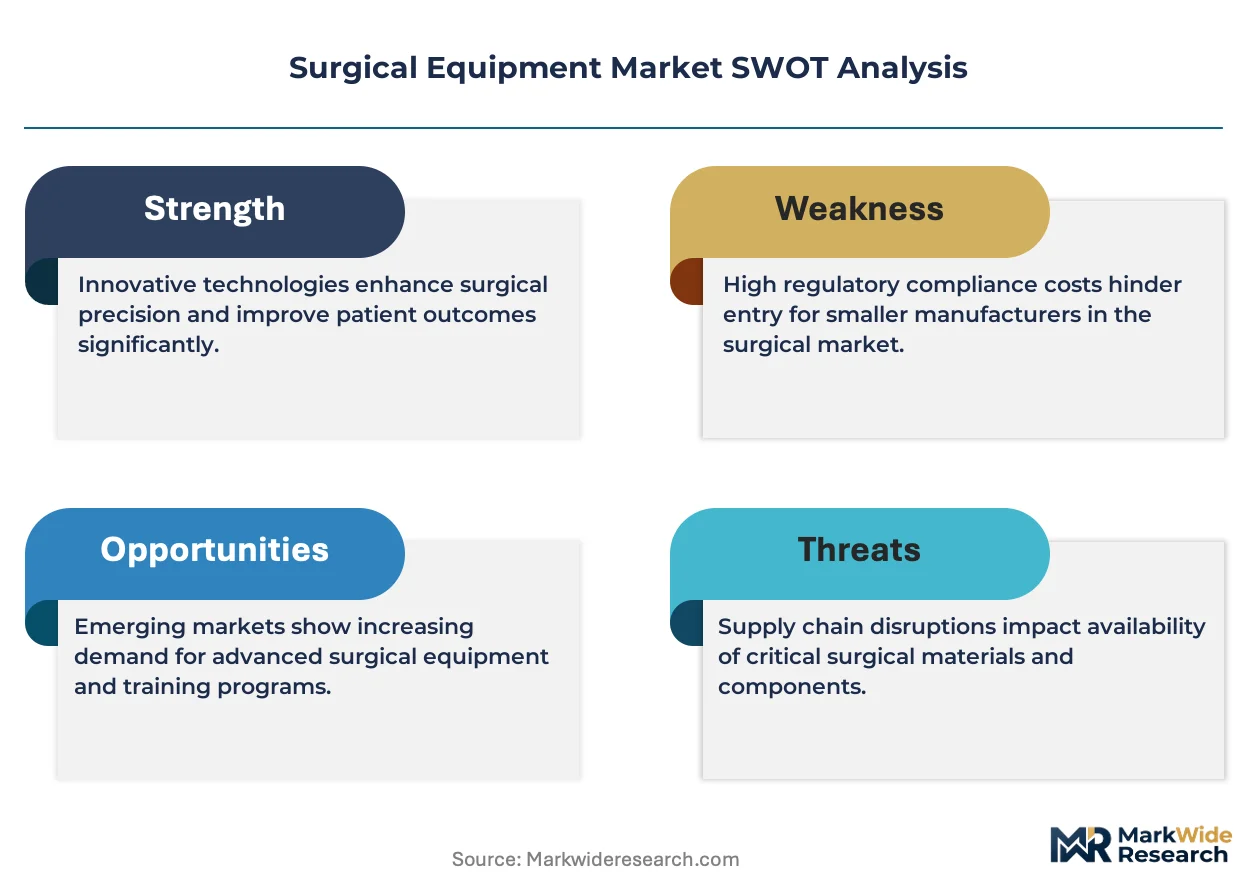
- High Development and Trial Costs:The significant capital investment required for research, development, and extensive clinical trials for innovative robotic platforms acts as a major barrier to entry for new competitors.
- Stringent Regulatory Hurdles:Complex and evolving regulations, such as the European Union's Medical Device Regulation (MDR), increase compliance burdens, lengthen approval timelines, and raise costs for market access.
- Specialized Material Dependencies:Reliance on a concentrated supply base for critical raw materials like medical-grade 316L stainless steel and specific biocompatible polymers creates vulnerability to price volatility and supply chain disruptions.
Strategic Opportunities
- Emerging Market Penetration:Developing healthcare systems in countries like Brazil and India offer significant growth potential as they increase spending on modern surgical technologies and expand access to care.
- AI and Data Integration:The convergence of artificial intelligence with robotic surgery platforms presents an opportunity to develop next-generation systems that offer predictive analytics and real-time decision support during procedures.
- Ambulatory Center-Specific Portfolios:Designing and marketing instrument sets and capital equipment tailored to the economic and operational needs of Ambulatory Surgical Centers addresses a distinct and expanding customer segment.
Industry Challenges
- Advanced Technology Skill Gaps:A shortage of surgeons and clinical staff trained to operate and maintain complex robotic surgery systems can limit the adoption and effective utilization of advanced equipment. *Interoperability with Legacy Systems: Ensuring new digital surgery platforms and connected devices can seamlessly integrate with existing hospital IT infrastructure and electronic health records is a major technical hurdle.
- Protracted Certification Timelines:Navigating the lengthy and rigorous approval pathways of regulatory bodies like the FDA in the US and the NMPA in China delays the commercialization of new innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Equipment Market |
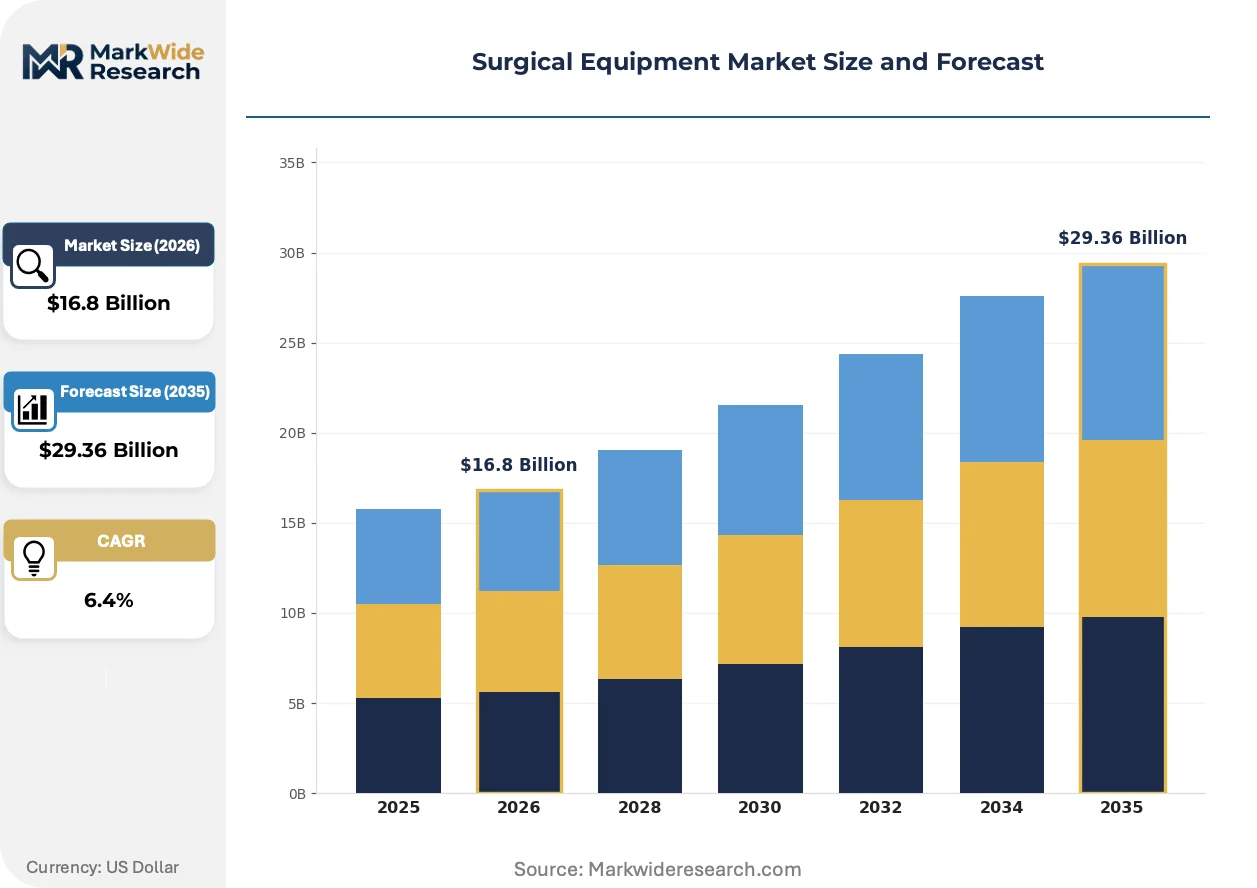
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $29.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Electrosurgical Devices, Operating Tables, Surgical Sutures End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialty Centers Technology: Robotic Surgery, Minimally Invasive Surgery, Traditional Surgery, Digital Surgery Application: Orthopedic Surgery, Cardiothoracic Surgery, Neurological Surgery, General Surgery |
| Companies Covered | Johnson & Johnson, Stryker, Medtronic, Boston Scientific Corporation, Zimmer Biomet Holdings, B. Braun Melsungen AG, Smith & Nephew, Intuitive Surgical, Becton Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Equipment Market Strategic Shifts & Innovations
The market is transitioning from a focus on standalone instruments to the development of integrated surgical ecosystems. This evolution prioritizes data connectivity, software-driven functionality, and procedural optimization, creating a new competitive layer above traditional hardware manufacturing.
Digital surgery platforms combine robotics, high-definition visualization, and data analytics into a single offering. Hospitals and large specialty centers are the primary adopters, seeking to improve outcomes in complex minimally invasive procedures. This technology is integrating formerly discrete hardware, software, and data services into a unified workflow, raising the competitive bar for component suppliers.
Regulatory frameworks are increasing in complexity, directly influencing design and market access strategies. The European Union's Medical Device Regulation (MDR) mandates more rigorous clinical evidence and post-market surveillance for all devices. This affects manufacturers of both high-risk systems and commodity instruments, forcing them to re-evaluate portfolios and invest more heavily in compliance infrastructure.
Purchasing power is migrating from large hospitals to networks of outpatient facilities. Ambulatory Surgical Centers (ASCs) prioritize total cost of ownership and procedural efficiency, disrupting the traditional capital sales model. This trend is most visible in the United States, where it favors vendors offering flexible, right-sized solutions over complex, high-cost platforms.
Surgical Equipment Market Segmentation
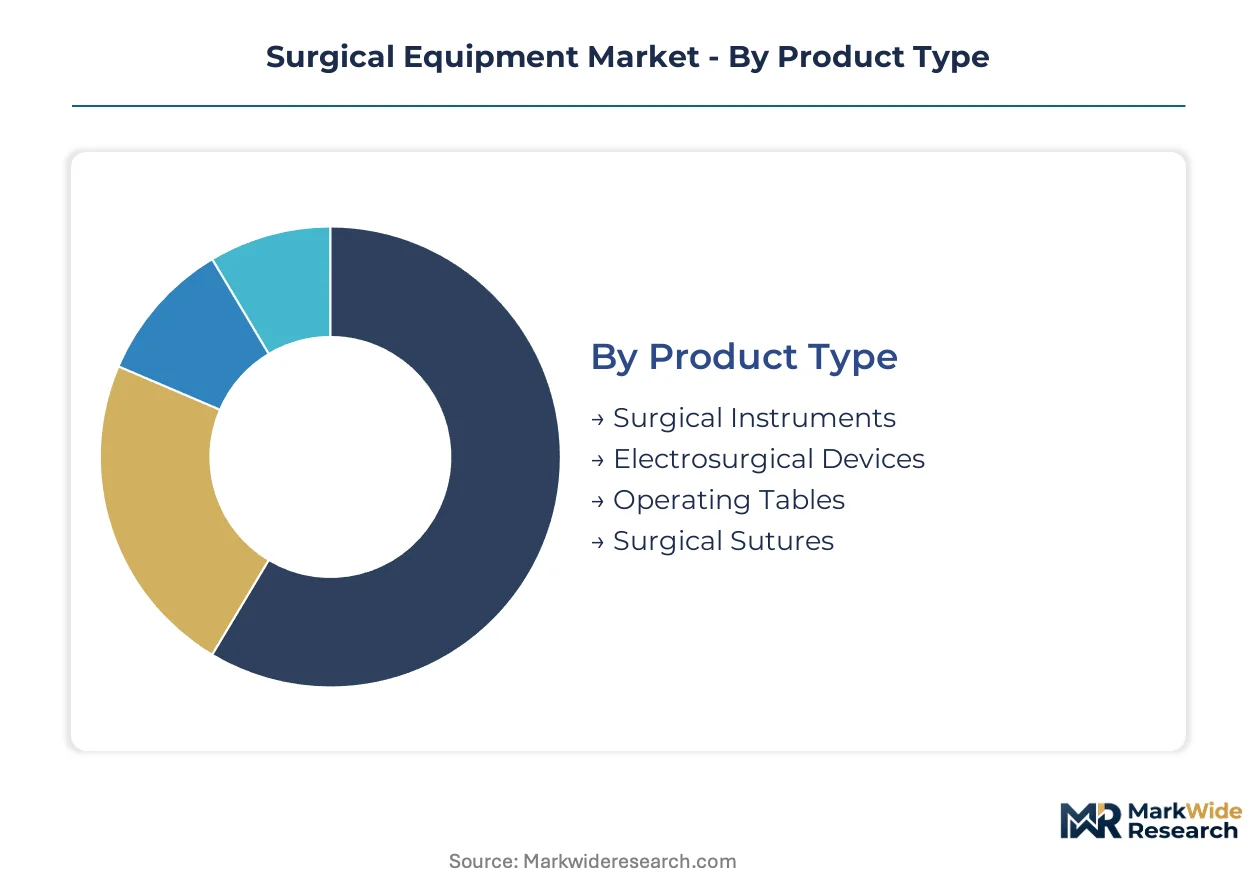
Understanding the segmentation of the surgical equipment market is critical for stakeholders to identify areas of investment, technological focus, and strategic market entry. The market's diverse product types, end-user settings, technological advancements, and surgical applications each present unique growth trajectories and regulatory considerations. Strategic resource allocation depends on a granular view of these distinct segments.
Product Type:
The procurement decisions for surgical equipment often hinge on the specific procedural requirements and material durability demanded by clinicians.
- Surgical Instruments:These include a wide array of handheld devices such as scalpels, forceps, retractors, and scissors, manufactured primarily from medical-grade stainless steel for precision. Demand remains consistently high in all surgical settings, driven by the sheer volume of operative procedures performed globally.
- Electrosurgical Devices:These instruments utilize high-frequency electrical current for cutting, coagulating, and dissecting tissue, featuring specialized electrodes and generators. Their adoption is expanding in minimally invasive surgeries, particularly in China and the US, due to benefits in blood loss control and surgical precision.
- Operating Tables:These are specialized patient support surfaces designed for surgical procedures, offering adjustable positioning and stability. Their demand is tied to new hospital constructions and upgrades in existing healthcare infrastructure.
- Surgical Sutures:These are sterile threads used to close wounds and approximate tissues after surgery, available in absorbable and non-absorbable varieties. They represent a high-volume consumable essential across all surgical disciplines.
Volume sits with Surgical Instruments; growth tilts toward Electrosurgical Devices.
End User:
Customer type dictates the scale and specialization of surgical equipment required for patient care.
- Hospitals:These large facilities serve as primary sites for complex and emergency surgical interventions, requiring a full spectrum of advanced and traditional surgical equipment. They represent the largest segment by capital expenditure, particularly for integrated robotic platforms.
- Ambulatory Surgical Centers:ASCs focus on outpatient procedures, prioritizing cost-efficiency, faster patient turnover, and equipment with smaller footprints and rapid sterilization capabilities. The US market shows significant expansion in this segment, driving demand for tailored instrument sets.
- Clinics:These smaller healthcare facilities primarily handle minor surgical procedures and diagnostic interventions, requiring basic surgical instruments and disposables. Their equipment needs are generally less complex than hospitals or ASCs.
- Specialty Centers:These facilities concentrate on specific surgical disciplines like ophthalmology or orthopedics, demanding highly specialized instruments and tailored capital equipment. Their growth is often linked to demographic shifts and specific disease prevalence.
Demand is concentrating in Hospitals for complex procedures, while Ambulatory Surgical Centers drive efficiency-focused equipment needs.
Technology:
The maturity level of surgical technology influences investment cycles and adoption rates across healthcare providers.
- Robotic Surgery:This segment involves sophisticated robotic systems that enhance surgeon precision, dexterity, and visualization during minimally invasive procedures. Intuitive Surgical dominates this space, with significant adoption in advanced hospitals across Europe and North America seeking improved patient outcomes.
- Minimally Invasive Surgery:This approach uses small incisions, specialized instruments, and cameras to perform operations, reducing patient trauma and recovery times. It is widely adopted across various specialties, driven by patient preference and clinical benefits, particularly in developed healthcare systems.
- Traditional Surgery:This category encompasses open surgical procedures utilizing conventional handheld instruments and direct visualization. It remains foundational for many complex cases and in regions with limited access to advanced technology.
- Digital Surgery:This emerging segment integrates advanced imaging, AI, and data analytics with robotic platforms to provide real-time guidance and predictive insights during operations. It represents a significant R&D focus for leading technology firms.
Shifting investment priorities favor Robotic Surgery platforms, while Traditional Surgery instruments maintain foundational utility.
Application:
Procedural volume directly influences the selection and inventory management of specialized surgical tools.
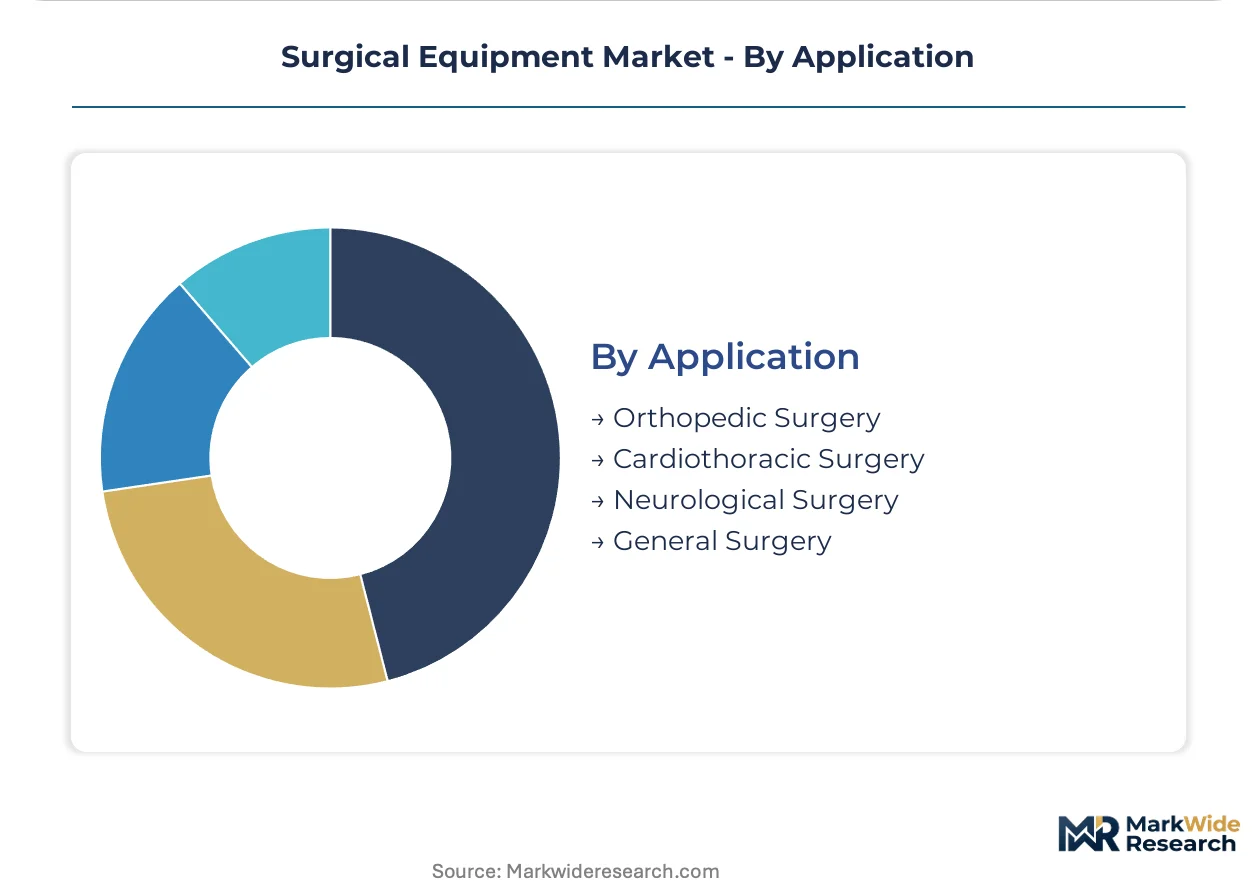
- Orthopedic Surgery:This application focuses on musculoskeletal system procedures, including joint replacements, fracture repairs, and spinal surgeries, requiring specialized implants and instruments. An aging global population sustains high demand for these interventions.
- Cardiothoracic Surgery:This segment addresses conditions of the heart, lungs, and chest cavity, utilizing highly specialized instruments for delicate tissue manipulation and bypass procedures. Technological advancements are focusing on less invasive approaches.
- Neurological Surgery:This application involves complex operations on the brain, spinal cord, and peripheral nerves, demanding micro-surgical instruments and advanced imaging integration. Precision and minimal invasiveness are paramount.
- General Surgery:This broad category encompasses common abdominal, gastrointestinal, and endocrine procedures, requiring a wide range of versatile instruments. It accounts for a substantial volume of routine surgical interventions globally.
Overall procedural demand is diversifying, with General Surgery maintaining broad utility and Orthopedic Surgery experiencing sustained growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston, Massachusetts, serves as a significant hub for surgical equipment innovation and demand within the global market. Healthcare infrastructure expansion drives sustained demand for advanced medical technologies. Regulatory frameworks in various nations influence market access and product development.
United States
Demand for robotic surgery platforms and minimally invasive surgical tools remains strong across US hospitals. The US Food and Drug Administration (FDA) sets rigorous approval standards for all medical devices. Major medical device clusters in California, such as those in San Jose, drive R&D and advanced manufacturing.
Germany
Europe's largest economy consistently shows demand for high-precision surgical instruments. The European Union's Medical Device Regulation (MDR) significantly impacts market entry for new products. The Tuttlingen region in Baden-Württemberg is a global center for surgical instrument production.
China
Healthcare modernization initiatives fuel substantial growth in surgical equipment procurement, particularly for electrosurgical devices. The National Medical Products Administration (NMPA) governs all medical device approvals, creating specific compliance pathways. Shanghai's medical technology parks attract significant investment in advanced manufacturing capabilities.
India
Underpenetration of advanced surgical technologies presents substantial market opportunities in India. The Central Drugs Standard Control Organization (CDSCO) regulates medical device imports and manufacturing. Bengaluru's burgeoning medical technology ecosystem supports local innovation and distribution networks.
Japan
An aging population drives demand for orthopedic and cardiovascular surgical interventions in Japan. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees strict regulatory clearances for surgical equipment. Tokyo's research institutions collaborate with industry on next-generation digital surgery platforms.
Surgical Equipment Market Key Industry Players
Premium-margin players sit above commodity-margin players across the surgical equipment value chain. The market structure exhibits a tiered consolidation, with a few large integrated firms dominating high-end segments. Several specialized archetypes include robotic surgery innovators and high-volume instrument manufacturers. Companies pursue strategic partnerships and portfolio diversification to expand market reach.
On the premium-tier vector, Intuitive Surgical represents a leader in integrated robotic surgery platforms. Johnson & Johnson occupies a position across a broad spectrum of medical devices, including surgical instruments and advanced systems. B. Braun Melsungen AG, a German-based company, exemplifies a diversified portfolio spanning traditional instruments and electrosurgical devices.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Stryker |
| Medtronic |
| Boston Scientific Corporation |
| Zimmer Biomet Holdings |
| B. Braun Melsungen AG |
| Smith & Nephew |
| Intuitive Surgical |
| Becton Dickinson and Company |
| Others |
Cost & Logistics Intelligence
Skilled engineering workforce concentrations in regions like Germany and the US influence pricing-tier spreads, reflecting higher R&D and manufacturing costs for advanced surgical equipment.
Pricing Analysis
Value-based pricing for integrated robotic platforms anchors premium offerings, tying costs to improved patient outcomes and surgical efficiency. Hybrid models blend per-unit transactional pricing for disposables with subscription-based software for digital ecosystems. FDA and MDR certification levels, alongside brand reputation, drive significant price differentiation. Cost compression in traditional instruments stems from high-volume manufacturing in Asia. Ambulatory Surgical Centers exhibit the highest price sensitivity, while large hospitals prioritize advanced technology regardless of initial capital outlay.
Supply Chain Analysis
Logistics and freight costs significantly impact the final price of surgical equipment, particularly for high-value, temperature-sensitive components. Geographic supply concentration includes Germany for precision instruments, China for high-volume electrosurgical devices, and the US for advanced robotic systems. Raw material dependencies center on medical-grade 316L stainless steel and specialized biocompatible polymers. Single-source vulnerability for critical components poses a structural risk. Distribution runs through direct sales channels for complex platforms and third-party distributors for commodity instruments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is ripe for consolidation, driven by the intense R&D investment required for advanced digital surgery platforms, which pressures smaller, less capitalized players.
For Market Incumbents: Anticipate increased regulatory scrutiny under the EU MDR and NMPA, leading to higher compliance costs. Incumbents should acquire niche technology firms specializing in AI or data analytics to enhance their digital surgery offerings. Deepen vertical integration into critical component manufacturing to mitigate supply chain risks. Investment in advanced AI integration for robotic systems provides a crucial lever against emerging digital surgery platforms from tech giants.
For New Entrants and Emerging Players: Group Purchasing Organizations (GPOs) represent a critical channel partner type for new entrants seeking market access in the US. Target Ambulatory Surgical Centers with cost-effective, efficiency-focused instrument sets tailored for outpatient procedures. Emerging markets like India also offer white-space opportunities for basic surgical tools. The most penetrable segment remains ASCs, prioritizing rapid sterilization capabilities and smaller footprints. A strong go-to-market angle involves offering bundled solutions for specific outpatient surgical specialties.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap digital surgery innovators given the accelerating demand for integrated platforms and predictive analytics capabilities. Long-term viability over the next 5-10 years favors firms with proprietary software ecosystems and strong data integration capabilities. Acquisition targets should include companies with robust intellectual property in AI-driven surgical guidance and real-time imaging. Increased hospital capital expenditure allocations specifically for digital surgery suite upgrades signal market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: AI-powered surgical guidance software | Enhances precision and decision support for complex procedures. |
| Strategic Partnership: Collaboration with hospital networks for data integration | Improves interoperability with existing IT infrastructure and electronic health records. |
| CE Marking Pathway: Securing EU MDR compliance for new devices | Ensures market access and regulatory adherence across European Union member states. |
| Geographic Expansion: Entry into high-growth Asian markets like China | Taps into significant government-led healthcare modernization investments. |
| Manufacturing Scale-Up: Increasing production of biocompatible polymer components | Mitigates single-source supply chain vulnerabilities for critical materials. |
Research Approach
SEC filings, academic journals, and industry association reports formed the secondary backbone, providing foundational market data and regulatory insights. Primary interviews with clinicians, hospital purchasing committees, biomedical engineers, and Group Purchasing Organization (GPO) contracts managers validated qualitative findings. This approach combined bottom-up market sizing with top-down industry trend analysis. Secondary data from FDA filings, EU MDR documents, and NMPA guidelines further informed the analysis.
Bottom-up market sizing informed the quantitative framework, projecting segment growth across the analysis window. The model integrated segmentation across product type, end user, technology, application, and regional regulatory cluster. Compound annual growth rates were derived from historical data extrapolation and future growth drivers. Key inputs included healthcare infrastructure spending and global aging population demographics.
Several conditions sit outside the modeled scope, including unforeseen geopolitical conflicts and major global economic downturns. Forecasts reflect assumptions regarding current regulatory stability and technological progression. Unforeseen regulatory changes or significant supply chain disruptions could revise these projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Middle East and Africa General Surgical Devices Market
Surgical Instruments
Cystoscopy Needles Market
Surgical Instruments
Endoluminal Suturing Devices Market
Surgical Instruments
Handheld Arthroscopic Instruments Market
Surgical Instruments
Disposable Ophthalmic Surgical Products Market
Surgical Instruments
Americas Suture Needles Market
Surgical Instruments
Endoscopic Spinal Surgery Market
Surgical Instruments
United States General Surgical Devices Market
Surgical Instruments
Disposable Laparoscopic Instruments Market
Surgical Instruments
Global Microsurgery Market
Surgical Instruments
Retractable Needles Market
Surgical Instruments
Europe Biosurgery Market
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
Huber Needles Market
Surgical Instruments
Global Gastroenterology Ambulatory Surgery Center Market