
 Global Surgical Retractor Market | 2026-2036
Global Surgical Retractor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Retractor Market Intelligence
The expansion of asset-light procurement models, such as equipment leasing and pay-per-use contracts favored by ambulatory surgery centers, is reshaping competitive positioning. Medtronic leverages its extensive device portfolio to secure system-wide contracts with large hospital networks. B. Braun Melsungen AG competes on the breadth of its general surgery offerings and supply chain efficiency. Stryker differentiates through its specialization in retractors for orthopedic and neurosurgery applications.
A surgical retractor is a medical instrument used to separate and hold back the edges of a surgical incision or organ to provide optimal exposure of the operative field. These devices, often manufactured from medical-grade stainless steel or titanium, feature specific blade designs to maintain tension. Self-retaining retractors are displacing handheld variants in complex procedures like neurosurgery and cardiothoracic surgery. While stainless steel instruments constitute the largest material segment, titanium commands higher margins.
Market access hinges on clearance from bodies like the US FDA, compliance with Europe's Medical Device Regulation (MDR), and approval from China's NMPA. These regulations mandate stringent testing for material biocompatibility and sterilization effectiveness. Stakeholders must navigate the strategic choice between investing in durable, reusable systems versus developing single-use retractors to address hospital infection control priorities.
Market Dynamics
The tension between infection control priorities, which favor single-use devices, and the established economic model of durable, reusable stainless steel and titanium instruments is the central force shaping the surgical retractor market's evolution.
Growth Catalysts
- Minimally Invasive Surgery:The rising volume of laparoscopic procedures creates demand for specialized, smaller retractors, driving innovation beyond traditional instruments.
- Aging Populations:Higher rates of orthopedic and cardiothoracic surgeries in nations like Japan and Germany expand the core market for retractors.
- Infection Control Policy:Hospital initiatives to cut HAIs, aligning with WHO guidance, accelerate the shift to sterile, single-use polymer retractors.
Market Restraints
- High Instrument Cost:The capital outlay for reusable systems, especially premium titanium retractors, remains a significant barrier for budget-constrained hospitals.
- Regulatory Hurdles:Lengthy clearance pathways, including the FDA's 510(k) process and Europe's MDR, delay market access for innovative retractor designs.
- Competition from Basic Tools:In routine surgeries, surgeons often prefer low-cost handheld retractors, limiting the market for advanced self-retaining systems.
Strategic Opportunities
- Robotic Surgery Integration:Designing retractors optimized for robotic surgical platforms is a key growth vector, aligning with modern operating room workflows.
- Emerging Market Expansion:Increased healthcare spending in countries like Brazil opens new channels as surgical capacity grows, requiring ANVISA approval.
- Multifunctional Instruments:Integrating features like LED lighting or smoke evacuation into retractor blades offers a clear path for product differentiation.
Industry Challenges
- Supply Chain Volatility:Reliance on a concentrated supply of medical-grade titanium creates vulnerability to price shocks and geopolitical disruption.
- Sterilization Compliance:Documenting the reprocessing of reusable retractors to meet strict hospital audit and MDR requirements is a significant operational burden.
- Complex System Training:Overcoming the learning curve for new self-retaining systems requires substantial investment in surgeon and staff education.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Retractor Market |
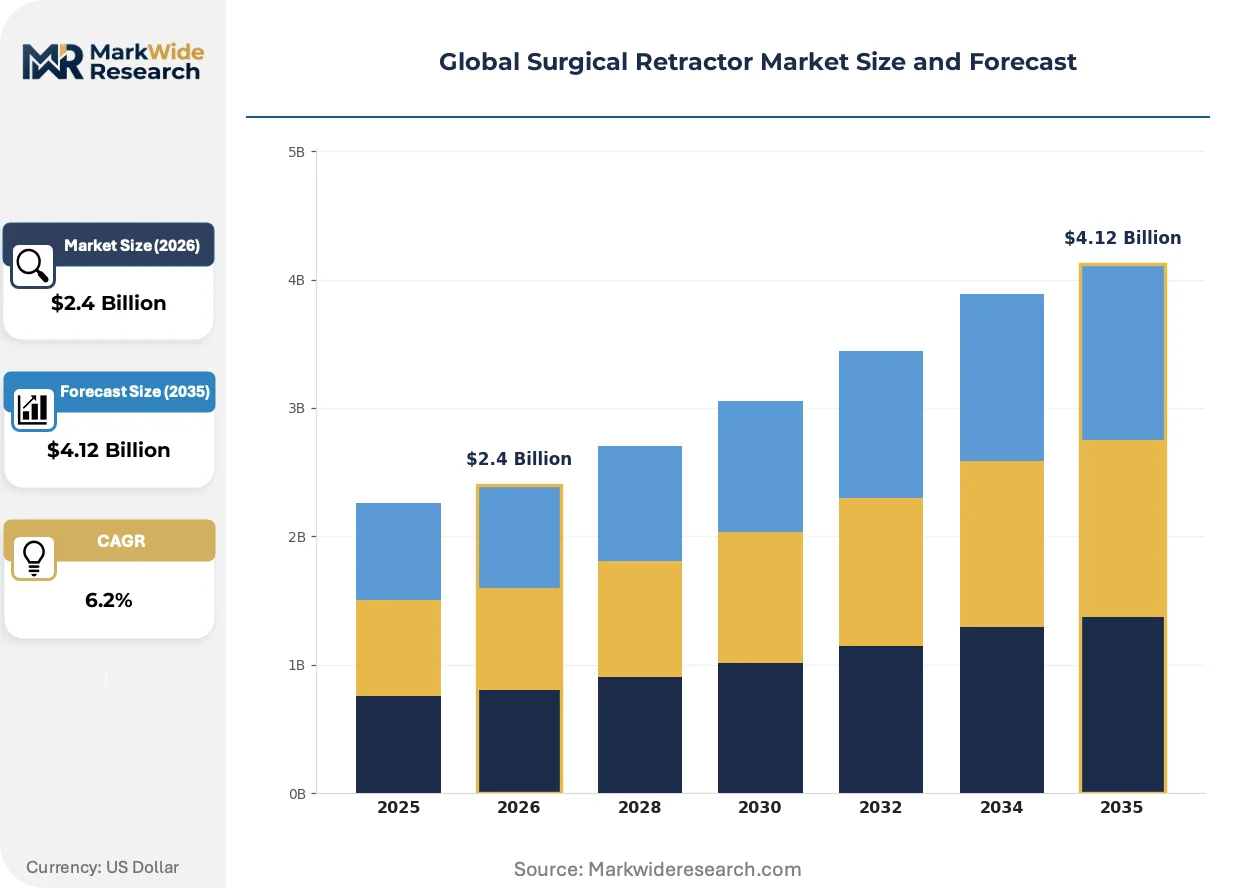
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Retractors, Self-Retaining Retractors, Pediatric Retractors, Orthopedic Retractors, Neuro Retractors Application: General Surgery, Cardiothoracic Procedures, Neurosurgery, Orthopedic Surgery, Urological Surgery Material: Stainless Steel, Carbon Steel, Titanium, Plastic, Aluminum End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Teaching Institutions, Diagnostic Centers |
| Companies Covered | Johnson & Johnson Services, Inc., Medtronic, BD, Teleflex Incorporated, B. Braun Melsungen AG, CONMED Corporation, Integra LifeSciences Corporation, Stryker, CooperSurgical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Retractor Market Strategic Shifts & Innovations
Materials science advancements and stricter infection control regulations are driving a bifurcated innovation path. This creates a market with both increasingly sophisticated, reusable metallic instruments and advanced, single-use polymer-based alternatives.
Smart retractors with embedded fiber optics or pressure sensors provide real-time feedback on tissue tension during surgery. These advanced systems are being adopted in high-stakes fields like neurosurgery, though adoption is deliberate due to cost. This capability is digitizing surgical field management, allowing for data collection on tissue stress to improve patient outcomes.
Europe's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and post-market surveillance on all medical devices. This regulation increases the compliance burden, demanding rigorous documentation for material biocompatibility and sterilization validation. The reusable instrument segment is most affected, forcing manufacturers to update technical files and re-certify products.
Asset-light acquisition models are gaining traction as ambulatory surgery centers and smaller hospitals favor equipment leasing over direct capital purchases. This approach shifts financial risk from the provider to the manufacturer, bypassing large upfront expenditures for surgical instrument sets. The trend is most visible in the United States, where the ASC market's expansion demands flexible operational financing.
Global Surgical Retractor Market Segmentation
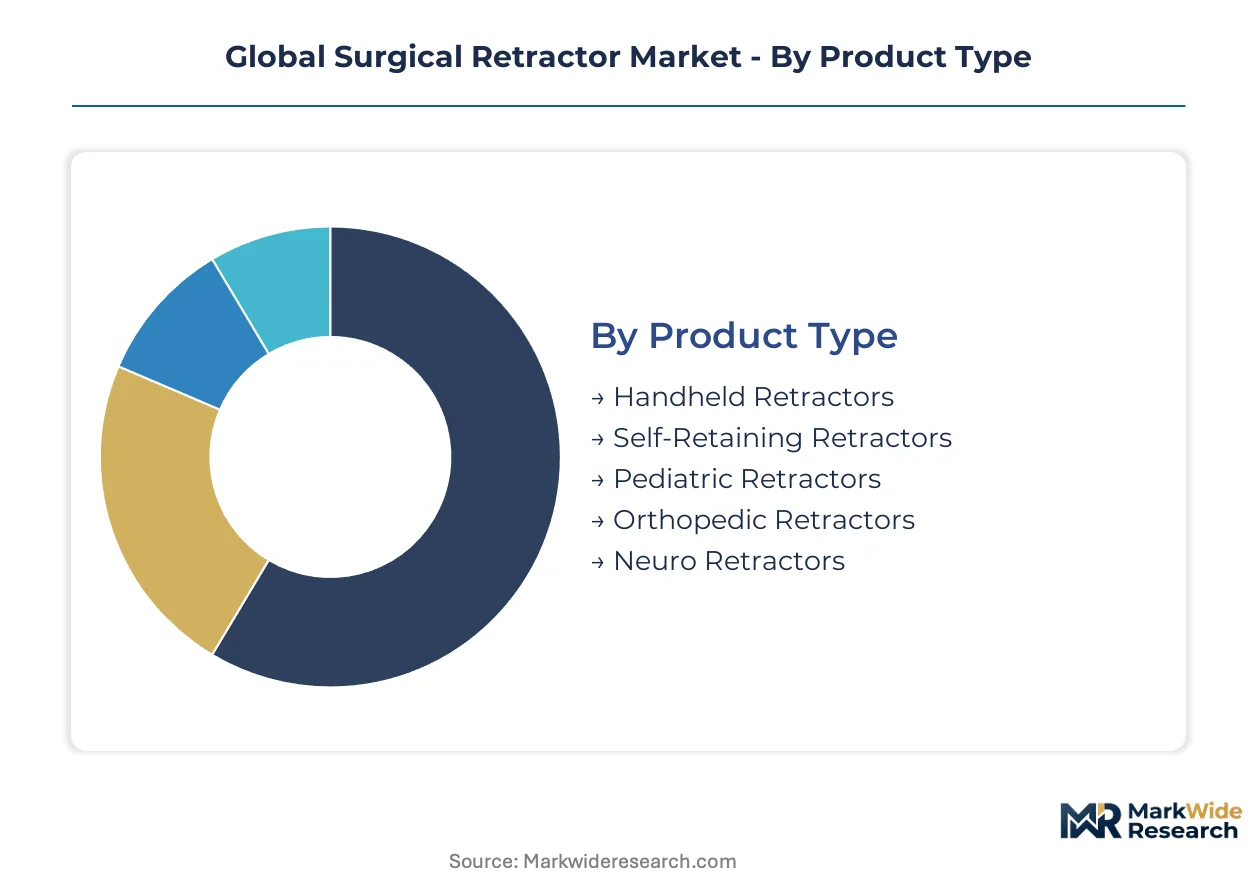
The surgical retractor market's structure reflects diverse clinical needs and operational priorities across healthcare settings. Understanding these distinct segments provides clarity on demand drivers, technological preferences, and procurement patterns shaping the industry.
Product Type:
The use-case spectrum for surgical retractors ranges from simple tissue manipulation to advanced exposure management in complex procedures, defining product type differentiation.
- Self-Retaining Retractors:These instruments feature locking mechanisms to maintain tissue retraction without continuous manual force, freeing surgeon hands. Demand concentrates in neurosurgery and cardiothoracic procedures for stable, prolonged exposure.
- Handheld Retractors:Manually operated devices requiring continuous manual force for tissue separation. They remain significant in routine surgeries but are being displaced by self-retaining variants in specialized fields.
- Pediatric Retractors:Smaller, delicate instruments specifically designed for the anatomical scale and tissue fragility of pediatric patients.
- Orthopedic Retractors:Robust devices engineered to manage dense bone and muscle tissue in orthopedic surgical interventions.
- Neuro Retractors:Highly specialized, often micro-sized retractors providing precise, minimal tissue displacement within delicate neurological structures.
The dominant share belongs to Handheld Retractors, while Self-Retaining Retractors is closing the gap fastest.
Application:
Surgical retractors are tailored to specific procedural requirements, with design variations optimizing visibility and access across different anatomical regions during interventions.
- Cardiothoracic Procedures:Specialized retractors provide broad, stable exposure of the chest cavity and heart. Growth is pronounced here, reflecting an aging population and advancements in cardiac surgery techniques.
- General Surgery:This broad category includes abdominal, gastrointestinal, and soft tissue procedures, demanding versatile retractors. The rising volume of laparoscopic procedures creates demand for smaller designs.
- Neurosurgery:Requires fine, non-traumatic retractors to gently hold delicate brain and spinal cord tissues, often integrating advanced illumination.
- Orthopedic Surgery:Utilizes robust retractors capable of significant force to expose bone and joint structures during reconstructive or trauma surgeries.
- Urological Surgery:Employs specific retractors designed for access to organs within the urinary and reproductive systems, often in confined spaces.
The market's expansion is primarily driven by Cardiothoracic Procedures, with significant innovation seen in General Surgery.
Material:
The choice of material for surgical retractors significantly impacts instrument durability, sterilization protocols, and overall cost, with performance characteristics dictating selection.
- Stainless Steel:This material offers excellent corrosion resistance, high strength, and is suitable for repeated sterilization, making it the largest segment for reusable instruments. Its widespread use stems from proven reliability.
- Titanium:Known for its superior strength-to-weight ratio, biocompatibility, and non-magnetic properties, titanium retractors command higher margins. These premium instruments are favored in specialized neurosurgery.
- Carbon Steel:Offers high hardness and strength but requires careful maintenance to prevent corrosion, making it less common for general retractors.
- Plastic:Increasingly utilized for single-use retractors, plastic and polymer-based materials address infection control priorities and eliminate reprocessing burdens.
- Aluminum:Provides a lighter alternative to steel, often used in components where weight reduction is beneficial, though less common for primary blades.
Material selection is balanced between Stainless Steel's cost-effectiveness and Titanium's premium performance.
End User:
Diverse healthcare facilities influence procurement models and product preferences for surgical retractors, each with distinct infrastructure and financial constraints.
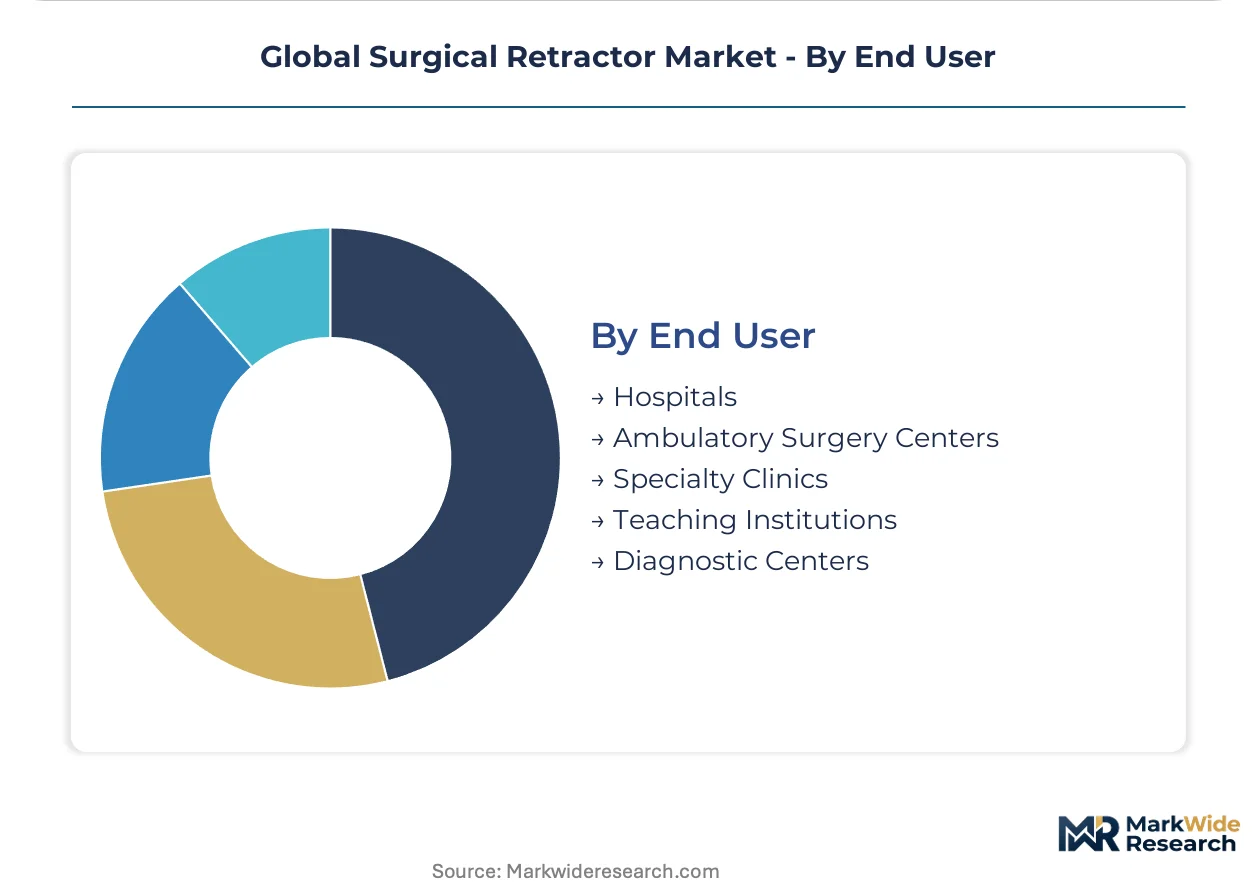
- Hospitals:These institutions represent the largest end-user segment, performing a high volume and variety of surgical interventions. They prioritize durable, reusable systems but increasingly adopt single-use options.
- Ambulatory Surgery Centers:ASCs favor asset-light procurement models like leasing and pay-per-use due to their focus on outpatient procedures and cost efficiency. Their expansion drives flexible instrument acquisition.
- Specialty Clinics:Focus on specific surgical areas, often requiring specialized retractors for niche procedures and smaller patient populations.
- Teaching Institutions:Utilize retractors for both patient care and surgical training, often requiring a broad range of instrument types for educational purposes.
- Diagnostic Centers:While not primary surgical sites, some diagnostic procedures requiring tissue exposure may use basic retractors, a minor segment.
While Hospitals remain the largest consumer, Ambulatory Surgery Centers demonstrate the most dynamic growth in procurement models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital initiatives to reduce healthcare-associated infections significantly influence surgical retractor procurement globally. These policies, often aligning with World Health Organization guidance, accelerate the shift towards sterile, single-use polymer retractors. This regulatory push shapes investment in both disposable and reusable instrument technologies.
United States
High volumes of surgical interventions and advanced healthcare infrastructure drive significant demand for both self-retaining and handheld retractors. The US FDA's 510(k) clearance process mandates rigorous testing for new medical devices, impacting market entry. Major medical device clusters in states like Massachusetts and California innovate in robotic surgery integration.
Germany
An aging population contributes to higher rates of orthopedic and cardiothoracic surgeries, expanding the core market for advanced retractors. Compliance with Europe's Medical Device Regulation (MDR) imposes strict requirements for clinical evidence and post-market surveillance. The medical technology hub around Tuttlingen actively develops specialized instruments for complex procedures.
Japan
Demographics characterized by an aging population create sustained demand for orthopedic and cardiothoracic surgical retractors. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees stringent approval pathways for medical instruments, ensuring product safety and efficacy. Tokyo's burgeoning medical innovation districts focus on integrating smart retractor technologies.
China
Increased healthcare spending and expanding surgical capacity open new channels for surgical retractor manufacturers. Approval from China's National Medical Products Administration (NMPA) is essential for market access, necessitating local clinical trials. Industrial zones in Shanghai and Shenzhen are critical manufacturing and distribution points for medical devices.
Brazil
Growing surgical volumes, particularly in general surgery and orthopedics, drive demand for a broader range of retractor types. ANVISA approval is a mandatory requirement for medical device market entry, focusing on product quality and safety. São Paulo's expanding healthcare infrastructure creates localized demand for diverse surgical instruments.
Global Surgical Retractor Market Key Industry Players
Channel-controlling players compete with product-specialist players across the surgical retractor market. The market structure exhibits a tiered consolidation, with large medical device conglomerates alongside niche innovators. Strategic archetypes include diversified portfolio giants, specialized instrument providers, and regional manufacturers focusing on cost-effectiveness. Portfolio diversification and strategic partnerships are dominant competitive moves among established firms.
Within the diversified medical technology segment, Medtronic and B. Braun Melsungen AG occupy positions as comprehensive device providers. Medtronic, a large US-based corporation, leverages its extensive device portfolio to secure system-wide contracts with large hospital networks. B. Braun Melsungen AG, a German-based company, competes on the breadth of its general surgery offerings and supply chain efficiency, particularly strong across European markets. Stryker, another prominent US-based corporation, exemplifies specialization in retractors tailored for orthopedic and neurosurgery applications, differentiating through targeted innovation and robust product design.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Medtronic |
| BD |
| Teleflex Incorporated |
| B. Braun Melsungen AG |
| CONMED Corporation |
| Integra LifeSciences Corporation |
| Stryker |
| CooperSurgical, Inc. |
Cost & Logistics Intelligence
Concentrated supply of medical-grade titanium directly influences premium product pricing, driving higher margins for specialized retractors. This reliance impacts overall market profitability for advanced surgical instruments.
Pricing Analysis
Compliance with FDA and MDR certification levels creates the primary pricing spread across the surgical retractor market. Per-unit transactional pricing dominates for handheld instruments, though long-term contracts secure sales for self-retaining systems. Material choice, particularly between stainless steel and premium titanium, drives significant price differentiation. Pricing pressure intensifies for reusable instruments due to the rise of cost-effective single-use polymer options, making Ambulatory Surgery Centers highly price sensitive.
Supply Chain Analysis
The upstream feedstock of medical-grade titanium and specialized polymers anchors the surgical retractor supply chain. Manufacturing concentrates in China for polymer-based devices and in advanced hubs like Germany for metallic instruments. Supply chain vulnerability stems from commodity price volatility for titanium and geopolitical disruption, impacting instrument availability. Distribution relies on direct sales channels for major hospital networks and medical distributors for smaller facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
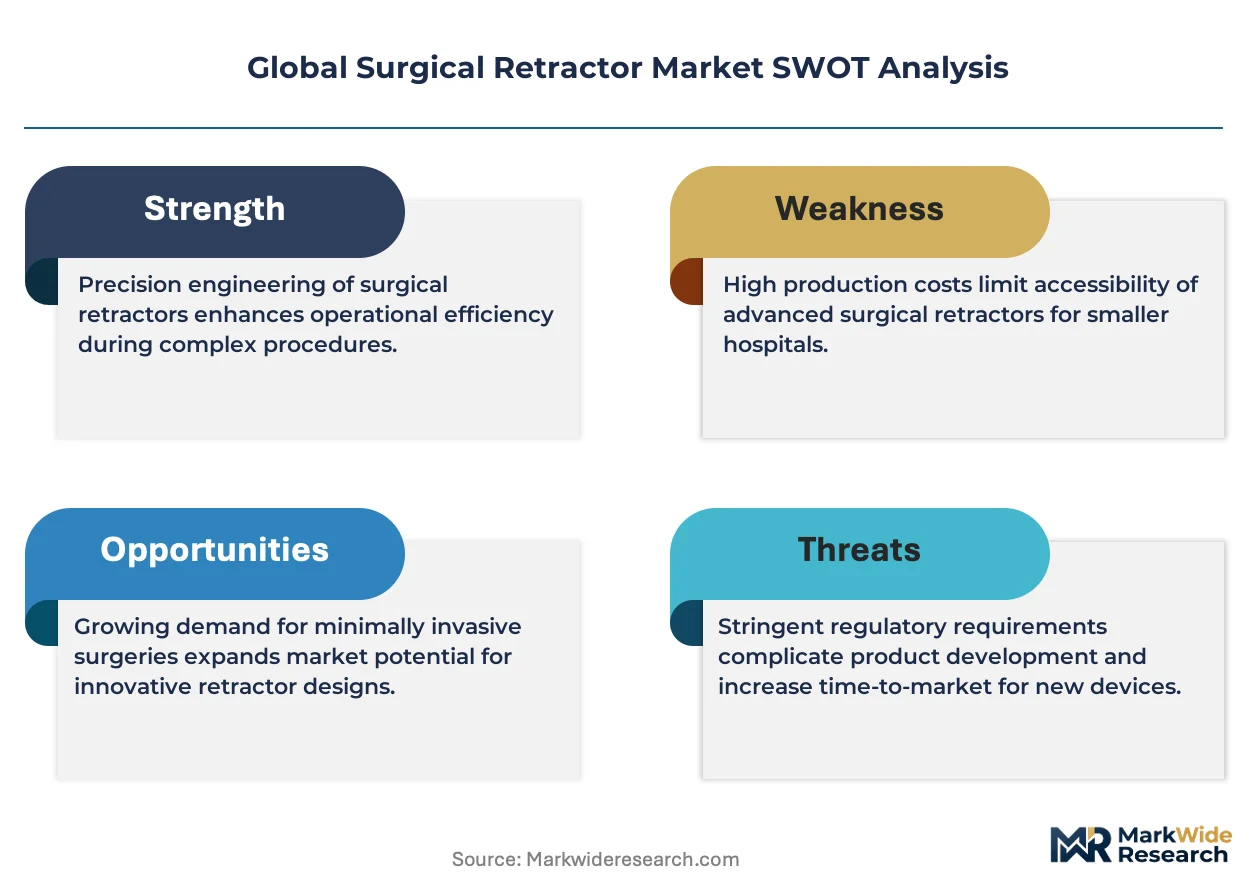
The surgical retractor market presents a defensive moat, primarily driven by significant regulatory entrenchment from bodies like the US FDA and Europe's MDR. This creates high barriers to entry and favors established players.
For Market Incumbents: Insulate existing market share by reinforcing long-term system-wide contracts with major hospital networks, leveraging Medtronic's strategy. Deepen R&D into multifunctional instruments like smart retractors, integrating features such as LED lighting and pressure sensors. This counters the threat of basic, low-cost handheld tools and the shift towards single-use polymer devices. Expand specialization in high-margin segments like neurosurgery, mirroring Stryker's focus.
For New Entrants and Emerging Players: Underpenetrated Ambulatory Surgery Centers in the United States represent a penetrable entry point for innovative retractor solutions. Focus on designing retractors optimized for robotic surgical platforms, aligning with modern operating room workflows. Target emerging markets like Brazil with ANVISA approval, leveraging growing surgical volumes in general surgery. Adopt asset-light procurement models, such as equipment leasing, to appeal to budget-conscious ASCs.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized instrument providers demonstrating strong regional supply chain efficiency or niche clinical focus. The market offers long-term viability over a 5-10 year window, driven by aging populations and surgical volume expansion. Prioritize acquiring firms with established regulatory clearances and robust R&D in smart retractor technologies. A key signal to watch is successful navigation of Europe's Medical Device Regulation (MDR) recertification.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Integration R&D | Optimizes retractor designs for modern operating room workflows, enhancing precision in complex procedures. |
| Single-Use Polymer Product Launch | Addresses hospital infection control priorities and reduces reprocessing burdens for healthcare facilities. |
| Emerging Market Regulatory Approval | Unlocks new revenue channels by accessing growing surgical capacity in countries like Brazil. |
| Multifunctional Instrument Development | Integrates advanced features like LED lighting or smoke evacuation for product differentiation and improved surgical visibility. |
| Long-Term Hospital Network Contracts | Secures stable revenue streams and reinforces competitive positioning with large healthcare providers. |
Research Approach
Initial hypotheses were tested against primary input from surgeons, hospital purchasing committees, and biomedical engineers, then refined through iterative analysis. This approach combined in-depth primary interviews with rigorous secondary validation from sources like FDA filings, Europe's MDR documentation, and WHO guidance. Bottom-up data collection from specific product segments was triangulated with top-down market sizing estimates.
A demand-supply balance framework underpinned the quantitative modeling across the analysis window. Market segmentation dimensions, including product type, application, material, end-user, and regional regulatory clusters, were thoroughly modeled. Compound Annual Growth Rates (CAGRs) were derived by analyzing historical growth trends and projected surgical procedure volumes. Key forecast inputs included evolving infection control policies.
Macroeconomic conditions sit as an overlay; deviation in global healthcare spending or geopolitical stability would shift the trajectory. Forecasts reflect assumptions on regulatory stability and technological adoption. Cross-checking against external medical device benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Endoluminal Suturing Devices Market
Surgical Instruments
Laparoscopic Needle Holder Robotic Devices Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
Gynecology Surgical Instruments Market
Surgical Instruments
Ultrasonic Scissors Market
Surgical Instruments
Operating Room Smoke Aspirators Market
Surgical Instruments
US Surgical Staplers Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
Endoscopic Spinal Surgery Market
Surgical Instruments
Surgical Stents Market
Surgical Instruments
Electrosurgery Market
Surgical Instruments
Laparotomy Sponges Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Global Surgical Instruments Market
Surgical Instruments
Global Surgical Scalpel Market
Surgical Instruments
Retractable Needles Market