
 Global Veterinary Surgical Instruments Market | 2026-2036
Global Veterinary Surgical Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary Surgical Instruments Market Foresight
Companion animal specialty care is shifting toward advanced surgical interventions in oncology and orthopedics. B. Braun Melsungen AG leverages its human-medical manufacturing scale to supply precision electrocautery platforms into veterinary channels. Integra LifeSciences dominates the regenerative surgery segment with dermal matrices adapted for equine and small-animal reconstructive procedures. Jørgen Kruuse A/S anchors the Nordic and Central European markets through deep distributor relationships with university teaching hospitals.
Veterinary surgical instruments encompass precision-engineered hand tools, powered devices, and energy-based systems designed for sterile tissue manipulation, hemostasis, and wound closure across species; stainless steel 440C and titanium alloys deliver the hardness and corrosion resistance required for repeated autoclave cycles. Scalpels and forceps constitute the mature volume base where procurement consolidates around group purchasing organizations. Ultrasonic and electrocautery technology segments capture expanding margin pools as referral clinics upgrade from manual dissection. Soft tissue surgery applications lead procedure volume while orthopedic surgery drives capital-intensive power tool replacement cycles.
FDA Center for Veterinary Medicine oversees device safety labeling and adverse event reporting for instruments used in food-producing animals. The EU Medical Device Regulation imposes conformity assessment burdens on manufacturers exporting electrosurgical and endoscopic systems into European veterinary clinics. ISO 13485 quality management certification functions as a de facto market access threshold for contract manufacturing relationships. Stakeholders must monitor how FDA guidance on veterinary device cybersecurity shapes connected electrosurgical platform development timelines.
Market Dynamics
Minimally invasive surgical platforms are compressing replacement cycles for conventional hand instruments while elevating capital equipment procurement thresholds across specialty veterinary hospitals.
Growth Catalysts
- Laparoscopic platform adoption:Referral clinics in the United States and Germany are replacing open procedures with minimally invasive techniques, requiring compatible trocar and insufflator systems.
- EU Medical Device Regulation:Conformity assessment requirements for electrosurgical units are filtering out low-quality imports, consolidating procurement around ISO 13485-certified suppliers.
- Oncology service line expansion:Soft tissue tumor resections in companion animals now command dedicated instrument sets, driving repeat purchases of specialized forceps and retractors.
Market Restraints
- Titanium alloy supply concentration:Surgical-grade titanium sourcing clusters with a limited set of Japanese and Chinese metallurgical processors, exposing manufacturers to price volatility.
- Autoclave compatibility requirements:Stainless steel 440C remains mandatory for instruments requiring repeated sterilization cycles, blocking substitution by polymer-based alternatives.
- CE marking cost escalation:MDR technical documentation burdens disproportionately affect small instrument manufacturers serving niche species segments.
Strategic Opportunities
- Brazilian specialty clinic formation:São Paulo and Rio de Janeiro referral hospitals are establishing independent surgical departments, creating first-mover advantage for electrosurgical platform suppliers.
- Telemedicine-integrated training:Remote surgical mentoring systems are reducing geographic barriers to advanced technique adoption in Australian regional practices.
- Japanese regenerative surgery protocols:METI-supported research initiatives are accelerating dermal matrix applications in equine reconstructive procedures.
Industry Challenges
- Minimally invasive technique certification:Veterinary surgeons require species-specific laparoscopy credentials that exceed standard residency training, constraining addressable procedure volume.
- Legacy power tool interoperability:Existing orthopedic drill and saw systems from prior-generation manufacturers resist interface standardization with new battery platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary Surgical Instruments Market |
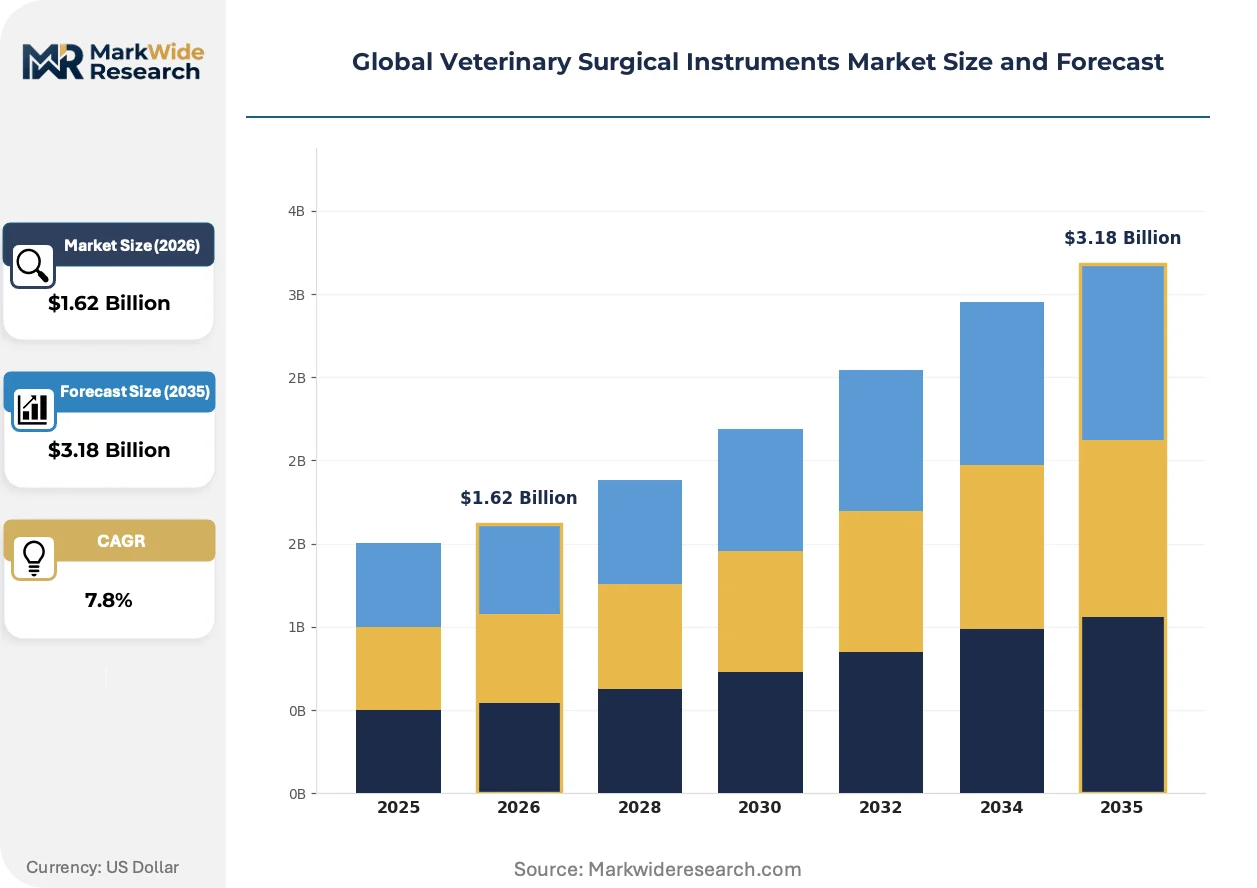
| Market Size in 2026 | $1.62 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scalpels, Forceps, Scissors, Needle Holders, Retractors, Suction Pumps Technology: Manual, Electric, Ultrasonic, Laser, Electrocautery, Endoscopic Application: Soft Tissue Surgery, Orthopedic Surgery, Ophthalmic Surgery, Dental Surgery, Neurosurgery, Emergency Procedures End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Zoos, Mobile Clinics, Universities |
| Companies Covered | B. Braun Melsungen AG, Jørgen Kruuse A/S, Integra LifeSciences, STERIS, Medtronic, Jorgensen Laboratories, Ethicon Inc., Neogen Corporation, World Precision Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary Surgical Instruments Market Shifts & Advancements
Energy-based hemostasis and connected device architectures are displacing manual dissection methods while introducing cybersecurity and maintenance complexity into procurement decisions.
Ultrasonic scalpel systems is rewriting procedural economics in soft tissue surgery. These platforms coagulate and dissect simultaneously, reducing operative time in spay and tumor resection procedures. Large specialty hospitals in Japan and Germany are standardizing ultrasonic platforms across surgical suites. The technology is compressing demand for traditional hemostatic forceps and ligature consumables.
REACH substance restrictions on nickel release are forcing metallurgical reformulation of instrument alloys used in European markets. Manufacturers must revalidate corrosion resistance and hardness specifications under revised composition limits. Electrosurgical handpiece producers serving EU veterinary channels are accelerating tungsten and ceramic coating substitutions.
Consolidated procurement through veterinary group purchasing organizations is concentrating vendor selection authority in the United States. Independent specialty clinics are surrendering direct supplier negotiations to centralized contracting entities. This channel shift is most advanced in California and Texas metropolitan corridors where hospital networks span dozens of locations.
Global Veterinary Surgical Instruments Market Segmentation
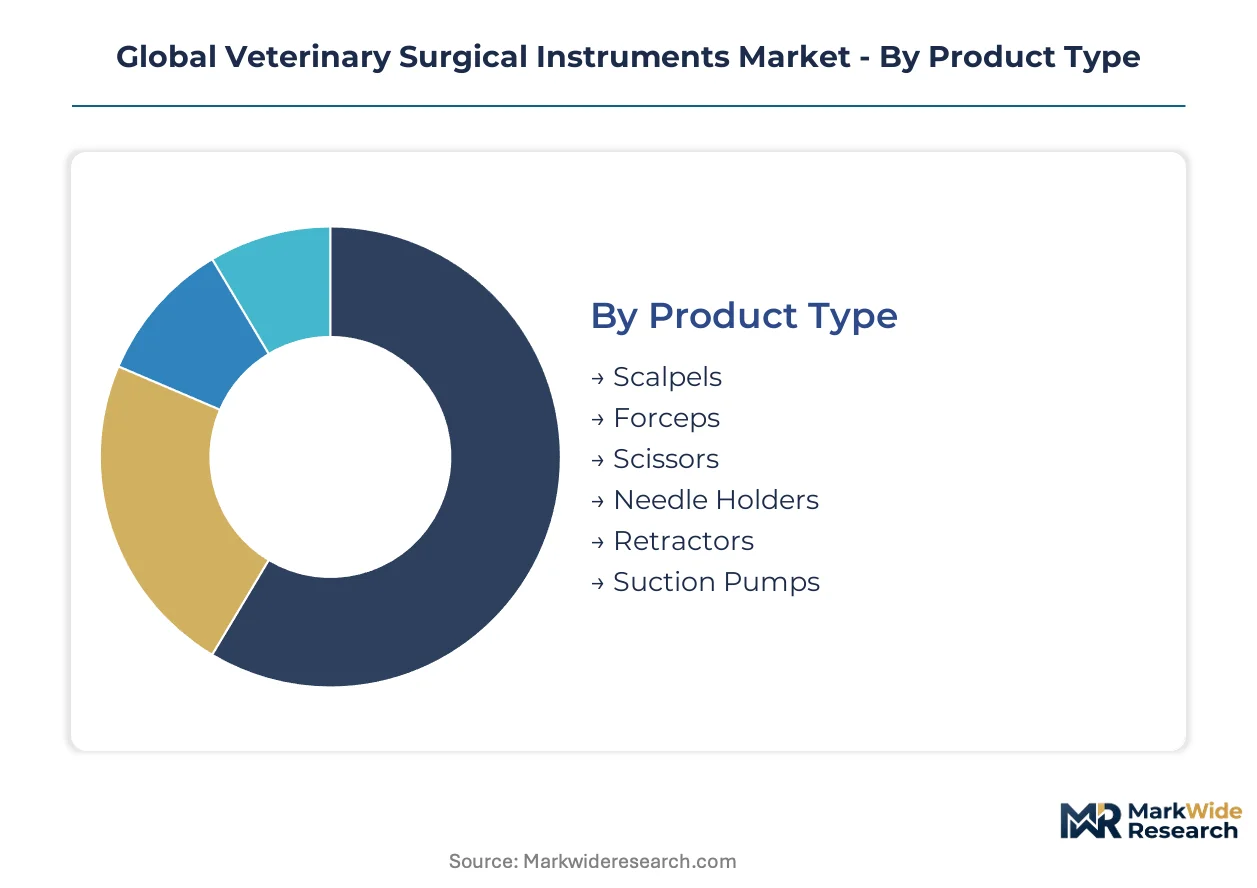
Segmentation in veterinary surgical instruments reveals distinct procurement patterns across product tiers and technology platforms. Stainless steel hand tools dominate volume while energy-based systems capture margin expansion in referral hospitals.
Product Type:
Supply concentration in metallurgical processing shapes competitive dynamics across instrument categories.
- Scalpels:Disposable blade systems and reusable handles comprise the highest-volume procurement category. United States group purchasing organizations consolidate contracts around carbon steel and ceramic blade suppliers, with California veterinary networks driving standardization toward safety-engineered designs.
- Forceps:Tissue-grasping instruments span hemostatic, dissecting, and atraumatic variants requiring precision tip geometry. German university teaching hospitals specify titanium alloy construction for cardiac and microsurgical applications, resisting price erosion through performance-based procurement.
- Scissors:Metzenbaum and Mayo patterns serve distinct tissue layers with differential edge angles.
- Needle Holders:Ratchet-lock mechanisms with tungsten carbide inserts withstand suture material abrasion.
- Retractors:Self-retaining and hand-held designs expose operative fields across species size variation.
- Suction Pumps:Powered aspiration systems support minimally invasive and open procedures.
Scalpels absorb the bulk of installed capacity; forceps is expanding most quickly through specialty surgical service lines.
Technology:
Cost tier stratification separates capital-intensive platforms from consumable-heavy manual systems.
- Manual:Hand-powered instruments require no external energy source, minimizing total cost of ownership. Rural Australian practices and Brazilian mobile clinics default to manual tools where infrastructure constraints limit electrosurgical adoption.
- Electric:Powered drills and saws enable orthopedic fixation with battery and corded variants. Japanese equine hospitals specify high-torque electric systems for large-bone osteotomy, driving replacement cycles every four to five years under heavy caseload conditions.
- Ultrasonic:High-frequency vibration achieves simultaneous cutting and coagulation.
- Laser:Photonic tissue ablation serves ophthalmic and soft tissue applications.
- Electrocautery:Radiofrequency current achieves hemostasis through tissue resistance heating.
- Endoscopic:Minimally invasive visualization and instrument channels reduce recovery times.
Manual technology retains the deepest installed base; ultrasonic platforms are climbing the fastest through specialty hospital upgrade cycles.
Application:
Procedure volume distribution concentrates investment in high-frequency surgical categories.
- Soft Tissue Surgery:Spay, neuter, and tumor resection procedures generate recurring instrument demand. United States specialty oncology practices in Texas metropolitan corridors procure dedicated soft tissue sets, with instrument turnover accelerating through high sterilization cycle exposure.
- Orthopedic Surgery:Fracture repair, joint stabilization, and arthrodesis require capital-intensive power systems. German referral hospitals standardize orthopedic drill platforms across surgical suites, creating captive demand for proprietary battery and attachment ecosystems.
- Ophthalmic Surgery:Microsurgical precision demands specialized instrument geometries.
- Dental Surgery:Extraction and periodontal procedures utilize high-speed rotary and hand instruments.
- Neurosurgery:Cranial and spinal access requires fine dissection and suction capabilities.
- Emergency Procedures:Trauma stabilization demands rapid instrument availability.
Soft tissue surgery commands the largest procedure volume; orthopedic surgery is gaining share fastest through pet insurance expansion.
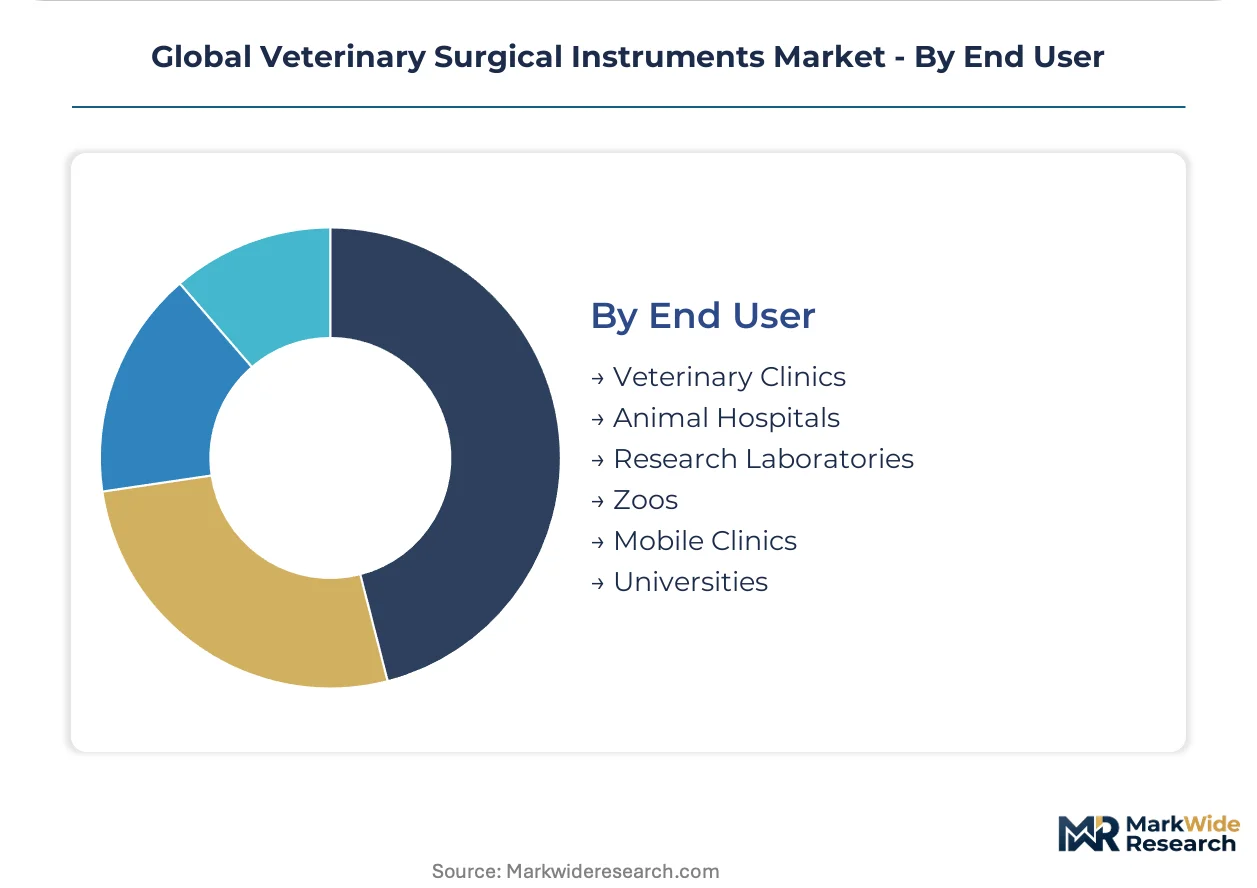
End User:
Customer type determines procurement authority structure and price sensitivity thresholds.
- Veterinary Clinics:General practice settings balance cost constraints with procedure breadth. Independent clinics in São Paulo negotiate directly with distributors, bypassing group purchasing organization fees while accepting longer delivery lead times.
- Animal Hospitals:Multi-specialty referral centers consolidate high-value surgical service lines. University-affiliated hospitals in Japan integrate research and clinical procurement, demanding instrument traceability systems that exceed standard commercial specifications.
- Research Laboratories:Preclinical surgical models require precision reproducibility.
- Zoos:Exotic species procedures demand instrument size variation.
- Mobile Clinics:Field surgical services prioritize portability and sterilization efficiency.
- Universities:Teaching hospitals combine clinical service with training mission requirements.
Animal hospitals absorb the bulk of premium technology procurement; mobile clinics are expanding most quickly through rural access initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Dongguan concentrate titanium alloy processing for surgical instrument manufacturers serving veterinary channels across East Asia.
United States
Group purchasing organizations in California and Texas metropolitan corridors consolidate procurement authority for specialty veterinary hospitals. FDA Center for Veterinary Medicine oversees device safety labeling for instruments used in food-producing animals. Greater Boston anchors regenerative surgery research with university-affiliated teaching hospitals demanding instrument traceability systems.
Germany
University teaching hospitals in Bavaria and Baden-Württemberg specify titanium alloy construction for cardiac and microsurgical applications. EU Medical Device Regulation imposes conformity assessment burdens on electrosurgical and endoscopic system exporters. The Stuttgart industrial cluster hosts precision metalworking facilities supplying orthopedic power tool components.
Japan
METI-supported research initiatives accelerate dermal matrix applications in equine reconstructive procedures. PMDA and JIS standards govern quality specifications for surgical-grade instruments. The Kansai region around Osaka concentrates ultrasonic scalpel platform manufacturing for domestic veterinary specialty hospitals.
Brazil
São Paulo and Rio de Janeiro referral hospitals establish independent surgical departments requiring electrosurgical platform upgrades. ANVISA regulates medical device registration for imported surgical instruments. The São Paulo metropolitan corridor attracts first-mover distributors bypassing traditional veterinary supply chains.
Australia
Regional practices adopt telemedicine-integrated surgical mentoring systems reducing geographic barriers to advanced technique adoption. TGA oversees therapeutic goods administration including veterinary surgical devices. Queensland and New South Wales mobile clinics expand rural access initiatives prioritizing portable manual instrument sets.
Global Veterinary Surgical Instruments Market Competitive Landscape
Top-tier vendors anchor premium technology segments, while mid-scale fabricators compete on stainless steel hand tool volume. The market exhibits tiered concentration with human-medical manufacturers leveraging manufacturing scale into veterinary channels. Three archetypes dominate: diversified medical device conglomerates, veterinary-specialized instrument houses, and contract manufacturers serving private-label distributors. Competitive moves center on M&A for technology access and strategic partnerships with university teaching hospitals for clinical validation.
Among European-based manufacturers, B. Braun Melsungen AG and Jørgen Kruuse A/S occupy distinct positions within the premium instrument tier. B. Braun Melsungen AG represents the diversified medical device conglomerate archetype with manufacturing scale extending from human surgical platforms. Jørgen Kruuse A/S exemplifies the veterinary-specialized instrument house model with distributor relationships anchored in Nordic and Central European university hospitals. Integra LifeSciences sits within the regenerative surgery-focused tier, occupying a position in dermal matrix applications adapted for veterinary reconstructive procedures.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Jørgen Kruuse A/S |
| Integra LifeSciences |
| STERIS |
| Medtronic |
| Jorgensen Laboratories |
| Ethicon Inc. |
| Neogen Corporation |
| World Precision Instruments |
| Others |
Supply & Pricing Matrix
Precision metalworking labor pools in Stuttgart and Shenzhen generate cost-of-production differentials that stratify pricing tiers across manual instrument and capital equipment categories. German-made titanium forceps command substantial premiums over Chinese-manufactured stainless steel equivalents, reflecting divergent labor rates and certification overhead.
Pricing Analysis
Lead-time premiums separate spot procurement from contract-scheduled deliveries, with urgent orders for specialized retractor sets attracting surcharges of 15-25 percent above standard terms. Three-tier pricing structure across premium, standard, and economy levels aligns with ISO 13485 certification status and metallurgical grade. Price differentiation stems from autoclave cycle durability guarantees and after-sales calibration service bundling. Cost compression in economy-grade hand tools is intensifying because Brazilian and Indian distributors are consolidating volume tenders, while university teaching hospitals in Japan and Germany demonstrate lowest price sensitivity due to research grant funding mechanisms.
Supply Chain Analysis
ISO 13485 certification gates access to contract manufacturing relationships with major distributors, filtering out unqualified fabricators from European and North American procurement channels. Titanium alloy processing concentrates in Japan, China, and Germany, while precision stainless steel forging clusters in Italy and Pakistan. Supply chains draw from surgical-grade 440C steel mills, tungsten carbide insert suppliers, and ceramic coating applicators. Single-source vulnerability persists in Japanese metallurgical processors serving high-performance equine orthopedic platforms. Distribution runs through veterinary group purchasing organizations in the United States and specialized distributors in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation erects substantial compliance cost barriers that protect incumbent ISO 13485-certified manufacturers from low-quality import competition, creating sustainable moats for compliant players.
For Market Incumbents: Extend certification coverage into emerging electrosurgical platform categories before MDR technical documentation requirements harden. Consolidate distributor relationships with Brazilian university teaching hospitals to preempt entrant access. Counter ultrasonic scalpel substitution threats by bundling legacy forceps with service contracts. Backward integration into titanium alloy sourcing mitigates Japanese processor concentration risk. For New Entrants and Emerging Players: Mobile veterinary clinics in Australian regional markets represent an underserved buyer archetype with limited capital equipment penetration and minimal group purchasing organization affiliation. Target São Paulo specialty hospitals establishing independent surgical departments for first-mover electrosurgical platform placement. Exploit telemedicine-integrated training partnerships to reduce technique certification barriers. A direct-to-clinic distribution model bypasses consolidated procurement channels. For Investors and Strategic Acquirers: Re-rating potential sits with regenerative surgery-focused instrument houses given METI-supported dermal matrix research acceleration in Japanese equine protocols. Long-term viability hinges on exposure to pet insurance expansion driving orthopedic procedure volume. Acquisition candidates should demonstrate university teaching hospital validation and proprietary battery platform ecosystems. Watch PMDA guidance on veterinary device cybersecurity as inflection indicator for connected electrosurgical platform development timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR conformity assessment unlocks European veterinary hospital procurement channels for electrosurgical exporters. |
| Hospital System Partnership | University teaching hospital validation accelerates specialty clinic adoption of ultrasonic scalpel platforms. |
| Backward Integration | In-house titanium alloy processing insulates margins from Japanese metallurgical processor price volatility. |
| Software Companion Development | Connected electrosurgical platforms with cybersecurity compliance meet FDA Center for Veterinary Medicine guidance. |
| Reimbursement Strategy | Pet insurance contract alignment with orthopedic procedure codes drives capital equipment replacement cycles. |
Research Methodology
Document review covered FDA Center for Veterinary Medicine guidance documents, EU MDR technical documentation requirements, and ISO 13485 certification databases, complemented by interviews with veterinary surgical instrument distributors, biomedical engineers at university teaching hospitals, group purchasing organization contract managers, and equine hospital procurement directors. Secondary validation drew from PMDA regulatory filings, ANVISA device registration records, and TGA therapeutic goods administration data. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data.
Cross-referencing historical procurement patterns against expert panel input informed the analytical framework across the analysis window. Segmentation dimensions modeled include product type, technology platform, surgical application, and end-user category. CAGRs were derived from weighted procedure volume projections and capital equipment replacement cycle assumptions. Forecast inputs incorporated pet insurance penetration rates and minimally invasive technique adoption curves.
Revisions become necessary when regulatory guidance on veterinary device cybersecurity materializes or when titanium alloy supply disruptions affect manufacturing capacity. Forecasts reflect assumptions regarding MDR implementation timelines and referral hospital formation rates. A model refresh is warranted upon material change in FDA Center for Veterinary Medicine labeling requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Absorbable Sutures Market
Surgical Instruments
Ultrasonic Tissue Ablation System Market
Surgical Instruments
Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Global Microsurgical Instruments Market
Surgical Instruments
Ultrasonic Surgical Cutters Market
Surgical Instruments
Disposable Surgical Devices Market
Surgical Instruments
Huber Needles Market
Surgical Instruments
Europe General Surgical Devices Market
Surgical Instruments
High Flow Needle Sets Market
Surgical Instruments
Ultrasonic Scalpel Market
Surgical Instruments
Cystoscopy Needles Market
Surgical Instruments
Surgical Stents Market
Surgical Instruments
Global Surgical Scissors Market
Surgical Instruments
Surgical Headband Market
Surgical Instruments
Adult Cardiovascular Surgical Instruments Package Market
Surgical Instruments
Global Electromagnetic Surgical Navigation System Market