
 Surgical Suction Pumps Market | 2026-2036
Surgical Suction Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Suction Pumps Market Analysis
German precision engineering clusters is recalibrating production schedules to address backlog in vacuum pump assemblies for operating rooms. B. Braun leverages its integrated manufacturing footprint across European sterile device hubs to sustain catheter-to-pump bundling contracts. Stryker competes through dedicated acute care sales teams that control purchasing committees at major hospital networks. Medela anchors its position in lactation-derived vacuum technology, extending know-how into surgical suction applications with specialized fluid management systems.
Surgical suction pumps are electromechanical or pneumatic devices that generate controlled negative pressure, typically between 80 and 600 mmHg, to evacuate blood, irrigants, and tissue debris during operative procedures. Their primary commercial purpose centers on maintaining clear operative fields and reducing aspiration risk across open, laparoscopic, and endoscopic interventions. Portable units are capturing disproportionate growth as ambulatory surgical centers prioritize space-efficient capital equipment with rapid turnover capability. Electric technology leads absolute volume while battery-operated systems represent the fastest-expanding margin pool, driven by cordless mobility demands in emergency care and field military medicine.
FDA 510(k) clearance pathways and EU MDR conformity assessments now demand expanded biocompatibility documentation and post-market surveillance for reusable suction canisters, reshaping product development timelines. ISO 10079 standards for suction equipment, coupled with OSHA bloodborne pathogen protocols, enforce material traceability and disposable component compatibility that filter smaller manufacturers from institutional procurement lists. Stakeholders must monitor how battery chemistry regulations from the EU's Battery Directive propagate into portable suction device design specifications.
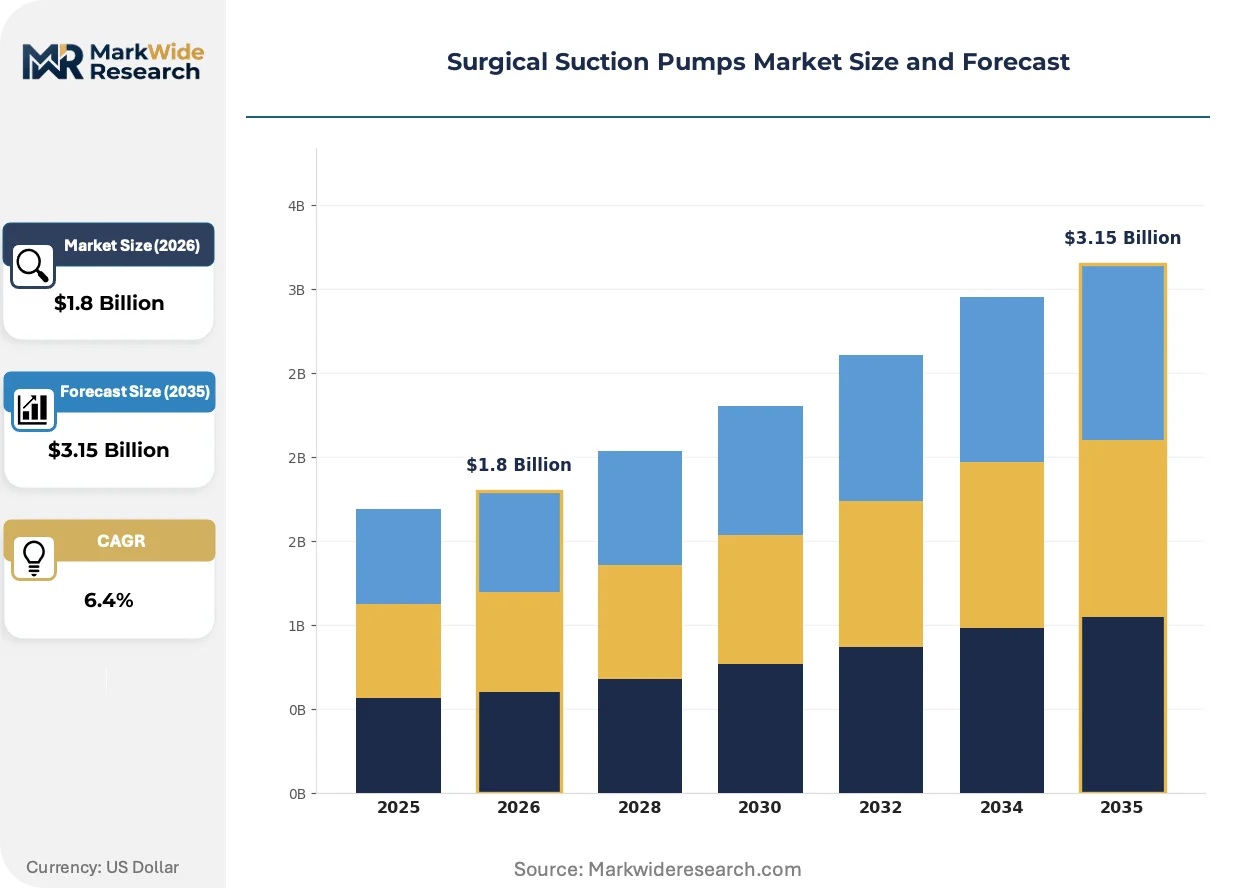
Market Dynamics
Ambulatory surgical centers are compressing capital equipment replacement cycles while FDA 510(k) clearance pathways for powered suction devices extend development timelines, creating simultaneous demand acceleration and supply friction.
Growth Catalysts
- EU MDR conformity assessments:Expanded biocompatibility documentation requirements for reusable suction canisters are filtering smaller manufacturers from institutional procurement lists, consolidating volume with certified suppliers.
- Battery chemistry advances:Lithium-ion cell density improvements are enabling cordless surgical suction systems with sustained negative pressure output across emergency care and field military medicine deployments.
- German precision engineering clusters:Vacuum pump assembly backlogs are recalibrating production schedules to prioritize operating room infrastructure orders from hospital networks.
Market Restraints
- Raw material concentration:Rare earth magnet supply for brushless DC motors concentrates in Chinese processing facilities, exposing pump manufacturers to export quota volatility.
- Technical limitation:Battery-operated systems face thermal runaway risks under sustained 600 mmHg negative pressure loads, constraining high-performance portable adoption.
- Regulatory friction:OSHA bloodborne pathogen protocols enforce disposable component compatibility that elevates per-procedure costs versus reusable canister systems.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for medical device manufacturing are attracting component suppliers to establish sterile device hub capacity for export markets.
- Technology convergence:Integration of pressure sensors with IoT telemetry is enabling real-time suction performance monitoring and predictive maintenance contracts.
- Direct-to-ASC distribution:Bypassing traditional hospital purchasing committees through specialized ambulatory surgical center sales channels captures faster decision cycles.
Industry Challenges
- Biomedical engineering talent scarcity:Cross-functional expertise in fluid dynamics, battery thermal management, and sterile packaging design remains concentrated in established manufacturing regions.
- Legacy OR integration:Retrofitting cordless suction systems into fixed electrical and gas infrastructure requires custom mounting solutions and staff retraining protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Suction Pumps Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Mobile, Fixed, Comprehensive Application: Surgery, Wound Care, Emergency Care, ICU End User: Hospitals, Clinics, Ambulatory Surgical Centers, Homecare Technology: Electric, Manual, Battery Operated, Pneumatic |
| Companies Covered | Allied Healthcare Products, B. Braun, Stryker, Medela, STERIS, Medtronic, Olympus, Anand Medicaids, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Suction Pumps Market Emerging Trajectories
Digital pressure sensing and wireless telemetry are compressing the gap between electromechanical performance and real-time clinical feedback, while regulatory documentation burdens are reshaping competitive entry barriers.
Battery-operated surgical suction technology is decentralizing operative field management by eliminating tethered power dependencies. Ambulatory surgical centers in the United States are adopting cordless units at accelerated replacement cycles for rapid turnover suites. This mobility shift is compressing installed base concentration among fixed-installation electric system incumbents.
EU MDR post-market surveillance mandates for reusable suction canisters are extending product development timelines by demanding expanded clinical evidence packages. Manufacturers must now maintain vigilance databases tracking adverse events across distributed hospital networks. Class IIa device reclassifications are most acutely affecting European sterile fluid management system suppliers.
Hospital purchasing committees are unbundling suction pump procurement from broader OR capital equipment bundles, enabling standalone vendor selection. Specialized acute care sales teams are displacing general surgical device distributors in major United States health networks. This disintermediation is most visible in metropolitan systems with dedicated value analysis committees.
Surgical Suction Pumps Market Segmentation
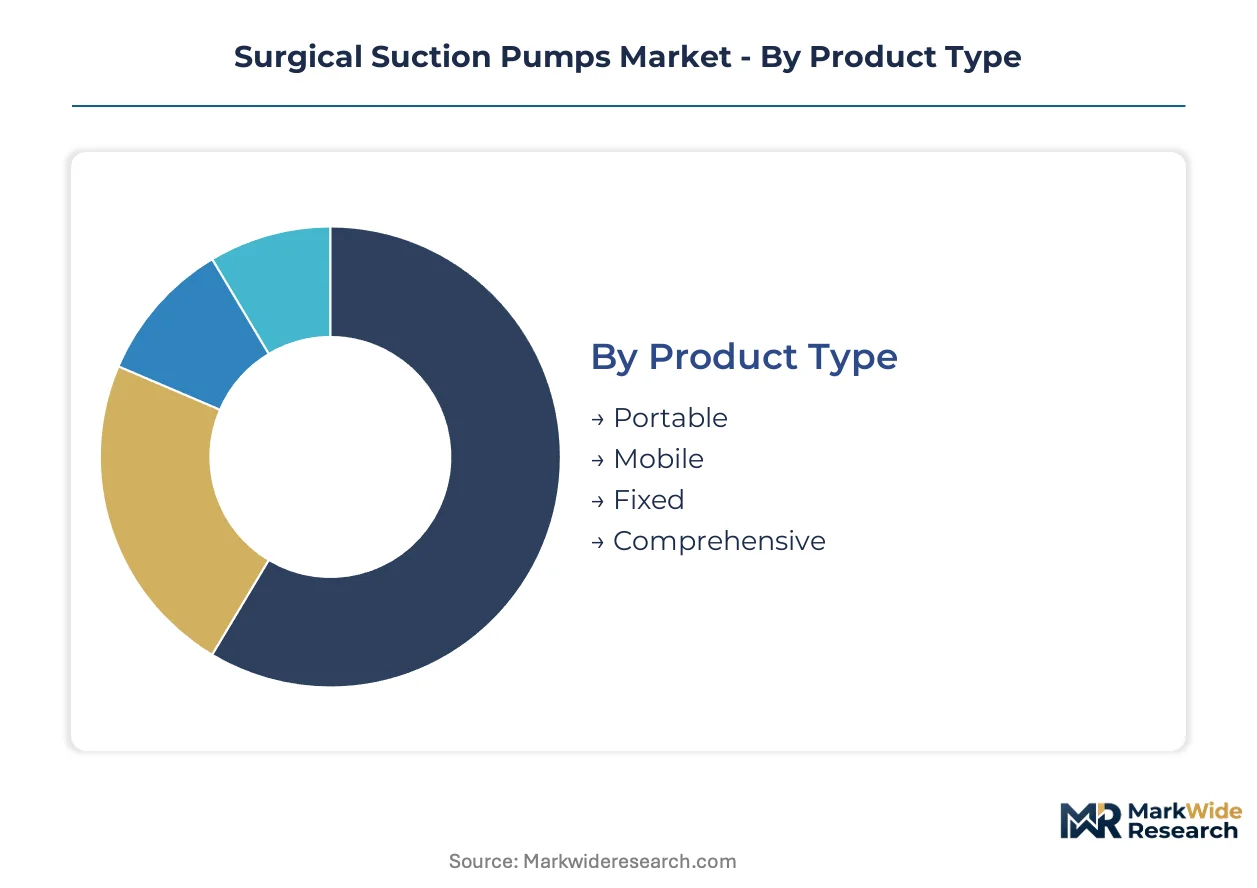
Surgical suction pumps serve distinct operational contexts ranging from embedded OR infrastructure to standalone emergency deployment. Segment boundaries reflect integration depth, power architecture, and care setting infrastructure requirements that dictate procurement priorities.
Product Type:
Standalone portable units operate independently of fixed gas or electrical infrastructure, while embedded fixed systems integrate directly into operating room ceiling booms and wall suction networks.
- Portable:Battery-powered or small electric units generating 80-200 mmHg negative pressure for field medicine and emergency transport. Demand concentrates in US ambulatory surgical centers prioritizing rapid suite turnover and space flexibility.
- Mobile:Wheeled electromechanical systems with intermediate vacuum capacity bridging fixed installation and true portability. German hospital networks favor these for inter-departmental flexibility without permanent infrastructure commitment.
- Fixed:Permanent wall or ceiling-mounted vacuum systems delivering sustained 600 mmHg output through centralized hospital suction plants. These dominate replacement cycles in US academic medical centers with dedicated OR infrastructure budgets.
- Comprehensive:Modular platforms combining portable, mobile, and fixed capabilities through interchangeable pump heads and power modules. Indian PLI scheme beneficiaries target these for export markets requiring flexible configuration.
Fixed systems lead volumes today; portable units are gaining share fastest.
Application:
Procedure-specific suction requirements vary by fluid viscosity, aspiration volume, and sterile field maintenance demands across operative and non-operative settings.
- Surgery:Open, laparoscopic, and endoscopic procedures requiring precise negative pressure control for blood and tissue debris evacuation. US metropolitan hospital networks with dedicated value analysis committees drive procurement concentration here.
- Wound Care:Negative pressure wound therapy systems applying sustained vacuum to promote granulation tissue formation. Homecare agencies in Germany and the United States are expanding rental programs for chronic wound management.
- Emergency Care:Rapid-deployment suction for airway clearance and trauma stabilization in pre-hospital and emergency department settings. Battery chemistry advances from South Korean cell manufacturers are enabling cordless deployment.
- ICU:Continuous respiratory secretion management and gastric decompression in ventilated patients. These applications demand integration with patient monitoring systems and alarm protocols.
Surgery commands the largest revenue pool; wound care is climbing the fastest.
End User:
Procurement authority and capital equipment replacement cycles diverge sharply between centralized hospital systems and distributed outpatient settings.
- Hospitals:Integrated delivery networks with dedicated biomedical engineering departments managing centralized suction infrastructure. US hospital capital expenditure on OR modernization sustains premium product demand.
- Clinics:Outpatient facilities performing minor procedures with lower suction volume requirements and compressed equipment footprints.
- Ambulatory Surgical Centers:Specialized same-day surgery facilities prioritizing rapid turnover, space efficiency, and portable equipment mobility. These settings are unbundling suction procurement from broader OR capital bundles.
- Homecare:Patient-directed negative pressure wound therapy and respiratory care with reimbursement-dependent equipment rental models.
Hospitals retain volume leadership; ambulatory surgical centers show the steepest expansion trajectory.
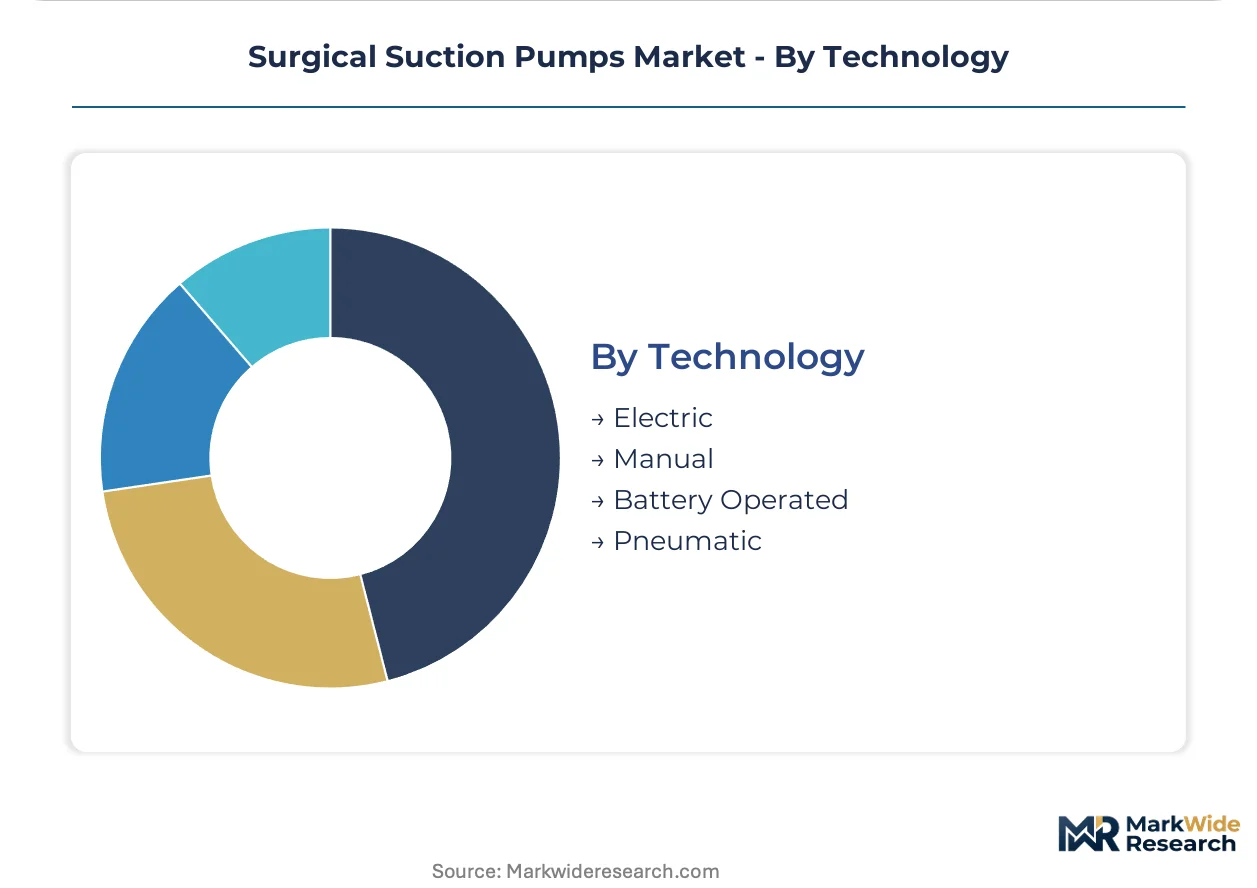
Technology:
Power architecture determines mobility, sustained output capacity, and regulatory classification pathways for market entry.
- Electric:AC-powered rotary vane or diaphragm pumps delivering consistent negative pressure for fixed installations. These systems anchor revenue in US and German hospital infrastructure replacement cycles.
- Manual:Hand-operated suction devices for emergency backup and resource-constrained settings requiring no power source.
- Battery Operated:Lithium-ion powered systems with cordless mobility for emergency care, military field medicine, and ambulatory surgical center rapid turnover suites. EU Battery Directive compliance requirements are reshaping design specifications.
- Pneumatic:Venturi-effect devices powered by compressed gas lines, common in operating rooms with existing medical gas infrastructure.
Electric technology dominates absolute volume; battery operated systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering clusters command premium vacuum pump assembly capacity while Indian production-linked incentives attract component suppliers seeking export positioning. This geographic divergence shapes procurement patterns across hospital networks and ambulatory surgical centers.
United States
Hospital capital expenditure on operating room modernization sustains fixed-installation suction system demand. FDA 510(k) clearance pathways for powered suction devices extend development timelines and elevate compliance costs. Metropolitan health networks in Texas and California unbundle suction procurement from broader OR capital equipment bundles.
Germany
Precision engineering clusters in Baden-Württemberg recalibrate production schedules to address backlog in vacuum pump assemblies. EU MDR conformity assessments for reusable suction canisters filter smaller manufacturers from institutional procurement lists. Stuttgart-based sterile device hubs sustain catheter-to-pump bundling contracts across European hospital networks.
India
Production-linked incentive schemes for medical device manufacturing attract sterile component suppliers to establish hub capacity. CDSCO medical device regulations align with international standards to facilitate export market access. Maharashtra and Gujarat manufacturing corridors target modular suction platform production for Middle East and African markets.
Japan
Aging demographics expand procedural volumes in acute care settings requiring sustained negative pressure systems. PMDA regulatory frameworks enforce biocompatibility documentation standards comparable to EU MDR requirements. Osaka and Nagoya industrial zones concentrate electromechanical pump component fabrication for domestic and regional supply.
South Korea
Battery chemistry advances from domestic cell manufacturers enable cordless surgical suction system development. MFDS medical device approval pathways accommodate accelerated review for emergency care equipment. Seoul metropolitan area electronics clusters supply pressure sensor and IoT telemetry components for next-generation portable units.
Surgical Suction Pumps Market Vendor Landscape
German and Swiss producers anchor the premium tier; US specialists hold dominant positions in acute care sales channels. Market structure concentrates among integrated surgical device conglomerates and dedicated fluid management system suppliers. Three archetypes prevail: sterile device bundlers, acute care sales specialists, and precision vacuum technology originators. Competitive moves center on dedicated sales team expansion and backward integration into sterile component manufacturing.
Among diversified surgical device conglomerates, Stryker and Medtronic exemplify scale-driven positioning through dedicated hospital network relationships. B. Braun occupies a position within the European sterile device bundler archetype, leveraging integrated manufacturing footprints. Medela represents the precision vacuum technology specialist segment, extending lactation-derived know-how into surgical fluid management applications.
| Leading Market Players |
|---|
| Allied Healthcare Products |
| B. Braun |
| Stryker |
| Medela |
| STERIS |
| Medtronic |
| Olympus |
| Anand Medicaids |
| Cardinal Health |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FDA-cleared Class II devices and unregistered regional alternatives manifests in both procurement premiums and supplier qualification barriers. Hospital networks in the United States and Germany pay substantial markups for validated vacuum assemblies while manufacturers in India and China compete on component cost without institutional access.
Pricing Analysis
Distributor margins absorb 25-40 points of end-user price in traditional hospital supply channels. Three-tier pricing structure across premium, standard, and economy levels separates German-engineered fixed installations from mobile electromechanical systems and basic portable units. Pricing pressure stems from ambulatory surgical centers unbundling suction procurement from broader OR capital bundles. Price sensitivity concentrates among ASC value analysis committees, while academic medical centers prioritize performance specifications over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from US hospital networks mandate qualified suppliers for rare earth magnets and lithium-ion cells across both Chinese and South Korean origins. Brushless DC motor assemblies draw from precision engineering clusters in Germany and Japan, while sterile canister molding concentrates in Malaysian and Thai contract facilities. Single-source vulnerability in neodymium magnet processing exposes pump manufacturers to export quota disruptions. Distribution runs through specialized surgical device distributors and direct-to-ASC sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
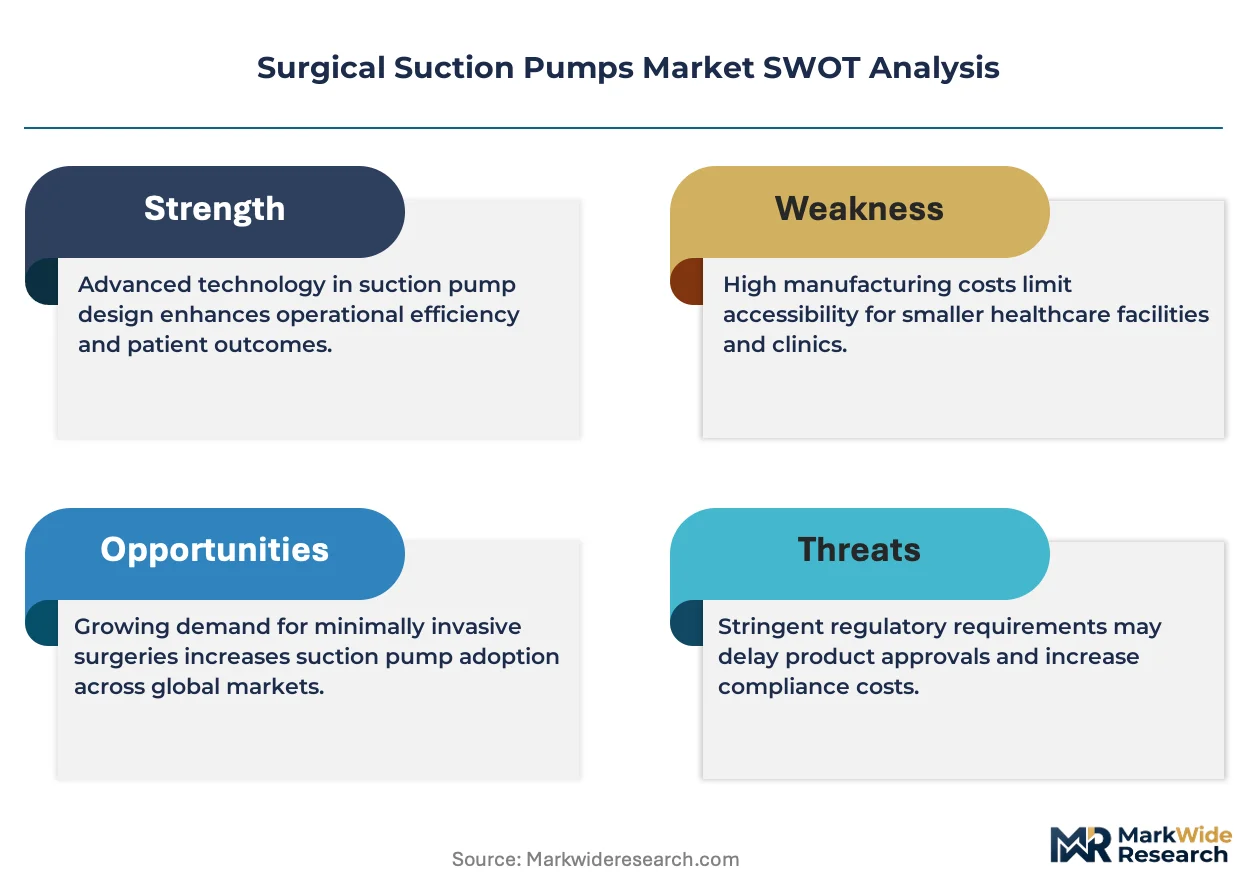
This market compounds regulatory validation into sustainable competitive position, with EU MDR conformity assessments and FDA 510(k) pathways extending development timelines that filter undercapitalized entrants.
For Market Incumbents: Hedge against cordless disruption by acquiring battery thermal management capabilities from South Korean electronics suppliers. Secure catheter-to-pump bundling contracts through backward integration into sterile component manufacturing. Consolidate position in fixed-installation hospital infrastructure before ASC replacement cycles accelerate. For New Entrants and Emerging Players: Direct-to-ASC e-commerce platforms bypass entrenched distributor relationships and purchasing committee gatekeeping. Target Indian PLI scheme beneficiaries seeking export positioning for modular comprehensive platforms. Penetrate Middle East and African markets through Maharashtra and Gujarat manufacturing corridors with CDSCO-aligned documentation. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance costs exceed smaller manufacturers' capital reserves. Long-term viability favors precision vacuum technology specialists with proprietary pump head designs over commodity assemblers. Monitor MFDS accelerated review pathways for emergency care equipment as signal of cordless technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance pathways for powered suction devices elevate compliance barriers against unregistered competitors. |
| CE Marking Pathway | EU MDR conformity assessments filter smaller manufacturers from European institutional procurement lists. |
| Hospital System Partnership | Integrated delivery network contracts anchor fixed-installation replacement cycles in academic medical centers. |
| Software Companion Development | IoT telemetry integration enables predictive maintenance contracts and real-time suction performance monitoring. |
| Reimbursement Strategy | Homecare agency rental programs for negative pressure wound therapy expand addressable market beyond acute care. |
Methodological Framework
Coverage spans the United States, Germany, India, Japan, and South Korea, with primary inputs from each market cluster. The approach combines structured interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and sterile device procurement leads with secondary validation from FDA 510(k) filings, EU MDR technical documentation, hospital capital expenditure databases, and CDSCO medical device registration records. Bottom-up unit demand modeling triangulates against top-down market sizing.
Granularity extends to product type, application, end user, and technology segments with regional regulatory cluster differentiation. CAGRs derive from procedure volume trajectories, capital equipment replacement cycles, and cordless technology penetration curves across the projection horizon. Modeled inputs include ambulatory surgical center expansion rates, battery chemistry energy density improvements, and EU Battery Directive compliance cost pass-through.
Regulatory timeline delays, raw material export quota volatility, and ASC capital budget freezes are the dominant revision risks to modeled assumptions. Forecasts reflect documented stakeholder input and validated secondary sources. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Surgical Instruments Market
Surgical Instruments
Germany General Surgical Devices Market
Surgical Instruments
Global Laparoscopic Instruments Market
Surgical Instruments
Surgical Visualization Market
Surgical Instruments
Medical Penlights Market
Surgical Instruments
Endoscopic Closure Systems Market
Surgical Instruments
Biosurgery Market
Surgical Instruments
Cryosurgery Market
Surgical Instruments
Europe Biosurgery Market
Surgical Instruments
Ophthalmology Surgical Devices Market
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Global Surgical Scalpel Market
Surgical Instruments
United Arab Emirates General Surgical Devices Market
Surgical Instruments
Hydrosurgery Systems Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Surgical Broaches Market