
 Surgical Site Infections Market | 2026-2036
Surgical Site Infections Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Site Infections Market Intelligence
Antimicrobial coating integration is narrowing the performance gap between passive and active barrier technologies in surgical drapes and implants. STERIS leverages integrated sterilization-to-delivery workflows that span preoperative preparation through postoperative monitoring. Johnson & Johnson anchors its position through sustained R&D investment in triclosan-alternative antiseptic formulations. Mölnlycke Health Care differentiates via proprietary soft silicone adhesive platforms that reduce skin trauma during dressing changes.
Surgical site infections are localized infections occurring at or near surgical incisions within thirty days of procedure, typically involving bacterial colonization of subcutaneous tissue, fascia, or organ spaces, with Staphylococcus aureus and coagulase-negative staphylococci representing predominant pathogens. The primary commercial purpose spans prevention through preoperative antisepsis, intraoperative barrier maintenance, and postoperative wound surveillance to reduce morbidity, readmission, and associated healthcare expenditure. Antiseptics occupy the largest revenue pool within product type segmentation, driven by mandatory preoperative skin preparation protocols, while negative pressure wound therapy represents the fastest-growing technology segment as hospitals adopt closed-incision systems for high-risk procedures. Hospitals dominate end user demand, though ambulatory surgical centers are gaining share as outpatient orthopedic and plastic surgery volumes expand.
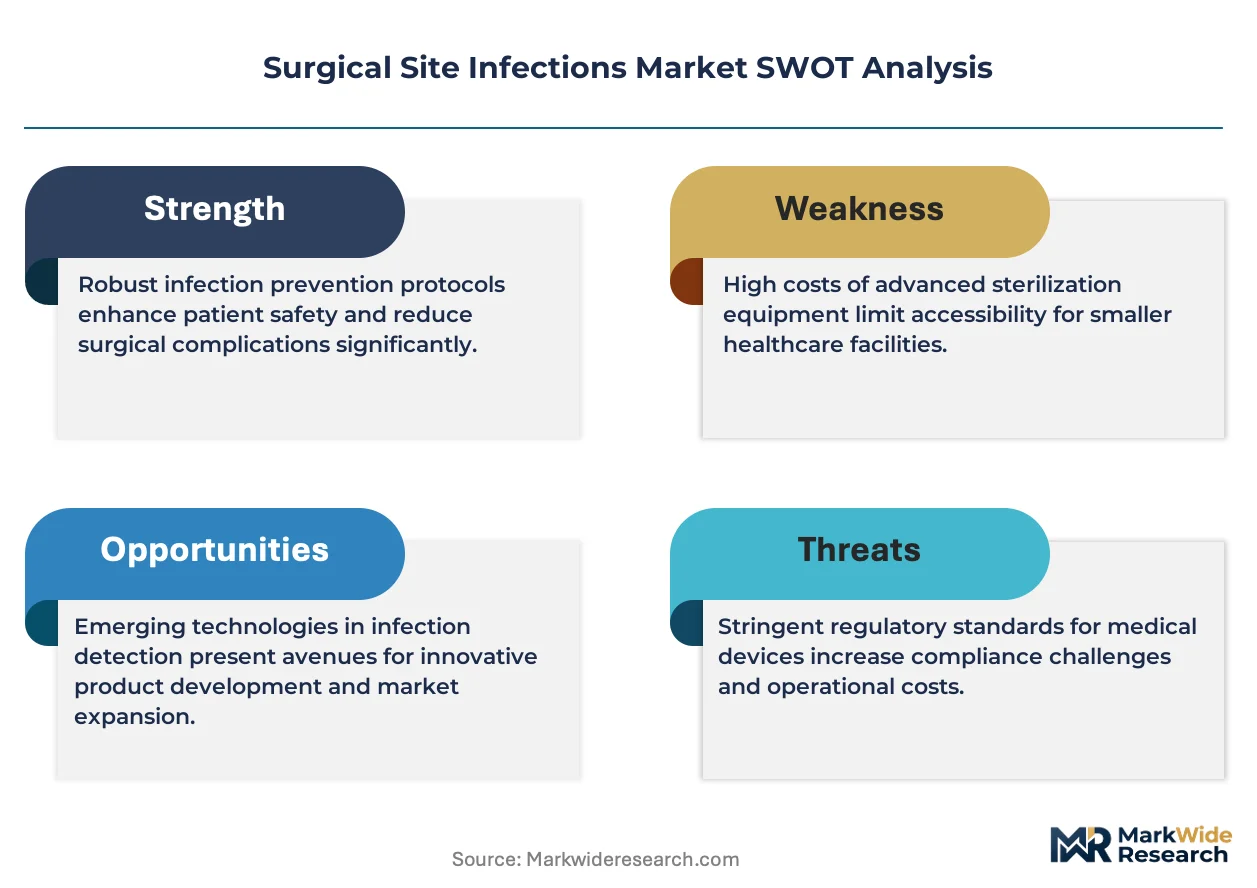
The FDA enforces premarket notification requirements for antimicrobial devices and monitors antiseptic efficacy claims under ongoing safety reviews, while the EPA regulates hospital disinfectant chemistries through pesticide registration pathways. ISO 14644 cleanroom standards and WHO surgical safety checklists shape international facility design and procedural compliance benchmarks. Stakeholders must monitor evolving resistance profiles against chlorhexidine-alcohol combinations and assess diagnostic technology shifts toward rapid molecular pathogen identification.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while elevating performance benchmarks for antiseptic efficacy and barrier technologies, forcing suppliers to demonstrate measurable readmission reduction rather than product features alone.
Growth Catalysts
- FDA Preoperative Skin Preparation Guidance:Updated efficacy benchmarks mandate higher antiseptic performance standards, accelerating hospital replacement cycles for chlorhexidine-alcohol formulations.
- Ambulatory Surgical Center Expansion:Outpatient orthopedic and plastic surgery volumes are expanding addressable demand for closed-incision negative pressure systems.
- WHO Surgical Safety Checklists:International facility compliance protocols are standardizing infection prevention infrastructure across emerging hospital networks.
Market Restraints
- Chlorhexidine Resistance Surveillance:Pathogen adaptation to standard antiseptic chemistries is narrowing effective prophylaxis windows and driving R&D recalibration.
- EPA Pesticide Registration Pathways:Hospital disinfectant approval timelines extend commercialization cycles for novel antimicrobial formulations.
- Single-Use Barrier Cost Structure:Raw material volatility in medical-grade polymers pressures margin stability for drape and gown manufacturers.
Strategic Opportunities
- Rapid Molecular Pathogen Identification:Diagnostic technology convergence with perioperative workflows enables targeted prophylaxis selection.
- Closed-Incision Negative Pressure Therapy:High-risk procedure segments remain underpenetrated relative to open wound applications.
- Integrated Sterilization-to-Delivery Workflows:Vendor consolidation of preoperative preparation through postoperative monitoring creates service differentiation.
Industry Challenges
- ISO 14644 Cleanroom Certification:Facility upgrade timelines for international manufacturing compliance compress capital deployment windows.
- Antimicrobial Device Premarket Notification:FDA documentation requirements for novel coating technologies extend development-to-revenue intervals.
- Legacy Wound Surveillance Integration:Electronic health record compatibility gaps complicate automated infection detection deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Site Infections Market |
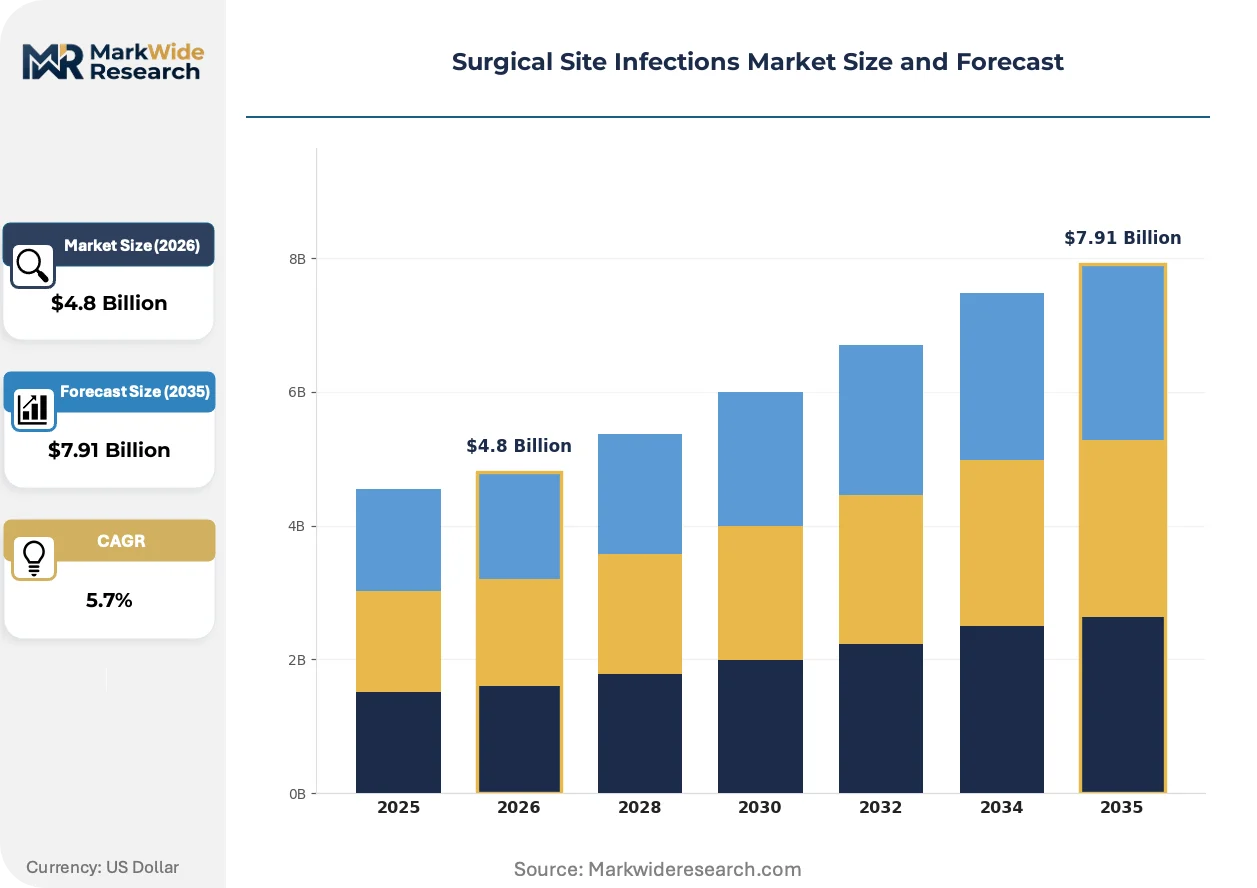
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiseptics, Antibiotics, Dressings, Disinfectants, Surgical Meshes Application: Cardiovascular Surgery, Orthopedic Procedures, General Surgery, Neurosurgery, Plastic Surgery End User: Hospitals, Ambulatory Surgical Centers, Clinics, Long-term Care Facilities, Specialty Centers Technology: Barrier Techniques, Negative Pressure Wound Therapy, Antimicrobial Coatings, Rapid Diagnostic Testing, UV Sterilization |
| Companies Covered | 3M, Getinge Group, STERIS, Becton, Dickinson and Company, Johnson & Johnson, Medtronic, Belimed, Mölnlycke Health Care, Ecolab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Site Infections Market Strategic Shifts & Innovations
Perioperative care is converging around closed-loop data systems that tie antiseptic application to postoperative outcomes, compressing the feedback cycle between intervention and measurable infection prevention.
Closed-incision negative pressure wound therapy is digitizing surgical site monitoring through integrated pressure sensors and automated drainage measurement. High-risk orthopedic and cardiothoracic units are adopting these systems at accelerated pace. This technology is digitizing postoperative surveillance from passive observation to continuous data capture, enabling earlier intervention triggers.
The EPA's updated hospital disinfectant registration framework is tightening efficacy claim substantiation requirements for antimicrobial chemistries. Manufacturers must now provide extended resistance surveillance data before market authorization. Antiseptic suppliers with existing pesticide registrations face lower compliance friction than novel entrants.
Hospital network procurement centralization is consolidating infection prevention purchasing decisions into system-level committees. Individual facility autonomy is contracting as integrated delivery networks standardize formulary selection. This pattern is most visible in United States metropolitan markets where hospital consolidation has advanced furthest.
Surgical Site Infections Market Segmentation
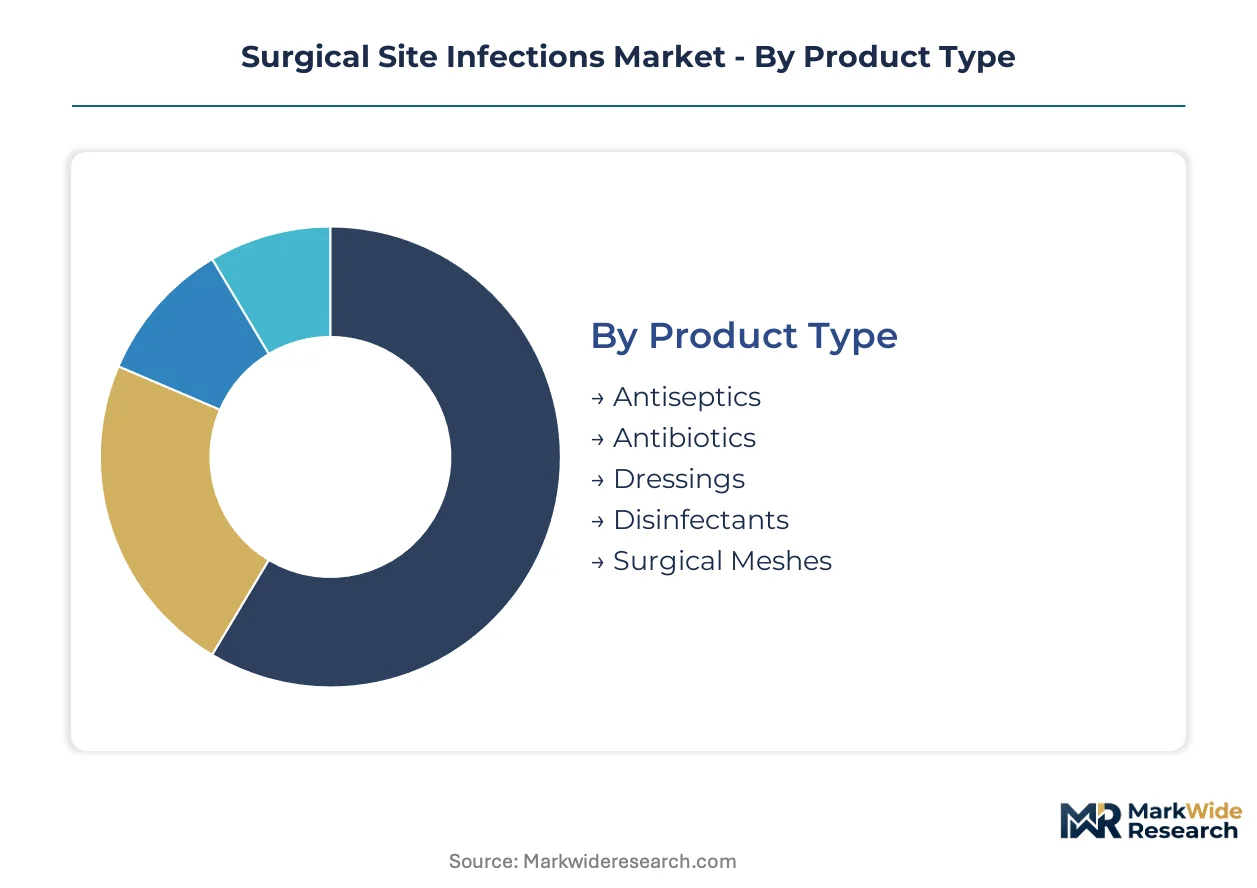
Surgical site infection prevention demands precise matching of intervention modality to procedure risk profile. Segmentation reveals where procurement budgets concentrate and which technology categories command premium positioning.
Product Type:
Antiseptics turn over fastest through mandatory preoperative application protocols, while surgical meshes cycle slowest via implant permanence. Antibiotics and disinfectants occupy intermediate replacement rhythms driven by formulary revision schedules.
- Antiseptics:Chlorhexidine-alcohol and povidone-iodine formulations dominate preoperative skin preparation protocols. United States hospital networks are consolidating procurement around efficacy-validated combinations as FDA guidance tightens performance benchmarks.
- Antibiotics:Prophylactic systemic administration targets Staphylococcus aureus and coagulase-negative staphylococci colonization. Resistance surveillance programs in tertiary care centers are narrowing formulary options and accelerating therapeutic substitution cycles.
- Dressings:Absorbent and occlusive variants manage postoperative exudate and barrier maintenance.
- Disinfectants:Surface and instrument chemistries require EPA pesticide registration compliance.
- Surgical Meshes:Implantable barriers for hernia and soft tissue reconstruction carry permanent placement characteristics.
Antiseptics dominate installed base. Antibiotics is where expansion concentrates.
Application:
Orthopedic procedures concentrate device expenditure through implant burden, while general surgery fragments across diverse intervention types. Cardiovascular and neurosurgery command specialized protocol premiums.
- Cardiovascular Surgery:Sternotomy and thoracotomy sites present elevated infection risk due to prosthetic valve and graft placement. United States academic medical centers are standardizing closed-incision negative pressure protocols for coronary artery bypass populations.
- Orthopedic Procedures:Joint arthroplasty and spinal instrumentation drive substantial antimicrobial consumption through prolonged operative duration and implant burden. Ambulatory surgical centers are expanding hip and knee replacement volumes, shifting prophylaxis demand patterns.
- General Surgery:Abdominal and soft tissue interventions span broad risk stratification.
- Neurosurgery:Craniotomy and spinal cord procedures require specialized barrier maintenance.
- Plastic Surgery:Aesthetic and reconstructive applications emphasize cosmetic outcome preservation alongside infection prevention.
General surgery dominates procedure volume. Orthopedic procedures is where value expansion concentrates.
End User:
Hospitals anchor capital-intensive technology deployment, while ambulatory surgical centers expand fastest through outpatient migration. Long-term care and specialty centers occupy niche maintenance roles.
- Hospitals:Inpatient surgical suites integrate comprehensive infection prevention infrastructure from preoperative preparation through intensive care surveillance. United States integrated delivery networks are centralizing procurement decisions into system-level infection control committees.
- Ambulatory Surgical Centers:Outpatient orthopedic and plastic surgery volumes are expanding closed-incision negative pressure adoption for same-day discharge protocols. Medicare reimbursement shifts are accelerating site-of-service migration.
- Clinics:Minor procedure settings require streamlined antiseptic protocols.
- Long-term Care Facilities:Post-acute wound management extends surveillance into rehabilitation phases.
- Specialty Centers:Dedicated cardiovascular and orthopedic facilities concentrate procedure-specific expertise.
Hospitals dominate technology infrastructure. Ambulatory surgical centers is where patient volume expansion concentrates.
Technology:
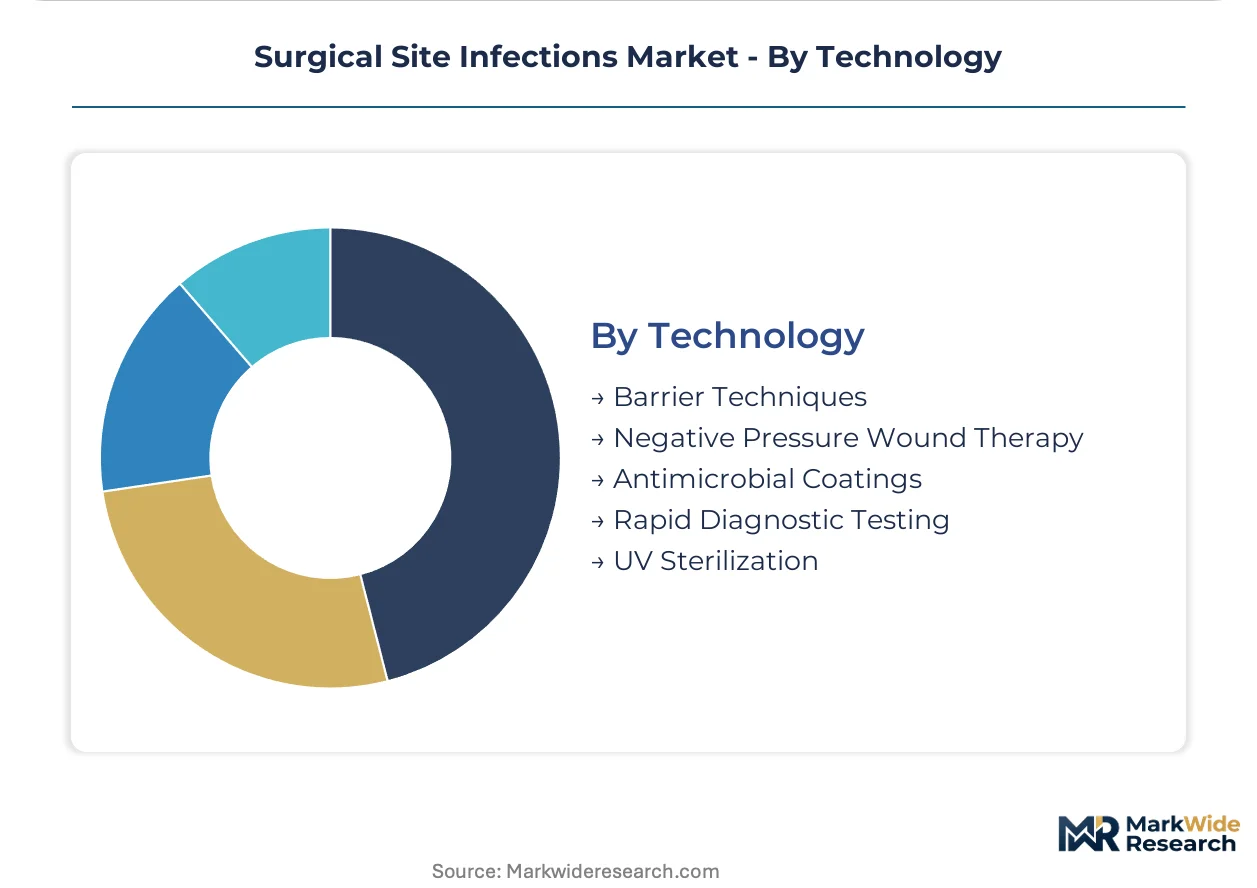
Barrier techniques constitute mature installed base with stable replacement cycles, while rapid diagnostic testing accelerates through molecular platform adoption. Negative pressure wound therapy and antimicrobial coatings occupy growth-phase investment profiles.
- Barrier Techniques:Surgical drapes, gowns, and sterile field maintenance represent foundational passive protection. Raw material volatility in medical-grade polymers pressures margin stability for disposable manufacturers.
- Negative Pressure Wound Therapy:Closed-incision systems digitize postoperative surveillance through integrated pressure sensors and automated drainage measurement. High-risk orthopedic and cardiothoracic units are adopting these systems at accelerated pace.
- Antimicrobial Coatings:Active surface treatments on implants and drapes narrow performance gaps with systemic prophylaxis.
- Rapid Diagnostic Testing:Molecular pathogen identification enables targeted perioperative antibiotic selection.
- UV Sterilization:Environmental decontamination supplements chemical protocols in operating suite turnover.
Barrier techniques dominate installed base. Negative pressure wound therapy is where technology investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consolidation concentrates purchasing power among integrated delivery networks in the United States, while ambulatory surgical center expansion redistributes procedural volumes across outpatient settings. Regulatory divergence between FDA premarket pathways and EPA pesticide registrations creates compliance complexity for multinational suppliers.
United States
Integrated delivery networks in metropolitan markets centralize infection prevention procurement into system-level committees. FDA premarket notification requirements for antimicrobial devices shape development timelines for novel coating technologies. The Cleveland Clinic and Mayo Clinic anchor tertiary care adoption of closed-incision negative pressure systems.
Germany
Tertiary care centers standardize WHO surgical safety checklist compliance across federal hospital networks. EMA device regulation and DIN standards for cleanroom certification elevate manufacturing benchmarks. The Rhine-Ruhr medical technology cluster concentrates sterilization equipment production and antiseptic formulation R&D.
China
Provincial hospital tier systems drive volume demand for cost-optimized barrier technologies in second-tier cities. NMPA medical device registration pathways extend commercialization timelines for imported antimicrobial coatings. The Yangtze River Delta medical device manufacturing belt scales domestic production of surgical drapes and sterile field maintenance products.
Japan
Academic medical centers prioritize rapid molecular pathogen identification integration with perioperative workflows. PMDA quality management system audits enforce documentation rigor for antimicrobial device manufacturers. The Kanto region's university hospital networks pilot closed-loop data systems linking antiseptic application to postoperative outcomes.
India
Corporate hospital chains expand infection prevention infrastructure as medical tourism volumes recover. CDSCO medical device rules and BIS standards for disinfectant efficacy create dual compliance obligations. The Maharashtra-Gujarat pharmaceutical corridor attracts contract manufacturing for chlorhexidine-alternative antiseptic formulations.
Surgical Site Infections Market Key Industry Players
Channel-controlling players compete with product-specialist players across procurement consolidation and technology differentiation vectors. The vendor base organizes around three strategic archetypes: integrated sterilization-to-delivery workflow providers, antiseptic formulation specialists, and barrier technology fabricators. M&A activity concentrates among sterilization equipment manufacturers acquiring diagnostic monitoring capabilities. Portfolio diversification into closed-incision negative pressure systems represents the dominant competitive move.
Among diversified health care conglomerates, 3M and Johnson & Johnson occupy positions spanning antiseptics through barrier technologies. STERIS exemplifies the integrated workflow archetype with sterilization-to-monitoring capabilities. These three companies anchor the competitive structure through distinct channel control strategies rather than overlapping product specialization.
| Leading Market Players |
|---|
| 3M |
| Getinge Group |
| STERIS |
| Becton, Dickinson and Company |
| Johnson & Johnson |
| Medtronic |
| Belimed |
| Mölnlycke Health Care |
| Ecolab |
| Others |
Cost & Logistics Intelligence
Chinese medical-grade polymer manufacturers anchor upstream supply for surgical drapes and barrier fabrics, concentrating margin capture in downstream antiseptic formulation and closed-incision system assembly where FDA validation creates pricing power.
Pricing Analysis
Cost-plus contracts with chlorhexidine feedstock indexation dominate antiseptic procurement between hospital networks and formulation suppliers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated combinations from institutional-grade alternatives and private-label economy tiers. Pricing pressure stems from integrated delivery network formulary consolidation forcing volume commitments for contract access. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement compression, while academic medical centers prioritize efficacy validation over unit cost.
Supply Chain Analysis
Contract manufacturing for sterile barrier fabrics concentrates in China's Yangtze River Delta medical device belt, India's Maharashtra-Gujarat pharmaceutical corridor, and Germany's Rhine-Ruhr sterilization equipment cluster. Raw material dependencies center on medical-grade polypropylene nonwovens, chlorhexidine gluconate active pharmaceutical ingredients, and silicone adhesive polymers. Single-source vulnerability runs through Chinese polymer feedstock concentration amid export license unpredictability. Distribution runs through group purchasing organizations and integrated delivery network central procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surgical site infections market is experiencing high-growth disruption as closed-incision negative pressure therapy digitization converges with FDA preoperative skin preparation guidance tightening efficacy benchmarks.
For Market Incumbents: Harden antiseptic formulation portfolios against chlorhexidine resistance surveillance by accelerating triclosan-alternative R&D through captive laboratory investment. Deepen backward integration into medical-grade polymer production to defend margin position against raw material volatility. Secure ISO 14644 cleanroom certification ahead of international manufacturing compliance deadlines to maintain barrier technology contract access.
For New Entrants and Emerging Players: India's corporate hospital chains present underpenetrated demand for rapid molecular pathogen identification integration with perioperative workflows. Target closed-incision negative pressure therapy adoption in Japan's Kanto region university hospital networks piloting closed-loop data systems. Pursue hospital system partnership go-to-market angles emphasizing measurable readmission reduction rather than product feature differentiation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across antimicrobial coating manufacturing as EPA pesticide registration pathways extend commercialization timelines for novel formulations. Long-term viability favors sterilization-to-delivery workflow integrators with diagnostic monitoring capabilities over single-product antiseptic specialists. Monitor FDA premarket notification approval velocity for antimicrobial devices as inflection indicator for coating technology valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Accelerates hospital formulary access for chlorhexidine-alternative antiseptic combinations. |
| Hospital System Partnership | Locks in multi-year closed-incision negative pressure therapy procurement through integrated delivery networks. |
| Backward Integration | Captures medical-grade polymer margin pools currently concentrated in Chinese contract manufacturers. |
| Software Companion Development | Enables digitized postoperative surveillance linking antiseptic application to infection outcomes. |
| Reimbursement Strategy | Secures Medicare coverage for ambulatory surgical center same-day discharge protocols. |
Research Approach
The analysis maps antiseptic formulations, barrier technologies, negative pressure systems, and rapid diagnostic platforms, each validated through infection control committee chairs, biomedical engineers, GPO contracts managers, and antiseptic formulation R&D directors. Primary interviews with hospital procurement leaders and ambulatory surgical center administrators combined with secondary validation from FDA 510(k) filings, EPA pesticide registration databases, hospital procurement contracts, and CMS Medicare reimbursement schedules. Bottom-up unit demand modeling and top-down healthcare expenditure allocation provided cross-verification across the analysis window.
Assumption sets held regulatory pathway timelines and resistance surveillance patterns fixed while varying ambulatory surgical center volume migration rates and integrated delivery network consolidation velocity. Segmentation dimensions modeled include product type, application risk profile, end-user facility category, and technology maturity tier. CAGRs were derived from procedural volume elasticity to demographic aging and surgical site infection rate reduction targets. Forecast inputs incorporated WHO surgical safety checklist adoption curves and EPA registration framework revision impacts.
Practitioners should monitor chlorhexidine resistance surveillance data, FDA premarket notification approval queues, and integrated delivery network procurement centralization announcements for early signals of forecast revision necessity. Quarterly review of hospital network formulary revision cycles and ambulatory surgical center Medicare reimbursement rate adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Hand Sanitizer Spray Market
Infection Control
Multi-Surface Disinfection Booster Systems with Low QAC Load Market
Infection Control
Point of Care Infection Control Market
Infection Control
Botulism Market
Infection Control
Global Hospital Disinfectant Products and Services Market
Infection Control
Disinfection Equipment Market
Infection Control
Virus Filtration Market
Infection Control
Australia Hand Sanitizer Market
Infection Control
Ultrasound Probe Disinfection Market
Infection Control
Community Acquired Pneumonia (CAP) Market
Infection Control
South Africa Antibacterial Soap Market
Infection Control
Antimicrobial Wipes Market
Infection Control
Ultraviolet Disinfection Equipment Market
Infection Control
Steam and Hydrogen Peroxide Biological Indicators Market
Infection Control
Global Sepsis Therapeutics Market
Infection Control
Global Dental Infection Control Products Market