
 Spain General Surgical Devices Market | 2026-2036
Spain General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Spain General Surgical Devices Market Analytics
Modular surgical kit bundling is pivoting hospital procurement patterns across Spain's national health system. Johnson & Johnson leverages its broad suture and stapling portfolio to anchor large-volume contracts with public hospital consortia. B. Braun Melsungen AG sustains manufacturing proximity through its Spanish production facilities, competing on logistics responsiveness for scheduled surgical procedures. Medtronic PLC differentiates through integrated energy platforms that combine electrosurgical generators with specialty instruments.
General surgical devices encompass handheld and powered instruments, disposable consumables, and accessory systems employed in open and minimally invasive procedures, typically manufactured from medical-grade stainless steel, polymers, or ceramic composites and sterilized to ISO 11135 or ISO 17665 standards before clinical use. Surgical sutures and electrosurgical platforms command the deepest margin pools as hospitals consolidate spend around proven wound closure and energy-based tissue management technologies. Forceps and scalpel segments retain stable volume positions in Spain's ambulatory surgery centers where cost-per-procedure sensitivity shapes purchasing.
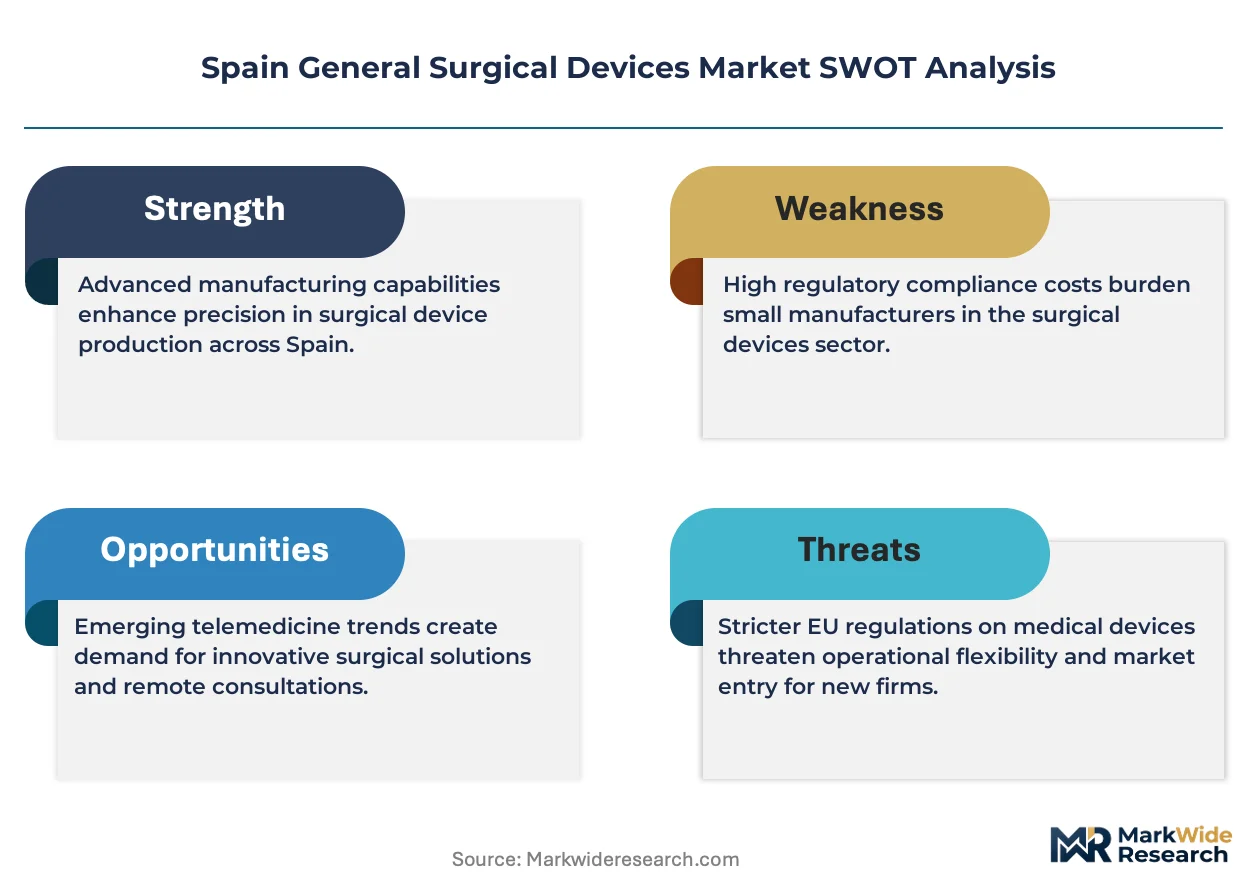
Spain's Ministry of Health and the Spanish Agency for Medicines and Health Products enforce CE marking compliance under EU Medical Device Regulation transition timelines, while ISO 13485 certification remains mandatory for domestic manufacturers and importers accessing public tenders. Stakeholders must monitor how regional health authority procurement consolidation affects vendor qualification criteria and long-term supply agreements.
Market Dynamics
Spain's public hospital procurement consolidation is compressing vendor margins while elevating technical qualification barriers for surgical device suppliers seeking national health system contracts.
Growth Catalysts
- EU Medical Device Regulation transition:CE marking upgrades under MDR timelines are filtering out marginal suppliers, concentrating contract awards among certified manufacturers with robust quality management systems.
- Minimally invasive procedure expansion:Madrid's hospital cluster and Catalonia's medical technology corridor are driving kit standardization for laparoscopic and robotic-assisted surgeries.
- Regional health authority consolidation:Andalusia and Valencia are merging procurement functions, creating larger-volume tenders that reward logistics-responsive suppliers with Spanish manufacturing presence.
Market Restraints
- Medical-grade stainless steel price volatility:Input cost swings for surgical-grade alloys compress margin pools on commoditized instruments like forceps and retractors.
- Single-source electrosurgical generator dependency:Hospital clusters in Basque Country and Galicia face supply concentration risk from limited domestic energy platform alternatives.
- ISO 13485 certification timeline friction:Extended audit backlogs for quality management system renewals delay new product introductions by Spanish manufacturers.
Strategic Opportunities
- Underpenetrated ambulatory surgery centers:Castile and León's outpatient surgical networks present volume expansion potential for cost-optimized disposable instrument portfolios.
- Integrated energy-platform convergence:Electrosurgical generator and specialty instrument bundling is creating preference lock-in among high-throughput hospital consortia.
- Reimbursement protocol modernization:Spain's Ministry of Health updated national healthcare framework reforms are expanding coverage for advanced wound closure technologies.
Industry Challenges
- Specialized surgical device sales force scarcity:Technical field specialists capable of OR-level training on energy platforms remain concentrated in Madrid and Barcelona.
- Legacy instrument sterilization infrastructure:ISO 11135 and ISO 17665 compliance upgrades require capital reinvestment at aging hospital central sterile supply departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain General Surgical Devices Market |
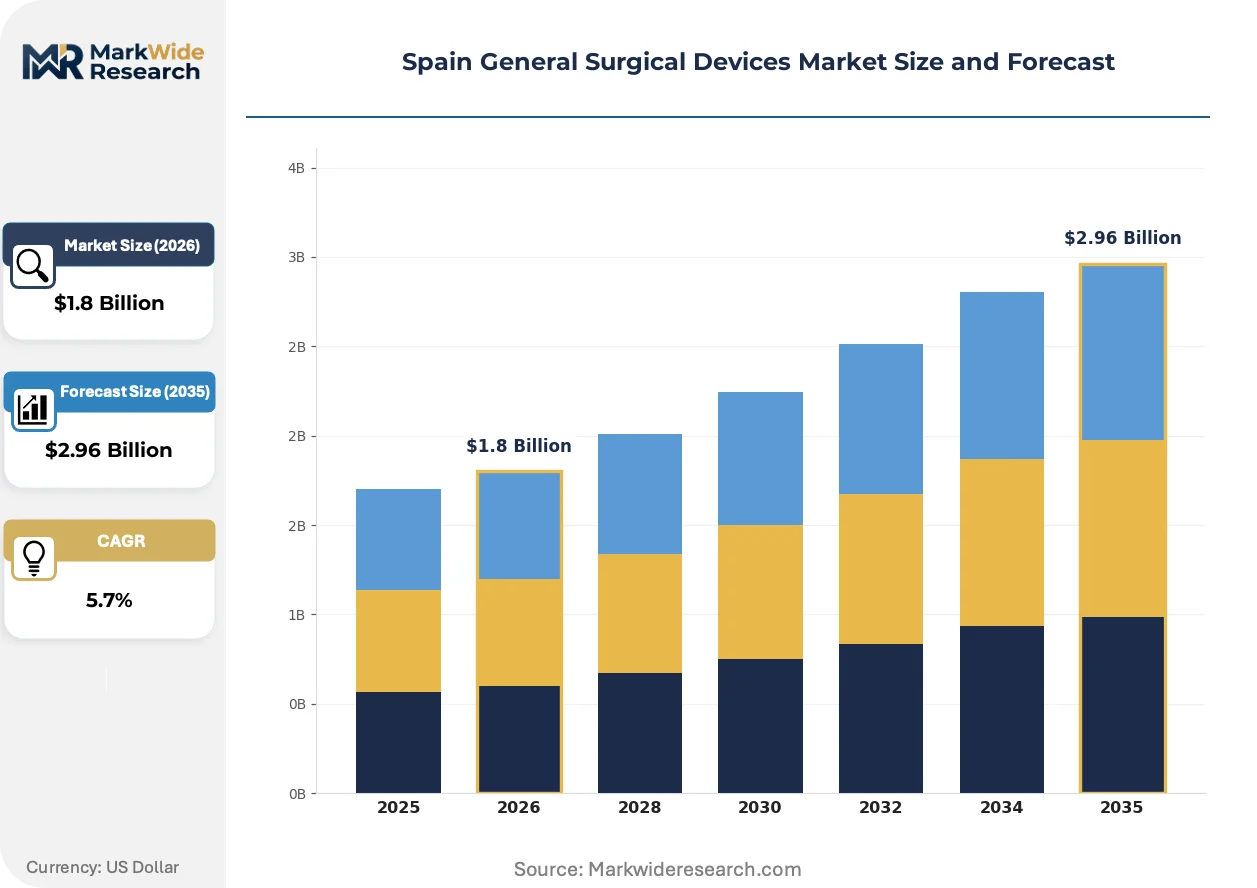
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Sutures, Forceps, Scalpels, Surgical Gloves End User: Hospitals, Ambulatory Surgery Centers, Clinics, Research Laboratories Application: Orthopedic, Cardiovascular, Gastrointestinal, Neurological Technology: Laparoendoscopic, Robotic-assisted, Electrosurgical, Ultrasonic |
| Companies Covered | Johnson & Johnson, CONMED Corporation, Boston Scientific Corporation, 3M Company, Olympus Corporation, Medtronic PLC, Stryker Corp., Smith & Nephew PLC, B. Braun Melsungen AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain General Surgical Devices Market Evolving Landscape
Modular surgical kit architectures are displacing standalone instrument purchasing across Spain's national health system, compressing supplier bases while elevating technical integration requirements.
Smart electrosurgical platforms with integrated tissue-sensing feedback are unifying generator and instrument control into single-vendor ecosystems. High-throughput hospital consortia in Madrid's cluster are adopting these systems for standardized laparoscopic workflows. This technology convergence is unifying purchasing decisions around energy platform vendors rather than discrete instrument suppliers.
Spain's Ministry of Health and the Spanish Agency for Medicines and Health Products are accelerating MDR compliance enforcement timelines for Class IIa and IIb surgical devices. Domestic manufacturers face compressed transition windows for technical documentation updates. Suture and stapling segments are responding with accelerated ISO 13485 quality system investments to maintain public tender eligibility.
Hospital procurement consortia are consolidating supplier panels through multi-year framework agreements with performance-based renewal clauses. Ambulatory surgery centers in Catalonia's corridor are displacing spot purchasing with scheduled kit replenishment contracts. This behavioral shift is most visible in Valencia's regional health authority, where cost-per-procedure metrics now dominate vendor selection criteria.
Spain General Surgical Devices Market Segmentation
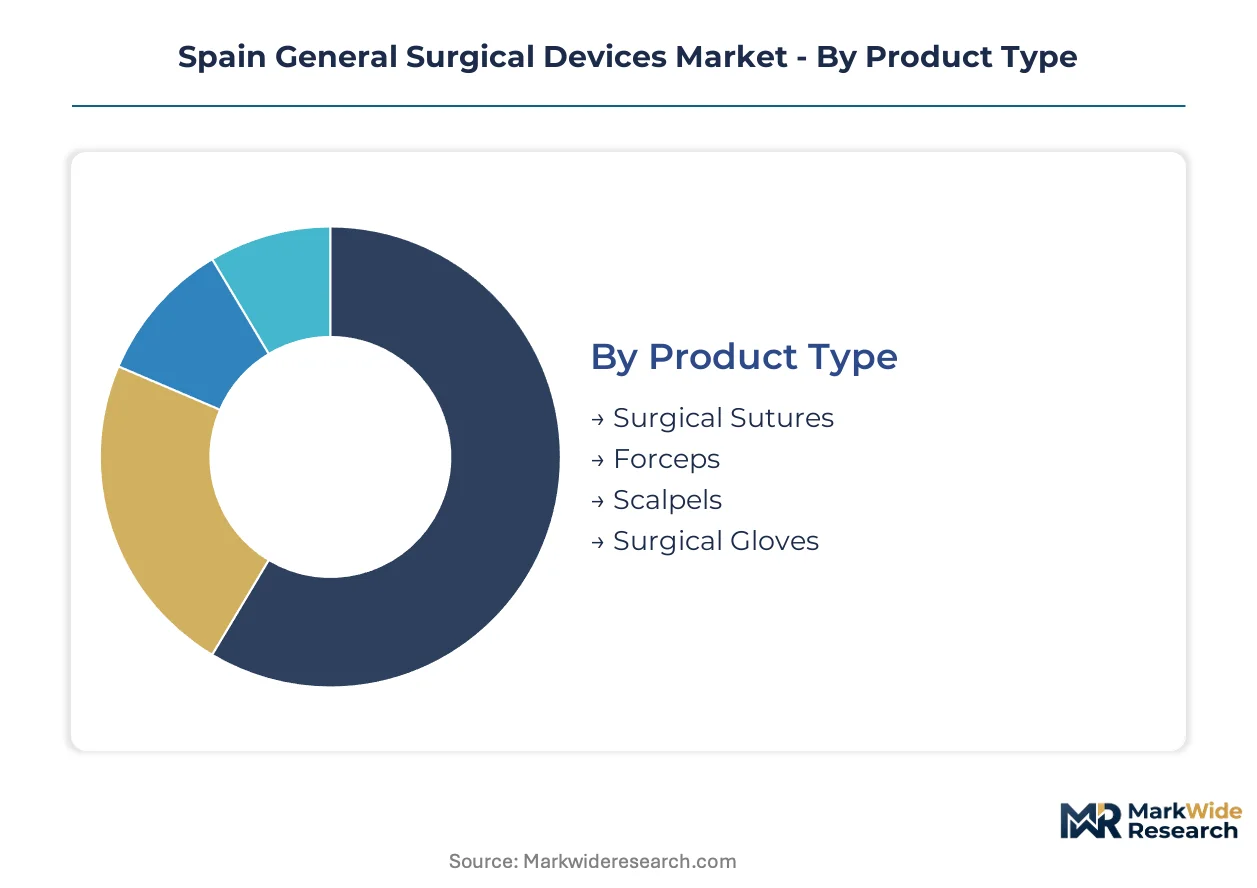
Surgical device procurement in Spain fragments across multiple technical and operational axes. Each segmentation layer reveals distinct margin structures, regulatory exposure, and vendor qualification requirements that shape competitive positioning within the national health system.
Product Type:
Material composition and sterilization compatibility define procurement tiers across Spain's public hospital networks.
- Surgical Sutures:Absorbable and non-absorbable configurations manufactured from synthetic polymers or natural collagen meet ISO 13485 quality benchmarks. Madrid's hospital cluster and Catalonia's medical technology corridor concentrate demand for advanced barbed and antimicrobial-coated variants under updated Ministry of Health reimbursement protocols.
- Forceps:Hemostatic and tissue-grasping instruments fabricated from medical-grade stainless steel or titanium alloys serve open and laparoscopic workflows. Ambulatory surgery centers in Castile and León drive volume for cost-optimized disposable forceps where cost-per-procedure sensitivity dominates purchasing criteria.
- Scalpels:Single-use carbon steel and reusable ceramic blade systems support precision incision requirements across general surgery departments.
- Surgical Gloves:Latex, nitrile, and neoprene barrier protection manufactured to EN 455 standards ensure infection control compliance in sterile fields.
Surgical sutures lead on scale; forceps lead on momentum as outpatient migration accelerates disposable adoption.
End User:
Facility scale and procedure throughput determine kit configuration complexity and vendor contract structures.
- Hospitals:Acute care institutions with central sterile supply departments manage high-volume instrument reprocessing and capital-intensive electrosurgical platform installations. Andalusia and Valencia regional health authority consolidation is merging procurement functions into larger-volume tenders rewarding logistics-responsive suppliers.
- Ambulatory Surgery Centers:Outpatient facilities prioritize disposable instrument portfolios and scheduled kit replenishment contracts over spot purchasing. Catalonia's medical technology corridor is displacing traditional procurement with cost-per-procedure metrics that favor streamlined vendor panels.
- Clinics:Smaller-scale surgical settings concentrate on wound closure consumables and basic handheld instruments for minor procedures.
- Research Laboratories:Academic and clinical research facilities source specialized instruments for experimental surgical protocols and device validation studies.
Hospitals anchor volume concentration; ambulatory surgery centers are expanding most quickly as regional networks proliferate.
Application:
Anatomical specialization drives instrument specification divergence and surgeon training requirements.
- Orthopedic:Bone saws, drills, and fixation systems require high-torque power sources and specialized sterilization protocols for metallic implant compatibility.
- Cardiovascular:Precision micro-instruments and sternal closure devices demand CE marking under EU Medical Device Regulation Class IIb timelines with enhanced clinical evidence requirements.
- Gastrointestinal:Endoscopic accessory channels and laparoscopic staplers support minimally invasive resection procedures with standardized kit configurations.
- Neurological:Microsurgical instruments with ergonomic handle designs and ultrasonic aspirators address delicate tissue manipulation in cranial and spinal access.
Gastrointestinal applications lead on scale; cardiovascular applications gain share fastest as structural heart procedure volumes rise.
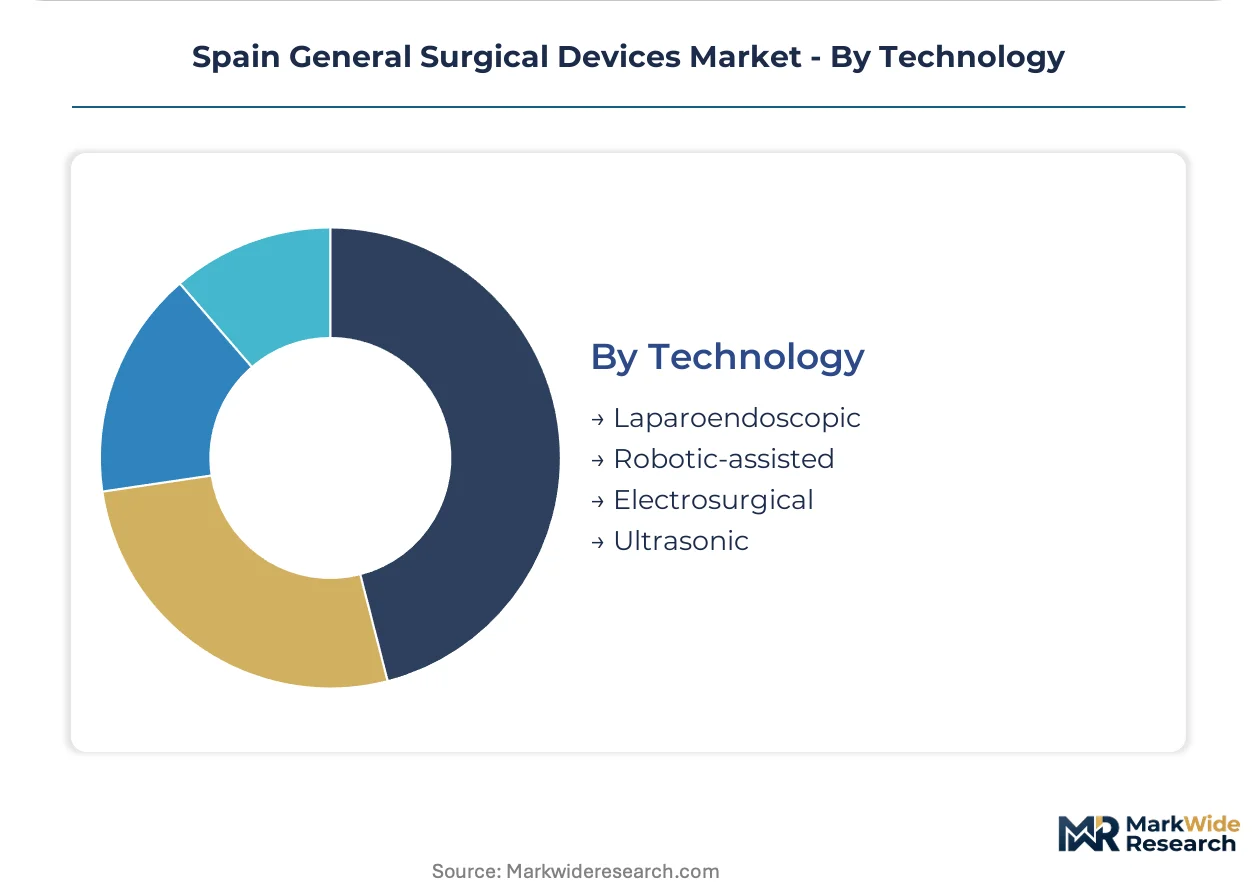
Technology:
Energy delivery mechanisms and control architectures differentiate platform ecosystems and create vendor lock-in effects.
- Laparoendoscopic:Video-assisted instrumentation with standardized trocar and port systems enables minimally invasive access across multiple surgical specialties. Madrid's hospital cluster is driving kit standardization for these workflows through consolidated procurement frameworks.
- Robotic-assisted:Telemanipulation platforms with articulated instrument wrists and haptic feedback systems command premium positioning in high-throughput hospital consortia. Basque Country and Galicia face supply concentration risk from limited domestic alternatives for integrated energy platform sourcing.
- Electrosurgical:Radiofrequency generators with monopolar and bipolar output modes provide hemostasis and tissue dissection through reusable and disposable handpieces.
- Ultrasonic:High-frequency mechanical vibration devices enable precise cutting with minimal thermal spread for sensitive anatomical regions.
Laparoendoscopic systems lead on scale; robotic-assisted platforms lead on momentum as capital investment cycles accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's surgical device industry traces its modern foundations to the 1980s expansion of public hospital networks under the national health system, with subsequent regional autonomy driving decentralized procurement evolution across autonomous communities.
Madrid
Madrid's hospital cluster concentrates the highest surgical procedure volumes in Spain, with twelve major acute care institutions driving demand for integrated energy platforms and minimally invasive instrument kits. The regional health authority enforces CE marking compliance under EU Medical Device Regulation timelines for all Class IIb device tenders. The capital's medical technology corridor around the Hospital Universitario La Paz anchors procurement standardization for laparoscopic workflows.
Catalonia
Catalonia's medical technology corridor generates substantial demand for disposable surgical consumables and scheduled kit replenishment contracts across its dense network of ambulatory surgery centers. The Catalan Health Service applies cost-per-procedure metrics that favor streamlined vendor panels with demonstrated logistics responsiveness. Barcelona's hospital consortium leads adoption of robotic-assisted surgical platforms for high-throughput procedures.
Basque Country
The Basque Country maintains specialized surgical capacity in cardiovascular and orthopedic interventions, with regional health authorities consolidating procurement for high-value electrosurgical generators. Spain's Ministry of Health reimbursement protocols under national healthcare framework reforms expanded coverage for advanced wound closure technologies here. Bilbao's hospital network faces supply concentration risk from limited domestic energy platform alternatives.
Andalusia
Andalusia's regional health authority is merging procurement functions across its eight provinces, creating larger-volume tenders that reward suppliers with Spanish manufacturing presence. The Junta de Andalucía enforces ISO 13485 certification requirements for all surgical device vendors accessing public tenders. Seville and Málaga anchor the southern concentration of outpatient surgical migration toward cost-optimized disposable portfolios.
Valencia
Valencia's regional health consolidation is compressing supplier margins while elevating technical qualification barriers for surgical device contracts across its three provinces. The Conselleria de Sanitat applies performance-based renewal clauses in multi-year framework agreements. The metropolitan hospital cluster is displacing spot purchasing with scheduled kit replenishment contracts for gastrointestinal and general surgery procedures.
Spain General Surgical Devices Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with broad surgical portfolios. Vendor qualification barriers under EU Medical Device Regulation transition timelines are filtering marginal participants, concentrating contract awards among established manufacturers with robust quality management systems. Three archetypes dominate: integrated platform vendors bundling generators with instruments, logistics-responsive suppliers with proximate manufacturing, and suture specialists anchoring wound closure procurement. Competitive moves center on multi-year framework agreements with performance clauses and backward integration into sterilization-compatible material production.
Among diversified conglomerates with Spanish market presence, Johnson & Johnson, Medtronic PLC, and B. Braun Melsungen AG occupy anchor positions within procurement networks. Johnson & Johnson exemplifies the integrated consumables archetype through its suture and stapling portfolio concentration. Medtronic PLC represents the energy-platform convergence strategy combining generator systems with specialty instruments. B. Braun Melsungen AG anchors the logistics-responsive tier through manufacturing proximity advantages for scheduled surgical procedures.
| Leading Market Players |
|---|
| Johnson & Johnson |
| CONMED Corporation |
| Boston Scientific Corporation |
| 3M Company |
| Olympus Corporation |
| Medtronic PLC |
| Stryker Corp. |
| Smith & Nephew PLC |
| B. Braun Melsungen AG |
| Others |
Value Network & Pricing Analysis
Medical-grade stainless steel price volatility cascades through Spain's surgical device supply chain, compressing margins on commoditized instruments while elevating premium positioning for integrated energy platforms with captive material sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement frameworks, with differentiation driven by CE marking tier under EU MDR transition timelines and volume scale in consolidated hospital consortia. Cost compression in economy-tier disposable instruments intensifies because regional health authority consolidation rewards logistics-responsive suppliers with Spanish manufacturing presence. Ambulatory surgery centers in Castile and León exhibit the highest price sensitivity, while Madrid's hospital cluster prioritizes technical integration over unit cost.
Supply Chain Analysis
Domestic-content requirements under Spain's national healthcare framework reforms are reshaping sourcing patterns toward EU-based manufacturers with ISO 13485-certified facilities. Supply concentration rests on Germany, Ireland, and domestic Spanish production hubs for finished devices, with raw material dependencies spanning Swedish surgical-grade steel, German polymer feedstocks, and Chinese rare earth elements for electrosurgical generator components. Single-source vulnerability concentrates in Basque Country and Galicia hospital clusters lacking domestic energy platform alternatives. Distribution runs through regional health authority procurement consortia with scheduled kit replenishment contracts displacing spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's general surgical devices market operates as a stable compounder, with minimally invasive procedure expansion providing durable demand tailwinds across public hospital networks.
For Market Incumbents: Hedge against margin compression from regional procurement consolidation by deepening backward integration into sterilization-compatible stainless steel processing and securing multi-year framework agreements with performance-based renewal clauses. ISO 13485 certification investments defend tender eligibility as EU MDR enforcement timelines accelerate. For New Entrants and Emerging Players: Begin with Castile and León's underpenetrated ambulatory surgery center networks, where cost-per-procedure metrics favor streamlined disposable instrument portfolios over capital-intensive platform competition. A direct-to-procurement-committee go-to-market model bypasses entrenched sales force concentration in Madrid and Barcelona. For Investors and Strategic Acquirers: Asymmetric upside sits with logistics-responsive mid-tier manufacturers possessing Spanish production footprints and suture-specialist capabilities, as hospital consortia prioritize supply security over brand premium in consolidated tenders. The inflection indicator to monitor is Andalusia and Valencia regional health authority merger completion rates, which accelerate volume concentration into qualified vendor panels.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance under Spain's accelerated timelines filters marginal suppliers from public tenders. |
| Hospital System Partnership | Madrid's cluster and Catalonia's corridor reward integrated energy platform vendors with preference lock-in. |
| Backward Integration | Captive surgical-grade steel processing defends margin pools against commodity price swings. |
| Software Companion Development | Smart electrosurgical platforms with tissue-sensing feedback unify purchasing decisions around single-vendor ecosystems. |
| Reimbursement Strategy | Spain's Ministry of Health protocol updates expand coverage for advanced wound closure technologies. |
Research Methodology
Coverage spans Madrid, Catalonia, Basque Country, Andalusia, and Valencia, with primary inputs from each autonomous community's regional health authority procurement offices. The approach combines structured interviews with hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and surgical device sales specialists with secondary validation against Spanish Agency for Medicines and Health Products regulatory filings, hospital procurement databases, and EU MDR transition documentation. Bottom-up procedure volume estimates and top-down healthcare expenditure flows undergo triangulation at the regional cluster level.
Granularity extends to product type, end user facility scale, anatomical application, and technology platform across the projection horizon. Modeled segmentation captures surgical suture absorption profiles, ambulatory versus acute care procurement patterns, gastrointestinal versus cardiovascular procedure volumes, and laparoendoscopic versus robotic-assisted platform adoption curves. CAGRs derive from regression analysis against historical public health expenditure trends and surgical procedure migration patterns, with sensitivity testing around EU MDR compliance cost pass-through and regional consolidation timelines.
Caveats apply where EU MDR audit backlog resolution delays, medical-grade alloy price spikes, or autonomous community procurement merger reversals could materially shift the outlook. Forecasts embed assumptions regarding reimbursement protocol stability and minimally invasive procedure conversion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Electrosurgery Market
Surgical Instruments
Surgical Stents Market
Surgical Instruments
Gynecology Surgical Instruments Market
Surgical Instruments
Articulating Paper Forceps Market
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Disposable Spinal Instruments Market
Surgical Instruments
Ultrasonic Tissue Ablation System Market
Surgical Instruments
Europe Biosurgery Market
Surgical Instruments
Dermal Curettes Market
Surgical Instruments
Iris Retractors Market
Surgical Instruments
Adult Cardiovascular Surgical Instruments Package Market
Surgical Instruments
Surgical Visualization Market
Surgical Instruments
Uro Gynaecological Surgical Devices Market
Surgical Instruments
Global Surgical Retractor Market
Surgical Instruments
US Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Japan General Surgical Devices Market