
 Global Electromagnetic Surgical Navigation System Market | 2026-2036
Global Electromagnetic Surgical Navigation System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electromagnetic Surgical Navigation System Market Foresight
Multi-source component procurement for electromagnetic field generators and sensor arrays is restructuring supply economics across the surgical navigation value chain. Medtronic leverages captive manufacturing of electromagnetic tracking subsystems to sustain margin control across its navigation portfolio. Brainlab competes through specialized software-hardware integration for cranial and spinal applications. Stryker Corporation anchors its position via broad orthopedic procedural coverage and dedicated sales infrastructure in major hospital systems.
Electromagnetic surgical navigation systems employ low-frequency magnetic field transmitters and miniature receiver coils embedded in instruments to calculate real-time three-dimensional position data with sub-millimeter accuracy, enabling surgeons to track tool trajectories relative to preoperative imaging without line-of-sight constraints. Navigation console hardware represents the largest installed base revenue stream, while imaging software commands the highest incremental margin per procedure through recurring licensing and upgrade cycles. Hybrid tracking configurations that blend electromagnetic and optical modalities are gaining fastest procedural adoption in complex cranial interventions where occlusion resilience matters.
FDA 510(k) clearances and EU MDR conformity assessments shape product launch cadence and clinical evidence requirements for electromagnetic navigation platforms across the United States and European markets. ISO 13485 quality management certification and IEC 60601 electromagnetic compatibility standards govern manufacturing access for subsystem vendors supplying into finished device assemblies. Stakeholders must monitor how FDA's evolving software-as-a-medical-device framework recategorizes AI-enabled navigation planning modules previously bundled under hardware clearances.
Market Dynamics
Hybrid electromagnetic-optical tracking configurations are compressing installed base renewal cycles as academic medical centers prioritize occlusion resilience in complex cranial workflows over legacy single-modality platforms.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined clearances for computer-assisted surgical devices reduce time-to-market for electromagnetic navigation platforms, expanding eligible product portfolios.
- Japan's aging surgical workforce:Demographic pressures on experienced neurosurgeons intensify hospital investment in image-guidance systems that compress training curves and standardize procedural outcomes.
- Real-time instrument tracking:Sub-millimeter electromagnetic field calculation enables trajectory visualization without line-of-sight constraints, driving replacement demand in orthopedic and spinal suites.
Market Restraints
- Sensor array supply concentration:Miniature receiver coil manufacturing concentrates among specialized German and Japanese component vendors, exposing finished device assemblers to single-source disruption risk.
- EU MDR clinical evidence escalation:Conformity assessment requirements for electromagnetic navigation systems demand expanded patient registry data, extending certification timelines and freezing product launch cadence.
- Optical tracking residual preference:Some cranial centers retain line-of-sight-dependent infrared systems for cost-sensitive routine procedures, capping electromagnetic penetration in price-pressured hospital networks.
Strategic Opportunities
- India's tertiary hospital expansion:Government infrastructure investment in metropolitan medical cities creates first-mover advantage for electromagnetic navigation vendors establishing training and service presence.
- AI-enabled preoperative planning modules:FDA's evolving software-as-a-medical-device framework recategorizes navigation planning algorithms, enabling standalone licensing revenue streams previously bundled under hardware clearances.
- Outpatient spine center channel:Ambulatory surgical facilities in the United States seek compact electromagnetic consoles with reduced footprint, opening distribution partnerships outside traditional hospital capital equipment procurement.
Industry Challenges
- Electromagnetic compatibility engineering:IEC 60601 certification for navigation consoles operating amid surgical equipment interference demands specialized testing protocols that compress engineering bandwidth at subsystem vendors.
- ISO 13485 quality management:Component suppliers face audit intensity escalation as finished device manufacturers consolidate vendor bases, forcing quality system investments that strain mid-tier electromagnetic field generator producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electromagnetic Surgical Navigation System Market |
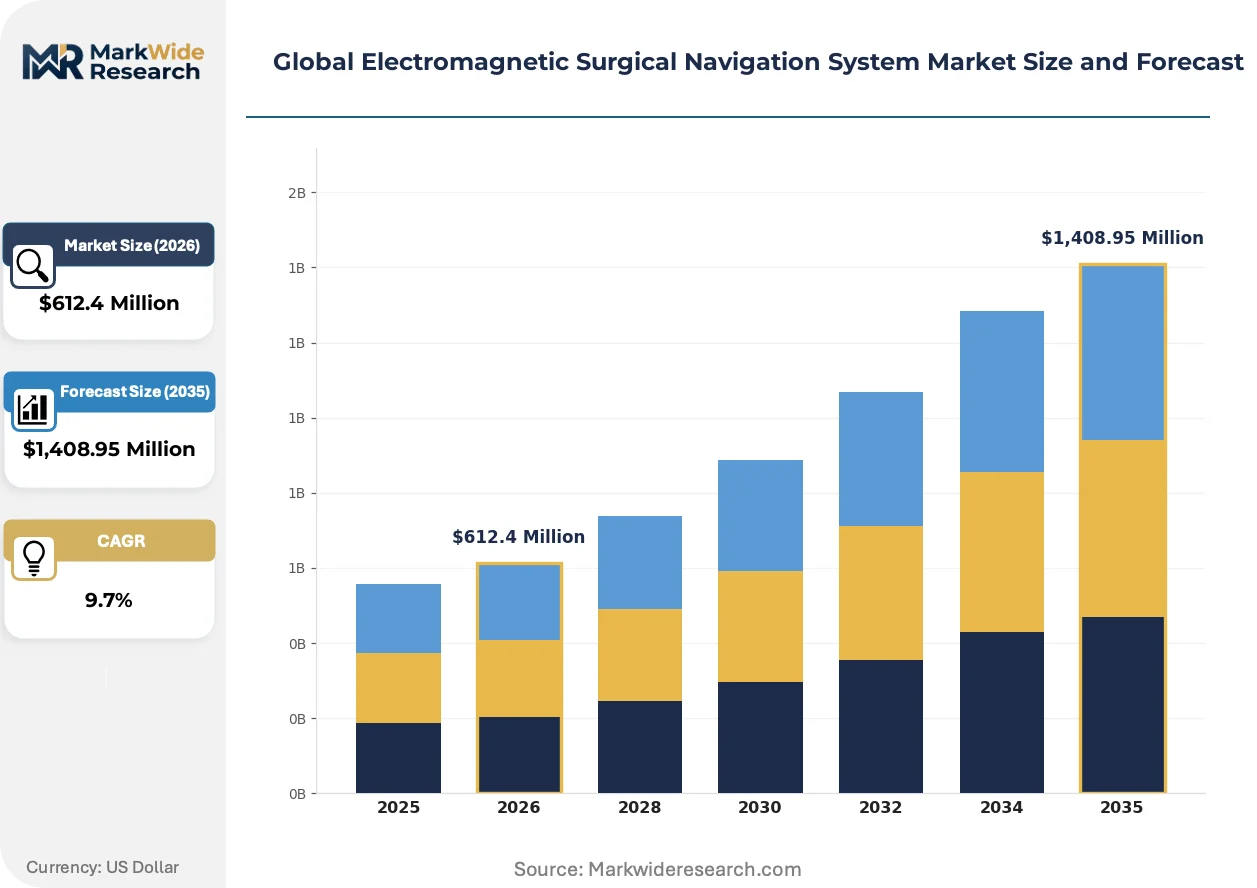
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,408.95 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Navigation Console, Tracking Sensors, Surgical Instruments, Imaging Software Technology: Electromagnetic Tracking, Optical Tracking, Hybrid Tracking, Infrared Tracking Application: Neurosurgery, Orthopedic Procedures, Cardiothoracic Surgery, Ear Nose Throat Surgery, Spinal Surgery End User: Hospitals, Ambulatory Surgical Centers, Research Institutes, Diagnostic Laboratories |
| Companies Covered | Medtronic, Brainlab, Stryker Corporation, Siemens Healthineers, Zimmer Biomet Holdings, B. Braun Melsungen, Fiagon, Northern Digital, CAScination, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electromagnetic Surgical Navigation System Market Shifts & Advancements
Navigation platform architecture is bifurcating between compact outpatient configurations and high-throughput academic suites, with software licensing models decoupling from hardware ownership to capture recurring revenue.
Hybrid electromagnetic-optical tracking is overtaking single-modality installations in complex cranial interventions. Electromagnetic field transmitters paired with infrared backup sensors eliminate line-of-sight vulnerabilities during tumor resections. Neurosurgery departments at German university hospitals are adopting these configurations fastest, prioritizing procedural continuity over capital cost minimization. The technology is overtaking standalone optical platforms in premium installed base segments.
EU MDR Article 10 post-market surveillance requirements are intensifying clinical evidence obligations for electromagnetic navigation systems. Manufacturers must maintain systematic patient outcome registries across notified body jurisdictions. Cranial application categories face the steepest documentation burden, prompting some vendors to narrow initial conformity scope before expanding indications.
Hospital procurement committees are unbundling navigation software licenses from console hardware acquisitions. German and Japanese health systems now negotiate three-year subscription terms for imaging planning modules separately from capital equipment financing. This shift concentrates vendor negotiation leverage with hospital IT departments rather than surgical service line administrators, altering sales force deployment patterns across major metropolitan clusters.
Global Electromagnetic Surgical Navigation System Market Segmentation
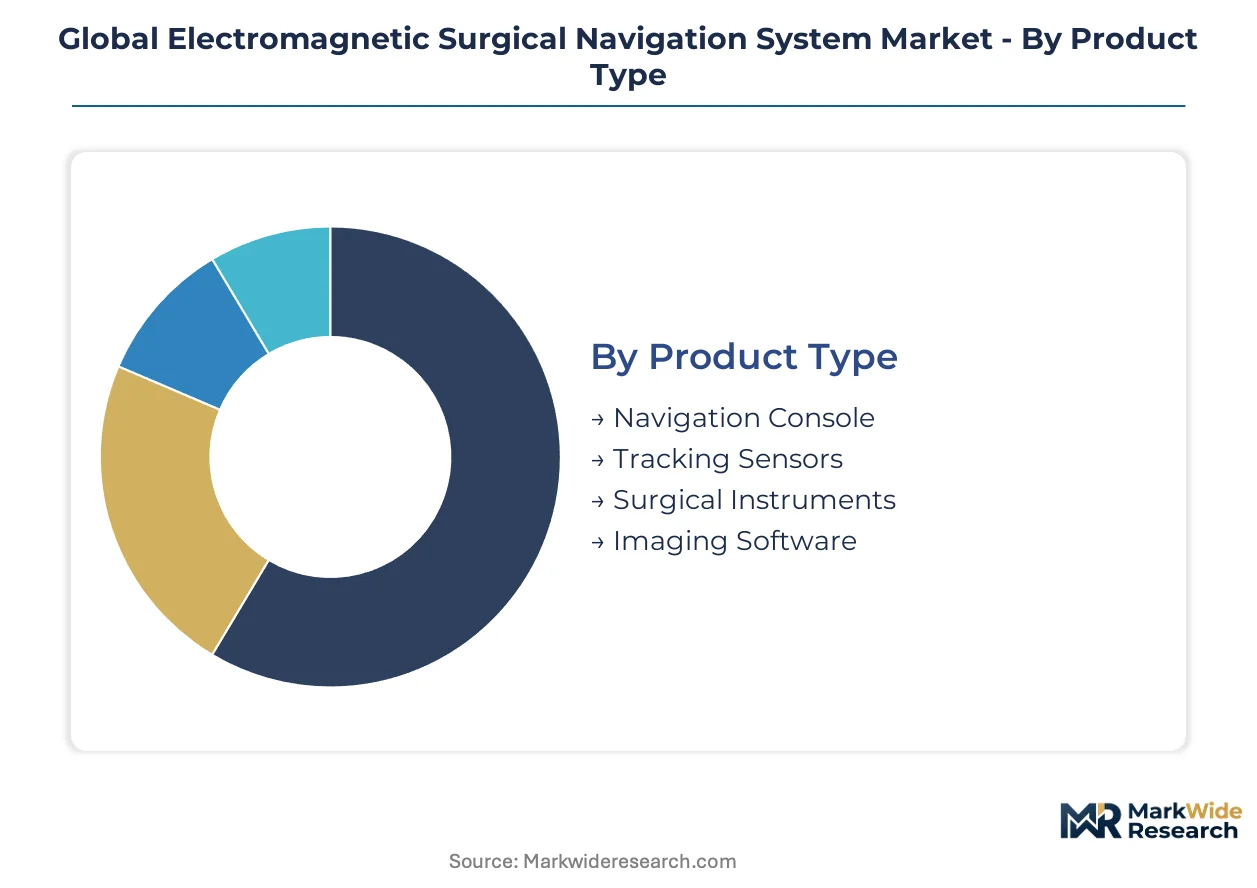
Electromagnetic surgical navigation systems fragment across four critical dimensions that determine procurement patterns, margin structures, and vendor competitive positioning. Product type and technology choices dictate whether hospitals acquire standalone platforms or embedded modules, while application and end-user segmentation shapes service intensity and training requirements.
Product Type:
Integration depth varies sharply: navigation consoles and tracking sensors function as standalone capital equipment, while surgical instruments and imaging software embed into broader surgical workflows.
- Navigation Console:Central hardware units housing electromagnetic field generators and processing units with sub-millimeter tracking algorithms. Demand concentrates at academic medical centers in the United States and Germany where capital budgets support high-throughput suites.
- Tracking Sensors:Miniature receiver coils and field detection arrays that instrument positioning data in real time. Japanese and German component vendors supply these subsystems, exposing finished device assemblers to single-source concentration risk.
- Surgical Instruments:Electromagnetically enabled probes, pointers, and drills with embedded sensor coils.
- Imaging Software:Preoperative planning and intraoperative visualization modules with recurring licensing terms.
Navigation console leads volumes today; imaging software is gaining share fastest.
Technology:
Cost tiers separate premium hybrid configurations from standard electromagnetic-only and economy optical alternatives, with reimbursement levels and procedural complexity driving selection.
- Electromagnetic Tracking:Low-frequency magnetic field transmitters calculate three-dimensional instrument position without line-of-sight constraints. Demand clusters in orthopedic and spinal suites across United States hospital networks where occlusion resilience matters less than capital cost control.
- Hybrid Tracking:Blended electromagnetic-optical modalities with infrared backup sensors for complex cranial workflows. German university hospitals adopt these configurations fastest, prioritizing procedural continuity over equipment minimization.
- Optical Tracking:Line-of-sight-dependent infrared camera systems with lower per-procedure costs.
- Infrared Tracking:Legacy wavelength-based positioning for cost-sensitive routine procedures.
Electromagnetic tracking leads volumes today; hybrid tracking is expanding most quickly.
Application:
Volume concentration and margin profiles diverge across surgical specialties, with cranial applications commanding premium pricing and spinal procedures driving installed base scale.
- Neurosurgery:Cranial tumor resections and deep-brain interventions requiring sub-millimeter accuracy and continuous tracking reliability. United States academic medical centers represent the core demand cluster, with FDA 510(k) pathway acceleration enabling faster platform upgrades.
- Spinal Surgery:Pedicle screw placement and deformity correction procedures with high annual caseloads. Japanese hospitals invest heavily here as aging surgical workforce pressures intensify demand for image-guidance systems that standardize outcomes.
- Orthopedic Procedures:Joint replacement and trauma applications with expanding ambulatory surgical center adoption.
- Cardiothoracic Surgery:Electromagnetically guided valve repair and arrhythmia ablation with emerging regulatory pathways.
- Ear Nose Throat Surgery:Sinus and skull-base procedures with smaller addressable volumes.
Spinal surgery leads volumes today; neurosurgery commands the steepest expansion trajectory.
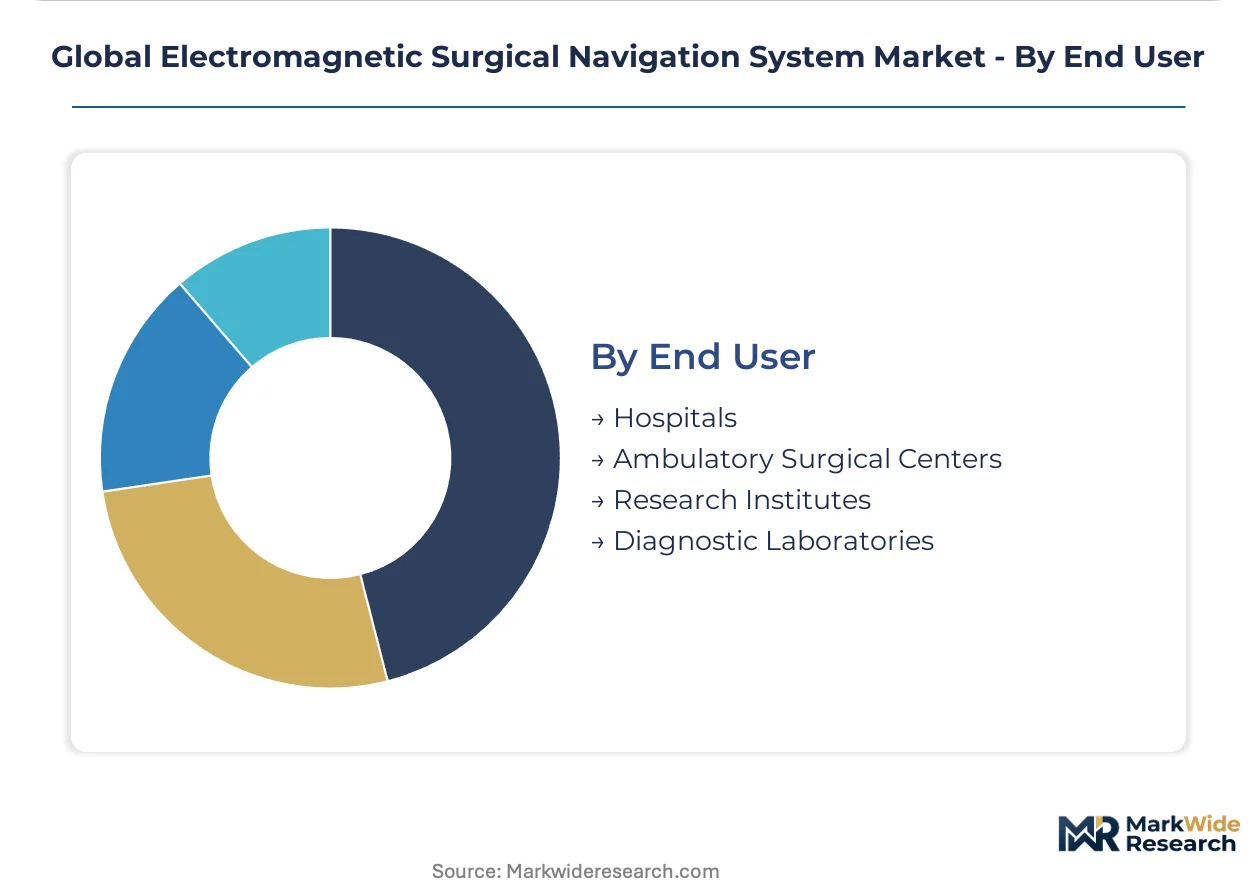
End User:
Customer type determines procurement authority, with hospital IT departments increasingly controlling software licensing negotiations separate from surgical service line capital requests.
- Hospitals:Integrated delivery networks and academic medical centers with dedicated capital equipment budgets and image-guided surgery suite investments. German and Japanese health systems now unbundle software subscriptions from hardware financing, concentrating vendor leverage with IT procurement committees.
- Ambulatory Surgical Centers:Outpatient spine and orthopedic facilities seeking compact electromagnetic consoles with reduced footprint. United States ASCs represent an emerging channel outside traditional hospital procurement.
- Research Institutes:Preclinical validation and algorithm development centers with specialized electromagnetic compatibility requirements.
- Diagnostic Laboratories:Imaging and pathology workflows with limited navigation integration today.
Hospitals lead volumes today; ambulatory surgical centers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between regulatory jurisdictions are redirecting electromagnetic navigation subsystem assembly toward manufacturing zones with streamlined medical device quality management pathways. German and Japanese component vendors retain sensor array production despite higher certification burdens, while final device integration concentrates in markets with accelerated FDA 510(k) timelines.
United States
Academic medical centers in Boston and Houston drive console procurement for high-throughput neurosurgery suites. FDA's streamlined 510(k) pathway for computer-assisted surgical devices compresses product launch timelines. The Minneapolis-St. Paul corridor anchors Medtronic's captive manufacturing of electromagnetic tracking subsystems.
Germany
University hospitals in Munich and Heidelberg prioritize hybrid electromagnetic-optical configurations for cranial tumor resections. EU MDR Article 10 post-market surveillance requirements intensify clinical evidence obligations for navigation platforms. The Karlsruhe-Stuttgart industrial cluster concentrates miniature receiver coil fabrication among specialized component vendors.
Japan
Tokyo and Osaka metropolitan hospitals invest heavily in spinal navigation systems as aging surgical workforce pressures intensify. PMDA regulatory harmonization with FDA standards accelerates product registration for electromagnetic platforms. The Nagoya medical device manufacturing belt supports subsystem assembly for domestic and export markets.
India
Government infrastructure investment in Delhi-NCR and Mumbai medical cities creates first-mover opportunities for navigation vendors establishing training networks. CDSCO medical device rules mandate local quality management certification for imported electromagnetic consoles. Hyderabad's life sciences corridor attracts subsystem assembly partnerships targeting price-sensitive hospital procurement.
Switzerland
Swissmedic's streamlined conformity assessment for class IIa surgical navigation devices attracts European headquarters placement. Basel and Zurich academic centers demand premium hybrid tracking configurations for complex neurosurgical workflows. The Swiss-German border region hosts specialized electromagnetic compatibility testing laboratories serving EU market access.
Global Electromagnetic Surgical Navigation System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-enabled software modules and ambulatory surgical center channels. The vendor base concentrates around three strategic archetypes: diversified medical technology conglomerates with captive navigation portfolios, specialized surgical software-hardware integrators, and component subsystem suppliers with electromagnetic field generator expertise. Competitive moves center on unbundling software licenses from hardware sales and consolidating vendor bases to compress quality audit overhead.
Among diversified medical technology conglomerates, Medtronic exemplifies the integrated archetype through captive manufacturing of electromagnetic tracking subsystems. Brainlab occupies a position within the specialized software-hardware integration tier, with its German origin reflecting European regulatory navigation capabilities. Stryker Corporation represents the orthopedic-procedural-coverage archetype, anchoring broad hospital system sales infrastructure. These three entities illustrate how competitive positioning fragments across integration depth rather than geographic coverage alone.
| Leading Market Players |
|---|
| Medtronic |
| Brainlab |
| Stryker Corporation |
| Siemens Healthineers |
| Zimmer Biomet Holdings |
| B. Braun Melsungen |
| Fiagon |
| Northern Digital |
| CAScination |
| Others |
Supply & Pricing Matrix
Electromagnetic compatibility engineering specialists concentrated in Germany's Karlsruhe-Stuttgart corridor command wage premiums that compress pricing-tier spreads between premium hybrid tracking configurations and standard electromagnetic-only platforms. Labor-cost differentials between these specialized engineers and general medical device assemblers in lower-cost manufacturing zones force tiered pricing structures that separate academic medical center procurement from ambulatory surgical center budgets.
Pricing Analysis
Distributor margins on navigation console hardware typically range from 15-22 percent, while direct-to-OEM procurement of tracking sensor arrays commands steeper volume discounts that compress channel economics. Three-tier pricing structure across premium hybrid, standard electromagnetic, and economy optical levels separates German university hospital budgets from United States ambulatory surgical center constraints. Pricing pressure stems from CDSCO local-content mandates in India that force landed-cost adjustments for imported electromagnetic field generators. Ambulatory surgical centers exhibit the highest price sensitivity, prioritizing compact footprint over sub-millimeter tracking precision.
Supply Chain Analysis
CDSCO medical device rules mandating local quality management certification for imported electromagnetic consoles are reshaping sourcing toward domestic subsystem assembly partnerships in Hyderabad's life sciences corridor. Miniature receiver coil fabrication concentrates in Germany and Japan, while final navigation console integration clusters in the United States and Switzerland. Raw material dependencies include rare-earth magnetic alloys, precision-wound copper coils, and medical-grade polymer housings. Single-source vulnerability pervades the sensor array tier, with specialized German and Japanese component vendors exposing finished device assemblers to disruption. Distribution runs through hospital capital equipment procurement committees and ambulatory surgical center group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by hospital procurement committees unbundling navigation software licenses from console hardware acquisitions toward premium subscription-based specifications.
For Market Incumbents: Deploy captive manufacturing of electromagnetic tracking subsystems to defend margin control against emerging AI-enabled software entrants seeking standalone licensing revenue. Consolidate vendor bases for sensor array components to compress ISO 13485 audit overhead. Invest in FDA 510(k) pathway acceleration capabilities to outpace EU MDR conformity assessment timelines that freeze competitor launch cadence. For New Entrants and Emerging Players: Enter via India's tertiary hospital expansion corridor where government infrastructure investment in Delhi-NCR and Mumbai medical cities creates first-mover advantage for training network establishment. Target ambulatory surgical centers in the United States seeking compact electromagnetic consoles with reduced footprint outside traditional hospital procurement channels. Pursue software-as-a-medical-device standalone clearances for AI-enabled preoperative planning modules previously bundled under hardware approvals. For Investors and Strategic Acquirers: Diversified medical technology conglomerates with captive navigation portfolios represent the most active acquirer in this space, seeking electromagnetic field generator expertise to deepen integration. Long-term viability hinges on hybrid tracking configuration dominance in complex cranial workflows over the next decade. Monitor FDA software-as-a-medical-device framework evolution as the critical inflection signal for standalone algorithm licensing revenue recognition.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Tracking Configuration Development | Blends electromagnetic-optical modalities to eliminate line-of-sight vulnerabilities during German university hospital tumor resections. |
| Software-as-a-Medical-Device Clearance Pathway | Enables standalone AI-enabled preoperative planning licensing revenue outside FDA hardware bundling constraints. |
| Hospital System Partnership | Secures preferred vendor status with United States academic medical centers expanding image-guided surgery suite investments. |
| CDSCO Local Quality Certification | Unlocks electromagnetic console procurement access to India's government-funded metropolitan medical cities expansion. |
| EU MDR Article 10 Post-Market Surveillance | Mandates systematic patient outcome registries that steepen clinical evidence burdens for cranial application competitors. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and Switzerland, with primary inputs from each market's hospital procurement committees, biomedical engineers, GPO contracts managers, and electromagnetic subsystem vendors. The analysis combines structured interviews with these stakeholders against secondary validation from FDA 510(k) filings, EU MDR notified body databases, PMDA registration records, CDSCO medical device rules, and hospital capital expenditure disclosures. Bottom-up installed base enumeration triangulates against top-down addressable procedure volume estimates.
Rate-of-change decomposition separates volume growth from pricing evolution across the modeling period, with CAGRs derived from segmented trajectory analysis rather than single-point extrapolation. The forecast framework models product type, technology tier, application specialty, and end-user channel dimensions alongside regulatory pathway acceleration indices specific to computer-assisted surgical devices. Industry-specific inputs include electromagnetic compatibility certification timelines and software-as-a-medical-device recategorization probabilities.
The model holds under stable FDA 510(k) pathway velocity and EU MDR notified body capacity; deviation in regulatory staffing constraints or electromagnetic component trade restrictions would shift launch cadence assumptions. Forecasts reflect these base conditions with explicit acknowledgment that sensor array supply concentration and ISO 13485 audit escalation present revision triggers. A small set of regulatory pathway velocity, component trade policy, and hospital IT procurement centralization warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Homecare Surgical Drains Market
Surgical Instruments
Gynecology Surgical Instruments Market
Surgical Instruments
Surgical Headband Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Brazil General Surgical Devices Market
Surgical Instruments
Italy General Surgical Devices Market
Surgical Instruments
Disposable Surgical Devices Market
Surgical Instruments
Global Minimally Invasive Surgery (MIS) Market
Surgical Instruments
Ultrasonic Scalpel Market
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Endoscopic Spinal Surgery Market
Surgical Instruments
US Integrated Operating Rooms Market
Surgical Instruments
Surgical Broaches Market
Surgical Instruments
Hemostatic Instruments Market
Surgical Instruments
Middle East and Africa General Surgical Devices Market
Surgical Instruments
Surgical Hemostats Market