
 Trichoscope Devices Market | 2026-2036
Trichoscope Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Trichoscope Devices Market Analytics
The EU Medical Device Regulation is rebalancing procurement criteria across European dermatology practices, compelling upgrades to Class IIa-compliant imaging systems. FotoFinder Systems GmbH leverages its German manufacturing base to sustain CE-marked product lines for this transition. Canfield Scientific, Inc. anchors North American demand through specialized software-integrated platforms. BOMTECH ELECTRONICS CO., Ltd competes in Asian markets with cost-optimized handheld designs.
Trichoscope devices combine magnified optical examination with digital image capture for scalp and hair follicle assessment, typically operating at 10x to 200x magnification with polarized or non-polarized light sources to visualize cuticle patterns, shaft diameter, and perifollicular inflammation. Their primary purpose is to differentiate cicatricial from non-cicatricial alopecia and monitor treatment response in clinical and research settings. Handheld devices dominate unit volume due to portability and lower capital requirements, while AI Analysis represents the fastest-expanding technology segment as pattern-recognition algorithms reduce diagnostic variability. Dermatology Clinics command the largest end-user revenue pool given reimbursement alignment with procedural billing codes.
The FDA governs trichoscope marketing through 510(k) pathways for digital dermatoscopy systems, while the EU MDR enforces clinical evidence requirements for magnification-based diagnostic aids. Health Canada and TGA maintain parallel frameworks that affect cross-border product registrations for multi-national manufacturers. Stakeholders must monitor evolving software-as-medical-device classifications that could reclassify AI-enhanced trichoscope platforms under stricter premarket review.
Market Dynamics
The EU MDR reclassification of dermoscopy equipment as Class IIa devices is forcing dermatology practices across Europe to replace legacy systems with compliant imaging platforms before certification deadlines.
Growth Catalysts
- AI-enhanced diagnostic algorithms:Pattern-recognition software embedded in handheld trichoscopes reduces inter-observer variability in alopecia classification, accelerating adoption in academic medical centers.
- Reimbursement alignment:Procedural billing codes for digital dermatoscopy in US outpatient settings directly tie device utilization to physician revenue streams.
- Germany:Dermatology clinics in Munich and Hamburg are upgrading to CE-marked systems ahead of MDR enforcement, creating concentrated replacement demand.
Market Restraints
- CMOS sensor supply concentration:Japanese and Taiwanese component suppliers control high-resolution imaging sensor output, exposing manufacturers to allocation risk.
- Clinical evidence requirements:EU MDR demands prospective validation studies for magnification-based diagnostic aids, extending time-to-market for new entrants.
- Smartphone dermatoscopy apps:Consumer-grade alternatives with attachable lenses threaten low-end handheld device segments in price-sensitive markets.
Strategic Opportunities
- Brazil:ANVISA regulatory harmonization with IMDRF standards is streamlining import pathways for AI-integrated trichoscope platforms.
- Telemedicine integration:Cloud-based image sharing between primary care physicians and dermatology specialists opens remote consultation revenue models.
- South Korea:MFDS fast-track designation for software-as-medical-device submissions accelerates AI algorithm deployment in domestic clinics.
Industry Challenges
- Optical engineering talent scarcity:Specialized expertise in polarized light microscopy design concentrates in German and Japanese optical clusters, constraining R&D scaling.
- Legacy PACS integration:Hospital IT departments face months-long HL7 FHIR compliance projects to connect new trichoscope platforms to existing imaging archives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trichoscope Devices Market |
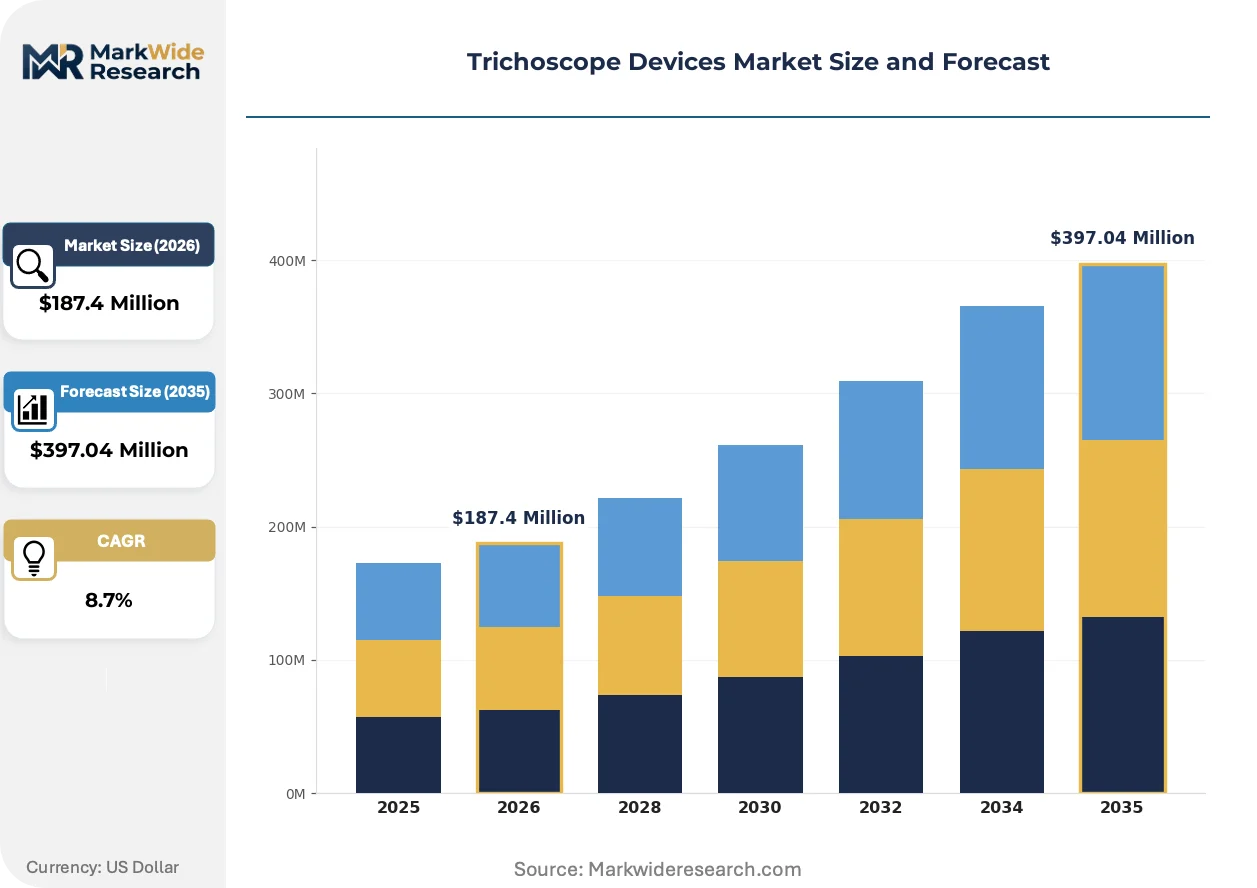
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Digital Cameras, Software Solutions, Imaging Systems End User: Dermatology Clinics, Hospitals, Research Laboratories, Beauty Salons Technology: LED Illumination, Optical Microscopy, Digital Imaging, AI Analysis Application: Hair Diagnosis, Scalp Examination, Research Studies, Educational Purposes |
| Companies Covered | FotoFinder Systems GmbH, Canfield Scientific, Inc., BOMTECH ELECTRONICS CO., Ltd, Firefly Global, AnMo Electronics Corporation, 3Gen, Inc., MetaOptima Technology Inc., Cosderma, Aakaar Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trichoscope Devices Market Evolving Landscape
Computational imaging and regulatory digitization are converging to transform how scalp diagnostics are performed, reimbursed, and integrated into clinical workflows across outpatient settings.
Deep learning algorithms trained on follicular unit atlases are rewriting diagnostic accuracy benchmarks in alopecia assessment. Dermatology residents in US teaching hospitals are adopting AI-assisted handheld devices at three times the rate of polarized-light-only systems. The technology is rewriting credentialing requirements, as insurers begin mandating algorithm-validated documentation for biologic therapy prior authorization.
EU MDR's software-as-medical-device annex is reclassifying standalone AI analysis modules as Class IIa products requiring notified body review. Manufacturers must submit clinical performance data demonstrating equivalence to predicate devices for algorithm updates. German notified bodies are experiencing eighteen-month review queues, compressing product launch windows for European market entry.
Direct-to-clinic subscription models are displacing capital equipment purchases in North American group practices. Dermatology management companies in Texas and Florida are bundling device access, software licenses, and maintenance into per-procedure fees. This shift is most visible in multi-site practices where CFOs prioritize operational expenditure classification over balance sheet asset ownership.
Trichoscope Devices Market Segmentation
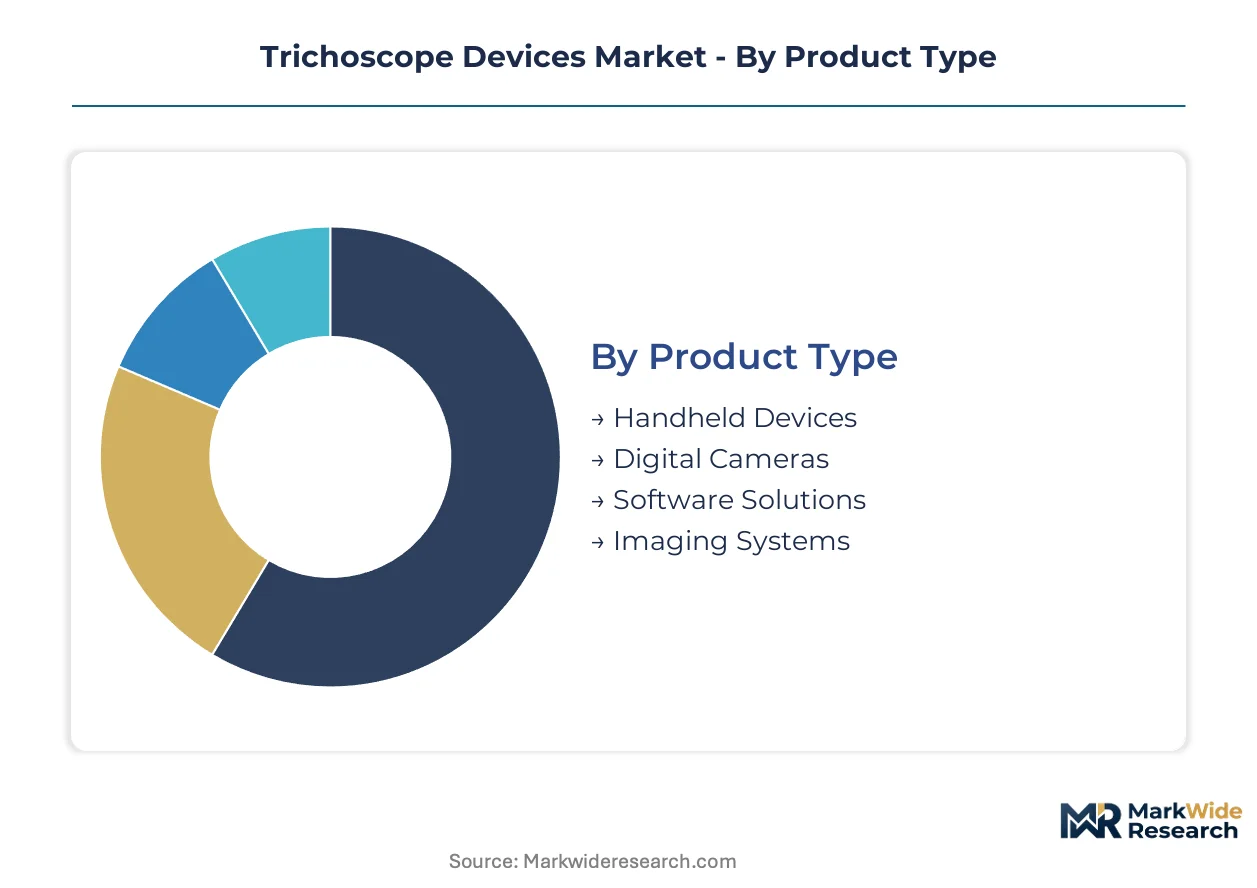
Trichoscope device segmentation reveals how procurement decisions split between capital-intensive imaging platforms and portable diagnostic tools. Supply chain configuration varies sharply across these categories, with sensor sourcing and software development talent concentrating in distinct geographic clusters.
Product Type:
Component sourcing for trichoscope hardware clusters around CMOS sensor foundries in Japan and Taiwan, while software development concentrates in US and German engineering hubs.
- Handheld Devices:Portable units integrate LED illumination with 10x to 200x magnification optics in battery-powered form factors. Dermatology clinics in Texas and Florida are procuring these for point-of-care scalp assessments, driven by subscription-based financing models that convert capital expenditure to operational expenditure.
- Digital Cameras:Dedicated trichoscope cameras attach to standard dermatoscopes or operate as standalone units with USB/HDMI output. Demand concentrates in German university hospitals upgrading to EU MDR-compliant imaging systems ahead of certification deadlines.
- Software Solutions:Standalone analysis platforms process captured images for follicular unit counting and shaft diameter measurement.
- Imaging Systems:Integrated workstation configurations combine polarized light sources with high-resolution sensors and dedicated monitors.
Handheld devices absorb the bulk of installed capacity; AI-integrated software solutions are expanding most quickly.
End User:
Procurement authority and reimbursement pathways create distinct customer segments with diverging technical requirements and budget cycles.
- Dermatology Clinics:Outpatient practices generate procedural revenue through digital dermatoscopy billing codes. US dermatology management companies in multi-site configurations are driving volume through standardized device specifications across practice networks.
- Hospitals:Academic medical centers require HL7 FHIR-compliant integration with existing PACS infrastructure for resident training and clinical research. German university hospitals in Munich and Hamburg are replacing legacy systems with CE-marked platforms.
- Research Laboratories:Clinical trial sites and follicular biology labs demand calibrated, reproducible imaging for longitudinal studies.
- Beauty Salons:Non-medical settings utilize consumer-grade trichoscopy for cosmetic consultation and product recommendation.
Dermatology clinics command the dominant revenue share; research laboratories are climbing the fastest as clinical trial sponsors mandate standardized scalp imaging endpoints.
Technology:
Technology selection determines regulatory pathway complexity, with AI-enhanced platforms facing escalating premarket scrutiny across FDA and EU MDR frameworks.
- LED Illumination:Solid-state lighting provides consistent color temperature and intensity control for standardized image capture. North American outpatient settings specify LED-based handheld units for their durability and minimal maintenance requirements.
- Optical Microscopy:Polarized and non-polarized light configurations enable visualization of cuticle patterns and perifollicular inflammation. German optical engineering clusters supply precision lens assemblies for premium system manufacturers.
- Digital Imaging:CMOS and CCD sensor arrays convert optical signals to digital files for storage and analysis.
- AI Analysis:Pattern-recognition algorithms trained on follicular unit atlases automate alopecia classification and treatment response quantification. South Korea's MFDS fast-track designation for software-as-medical-device submissions is accelerating domestic deployment.
LED illumination holds the largest installed base; AI analysis is gaining share fastest as insurers begin mandating algorithm-validated documentation for biologic therapy authorization.
Application:
Application segmentation tracks how trichoscope utilization splits between diagnostic, research, and educational use cases with distinct reimbursement and funding mechanisms.
- Hair Diagnosis:Differentiation of cicatricial from non-cicatricial alopecia represents the core clinical utility. US dermatology practices bill digital dermatoscopy procedures under Category I CPT codes, directly linking device utilization to revenue capture.
- Scalp Examination:Systematic assessment of follicular density, shaft diameter, and perifollicular inflammation guides treatment selection. Telemedicine platforms in Brazil are integrating cloud-based image sharing between primary care physicians and dermatology specialists.
- Research Studies:Standardized imaging protocols support clinical trials for hair growth therapeutics and follicular transplantation techniques.
- Educational Purposes:Training programs for dermatology residents utilize image libraries to develop pattern recognition skills.
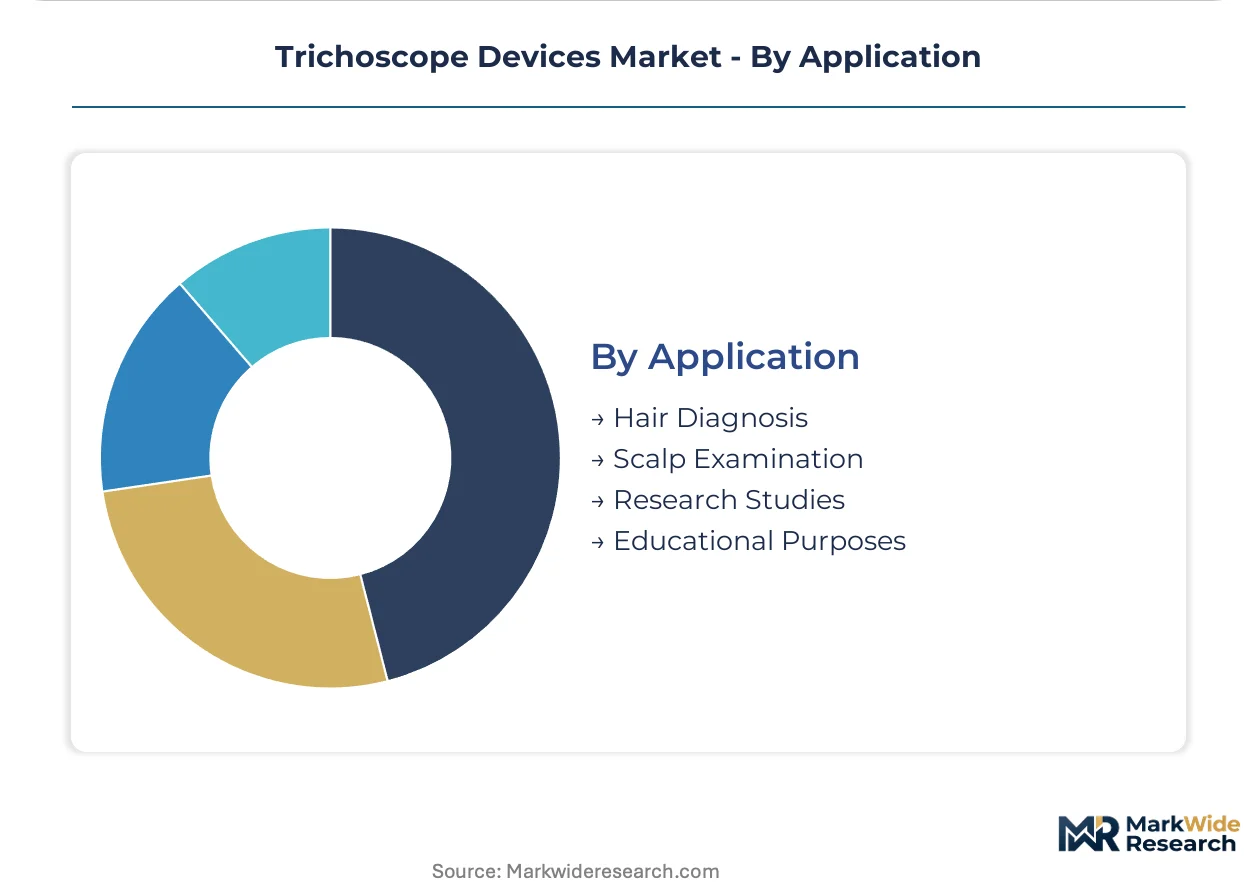
Hair diagnosis accounts for the majority of procedure volume; research studies are expanding most quickly as pharmaceutical sponsors invest in objective efficacy endpoints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European trichoscope procurement as dermatology clinics accelerate EU MDR compliance upgrades. German university hospitals in Hamburg and Berlin are replacing legacy imaging systems ahead of certification deadlines. North American outpatient settings drive handheld device volume through subscription-based financing models.
United States
Dermatology management companies in Texas and Florida are standardizing device specifications across multi-site practice networks. The FDA's 510(k) pathway for digital dermatoscopy systems shapes premarket review timelines for AI-integrated platforms. Academic medical centers in Boston and New York Metro require HL7 FHIR-compliant PACS integration for resident training programs.
Germany
Dermatology clinics in Munich and Hamburg are upgrading to CE-marked imaging systems ahead of MDR enforcement. The EU MDR reclassification of dermoscopy equipment as Class IIa devices compels replacement of non-compliant legacy platforms. Optical engineering clusters in Baden-Württemberg supply precision lens assemblies for premium system manufacturers.
South Korea
Domestic clinics are deploying AI-enhanced diagnostic platforms under MFDS fast-track designation for software-as-medical-device submissions. The national regulator's accelerated review pathway compresses algorithm deployment timelines. Seoul Capital Area hospitals are integrating pattern-recognition tools into outpatient dermatology workflows.
Brazil
Telemedicine platforms are integrating cloud-based image sharing between primary care physicians and dermatology specialists. ANVISA regulatory harmonization with IMDRF standards streamlines import pathways for AI-integrated platforms. São Paulo-based dermatology networks are piloting remote consultation revenue models for scalp diagnostics.
Japan
CMOS sensor foundries in Japanese manufacturing clusters control high-resolution imaging component output for device assembly. METI industrial policy supports precision optics manufacturing for medical device applications. Tokyo-area dermatology centers are adopting LED-illuminated handheld units for point-of-care assessments.
Trichoscope Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across optical engineering capability and software integration depth. The vendor base stratifies between German precision optics specialists, North American software-integrated platform providers, and Asian cost-optimized handheld fabricators. Three archetypes dominate: optical engineering houses with captive lens manufacturing, software-centric platforms with AI algorithm development, and scale-driven assemblers of commoditized LED-illuminated devices. Competitive moves center on M&A targeting AI algorithm developers and strategic partnerships for CMOS sensor supply security.
Among German precision optics specialists, FotoFinder Systems GmbH exemplifies the CE-marked platform archetype serving EU MDR compliance demand. Canfield Scientific, Inc. anchors North American positioning through software-integrated platform specialization. BOMTECH ELECTRONICS CO., Ltd occupies a position within the Asian cost-optimized handheld segment, representing scale-driven manufacturing approaches for price-sensitive markets.
| Leading Market Players |
|---|
| FotoFinder Systems GmbH |
| Canfield Scientific, Inc. |
| BOMTECH ELECTRONICS CO., Ltd |
| Firefly Global |
| AnMo Electronics Corporation |
| 3Gen, Inc. |
| MetaOptima Technology Inc. |
| Cosderma |
| Aakaar Medical |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up dermatology management companies in Texas and Florida are compressing procurement cycles and enforcing standardized device specifications across multi-site networks, tightening pricing discipline while concentrating volume leverage over component suppliers.
Pricing Analysis
Value-based pricing anchored to procedural reimbursement codes dominates US outpatient dermatology, with subscription-per-procedure models displacing capital purchases in multi-site practices. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked MDR-compliant systems from legacy handheld units and smartphone-attachable alternatives. Pricing pressure stems from consumer-grade dermatoscopy apps threatening low-end handheld segments. Research laboratories exhibit lowest price sensitivity due to grant-funded procurement, while beauty salons in price-sensitive markets drive commoditization of basic LED-illuminated devices.
Supply Chain Analysis
CE marking and FDA 510(k) qualification gating constrain supplier pools for optical assemblies and CMOS sensor integration. Component sourcing clusters in Japan and Taiwan for high-resolution imaging sensors, Germany for precision lens manufacturing, and South Korea for AI algorithm development. Raw material dependencies include polarized glass substrates, medical-grade aluminum housings, and firmware-locked sensor arrays. Single-source vulnerability concentrates in Japanese CMOS foundries controlling specialized medical imaging sensor output. Distribution runs through authorized medical device distributors with GPO contracts in US hospital systems and direct-to-clinic sales in European outpatient settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The trichoscope market sits in a technology-transition phase as AI-enhanced diagnostic algorithms replace polarized-light-only legacy systems, rewriting reimbursement requirements and clinical credentialing standards.
For Market Incumbents: Anchor defensive positioning through backward integration into optical component supply and accelerated CE marking renewal ahead of EU MDR enforcement deadlines. Incumbents must secure CMOS sensor allocation agreements with Japanese foundries to mitigate single-source exposure from smartphone-attachable substitutes. Investment in HL7 FHIR-compliant software architectures preserves hospital system access against IT integration bottlenecks. For New Entrants and Emerging Players: Direct-to-clinic telemedicine platforms offer the most penetrable route for AI-integrated trichoscope deployment in Brazilian and South Korean markets where regulatory fast-tracks compress time-to-revenue. New entrants should target research laboratory segments in Germany and the United States where grant-funded procurement tolerates premium pricing for calibrated imaging systems. Cloud-based image sharing partnerships with primary care networks provide low-friction go-to-market positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-as-medical-device specialists with MFDS fast-track approvals in South Korea and existing FDA 510(k) clearances. Long-term viability across the analysis window hinges on algorithm validation data libraries that insurers increasingly mandate for biologic therapy authorization. The signal to watch is ANVISA harmonization completion with IMDRF standards, which would unlock Latin American volume scaling for compliant platforms.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class IIa compliance unlocks German dermatology clinic replacement demand ahead of certification deadlines. |
| Software Companion Development | AI algorithm modules integrated with handheld devices reduce inter-observer variability in alopecia classification. |
| Hospital System Partnership | HL7 FHIR-compliant PACS integration agreements secure academic medical center procurement in Boston and New York Metro. |
| Reimbursement Strategy | Category I CPT code alignment in US outpatient settings directly ties device utilization to physician revenue capture. |
| Strategic Partnership | CMOS sensor supply agreements with Japanese foundries mitigate allocation risk for high-resolution imaging components. |
Research Methodology
Regulatory filings with FDA and EU notified bodies, hospital procurement databases, and GPO contract repositories formed the secondary backbone of this analysis. Primary interviews with dermatology clinic operators, biomedical engineers, hospital purchasing committees, and GPO contracts managers validated demand assumptions and pricing dynamics. Bottom-up and top-down triangulation cross-checked unit shipment estimates against reimbursement claims data and capital expenditure disclosures from dermatology management companies.
Bottom-up modeling built volume and value outputs from installed base estimates, replacement cycles, and procedure frequency assumptions across the projection horizon. Segmentation dimensions included product type, end user, technology, and application with geographic regulatory cluster overlays. CAGRs derived from trend-line extrapolation of historical reimbursement alignment and MDR compliance upgrade patterns. Industry-specific forecast inputs incorporated AI algorithm validation timelines and telemedicine platform integration adoption curves.
Inputs from FDA 510(k) databases and German notified body review queues were available through the study window; gaps in real-time CMOS sensor allocation data from Japanese suppliers introduce uncertainty bands around hardware shipment projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Pachymeter Market
Diagnostic Instruments
Europe Immunoassay-Gamma Counters Market
Diagnostic Instruments
Lower GI Series Market
Diagnostic Instruments
Blood Flow Measurement Devices Market
Diagnostic Instruments
Gastroesophageal Ph Meter Market
Diagnostic Instruments
US Medical Thermometer Market
Diagnostic Instruments
Global Cell Surface Markers Detection Market
Diagnostic Instruments
Dry Chemistry Analyzers Market
Diagnostic Instruments
Diagnostic Electrocardiograph Market
Diagnostic Instruments
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market
Diagnostic Instruments
Gram Staining System Market
Diagnostic Instruments
Immunoassay Instruments Market
Diagnostic Instruments
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market
Diagnostic Instruments
Tympanometers Market
Diagnostic Instruments
Platelet Aggregation Devices Market
Diagnostic Instruments
Hair Mineral Analyzer Market