
 Resectoscopes Market | 2026-2036
Resectoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Resectoscopes Market Outlook
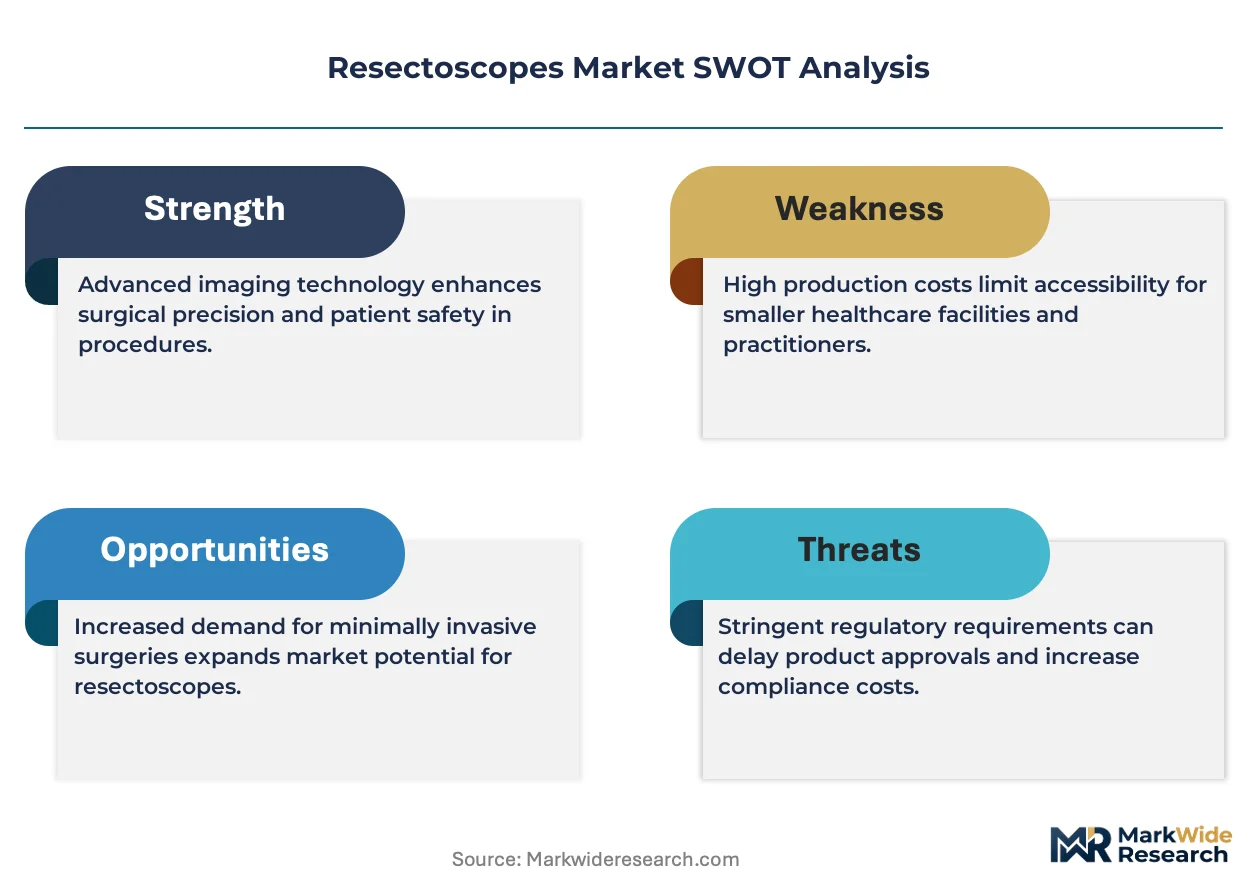
The EU Medical Device Regulation is pivoting procurement criteria across European healthcare systems toward reusable instrument traceability and biocompatibility documentation. Olympus Corporation leverages its end-to-end manufacturing scale to sustain compliance leadership across sterilization protocols. KARL STORZ SE & Co. KG anchors its competitive position through specialized optical systems for minimally invasive urology. Boston Scientific Corporation differentiates via integrated electrosurgical generator compatibility across hospital networks.
A resectoscope is a rigid endoscopic instrument featuring a built-in electrosurgical loop, sheath, and optical channel designed for tissue resection and coagulation during transurethral or hysteroscopic procedures; standard working lengths range from 180 to 280 millimeters with 4-millimeter rod-lens optics. Bipolar resectoscopes now lead product category preference due to reduced fluid absorption risks and broader patient eligibility, while disposable resectoscopes capture fastest-growing share in ambulatory settings where sterilization infrastructure remains limited. Electrosurgery dominates technology deployment, though robotic-assisted surgery integration is expanding in academic hospital systems seeking precision control for complex resections.
FDA 510(k) clearance pathways shape United States market entry timelines for novel resectoscope designs, while EUDAMED registration requirements enforce post-market surveillance obligations across European Economic Area states. Japan's PMDA maintains distinct biological safety testing standards that filter non-compliant imports from Western manufacturers. Stakeholders must monitor evolving reimbursement codes for outpatient hysteroscopy and transurethral resection procedures across Medicare, NHS England, and Japan's MHLW fee schedules to align portfolio investments with shifting site-of-care economics.
Market Dynamics
The transition from monopolar to bipolar electrosurgical systems constitutes the dominant structural force reshaping competitive positioning across resectoscope procurement channels. EUDAMED traceability mandates are accelerating this technology displacement while compressing reimbursement timelines for legacy instrument categories.
Growth Catalysts
- Bipolar Electrosurgery:Reduced fluid absorption risks and broader patient eligibility criteria are expanding procedure volumes across outpatient urology and gynecology settings.
- EUDAMED Traceability Mandates:The EU Medical Device Regulation is pivoting procurement criteria toward reusable instrument documentation and sterilization protocol compliance.
- Aging Demographics:Germany, the United States, and Japan are experiencing sustained transurethral resection volume expansion driven by prostate and bladder pathology prevalence.
Market Restraints
- Capital Equipment Intensity:Bipolar electrosurgical generators require substantial upfront investment, limiting adoption in ambulatory settings with constrained capital budgets.
- Supply Concentration:Optical component manufacturing concentrates among specialized German and Japanese suppliers, creating vulnerability to regional production disruptions.
- Regulatory Friction:Japan's PMDA maintains distinct biological safety testing standards that filter non-compliant imports and extend market entry timelines.
Strategic Opportunities
- Disposable Resectoscopes:Ambulatory surgery centers lacking sterilization infrastructure represent an underpenetrated channel for single-use instrument categories.
- Robotic-Assisted Integration:Academic hospital systems are converging resectoscope platforms with precision surgical robotics for complex resection procedures.
- Outpatient Reimbursement Expansion:Medicare and NHS England fee schedule revisions for transurethral resection and hysteroscopy are creating site-of-care economics favorable to high-volume ambulatory providers.
Industry Challenges
- Electrosurgical Generator Compatibility:Integration complexity with legacy hospital network infrastructure requires specialized biomedical engineering support and extended implementation cycles.
- Sterilization Protocol Standardization:Variability in hydrogen peroxide plasma and steam sterilization validation across health systems complicates multi-site instrument deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resectoscopes Market |
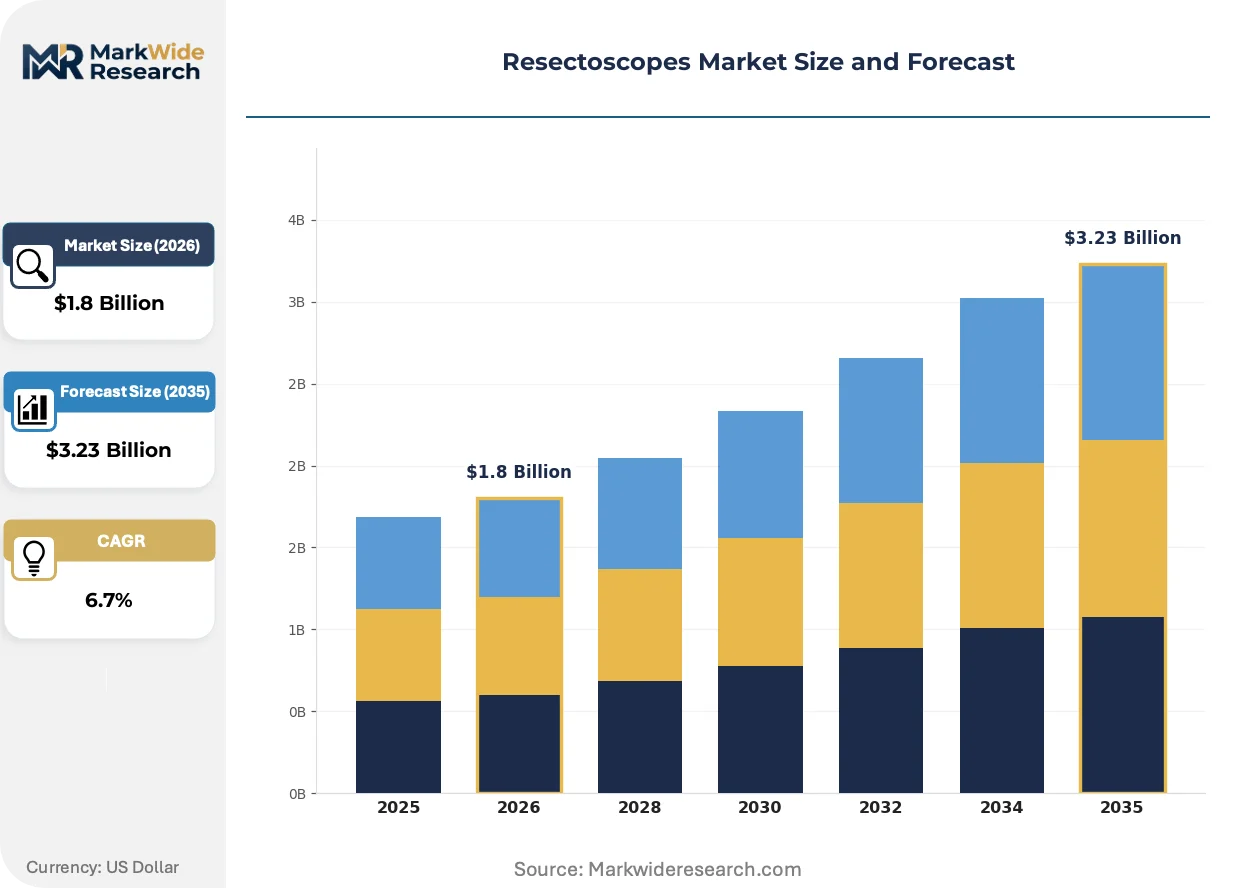
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
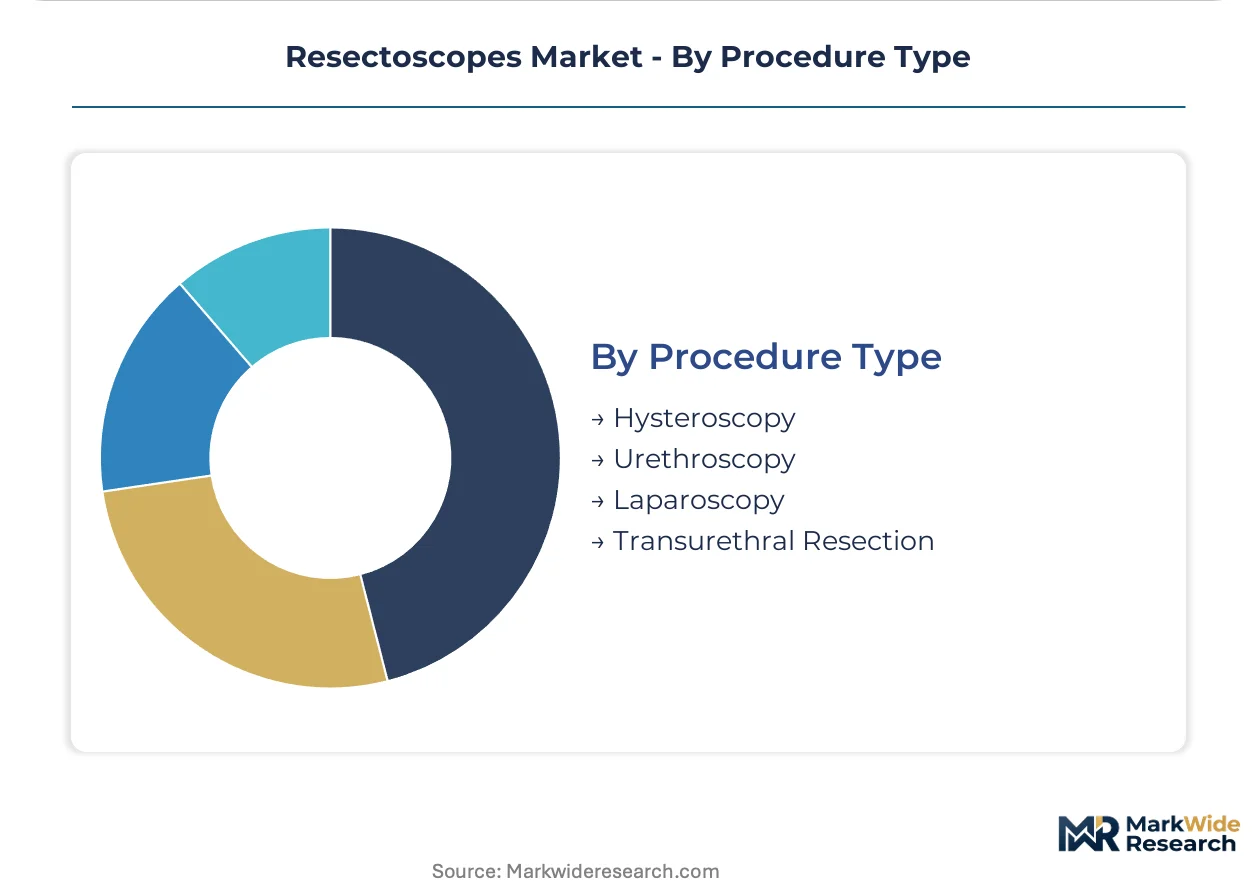
| Segmentation | Product Type: Monopolar Resectoscopes, Bipolar Resectoscopes, Hybrid Resectoscopes, Disposable Resectoscopes End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Technology: Optical Coherence Tomography, Electrosurgery, Robotic-assisted Surgery, Video Endoscopy Procedure Type: Hysteroscopy, Urethroscopy, Laparoscopy, Transurethral Resection |
| Companies Covered | Olympus Corporation, Stryker, KARL STORZ SE & Co. KG, Richard Wolf GmbH, Boston Scientific Corporation, Medtronic, Hologic, Inc, Cook Medical, PENTAX Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resectoscopes Market Strategic Shifts
Bipolar electrosurgical architectures are absorbing market share from monopolar systems through measurable safety profile improvements and expanded patient eligibility. Three interconnected developments are restructuring technology adoption patterns and procurement decision frameworks.
Bipolar resectoscope technology is absorbing procedural volume previously captured by monopolar platforms through reduced TUR syndrome risk and saline irrigation compatibility. Academic medical centers in the United States and Germany are adopting these systems at accelerated replacement cycles. The technology shift is compressing residual value for monopolar instrument inventories and forcing distributor portfolio rebalancing.
Europe's Medical Device Regulation is enforcing post-market surveillance obligations through EUDAMED registration requirements that extend across all European Economic Area states. Manufacturers must maintain sterilization protocol documentation and biocompatibility testing records for reusable instrument traceability. Bipolar resectoscope categories face heightened compliance scrutiny relative to disposable alternatives due to reprocessing complexity.
Hospital procurement departments are consolidating vendor relationships around integrated electrosurgical generator compatibility to reduce training burden and spare parts fragmentation. Multi-hospital networks in Germany and Japan are replacing fragmented instrument purchasing with standardized platform contracts. This concentration is most visible in metropolitan hospital systems seeking volume-based pricing leverage across urology and gynecology service lines.
Resectoscopes Market Segmentation
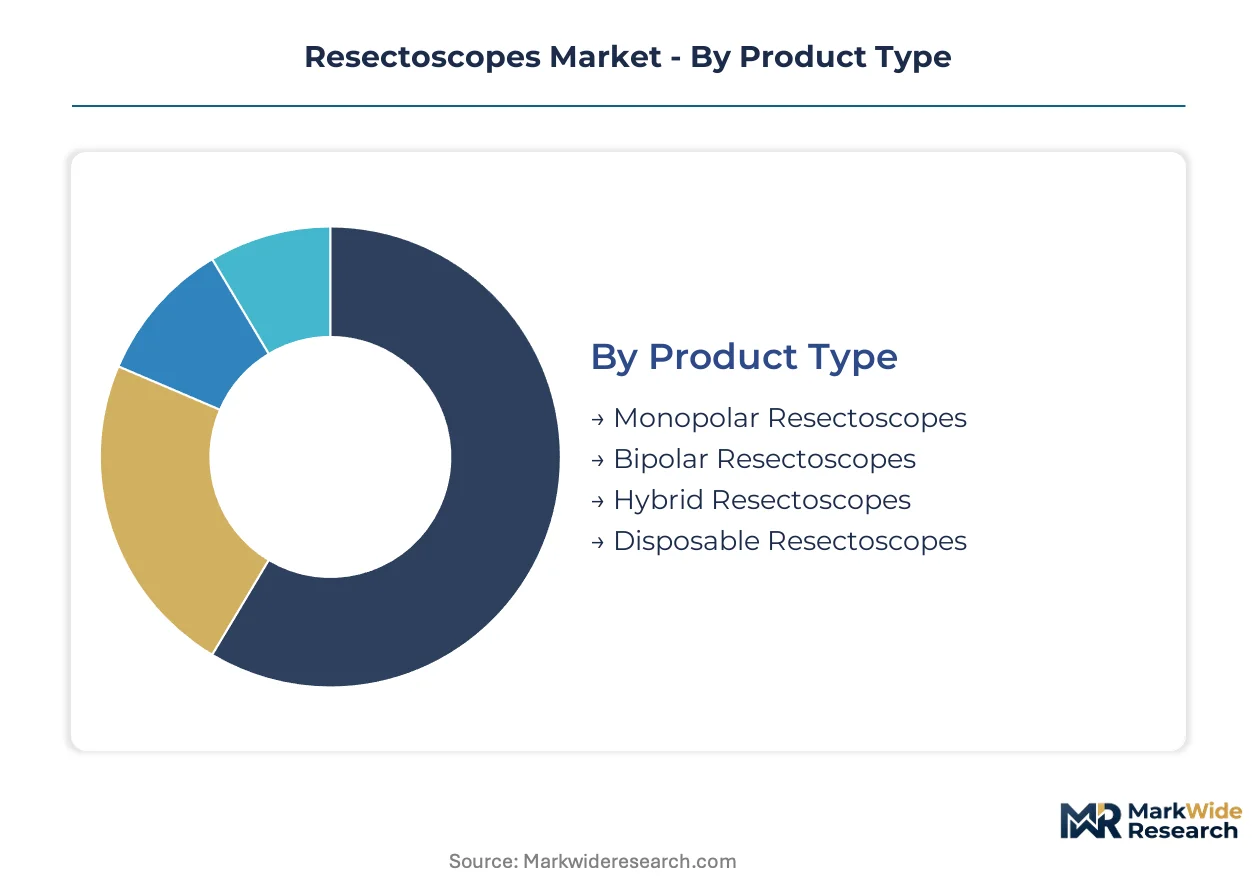
Resectoscope procurement decisions diverge sharply across clinical settings and technological architectures. Manufacturers must align portfolio investments with distinct sterilization capabilities, reimbursement codes, and precision requirements that vary by procedure type and facility infrastructure.
Product Type:
Volume concentration favors established reusable platforms, while premium pricing migrates toward safety-enhanced and single-use alternatives.
- Bipolar Resectoscopes:These instruments deploy isolated current return paths enabling saline irrigation, eliminating TUR syndrome risk in transurethral prostate procedures. German hospital systems and United States academic medical centers are replacing monopolar inventories at accelerated replacement cycles under updated AUA guidelines. EUDAMED traceability mandates favor these systems due to established sterilization protocol documentation.
- Disposable Resectoscopes:Single-use polycarbonate instruments eliminate reprocessing overhead for ambulatory surgery centers lacking hydrogen peroxide plasma infrastructure. Japan's constrained sterilization technician workforce and NHS England's outpatient hysteroscopy expansion are concentrating demand in metropolitan clusters lacking centralized sterilization departments.
- Monopolar Resectoscopes:Glycine-dependent irrigation systems retain installed base in developing health systems with limited capital replacement budgets.
- Hybrid Resectoscopes:Modular platforms accommodating both monopolar and bipolar generator compatibility serve mixed-procedure hospital networks seeking vendor consolidation.
Today's leader: Bipolar Resectoscopes. Tomorrow's challenger: Disposable Resectoscopes.
End User:
Facility-scale economics determine capital intensity tolerance and reprocessing investment capacity.
- Hospitals:Integrated delivery networks in Germany and the United States sustain multi-generator electrosurgical suites supporting high-volume urology and gynecology service lines with dedicated biomedical engineering support.
- Ambulatory Surgical Centers:These facilities are expanding transurethral resection volumes under Medicare's site-neutral payment reforms, though capital constraints favor disposable instrument categories or generator leasing arrangements.
- Specialty Clinics:Gynecology-focused practices in Japan's urban corridors are adopting compact hysteroscopy systems with integrated video processors for office-based procedures.
- Research Institutions:Academic medical centers in the United States are piloting robotic-assisted resectoscope integration for precision oncology applications requiring intraoperative margin assessment.
Procurement authority concentrates in Hospitals. Volume expansion accelerates fastest in Ambulatory Surgical Centers.
Technology:
Core energy delivery methods compete with adjunctive imaging and automation layers for incremental value capture.
- Electrosurgery:Radiofrequency-based tissue resection and coagulation remain the foundational energy modality, with bipolar architectures displacing monopolar systems across European Economic Area markets under MDR compliance timelines.
- Video Endoscopy:High-definition rod-lens optics with digital image processing are standardizing across German and Japanese hospital procurement specifications, replacing fiberoptic alternatives.
- Optical Coherence Tomography:Real-time subsurface tissue imaging is emerging in academic settings for bladder cancer margin assessment during transurethral resection.
- Robotic-assisted Surgery:Precision instrument positioning systems are penetrating high-complexity academic centers in the United States for en bloc resection procedures requiring submillimeter control.
Electrosurgery commands current volume. Robotic-assisted Surgery claims the steepest expansion trajectory.
Procedure Type:
Reimbursement code valuations and site-of-care migration patterns reshape demand concentration across anatomical applications.
- Transurethral Resection:Prostate and bladder tumor resections drive the highest instrument utilization intensity, with bipolar saline-irrigated systems preferred for elderly patient cohorts in Japan and Germany.
- Hysteroscopy:Diagnostic and operative uterine procedures are migrating to outpatient settings under revised NHS England and Medicare fee schedules, favoring smaller-diameter instrument platforms.
- Urethroscopy:Stricture evaluation and intervention procedures require flexible or rigid optical systems depending on anatomical complexity and provider preference.
- Laparoscopy:Abdominal access procedures utilizing resectoscope-derived electrosurgical loops represent a niche application in gynecologic oncology.
Transurethral Resection anchors revenue. Hysteroscopy is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered rigid endoscope manufacturing in the early twentieth century, establishing optical engineering clusters that persist today. Japanese and American firms subsequently scaled production, creating a tripartite supply structure concentrated in high-precision manufacturing corridors.
Germany
Bipolar electrosurgery adoption accelerates across Baden-Württemberg and Bavaria hospital networks under EUDAMED traceability mandates. The MDR requires sterilization protocol documentation for reusable instruments, favoring established German manufacturers with compliant quality systems. Tübingen and Stuttgart surgical device clusters concentrate optical component fabrication and electrosurgical generator assembly.
United States
Academic medical centers in Boston and Houston drive robotic-assisted resectoscope integration for precision oncology applications. FDA 510(k) clearance pathways shape market entry timelines for novel instrument designs, with Medicare site-neutral payment reforms expanding ambulatory procedure volumes. The Southeast corridor from Florida to Georgia concentrates ambulatory surgery center construction.
Japan
Aging demographics in Kanto and Kansai regions sustain transurethral resection volume expansion for prostate pathology. PMDA biological safety testing standards filter non-compliant Western imports, extending market entry timelines for foreign manufacturers. Nagoya and Osaka maintain specialized optical systems manufacturing for domestic hospital procurement.
United Kingdom
NHS England fee schedule revisions for outpatient hysteroscopy accelerate site-of-care migration from inpatient settings. The MHRA enforces post-market surveillance aligned with EUDAMED requirements, though with distinct implementation timelines. London and Manchester metropolitan hospital systems consolidate vendor relationships around integrated generator compatibility.
India
Private hospital chains in Maharashtra and Karnataka expand urology service lines with capital equipment leasing arrangements. CDSCO medical device registration requirements are tightening for imported electrosurgical systems, favoring local assembly partnerships. Chennai and Hyderabad surgical device distributors build sterilization infrastructure for reusable instrument reprocessing.
Resectoscopes Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology integration depth and regulatory compliance documentation. The vendor base stratifies into three tiers: full-stack electrosurgical platform providers, specialized optical instrument fabricators, and regional disposable instrument suppliers. Dominant competitive moves include generator-instrument bundling contracts and sterilization protocol standardization across hospital networks.
Within the full-stack platform tier, Olympus Corporation and Boston Scientific Corporation occupy positions defined by end-to-end manufacturing scale and integrated generator compatibility. KARL STORZ SE & Co. KG exemplifies the specialized optical systems archetype, anchoring competitive positioning through precision engineering heritage. These three firms represent distinct strategic approaches: manufacturing breadth, electrosurgical integration, and optical specialization.
| Leading Market Players |
|---|
| Olympus Corporation |
| Stryker |
| KARL STORZ SE & Co. KG |
| Richard Wolf GmbH |
| Boston Scientific Corporation |
| Medtronic |
| Hologic, Inc |
| Cook Medical |
| PENTAX Medical |
| Others |
Value Chain & Pricing Dynamics
EUDAMED sterilization protocol documentation gates qualified supply for reusable bipolar resectoscope platforms and anchors premium-tier pricing access for manufacturers with compliant quality systems. German and Japanese hospital procurement departments leverage this compliance filter to consolidate vendor relationships around integrated electrosurgical generator platforms, compressing margins for non-compliant instrument categories.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates MDR-compliant bipolar systems with full traceability documentation from legacy monopolar inventories and basic disposable alternatives. Price differentiation rests on sterilization validation depth and generator compatibility certification, with academic medical centers in Germany and the United States showing lowest price sensitivity. Cost compression in the standard tier is intensifying because NHS England and Medicare site-neutral payment reforms favor ambulatory providers with constrained capital budgets.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Minneapolis anchor hub-and-spoke patterns serving metropolitan hospital networks with dedicated biomedical engineering support. Optical rod-lens fabrication concentrates in Baden-Württemberg and Osaka prefectures, drawing from specialized glass-ceramic suppliers and precision electrosurgical generator component manufacturers. Single-source vulnerability in hydrogen peroxide plasma sterilization equipment exposes multi-site instrument deployment to regional production disruptions. Distribution runs through GPO contracts and direct hospital system agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through bipolar platform replacement cycles and disposable category premiumization in sterilization-constrained settings. Cost-down drivers include generator-instrument bundling contracts and standardized reprocessing protocols across integrated delivery networks.
For Market Incumbents: Deploy sterilization protocol standardization as the primary lever to defend installed base against disposable resectoscope entrants targeting ambulatory surgery centers. Consolidate biomedical engineering service contracts across German and United States hospital networks to raise switching costs. Deepen backward integration into optical component fabrication to secure supply continuity from Baden-Württemberg and Osaka manufacturing clusters. For New Entrants and Emerging Players: EUDAMED traceability mandates in the European Economic Area open a window for disposable resectoscope categories that eliminate reprocessing documentation overhead. Target ambulatory surgery centers in Japan's urban corridors and NHS England outpatient hysteroscopy expansion zones where sterilization technician scarcity constrains reusable instrument adoption. Pursue generator leasing arrangements rather than capital equipment sales to bypass upfront investment barriers. For Investors and Strategic Acquirers: Roll-up economics work for specialized optical instrument fabricators because hospital procurement consolidation favors vendors with end-to-end sterilization validation capabilities. Mid-cap targets with established PMDA biological safety testing records and CE marking pathways offer defensive positioning against regulatory friction. Watch Medicare and NHS England fee schedule revisions for outpatient transurethral resection as the signal indicating ambulatory volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Pathway | EUDAMED traceability documentation secures hospital procurement eligibility across European Economic Area states. |
| Hospital System Partnership | Integrated generator compatibility contracts reduce training burden and spare parts fragmentation for multi-site networks. |
| Disposable Platform Launch | Single-use polycarbonate instruments capture ambulatory surgery center volumes lacking hydrogen peroxide plasma infrastructure. |
| Robotic Integration Development | Precision instrument positioning systems penetrate academic medical centers for complex en bloc resection procedures. |
| Reimbursement Strategy | Site-of-care economics alignment with Medicare and NHS England fee schedules accelerates outpatient procedure migration. |
Study Parameters
Multiple input streams — primary interviews with urology service line directors and GPO contracts managers, secondary validation through FDA 510(k) filings and EUDAMED registration databases, and hospital procurement database analysis — were reconciled using bottom-up instrument shipment tracking and top-down electrosurgical suite installation estimates. Clinicians, biomedical engineers, and sterilization department supervisors across Germany, the United States, and Japan provided procedure volume and technology preference intelligence. Trade customs data and SEC medical device segment disclosures supplied manufacturing capacity and revenue allocation benchmarks.
Historical shipment patterns were cross-referenced against panel input from hospital purchasing committees to model adoption curves across the projection horizon. Segmentation dimensions included product architecture (bipolar, monopolar, disposable, hybrid), end-user facility type, energy delivery technology, and anatomical procedure application. CAGRs were derived from installed base replacement cycle analysis and outpatient reimbursement code expansion trajectories. Procedure volume forecasts incorporated aging demographic projections and prostate pathology prevalence data from national health registries.
Revisions become necessary when PMDA biological safety testing standards tighten, EUDAMED implementation timelines shift, or Medicare site-neutral payment reforms accelerate faster than modeled. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Surgical Snare Market
Surgical Instruments
Disposable Spinal Instruments Market
Surgical Instruments
Huber Needles Market
Surgical Instruments
Minimally Invasive Surgical Instruments Market
Surgical Instruments
Global Minimally Invasive Surgery (MIS) Market
Surgical Instruments
Dissolvable Sutures Market
Surgical Instruments
Global Urology Surgical Instruments Market
Surgical Instruments
United States Minimally Invasive Surgery Market
Surgical Instruments
Iris Retractors Market
Surgical Instruments
Neurosurgery Surgical Power Tools Market
Surgical Instruments
Laparoscopic Sutures Market
Surgical Instruments
High Flow Needle Sets Market
Surgical Instruments
Global Myomectomy Market
Surgical Instruments
Articulating Paper Forceps Market
Surgical Instruments
Biosurgery Market
Surgical Instruments
Global Surgical Booms Market