
 India Surgical Sutures Market | 2026-2036
India Surgical Sutures Market Size, Share, and Industry Trends Forecast 2026-2036
India Surgical Sutures Market Outlook
Market Context with Strategic Players
Multi-source procurement among hospital chains is repositioning how suture vendors compete for institutional contracts. Healthium Medtech Limited leverages its domestic manufacturing footprint to anchor supply agreements with government health programs. Medtronic PLC sustains premium positioning through specialized cardiovascular suture lines. Johnson & Johnson (Ethicon Inc) dominates the high-end absorbable segment with proprietary polymer technology.
Technical Definition and Structural Segments
Surgical sutures are sterile threads manufactured from natural or synthetic polymers, designed to approximate wound edges with tensile strengths ranging from 0.5 to 8.0 metric dimensions depending on tissue requirements. These devices serve the fundamental purpose of maintaining wound closure during healing phases across operative procedures. Absorbable sutures built from polyglactin polymers capture expanding share in gastrointestinal and orthopedic applications where internal tissue support degrades predictably. Non-absorbable sutures in polypropylene and nylon sustain durable demand in cardiovascular and cosmetic surgery where long-term wound integrity remains critical. Hospitals as the dominant end-user channel concentrate procurement volume, while ambulatory surgical centers represent the fastest-growing outlet for minimally invasive closure products.
Regulatory Framework and Forward Outlook
CDSCO's Medical Device Rules framework, BIS certification requirements, and the phased alignment with ISO 13485 standards collectively elevate compliance costs for new market entrants while reinforcing quality benchmarks for established manufacturers. The PLI scheme for medical devices is channeling capital toward domestic suture production capacity, reducing import dependence for synthetic polymer threads. Stakeholders must monitor how state-level tender reforms reshape procurement concentration and whether domestic polymer sourcing achieves cost parity with imported raw materials.
Market Dynamics
CDSCO's tightened quality standards for medical devices are forcing domestic manufacturers toward ISO-certified production lines, fundamentally reshaping competitive positioning between established importers and emerging domestic suppliers.
Growth Catalysts
- PLI Scheme for Medical Devices:Government incentives are channeling capital toward domestic suture production capacity, reducing import dependence for synthetic polymer threads.
- Maharashtra:Private hospital chains in this state are building dedicated surgical centers, concentrating demand for advanced wound closure products.
- Absorbable Polyglactin Polymers:These materials are capturing expanding share in gastrointestinal and orthopedic applications where internal tissue support degrades predictably.
Market Restraints
- Imported Raw Material Costs:Domestic polymer sourcing has not yet achieved cost parity with imported synthetic threads, compressing margins for local manufacturers.
- BIS Certification Requirements:Compliance costs for new market entrants have risen substantially, creating barriers to market entry.
- Non-Absorbable Sutures:Long-term wound integrity requirements in cardiovascular surgery limit substitution potential for newer materials.
Strategic Opportunities
- Tier-2 Cities:Government hospitals in these locations are expanding procurement of advanced wound closure products, creating underpenetrated demand pockets.
- Ambulatory Surgical Centers:This channel represents the fastest-growing outlet for minimally invasive closure products outside traditional hospital procurement.
- CDSCO-ISO Alignment:Phased harmonization with ISO 13485 standards creates regulatory tailwinds for certified domestic producers to displace uncertified competitors.
Industry Challenges
- ISO 13485 Certification Timelines:Domestic manufacturers face extended compliance periods that delay market access against established competitors.
- Polymer Sourcing Reconfiguration:Supply chain friction persists as manufacturers shift from imported to domestic raw material suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Surgical Sutures Market |
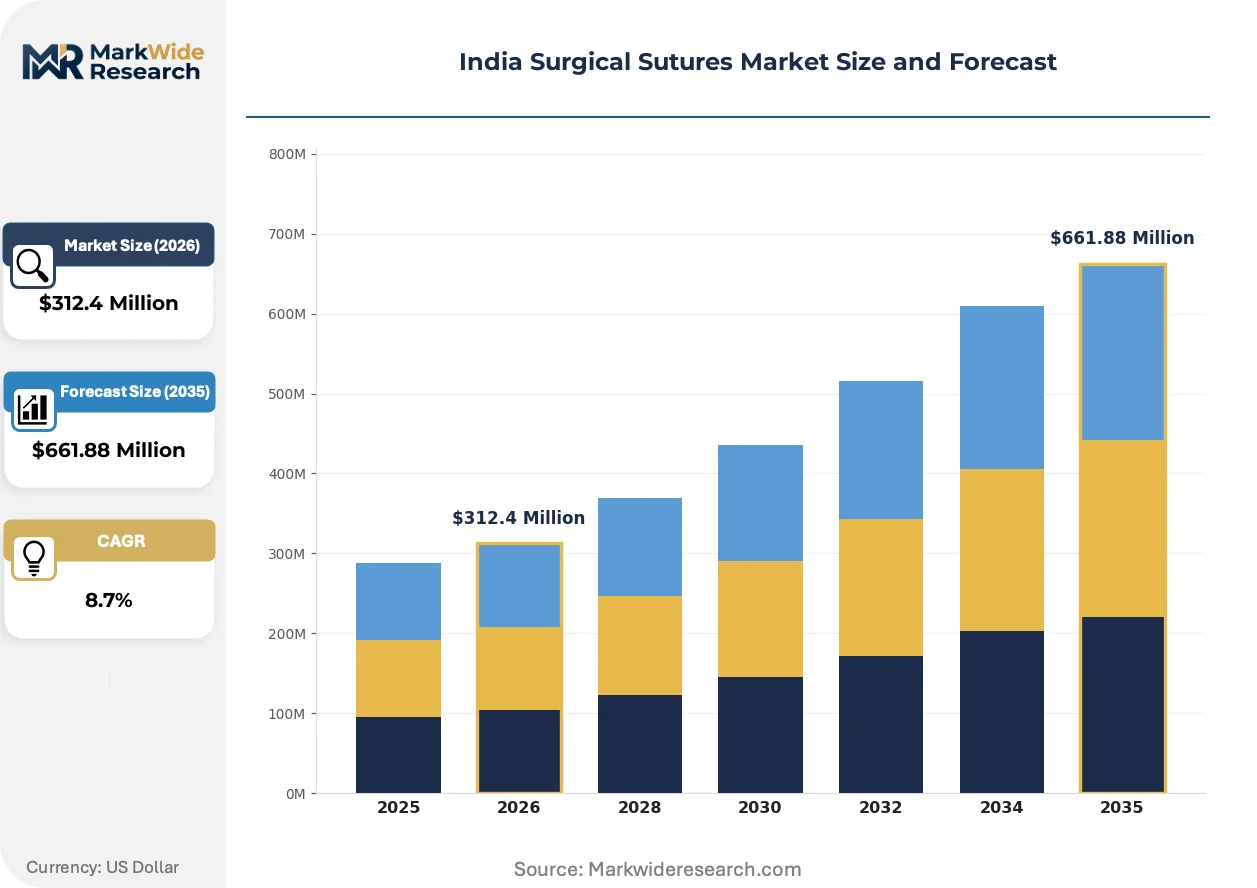
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable Sutures, Non-Absorbable Sutures, Surgical Staples, Combination Sutures Material: Silk, Nylon, Polypropylene, Polyglactin Application: Cardiovascular Surgery, Orthopedic Surgery, Gastrointestinal Surgery, Cosmetic Surgery End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutions |
| Companies Covered | CONMED Corporation, Healthium Medtech Limited, Medtronic PLC, Lotus Surgicals Pvt Ltd, Smith & Nephew PLC, B. Braun SE, Teleflex Incorporated, Unisur Lifecare Private Limited, Johnson & Johnson (Ethicon Inc), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Surgical Sutures Market Strategic Shifts
Antimicrobial coating technologies and polymer engineering advances are compressing healing timelines while CDSCO's evolving framework rewards quality-certified domestic production.
Barbed suture technology is modularizing wound closure procedures by eliminating knot-tying steps and reducing operative time. Tertiary care centers in Gujarat and Tamil Nadu are adopting these devices for laparoscopic applications. The structural consequence is compression of training curves for surgical residents while enabling faster patient throughput.
CDSCO's Medical Device Rules framework is elevating documentation and traceability requirements across the supply chain. Domestic manufacturers must now maintain batch-level quality records that match import standards. The absorbable suture segment faces the steepest compliance adjustment as these products carry higher biological risk classifications.
Hospital procurement committees are consolidating vendor lists around multi-year supply agreements with quality-certified manufacturers. Government tender reforms in Maharashtra and Gujarat are replacing single-source awards with panel contracts spanning three to five approved suppliers. This pattern is most visible in state-level health programs where audit scrutiny of procurement decisions has intensified.
India Surgical Sutures Market Segmentation
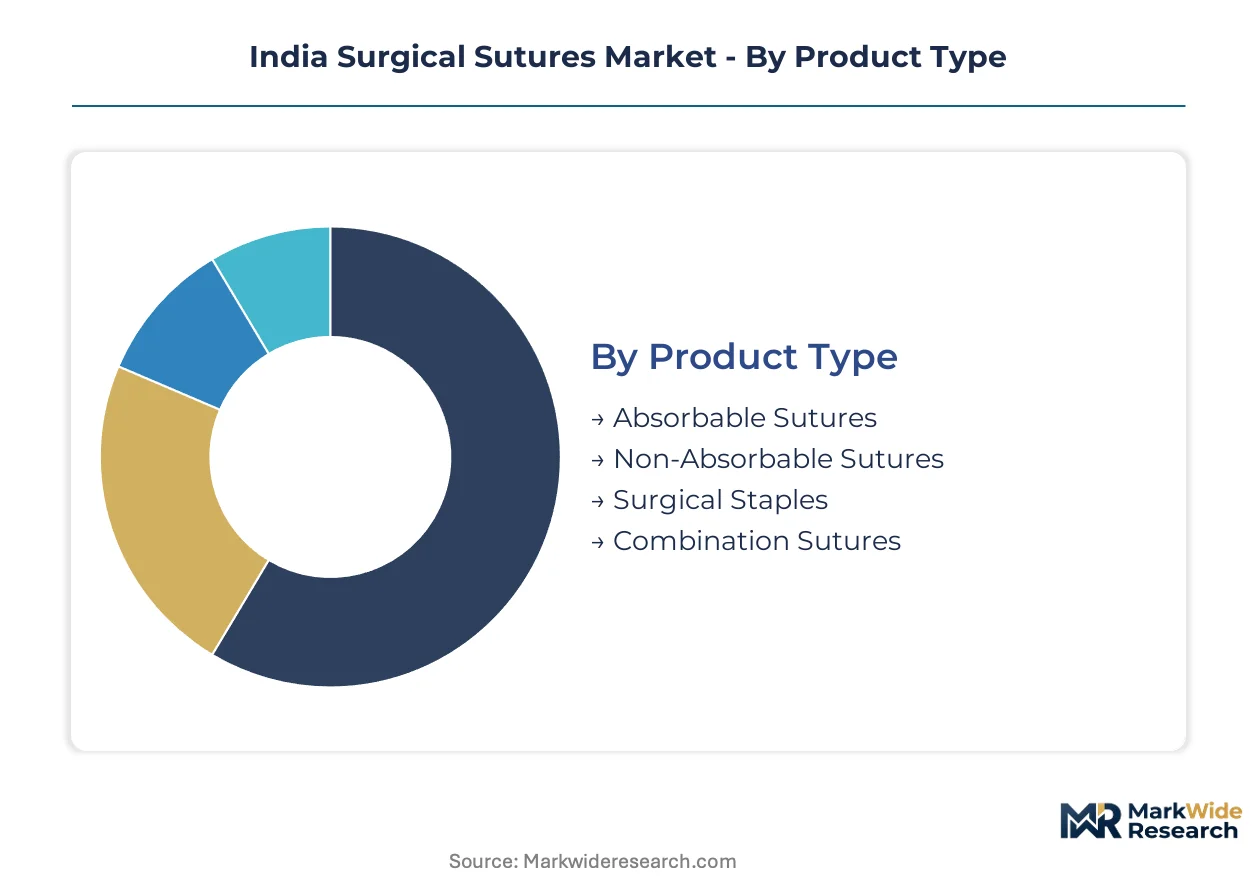
Segmentation in the India surgical sutures market reveals how procurement priorities diverge across institutional buyers and procedural requirements. Understanding these splits enables manufacturers to align production capacity with the specific compliance and performance standards each segment demands.
Product Type:
Capital intensity varies sharply across product categories, with absorbable polymer lines requiring sterile fermentation and extrusion infrastructure that non-absorbable threads do not.
- Absorbable Sutures:Polyglactin and polydioxanone polymers degrade through hydrolysis, eliminating removal procedures. Demand concentrates in Maharashtra's government hospital expansion for gastrointestinal and orthopedic procedures where internal support must dissolve predictably.
- Non-Absorbable Sutures:Polypropylene and nylon threads maintain tensile strength indefinitely. Cardiovascular centers in Tamil Nadu drive procurement for procedures requiring permanent wound integrity, though CDSCO's tightened biological risk classifications elevate documentation burdens for these imports.
- Surgical Staples:Metal and polymer clips compress tissue edges mechanically. Ambulatory surgical centers in Gujarat adopt these for rapid closure in laparoscopic cases.
- Combination Sutures:Hybrid designs integrate absorbable cores with non-absorbable sheaths. Research institutions in tier-2 cities trial these for complex trauma reconstruction.
Absorbable sutures absorb the bulk of installed capacity; combination sutures are expanding most quickly.
Material:
Raw material sourcing geography determines margin structure, with imported synthetic polymers carrying currency and duty exposure that domestic silk and nylon do not.
- Polyglactin:Synthetic copolymer of glycolide and lactide engineered for predictable degradation rates. Private hospital chains in Maharashtra specify this for orthopedic soft-tissue repair where absorption timing correlates with healing phases.
- Polypropylene:Monofilament polymer with minimal tissue reactivity and permanent tensile retention. Cardiovascular surgery units across Tamil Nadu and Gujarat favor this for vascular anastomosis requiring lifelong patency.
- Silk:Natural protein fiber braided for handling ease. Traditional general surgery applications in government hospitals persist despite synthetic substitution.
- Nylon:Polyamide monofilament with high elasticity and low tissue drag. Cosmetic surgery clinics specify this for subcuticular closures where scar minimization matters.
Polyglactin commands the highest unit economics; polypropylene maintains steadiest volume throughput.
Application:
Procedure complexity dictates suture specification, with cardiovascular and orthopedic segments requiring specialized tensile and handling properties that general surgery does not.
- Orthopedic Surgery:Tendon and ligament repair demands high initial tensile strength with gradual load transfer as tissue heals. Sports medicine centers in Maharashtra and Tamil Nadu drive consumption of braided polyglactin variants.
- Cardiovascular Surgery:Vascular anastomosis requires permanent, non-reactive monofilament with precise diameter control. Tertiary centers in Gujarat concentrate procurement of imported polypropylene for coronary bypass procedures.
- Gastrointestinal Surgery:Bowel anastomosis relies on absorbable material that maintains strength through critical healing windows. Government hospital expansions in tier-2 cities elevate demand for cost-optimized polyglactin.
- Cosmetic Surgery:Subcuticular and intradermal closures prioritize scar minimization over tensile strength. Private clinics in metropolitan areas specify fine-gauge nylon and proprietary absorbable monofilaments.
Orthopedic surgery absorbs the bulk of polymer innovation investment; cosmetic surgery climbs the fastest as disposable incomes rise.
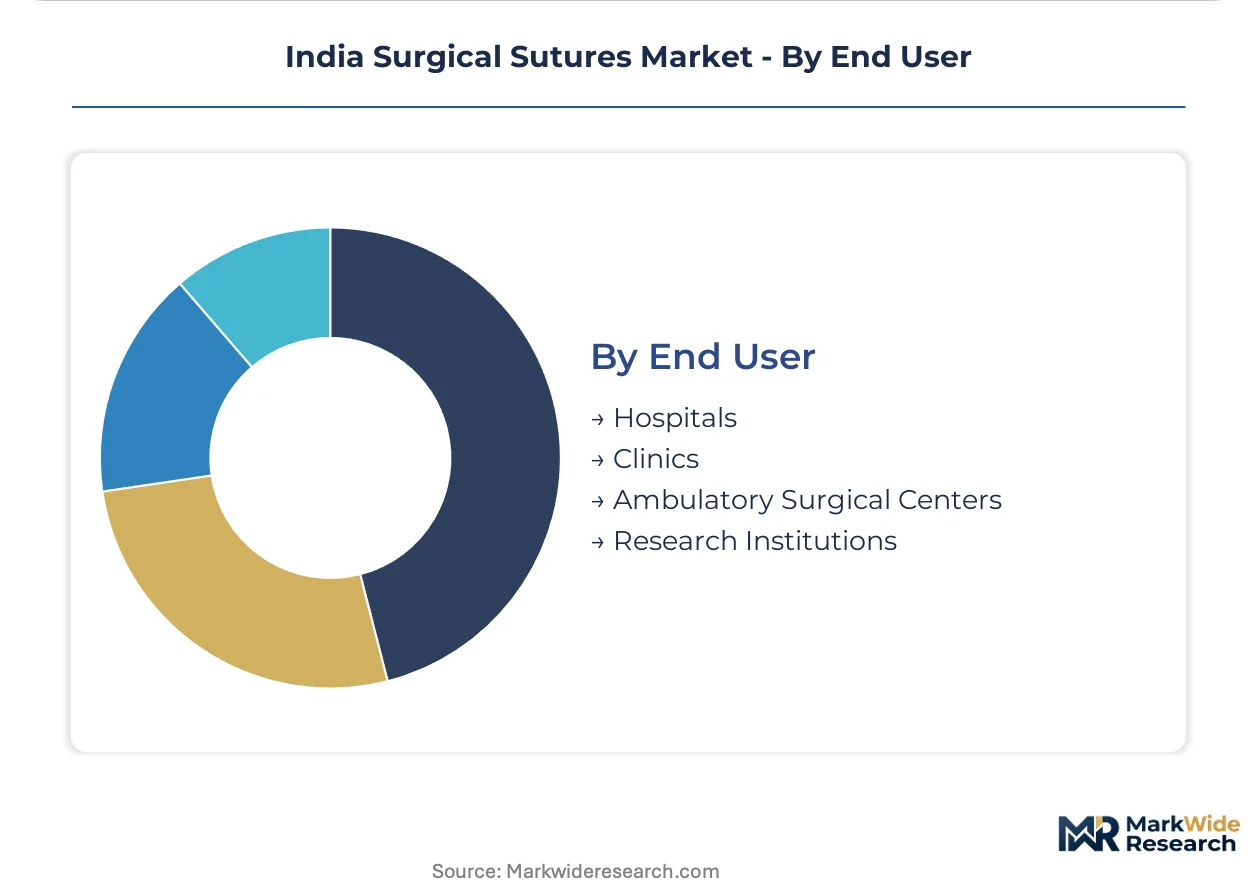
End User:
Procurement scale and specification authority diverge across institutional types, with hospitals consolidating multi-year vendor contracts that smaller facilities cannot negotiate.
- Hospitals:Multi-specialty institutions with centralized purchasing committees and CDSCO-mandated quality documentation. Maharashtra's state health programs and private chains anchor volume concentration.
- Ambulatory Surgical Centers:Focused facilities performing same-day procedures with compressed supply chains. Gujarat's laparoscopy-focused centers drive fastest adoption of barbed and stapled closure technologies.
- Clinics:Small-scale surgical practices with limited sterilization infrastructure. Tier-2 city dermatology and minor surgery units source pre-sterilized disposable suture packs.
- Research Institutions:Academic medical centers evaluating novel materials and techniques. Tamil Nadu's surgical training hubs trial antimicrobial-coated and bioactive suture variants.
Hospitals absorb the bulk of vendor relationship investment; ambulatory surgical centers are gaining share fastest as procedure migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer feedstock clusters in Gujarat and Maharashtra anchor domestic suture manufacturing capacity. State-level procurement reforms and CDSCO compliance timelines are redistributing demand across India's tiered hospital network.
Maharashtra
Private hospital chains in Mumbai and Pune are constructing dedicated surgical centers with centralized purchasing authority. The state health department's panel-contract reforms now require three to five approved suppliers per tender, displacing single-source arrangements. Tertiary cardiac centers in Mumbai concentrate polypropylene procurement for coronary bypass procedures.
Gujarat
Ambulatory surgical centers in Ahmedabad and Surat are adopting barbed suture technology for laparoscopic throughput gains. CDSCO's Medical Device Rules enforcement has accelerated ISO 13485 certification among Ahmedabad-based manufacturers. The state's polymer processing corridor supplies raw material to domestic suture extrusion facilities.
Tamil Nadu
Cardiovascular surgery units in Chennai drive permanent monofilament demand for vascular anastomosis requiring lifelong patency. The state's medical device park scheme offers subsidized land and utilities for sterile suture production lines. Research institutions in Coimbatore trial antimicrobial-coated variants for trauma reconstruction.
Karnataka
Bengaluru's medical technology cluster attracts contract manufacturing for absorbable polymer lines. The state's startup policy channels seed funding toward novel wound closure materials. Private equity interest in Bengaluru-based surgical device ventures has intensified following PLI scheme notifications.
Telangana
Hyderabad's pharmaceutical manufacturing base is extending into medical device sterile processing. The state's life sciences park infrastructure supports suture sterilization and packaging operations. Government hospital procurement in tier-2 districts is expanding beyond basic silk and nylon threads.
India Surgical Sutures Market Competitive Environment
Global majors compete with regional champions across certification tiers and procurement channel access. The vendor base stratifies between ISO-certified domestic producers and import-dependent premium suppliers. Three archetypes dominate: multinational technology licensors, vertically integrated domestic champions, and specialized regional fabricators. Competitive moves center on multi-year supply agreement consolidation and sterile production capacity expansion.
Among multinational technology holders, Johnson & Johnson (Ethicon Inc) and Medtronic PLC occupy positions at the premium-absorbable and cardiovascular-specialist vectors respectively. Healthium Medtech Limited exemplifies the domestic champion archetype with government program anchoring. These three represent the certification-tier stratification that CDSCO's quality enforcement is crystallizing.
| Leading Market Players |
|---|
| CONMED Corporation |
| Healthium Medtech Limited |
| Medtronic PLC |
| Lotus Surgicals Pvt Ltd |
| Smith & Nephew PLC |
| B. Braun SE |
| Teleflex Incorporated |
| Unisur Lifecare Private Limited |
| Johnson & Johnson (Ethicon Inc) |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap domestic manufacturers anchor India's suture production base, channeling retained earnings into ISO-certified sterile lines while pricing discipline erodes among import-dependent distributors facing CDSCO compliance deadlines.
Pricing Analysis
Warranty and technical service bundling separates premium-tier multinational supply agreements from unbundled transactional sales by uncertified regional traders. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification status and batch-level traceability documentation. Cost compression in the economy tier is intensifying because domestic polymer sourcing has not achieved import parity. Government hospital procurement committees in Maharashtra exhibit highest price sensitivity, while private cardiac centers in Tamil Nadu absorb premium markups for permanent monofilament lines.
Supply Chain Analysis
Polymer feedstock supply rests on petrochemical producers in Gujarat, specialty chemical manufacturers in South Korea, and monofilament extrusion specialists in Germany. Raw material dependencies span polyglactin copolymers, polypropylene resin grades, and medical-grade dye additives. Single-source vulnerability concentrates in imported synthetic thread precursors subject to DGFT licensing delays. Distribution runs through state-level medical supply corporations, private hospital GPOs, and direct manufacturer contracts with tier-2 government facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into polymer extrusion and sterile packaging represents the decisive vertical-integration race, with CDSCO's ISO alignment timeline rewarding first-movers who capture upstream capacity before compliance deadlines harden.
For Market Incumbents: Deploy multi-year panel contract consolidation with Maharashtra and Gujarat state health programs to lock out emerging domestic competitors. Anchor defensive positioning through captive polypropylene sourcing agreements that offset currency exposure on imported cardiovascular threads. Accelerate sterile fermentation capacity for absorbable polymer lines before CDSCO's biological risk reclassification elevates documentation burdens.
For New Entrants and Emerging Players: Enter via ambulatory surgical center channels in tier-2 Gujarat cities where barbed suture adoption outpaces established vendor relationships. Target pre-sterilized disposable suture packs for clinic-tier dermatology and minor surgery units lacking central sterilization infrastructure. Lead with rapid-turn technical service response that multinational distributors cannot match.
For Investors and Strategic Acquirers: Distressed-cycle entries favor ISO 13485-certified domestic manufacturers with underutilized sterile lines in Tamil Nadu medical device parks. Long-term viability hinges on polymer sourcing reconfiguration achieving cost parity with imports within the analysis window. Watch PLI scheme disbursement velocity as the inflection signal for domestic capacity viability.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acceleration | CDSCO's phased alignment rewards certified producers with preferred vendor status in state tenders. |
| Backward Integration into Polymer Extrusion | Captive polyglactin production reduces import dependence and currency exposure for domestic manufacturers. |
| Hospital System Partnership | Multi-year supply agreements with Maharashtra private chains anchor volume against panel-contract competition. |
| Barbed Suture Technology Licensing | Gujarat ambulatory centers adopt knotless closure for laparoscopic throughput gains. |
| Reimbursement Strategy Alignment | State health program inclusion criteria determine addressable market for economy-tier products. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews among hospital purchasing committee members, biomedical engineers at tertiary cardiac centers, GPO contracts managers, and CDSCO regulatory affairs specialists. CDSCO Medical Device Rules notifications, BIS certification databases, state tender award records, and PLI scheme disbursement filings supplied quantitative anchors. Bottom-up suture volume estimates by procedure type triangulated against top-down polymer import value trends.
Segment-level modeling tracked absorbable versus non-absorbable product splits, polyglactin versus polypropylene material shares, and orthopedic versus cardiovascular versus gastrointestinal application demand across the projection horizon. State-level procurement reform timelines and CDSCO compliance phase-ins fed scenario-weighted CAGRs. Hospital bed expansion data and ambulatory surgical center registration counts supplied procedure-volume proxies.
Forecast precision tightens around the base case; tail outcomes carry wider variance under polymer sourcing reconfiguration delays or PLI scheme disbursement disruptions. Forecasts reflect assumptions around CDSCO enforcement intensity and state tender reform adoption velocity. A small set of named triggers—domestic polymer cost parity achievement, barbed suture reimbursement inclusion, and tier-2 government hospital procurement expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Ischemic Stroke Surgery Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Knee Surgical Impactor Market
Surgical Instruments
Global Surgical Scissors Market
Surgical Instruments
Americas Suture Needles Market
Surgical Instruments
Tonsil and Adenoid Removal Products Market
Surgical Instruments
Surgical Snare Market
Surgical Instruments
US Surgical Sutures Market
Surgical Instruments
Uro Gynaecological Surgical Devices Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
Electrocautery Enhanced Delivery System Market
Surgical Instruments
Global Biopsy Needles Market
Surgical Instruments
Global Microsurgical Instruments Market
Surgical Instruments
Skin Graft Blades Market
Surgical Instruments
Surgical Stapling Devices Market