
 Global Minimally Invasive Surgery (MIS) Market | 2026-2036
Global Minimally Invasive Surgery (MIS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Minimally Invasive Surgery (MIS) Market Foresight
Specialized laparoscopic surgeon training capacity is rotating toward robotic-assisted platforms across academic medical centers, constraining pure manual MIS expansion in smaller facilities. Medtronic leverages integrated surgical ecosystems spanning energy devices to navigation platforms. Johnson & Johnson sustains broad procedure coverage across endomechanical and advanced stapling portfolios. Intuitive Surgical dominates robotic surgery systems with installed base density in North American specialty hospitals.
Minimally invasive surgery encompasses operative techniques performed through small incisions using specialized instruments, cameras, and energy devices, typically requiring pneumoperitoneum insufflation pressures of 12-15 mmHg for abdominal access and high-definition imaging with 1080p or 4K resolution for visual fidelity. The primary commercial purpose centers on reducing postoperative morbidity, shortening hospital length of stay, and enabling same-day discharge protocols across gastrointestinal and gynecological procedures. Robotic surgery systems command premium capital placement cycles and recurring instrument revenue streams, while laparoscopy maintains volume leadership in cost-sensitive settings. Electrosurgical devices concentrate margin pools through disposable generator-compatible handpieces with proprietary connectors.
FDA 510(k) clearance pathways and CE marking under the EU MDR govern device safety and clinical validation requirements, with FDA scrutiny intensifying for software-enabled surgical navigation systems. ISO 13485 quality management standards and IEC 60601-1 electrical safety specifications shape manufacturing compliance for electrosurgical and laser-based platforms. Stakeholders must monitor reimbursement parity between robotic and conventional laparoscopic codes as health technology assessment bodies in Germany and Japan recalibrate procedure valuations.
Market Dynamics
Robotic-assisted surgical platforms are decomposing traditional laparoscopic training hierarchies across academic medical centers, forcing hospital systems to reallocate capital toward integrated digital ecosystems rather than standalone instrument procurement.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for electrosurgical handpieces with proprietary generator interfaces reduce commercialization friction for validated device categories.
- Japan's aging surgical population:METI reimbursement alignment for outpatient MIS procedures drives same-day discharge protocol adoption in Tokyo and Osaka hospital clusters.
- 4K visualization systems:Ultra-high-definition laparoscopes compress visual fidelity gaps between manual and robotic platforms in cost-sensitive German ambulatory centers.
Market Restraints
- Capital intensity concentration:Robotic surgery systems require eight-figure capital commitments with seven-year depreciation cycles, freezing smaller US community hospitals in leasing dependency.
- EU MDR transition friction:Extended clinical validation timelines for legacy electrosurgical devices under 2017/745 recast directives delay CE marking renewals for mid-tier manufacturers.
- Insufflation gas supply volatility:Medical-grade CO2 sourcing bottlenecks from industrial gas consolidation in the Rhine-Ruhr corridor inflate per-procedure consumable costs.
Strategic Opportunities
- India's tier-2 city penetration:CDSCO streamlined import licensing for refurbished laparoscopic towers opens procedural access in Pune, Kochi, and Jaipur private hospital chains.
- AI-enabled surgical navigation:Convergence of intraoperative imaging with real-time instrument tracking creates premium positioning for software-integrated platform vendors.
- Direct-to-hospital instrument leasing:Subscription-based robotic arm and console models bypass traditional distributor markups in German Klinikverbünde purchasing consortia.
Industry Challenges
- Robotic console operator certification:Intuitive Surgical's proprietary training credentialing creates bottlenecked surgeon throughput and extended proctoring timelines.
- Legacy laparoscope integration:HD-to-4K signal compatibility failures between third-party camera heads and existing tower infrastructure force premature capital replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Minimally Invasive Surgery (MIS) Market |
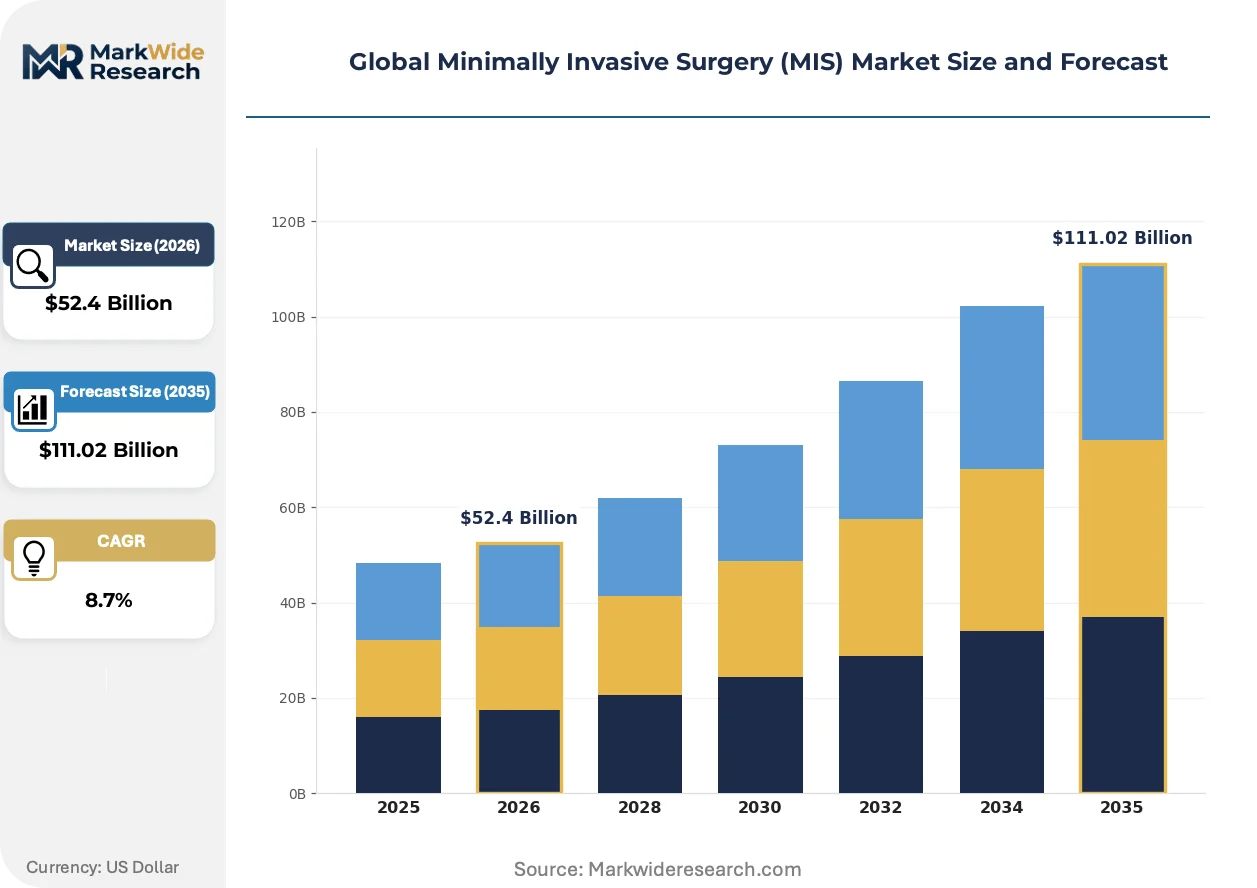
| Market Size in 2026 | $52.4 Billion |
| Market Size in 2035 | $111.02 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Endoscopy, Laparoscopy, Arthroscopy, Thoracoscopy, Hysteroscopy Technology: Robotic Surgery Systems, Image-Guided Systems, Electrosurgical Devices, Ultrasound Systems, Laser Systems Application: Gastrointestinal Surgery, Cardiothoracic Surgery, Urological Surgery, Gynecological Surgery, Neurological Surgery End User: Specialty Clinics, Ambulatory Surgical Centers, Academic Medical Centers, Physician Offices, Specialty Hospitals |
| Companies Covered | Medtronic, Johnson & Johnson, Stryker, Boston Scientific Corporation, Intuitive Surgical, Olympus Corporation, Abbott, Zimmer Biomet, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Minimally Invasive Surgery (MIS) Market Shifts & Advancements
Energy delivery modalities and imaging architectures are fragmenting into modular, software-defined configurations that decouple hardware from disposable revenue streams and compress specialist training timelines.
Single-use laparoscopic instruments with integrated bipolar energy delivery are decomposing capital equipment dependency models in European day-surgery centers. German and Dutch hospital procurement coalitions now specify sterile-packed, procedure-matched instrument kits that eliminate reprocessing infrastructure. This shift is compressing margin pools toward disposable handpiece manufacturers while eroding service contract value for legacy tower vendors.
EU MDR Article 10 post-market surveillance mandates are intensifying clinical evidence requirements for electrosurgical devices with software-controlled energy modulation. Manufacturers must now submit periodic safety update reports with real-world performance data from implanted patient registries. German notified bodies are applying heightened scrutiny to 4K camera systems with AI-enhanced image processing, extending conformity assessment timelines by twelve to eighteen months.
Hospital purchasing committees are consolidating vendor relationships around full-procedure platforms rather than best-of-breed instrument sourcing. US IDN procurement offices now require single-contract accountability for energy devices, staplers, and imaging systems across service line agreements. This concentration is visible in California and Texas health system RFPs that penalize fragmented supplier ecosystems with total cost-of-ownership penalties.
Global Minimally Invasive Surgery (MIS) Market Segmentation
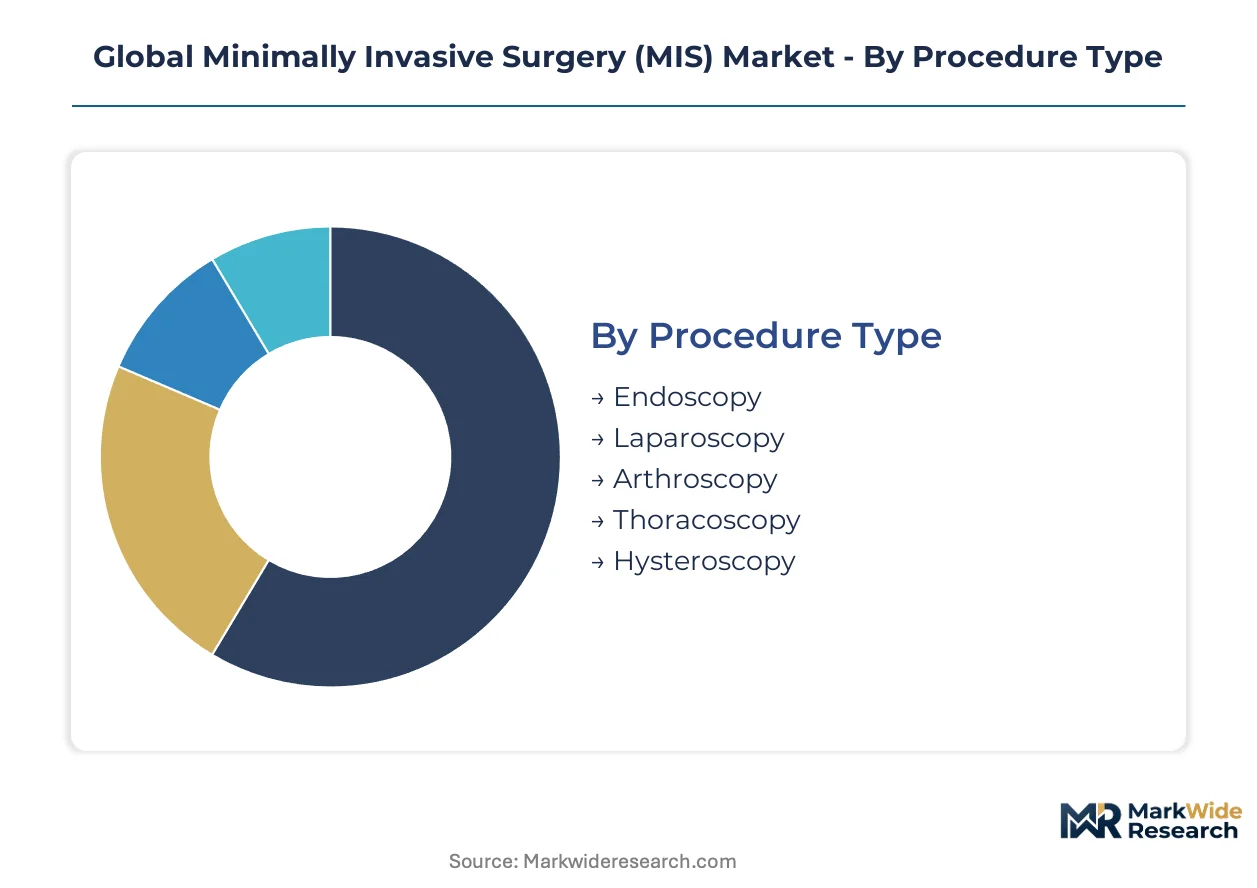
Segmentation in minimally invasive surgery reveals how capital allocation, reimbursement structures, and training pipelines concentrate demand across distinct procedure and technology clusters. Each category exposes different competitive dynamics between disposable instrument manufacturers and integrated platform vendors.
Procedure Type:
Geographic demand patterns diverge sharply: laparoscopy and endoscopy dominate domestic procedure volumes in the United States, Germany, and Japan, while arthroscopy and hysteroscopy show stronger export-led growth through medical tourism corridors into Thailand and Turkey.
- Laparoscopy:Abdominal access through 5-12mm trocar ports with carbon dioxide insufflation enables cholecystectomy, hernia repair, and colorectal resection. German ambulatory surgery centers in the Rhine-Ruhr corridor drive same-day discharge protocol standardization. The steepest expansion runs through single-incision and reduced-port techniques.
- Endoscopy:Flexible scope platforms with biopsy channel instrumentation target diagnostic and therapeutic interventions across upper and lower gastrointestinal tracts. Japanese endoscope manufacturers concentrate production in Tokyo-Osaka clusters for Asia-Pacific distribution. The established base commands diagnostic screening volumes.
- Arthroscopy:Joint-space visualization through saline irrigation distension supports meniscal repair and ligament reconstruction in orthopedic settings.
- Thoracoscopy:Pleural cavity access without sternotomy or thoracotomy enables lung biopsy and mediastinal mass resection.
- Hysteroscopy:Uterine cavity inspection with distension media management targets polypectomy and myomectomy in gynecological suites.
Laparoscopy commands the established base. The steepest expansion runs through hysteroscopy as office-based diagnostic protocols proliferate.
Technology:
Cost tier stratification separates capital-intensive robotic platforms from disposable electrosurgical handpieces, with image-guided systems occupying a mid-tier hybrid position requiring both equipment investment and per-procedure software licensing.
- Robotic Surgery Systems:Multi-arm telemanipulator consoles with 3D vision and wristed instrument articulation command seven-figure capital placement cycles. United States specialty hospitals in California and Texas concentrate installed base density. The established base commands premium recurring instrument revenue.
- Electrosurgical Devices:Generator-compatible handpieces with proprietary connectors deliver monopolar and bipolar energy for tissue cutting and coagulation. German day-surgery centers specify sterile-packed disposable units to eliminate reprocessing infrastructure. The steepest expansion runs through vessel sealing and advanced bipolar platforms.
- Image-Guided Systems:Intraoperative navigation overlays preoperative imaging onto real-time surgical views for tumor localization.
- Ultrasound Systems:Laparoscopic probe integration enables real-time vascular assessment and lesion characterization.
- Laser Systems:Fiber-delivered energy platforms target precise tissue ablation in urological and gynecological applications.
Electrosurgical devices command the established base through disposable revenue scale. The steepest expansion runs through robotic surgery systems as academic medical centers consolidate training pipelines.
Application:
Customer type differentiation separates high-volume gastrointestinal and gynecological procedures reimbursed through outpatient prospective payment systems from lower-volume neurological interventions concentrated in academic referral networks.
- Gastrointestinal Surgery:Laparoscopic colectomy, fundoplication, and bariatric procedures dominate MIS volume through established CPT code reimbursement. United States hospital systems in Florida and Arizona expand ambulatory surgery center capacity for these cases. The established base commands procedure volume leadership.
- Gynecological Surgery:Hysterectomy, myomectomy, and endometriosis excision through laparoscopic and robotic platforms concentrate in specialty hospital settings. German Klinikverbünde purchasing consortia negotiate bundled pricing for energy devices and staplers across these procedures. The steepest expansion runs through same-day hysterectomy protocols.
- Cardiothoracic Surgery:Minimally invasive valve repair and coronary bypass through thoracoscopic and robotic access.
- Urological Surgery:Prostatectomy and partial nephrectomy through robotic-assisted platforms.
- Neurological Surgery:Endoscopic skull base and ventricular procedures requiring specialized navigation integration.
Gastrointestinal surgery commands the established base. The steepest expansion runs through gynecological surgery as outpatient migration accelerates.
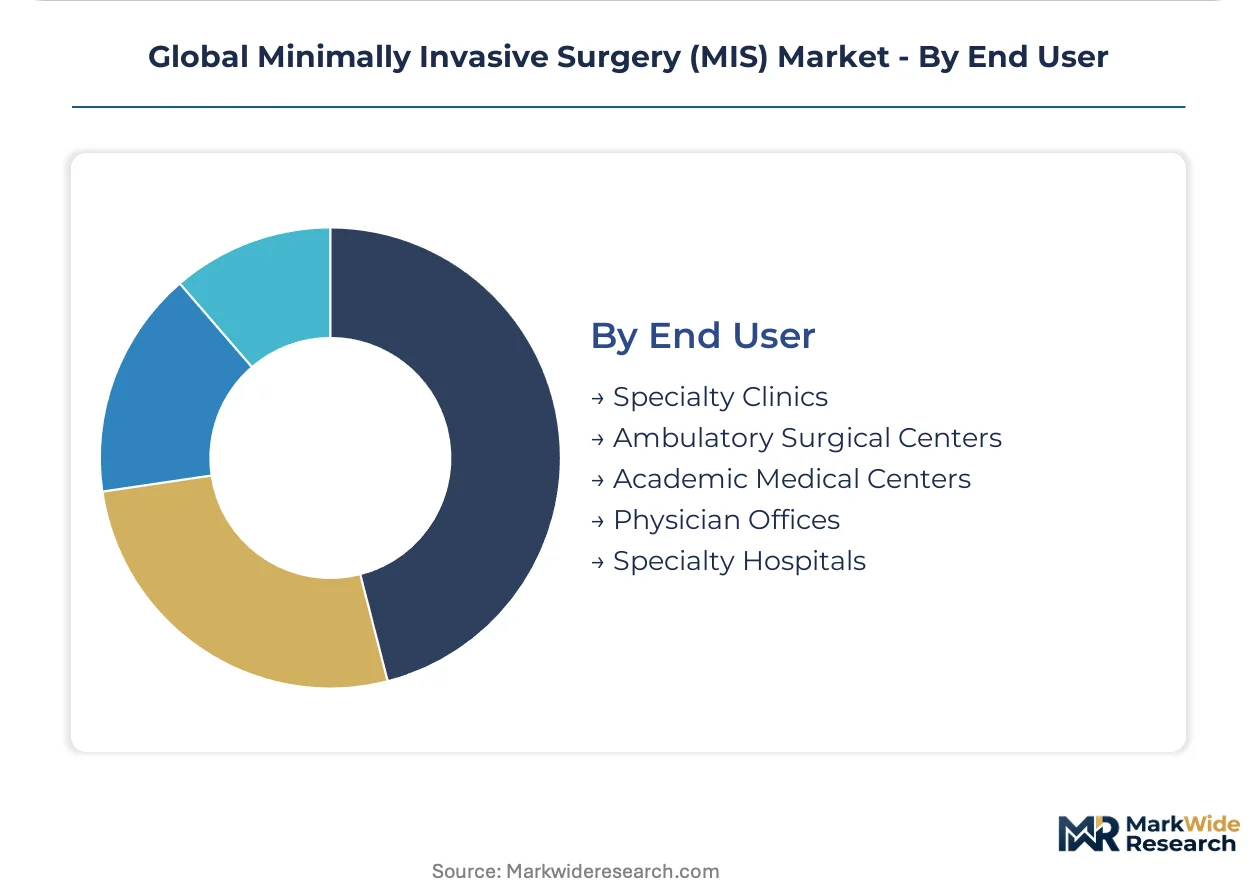
End User:
Supply concentration favors integrated platform vendors serving academic medical centers with full-procedure ecosystems, while fragmented procurement across physician offices creates pricing pressure on standalone instrument suppliers.
- Academic Medical Centers:Training program accreditation requirements drive robotic surgery system placement and specialized fellowship curricula. United States university hospitals in Massachusetts and North Carolina anchor residency competency shifts toward MIS platforms. The established base commands capital equipment procurement volume.
- Ambulatory Surgical Centers:Medicare reimbursement alignment for outpatient MIS procedures concentrates laparoscopic and endoscopic case migration. Japanese Tokyo and Osaka clusters lead same-day discharge protocol adoption under METI guidance. The steepest expansion runs through multi-specialty ASC development.
- Specialty Hospitals:Orthopedic and cardiovascular focused facilities concentrate arthroscopy and cardiothoracic procedure volume.
- Specialty Clinics:Gastroenterology and urology practices maintain endoscopy and cystoscopy suites for diagnostic throughput.
- Physician Offices:Hysteroscopy and minor endoscopic procedures migrate to office-based settings with reduced anesthesia requirements.
Academic medical centers command the established base. The steepest expansion runs through ambulatory surgical centers as reimbursement migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) pathway streamlining anchors United States market access for electrosurgical devices, while Japan's METI reimbursement alignment and Germany's EU MDR implementation create distinct regulatory environments across the three dominant geographies.
United States
Medicare outpatient prospective payment system expansion drives ambulatory surgery center development in Florida and Arizona hospital clusters. FDA intensifies scrutiny for software-enabled surgical navigation systems under 510(k) premarket notification pathways. California and Texas health systems consolidate vendor relationships around full-procedure platform contracts with total cost-of-ownership penalties.
Germany
Rhine-Ruhr corridor ambulatory surgery centers standardize same-day discharge protocols for laparoscopic cholecystectomy and hernia repair. EU MDR 2017/745 recast directives extend clinical validation timelines for legacy electrosurgical devices through notified body backlogs. Baden-Württemberg and Bavaria Klinikverbünde purchasing consortia negotiate bundled pricing for energy devices and staplers.
Japan
Tokyo and Osaka hospital clusters accelerate outpatient MIS procedure adoption under METI reimbursement guidance for aging surgical populations. PMDA consultation pathways for novel electrosurgical instruments align with international harmonization initiatives. Domestic endoscope manufacturers concentrate production capacity for Asia-Pacific distribution.
India
Pune, Kochi, and Jaipur private hospital chains expand laparoscopic capacity through CDSCO streamlined import licensing for refurbished instrument towers. Central Drugs Standard Control Organization rationalizes medical device registration timelines under 2017 Medical Device Rules. Tier-2 city penetration creates procedural access beyond metropolitan concentration.
United Kingdom
NHS England integrated care systems reallocate capital toward robotic surgery training infrastructure across academic medical centers. MHRA post-Brexit regulatory autonomy maintains CE marking recognition with parallel UKCA conformity assessment pathways. London and Southeast England specialty hospitals concentrate installed base density for advanced laparoscopic platforms.
Global Minimally Invasive Surgery (MIS) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the minimally invasive surgery market structure. Tier-one vendors command full-procedure ecosystems spanning energy devices, stapling platforms, and imaging systems, while mid-tier manufacturers concentrate margin pools in disposable handpieces with proprietary generator interfaces. Strategic archetypes separate integrated platform vendors from pure-play electrosurgical specialists and regional laparoscopic tower suppliers. Competitive moves concentrate on M&A for navigation software capabilities and direct-to-hospital leasing models that bypass distributor markups.
Within the integrated platform tier, Medtronic and Johnson & Johnson occupy positions spanning energy devices to navigation platforms, while Intuitive Surgical exemplifies the capital-intensive robotic surgery archetype with installed base concentration in North American specialty hospitals. Stryker represents the orthopedic-anchored diversification vector into arthroscopic and MIS adjacencies.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Stryker |
| Boston Scientific Corporation |
| Intuitive Surgical |
| Olympus Corporation |
| Abbott |
| Zimmer Biomet |
| Koninklijke Philips N.V. |
| Others |
Supply & Pricing Matrix
Capital-intensive robotic console manufacturing in California and Texas generates scale economies that compress per-procedure instrument costs while elevating price floors for mid-tier electrosurgical handpieces. This concentration of production capacity in United States academic medical center clusters simultaneously shapes procurement leverage for hospital systems and limits pricing flexibility for standalone disposable manufacturers competing against integrated platform vendors.
Pricing Analysis
German ambulatory surgery centers pay 15-25% premiums for sterile-packed disposable electrosurgical kits compared to reprocessed alternatives, while Indian tier-2 hospitals source refurbished laparoscopic towers at 40-60% discounts to new equipment. Three-tier pricing structure across premium robotic systems, standard laparoscopic platforms, and economy refurbished instruments dominates capital allocation decisions. Pricing pressure stems from EU MDR compliance costs extending conformity assessment timelines for legacy device manufacturers. Academic medical centers demonstrate lowest price sensitivity due to training program accreditation requirements, while physician office hysteroscopy suites operate under severe budget constraints.
Supply Chain Analysis
Strategic stockpiling of medical-grade CO2 insufflation gas predominates among German Klinikverbünde purchasing consortia facing Rhine-Ruhr corridor supply volatility, while United States hospital systems maintain just-in-time instrument flows through distributor-managed inventory programs. Component manufacturing concentrates in Japan for endoscope optics, Germany for electrosurgical generators, and United States for robotic console assemblies. Supply chains draw from specialized optical glass, medical-grade polymers, and precision-machined surgical alloys. Single-source vulnerability persists for proprietary generator-compatible handpiece connectors. Distribution runs through regional medical device distributors with hospital system direct contracting gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities proliferate as reimbursement migration toward ambulatory settings splinters demand across procedure-specific disposable kits and software-integrated navigation platforms. This demand-side shift creates viable entry points for specialists unburdened by legacy capital equipment service obligations.
For Market Incumbents: Compound installed base density through exclusive training program partnerships with Massachusetts and North Carolina academic medical centers, locking residency competency pipelines. Extend backward integration into sterile-packed disposable manufacturing to capture margin pools eroding from reprocessing elimination. Defend against single-use instrument specialists by bundling energy devices with imaging system service contracts. For New Entrants and Emerging Players: Lead with AI-enabled surgical navigation software licensing to hospital systems seeking differentiation without eight-figure capital commitments. Target Indian tier-2 city private hospital chains in Pune and Jaipur through CDSCO streamlined import pathways for refurbished tower configurations. Pursue direct-to-hospital instrument leasing models bypassing traditional distributor markups in German purchasing consortia. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-integrated platform vendors over pure-play electrosurgical specialists facing EU MDR surveillance burden escalation. Five-to-ten year viability concentrates in navigation algorithm developers with FDA 510(k) pathway traction and hospital system pilot deployments. Acquisition targets include AI surgical tracking specialists with real-time instrument localization capabilities. The signal to watch is reimbursement parity recalibration between robotic and conventional laparoscopic procedure codes by German and Japanese health technology assessment bodies.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance accelerates market access for validated electrosurgical devices through notified body streamlining. |
| Hospital System Partnership | Single-contract accountability for energy devices and staplers reduces total cost-of-ownership penalties in California health system RFPs. |
| Software Companion Development | AI-enhanced image processing integration extends 4K camera system value capture beyond hardware depreciation cycles. |
| Reimbursement Strategy | METI outpatient MIS alignment in Tokyo clusters accelerates same-day discharge protocol adoption for aging surgical populations. |
| Backward Integration | In-house sterile-packed kit manufacturing captures margin pools shifting from reprocessing infrastructure toward disposable handpiece vendors. |
Research Methodology
A spread of perspectives from hospital purchasing committee directors, biomedical engineering specialists, GPO contracts managers, and laparoscopic fellowship program directors converged on the working assumptions underlying procedure volume and capital placement trajectories. Primary interview intelligence combined with secondary validation from FDA 510(k) premarket notification databases, CMS Medicare outpatient prospective payment system filings, hospital procurement contract registries, and EU MDR notified body conformity assessment records. Bottom-up modeling of installed base depreciation cycles and top-down triangulation against health system capital expenditure disclosures anchored value estimates.
Segmentation dimensions modeled span procedure type, technology platform, application specialty, and end-user facility category across the projection horizon. CAGRs derived from weighted procedure volume growth rates, reimbursement trajectory assumptions, and capital equipment replacement cycle analysis. Industry-specific forecast inputs incorporate robotic console placement density in academic medical centers and single-use instrument conversion rates in European day-surgery centers.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) pathway velocity and EU MDR notified body capacity expansion would require recalibration. Forecasts reflect assumptions regarding reimbursement parity maintenance and medical-grade gas supply stability. Revision becomes warranted when health technology assessment body procedure valuation recalibrations cross thresholds altering capital allocation priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Laparotomy Sponges Market
Surgical Instruments
Spain General Surgical Devices Market
Surgical Instruments
Intraoperative Aberrometry Market
Surgical Instruments
Non-Absorbable Sutures Market
Surgical Instruments
Medical Penlights Market
Surgical Instruments
Dermal Curettes Market
Surgical Instruments
Global Veterinary Surgical Instruments Market
Surgical Instruments
Global Dental Surgical Instruments Market
Surgical Instruments
Adult Cardiovascular Surgical Instruments Package Market
Surgical Instruments
Global Surgical Case Carts Market
Surgical Instruments
Hand-Held Surgical Instruments Market
Surgical Instruments
Operating Room Smoke Aspirators Market
Surgical Instruments
Surgical Drainage Devices Market
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
Needle Holders Market
Surgical Instruments
Asia Pacific Surgical Equipment Market