
 Europe Biosurgery Market | 2026-2036
Europe Biosurgery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biosurgery Market Analytics
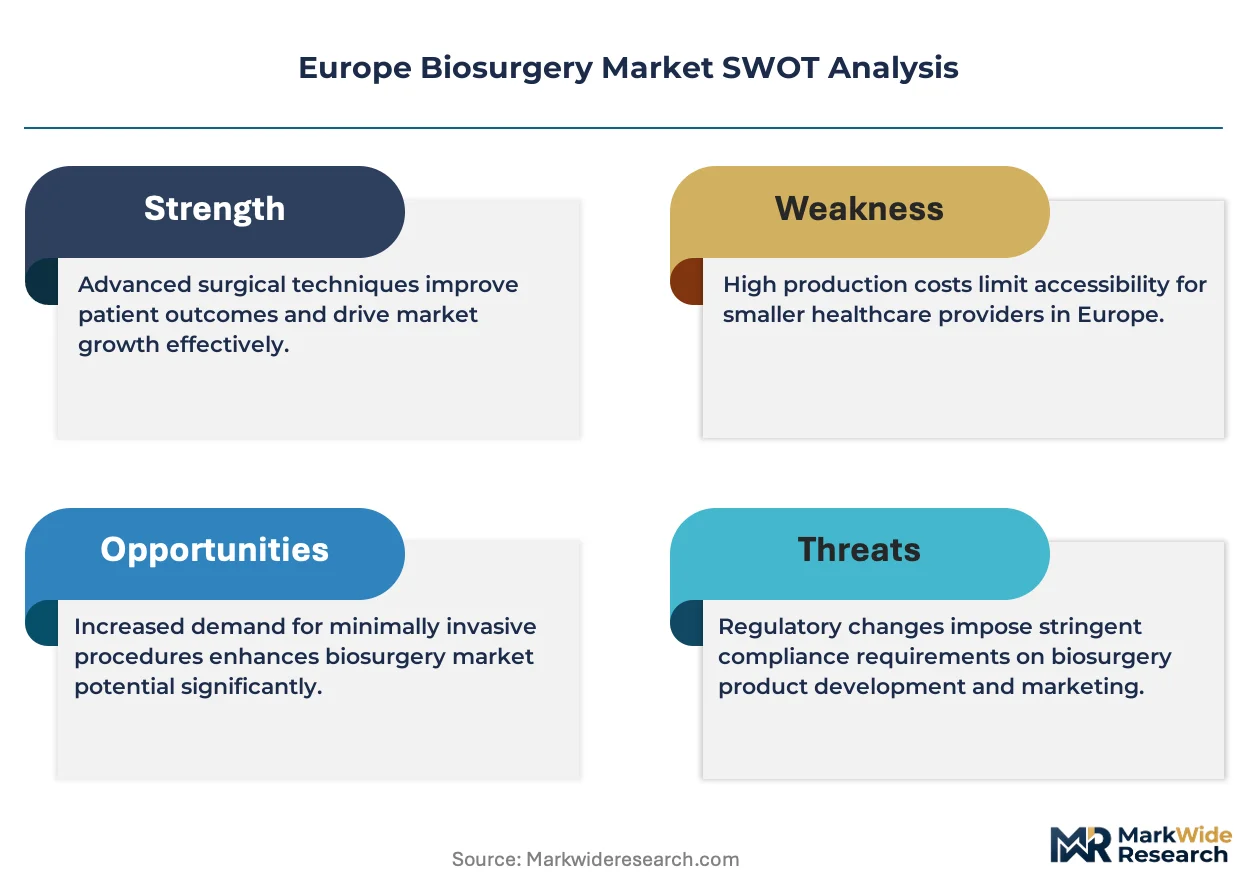
CE marking under the EU Medical Device Regulation is redrawing competitive boundaries in European biosurgery. B. Braun Melsungen AG leverages its German manufacturing footprint to sustain dual certification for sutures and sealants. Stryker anchors its position through specialized orthopedic biosurgery portfolios that dominate bone regeneration applications in tertiary hospitals.
Biosurgery encompasses biologically active or biologically derived materials—fibrin sealants, collagen-based hemostats, synthetic polymer adhesives, and absorbable sutures—engineered to achieve hemostasis, tissue adhesion, or guided regeneration without permanent implantation. These products typically degrade via enzymatic hydrolysis within 7 to 30 days post-application, serving surgical teams across wound closure, tissue repair, and reconstructive disciplines. Sealants and adhesives command premium pricing due to complex polymer chemistry and sterility requirements, while sutures represent the mature volume base with thinner margin pools. Bone regeneration applications within plastic surgery are expanding fastest as ambulatory surgical centers adopt minimally invasive delivery modes.
The European Medicines Agency coordinates pharmacovigilance for biological components, while national competent authorities in Germany, France, and Italy enforce MDR compliance through unannounced facility audits. REACH chemical safety rules additionally constrain synthetic adhesive formulations, elevating R&D costs for non-biological alternatives. Stakeholders must monitor how the EU AI Act's risk classification framework will apply to software-integrated biosurgery delivery systems before procurement cycles finalize.
Market Dynamics
The EU Medical Device Regulation's clinical evidence requirements are compressing supplier margins while concentrating procurement authority in centralized hospital purchasing consortia across France, Germany, and Italy.
Growth Catalysts
- Orthopedic procedure volumes:German university hospitals are expanding biosurgery adoption for bone regeneration, creating pull-through demand for fibrin sealants and collagen-based hemostats in spinal and trauma applications.
- REACH compliance elevation:Chemical safety rules for synthetic polymer adhesives are favoring biological alternatives, accelerating R&D investment in enzymatic hydrolysis formulations that degrade within controlled windows.
- CE marking portfolio breadth:Public hospital procurement centralization in France rewards suppliers with full MDR certification across sutures, sealants, and regenerative matrices, locking out narrow-range competitors.
Market Restraints
- Biological raw material concentration:Bovine and human plasma sourcing for fibrin sealants depends on specialized European abattoirs and blood processing facilities, creating supply vulnerability.
- MDR transition friction:The 2017/745 regulation's tightened clinical evidence requirements extend certification timelines for Class III devices, freezing product pipelines for mid-tier manufacturers.
- Synthetic adhesive cost pressure:Petrochemical feedstock volatility and REACH compliance testing elevate R&D burn rates for non-biological alternatives, compressing development budgets.
Strategic Opportunities
- Ambulatory surgical center penetration:Minimally invasive delivery modes for bone regeneration applications in plastic surgery are expanding fastest in French and Spanish day-surgery clinics.
- Software-integrated delivery systems:The EU AI Act's risk classification framework for algorithm-controlled biosurgery applicators creates first-mover advantage for compliant hardware-software bundles.
- Italian procurement fragmentation:Regional health authority purchasing outside Lombardy and Veneto remains decentralized, offering entry points for specialized sealant suppliers without national scale.
Industry Challenges
- Pharmacovigilance integration:EMA-coordinated biological component tracking demands specialized regulatory affairs talent scarce in midsize device firms.
- Dual certification complexity:Maintaining parallel MDR and ISO 13485 compliance across German manufacturing footprints requires sustained quality management system investment.
- Legacy suture margin compression:Mature absorbable suture categories face pricing pressure from low-cost Eastern European producers, forcing portfolio rebalancing toward premium sealants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biosurgery Market |
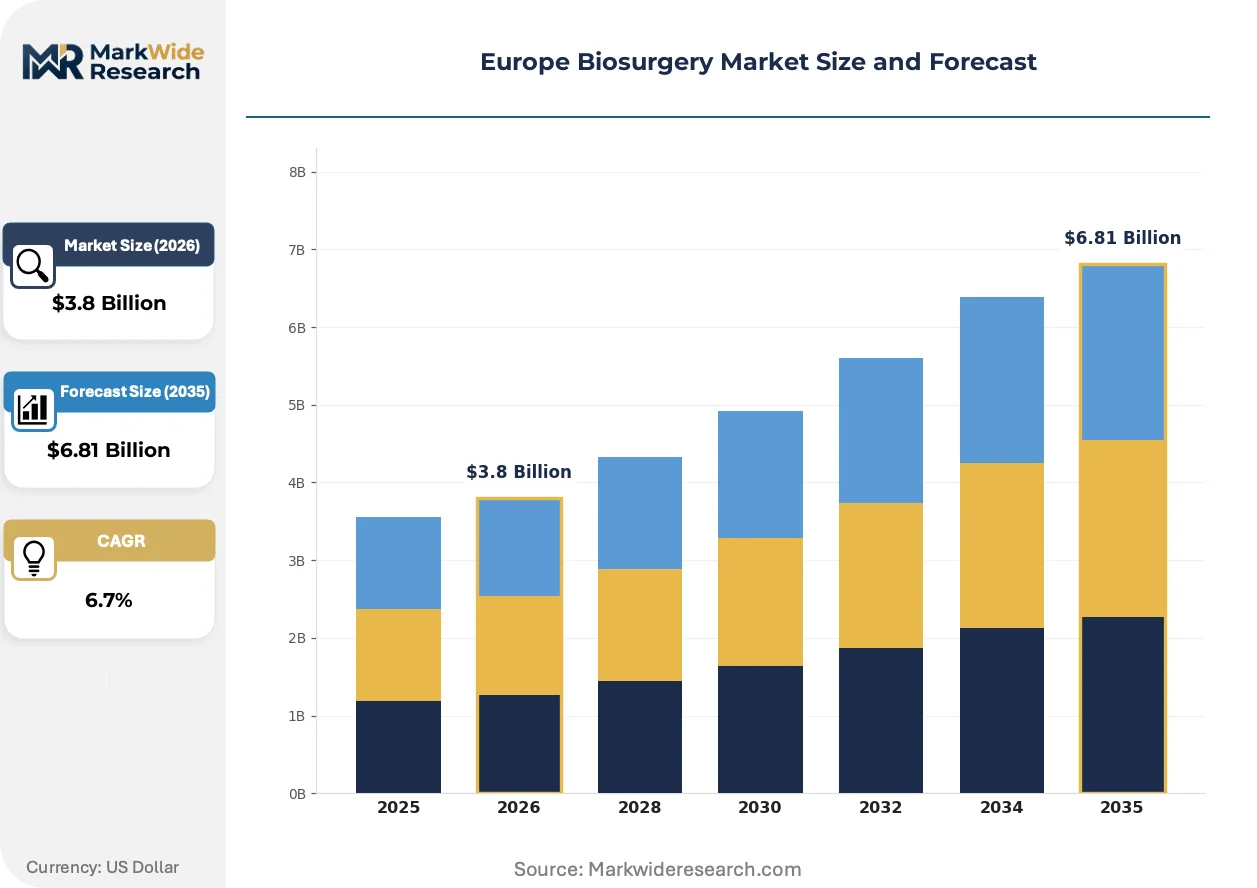
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stitches, Sutures, Sealants, Adhesives Application: Wound Closure, Tissue Repair, Bone Regeneration, Plastic Surgery End User: Hospitals, Clinics, Ambulatory Surgical Centers, Rehabilitation Centers Delivery Mode: Surgical, Laparoscopic, Endoscopic, Local |
| Companies Covered | B. Braun Melsungen AG, Stryker, Integra LifeSciences, Baxter International, Johnson & Johnson Services, Medtronic, BD, Sanofi, Zimmer Biomet, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biosurgery Market Evolving Landscape
Biological material science and regulatory technology are converging to reshape how European surgical teams select and deploy hemostatic and regenerative products.
Recombinant thrombin formulations are decomposing traditional plasma-derived sourcing models by eliminating bovine origin risk and simplifying supply chains. Tertiary hospitals in Germany and the Netherlands are adopting these alternatives at accelerated pace. The technology is decomposing established fibrin sealant pricing structures by removing biological raw material volatility from cost calculations.
MDR Article 117's strengthened clinical evaluation requirements are forcing manufacturers to generate post-market surveillance data beyond pre-2017 levels. This regulatory tightening is elevating documentation costs and extending time-to-market for novel synthetic adhesives. Class III device categories face the steepest compliance burden, with notified bodies in Germany and France reporting extended audit queues.
Hospital buying consortiums are consolidating vendor relationships around full-line suppliers capable of delivering sutures, sealants, and regenerative matrices under unified framework agreements. Independent distributors in Southern Europe are losing share to direct manufacturer contracts. This concentration is most visible in France, where the RESAH central purchasing platform now controls the majority of public hospital biosurgery spend.
Europe Biosurgery Market Segmentation
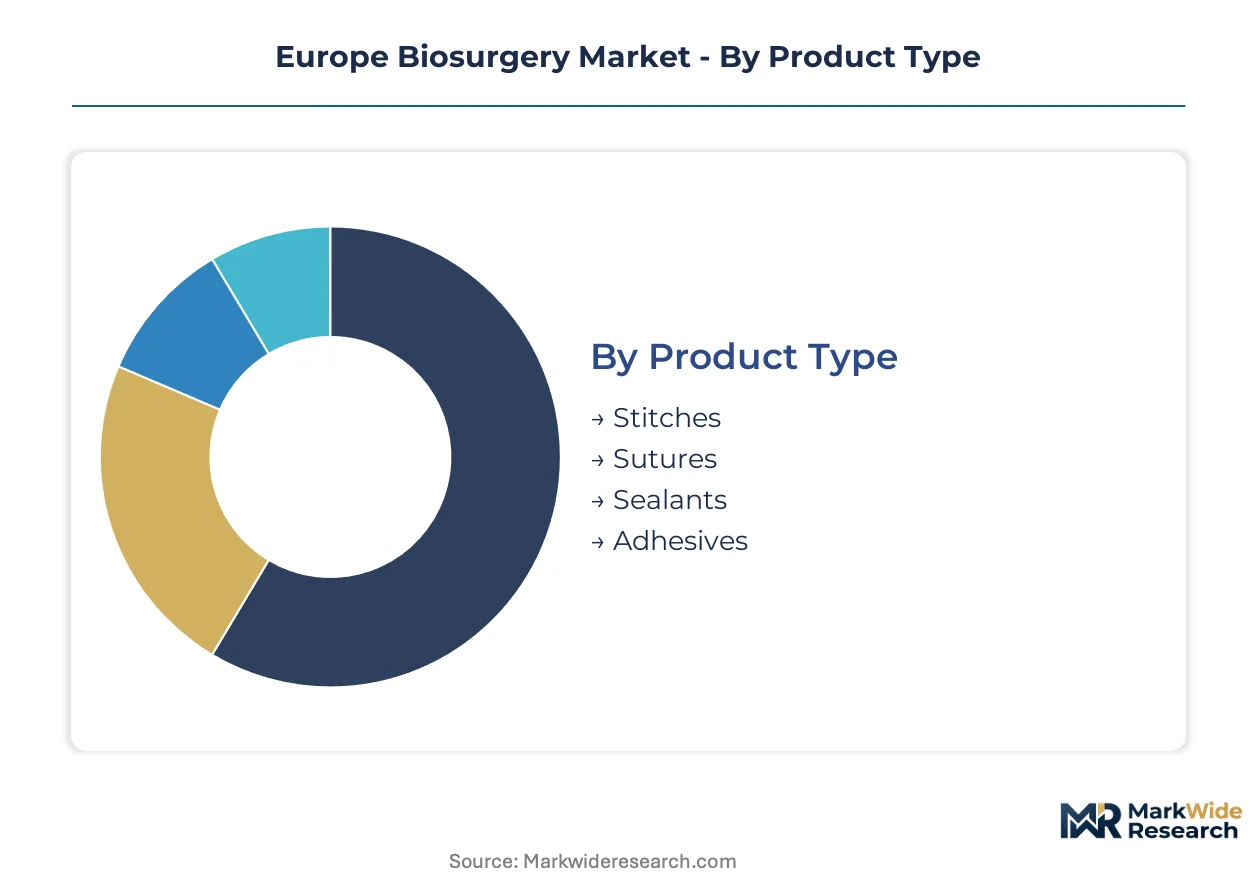
Biosurgery segmentation reveals how margin pools migrate toward biologically active formulations and minimally invasive delivery systems. Hospital procurement centralization across France and Germany rewards suppliers spanning multiple product tiers rather than single-category specialists.
Product Type:
Premium margin concentration sits with biological sealants and advanced adhesives, while sutures operate as volume anchors with thinner returns.
- Stitches:Traditional mechanical wound closure using non-absorbable materials such as silk, nylon, or polypropylene. Demand concentrates in Italian regional hospitals and Eastern European facilities where procurement budgets favor established technologies over advanced sealants.
- Sutures:Absorbable and non-absorbable threads for tissue approximation, with enzymatic hydrolysis degradation profiles from 7 to 90 days. German university hospitals drive specification toward synthetic absorbable variants in orthopedic and cardiovascular applications, pulled by MDR documentation requirements favoring predictable degradation kinetics.
- Sealants:Fibrin-based and synthetic polymer formulations achieving hemostasis through coagulation cascade activation. REACH chemical safety rules elevate biological alternatives in French and Dutch tertiary centers.
- Adhesives:Cyanoacrylate and polyethylene glycol formulations for tissue bonding without mechanical support. Cyanoacrylate variants face feedstock volatility from petrochemical supply chains.
Sutures hold installed capacity. Sealants are rotating up the share rankings.
Application:
Volume distribution tracks surgical procedure mix, with bone regeneration applications capturing the steepest expansion trajectory as ambulatory settings adopt minimally invasive techniques.
- Wound Closure:Primary intention healing across surgical incisions and traumatic lacerations. Spanish and Portuguese public hospitals concentrate demand for cost-optimized suture portfolios under regional purchasing frameworks.
- Tissue Repair:Hernia mesh fixation, cardiovascular anastomosis reinforcement, and soft tissue reconstruction. French cardiac surgery centers specify fibrin sealants for suture line sealing, driven by RESAH framework agreement consolidation.
- Bone Regeneration:Guided tissue regeneration in spinal fusion, maxillofacial reconstruction, and orthopedic trauma. German university hospitals anchor European demand for collagen-based hemostats and demineralized bone matrices in tertiary referral patterns.
- Plastic Surgery:Aesthetic and reconstructive procedures requiring precise tissue approximation with minimal scarring. French and Spanish day-surgery clinics are expanding fastest for minimally invasive adhesive delivery in facial reconstruction.
Wound closure maintains procedure volume leadership. Bone regeneration is climbing the fastest.
End User:
Customer type determines pricing power and contract structure, with centralized hospital procurement extracting volume discounts while ambulatory centers pay premium for specialized delivery formats.
- Hospitals:Tertiary and secondary acute care facilities performing complex surgical procedures. French public hospitals through RESAH and German university hospitals through regional purchasing cooperatives concentrate biosurgery spend, favoring full-line suppliers with complete CE marking portfolios.
- Clinics:Specialized surgical facilities performing routine procedures outside acute care settings. Italian private ophthalmology and dermatology clinics generate concentrated demand for precision sutures and topical adhesives.
- Ambulatory Surgical Centers:Day-surgery facilities emphasizing rapid patient turnover and minimally invasive techniques. Spanish and French ASCs are expanding sealant adoption for laparoscopic procedures, constrained by reimbursement coding complexity.
- Rehabilitation Centers:Post-acute facilities managing wound care and tissue healing. German rehabilitation networks specify advanced wound closure products for pressure ulcer and diabetic wound protocols.
Hospitals anchor procurement volume. Ambulatory surgical centers are gaining share fastest.
Delivery Mode:
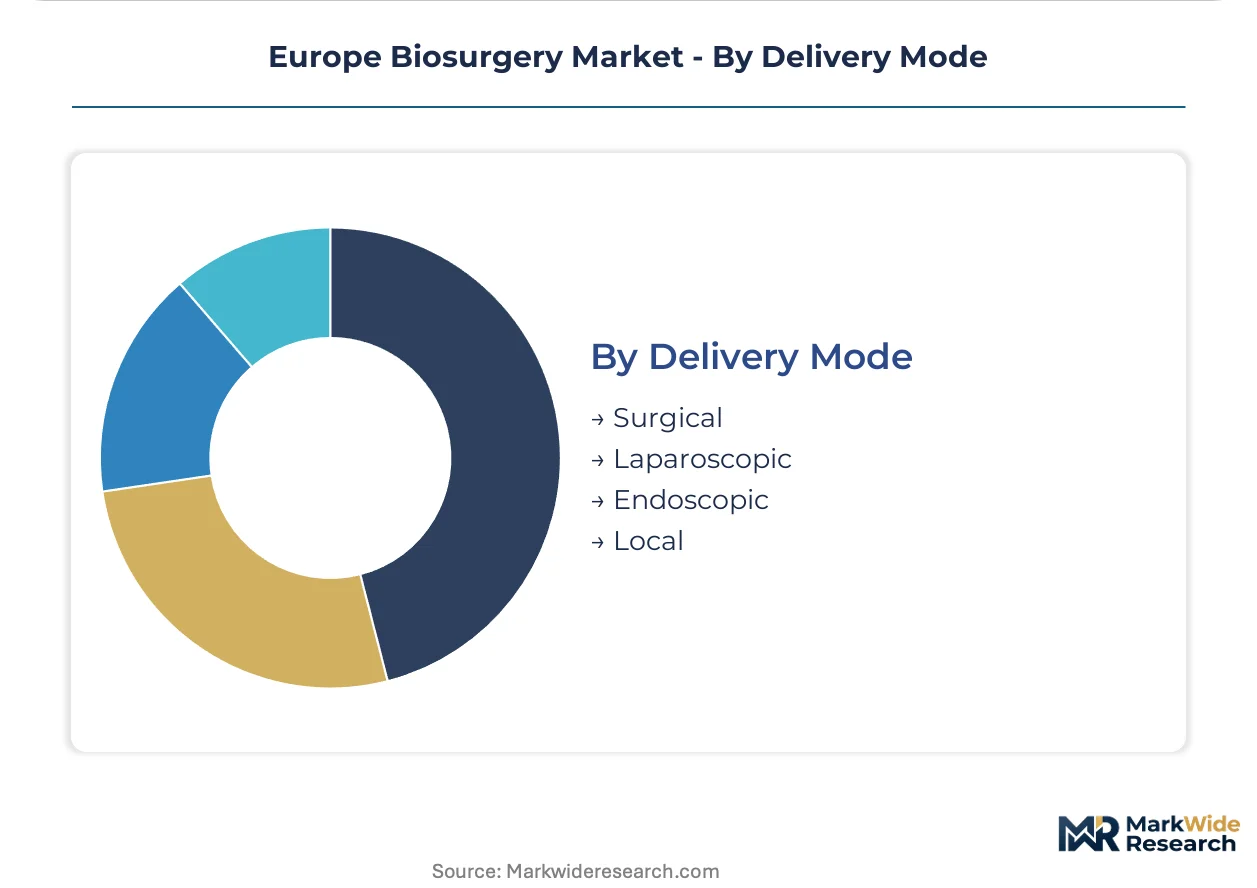
Technology integration requirements escalate from open surgical application through endoscopic systems, with software-controlled applicators facing emerging EU AI Act compliance obligations.
- Surgical:Direct manual application during open procedures. German and French tertiary hospitals maintain dominant utilization for complex orthopedic and cardiovascular cases requiring tactile feedback.
- Laparoscopic:Minimally invasive abdominal and pelvic surgery through trocar access. French gynecology and general surgery departments concentrate demand for specialized sealant applicators with extended reach capabilities.
- Endoscopic:Natural orifice and internal cavity access for gastrointestinal, pulmonary, and urological applications. Dutch and Belgian endoscopy centers specify hemostatic sprays with precise delivery control.
- Local:Topical or site-specific application without systemic exposure. Italian dermatology and oral surgery clinics favor local adhesive delivery for superficial wound closure.
Surgical delivery holds installed base dominance. Laparoscopic application is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Medical Device Regulation harmonization is redistributing biosurgery procurement power toward centralized purchasing platforms in France, Germany, and Italy. National competent authorities enforce MDR compliance through unannounced facility audits. REACH chemical safety rules additionally constrain synthetic adhesive formulations across manufacturing clusters.
Germany
University hospitals in Berlin and Munich anchor European demand for collagen-based hemostats in spinal fusion procedures. The Federal Institute for Drugs and Medical Devices enforces MDR Article 117 clinical evaluation requirements through extended audit queues. The Tübingen-Stuttgart medical technology corridor concentrates sealant manufacturing and notified body certification services.
France
Public hospital procurement through RESAH centralizes biosurgery spend toward full-line suppliers with complete CE marking portfolios. ANSM coordinates pharmacovigilance for biological components alongside EMA frameworks. The Paris-Saclay medical cluster dominates tertiary cardiac surgery demand for fibrin sealants in suture line reinforcement applications.
Italy
Regional health authority purchasing outside Lombardy and Veneto remains decentralized, offering entry points for specialized sealant suppliers. The Ministry of Health enforces MDR transition timelines through regional surveillance units. The Milan-Bergamo industrial corridor concentrates orthopedic biosurgery distribution networks serving Lombardy's dense hospital infrastructure.
Netherlands
Endoscopy centers in Amsterdam and Rotterdam specify hemostatic sprays with precise delivery control for gastrointestinal applications. The Healthcare Inspectorate aligns MDR enforcement with EMA pharmacovigilance coordination for plasma-derived products. The Leiden biotech cluster supports recombinant thrombin development as an alternative to bovine-sourced formulations.
Spain
Ambulatory surgical centers in Madrid and Barcelona expand sealant adoption for laparoscopic procedures despite reimbursement coding complexity. The Spanish Agency for Medicines and Health Products enforces REACH compliance for synthetic polymer adhesives through chemical safety assessments. The Barcelona medical technology hub concentrates day-surgery clinic networks driving minimally invasive delivery mode penetration.
Europe Biosurgery Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with full MDR certification portfolios across sutures, sealants, and regenerative matrices. Market structure concentrates procurement authority in hands of suppliers capable of unified framework agreements with centralized hospital purchasing consortia. Two strategic archetypes dominate: German manufacturing-footprint holders leveraging dual certification efficiency, and orthopedic-specialized portfolios anchoring bone regeneration applications in tertiary hospitals. Competitive moves center on M&A to fill portfolio gaps and vertical integration into biological raw material sourcing.
Within the diversified conglomerate tier, B. Braun Melsungen AG and Stryker exemplify contrasting geographic anchoring strategies. B. Braun Melsungen AG represents the German manufacturing-footprint archetype, sustaining dual MDR and ISO 13485 certification across suture and sealant production. Stryker occupies a position emphasizing orthopedic biosurgery specialization that dominates bone regeneration applications in German and French university hospitals. Baxter International sits within the biological-component sourcing tier, though its strategic positioning reflects broader plasma-derived product portfolio considerations rather than device-centric manufacturing.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Stryker |
| Integra LifeSciences |
| Baxter International |
| Johnson & Johnson Services |
| Medtronic |
| BD |
| Sanofi |
| Zimmer Biomet |
| Others |
Value Network & Pricing Analysis
Long-term framework agreements with RESAH and German regional purchasing cooperatives lock in supply access for sealant and suture portfolios while anchoring price visibility across multi-year procurement cycles. These structures concentrate pricing power with full-line suppliers holding complete MDR certification, compressing margins for narrow-range competitors locked out of centralized tenders.
Pricing Analysis
Cost-plus contracts indexed to bovine plasma and petrochemical feedstock benchmarks dominate biological sealant and synthetic adhesive procurement. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified biologics from legacy sutures and unbranded alternatives. Pricing pressure stems from REACH compliance testing elevating R&D burn rates for non-biological alternatives. Italian regional hospitals and Eastern European facilities exhibit highest price sensitivity, while French tertiary centers prioritize certification breadth over unit cost.
Supply Chain Analysis
Inventory lead times for fibrin sealants extend due to European abattoir sourcing constraints and plasma fractionation bottlenecks. Manufacturing concentrates in Germany, Switzerland, and Ireland, with biological raw material processing anchored in specialized French and German blood facilities. Supply chain risk centers on single-source vulnerability for bovine thrombin derived from controlled European herd populations. Distribution runs through direct manufacturer contracts with hospital buying consortiums, displacing independent Southern European distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in European biosurgery reflects orthopedic procedure volume growth and ambulatory surgical center penetration outpacing mature suture replacement demand. Bone regeneration applications in German university hospitals and French day-surgery clinics anchor this adoption tailwind.
For Market Incumbents: Compound MDR certification advantages by accelerating post-market surveillance data generation beyond Article 117 baselines, locking out mid-tier manufacturers frozen in extended audit queues. Backward integration into recombinant thrombin production eliminates bovine origin risk while capturing margin from biological raw material volatility. Prioritize unified framework agreements with RESAH and German regional cooperatives before procurement centralization completes.
For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany and France offers entry into Italian regional health authority purchasing outside Lombardy and Veneto. Target ambulatory surgical centers in Spain and France with minimally invasive sealant applicators, exploiting reimbursement coding complexity that delays incumbent response. Lead with software-integrated delivery systems compliant with EU AI Act risk classification ahead of hardware-software bundle standardization.
For Investors and Strategic Acquirers: Specialized sealant suppliers with recombinant biological pipelines and MDR transition completion represent the acquisition target archetype with strongest strategic value. Long-term viability hinges on portfolio breadth spanning sutures, sealants, and regenerative matrices under unified certification. Watch Italian procurement fragmentation resolution as the inflection signal—consolidation into national frameworks would eliminate remaining entry points for narrow-range competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 117 compliance accelerates access to French RESAH and German university hospital tenders. |
| Recombinant Biological Pipeline | Recombinant thrombin development eliminates bovine sourcing risk while simplifying EMA pharmacovigilance tracking. |
| Hospital System Partnership | Direct contracts with Spanish and French ambulatory surgical centers bypass distributor displacement. |
| Software Companion Development | EU AI Act-compliant algorithm-controlled applicators create first-mover advantage in laparoscopic delivery. |
| Reimbursement Strategy | Reimbursement coding alignment for minimally invasive bone regeneration unlocks French day-surgery clinic expansion. |
Research Methodology
Operator-level perspectives from hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and regulatory affairs leads anchored the qualitative base. Primary interview insights combined with secondary validation from EMA pharmacovigilance databases, notified body audit disclosures, hospital procurement platform records, and REACH chemical safety filings. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation cross-checked segment-level outputs.
Sensitivity analysis tested forecast robustness across MDR transition timeline scenarios and raw material sourcing disruption assumptions. Segmentation dimensions modeled include product type, application, end user, and delivery mode across the analysis window. CAGRs derived from procedure volume elasticities, pricing trajectory assumptions, and technology substitution curves. Forecast inputs incorporated orthopedic surgery growth rates and ambulatory surgical center penetration patterns.
Underlying assumptions cover MDR enforcement consistency, plasma supply stability, and REACH compliance cost trajectories, with deviation risk concentrated in notified body audit queue extensions and bovine-origin regulatory restrictions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Surgical Blades Market
Surgical Instruments
Surgical Drainage Devices Market
Surgical Instruments
Uro Gynaecological Surgical Devices Market
Surgical Instruments
Hemostatic Instruments Market
Surgical Instruments
Surgical Stapling Devices Market
Surgical Instruments
Global Surgical Scissors Market
Surgical Instruments
Electrocautery Enhanced Delivery System Market
Surgical Instruments
Knotless Tissue Control Devices Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
Surgical Clips Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market
Surgical Instruments
Global Veterinary Surgical Instruments Market
Surgical Instruments
Cardiac Surgery Instruments Market
Surgical Instruments
Laparoscopic Sutures Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
US Ophthalmic Handheld Surgical Instruments Market