
 Prefilled Syringe Contract Manufacturing Market | 2026-2036
Prefilled Syringe Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Prefilled Syringe Contract Manufacturing Market Analytics
Buyer concentration among large-cap biopharmaceutical sponsors is consolidating procurement volumes with a shrinking pool of qualified contract manufacturers. Vetter leverages its German campus network to sustain sterile fill-finish capacity for complex biologics. BD anchors North American supply through integrated needle-syringe systems and automated assembly platforms. Catalent competes globally with multi-site aseptic processing capabilities spanning small molecules and cell therapies.
Prefilled syringe contract manufacturing encompasses the sterile filling, stoppering, and final assembly of drug-device combination products within ISO 5 cleanroom environments using blow-fill-seal or nested tub technologies. These services eliminate compounding risks at point-of-care while ensuring precise dosing for parenteral therapies requiring subcutaneous or intramuscular administration. Glass syringes dominate current volume due to established compatibility with sensitive biologics and proven barrier properties against oxygen and moisture ingress. Plastic syringes represent the fastest-expanding segment as cyclic olefin polymer formulations reduce breakage rates and enable integrated needle safety systems. Oncology and immunology therapy areas command premium pricing within the manufacturing mix due to high-potency handling requirements and dedicated containment infrastructure.
The FDA enforces container closure integrity validation and extractables-leachables testing under combination product regulations, elevating compliance costs for contract providers without dedicated analytical laboratories. EMA's Annex 1 revision mandates continuous viable particle monitoring and barrier technology adoption for Grade A operations, reshaping capital deployment across European fill-finish networks. ISO 11040 series standards govern syringe dimensional tolerances and functional performance, creating technical barriers for new market entrants lacking metrology investment. Stakeholders must monitor regulatory divergence between US and European quality expectations when selecting multi-jurisdictional manufacturing partners.
Market Dynamics
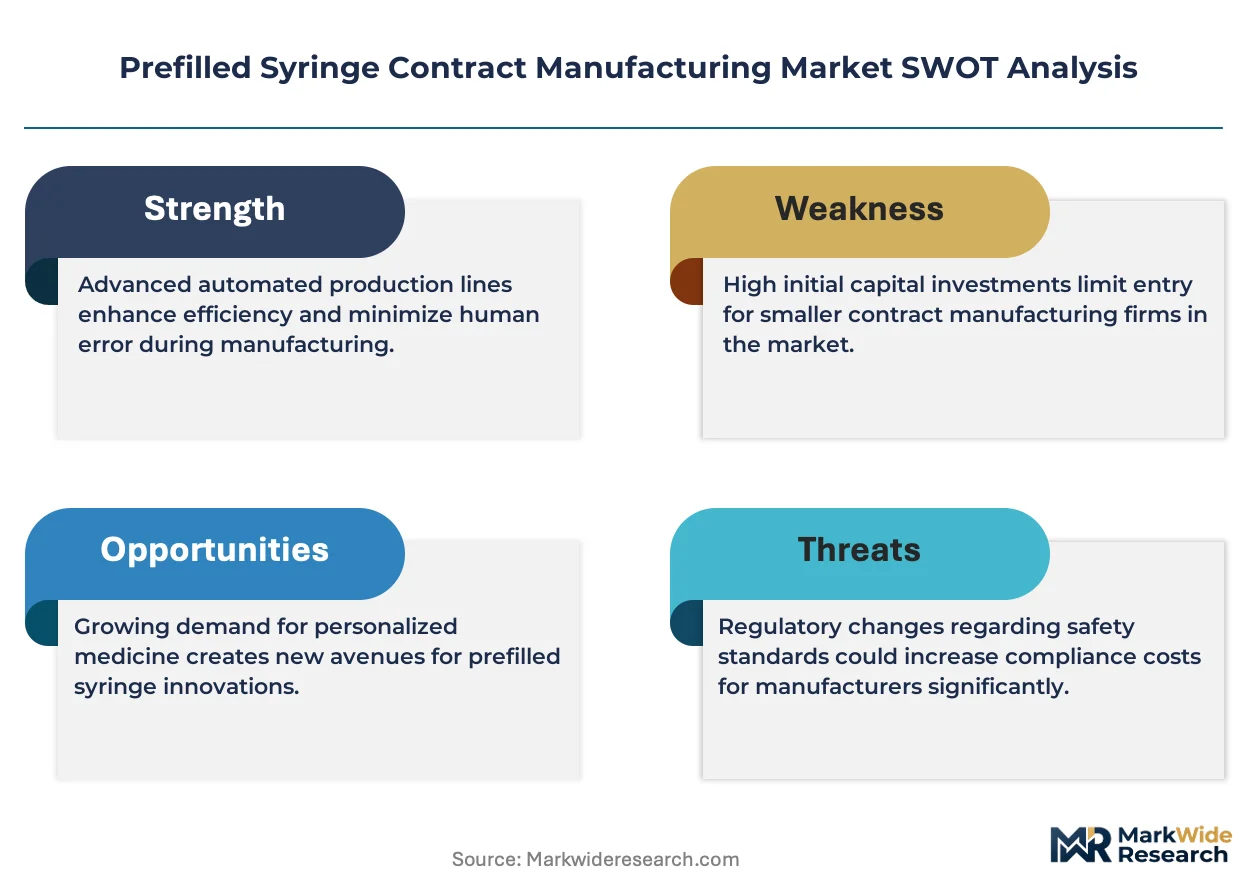
Biologics sponsors are consolidating sterile fill-finish procurement with fewer contract manufacturers possessing dedicated containment infrastructure for high-potency compounds. This concentration dynamic is reshaping capacity allocation and qualification timelines across the prefilled syringe value chain.
Growth Catalysts
- FDA combination product regulations:Tighter container closure integrity requirements are forcing sponsors toward qualified contract manufacturers with validated analytical capabilities, accelerating outsourcing migration from in-house operations.
- Oncology biologics pipeline:High-potency antibody-drug conjugates require isolator-based filling lines that only specialized contract providers maintain, concentrating demand among sterile processing specialists.
- Cyclic olefin polymers:Advanced polymer syringes reduce breakage and enable integrated safety systems, expanding addressable therapy areas beyond traditional glass-compatible biologics.
Market Restraints
- Specialized glass supply concentration:Borosilicate tubing for pharmaceutical-grade syringes sources predominantly from German and Japanese suppliers, creating input vulnerability for manufacturers without long-term supply agreements.
- EMA Annex 1 compliance costs:Continuous viable particle monitoring and barrier technology mandates require capital deployment exceeding mid-tier contract manufacturers' balance sheet capacity.
- Isolator technology limitations:Current gloveless isolator designs restrict line flexibility for multi-product campaigns, constraining batch size economics for niche biologics.
Strategic Opportunities
- Cell therapy autologous filling:Patient-specific manufacturing requires distributed sterile processing networks near clinical sites, creating regional hub opportunities beyond traditional centralized fill-finish.
- India CDSCO manufacturing incentives:Production-linked incentive schemes for medical devices are attracting capital toward domestic sterile filling capacity for export markets.
- Pre-filled diluent syringes:Lyophilized drug reconstitution systems combine two-device workflows into single-unit presentations, opening formulation partnerships with biologics sponsors.
Industry Challenges
- Aseptic processing technician scarcity:ISO 5 cleanroom operators with media fill validation experience command premium wages, constraining line utilization rates at expansion sites.
- Extractables-leachables study timelines:Polymer syringe qualification requires 24-month analytical programs that delay product launches and tie up sponsor regulatory resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prefilled Syringe Contract Manufacturing Market |
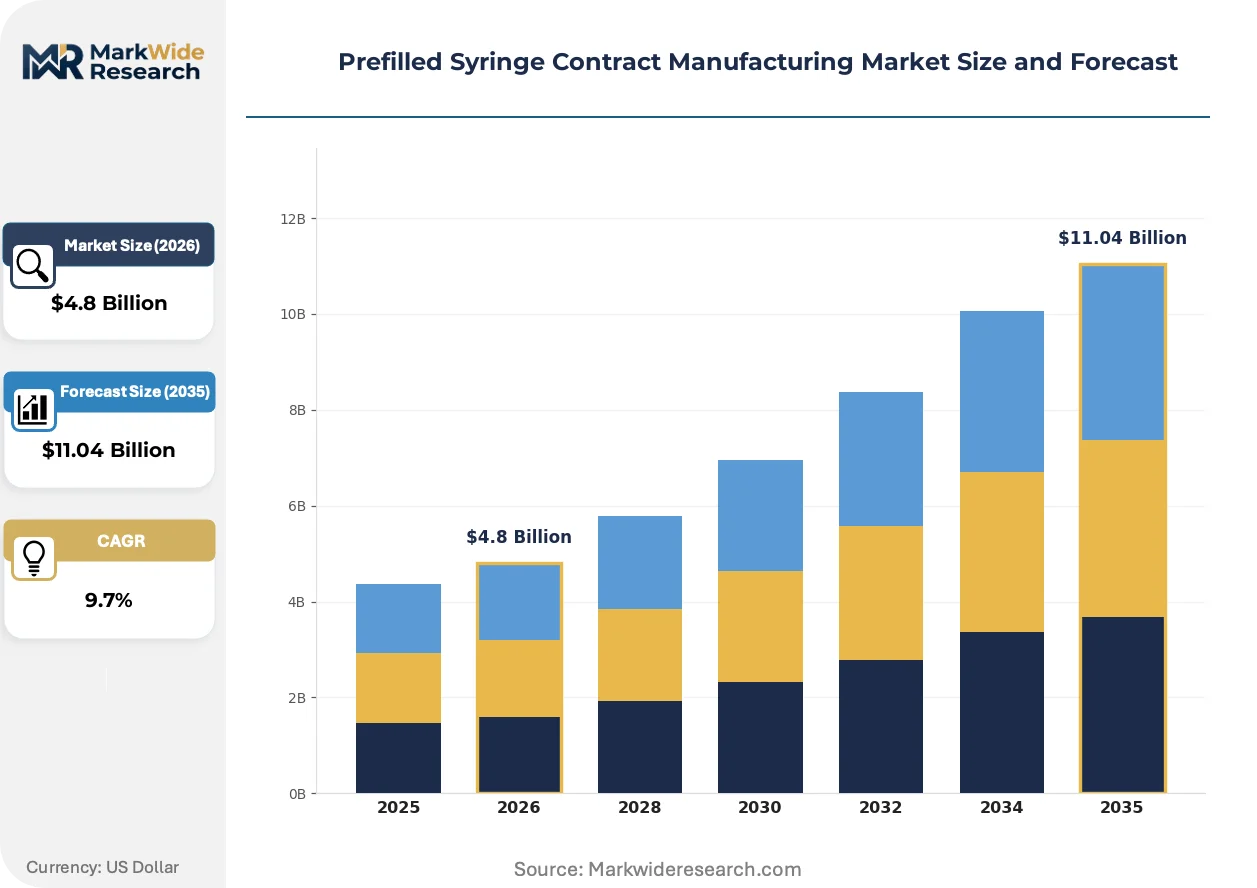
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Syringes, Plastic Syringes, Reusable Syringes, Disposable Syringes Therapy Area: Oncology, Immunology, Vaccines, Hormonal Therapies End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Service Organizations Distribution Channel: Direct Sales, Online Distribution, Third-Party Distributors, Hospitals |
| Companies Covered | West Pharmaceutical Services, Vetter, BD, Nipro Corporation, Catalent, Gerresheimer AG, Stevanato Group, Terumo Corporation, SCHOTT Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prefilled Syringe Contract Manufacturing Market Evolving Landscape
Sterile fill-finish automation is advancing beyond mechanical speed improvements toward integrated process analytical technology that enables real-time release decisions. These shifts are compressing batch release cycles while elevating data integrity requirements for contract providers.
Nested tub packaging systems are converging with robotic de-nesting and vision inspection platforms to eliminate human intervention during sterile filling operations. Biologics sponsors with high-potency portfolios are adopting these systems fastest, driven by containment assurance requirements. This convergence is compressing the viable manufacturing base to providers with capital-intensive automation platforms.
EMA's Annex 1 revision mandates barrier technology and continuous environmental monitoring for Grade A operations, elevating facility qualification thresholds across European manufacturing networks. Contract manufacturers are responding with isolator retrofits and single-use fluid path conversions. Small-molecule sterile injectables face the steepest compliance cost escalation relative to revenue per unit.
Large-cap biopharmaceutical sponsors are consolidating prefilled syringe procurement with dual-source strategies that favor manufacturers offering integrated device assembly and final packaging. This behavior is displacing standalone fill-finish providers from oncology and immunology therapy portfolios. Germany and Switzerland anchor the highest concentration of these integrated service contracts.
Prefilled Syringe Contract Manufacturing Market Segmentation
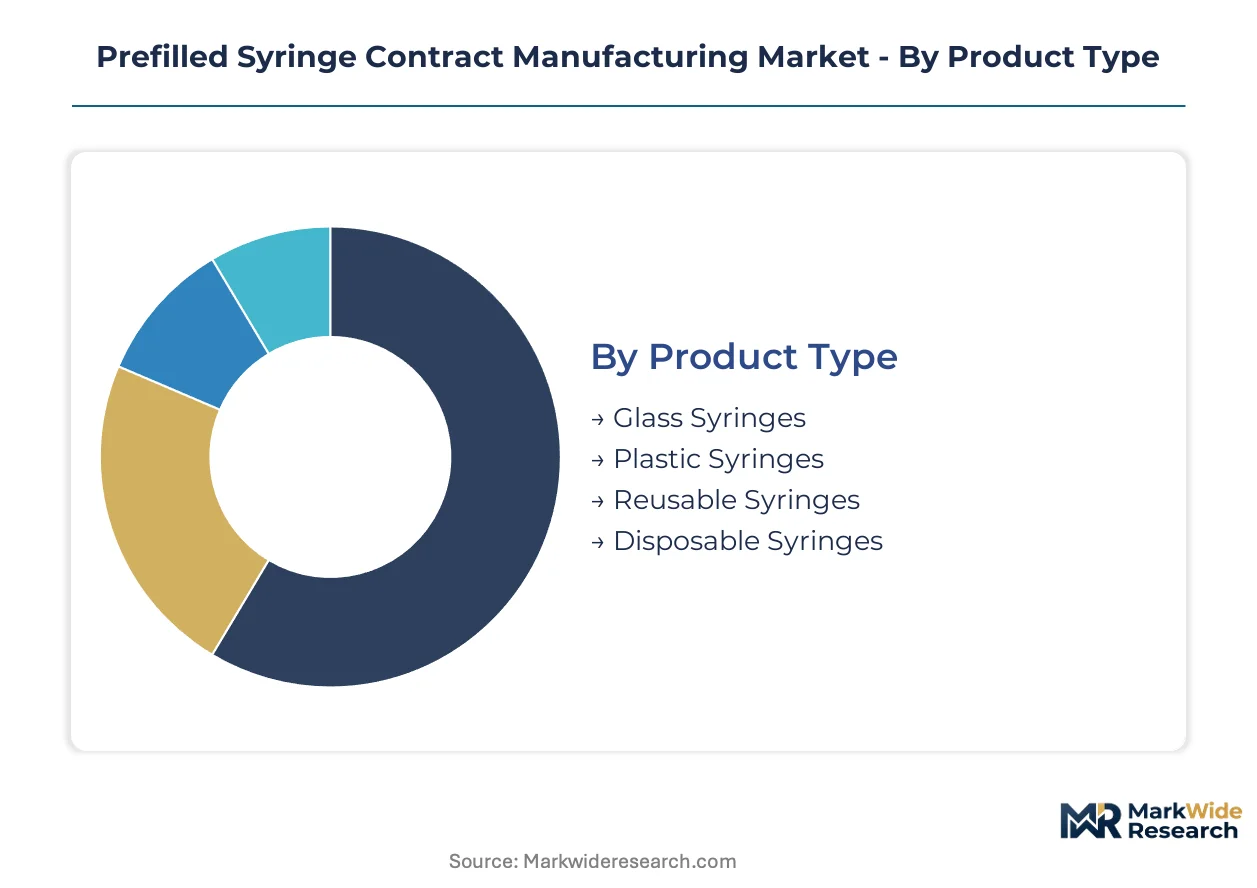
Segmentation in prefilled syringe contract manufacturing reveals distinct procurement patterns across material technologies and therapy applications. Contract manufacturers align sterile fill-finish capabilities with sponsor portfolios based on containment requirements, regulatory pathways, and volume economics.
Product Type:
Material selection drives qualification timelines, extractables-leachables testing burdens, and breakage risk allocation between sponsors and contract providers.
- Glass Syringes:Borosilicate construction delivers proven barrier properties against oxygen and moisture ingress for sensitive biologics. Demand concentrates among oncology and immunology sponsors in Germany and Switzerland where Vetter and SCHOTT Pharma anchor specialized manufacturing clusters requiring established compatibility data.
- Plastic Syringes:Cyclic olefin polymer formulations reduce breakage rates and enable integrated needle safety systems. Biotechnology firms expanding into patient self-administration are accelerating adoption, particularly for therapies requiring cold-chain distribution where mechanical shock risks escalate.
- Reusable Syringes:Stainless-steel designs with replaceable cartridges serve niche hormonal therapy markets in Switzerland with established refill infrastructure.
- Disposable Syringes:Single-use presentations dominate vaccine campaigns requiring rapid scale-up and minimal cross-contamination protocols.
Glass syringes lead on scale; plastic syringes lead on momentum.
Therapy Area:
Containment infrastructure requirements and handling protocols create tiered pricing structures across therapeutic categories.
- Oncology:High-potency antibody-drug conjugates demand isolator-based filling lines with dedicated HVAC and waste containment systems. Procurement concentrates with contract manufacturers possessing occupational exposure band 5 capabilities, particularly for cytotoxic compounds requiring closed-system drug transfer devices.
- Immunology:Monoclonal antibodies for autoimmune conditions require validated cold-chain fill-finish with controlled ice nucleation during freezing. Sponsors prioritize manufacturers with demonstrated batch consistency across multi-year campaigns.
- Vaccines:Pandemic response capabilities and antigen stability protocols shape supplier selection for public health procurement frameworks.
- Hormonal Therapies:Peptide formulations with narrow therapeutic indices require precise dosing verification and particulate control below pharmacopeial limits.
Oncology commands premium pricing; immunology delivers volume stability.
End User:
Internal manufacturing depth versus outsourcing appetite varies sharply across sponsor organizational types and capital allocation priorities.
- Pharmaceutical Companies:Large-cap sponsors with legacy sterile processing assets are divesting fill-finish infrastructure to unlock capital for discovery platforms, consolidating procurement with dual-source contract manufacturing strategies.
- Biotechnology Firms:Venture-backed developers without manufacturing footprints represent the purest outsourcing demand, requiring contract partners with integrated device assembly and regulatory submission support.
- Research Institutions:Academic medical centers with GMP pilot facilities handle early-phase clinical supplies internally before technology transfer to commercial-scale providers.
- Contract Service Organizations:CDMOs themselves subcontract specialized capabilities such as high-potency containment or specific polymer syringe formats.
Pharmaceutical companies anchor revenue concentration; biotechnology firms drive expansion velocity.
Distribution Channel:
Channel selection reflects sponsor commercial infrastructure depth and geographic reach requirements.
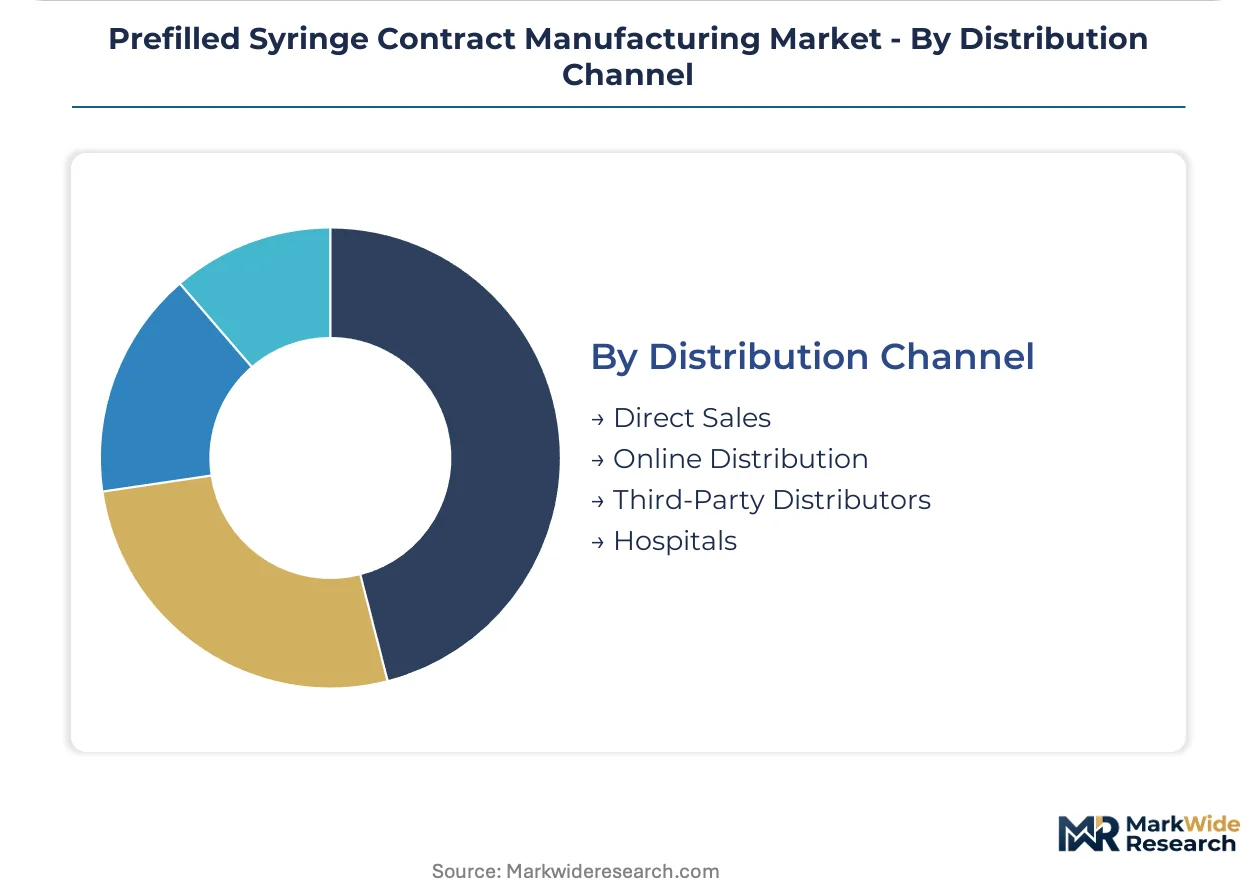
- Direct Sales:Sponsors with established hospital contracting teams and field inventory management systems procure finished combination products directly from fill-finish providers, capturing margin that would otherwise accrue to distribution intermediaries.
- Online Distribution:Emerging channel for standardized disposable syringes in research and veterinary applications with lower regulatory documentation requirements.
- Third-Party Distributors:Regional logistics specialists with temperature-controlled warehousing and customs brokerage capabilities serve sponsors lacking in-market commercial infrastructure, particularly for emerging market access.
- Hospitals:Integrated delivery networks with centralized pharmacy operations negotiate direct procurement agreements for high-volume standardized presentations, bypassing traditional wholesale channels.
Direct sales dominate value capture; third-party distributors enable geographic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands specialized sterile fill-finish capacity for European biologics sponsors, while the United States anchors integrated device assembly platforms serving North American pharmaceutical procurement.
Germany
Vetter and SCHOTT Pharma maintain manufacturing clusters in Ravensburg and Mainz serving oncology and immunology therapy portfolios. EMA's Annex 1 revision mandates barrier technology adoption for Grade A operations, elevating qualification thresholds for contract providers. The Baden-Württemberg corridor concentrates isolator-based filling lines for high-potency antibody-drug conjugates.
United States
BD anchors North American supply through automated needle-syringe assembly systems in New Jersey and Illinois. FDA combination product regulations tighten container closure integrity requirements, forcing sponsors toward qualified contract manufacturers with validated analytical laboratories. The Boston-Cambridge biotechnology corridor drives demand for cell therapy autologous filling capabilities.
Switzerland
Swissmedic oversight and established GMP infrastructure attract biologics sponsors requiring occupational exposure band 5 containment for cytotoxic compounds. The Basel-Lucerne manufacturing belt hosts specialized sterile processing for monoclonal antibodies with narrow therapeutic indices. Swiss contract providers command premium pricing for validated cold-chain fill-finish with controlled ice nucleation protocols.
India
CDSCO production-linked incentive schemes for medical devices attract capital toward domestic sterile filling capacity for export markets. The Maharashtra-Gujarat pharmaceutical belt expands aseptic processing infrastructure to serve biotechnology firms seeking cost-optimized manufacturing partnerships. Pune and Ahmedabad clusters specialize in disposable syringe formats for vaccine campaigns requiring rapid scale-up.
Japan
PMDA quality benchmarks and established polymer syringe expertise position Japanese contract manufacturers for integrated safety system assemblies. The Kanto and Kansai regions maintain precision molding capabilities for cyclic olefin polymer formulations reducing breakage rates. Osaka-based specialists focus on pre-filled diluent syringes combining lyophilized drug reconstitution workflows.
Prefilled Syringe Contract Manufacturing Market Competitive Landscape
German producers anchor one tier of specialized sterile fill-finish capacity; North American specialists hold integrated device assembly platforms. The market structure concentrates procurement volumes among large-cap biopharmaceutical sponsors consolidating with fewer qualified contract manufacturers. Three archetypes dominate: multi-site aseptic processors with global networks, regional isolator-based specialists for high-potency compounds, and integrated device assemblers with automated packaging platforms. Competitive moves center on capacity expansion for cell therapy applications and strategic partnerships for polymer syringe qualification programs.
Within the German specialist tier, Vetter and SCHOTT Pharma exemplify regional cluster concentration with dedicated containment infrastructure. BD occupies a position among North American integrated platform providers. Catalent represents the multi-site aseptic processor archetype spanning small molecules and cell therapies across jurisdictions. These anchors illustrate how contract manufacturers align sterile fill-finish capabilities with sponsor portfolios based on containment requirements, regulatory pathways, and volume economics.
| Leading Market Players |
|---|
| West Pharmaceutical Services |
| Vetter |
| BD |
| Nipro Corporation |
| Catalent |
| Gerresheimer AG |
| Stevanato Group |
| Terumo Corporation |
| SCHOTT Pharma |
| Others |
Value Network & Pricing Analysis
ISO 5 cleanroom operators with media fill validation experience in Germany and Switzerland command premium wages that compress margins at mid-tier facilities and widen spreads between premium isolator-based services and standard aseptic processing tiers.
Pricing Analysis
Capacity additions in India are reshaping price floors for disposable syringe formats serving vaccine campaigns. Three-tier pricing structure across premium isolator-based, standard barrier, and economy open-filling levels stratifies by containment certification and occupational exposure band rating. Cost compression in standard aseptic tiers is intensifying because EMA Annex 1 retrofit capital requirements are forcing mid-tier providers to exit. Biotechnology firms without manufacturing footprints exhibit highest price sensitivity; oncology sponsors with cytotoxic portfolios show lowest sensitivity due to irreplaceable containment requirements.
Supply Chain Analysis
Borosilicate glass tubing supply rests on German and Japanese specialty manufacturers with limited alternative sources. Cyclic olefin polymer resins draw from Japanese and South Korean petrochemical complexes, while stainless-steel cannula production centers on Chinese and Italian metalworking clusters. Single-source vulnerability pervades pharmaceutical-grade glass tubing where long-term qualification timelines prevent rapid supplier switching. Distribution runs through direct sponsor-procurement channels for integrated device assemblies and third-party logistics providers for cold-chain finished goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The prefilled syringe contract manufacturing market represents a late-cycle quality story as biologics sponsors shift procurement toward EMA Annex 1-compliant providers with validated isolator infrastructure and continuous environmental monitoring capabilities.
For Market Incumbents: Anchor premium positioning through backward integration into cyclic olefin polymer compounding and captive needle-safety system assembly. Invest in isolator retrofit programs at German and Swiss facilities before qualification timelines extend. Defend against mid-tier Indian entrants by emphasizing FDA combination product regulatory dossier support and established extractables-leachables databases. For New Entrants and Emerging Players: Begin with cell therapy autologous filling networks requiring distributed sterile processing near clinical sites in the Boston-Cambridge corridor. Target pre-filled diluent syringe partnerships for lyophilized biologics reconstitution workflows. Pursue CDSCO production-linked incentive schemes to establish Maharashtra-based capacity for export-market qualification. For Investors and Strategic Acquirers: Large-cap biopharmaceutical sponsors with dual-source consolidation strategies are the most active acquirer in this space, seeking integrated device assembly capabilities. Five-to-ten-year viability favors regional isolator-based specialists with occupational exposure band 5 containment and established oncology sponsor relationships. Watch FDA guidance evolution on container closure integrity validation as inflection indicator for compliance-cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Retrofit | EMA Annex 1 mandates barrier adoption for Grade A operations across European fill-finish networks. |
| Backward Integration into Polymer Compounding | Cyclic olefin polymer formulation control reduces extractables-leachables study timelines for biologics sponsors. |
| Cell Therapy Distributed Network Buildout | Patient-specific autologous manufacturing requires sterile processing hubs near clinical trial sites. |
| Pre-filled Diluent Syringe Partnership | Lyophilized drug reconstitution systems combine dual-device workflows into single-unit presentations. |
| CDSCO Incentive Scheme Participation | Indian production-linked incentives attract capital toward export-qualification sterile filling capacity. |
Research Methodology
Coverage spans Germany, Switzerland, the United States, India, and Japan, with primary inputs from each jurisdiction combining structured interviews with sterile fill-finish operations directors, regulatory affairs leads at biologics sponsors, hospital pharmacy procurement managers, and GPO contract specialists. Secondary validation draws from FDA combination product filings, EMA GMP inspection databases, CDSCO medical device registration records, and ISO 11040 series standards documentation. Bottom-up capacity modeling and top-down sponsor procurement budget triangulation anchor volume and value estimates.
Granularity-level modeling disaggregates the analysis window by material technology, therapy area containment requirement, end-user outsourcing depth, and regional regulatory cluster. CAGRs derive from sponsor pipeline analysis, capacity expansion announcements, and qualification timeline projections across the modeling period. Forecast inputs incorporate isolator technology adoption curves, polymer syringe breakage rate improvements, and biologics sponsor dual-source consolidation patterns.
Several conditions sit outside the modeled scope, including pandemic-scale demand surges, sudden glass tubing supply disruptions, and radical shifts in FDA combination product enforcement posture. Forecasts reflect assumptions about regulatory stability, sponsor outsourcing appetite continuity, and capital availability for EMA Annex 1 compliance. A small set of named triggers warrants ongoing watch: FDA container closure integrity guidance revisions, CDSCO incentive scheme renewal decisions, and breakthrough isolator designs enabling multi-product campaign flexibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intelligent Electronic Sphygmomanometers Market
Medical Devices
Neurovascular Access Catheters Market
Medical Devices
Smart Stairlift Market
Medical Devices
US Bathroom and Toilet Assist Devices Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
Expandable Interbody Fusion System Market
Medical Devices
North America Pen Needles Market
Medical Devices
United States Respiratory Devices Market
Medical Devices
Hybrid Microcirculation Detector Market
Medical Devices
Small Bone and Joint Devices Market
Medical Devices
Middle East and Africa Sleep Apnea Devices Market
Medical Devices
United States Minimally Invasive Surgery Device Market
Medical Devices
Adsorption Apheresis Devices Market
Medical Devices
Artificial Eye Lenses Market
Medical Devices
Global Cardiac Reader System Market
Medical Devices
Italy Minimally Invasive Surgery Devices Market