
 Medical Scrubs Market | 2026-2036
Medical Scrubs Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Scrubs Market Analytics
Post-acute nursing labor shortages is unwinding volume growth in institutional scrub procurement. FIGS leverages direct-to-consumer channels to bypass traditional group purchasing organizations. Medline sustains hospital contract dominance through captive distribution networks spanning acute and long-term care facilities.
Medical scrubs are standardized protective garments engineered from cotton-polyester blends or microfiber weaves with antimicrobial finishes, designed to reduce cross-contamination in clinical environments while meeting occupational safety requirements. Surgical scrubs command premium positioning due to stricter barrier performance specifications and shorter replacement cycles in operating theaters. Designer scrubs are gaining traction among younger clinicians who prioritize aesthetic differentiation alongside functional compliance.
FDA textile biocompatibility guidelines and OSHA bloodborne pathogen standards shape material selection and laundering protocol requirements across healthcare employers. EPA-registered antimicrobial claims face escalating verification scrutiny, forcing suppliers to reformulate fiber treatments or risk label restrictions. Stakeholders must track evolving state-level healthcare worker safety mandates that could mandate flame-resistant or fluid-repellent specifications beyond current federal baselines.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships as infection control protocols tighten, compressing supplier margins while elevating technical compliance requirements across polyester-microfiber blend specifications.
Growth Catalysts
- Antimicrobial Fabric Standards:EPA-registered fiber treatments are accelerating material substitution away from untreated cotton-polyester weaves in US acute care facilities.
- Operating Theater Replacement Cycles:Surgical scrub protocols demand shorter refresh intervals than general ward garments, concentrating recurring demand within sterile processing departments.
- China:NMPA biocompatibility guidelines for medical textiles are expanding addressable demand for barrier-performance certified scrubs in tier-one hospital systems.
Market Restraints
- Polyester-Microfiber Input Volatility:Petrochemical feedstock fluctuations compress margin stability for blend-dependent manufacturers.
- FDA Label Scrutiny:Escalating verification requirements for antimicrobial claims extend reformulation timelines and raise compliance costs.
- Post-Acute Labor Shortages:Nursing workforce attrition in long-term care facilities is unwinding institutional scrub procurement volumes.
Strategic Opportunities
- Direct-to-Consumer Channels:Digital-native clinicians are bypassing group purchasing organizations, creating margin capture opportunities outside hospital contract structures.
- India:CDSCO medical device textile classifications are formalizing standards that reward early-mover suppliers with certified manufacturing capabilities.
- Designer Aesthetic Convergence:Younger clinicians prioritize functional compliance alongside visual differentiation, opening premium positioning above commodity tiers.
Industry Challenges
- OSHA Bloodborne Pathogen Compliance:Laundering protocol validation requires capital-intensive wash monitoring systems and staff certification programs.
- State-Level Mandate Fragmentation:Evolving healthcare worker safety regulations across US jurisdictions create specification complexity exceeding federal OSHA baselines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Scrubs Market |
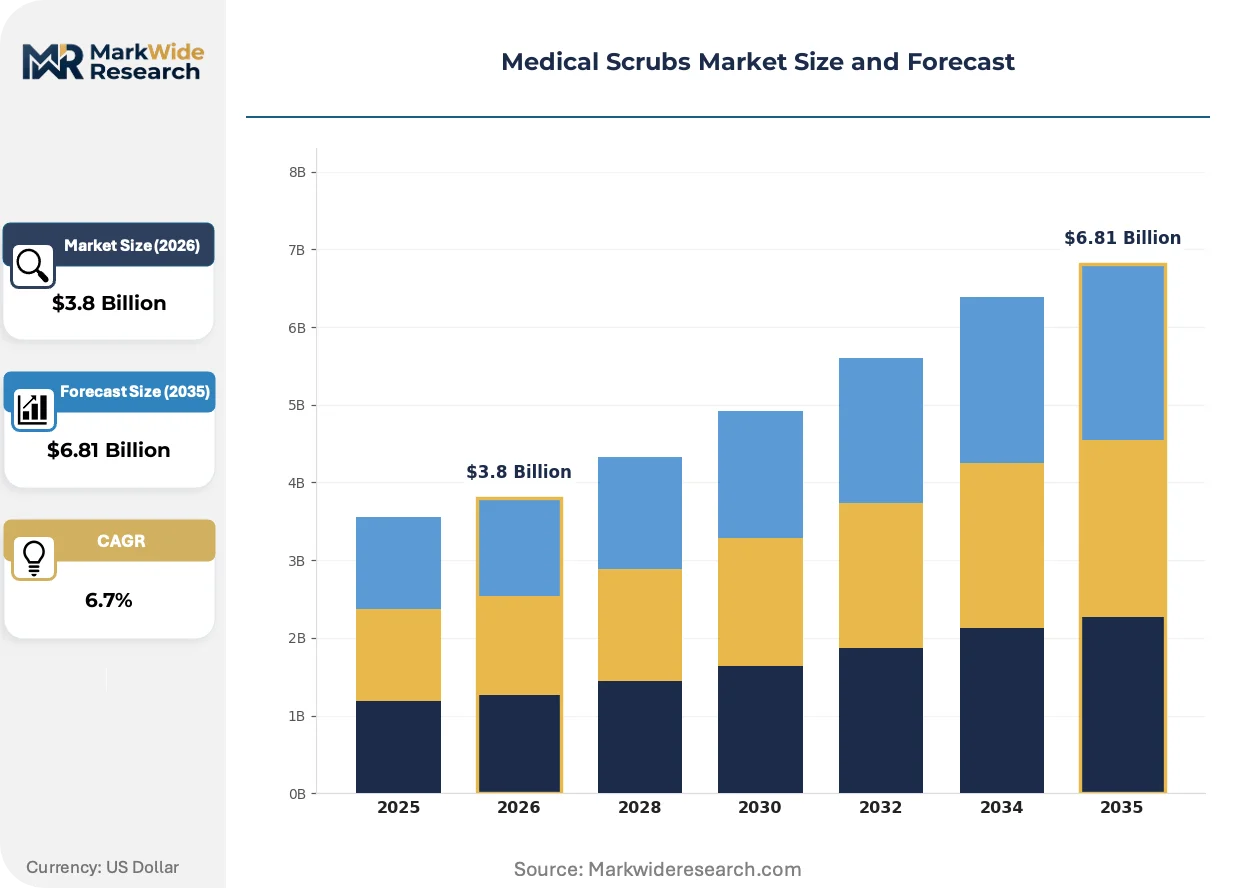
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Scrubs, Designer Scrubs, Pediatric Scrubs, Surgical Scrubs Material: Cotton, Polyester, Blends, Microfiber End User: Nurses, Doctors, Medical Students, Veterinary Staff Distribution Channel: Online Retail, Specialty Stores, Medical Supply Outlets, Hospitals |
| Companies Covered | Landau, Jaanuu, Careismatic Brands, Maevn, WonderWink, FIGS, Medline, Adar, Barco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Scrubs Market Evolving Landscape
Material science advances and procurement model evolution are restructuring competitive advantage around compliance velocity and channel control rather than manufacturing scale alone.
Silver-ion and copper-infused fiber treatments are bifurcating the antimicrobial scrub category. Operating theater buyers are adopting these finishes at accelerated rates for barrier-performance garments. The technology is bifurcating supplier tiers between EPA-registered formulation holders and commodity blenders lacking verified claims.
REACH textile biocide restrictions are reshaping antimicrobial chemistry portfolios for European market access. Suppliers are reformulating active agents to maintain efficacy while meeting SVHC screening thresholds. Surgical scrub lines destined for EU distribution face the steepest reformulation timelines and third-party certification costs.
Clinician purchasing behavior is fragmenting across employer-provisioned and self-funded acquisition models. Group purchasing organizations are losing volume to direct e-commerce platforms among younger nursing cohorts. This channel rotation is most pronounced in US metropolitan markets where health system employment is less concentrated.
Medical Scrubs Market Segmentation
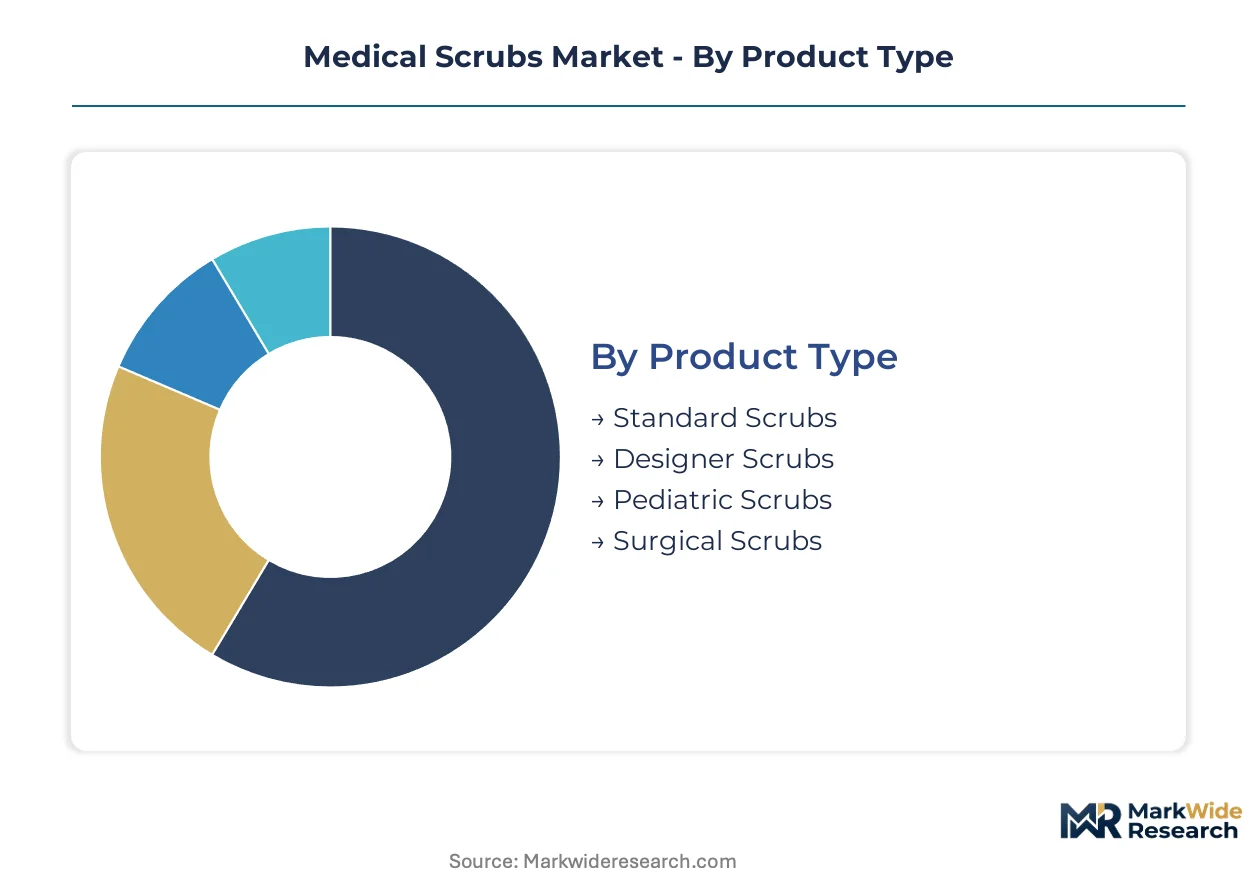
Medical scrub segmentation reflects divergent compliance burdens across clinical environments. Product specifications, material chemistry, and procurement channel selection each carry distinct regulatory triggers that reshape supplier economics.
Product Type:
FDA textile biocompatibility guidelines and OSHA bloodborne pathogen standards create tiered compliance intensity across garment categories.
- Surgical Scrubs:Engineered to AAMI Level 3-4 barrier specifications with fluid-resistant seams and shorter replacement cycles mandated by sterile processing protocols. Operating theater procurement in US acute care facilities concentrates demand here as Joint Commission audits tighten laundering validation requirements.
- Designer Scrubs:Aesthetic-forward garments incorporating antimicrobial finishes and stretch-weave construction for clinician mobility. Younger nursing cohorts in metropolitan US markets are driving direct-to-consumer volume as employer-provided allowances expand.
- Standard Scrubs:Basic cotton-polyester garments meeting minimum OSHA compliance for general ward use.
- Pediatric Scrubs:Smaller-scale garments with print-pattern differentiation for child-facing clinical environments.
Surgical scrubs handle the majority of throughput; designer scrubs are expanding most quickly on share.
Material:
Petrochemical feedstock volatility and EPA-registered antimicrobial verification requirements are restructuring supplier tier economics.
- Microfiber:Ultra-fine synthetic weaves below 1.0 denier enabling superior moisture wicking and bacterial retention reduction. US hospital systems are accelerating procurement of microfiber-polyester blends as CDC laundering guidelines emphasize lower-temperature disinfection compatibility.
- Blends:Cotton-polyester combinations balancing breathability against shrinkage control and industrial wash durability. Long-term care facilities prioritize these formulations for cost-managed refresh cycles amid nursing labor attrition.
- Polyester:Pure synthetic construction offering maximum chemical resistance and rapid drying for high-turnover environments.
- Cotton:Natural fiber construction with limited antimicrobial treatment retention, declining in acute care procurement.
Blends dominate current procurement volumes; microfiber is climbing the fastest on specification upgrades.
End User:
Professional licensing requirements and employer liability frameworks segment scrub procurement authority across clinical roles.
- Nurses:The largest addressable population with dual procurement pathways — employer-provisioned bulk contracts and self-funded individual purchases. US health system nursing unions are negotiating expanded uniform allowances, redirecting volume toward direct-to-consumer channels in competitive labor markets.
- Doctors:Physician-owned practice structures and hospital employment models create fragmented purchasing with premium tier bias. Surgical specialists command highest per-unit expenditure due to barrier-performance requirements in operating theater assignments.
- Medical Students:Price-sensitive volume concentrated in institutional bulk programs with standardized color-coding requirements.
- Veterinary Staff:Specialized barrier needs against zoonotic transmission with distinct laundering protocol specifications.
Nurses generate the majority of unit demand; doctors show the steepest per-unit expenditure trajectory.
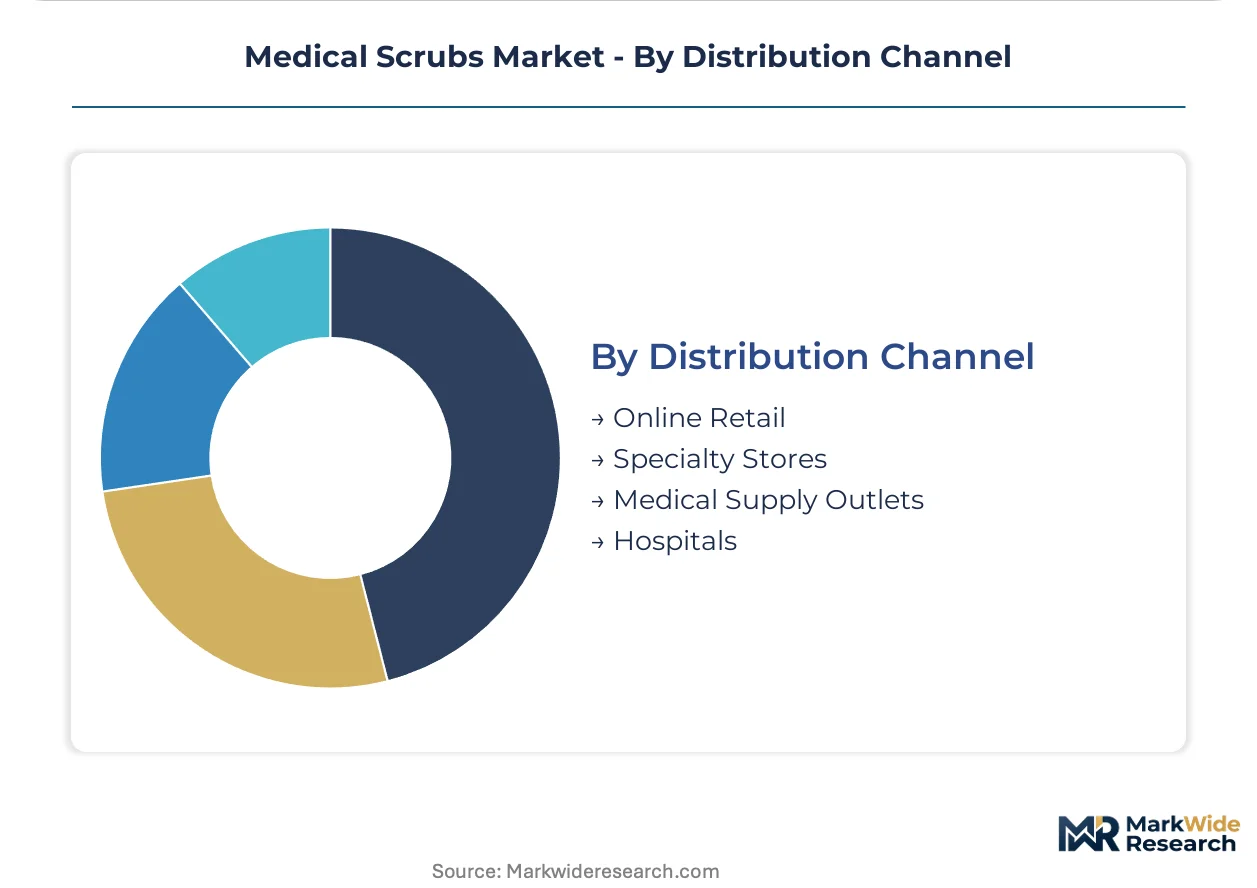
Distribution Channel:
Group purchasing organization consolidation and digital platform penetration are restructuring margin capture across channel tiers.
- Hospitals:Centralized procurement through materials management departments with multi-year contract structures. Large US health systems leverage volume concentration to extract technical compliance guarantees and captive inventory management from suppliers.
- Online Retail:Direct-to-consumer platforms bypassing GPO fee structures with personalized fit algorithms and subscription replenishment models. FIGS and comparable digital-native operators are capturing younger clinician cohorts in urban US markets.
- Specialty Stores:Brick-and-mortar fitting services with immediate inventory availability for urgent replacement needs.
- Medical Supply Outlets:Local distributors serving independent practices and post-acute facilities with limited procurement infrastructure.
Hospitals channel the majority of contract value; online retail is gaining share fastest among non-institutional purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in US health systems negotiating multi-year scrub contracts, while Indian suppliers compete on contract manufacturing margins without equivalent brand premium capture.
United States
Hospital procurement consolidation and infection control protocol tightening drive specification upgrades toward polyester-microfiber blends. FDA textile biocompatibility guidelines and OSHA bloodborne pathogen standards mandate laundering validation systems. Texas Medical Center and Mayo Clinic Rochester anchor sterile processing department demand for AAMI Level 3-4 surgical scrubs.
China
NMPA biocompatibility guidelines for medical textiles expand addressable demand in tier-one hospital systems undergoing accreditation upgrades. Dual carbon goals accelerate domestic microfiber production capacity expansion. Shanghai and Beijing hospital clusters import barrier-performance certified scrubs for international-standard operating theaters.
Germany
REACH textile biocide restrictions reshape antimicrobial chemistry portfolios for EU market access. ECHA SVHC screening thresholds force reformulation of silver-ion fiber treatments. Bavarian medical textile manufacturers in Augsburg and Munich regions face steepest third-party certification costs for surgical scrub lines.
India
CDSCO medical device textile classifications formalize standards rewarding early-mover suppliers with certified manufacturing capabilities. PLI scheme incentives attract polyester-microfiber weaving capacity to Tamil Nadu and Gujarat. Tiruppur and Surat industrial clusters supply untreated cotton-polyester blends to cost-managed long-term care facilities.
Japan
PMDA quality management system requirements elevate compliance barriers for imported antimicrobial scrubs. METI standards promote domestic microfiber innovation for high-turnover clinical environments. Osaka and Nagoya metropolitan hospital networks concentrate demand for premium barrier-performance garments.
Medical Scrubs Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with EPA-registered formulation holders commanding premium positioning while commodity blenders compete on contract manufacturing scale. The vendor base spans consolidated hospital suppliers with captive distribution networks and digital-native direct-to-consumer operators. Three archetypes dominate: integrated health system contractors, antimicrobial technology licensors, and aesthetic-focused direct brands. M&A activity concentrates on antimicrobial formulation assets, while strategic partnerships target GPO bypass channels.
Among US-based health system contractors, Medline occupies a position exemplifying integrated supply chain control spanning acute and long-term care facilities. Within the direct-to-consumer archetype, FIGS represents digital-native channel disruption targeting younger clinician cohorts in metropolitan markets. On the premium technology tier, Barco anchors designer aesthetic convergence with antimicrobial finish integration.
| Leading Market Players |
|---|
| Landau |
| Jaanuu |
| Careismatic Brands |
| Maevn |
| WonderWink |
| FIGS |
| Medline |
| Adar |
| Barco |
| Others |
Value Network & Pricing Analysis
Polyester-microfiber blend substitution for untreated cotton-polyester weaves is redrawing procurement geography toward petrochemical-adjacent manufacturing zones while compressing margin structures for legacy cotton-dependent suppliers.
Pricing Analysis
The customization-premium spread between configured-to-order surgical scrubs and standard ward garments runs wide. Contract-based long-term offtake dominates hospital procurement, with price differentiation driven by AAMI certification tier and volume scale. Cost compression in standard scrub tiers is intensifying because post-acute nursing labor attrition shrinks institutional procurement volumes. Medical students represent the most price-sensitive segment, while surgical specialists show lowest sensitivity due to barrier-performance mandates.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific trade lanes fluctuate with container availability at Los Angeles and Long Beach ports. Manufacturing concentrates in China, Vietnam, and India for polyester-microfiber weaving and cut-sew assembly. Raw material dependencies center on petrochemical feedstocks, silver-ion antimicrobial agents, and copper-infused fiber treatments. Single-source vulnerability in EPA-registered antimicrobial formulation supply creates concentration risk. Distribution runs through captive hospital networks, direct-to-consumer platforms, and medical supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated US health systems negotiating multi-year scrub contracts, fragmenting vendor margins while elevating technical compliance requirements.
For Market Incumbents: Fortify EPA-registered antimicrobial formulation assets through backward integration into fiber treatment chemistry. Deepen hospital contract stickiness by embedding sterile processing department validation services. The threat of digital-native direct-to-consumer entrants bypassing GPO fee structures demands channel control investment.
For New Entrants and Emerging Players: Subscription replenishment models for designer scrubs represent a service-layer gap where incumbents under-serve younger metropolitan nursing cohorts. White-space targets include personalized fit algorithms and antimicrobial finish customization. The most penetrable segment is direct-to-consumer online retail in competitive US labor markets where employer-provided uniform allowances expand.
For Investors and Strategic Acquirers: The market sits at a specification-upgrade phase that favors antimicrobial technology licensors over commodity blenders. Long-term viability hinges on compliance velocity rather than manufacturing scale alone. Acquisition targets should demonstrate EPA formulation holdings or CDSCO-certified Indian manufacturing capabilities. The signal to watch is state-level healthcare worker safety mandate fragmentation exceeding federal OSHA baselines.
| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Formulation Investment | EPA-registered chemistry holdings differentiate premium tier positioning from commodity blenders lacking verified claims. |
| Hospital System Partnership | Multi-year contracts with Texas Medical Center or Mayo Clinic Rochester anchor sterile processing department demand. |
| Direct-to-Consumer Platform Launch | Digital-native channel bypasses GPO fee structures to capture younger clinician cohorts in metropolitan markets. |
| CDSCO Certification Pathway | Early-mover certified manufacturing capabilities in Tamil Nadu or Gujarat unlock formalized Indian medical device textile standards. |
| REACH Reformulation Program | Silver-ion chemistry adaptation for ECHA SVHC screening thresholds preserves EU market access for surgical scrub lines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement directors, sterile processing department managers, GPO contracts managers, and antimicrobial textile R&D leads. Secondary validation drew from FDA textile biocompatibility filings, EPA antimicrobial claim registrations, hospital procurement database extracts, and customs records of polyester-microfiber weave imports. Bottom-up volume modeling triangulated against top-down health system expenditure estimates.
Across the analysis window, projections integrate product type segmentation by barrier performance tier, material chemistry by antimicrobial finish category, end user by professional licensing requirements, and distribution channel by procurement authority concentration. CAGRs were derived from trend extrapolation of refresh cycle compression and specification upgrade rates. Forecast inputs incorporated NMPA biocompatibility guideline implementation timelines and CDSCO medical device textile classification formalization.
Forecasts assume regulatory continuity in FDA textile biocompatibility regimes and EPA antimicrobial claim verification protocols; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Blood and Organ Bank Market
Healthcare Products
Isolation Gowns Market
Healthcare Products
Hospital Privacy Screens Market
Healthcare Products
Automatic Hand Sanitizer Dispenser Market
Healthcare Products
Cooling Mattress Market
Healthcare Products
Global Consumer Healthcare Products Market
Healthcare Products
Italy Hand Sanitizer Market
Healthcare Products
Consumer Healthcare Market
Healthcare Products
Medical Products Market
Healthcare Products
Blood and Blood Components Market
Healthcare Products
Artificial Saliva Market
Healthcare Products
Global Clinical Trial Consumables Market
Healthcare Products
Ejiao Health Products Market
Healthcare Products
Smoking Cessation Aids Market
Healthcare Products
Australia Hair Transplant Market
Healthcare Products
Global Healthcare Distribution Market