
 Wearable Ambulatory Monitoring Device Market | 2026-2036
Wearable Ambulatory Monitoring Device Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Ambulatory Monitoring Device Market Analytics
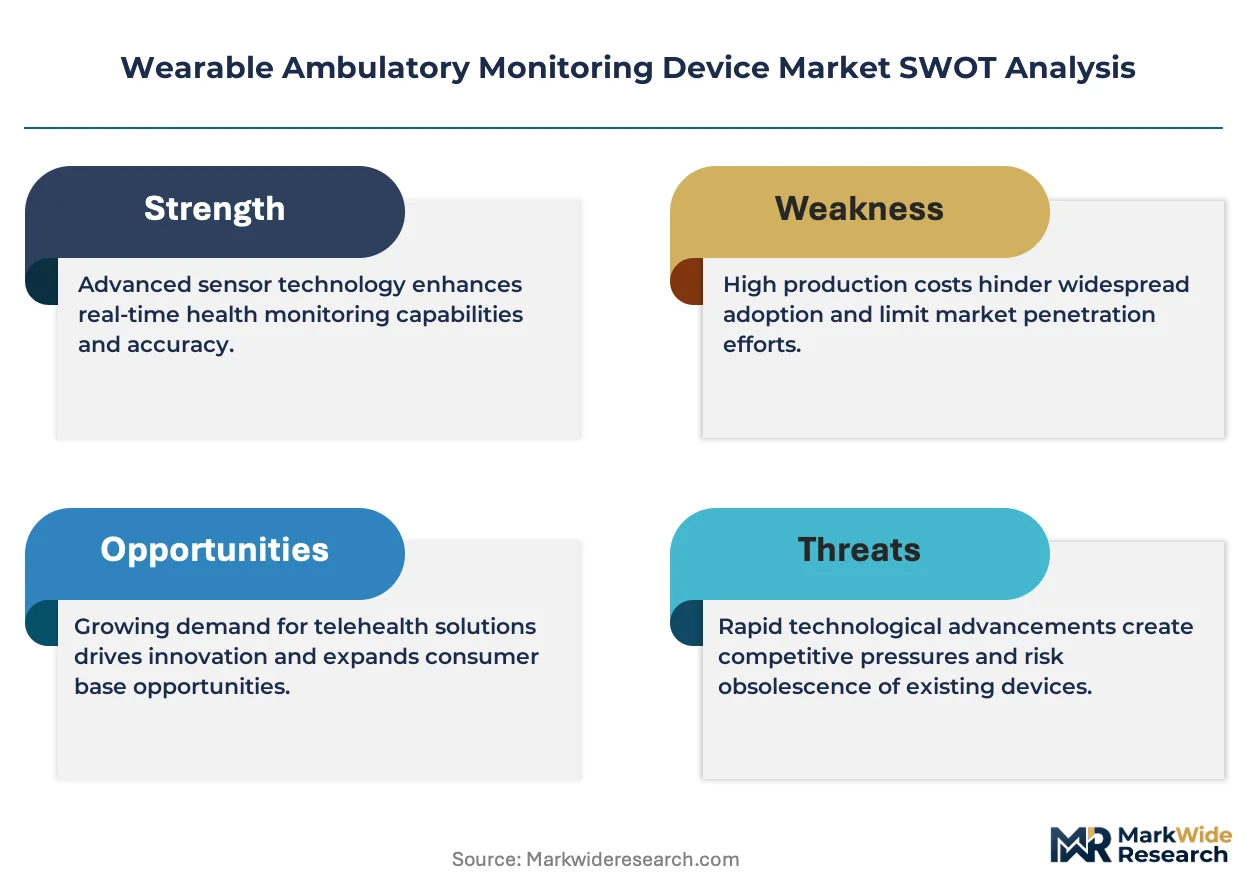
The capital-intensity divergence between semiconductor fabrication investments and cloud infrastructure spending is unwinding competitive dynamics among wearable device manufacturers. Apple Inc. leverages its vertically integrated silicon design to control power efficiency in health sensors. Abbott sustains dominance in continuous glucose monitoring through proprietary enzymatic sensor chemistry. Medtronic anchors hospital channel relationships that shape enterprise procurement decisions for ambulatory cardiac systems.
Wearable ambulatory monitoring devices are portable electronic systems incorporating biosensors, accelerometers, and wireless transceivers that capture physiological data outside clinical settings with sampling frequencies ranging from 1 Hz to 512 Hz for cardiac applications. These instruments serve primarily to detect arrhythmias, track metabolic markers, and flag acute events for clinical intervention before emergency presentation. ECG Monitors command premium pricing due to regulatory clearance requirements and clinical validation burdens that create barriers to entry. Bluetooth-enabled devices occupy volume leadership in consumer channels, while Cellular-connected systems are expanding fastest among remote monitor populations requiring uninterrupted data streams independent of smartphone proximity.
FDA premarket clearance pathways under 21 CFR 870 shape product development timelines and predicate device selection for cardiac monitoring submissions. CMS national coverage determinations for ambulatory electrocardiography directly influence hospital system adoption curves and manufacturer revenue recognition patterns. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled diagnostic algorithms, as predicate-based clearance frameworks face pressure from machine-learning models that continuously update after commercialization.
Market Dynamics
CMS reimbursement expansion for continuous cardiac monitoring is restructuring procurement authority from hospital IT departments toward cardiology service lines with direct patient outcome accountability.
Growth Catalysts
- Remote Patient Monitoring Reimbursement:CMS national coverage determinations for ambulatory electrocardiography create sustainable revenue streams for hospital systems deploying cellular-connected monitors.
- Artificial Intelligence Diagnostic Algorithms:FDA 510(k) clearance pathways for AI-enabled arrhythmia detection accelerate clinical validation timelines for algorithm developers.
- United States:Medicare coverage decisions for continuous cardiac monitoring establish precedents that influence procurement patterns across OECD health systems.
Market Restraints
- Semiconductor Fabrication Concentration:Taiwan and South Korea dominate advanced node production for biosensor microcontrollers, creating supply vulnerability for wearable device manufacturers.
- Enzymatic Sensor Chemistry:Proprietary glucose oxidase formulations require cold-chain logistics that inflate distribution costs for continuous metabolic monitors.
- FDA Predicate Device Requirements:21 CFR 870 clearance frameworks demand extensive clinical equivalence studies that extend development timelines for novel form factors.
Strategic Opportunities
- India:CDSCO regulatory harmonization with IMDRF standards reduces dual-certification burdens for manufacturers entering the subcontinent's hospital procurement channels.
- Photoplethysmography-ECG Fusion:Convergent optical and electrical sensing modalities enable single-device multi-parameter monitoring without separate hardware attachments.
- Direct-to-Employer Contracting:Self-insured corporations bypass traditional payer networks to procure ambulatory monitoring for workforce cardiovascular risk management.
Industry Challenges
- Embedded Firmware Engineering:Scarcity of developers with combined signal processing and ultra-low-power optimization skills constrains product iteration velocity.
- HIPAA Technical Safeguards:Encryption key management for Bluetooth Low Energy transmission streams complicates interoperability with legacy hospital information systems.
- ISO 13485 Certification:Quality management system audits for medical device software require 12-18 month preparation cycles that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Ambulatory Monitoring Device Market |
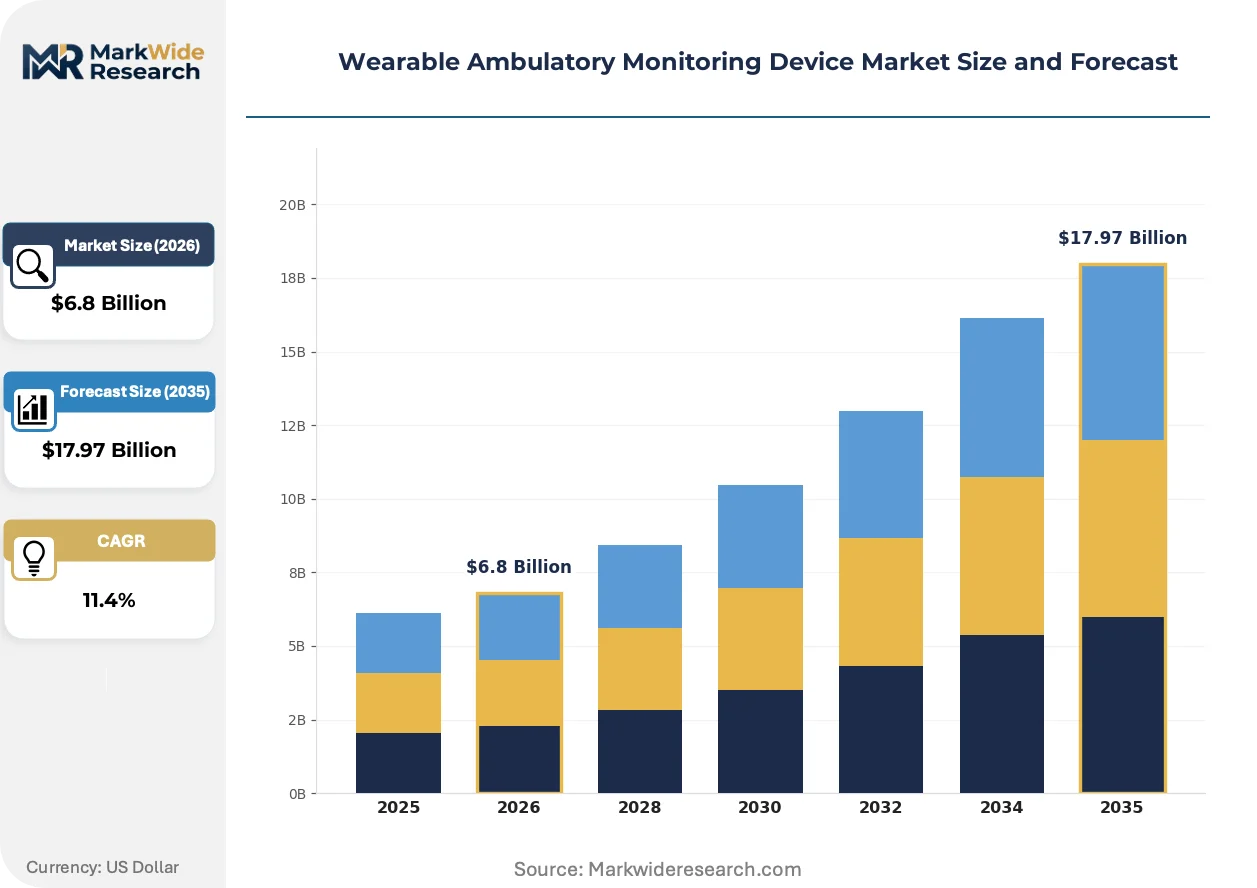
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Health Monitors, ECG Monitors Technology: Bluetooth, NFC, Wi-Fi, Cellular End User: Patients, Healthcare Providers, Fitness Enthusiasts, Remote Monitors Application: Chronic Disease Management, Fitness Tracking, Emergency Monitoring, Telehealth |
| Companies Covered | Apple Inc., Abbott, Medtronic, Koninklijke Philips N.V., GE HealthCare, iRhythm Technologies, Dexcom, Inc., Samsung, Fitbit Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Ambulatory Monitoring Device Market Evolving Landscape
Silicon architecture decisions are fragmenting competitive positioning between consumer wellness devices and clinical-grade monitors as sampling fidelity requirements diverge.
Photoplethysmography is bifurcating into two performance tiers. Optical heart rate sensors in consumer wearables operate at 25 Hz sampling sufficient for fitness tracking. Hospital-grade photoplethysmography arrays now achieve 512 Hz resolution for pulse wave velocity analysis. Cardiology departments at US academic medical centers are adopting the high-fidelity variant for heart failure decompensation prediction.
EU MDR Article 117 requirements for notified body involvement in software-as-a-medical-device classifications are extending conformity assessment timelines. Manufacturers previously self-certifying under MDD Annex II must now engage designated bodies for clinical evaluation report review. Class IIa cardiac monitoring submissions face 9-14 month additional delays versus pre-2021 pathways.
Hospital procurement committees are consolidating vendor relationships around enterprise-wide remote monitoring platforms. Discrete point solutions for single disease states lose shelf space to integrated systems spanning cardiac, respiratory, and metabolic parameters. Integrated delivery networks in Texas and Florida now mandate API interoperability with Epic and Cerner as table-stake requirements.
Wearable Ambulatory Monitoring Device Market Segmentation
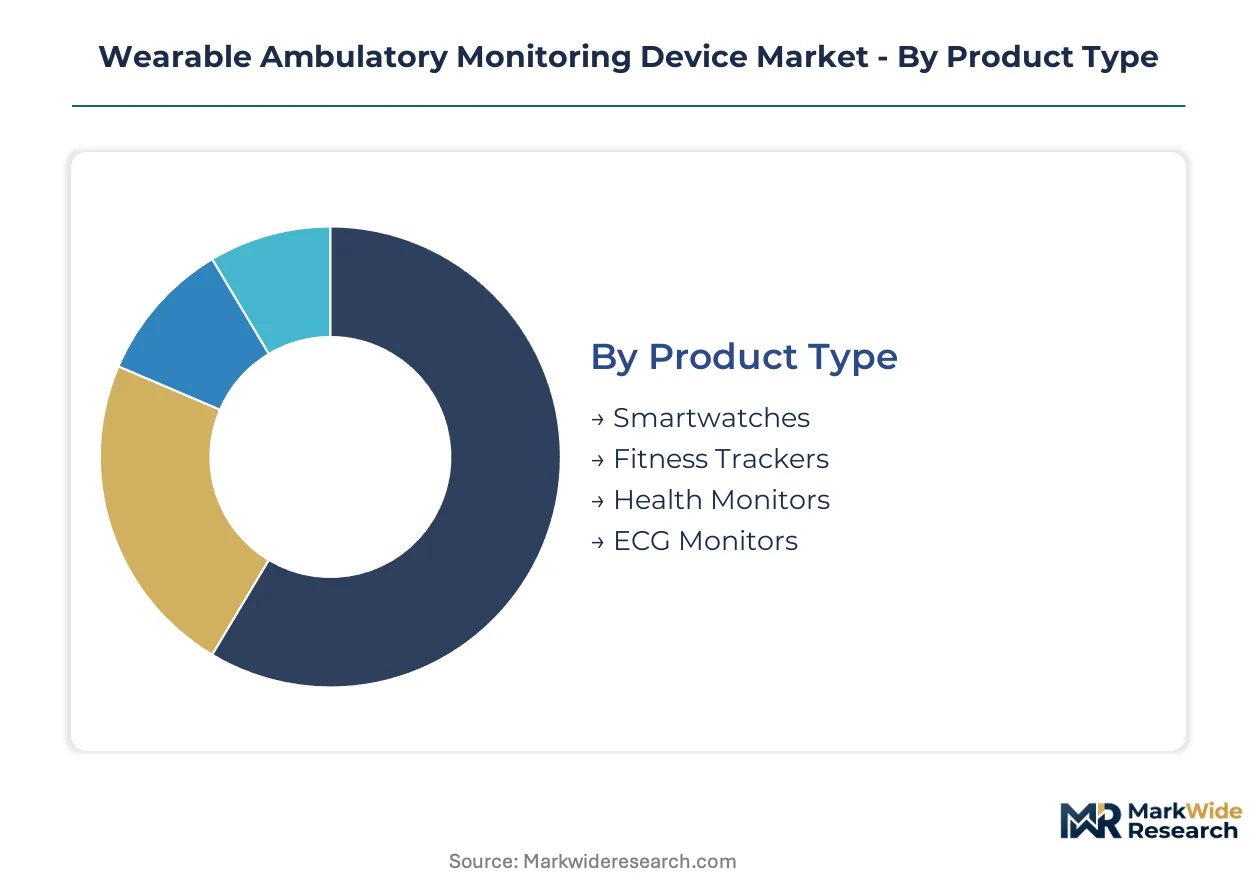
Segmentation in wearable ambulatory monitoring reveals how clinical validation requirements and connectivity specifications partition demand across consumer wellness and medical-grade channels. Manufacturers face divergent R&D investments depending on which segments they target.
Product Type:
Substitution pressure runs strongest against general-purpose wearables as smartphone-native health apps encroach on basic tracking functions.
- Smartwatches:Multi-function wrist-worn computers integrating accelerometers, gyroscopes, and optical heart rate sensors at 25-100 Hz sampling. Demand concentrates among fitness enthusiasts in the United States where Apple Watch and Samsung Galaxy Watch dominate consumer channels, though FDA 510(k) clearances for atrial fibrillation detection are shifting procurement toward cardiology-validated models.
- ECG Monitors:Single-lead or multi-lead electrical sensing devices capturing cardiac depolarization waveforms at 128-512 Hz with diagnostic-grade resolution. Hospital systems in Germany and the United States are expanding deployment for post-discharge arrhythmia surveillance as EU MDR and FDA predicate pathways mature, though reimbursement coding complexity constrains patient access.
- Fitness Trackers:Stripped-down wearables prioritizing step counting and sleep staging with minimal clinical validation.
- Health Monitors:Dedicated devices for specific biomarkers such as continuous glucose or blood pressure.
Fitness Trackers anchor the volume base while ECG Monitors gain share at the steepest rate.
Technology:
Cost tiering separates premium cellular connectivity from commodity Bluetooth implementations.
- Cellular:Embedded LTE/5G modems enabling autonomous data transmission without smartphone tethering. Remote monitor populations in rural United States and elderly cohorts in Japan drive demand as CMS reimbursement and Japan's Ministry of Health, Labour and Welfare expand coverage for uninterrupted cardiac surveillance.
- Bluetooth:Low-energy 2.4 GHz protocols dominating consumer wearables through smartphone gateway dependency. Volume leadership in fitness and wellness channels reflects hardware cost minimization, though HIPAA Technical Safeguards for encryption key management complicate hospital information system integration.
- Wi-Fi:Higher-bandwidth connectivity for home-based monitoring stations with stationary power sources.
- NFC:Proximity-based pairing and payment integration with limited continuous monitoring utility.
Bluetooth anchors the volume base while Cellular climbs the fastest among reimbursed clinical applications.
End User:
Customer type determines whether procurement flows through retail, hospital supply chain, or direct-to-employer contracting.
- Healthcare Providers:Hospital systems, accountable care organizations, and cardiology practices purchasing enterprise-grade monitoring platforms. Integrated delivery networks in Texas and Florida now mandate API interoperability with Epic and Cerner as mandatory requirements, consolidating vendor relationships around multi-parameter systems.
- Remote Monitors:Post-acute patients requiring continuous surveillance outside clinical settings. CMS national coverage determinations for ambulatory electrocardiography in the United States and similar frameworks in Germany are expanding this segment fastest as value-based care models shift accountability to cardiology service lines.
- Patients:Direct-purchase consumers seeking wellness insights without clinical oversight.
- Fitness Enthusiasts:Performance-oriented users prioritizing training load and recovery metrics.
Patients anchor the volume base while Remote Monitors expand most quickly under evolving reimbursement.
Application:
Maturity differentiation separates established fitness tracking from emerging clinical use cases.
- Chronic Disease Management:Long-term monitoring for heart failure, diabetes, and hypertension progression. Abbott's proprietary enzymatic sensor chemistry sustains dominance in continuous glucose monitoring, while Medtronic anchors hospital channel relationships for ambulatory cardiac systems in the United States and Western Europe.
- Telehealth:Synchronous and asynchronous virtual care delivery enabled by biometric data streaming. COVID-19-accelerated regulatory flexibility from FDA and CMS has persisted, with Texas and California Medicaid programs now reimbursing remote physiologic monitoring codes that include wearable-derived data.
- Fitness Tracking:Wellness and performance optimization without diagnostic intent.
- Emergency Monitoring:Fall detection and acute event flagging for elderly populations.
Fitness Tracking anchors the volume base while Telehealth shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in wearable ambulatory monitoring devices tilt toward net imports in emerging health systems while established markets export clinical validation expertise and regulatory consulting services. The United States, Germany, Japan, and China concentrate manufacturing partnerships and reimbursement policy innovation that shape procurement patterns elsewhere.
United States
Hospital systems in Texas and Florida are consolidating vendor relationships around enterprise remote monitoring platforms as CMS expands national coverage determinations for ambulatory electrocardiography. FDA premarket clearance pathways under 21 CFR 870 continue shaping predicate device selection for cardiac monitoring submissions. The Minneapolis-St. Paul corridor anchors Medtronic's hospital channel operations while Silicon Valley clusters Apple Inc.'s vertically integrated silicon design teams.
Germany
Cardiology departments at Charité Berlin and Heidelberg University Hospital are adopting 512 Hz photoplethysmography arrays for heart failure decompensation prediction. EU MDR Article 117 requirements for notified body involvement extend conformity assessment timelines for software-as-a-medical-device classifications. The Baden-Württemberg region clusters precision sensor manufacturing operations serving both automotive and medical device supply chains.
Japan
Elderly cohorts in rural prefectures drive demand for cellular-connected monitors as Japan's Ministry of Health, Labour and Welfare expands reimbursement for uninterrupted cardiac surveillance. METI standards harmonization with IMDRF frameworks reduces dual-certification burdens for manufacturers entering hospital procurement channels. The Kansai region around Osaka concentrates precision electronics manufacturing for biosensor microcontrollers.
China
Domestic manufacturers are capturing share in fitness tracker volume segments while foreign clinical-grade devices retain hospital channel dominance. NMPA regulatory harmonization with international standards accelerates market entry timelines for multinational submissions. The Yangtze River Delta around Shanghai anchors contract manufacturing operations for Bluetooth-enabled consumer wearables serving export markets.
India
CDSCO regulatory harmonization with IMDRF standards is reducing dual-certification burdens for manufacturers entering hospital procurement channels in Maharashtra and Karnataka. The country's national pharmaceutical regulator is streamlining import licensing for continuous glucose monitoring devices. The Delhi-NCR corridor concentrates medical device distribution networks serving tertiary care hospitals across North India.
Wearable Ambulatory Monitoring Device Market Competitive Landscape
Concentration sits with diversified technology conglomerates and specialized medical device manufacturers competing across distinct validation tiers. The vendor base separates into consumer wellness platforms, clinical-grade monitoring specialists, and hospital channel incumbents with enterprise procurement relationships. Three archetypes dominate: vertically integrated silicon designers, proprietary sensor chemistry holders, and enterprise platform consolidators. Competitive moves center on API interoperability mandates and photoplethysmography-ECG fusion R&D rather than price-based rivalry.
Within the diversified technology tier, Apple Inc. and Samsung occupy positions spanning consumer wellness and regulated health applications. Abbott exemplifies the proprietary chemistry archetype through enzymatic sensor formulations. Medtronic anchors the hospital channel incumbent position. iRhythm Technologies and Dexcom, Inc. represent pure-play monitoring specialists. Koninklijke Philips N.V. and GE HealthCare sit within diversified health technology conglomerates. Fitbit Inc. exemplifies the wellness-to-clinical transition archetype.
| Leading Market Players |
|---|
| Apple Inc. |
| Abbott |
| Medtronic |
| Koninklijke Philips N.V. |
| GE HealthCare |
| iRhythm Technologies |
| Dexcom, Inc. |
| Samsung |
| Fitbit Inc. |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with Taiwan-based foundries lock in microcontroller supply for cardiac monitor manufacturers while fixing wafer costs across multi-year procurement horizons. These arrangements insulate FDA-cleared device makers from spot-market volatility in advanced node semiconductors, though they require minimum volume commitments that strain emerging entrants.
Pricing Analysis
Hospital procurement committees anchor pricing negotiations for enterprise-grade ambulatory monitors, driving three-tier pricing structure across premium diagnostic, standard clinical, and economy wellness tiers. FDA 510(k) clearance tier and ISO 13485 certification status differentiate price bands, with predicate-device equivalence studies adding substantial cost burdens to premium tier development. Pricing pressure stems from CMS reimbursement compression on remote physiologic monitoring codes, squeezing margins for cellular-connected systems. Direct-to-consumer buyers show highest price sensitivity, while integrated delivery networks in Texas and Florida demonstrate lowest sensitivity due to outcome-based contracting frameworks.
Supply Chain Analysis
Just-in-time inventory strategies dominate Bluetooth-enabled consumer wearables, whereas clinical-grade cardiac monitors rely on strategic stockpiles of enzymatic sensor chemistries and specialized ECG electrodes. Taiwan, South Korea, and China concentrate advanced node production for biosensor microcontrollers, with the Yangtze River Delta anchoring contract assembly operations. Cold-chain logistics for glucose oxidase formulations and lithium-polymer battery cells constitute critical input dependencies. Single-source vulnerability in Taiwan semiconductor fabrication creates structural risk exposure. Distribution runs through hospital GPO contracts in the United States and specialized medical device distributors in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wearable ambulatory monitoring sits in early-cycle expansion as CMS national coverage determinations for continuous cardiac monitoring unlock hospital procurement budgets previously constrained by fee-for-service limitations.
For Market Incumbents: Fortify enterprise platform positions by deepening API interoperability with Epic and Cerner installations across Texas and Florida integrated delivery networks. Expand backward integration into photoplethysmography-ECG fusion sensor modules to defend against consumer wellness encroachment from Apple and Samsung. Prioritize ISO 13485 certification maintenance as EU MDR Article 117 extends conformity assessment timelines for software-as-a-medical-device classifications. For New Entrants and Emerging Players: CDSCO regulatory harmonization with IMDRF standards offers a certification fast-track for manufacturers targeting Maharashtra and Karnataka hospital procurement channels. Target direct-to-employer contracting for workforce cardiovascular risk management as the most penetrable white-space, bypassing traditional payer network complexity. Pursue photoplethysmography-ECG convergence R&D as the primary go-to-market differentiator against single-modality incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward proprietary sensor chemistry holders with enzymatic formulation IP and established hospital channel relationships. Five-to-ten year viability favors manufacturers with vertically integrated silicon design capabilities and CMS reimbursement strategy expertise. Watch FDA guidance evolution on artificial intelligence-enabled diagnostic algorithms as the critical inflection signal, as continuous-learning models may disrupt predicate-based clearance frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Pathway Optimization | Accelerates clearance timelines for cardiac monitoring submissions under 21 CFR 870 frameworks. |
| Cellular Connectivity Integration | Captures CMS reimbursement expansion for remote patient monitoring in rural United States. |
| Photoplethysmography-ECG Fusion Development | Enables single-device multi-parameter monitoring without separate hardware attachments. |
| Hospital System Partnership Consolidation | Locks in enterprise procurement relationships with integrated delivery networks in Texas and Florida. |
| AI Diagnostic Algorithm Validation | Positions manufacturers for FDA clearance of continuous-learning arrhythmia detection models. |
Research Methodology
Cross-validation between hospital procurement database analysis and CMS reimbursement filing review anchors the qualitative findings on adoption curve dynamics. Primary interviews with cardiology service line directors, biomedical engineers, GPO contracts managers, and FDA regulatory affairs specialists combined with secondary validation from FDA 510(k) clearances, CMS national coverage determinations, EU MDR notified body assessments, and hospital supply chain disclosures. Bottom-up demand modeling from device shipment data triangulates against top-down healthcare expenditure analysis across the analysis window.
Sensitivity analysis around reimbursement policy scenarios and semiconductor supply disruption probabilities informs the projection framework. Segmentation dimensions modeled include product type, connectivity technology, end-user archetype, and application across the modeling period. CAGRs derive from regression analysis of historical adoption curves adjusted for regulatory inflection points. Key forecast inputs incorporate CMS remote physiologic monitoring code valuation updates and Taiwan foundry capacity expansion announcements.
Decision-makers should treat outputs as directional under stable reimbursement policy and supply chain continuity assumptions; material deviation in FDA AI guidance or Taiwan semiconductor export restrictions would warrant model refresh. Practitioners should keep alternative scenarios live as EU MDR conformity assessment timelines and CMS value-based care model penetration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
North America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Wearable Cardiac Monitors Market
Patient Monitoring
South America Remote Patient Monitoring Systems Market
Patient Monitoring
North America Patient Temperature Management Market
Patient Monitoring
Germany Patient Care Monitoring Equipment Market
Patient Monitoring
Sleep Monitoring Devices Market
Patient Monitoring
Patient Temperature Management Systems Market
Patient Monitoring
Remote Patient Monitoring Software and Services Market
Patient Monitoring
IoT in Healthcare Market
Patient Monitoring
Oman Blood Glucose Monitoring Market
Patient Monitoring
Respiratory Monitoring Devices Market
Patient Monitoring
China Patient Monitoring Market
Patient Monitoring
Urine Output Monitoring Systems Market
Patient Monitoring
Remote Electrocardiogram Monitoring Market
Patient Monitoring
South America Body Temperature Monitoring Market
Patient Monitoring
ICU ECG Patient Monitor Market