
 Lactose-Free Milk Market | 2026-2036
Lactose-Free Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Lactose-Free Milk Market Analysis
Supermarket dairy aisles is narrowing as retailers consolidate shelf space behind faster-turning functional milk SKUs. Danone S.A. leverages its specialized nutrition heritage to command premium positioning in European lactose-free dairy. Nestle S.A. anchors volume through multi-format distribution spanning ambient tetra packs and chilled bottles. Arla Foods Group differentiates via farm-gate traceability programs that resonate with health-conscious shoppers.
Lactose-free milk denotes fluid dairy processed with lactase enzyme to hydrolyze disaccharides into glucose and galactose, yielding sweetness without added sugars while maintaining protein and calcium profiles comparable to conventional milk. The primary commercial purpose centers on delivering digestible dairy nutrition to lactose-intolerant consumers and expanding addressable demand beyond traditional dairy drinkers. Whole milk formulations lead value contribution due to fuller mouthfeel and premium pricing acceptance, while online retail channels represent the fastest-expanding distribution vector as subscription replenishment models gain traction among households. Carton packaging dominates ambient logistics but faces margin pressure from lightweight pouch alternatives in emerging markets.
FDA labeling standards for enzyme-modified dairy and EU F-Gas Regulation governing cold-chain refrigerants shape product formulation and distribution infrastructure decisions across North American and European supply chains. USDA organic certification and EFSA health claim protocols further segment competitive positioning between conventional and premium-tier offerings. Stakeholders must monitor evolving national school nutrition programs and hospital procurement standards that increasingly specify lactose-free options as default dairy service.
Market Dynamics
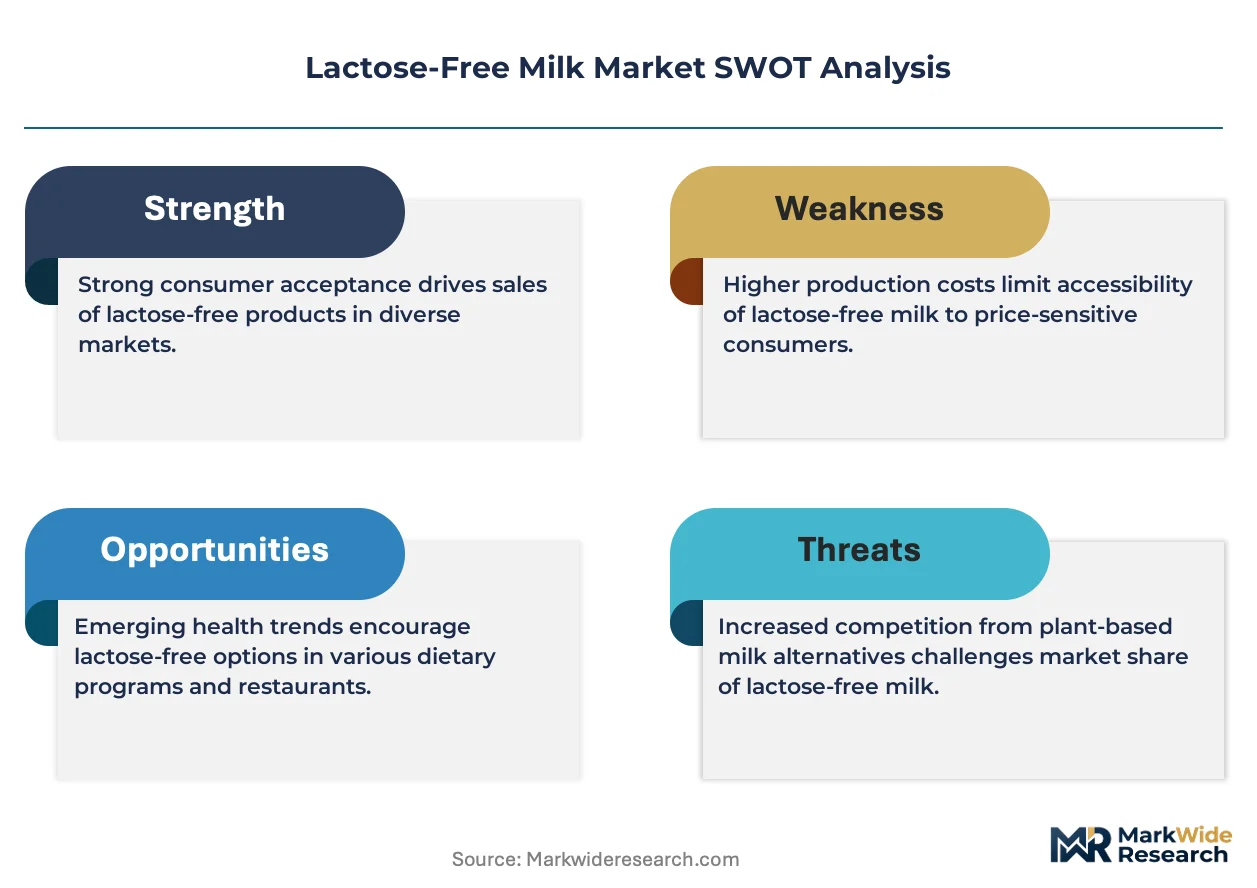
Enzyme hydrolysis technology has concentrated production among REACH-compliant European suppliers, creating supply-side gatekeeping that shapes competitive access to functional milk formulations.
Growth Catalysts
- USDA School Nutrition Standards:Federal procurement guidelines increasingly specify lactose-free dairy as default service in K-12 cafeterias, institutionalizing volume demand through annual bid cycles.
- Filtration capacity expansion:Dutch and Danish enzyme suppliers have scaled membrane separation infrastructure, reducing hydrolysis batch times and enabling just-in-time production for refrigerated distribution.
- Foodservice operator adoption:Major US restaurant chains now maintain dedicated lactose-free SKUs to reduce liability exposure and capture dairy-sensitive patron spending.
Market Restraints
- Input cost volatility:Lactase enzyme prices fluctuate with pharmaceutical-grade fermentation substrate costs, compressing margins for hydrolyzed milk processors without long-term supply contracts.
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon refrigerants raises cold-chain infrastructure costs for chilled bottle distribution, disadvantaging smaller regional dairies.
- Plant-based substitution:Oat and pea protein beverages capture price-sensitive consumers seeking dairy alternatives, limiting addressable market expansion for enzyme-modified fluid milk.
Strategic Opportunities
- Subscription replenishment models:Direct-to-consumer platforms bypass retail slotting fees and capture recurring revenue from diagnosed lactose-intolerant households.
- EFSA health claim protocols:Approved digestive comfort claims enable premium positioning for clinically tested formulations in German and French pharmacy channels.
- Ambient pouch formats:Lightweight aseptic packaging reduces logistics costs for emerging market entry where refrigerated distribution remains underdeveloped.
Industry Challenges
- Organic certification timelines:USDA organic lactose-free milk requires dual verification of enzyme source and dairy origin, extending product development cycles by 8-14 months.
- Cross-contamination protocols:Shared processing lines demand validated clean-in-place sequences between conventional and hydrolyzed milk runs, constraining batch scheduling flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactose-Free Milk Market |
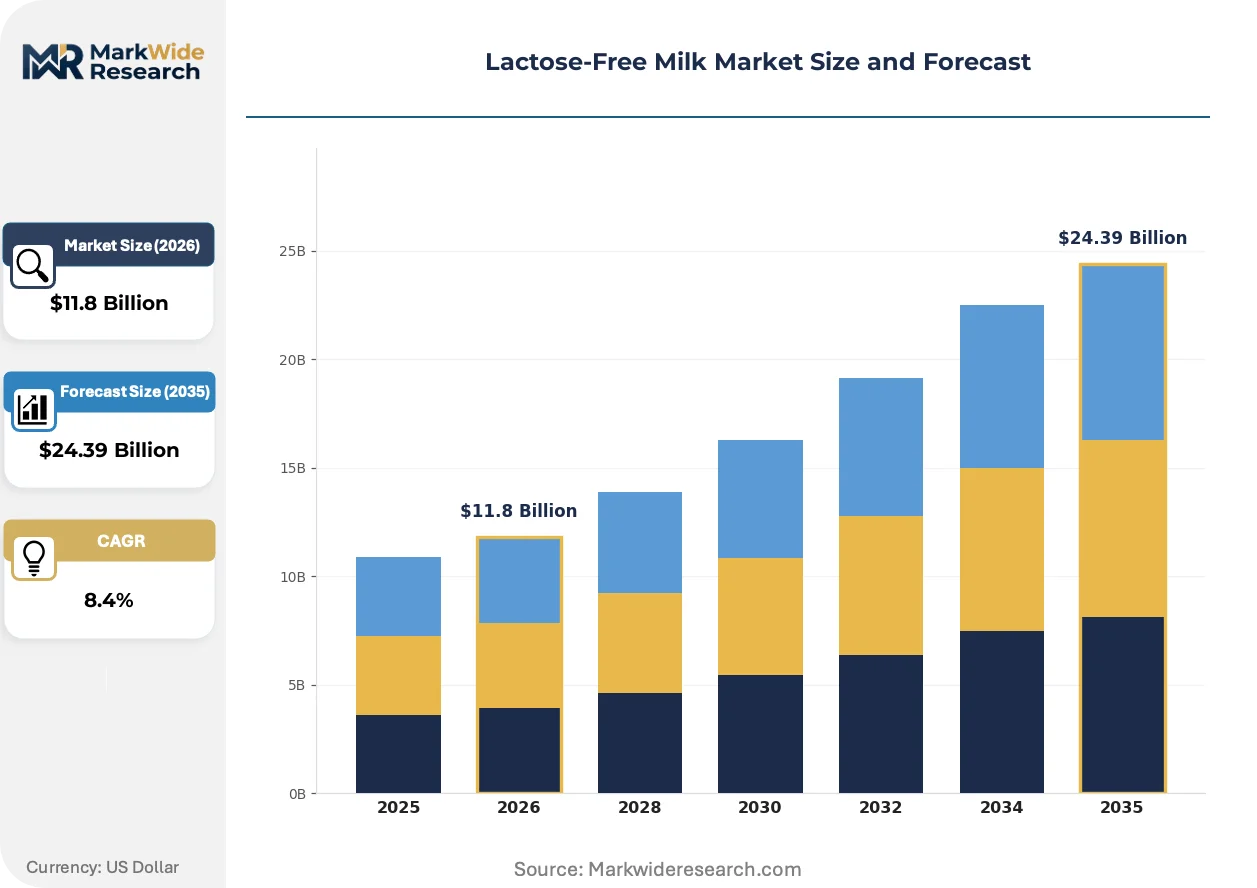
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Milk, Skim Milk, Low-Fat Milk, Cream Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores Customer Type: Households, Restaurants, Cafés, Health Facilities Packaging Type: Cartons, Bottles, Tetra Packs, Pouches |
| Companies Covered | Nestle S.A., Danone S.A., Fonterra Co-operative Group Ltd., Arla Foods Group, Organic Valley, Horizon Organic, Lactalis International, Valio Ltd., Royal FrieslandCampina N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactose-Free Milk Market Emerging Trajectories
Continuous-flow enzyme immobilization is replacing batch hydrolysis, while regulatory pressure on refrigerants and shifting procurement patterns reshape how value flows through dairy supply chains.
Membrane-immobilized lactase systems enable real-time hydrolysis during ultrafiltration, eliminating separate holding tanks and reducing processing time by half. Mid-sized US dairies in Wisconsin and New York are retrofitting existing ultrafiltration lines with these catalytic modules. Traditional batch enzyme addition is rendering obsolete for volume producers seeking throughput gains.
EU F-Gas Regulation mandates 80% reduction in hydrofluorocarbon refrigerants by 2030, forcing cold-chain infrastructure replacement across European dairy distribution. Natural refrigerant systems using CO2 or ammonia require capital-intensive retrofits of existing chilled storage facilities. Ambient-stable UHT lactose-free milk formats gain share in Germany and France as processors defer refrigeration investments.
Hospital and eldercare facilities are consolidating dairy procurement through group purchasing organizations, compressing supplier lists to single-source contracts with full nutritional documentation. Smaller regional dairies without dedicated lactose-free production lines lose institutional access. This concentration is most visible in the US Northeast, where health system mergers have reduced active dairy vendors by two-thirds since 2020.
Lactose-Free Milk Market Segmentation
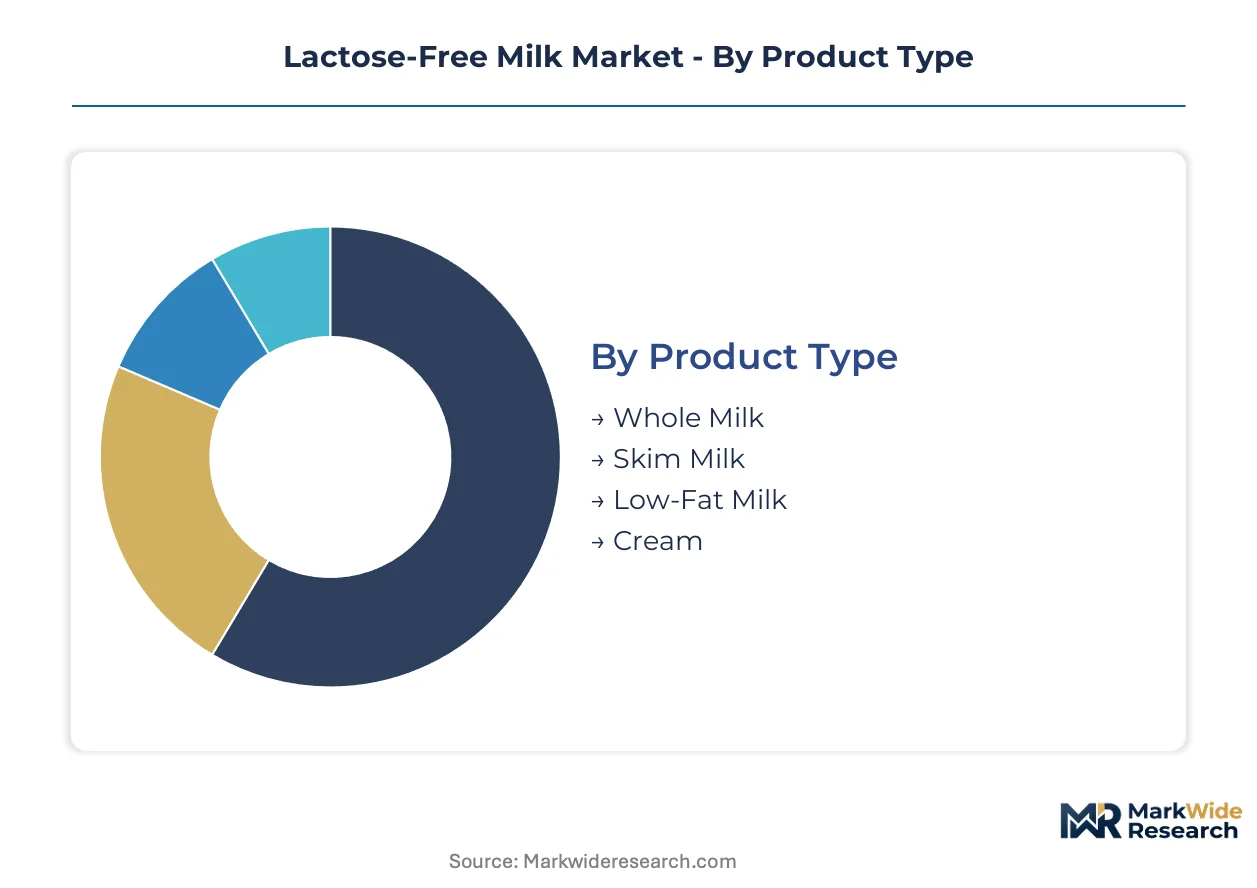
Segmentation in lactose-free milk reveals how enzyme hydrolysis technology, packaging logistics, and procurement concentration create divergent margin profiles across product tiers and channel configurations. Understanding these divisions exposes where capital deployment yields differential returns.
Product Type:
Whole milk turns over slowest due to premium positioning and extended shelf-life tolerance, while skim milk cycles fastest through health-focused retail channels with tighter expiration windows.
- Whole Milk:Higher butterfat content (3.25%+) delivers fuller mouthfeel and carries premium pricing acceptance in US and German retail. Demand concentrates in household pantry stocking and eldercare institutional procurement where caloric density carries nutritional priority.
- Skim Milk:Zero-fat formulation appeals to weight-management demographics and integrates into barista protocols requiring foam stability. US fitness-oriented households and boutique café chains in New York and Los Angeles drive replenishment velocity through subscription platforms.
- Low-Fat Milk:1-2% fat range splits the difference for price-sensitive consumers seeking moderate indulgence. European supermarket private-label programs favor this tier for volume positioning.
- Cream:High-fat derivative (18%+) serves foodservice sauce applications and premium coffee preparation. Limited production runs constrain availability outside dedicated dairy processing lines.
Whole milk anchors the volume base while skim milk gains share at the steepest rate.
Distribution Channel:
Channel economics separate by cold-chain dependency and slotting fee structures, with ambient-capable formats commanding logistics advantages in underdeveloped refrigeration markets.
- Supermarkets:Refrigerated case placement dominates volume in US and European grocery, where retailer consolidation has narrowed SKU counts behind faster-turning functional dairy. Reset schedules favor established suppliers with multi-year contracts.
- Online Retail:Direct-to-consumer subscription models bypass retail margin stacking and capture recurring revenue from diagnosed lactose-intolerant households. German and French pharmacy-adjacent platforms expand fastest through EFSA-compliant health claim positioning.
- Specialty Stores:Organic and allergen-focused independents carry premium-tier SKUs with traceability documentation. Limited footprint constrains national scale.
- Convenience Stores:Ambient UHT formats suit grab-and-go consumption in markets with refrigeration gaps. Emerging market entry point where cold-chain infrastructure remains capital-constrained.
Supermarkets retain the dominant revenue position while online retail climbs fastest among channel alternatives.
Customer Type:
Procurement concentration diverges sharply between fragmented household purchasing and consolidated institutional contracting, reshaping supplier access requirements.
- Households:Fragmented end-consumers purchase through retail and subscription channels based on diagnosed intolerance or preventive health preferences. USDA school nutrition standards increasingly specify lactose-free as default K-12 service.
- Restaurants:Major US chains now maintain dedicated SKUs to reduce liability exposure and capture dairy-sensitive patron spending. Group purchasing organizations compress vendor lists to single-source contracts.
- Cafés:Specialty coffee operators require barista-grade foam performance, favoring specific fat-content formulations. Independent operators in urban clusters drive regional demand variation.
- Health Facilities:Hospital and eldercare procurement consolidation through GPOs demands full nutritional documentation and batch traceability. US Northeast health system mergers have reduced active dairy vendors substantially.
Households generate the broadest revenue base while health facilities procurement expands most quickly through institutional mandate expansion.
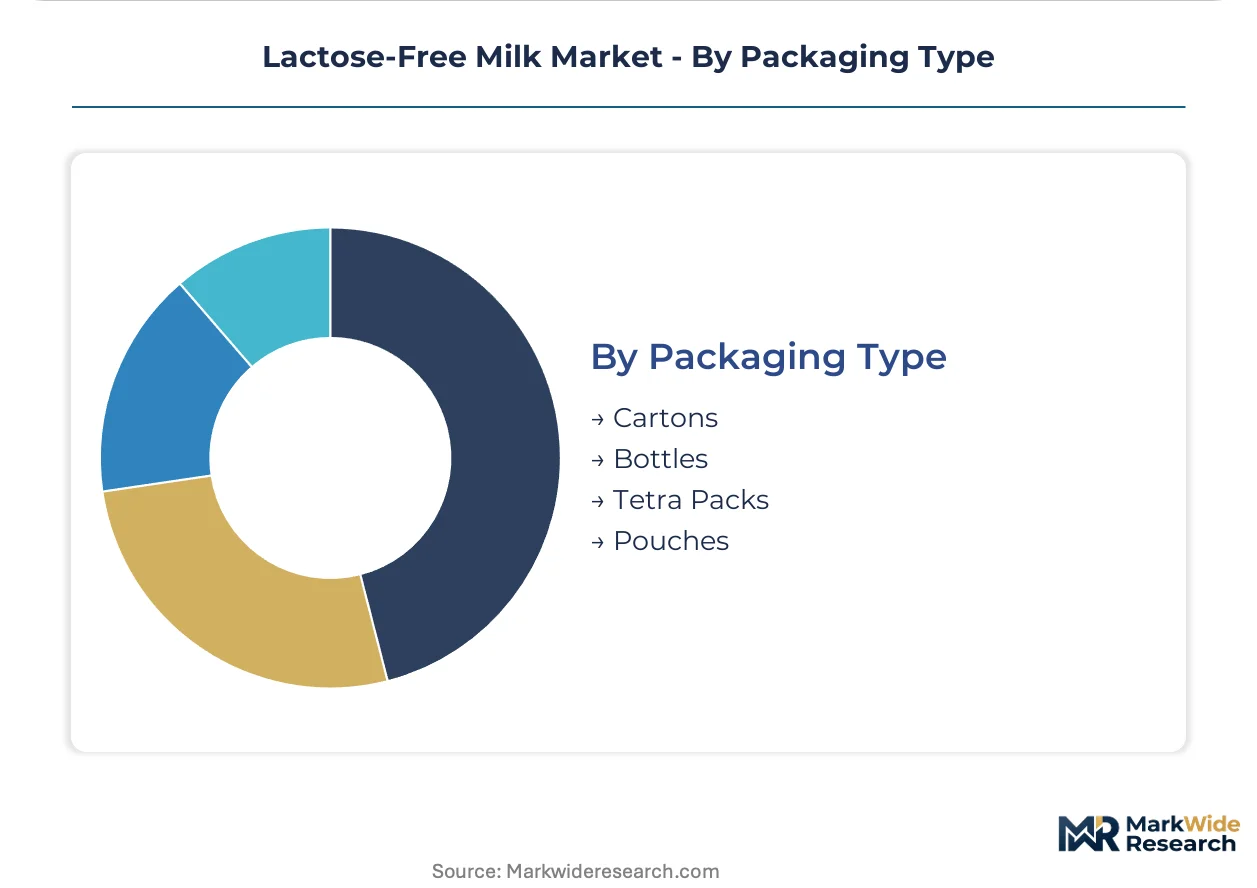
Packaging Type:
Material selection determines logistics economics and shelf-life extension, with lightweight alternatives gaining traction in cost-sensitive emerging markets.
- Cartons:Paperboard laminates dominate ambient logistics and refrigerated case presentation in North American and European retail. Established recycling infrastructure supports sustainability positioning.
- Bottles:PET and HDPE formats suit chilled distribution with consumer-preferred handling characteristics. EU F-Gas Regulation raises cold-chain infrastructure costs for this format.
- Tetra Packs:Aseptic brick packaging enables extended shelf-life without refrigeration, critical for emerging market penetration. Nestle and Danone deploy this format for ambient distribution reach.
- Pouches:Lightweight flexible packaging reduces material costs and shipping weight, gaining share in price-sensitive Asian and Latin American markets where refrigeration remains underdeveloped.
Cartons hold the installed volume base while pouches expand fastest through emerging market cost optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing acceptance in Germany and the United States exceeds emerging market benchmarks by substantial margins, creating a bifurcated revenue geography where developed economies capture disproportionate value per liter despite slower volume expansion rates.
United States
USDA school nutrition standards now specify lactose-free dairy as default service in K-12 cafeterias, institutionalizing volume demand through annual procurement bid cycles. FDA labeling requirements for enzyme-modified dairy shape formulation decisions across domestic supply chains. Wisconsin and New York dairy clusters are retrofitting ultrafiltration lines with membrane-immobilized lactase systems to reduce processing time.
Germany
EFSA health claim protocols enable premium positioning for clinically tested formulations in pharmacy-adjacent retail channels. EU F-Gas Regulation mandates phasedown of hydrofluorocarbon refrigerants, raising cold-chain infrastructure costs and accelerating ambient UHT format adoption. Bavarian and North Rhine-Westphalian processors are consolidating production to amortize natural refrigerant system investments.
France
Danone S.A. leverages specialized nutrition heritage to command premium positioning in domestic lactose-free dairy segments. ANSM pharmaceutical-adjacent distribution standards influence digestive comfort claim substantiation requirements. Paris and Lyon metropolitan areas concentrate subscription platform growth for diagnosed lactose-intolerant households.
China
SAMR dairy safety standards govern enzyme source verification and hydrolysis process documentation for imported and domestic production. Dual carbon goals accelerate lightweight pouch packaging adoption to reduce logistics emissions. Yangtze River Delta processors are expanding ambient-stable UHT capacity to serve interior provinces with underdeveloped refrigerated distribution.
Brazil
ANVISA dairy product registration requirements extend approval timelines for enzyme-modified fluid milk introductions. Price-sensitive consumer segments drive private-label volume in supermarket channels. São Paulo and Minas Gerais dairy cooperatives are evaluating aseptic pouch formats to reduce material costs and extend distribution reach into the Northeast region.
Lactose-Free Milk Market Vendor Landscape
Multinational nutrition conglomerates and cooperative dairy processors split the market between premium branded positioning and farm-gate traceability claims. The vendor base concentrates around entities with captive enzyme supply relationships or established cold-chain distribution infrastructure. Three archetypes dominate: diversified food majors leveraging multi-format distribution, dairy cooperatives emphasizing origin transparency, and specialized organic operators targeting health-channel placement. Capacity expansion in membrane-immobilized lactase systems and strategic partnerships for emerging market ambient distribution represent the dominant competitive vectors.
Among diversified food majors, Nestle S.A. and Danone S.A. exemplify multi-format distribution archetypes spanning ambient tetra packs and chilled bottles. Arla Foods Group occupies a position within the cooperative traceability tier, anchoring farm-gate documentation programs that resonate with health-conscious retail segments. These three entities represent contrasting strategic postures: scale-driven format flexibility, specialized nutrition heritage, and agricultural origin control.
| Leading Market Players |
|---|
| Nestle S.A. |
| Danone S.A. |
| Fonterra Co-operative Group Ltd. |
| Arla Foods Group |
| Organic Valley |
| Horizon Organic |
| Lactalis International |
| Valio Ltd. |
| Royal FrieslandCampina N.V. |
| Others |
Supply Flow & Price Mechanics
REACH-compliant enzyme suppliers in the Netherlands and Denmark anchor upstream concentration, directing margin capture toward processors with long-term lactase supply contracts and dedicated hydrolysis infrastructure. Premium positioning in pharmacy-adjacent retail channels and institutional procurement programs downstream reflects this supply-side gatekeeping dynamic.
Pricing Analysis
The customization-premium spread separates clinically tested formulations with EFSA-substantiated digestive comfort claims from standard supermarket SKUs. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and enzyme source verification, with USDA organic lactose-free milk commanding the widest spread due to dual verification timelines. Pricing pressure stems from pharmaceutical-grade fermentation substrate cost volatility compressing processor margins. Household subscription purchasers show lowest price sensitivity while emerging market convenience channel buyers exhibit highest elasticity.
Supply Chain Analysis
Contract-manufacturing concentration sits with Dutch and Danish membrane filtration specialists holding scaled lactase immobilization capacity. Raw material flows draw from Irish and German dairy cooperatives for milk base, while enzyme supply rests on Austrian and German pharmaceutical fermentation facilities. Single-source vulnerability concentrates in lactase supply where three suppliers dominate REACH-compliant production. Distribution runs through chilled bottle networks in developed markets and ambient UHT tetra pack logistics in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lactose-free milk market represents an early-cycle expansion story where USDA institutional procurement mandates and EFSA health claim protocols are accelerating penetration beyond diagnosed intolerance populations into preventive health segments.
For Market Incumbents: Harden enzyme supply security through captive fermentation partnerships or long-term offtake agreements with REACH-compliant suppliers, insulating against pharmaceutical-grade substrate cost volatility. Fortify institutional access by consolidating GPO relationships and securing dedicated production lines to eliminate cross-contamination scheduling constraints that disadvantage shared-facility competitors. For New Entrants and Emerging Players: Pursue ambient-stable UHT pouch formats in Brazil and China's interior provinces where refrigerated distribution gaps persist and price-sensitive volume concentrates. Target pharmacy-adjacent subscription platforms in Germany and France where EFSA-compliant health claim positioning enables premium capture with lower slotting fee burdens than supermarket retail. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across membrane-immobilized lactase processing as continuous-flow systems displace batch hydrolysis infrastructure. Mid-sized dairies with retrofit ultrafiltration lines and established cold-chain relationships present acquisition targets with embedded distribution leverage. Monitor USDA school nutrition standard revisions and EU F-Gas Regulation compliance timelines as demand and cost structure inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane-Immobilized Lactase Retrofit | Wisconsin and New York dairies halve processing time through continuous-flow enzyme systems. |
| EFSA Health Claim Substantiation | Danone and Nestle capture pharmacy channel premium through clinically tested digestive comfort positioning. |
| Ambient Pouch Format Expansion | Brazilian cooperatives reduce logistics costs to serve Northeast regions lacking refrigerated distribution. |
| GPO Consolidation Response | US Northeast health system mergers reduce vendor lists, favoring suppliers with dedicated lactose-free lines. |
| Natural Refrigerant Infrastructure | German processors amortize CO2 and ammonia system investments through production consolidation. |
Methodological Framework
Desk research of FDA labeling guidance documents, EFSA health claim registers, and USDA procurement databases preceded structured interviews with dairy processing executives, enzyme supply technical directors, retail category buyers, and hospital GPO contracting officers. Primary fieldwork across Wisconsin, New York, Bavaria, and the Netherlands validated secondary findings on membrane-immobilized lactase adoption rates. Bottom-up volume modeling triangulated against top-down category spend estimates from customs records and dairy cooperative disclosures.
Assumption sets held FDA and EFSA regulatory frameworks stable while varying enzyme cost trajectories and institutional procurement penetration rates across the projection horizon. Segmentation dimensions modeled include product fat content tier, packaging cold-chain dependency, channel configuration, and customer procurement concentration. CAGRs derived from fitted growth curves applied to verified base-year volumes, with enzyme price elasticity and school nutrition program adoption curves as lactose-free milk-specific forecast inputs.
Sensitivities concentrate around lactase supply contract renegotiations, EU F-Gas Regulation compliance cost pass-through, and plant-based substitution rates in price-sensitive consumer segments. Forecasts embed these assumptions without contingency scenarios for regulatory reversal or breakthrough non-enzyme hydrolysis technologies. Quarterly review of USDA school nutrition program bid awards and REACH enzyme supplier capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
United Kingdom Dairy Alternatives Market
Dairy Alternatives
Europe Non-Dairy Milk Market
Dairy Alternatives
Europe Dairy Alternatives Market
Dairy Alternatives
Cashew Milk Market
Dairy Alternatives
Coconut Yogurt Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
Sugar-Free Soy Milk Powder Market
Dairy Alternatives
Coconut Milk Market
Dairy Alternatives
South America Dairy Alternatives Market
Dairy Alternatives
Banana Milk Market
Dairy Alternatives
Walnut Milk Market
Dairy Alternatives
On-The-Go Yoghurt Market
Dairy Alternatives
Global Vegan Sour Cream Market
Dairy Alternatives
Global Soy Desserts Market
Dairy Alternatives
Asia-Pacific Walnut Milk Market
Dairy Alternatives
Asia-Pacific Non-Dairy Milk Market