
 Japan Lactose-Free Dairy Market | 2026-2036
Japan Lactose-Free Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Lactose-Free Dairy Market Insights
Premium enzyme-treated formulations is rotating toward the center of competitive strategy in Japanese dairy. Meiji Co., Ltd. leverages its nationwide cold-chain infrastructure to secure shelf presence in top-tier supermarkets. Morinaga Milk Industry Co., Ltd. anchors its position through specialized lactase application R&D at its Zama facility. Yakult Honsha Co., Ltd. differentiates via probiotic-lactose-free hybrid positioning that commands loyalty among digestive-health shoppers.
Lactose-free dairy comprises milk and derivative products treated with lactase enzyme to hydrolyze lactose into glucose and galactose, yielding sweetness without added sugars while improving digestibility for lactase-deficient consumers. The hydrolysis process typically achieves 99.9% lactose reduction and requires precise temperature control during enzymatic treatment to preserve protein structure and sensory profile. Lactose-free milk dominates volume throughput across Japanese retail channels due to its substitution parity with conventional milk in cooking and beverage applications. Lactose-free yogurt captures accelerating interest among health-conscious consumers seeking dual-function digestive benefits. Powder formats sustain niche traction in institutional and export-oriented production lines where extended shelf stability reduces logistics complexity.
METI enforces clear allergen and process-labeling rules that compel manufacturers to declare enzymatic treatment methods, while the Consumer Affairs Agency monitors health claim substantiation on functional dairy packaging. JAS organic certification and regional prefectural quality marks create layered compliance thresholds that filter market entrants and elevate production costs for smaller processors. Stakeholders must track evolving F-Gas Regulation alignment for refrigeration systems and anticipate stricter carbon-footprint disclosure requirements affecting dairy supply chain investments.
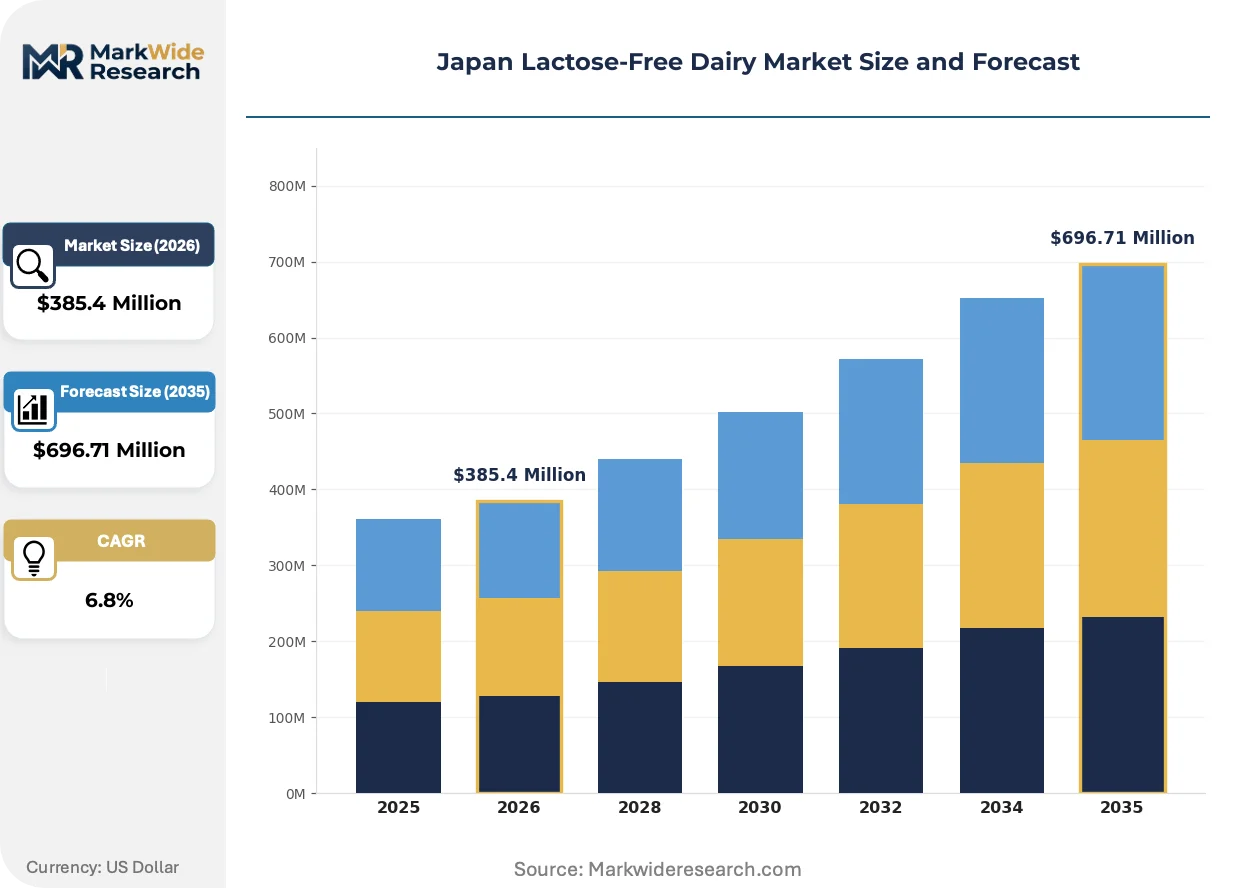
Market Dynamics
Enzymatic hydrolysis precision is reshaping competitive differentiation in Japanese lactose-free dairy, as manufacturers invest in temperature-controlled processing to preserve protein integrity while achieving near-complete lactose reduction.
Growth Catalysts
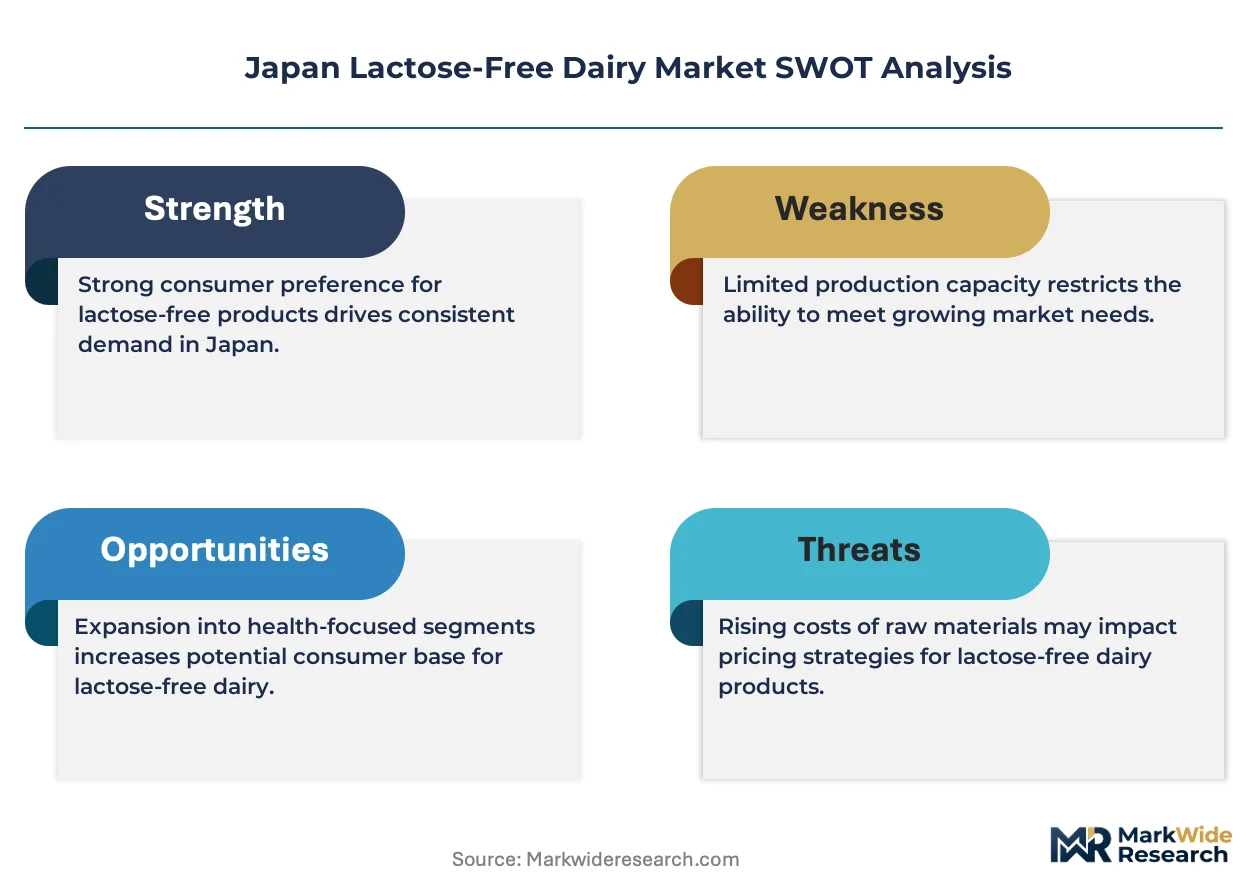
- Fitness-oriented protein demand:Athletes in Tokyo and Osaka seek digestible dairy proteins, expanding the addressable consumer base beyond lactose-intolerant populations.
- METI labeling transparency:Clear enzymatic treatment disclosure requirements build consumer trust and reduce purchase hesitation for functional dairy products.
- Dual-function positioning:Probiotic-lactose-free hybrid formulations capture digestive-health shoppers seeking consolidated nutritional solutions.
Market Restraints
- Cold-chain infrastructure costs:Nationwide refrigerated distribution requirements elevate operational expenditure for processors serving premium retail channels.
- Organic certification layering:JAS organic standards叠加 prefectural quality marks create compliance thresholds that filter smaller market entrants.
- Plant-based substitution:Oat and soy milk alternatives compete for shelf space and consumer trial among health-conscious urban demographics.
Strategic Opportunities
- Kansai corridor penetration:Osaka and Kyoto metropolitan areas show underdeveloped lactose-free yogurt distribution relative to Tokyo saturation.
- Institutional powder formats:Extended-shelf-stability products address export-oriented production lines and foodservice bulk procurement needs.
- F-Gas refrigeration alignment:Anticipated carbon-footprint disclosure requirements create first-mover advantage for processors retrofitting cold-chain assets.
Industry Challenges
- Enzyme application expertise:Precise lactase dosing and temperature protocol management require specialized technical talent scarce in regional dairy processing.
- Health claim substantiation:Consumer Affairs Agency scrutiny of functional packaging claims extends product development timelines and legal review costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Lactose-Free Dairy Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lactose-Free Milk, Lactose-Free Yogurt, Lactose-Free Cheese, Lactose-Free Ice Cream Form: Liquid, Powder, Cream, Solid Sales Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Shops Customer Type: Health-Conscious Consumers, Lactose Intolerant Individuals, Families, Athletes |
| Companies Covered | Yakult Honsha Co., Ltd., Glico Dairy Products Co., Ltd., Morinaga Milk Industry Co., Ltd., Nippon Milk Community Co., Ltd., Calpis Co., Ltd., Meiji Co., Ltd., Asahi Group Holdings, Ltd., DyDo Group Holdings, Inc., Megmilk Snow Brand Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Lactose-Free Dairy Market Trends and Innovations
Advanced enzymatic processing is compressing production timelines while preserving sensory profiles, fundamentally altering how Japanese manufacturers compete on taste parity with conventional dairy.
Membrane filtration combined with immobilized lactase systems is decomposing traditional batch-processing economics. Mid-scale dairies in Hokkaido and Kyushu adopt continuous-flow enzymatic treatment to reduce holding times and improve yield consistency. This technology is decomposing the cost advantage previously held by mass-volume processors, enabling regional players to achieve comparable efficiency at smaller scale.
METI's evolving food labeling standards now mandate granular disclosure of hydrolysis methods and residual lactose thresholds. Manufacturers must reformulate packaging and audit supply chains to maintain shelf access in top-tier retail channels. Yogurt segments face the steepest compliance burden due to dual fermentation and enzymatic process documentation requirements.
Subscription-based home delivery is fragmenting traditional supermarket dominance for fresh lactose-free milk. Direct-to-consumer platforms in Greater Tokyo capture time-constrained professionals seeking scheduled replenishment without store visits. This channel shift concentrates initially in dense urban corridors where cold-chain logistics density supports reliable same-day or next-day fulfillment.
Japan Lactose-Free Dairy Market Segmentation
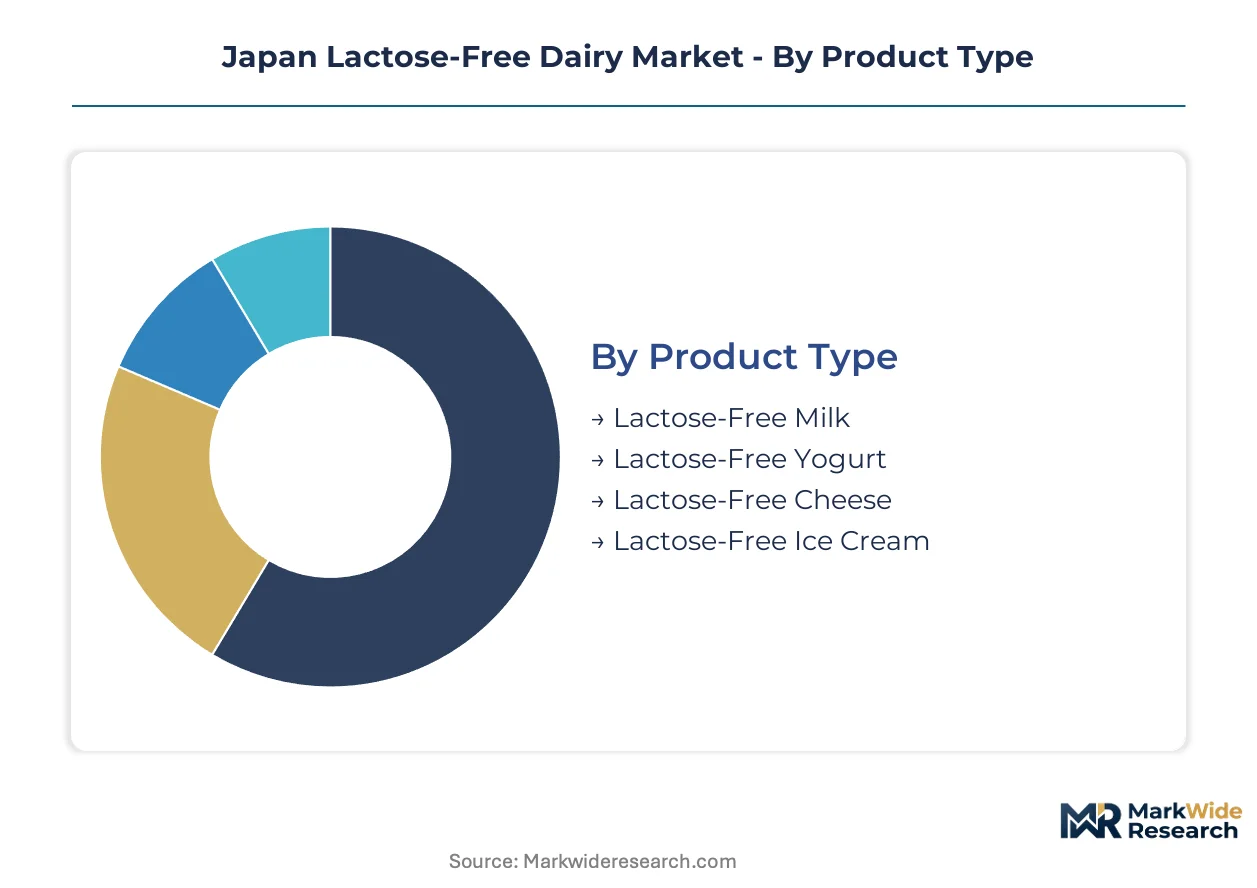
Segmentation in Japanese lactose-free dairy reveals distinct channel affinities and consumption occasions that shape formulation priorities. Manufacturers calibrate enzyme treatment intensity, packaging formats, and shelf positioning against where each segment concentrates purchase behavior.
Product Type:
Channel mix varies sharply by product format, with fluid milk dominating mainstream retail while cultured products concentrate in premium health channels.
- Lactose-Free Milk:Hydrolyzed fluid milk achieves 99.9% lactose reduction through controlled enzymatic treatment at precise temperature thresholds. Tokyo and Osaka supermarkets move the highest throughput volumes as fitness-oriented athletes and lactose-intolerant households substitute directly for conventional milk in cooking and beverage applications.
- Lactose-Free Yogurt:Dual-fermentation products combining probiotic cultures with lactase pretreatment command premium positioning in health food stores. Health-conscious consumers in urban centers seek consolidated digestive benefits, driving accelerated shelf space allocation in Greater Tokyo's specialty retail corridors.
- Lactose-Free Cheese:Enzyme-treated curd formulations maintain protein structure while eliminating residual lactose through extended aging protocols. Regional prefectural producers in Hokkaido leverage traditional dairy expertise for export-oriented powder derivatives.
- Lactose-Free Ice Cream:Ultra-filtered base mixes with hydrolyzed lactose enable clean-label sweetness without added sugars. Seasonal demand concentrates in convenience retail and online flash-sale channels during summer months.
Lactose-free milk dominates installed base. Lactose-free yogurt is where expansion concentrates.
Form:
Cost tier stratification separates premium fresh formats from economy bulk alternatives, with powder commanding institutional procurement and liquid capturing household replenishment.
- Liquid:Refrigerated cartons and PET bottles require continuous cold-chain integrity from Zama processing facilities through Tokyo metropolitan distribution. METI labeling mandates for enzymatic treatment disclosure elevate packaging compliance costs relative to powder alternatives.
- Powder:Spray-dried formulations with extended shelf stability reduce logistics complexity for export-oriented production lines and foodservice bulk procurement. Kyushu-based processors leverage lower energy costs for dehydration operations.
- Cream:High-fat hydrolyzed derivatives serve professional bakery and confectionery channels in Osaka's food manufacturing cluster.
- Solid:Compressed tablet and block formats address niche portability needs among traveling professionals and outdoor recreation segments.
Liquid formats anchor household penetration. Powder is climbing the fastest in institutional contracting.
Sales Channel:
Customer type concentration dictates channel strategy, with athlete segments over-indexing online while family households remain supermarket-anchored.
- Supermarkets:Nationwide chains in Tokyo, Osaka, and Nagoya provide the foundational volume platform for lactose-free milk replenishment. Cold-chain infrastructure investments by Meiji and Morinaga secure prime refrigerated positioning against plant-based alternatives.
- Health Food Stores:Specialty retailers in Aoyama and Shibuya curate premium yogurt and probiotic-hybrid assortments for digestive-health seekers. Knowledgeable staff consultation reduces purchase hesitation for first-time lactose-free adopters.
- Online Retailers:Subscription platforms capture time-constrained professionals in dense urban corridors through scheduled replenishment without store visits. Same-day fulfillment density in Greater Tokyo supports fresh milk logistics.
- Specialty Shops:Regional cheese mongers and organic grocers in Kyoto and Kobe serve affluent consumers seeking JAS-certified premium positioning.
Supermarkets dominate installed base. Online retailers are where expansion concentrates.
Customer Type:
Application urgency separates medical-necessity purchasers from lifestyle-optimization segments, with lactose-intolerant consumers showing price inelasticity and athletes driving premium innovation.
- Health-Conscious Consumers:Preventive wellness seekers in urban centers trial lactose-free options as part of broader dietary diversification strategies. Yogurt hybrids with probiotic positioning capture this segment's preference for multifunctional nutrition.
- Lactose Intolerant Individuals:Medically necessitated purchasers exhibit strong brand loyalty and low price sensitivity once effective products are identified. METI's clear allergen labeling reduces trial risk for this core constituency.
- Families:Multi-person households in suburban Tokyo and Osaka prioritize cooking versatility and child-friendly taste profiles in volume-format milk purchases.
- Athletes:Protein-focused competitors in competitive cycling and marathon communities seek rapidly digestible dairy for post-training recovery. Specialized sports nutrition retailers in Osaka's Umeda district serve this high-value niche.
Lactose-intolerant individuals anchor core demand. Athletes represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing capacity clusters in Hokkaido and the Kanto corridor, with enzymatic treatment facilities concentrated near metropolitan demand centers. Prefectural quality marks and cold-chain density create distinct competitive zones across the archipelago.
Kanto/Tokyo
Fitness-oriented athletes and time-constrained professionals drive lactose-free milk subscriptions in Greater Tokyo. METI labeling standards mandate enzymatic treatment disclosure on all packaged dairy. Zama processing facilities anchor production for nationwide distribution through refrigerated supermarket networks.
Kansai/Osaka
Health-conscious consumers in Osaka and Kyoto seek probiotic-lactose-free yogurt hybrids. The Consumer Affairs Agency monitors health claim substantiation on functional packaging in this premium retail corridor. Umeda district sports nutrition retailers serve protein-focused athletes with specialized dairy formulations.
Hokkaido
Traditional dairy expertise supports regional cheese production and export-oriented powder derivatives. JAS organic certification requirements filter smaller processors from premium market tiers. Sapporo-based cooperatives leverage cold-chain infrastructure for fresh milk distribution across northern prefectures.
Kyushu
Lower energy costs attract spray-dried lactose-free powder operations for institutional procurement. F-Gas Regulation alignment pressures refrigeration system retrofits in regional processing plants. Fukuoka metropolitan consumers trial subscription delivery platforms for fresh milk replenishment.
Chubu/Nagoya
Industrial foodservice demand concentrates in Nagoya's manufacturing corridor for bulk cream and bakery applications. Prefectural quality marks create layered compliance thresholds above national standards. Toyota-adjacent logistics networks support just-in-time cold-chain distribution to central Japan retail channels.
Japan Lactose-Free Dairy Market Competitive Landscape
Concentration sits with diversified dairy conglomerates possessing captive cold-chain infrastructure. Three structural tiers separate national-scale processors from regional specialists and beverage-diversified entrants. Dominant competitive moves include enzymatic R&D partnerships and refrigerated distribution capacity expansion.
Among Tokyo and Osaka-based dairy processors, Meiji Co., Ltd., Morinaga Milk Industry Co., Ltd., and Yakult Honsha Co., Ltd. occupy positions across the premium functional tier. Meiji exemplifies scale-driven cold-chain dominance through nationwide supermarket presence. Morinaga represents specialized enzymatic application expertise at dedicated R&D facilities. Yakult anchors the probiotic-lactose-free hybrid segment where digestive-health positioning commands consumer loyalty.
| Leading Market Players |
|---|
| Yakult Honsha Co., Ltd. |
| Glico Dairy Products Co., Ltd. |
| Morinaga Milk Industry Co., Ltd. |
| Nippon Milk Community Co., Ltd. |
| Calpis Co., Ltd. |
| Meiji Co., Ltd. |
| Asahi Group Holdings, Ltd. |
| DyDo Group Holdings, Inc. |
| Megmilk Snow Brand Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Scale economies at refrigerated processing facilities in Kanto and Hokkaido compress unit economics for enzyme-treated milk, concentrating supply-side power among national dairies while establishing price floors that regional entrants struggle to match. METI's labeling compliance costs and cold-chain infrastructure requirements amplify this concentration, embedding pricing power within integrated processors serving Tokyo and Osaka metropolitan corridors.
Pricing Analysis
METI's food labeling standards dictate the pricing tier structure across Japanese lactose-free dairy, with JAS organic certification commanding premium positioning above conventional enzyme-treated tiers. Three-tier pricing structure across premium certified, standard hydrolyzed, and economy private-label levels separates household replenishment from institutional procurement. Cost compression in standard fluid milk is intensifying because oat and soy alternatives compete for refrigerated shelf space in Tokyo supermarkets. Athletes in Osaka's Umeda district exhibit the lowest price sensitivity, while suburban families purchasing volume-format milk show the highest.
Supply Chain Analysis
Refrigerated inventory cycles of 7-10 days for fresh liquid formats compress lead-time tolerance and elevate spoilage risk across distribution networks. Domestic supply concentrates in Hokkaido dairy cooperatives and Kanto processing clusters, with enzyme suppliers drawing from Danish and Dutch biotechnology specialists. Lactase enzyme procurement rests on single-source vulnerability for regional processors lacking backward integration into biotechnology partnerships. Distribution runs through nationwide supermarket refrigerated networks anchored by Meiji and Morinaga captive logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward subscription-platform intermediaries in Greater Tokyo, where direct-to-consumer consolidation fragments traditional supermarket channel control and pressures processor margin capture.
For Market Incumbents: Fortify cold-chain infrastructure density in the Kansai corridor to preempt regional specialist expansion into underserved Osaka and Kyoto markets. Deepen backward integration into lactase enzyme biotechnology partnerships to reduce single-source dependency from European suppliers. METI's anticipated carbon-footprint disclosure requirements threaten margin compression for processors delaying refrigeration retrofits. For New Entrants and Emerging Players: Differentiate on probiotic-lactose-free hybrid formulations targeting digestive-health seekers in Aoyama and Shibuya specialty retail corridors. The most penetrable white-space sits in institutional powder formats for Kyushu-based foodservice and export-oriented production lines. A direct-to-consumer subscription launch in Fukuoka metropolitan areas bypasses incumbent supermarket shelf dominance. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional processors with continuous-flow enzymatic treatment capabilities that match national-scale efficiency at smaller volume. Long-term viability over the next decade hinges on F-Gas Regulation alignment and carbon-disclosure readiness rather than raw scale. The signal to watch is METI enforcement timing on residual lactose threshold verification.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic R&D Partnership | Specialized lactase application expertise at Zama-equivalent facilities reduces treatment cost curves. |
| Cold-Chain Capacity Expansion | Refrigerated distribution investments in Kansai corridor capture underdeveloped Osaka yogurt penetration. |
| JAS Organic Certification | Prefectural quality mark layering filters smaller competitors from premium retail shelf allocation. |
| Subscription Platform Launch | Direct-to-consumer density in Greater Tokyo fragments traditional supermarket replenishment dominance. |
| F-Gas Refrigeration Retrofit | Anticipated carbon-footprint disclosure rules create first-mover advantage in METI compliance. |
Research Methodology
Operator-level perspectives from dairy processing executives, cold-chain logistics managers, supermarket category buyers, and enzymatic application specialists anchored the qualitative base for this study. Primary interviews combined with secondary validation from METI regulatory filings, Consumer Affairs Agency health claim databases, JAS organic certification records, and refrigerated distribution customs data. Bottom-up volume modeling and top-down market sizing triangulation cross-checked segment-level assumptions.
Sensitivity analysis across enzyme cost volatility, cold-chain infrastructure investment timing, and plant-based substitution rates tested forecast robustness throughout the projection horizon. Segmentation dimensions modeled include product type, form factor, sales channel, and customer archetype alongside prefectural regulatory cluster variations. CAGRs derived from historical trajectory analysis and category penetration elasticity curves, with inputs from lactose intolerance prevalence demographics and fitness-oriented protein demand indices.
Material uncertainties — regulatory enforcement timing on carbon-footprint disclosure, enzyme supplier consolidation, and oat milk substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Sugar Free Food and Beverage Market
Food Intolerance Products
Brazil Gluten-Free Food and Beverages Market
Food Intolerance Products
Asia-Pacific Gluten-Free Breakfast Cereals Market
Food Intolerance Products
United States Gluten Free Foods and Beverages Market
Food Intolerance Products
Germany Gluten-Free Foods and Beverages Market
Food Intolerance Products
Gluten Free Products Market
Food Intolerance Products
Gluten-Free Popcorn Products Market
Food Intolerance Products
France Gluten-Free Food and Beverage Market
Food Intolerance Products
India Gluten-Free Food and Beverage Market
Food Intolerance Products
Lactose Free Products Market
Food Intolerance Products
Japan Gluten-Free Food and Beverages Market
Food Intolerance Products
Global Gluten Free Prepared Foods Market
Food Intolerance Products
Gluten Free Food Market
Food Intolerance Products
Global Lactose Intolerance Treatment Market
Food Intolerance Products
Gluten-Free Soup Market
Food Intolerance Products
Lactose-Free Food Market