
 Walnut Milk Market | 2026-2036
Walnut Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Walnut Milk Market Analysis
California's walnut processor cooperatives is rebalancing raw nut allocation toward beverage-grade supply as dairy alternatives command higher margins. Califia Farms leverages its Los Angeles production base to anchor West Coast distribution density. Elmhurst 1925 specializes in hydroponic extraction methods that sustain cleaner ingredient labels. Mengniu Dairy competes through its Shandong facility's scale advantages in Asian markets.
Walnut milk is an aqueous emulsion produced by milling shelled walnuts with water, typically containing 2-4% fat and 1-2% protein, then homogenizing and pasteurizing for shelf stability; it serves as a lactose-free, omega-3-rich alternative to dairy and other plant milks in beverage and culinary applications. Unsweetened formulations dominate household purchases where sugar reduction drives selection, while flavored variants capture cafe menu placements as signature offerings. Online Retailers represent the fastest-growing distribution channel as direct-to-subscription models bypass traditional grocery slotting fees.
The FDA governs allergen labeling for tree nut beverages under FALCPA, while USDA Organic certification shapes premium tier access and pricing power. China's SAMR enforces GB standards on plant protein drinks that constrain imported formulation consistency. Stakeholders must monitor evolving protein fortification rules and carbon disclosure mandates that will reshape supplier qualification criteria.
Market Dynamics
Processor cooperatives in California's Central Valley are redirecting raw walnut supply from bulk commodity channels toward beverage-grade specifications, compressing ingredient sourcing timelines for dairy-alternative formulators.
Growth Catalysts
- EU Farm to Fork Strategy:Mandatory sustainability disclosure requirements on plant-based beverages are accelerating certified organic production investments across European processing facilities.
- Specialty coffee chains:Premium menu positioning of walnut milk as a signature alternative is pulling volume through foodservice channels ahead of retail penetration.
- Hydroponic extraction methods:Cleaner-label processing technologies are reducing additive dependency and expanding clean-ingredient claim eligibility.
Market Restraints
- Input cost volatility:California drought cycles and water allocation disputes create raw nut price instability that compresses processor margins.
- Supply concentration risk:Over 80% of global walnut supply originates from California's Central Valley, creating single-point vulnerability to climate events.
- Regulatory friction:China's SAMR enforces GB standards on plant protein drinks that constrain formulation consistency for imported products.
Strategic Opportunities
- Direct-to-subscription models:Online Retailers bypass traditional grocery slotting fees and capture recurring revenue through personalized flavor rotations.
- Omega-3 fortification convergence:Combination of walnut milk with marine-derived DHA technologies targets cognitive health positioning in functional beverage segments.
- Carbon disclosure mandates:Early compliance with emerging Scope 3 reporting requirements qualifies suppliers for preferred procurement lists at sustainability-focused retailers.
Industry Challenges
- Homogenization engineering talent:Specialized expertise in aqueous emulsion stability for tree-nut beverages commands premium compensation and creates hiring bottlenecks.
- Allergen segregation infrastructure:FALCPA-compliant facility reconfiguration demands capital-intensive production line separation for tree-nut processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Walnut Milk Market |
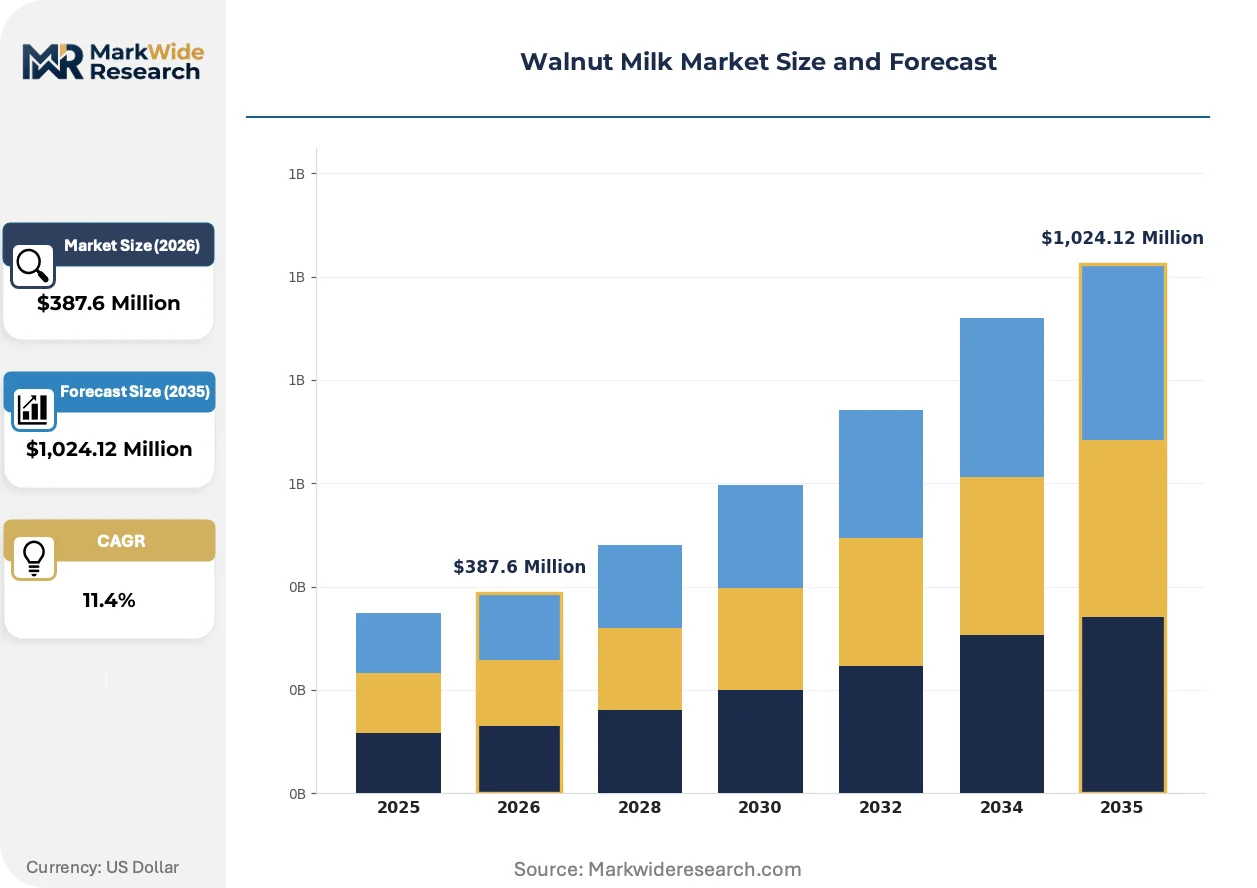
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unsweetened, Sweetened, Flavored, Organic Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Stores End User: Households, Cafes, Restaurants, Bakeries Packaging Type: Cartons, Bottles, Tetra Packs, Pouches |
| Companies Covered | Califia Farms, Chengde Lulu Co., Ltd., Elmhurst 1925, Inc., Mengniu Dairy, Inner Mongolia Yili Industrial Group Co., Ltd., Mariani Nut Company, Inc., Silk, RITA Food & Drink Co., Ltd., Hain Celestial Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Walnut Milk Market Emerging Trajectories
Formulation science and distribution architecture are converging to reshape competitive positioning, with extraction efficiency and regulatory compliance emerging as the primary axes of differentiation.
Cold-press hydroponic extraction is consolidating control over ingredient label brevity. This method eliminates enzymatic browning without chemical inhibitors. Beverage manufacturers adopting it are compressing additive counts to three or fewer ingredients. The technology is consolidating premium-tier pricing power around transparency claims.
REACH chemical safety evaluations are extending scrutiny to processing aids used in plant-milk production. The European Chemicals Agency is requiring substance-by-substance dossiers for enzymatic clarifiers. Organic-certified processors are responding by qualifying enzymatic alternatives on the Union's approved substances list.
Subscription-based replenishment is displacing conventional grocery purchasing among health-conscious households. Direct-to-consumer platforms are capturing recurring orders through personalized flavor curation and flexible delivery intervals. This shift is most visible in coastal metropolitan markets where specialty diet penetration exceeds national averages.
Walnut Milk Market Segmentation
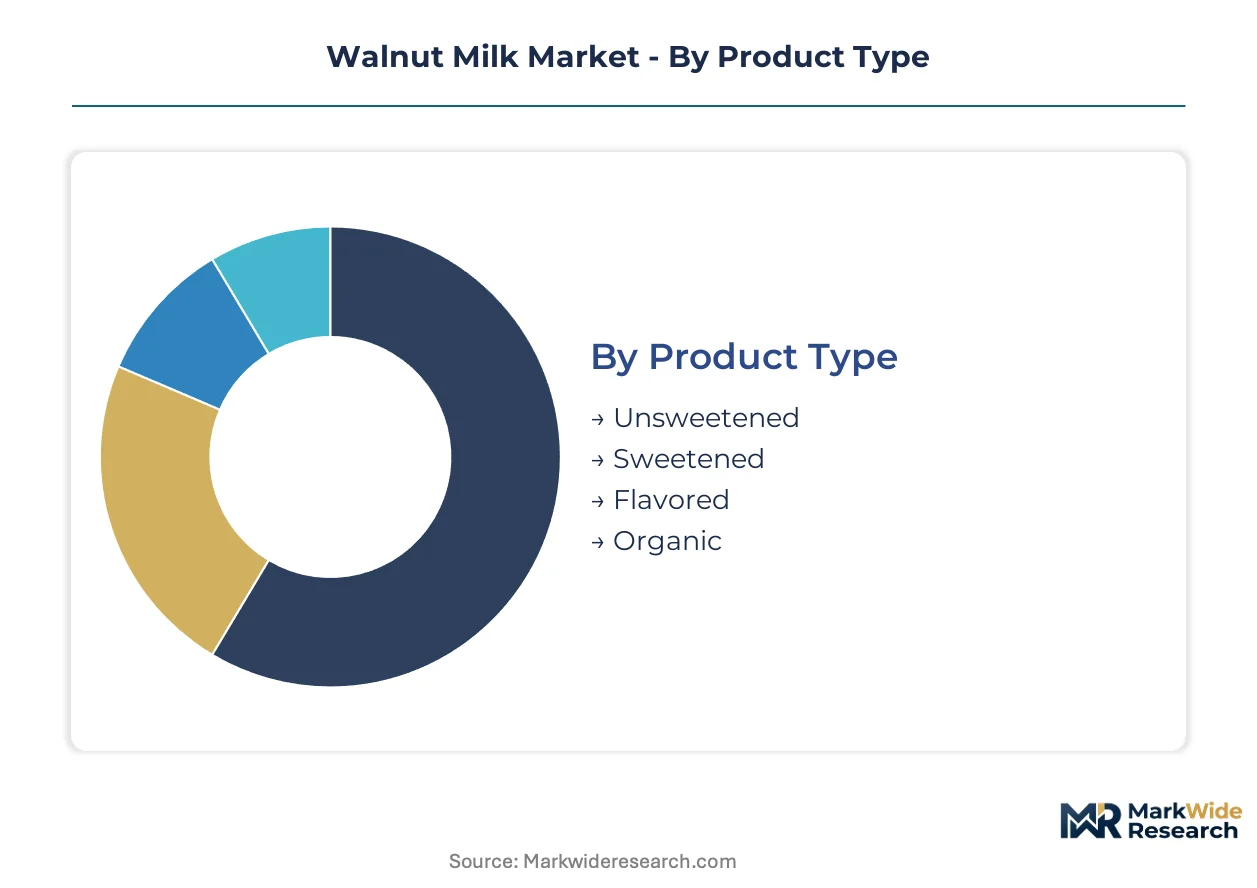
Walnut milk segmentation reflects divergent capital requirements across extraction technologies and channel infrastructure. Processor investments in beverage-grade capacity concentrate in segments where margin recovery justifies equipment specialization.
Product Type:
Capital intensity peaks in organic certification pathways, where segregated supply chains and third-party audit infrastructure demand sustained overhead commitment.
- Unsweetened:Formulations containing 2-4% walnut fat with zero added sugars, stabilized through homogenization without sweetener masking. Household purchases in California's Central Valley cluster dominate volume, driven by sugar-reduction dietary protocols among health-conscious consumers.
- Organic:USDA-certified supply chains requiring segregated handling from orchard through extraction. Premium tier pricing power accrues to processors maintaining dual organic-kosher certifications for specialty retail placement.
- Sweetened:Cane sugar or alternative sweetener additions typically targeting 8-12g sugar per serving. Cafe menu integration drives intermittent demand spikes.
- Flavored:Vanilla, chocolate, or spice infusions positioned as signature offerings. Seasonal rotation programs support subscription retention.
Most installed capacity flows through Unsweetened. Expansion is steepest in Organic.
Distribution Channel:
Channel economics separate by slotting fee exposure and working capital intensity, with direct models bypassing traditional retail gatekeeping costs.
- Online Retailers:Direct-to-subscription platforms capturing recurring revenue through personalized flavor rotations and flexible delivery intervals. Coastal metropolitan markets show highest penetration where specialty diet adoption exceeds national benchmarks.
- Supermarkets:Conventional grocery placement requiring trade spend negotiation and shelf-stable logistics at scale. Volume concentration in California and Pacific Northwest retail banners.
- Health Food Stores:Curated assortment positioning emphasizing clean-label claims and local sourcing narratives. Independent operators maintain higher margin tolerance.
- Specialty Stores:Gourmet and ethnic food retailers with limited SKU breadth. Regional clustering supports premium pricing.
Supermarkets anchor current volume. Online Retailers are gaining share fastest.
End User:
User segments diverge by purchase frequency, batch size requirements, and formulation specification tolerance.
- Households:Individual and family consumption with emphasis on refrigerated freshness dating and single-serve convenience. Unsweetened variants dominate pantry stocking behavior.
- Cafes:Specialty coffee chains featuring walnut milk as premium alternative to oat and almond. Frothability and latte art stability drive technical selection criteria.
- Restaurants:Foodservice procurement through broadline distributors with volume pricing tiers. Menu integration as dairy substitute in sauces and desserts.
- Bakeries:Ingredient-scale purchasing for recipe incorporation. Fat content consistency requirements for formulation reliability.
Cafes command highest per-unit pricing. Households show steepest expansion trajectory.
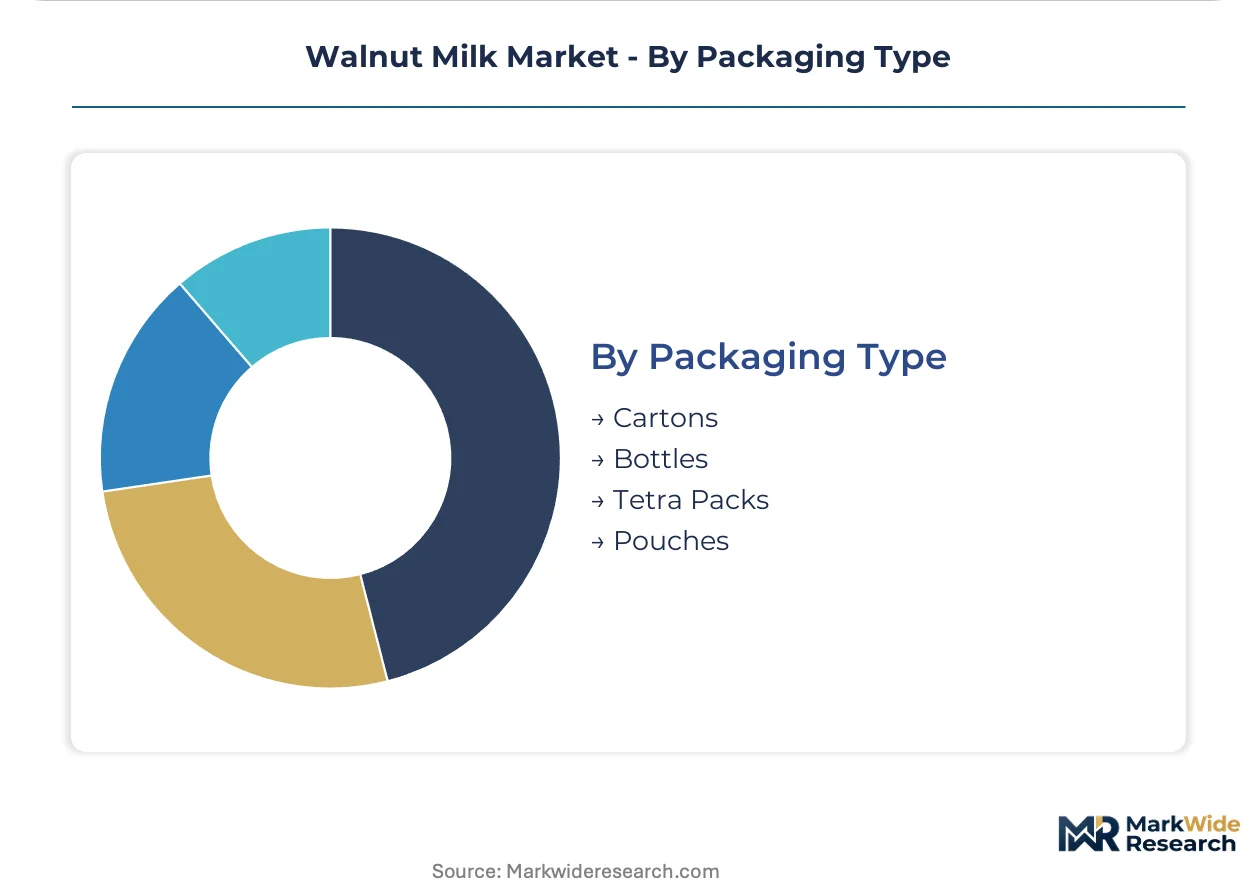
Packaging Type:
Packaging capital allocation separates by aseptic line investment requirements and shelf-life extension technology.
- Tetra Packs:Aseptic carton systems enabling ambient distribution without cold-chain dependency. European processing facilities lead adoption under EU Farm to Fork sustainability disclosure pressures.
- Cartons:Gable-top refrigerated formats with lower barrier properties and shorter dating. Standard for domestic US retail placement.
- Bottles:PET or glass containers supporting premium visual differentiation. Higher freight cost per unit limits geographic radius.
- Pouches:Flexible format targeting single-serve and on-premise consumption. Minimal material intensity aligns with carbon disclosure priorities.
Tetra Packs concentrate international shipment capacity. Pouches show most rapid adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions with streamlined organic certification pathways, as EU Farm to Fork disclosure requirements and China's GB standards create divergent cost-of-compliance environments that reshape processor location decisions.
United States
California's Central Valley dominates raw nut supply with over 80% concentration, where processor cooperatives redirect commodity-grade walnuts toward beverage specifications. The FDA enforces FALCPA allergen labeling that shapes facility segregation investments. Los Angeles anchors West Coast distribution density through integrated production-logistics hubs.
China
Shandong Province leverages scale advantages for Asian market penetration, with industrial dairy processors expanding plant-based portfolios. SAMR enforces GB standards on plant protein drinks that constrain imported formulation consistency. Qingdao and Yantai processing clusters concentrate hydroponic extraction technology deployment.
Germany
REACH chemical safety evaluations extend scrutiny to enzymatic clarifiers used in plant-milk production. The European Chemicals Agency requires substance-by-substance dossiers that elevate compliance overhead. Bavarian processing facilities lead certified organic investments under EU Green Deal sustainability disclosure pressures.
Japan
Tokyo-Osaka metropolitan corridors show highest specialty diet penetration, driving subscription-based replenishment adoption. METI oversees food labeling standards that shape clean-claim eligibility. Kansai region processors concentrate aseptic Tetra Pack capacity for ambient distribution.
Australia
Sydney and Melbourne coastal markets exceed national benchmarks for health-conscious household purchasing. The TGA regulates novel food ingredients entering plant-based beverage formulations. Victorian processing infrastructure expands to capture Asia-Pacific export demand through reduced freight radii.
Walnut Milk Market Vendor Landscape
California producers anchor one tier; Shandong-based specialists hold scale-driven positions in Asian markets. The structure bifurcates between integrated nut processors with captive supply and dairy-alternative pure-plays with formulation expertise. Three archetypes dominate: cooperative-backed verticalists, hydroponic extraction technology specialists, and diversified dairy conglomerates extending into plant-based lines. Capacity expansion and clean-label certification acquisition constitute the dominant competitive moves.
Within the technology-specialist tier, Elmhurst 1925 occupies a position exemplifying hydroponic extraction purity, while Califia Farms anchors West Coast distribution density. Mengniu Dairy represents the diversified-dairy archetype extending into plant-based portfolios through Shandong facility scale.
| Leading Market Players |
|---|
| Califia Farms |
| Chengde Lulu Co., Ltd. |
| Elmhurst 1925, Inc. |
| Mengniu Dairy |
| Inner Mongolia Yili Industrial Group Co., Ltd. |
| Mariani Nut Company, Inc. |
| Silk |
| RITA Food & Drink Co., Ltd. |
| Hain Celestial Group, Inc. |
| Others |
Supply Flow & Price Mechanics
EU Farm to Fork Strategy disclosure mandates gate qualified supply access and premium-tier pricing power for walnut milk processors, compressing margin recovery to certified organic pathways while disqualifying conventional production from sustainability-focused retail placement.
Pricing Analysis
Retailer markup layers dominate downstream economics, with specialty coffee chains absorbing higher per-unit costs for frothability-optimized formulations while subscription direct-to-consumer models bypass slotting fees entirely. Three-tier pricing structure across organic-certified premium, conventional standard, and private-label economy levels separates margin capture by certification grade and channel control depth. Pricing pressure stems from California drought-driven raw nut cost volatility compressing processor margins. Household purchasers in coastal metropolitan markets show lowest price sensitivity, while broadline foodservice procurement demonstrates highest elasticity.
Supply Chain Analysis
Reverse-logistics infrastructure for aseptic Tetra Pack returns and expired inventory refurbishment remains underdeveloped, creating working capital drag for processors managing shelf-life risk. Geographic supply concentrates in California, China, and Germany, with over 80% of raw walnut feedstock originating from California's Central Valley. Beverage-grade production draws from orchard-grade nuts, hydroponic extraction equipment, and enzymatic clarifier inputs. Single-source vulnerability to California climate events constitutes the dominant structural risk. Distribution runs through cooperative-processor verticals, Los Angeles-anchored West Coast logistics hubs, and Qingdao-Shandong export corridors for Asian market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Walnut milk functions as a regulatory compounder where EU Farm to Fork disclosure mandates and China's GB standards are accelerating certified organic capacity investments and reshaping supplier qualification criteria.
For Market Incumbents: To counter supply concentration risk from California drought cycles, deepen backward integration into Central Valley orchard assets and expand dual organic-kosher certification coverage for specialty retail placement. Secure hydroponic extraction engineering talent through premium compensation structures to maintain clean-label formulation leadership. For New Entrants and Emerging Players: Capture white-space in direct-to-subscription personalized flavor rotations targeting coastal metropolitan households with specialty diet penetration above national benchmarks. Exploit underdeveloped pouch packaging adoption for single-serve convenience and carbon disclosure alignment. Lead with marine-derived DHA fortification convergence for cognitive health positioning in functional beverage segments. For Investors and Strategic Acquirers: Roll-up economics work for hydroponic extraction technology specialists because clean-ingredient claim eligibility is consolidating premium-tier pricing power around transparency credentials. Five-to-ten year viability hinges on early Scope 3 carbon disclosure compliance qualifying suppliers for preferred procurement lists. Monitor EU REACH substance-by-substance dossier requirements for enzymatic clarifiers as inflection indicator for organic-certified processor valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Acquisition | USDA Organic and dual kosher certifications unlock specialty retail placement and premium pricing tiers. |
| Hydroponic Extraction Scale-Up | Cold-press technology deployment compresses additive counts to three ingredients and sustains clean-label claims. |
| Direct-to-Consumer Platform Launch | Subscription models bypass grocery slotting fees and capture recurring revenue through flavor curation. |
| Backward Integration into Orchards | Central Valley orchard assets hedge raw nut price volatility and secure beverage-grade supply allocation. |
| Carbon Disclosure Program | Early Scope 3 reporting compliance qualifies processors for sustainability-focused retailer preferred procurement lists. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with walnut processor cooperative managers, specialty coffee chain procurement directors, organic certification auditors, hydroponic extraction equipment engineers, and health food store category buyers with secondary validation against USDA organic certification databases, FDA FALCPA guidance documents, EU Farm to Fork Strategy implementation reports, and China SAMR GB standards filings. Bottom-up volume modeling from processor capacity installations and top-down demand triangulation from channel shipment data converged on segment-level outputs.
Segment-weighting approaches distributed value across product type, distribution channel, end user, and packaging format dimensions, with organic certification pathways and hydroponic extraction technology adoption receiving distinct analytical treatment. CAGRs were derived from installed capacity trajectories and penetration rate assumptions across the projection horizon. Forecast inputs incorporated California water allocation dispute resolution patterns, EU REACH enzymatic clarifier approval timelines, and specialty coffee chain menu integration velocity.
California drought severity, EU chemical safety evaluation acceleration, and China import formulation standard enforcement are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding certified organic supply chain scalability and hydroponic extraction equipment deployment rates. Practitioners should monitor water rights adjudication outcomes, ECHA substance dossier completion schedules, and SAMR cross-border compliance bulletins for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Organic Milk Replacers Market
Dairy Alternatives
Camel Milk Products Market
Dairy Alternatives
Asia-Pacific Walnut Milk Market
Dairy Alternatives
Dairy-Free Smoothies Market
Dairy Alternatives
Vegan Coffee Creamer Market
Dairy Alternatives
North America Non-Dairy Yogurt Market
Dairy Alternatives
Vegan Cheese Market
Dairy Alternatives
Non-Dairy Yogurt Market
Dairy Alternatives
Vegan Cheese Alternatives Market
Dairy Alternatives
Buttermilk Market
Dairy Alternatives
United States Dairy Alternatives Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
Asia-Pacific Sour Milk Drinks Market
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
Chickpea Milk Market
Dairy Alternatives
Vegan Ice Cream Market