
 Zero-Fat Protein Market | 2026-2036
Zero-Fat Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Zero-Fat Protein Market Analytics
A capital-intensity divergence between spray-drying asset owners and toll-manufacturing-dependent brands is reorganizing competitive tiers in zero-fat protein supply. Cargill Incorporated leverages backward integration into pea and soy processing to secure raw protein isolate streams at scale. Kerry Group anchors its position through flavor-mask technology leadership, which sustains palatability in sub-1% fat formulations that dominate sports nutrition contracts. Roquette Frères specializes in European pea protein extraction, occupying the premium non-GMO and allergen-free tier that commands shelf-space in German and French retail channels.
Zero-fat protein denotes protein isolates or hydrolysates with less than 0.5% fat content by dry weight, typically manufactured via alkaline extraction, isoelectric precipitation, or membrane filtration followed by spray-drying to preserve functional solubility and emulsification capacity. These ingredients serve primarily as macronutrient fortifiers in weight-management foods, clinical nutrition, and performance sports products where caloric density must be minimized without sacrificing amino acid completeness. Protein powders retain the largest revenue pool within product type segmentation, though ready-to-drink protein is expanding fastest as convenience formats displace shake-from-scratch routines among time-constrained consumers. Powder form dominates manufacturing economics due to superior shelf stability and lower logistics cost per gram of protein, while liquid form captures premium placement in refrigerated retail sets where taste freshness drives repeat purchase.
The FDA nutrition-labeling regulations and EFSA health-claims framework jointly enforce strict fat-content thresholds and substantiation standards for products marketed as "zero-fat," compelling manufacturers to invest in analytical verification and documentation systems. ISO 17025-accredited third-party testing has become a de facto market-access requirement for brands supplying Walmart, Carrefour, and Aldi corporate buying desks. Stakeholders must monitor evolving amino acid scoring methods and emerging carbon-footprint disclosure rules, as these will determine which protein sources maintain formulation priority in next-generation product development cycles.
Market Dynamics
Membrane filtration technology maturation is compressing extraction costs for zero-fat protein isolates, enabling mid-tier brands to bypass toll-manufacturing dependencies and establish captive production capabilities.
Growth Catalysts
- FDA Nutrition Labeling Modernization:The agency's tightened fat-content verification standards for "zero-fat" claims force manufacturers toward ISO 17025-accredited testing, creating demand for certified ingredient supply chains.
- Sports Nutrition Formulation Budgets:Leading athletic supplement brands now allocate dedicated R&D streams to sub-0.5% fat protein SKUs, prioritizing amino acid density over caloric load in pre-workout and recovery products.
- Pea Protein Extraction Scale-Up:European non-GMO pea processing capacity expansion in France and Germany secures allergen-free raw material streams for clinical weight-management applications.
Market Restraints
- Input Cost Volatility:Yellow pea and soy isolate feedstock prices fluctuate with North American and Black Sea region agricultural yields, compressing margin stability for non-integrated processors.
- Supply Concentration Risk:Spray-drying asset ownership clusters among a handful of Midwest US and Northern European toll operators, creating bottleneck vulnerability for brands lacking backward integration into drying infrastructure.
- Technical Palatability Ceiling:Sub-1% fat protein formulations retain residual bitterness and chalking that flavor-mask technologies have not fully neutralized, limiting repeat purchase rates in mass-market retail.
Strategic Opportunities
- China Gym Penetration Expansion:Tier-1 and Tier-2 city fitness club membership growth outpaces ready-to-drink protein availability, opening white space for localized RTD manufacturing partnerships.
- EFSA Health Claims Framework:Pending approvals for muscle-maintenance and weight-management substantiation pathways would unlock premium shelf positioning for clinically validated zero-fat protein SKUs in German and French pharmacies.
- Carbon Footprint Disclosure Convergence:Emerging ISO 14067-compliant lifecycle assessment requirements favor pea and fava bean proteins over dairy isolates, rewarding early adopters with ESG-aligned procurement contracts.
Industry Challenges
- Analytical Verification Talent Scarcity:ISO 17025-accredited fat-content testing requires specialized chromatography expertise that contract laboratories struggle to staff at scale.
- Capex Intensity for Membrane Filtration:Ceramic and polymeric ultrafiltration skids demand seven-figure capital commitments that mid-market brands must finance against uncertain volume offtake.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zero-Fat Protein Market |
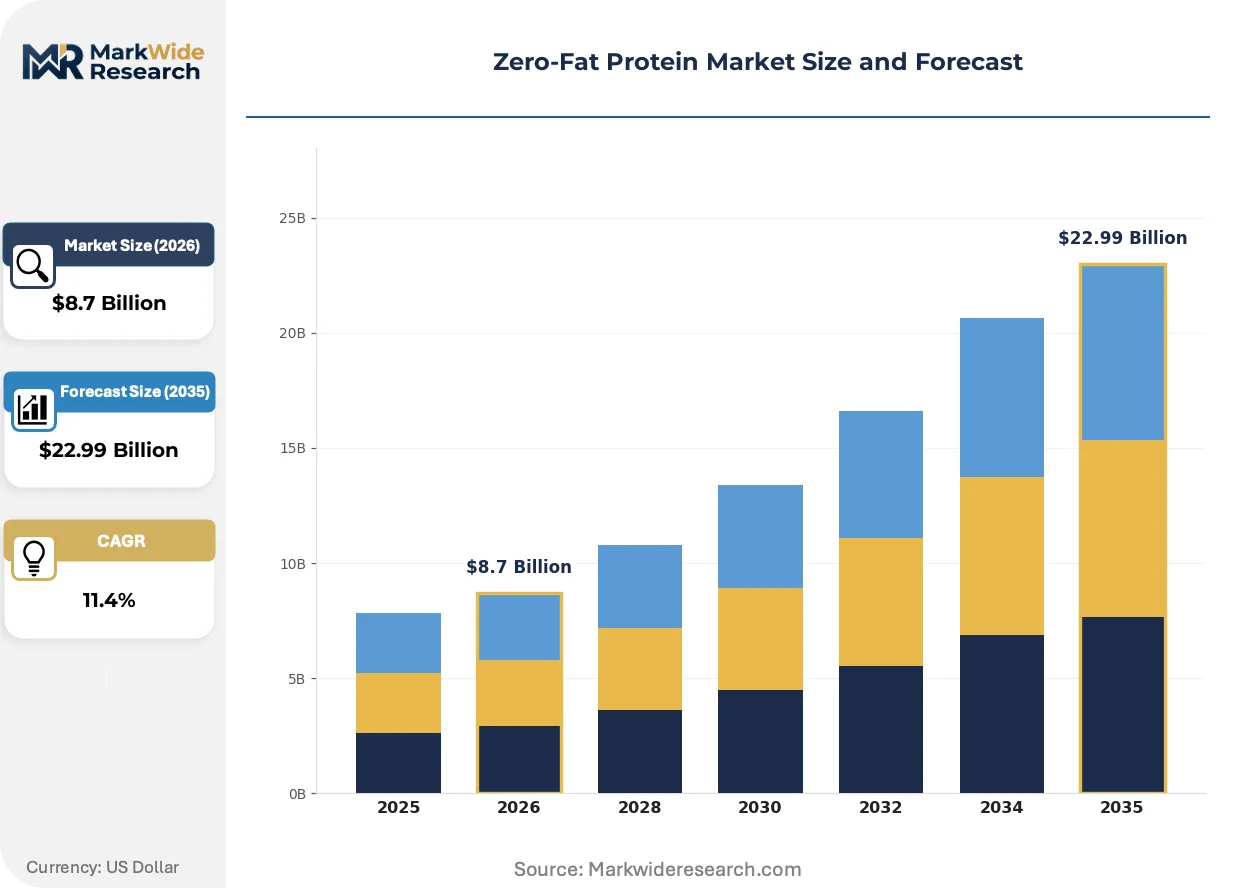
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powders, Protein Bars, Ready-to-Drink Protein, Protein Snacks Form: Liquid, Powder, Solid, Capsule Customer Type: Fitness Enthusiasts, Bodybuilders, Weight Watchers, Health-Conscious Consumers Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Health Clubs |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Kerry Group, Ingredion Incorporated, Glanbia plc, Tate & Lyle PLC, Koninklijke DSM N.V., International Flavors & Fragrances Inc., Roquette Frères, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zero-Fat Protein Market Evolving Landscape
Enzymatic hydrolysis protocols are shortening extraction cycles while preserving functional solubility, fundamentally altering the capital efficiency calculus for zero-fat protein manufacturing.
Precision enzymatic hydrolysis is displacing traditional alkaline extraction in whey and plant protein processing, cutting extraction time by half while maintaining amino acid profiles. Sports nutrition contract manufacturers in the United States and Germany are retrofitting existing spray-dry lines to accommodate these lower-temperature processes. The technology is displacing legacy isoelectric precipitation equipment, forcing asset-heavy processors to write down alkaline-based infrastructure or exit isolate production entirely.
REACH Annex XVII restrictions on solvent residues in food-contact materials are tightening permissible limits for hexane traces in soy protein isolates, compelling European processors to accelerate aqueous extraction investments. The regulation's industrial consequence is a capacity crunch for hexane-free soy isolate supply ahead of the 2027 compliance deadline. German retail chains and Aldi's corporate buying desk are now requiring third-party solvent residue documentation, shifting procurement priority toward aqueous-extracted SKUs.
Clinical nutrition procurement teams are consolidating supplier rosters from twelve-plus vendors to three or four strategic partners, prioritizing integrated flavor-mask and certification capabilities over unit cost. Hospital and long-term care facility buyers in France and Switzerland now bundle zero-fat protein purchasing with amino acid scoring and carbon footprint data services. This concentration is most visible in German clinical nutrition, where Roquette and Kerry Group have captured multi-year sole-source contracts through bundled analytical and formulation support.
Zero-Fat Protein Market Segmentation
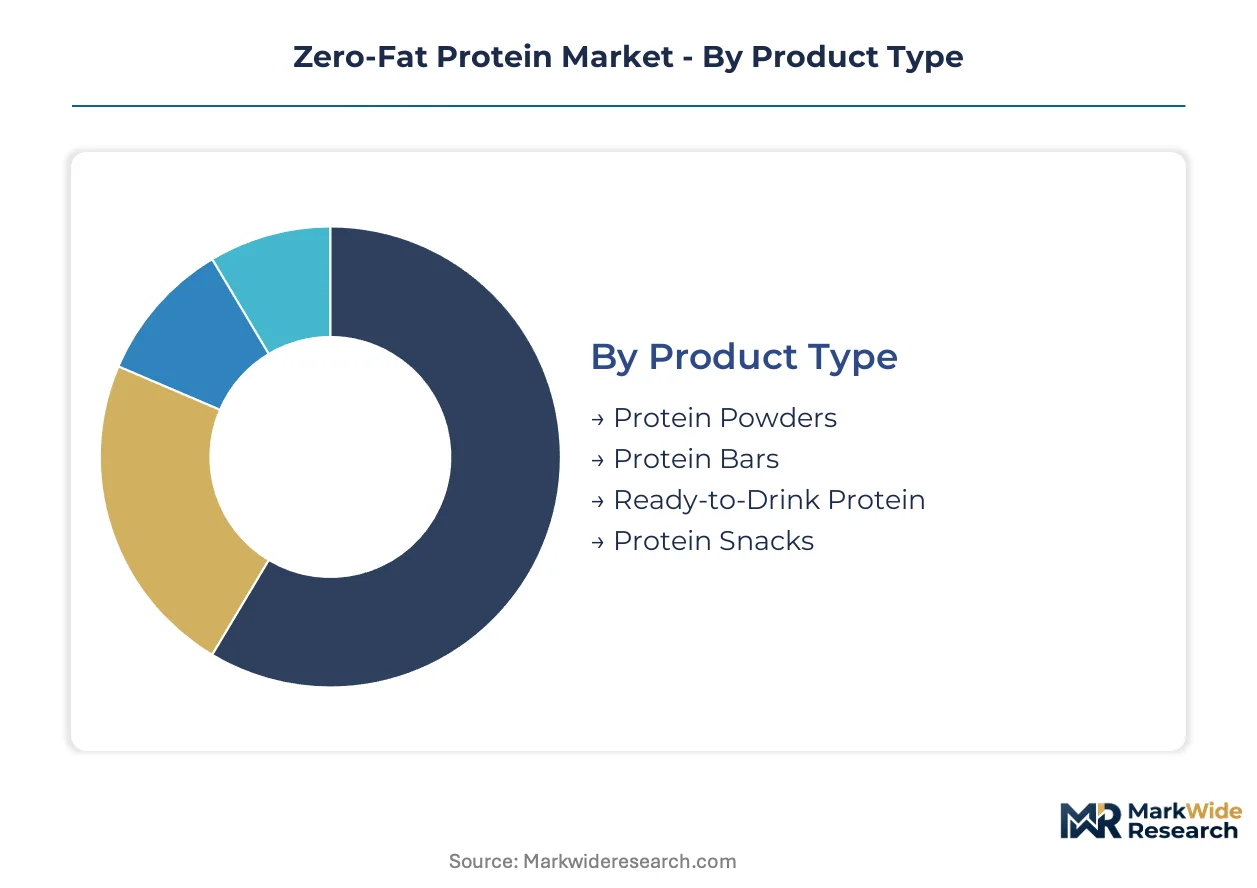
Zero-fat protein segmentation reveals divergent margin architectures across delivery formats and purchase contexts. Powder concentrates command manufacturing scale advantages, while convenience formats extract premiums through refrigerated logistics and flavor-mask investments.
Product Type:
Protein powders concentrate the largest margin pools through bulk manufacturing efficiencies and extended shelf stability, though liquid formats capture higher per-unit premiums.
- Protein Powders:Spray-dried isolates with sub-0.5% fat content dominate sports nutrition contract manufacturing. Demand clusters in United States gym chains and German clinical weight-management protocols where shake-from-scratch routines persist.
- Protein Bars:Extruded formats face technical palatability ceilings from residual bitterness in sub-1% fat formulations, limiting repeat purchase rates in mass-market retail despite convenience positioning.
- Ready-to-Drink Protein:Refrigerated RTD placement in United States and Chinese Tier-1 city fitness clubs commands premium shelf positioning as time-constrained consumers abandon powder preparation.
- Protein Snacks:Puffed and extruded savory formats occupy emerging white space in German and French pharmacy retail, though EFSA health claims substantiation remains pending for muscle-maintenance positioning.
The dominant share belongs to Protein Powders, while Ready-to-Drink Protein is closing the gap fastest.
Form:
Logistics cost per gram of protein varies dramatically across physical states, with powder formats minimizing transport expenditure and liquid formats maximizing retail placement fees.
- Liquid:Aseptic filling and cold-chain requirements restrict manufacturing to regional dairy and beverage co-packers. United States and China gym penetration expansion drives localized production partnerships.
- Powder:Superior shelf stability and lower logistics cost per gram of protein anchor manufacturing economics. Spray-drying asset ownership clusters among Midwest US and Northern European toll operators.
- Solid:Extruded bar and snack formats require binding agents that complicate sub-0.5% fat achievement, compressing margins for non-integrated processors.
- Capsule:Clinical nutrition procurement in French and Swiss hospital systems favors encapsulated amino acid delivery for precise dosing compliance.
Powder form retains volume leadership, yet Liquid form is expanding most quickly through refrigerated retail set penetration.
Customer Type:
Formulation budgets and certification requirements diver sharply between performance-oriented and clinically supervised consumption contexts.
- Fitness Enthusiasts:Time-constrained urban professionals in United States and Chinese Tier-1 cities prioritize convenience formats over amino acid density, shifting procurement toward RTD partnerships.
- Bodybuilders:Pre-workout and recovery product R&D streams prioritize amino acid completeness over caloric load, sustaining demand for isolate-dense powder formulations.
- Weight Watchers:Clinical protocols in German and French weight-management clinics require third-party fat-content verification and carbon footprint documentation.
- Health-Conscious Consumers:Mass-market retail penetration depends on flavor-mask technology neutralizing residual bitterness in sub-1% fat formulations.
Fitness Enthusiasts constitute the largest addressable base, though Bodybuilders deliver the highest per-capita formulation spend.
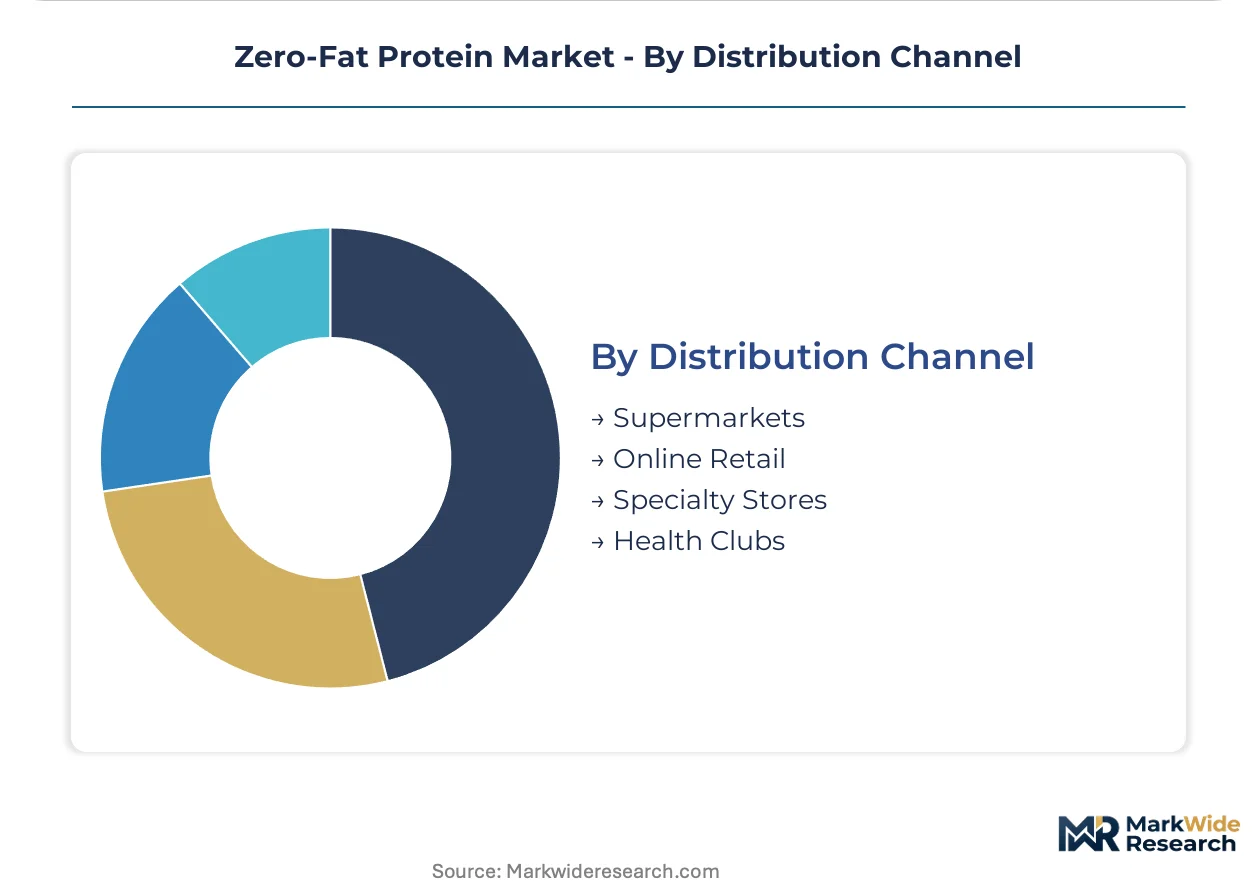
Distribution Channel:
Channel selection determines regulatory exposure and certification requirements, with corporate buying desks enforcing ISO 17025 documentation standards.
- Supermarkets:Walmart and Aldi corporate procurement mandates ISO 17025-accredited third-party testing for zero-fat claims, filtering out non-compliant suppliers.
- Online Retail:Direct-to-consumer subscription models in United States and Germany bypass shelf-space competition but require last-mile cold-chain investment for liquid formats.
- Specialty Stores:German and French pharmacy channels bundle zero-fat protein with amino acid scoring services, concentrating procurement among three to four strategic partners.
- Health Clubs:Tier-1 and Tier-2 city fitness club membership growth in China outpaces RTD availability, creating white space for localized manufacturing partnerships.
Supermarkets command the dominant volume flow, while Health Clubs are gaining share fastest through captive consumption environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and the United States, where ISO 17025 certification mandates and sports nutrition R&D budgets command premium ingredient premiums over Chinese and Brazilian markets lacking equivalent regulatory enforcement.
United States
Fitness club membership expansion in Texas and Florida drives RTD protein demand, while Walmart and Aldi procurement desks enforce FDA-aligned third-party fat-content verification. Spray-drying asset ownership clusters in Midwest toll-manufacturing corridors around Illinois and Wisconsin.
Germany
Clinical weight-management protocols in Bavaria and North Rhine-Westphalia sustain demand for EFSA-compliant health claims documentation. REACH Annex XVII solvent restrictions accelerate aqueous extraction investments in Frankfurt-Rhine-Main chemical processing zones ahead of 2027 deadlines.
China
Tier-1 city gym penetration in Shanghai and Beijing outpaces localized RTD manufacturing capacity, creating partnership opportunities for regional co-packers. SAMR nutrition-labeling enforcement tightens parallel to FDA standards, though ISO 17025 accreditation remains less prevalent among domestic suppliers.
France
Pharmacy retail consolidation in Île-de-France and Auvergne-Rhône-Alpes bundles zero-fat protein procurement with amino acid scoring services. ANSM clinical nutrition guidelines favor encapsulated formats for hospital and long-term care facility compliance.
Switzerland
Swissmedic clinical nutrition standards in Zurich and Geneva metropolitan areas prioritize carbon footprint documentation alongside fat-content verification. Roquette and Kerry Group have captured multi-year sole-source contracts through bundled analytical support in these procurement clusters.
Zero-Fat Protein Market Competitive Landscape
Concentration sits with integrated ingredient processors and flavor-technology specialists rather than commodity traders. The vendor base separates into three strategic archetypes: backward-integrated agricultural processors controlling pea and soy isolate streams, flavor-mask technology leaders sustaining palatability in sub-1% fat formulations, and toll-manufacturing-dependent brands vulnerable to spray-drying bottlenecks. Dominant competitive moves include membrane filtration capacity expansion and multi-year sole-source contracting with clinical nutrition procurement teams.
Among North American and European integrated processors, Cargill Incorporated, Kerry Group, and Roquette Frères occupy positions that exemplify divergent competitive vectors. Cargill represents the agricultural-integration archetype with captive raw protein isolate supply. Kerry Group anchors the flavor-technology tier where palatability solutions sustain sports nutrition contracts. Roquette Frères sits within the European non-GMO premium tier commanding German and French retail shelf space through allergen-free positioning.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Kerry Group |
| Ingredion Incorporated |
| Glanbia plc |
| Tate & Lyle PLC |
| Koninklijke DSM N.V. |
| International Flavors & Fragrances Inc. |
| Roquette Frères |
| Others |
Value Network & Pricing Analysis
Spray-drying asset utilization rates above 85% in Midwest US corridors anchor price floors for zero-fat protein isolates, concentrating supply power among toll operators while forcing brands toward captive membrane filtration investments to escape margin compression. Scale economies in pea protein extraction across France and Germany reinforce this dynamic, as non-integrated processors face widening cost gaps against backward-integrated agricultural processors.
Pricing Analysis
The customization-premium spread separates standard spray-dried isolates from configured-to-order formulations with bundled flavor-mask technology and ISO 17025 documentation. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with EFSA-compliant health claims documentation commanding substantial uplifts in German pharmacy channels. Cost compression in standard-tier powder formulations is intensifying because membrane filtration technology maturation enables mid-tier brands to bypass toll-manufacturing dependencies. Health-conscious consumers in mass-market retail exhibit highest price sensitivity, while clinical nutrition procurement teams in French and Swiss hospital systems prioritize bundled analytical services over unit cost.
Supply Chain Analysis
Port congestion in Rotterdam and Hamburg has elevated inbound logistics costs for European pea protein processors sourcing raw material from Black Sea region agricultural suppliers. Supply concentrates in the United States, Germany, and China, with spray-drying asset ownership clustering in Midwest US and Northern European toll corridors. Raw material dependencies center on yellow pea isolate, soy protein concentrate, and fava bean flour streams. Single-source vulnerability pervades ceramic ultrafiltration skid manufacturing, where seven-figure capital commitments tether mid-market brands to toll operators. Distribution runs through Walmart and Aldi corporate buying desks in the United States, German pharmacy retail chains, and Chinese Tier-1 city fitness club captive environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement desks as hospital systems and retail chains slash supplier rosters from twelve-plus vendors to three or four strategic partners, extracting bundled certification and analytical services as table stakes.
For Market Incumbents: Fortify membrane filtration capacity in United States Midwest corridors and German chemical processing zones to defend against toll-manufacturing bottlenecks. Deepen backward integration into pea and soy isolate streams to secure raw material cost stability against Black Sea region agricultural yield volatility. Prioritize ISO 17025-accredited fat-content verification systems to meet Walmart and Aldi corporate procurement mandates. For New Entrants and Emerging Players: RTD manufacturing service gaps in Chinese Tier-1 cities present white-space entry points where gym penetration expansion outpaces localized production capacity. Target aqueous extraction technology deployment ahead of REACH Annex XVII hexane residue compliance deadlines to capture German retail chain procurement priority. Pursue sole-source contracting with clinical nutrition procurement teams through bundled amino acid scoring and carbon footprint documentation services. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors flavor-mask technology specialists with integrated certification capabilities over commodity isolate processors. Long-term viability across the analysis window hinges on membrane filtration asset ownership and ESG-aligned procurement contract access. Watch for EFSA muscle-maintenance health claims approvals as inflection indicators for premium shelf positioning in German and French pharmacy channels.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Captive production capabilities reduce toll-manufacturing dependency and margin compression risk. |
| Backward Integration into Pea Processing | Raw isolate stream control secures cost stability against Black Sea agricultural yield volatility. |
| ISO 17025 Certification Investment | Third-party verification meets Walmart and Aldi corporate buying desk entry requirements. |
| Flavor-Mask Technology Development | Palatability solutions sustain repeat purchase rates in sub-1% fat mass-market formulations. |
| Localized RTD Manufacturing Partnership | Regional co-packer alliances capture Chinese Tier-1 city gym penetration growth ahead of supply. |
Research Methodology
A standing panel of sports nutrition formulation directors, clinical nutrition procurement managers, toll-manufacturing plant engineers, and membrane filtration technology specialists provided ongoing calibration against market developments. Primary interviews with FDA regulatory affairs consultants and EFSA health claims submission advisors combined with secondary validation from FDA nutrition-labeling guidance documents, EFSA substantiation databases, REACH Annex XVII compliance bulletins, and customs trade data for pea and soy isolate flows. Bottom-up volume modeling across product type, form, customer segment, and distribution channel triangulated against top-down value estimates derived from sports nutrition contract manufacturing disclosures.
Consistency checks validated volume and value outputs against external benchmarks including SEC filings from integrated ingredient processors, industry association capacity reports, and retail audit data from Nielsen and Circana. The analytical framework modeled growth across protein powder, RTD, bar, and snack formats by liquid versus powder versus solid versus capsule states, further segmented by fitness enthusiast, bodybuilder, weight watcher, and health-conscious consumer archetypes. CAGRs were derived from regression analysis of historical volume trajectories and forward-looking procurement budget disclosures from leading athletic supplement brands. Forecast inputs incorporated gym penetration expansion rates in Chinese Tier-1 cities and EFSA health claims approval probability assessments.
Material uncertainties — regulatory enforcement intensity variations across SAMR, FDA, and EFSA jurisdictions, membrane filtration technology adoption pace, and carbon footprint disclosure rule finalization — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained sports nutrition R&D budget allocation to sub-0.5% fat SKUs and continued clinical weight-management protocol expansion in German and French healthcare systems. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Hiking Functional Energy Bars Market
Functional Food and Beverage
Low Fat Smoothies Market
Functional Food and Beverage
Antioxidant Beverages Market
Functional Food and Beverage
Europe Health Drinks Market
Functional Food and Beverage
Asia-Pacific Functional Water Market
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
GCC Functional Food Market
Functional Food and Beverage
Asia-Pacific Phytosterols Market
Functional Food and Beverage
North America Functional Water Market
Functional Food and Beverage
Global Functional Mushrooms Market
Functional Food and Beverage
Asia-Pacific Beauty Drinks Market
Functional Food and Beverage
Flavored and Functional Water Market
Functional Food and Beverage
Global Functional Foods Market
Functional Food and Beverage
Functional Food and Beverage Market
Functional Food and Beverage
Europe Functional Water Market