
 China Lactose-Free Dairy Market | 2026-2036
China Lactose-Free Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
China Lactose-Free Dairy Market Insights
Subscription-based replenishment models for lactose-free milk is decoupling volume sales from traditional retail foot traffic. Inner Mongolia Yili Industrial Group leverages its cold-chain logistics network to dominate home-delivery channels. Mengniu Dairy Company Limited anchors its position through R&D intensity in enzymatic lactose hydrolysis technology. Nestlé S.A. competes by specializing in pediatric lactose-free formulations that command premium shelf placement.
China lactose-free dairy refers to milk and derivative products treated with beta-galactosidase enzyme to hydrolyze lactose into glucose and galactose, yielding sweetness without added sugars while maintaining protein and calcium profiles. These products serve consumers with lactase non-persistence, a condition affecting over ninety percent of Han Chinese adults, by eliminating gastrointestinal distress while preserving nutritional equivalence to conventional dairy. The milk segment leads volume due to daily consumption habits, though yogurt captures expanding margin pools through probiotic-lactose-free hybrid positioning. Online retail represents the fastest-growing distribution channel as live-streaming commerce and platform algorithms target diagnosed and self-identified lactose-intolerant shoppers. Health food stores retain niche strength among athletes seeking protein-dense, gut-friendly recovery options.
SAMR enforces GB 19645 and GB 25190 labeling standards that mandate clear lactose-free claims and prohibit misleading nutritional equivalence statements. The NHC's dietary guidelines for Chinese residents explicitly recognize lactose-free dairy as an alternative calcium source for intolerance populations, shaping hospital and clinic recommendation patterns. BIS-relevant import standards for cross-border e-commerce dairy also filter which international brands access Chinese consumers through bonded warehouse channels. Stakeholders must monitor how SAMR's evolving functional food classification rules will redraw the boundary between standard dairy and health-positioned lactose-free products.
Market Dynamics
Enzymatic lactose hydrolysis technology is redistributing competitive advantage toward cold-chain logistics operators, as freshness windows for ultra-high-temperature treated lactose-free milk compress delivery tolerances below 72 hours from production to Shanghai households.
Growth Catalysts
- NHC Dietary Guidelines:China's National Health Commission explicitly recognizes lactose-free dairy as an alternative calcium source for intolerance populations, driving hospital and clinic recommendation patterns that steer diagnosed patients toward enzymatically treated products.
- Live-streaming commerce algorithms:E-commerce platforms deploy targeted content to self-identified lactose-intolerant shoppers, collapsing discovery friction and converting awareness into replenishment subscriptions within single sessions.
- Han Chinese lactase non-persistence:Over ninety percent genetic prevalence of lactose intolerance among the majority ethnic population creates a structurally guaranteed demand base that expands with urban household formation rates.
Market Restraints
- Beta-galactosidase enzyme cost volatility:Enzyme supply concentrates among European and Japanese specialty chemical producers, exposing Chinese dairy processors to input price swings and forex risk.
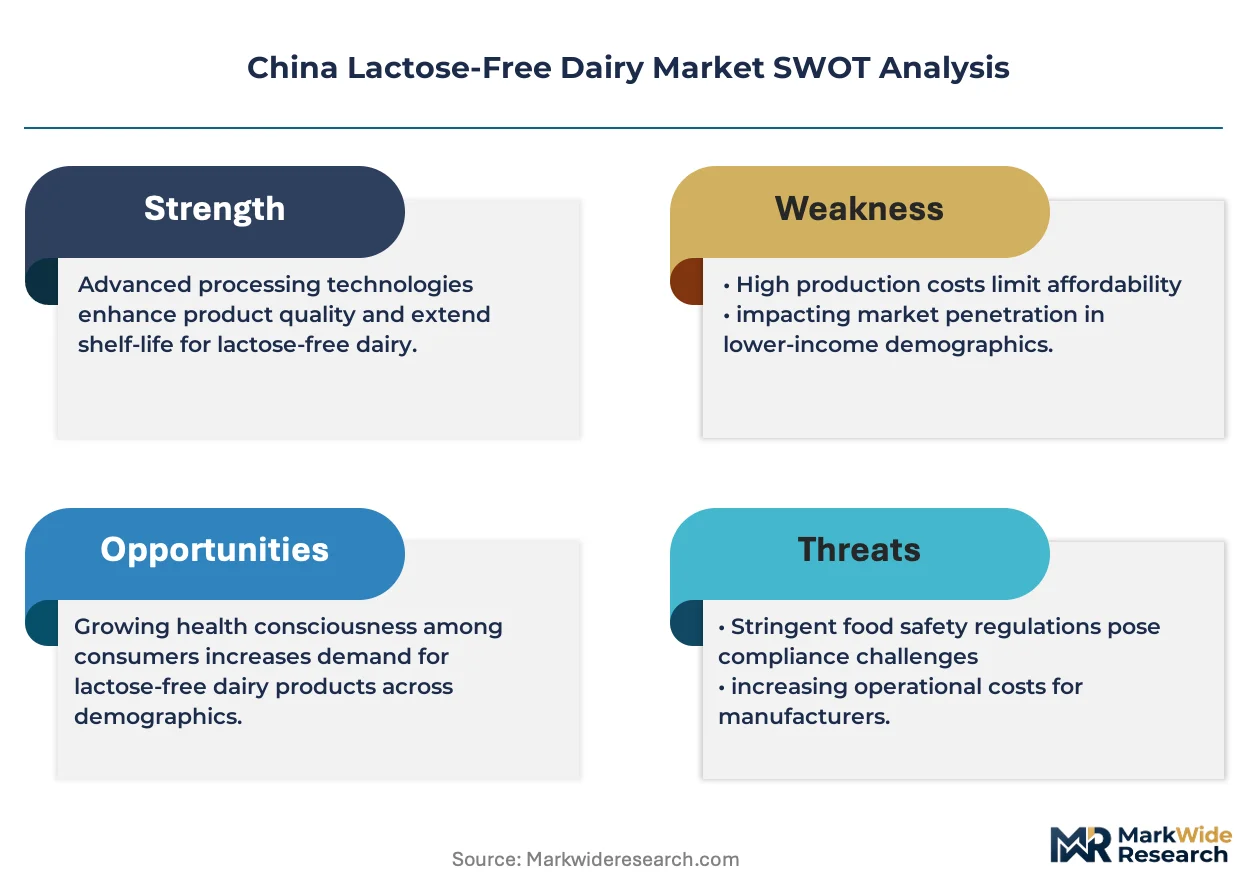
- GB 19645 labeling stricture:SAMR mandates prohibit misleading nutritional equivalence statements, constraining marketing vocabulary and forcing reformulation investments to substantiate parity claims with conventional dairy.
- Plant-based milk substitution:Oat and soy milk alternatives capture price-sensitive segments with lower unit economics, pressuring lactose-free dairy to defend premium positioning through protein density differentiation.
Strategic Opportunities
- Second-tier city underpenetration:Chengdu, Hangzhou, and Wuhan exhibit lactose-free dairy penetration rates below one-third of Shanghai levels, presenting whitespace for cold-chain network extension.
- Probiotic-lactose-free hybrid yogurt:Gut-health positioning converges enzymatic hydrolysis with live culture delivery, opening margin pools in functional dairy that commands shelf space in health food stores.
- Cross-border e-commerce bonded warehouses:BIS-relevant import standards filter international brand access, creating regulatory moats for early entrants who establish compliant supply routes through Shanghai and Guangzhou free trade zones.
Industry Challenges
- Enzyme application technician scarcity:Precision control of lactose hydrolysis degree requires specialized dairy technologists, and training pipelines lag plant capacity expansion timelines.
- GB standard revision uncertainty:SAMR's evolving functional food classification rules threaten to recategorize lactose-free products, forcing compliance system investments before regulatory clarity emerges.
- Cold-chain infrastructure capex intensity:Home-delivery channel dominance demands refrigerated fleet and warehouse investments that strain mid-tier dairy processors' balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Lactose-Free Dairy Market |
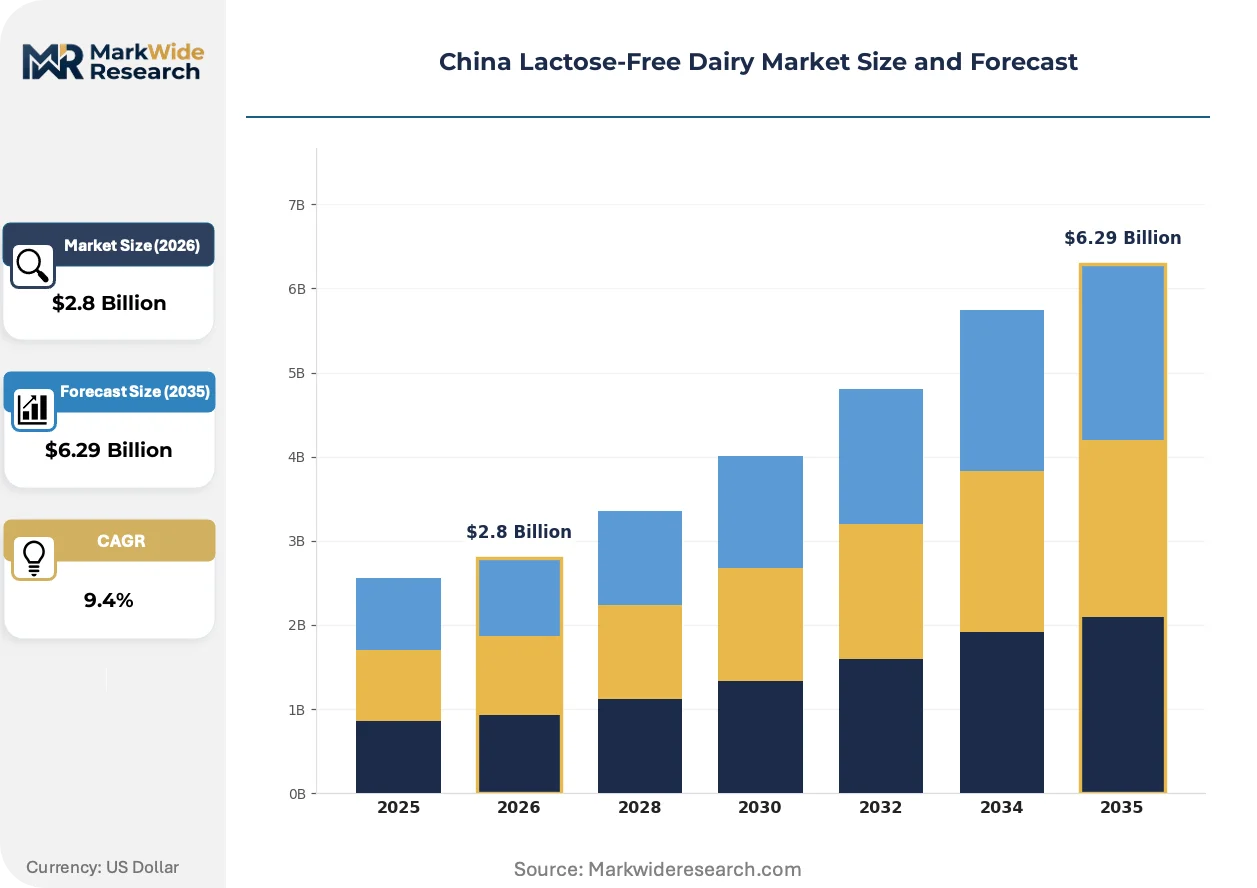
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Yogurt, Cheese, Ice Cream Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Stores End User: Health-Conscious Consumers, Children, Adults, Athletes Packaging Type: Bottles, Tetra Packs, Plastic Containers, Cartons |
| Companies Covered | Inner Mongolia Yili Industrial Group Co. Ltd, Mengniu Dairy Company Limited, Danone S.A., Hebei Yangyuan Zhihui Beverage Co. Ltd, Vitasoy International Holdings Ltd, Junlebao Dairy Group, Bright Food Group Co. Ltd, Nestlé S.A., China Modern Dairy Holdings Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Lactose-Free Dairy Market Trends and Innovations
Live-streaming commerce is collapsing the traditional retail discovery window for specialty dairy, while enzymatic process refinements and regulatory clarity efforts reshape product positioning and supply chain configuration simultaneously.
Membrane filtration technology is converging with enzymatic hydrolysis in advanced production lines, enabling processors to recover protein fractions while achieving precise lactose reduction targets. Premium yogurt manufacturers in Beijing and Guangzhou adopt these hybrid systems to shorten production cycles and reduce enzyme consumption per liter. The technology is converging with probiotic stabilization methods, creating shelf-stable formats that penetrate convenience store channels previously closed to refrigerated lactose-free products.
SAMR's enforcement of GB 25190 labeling standards tightens scrutiny on lactose-free claims and nutritional equivalence statements, forcing reformulation investments and third-party testing protocols. Dairy processors must now maintain batch-level documentation to substantiate hydrolysis completeness, raising compliance costs but also creating barriers against inferior imports. Pediatric formulations face the strictest interpretation, as SAMR coordinates with NHC to align product claims with clinical dietary guidance.
Subscription-based replenishment models displace traditional retail foot traffic for daily-consumption lactose-free milk, as urban households prioritize convenience over in-store selection. Platform algorithms identify diagnosed and self-identified intolerance shoppers, collapsing the gap between symptom awareness and first purchase. Shanghai and Beijing households lead this behavioral shift, with Guangzhou following as cold-chain reliability improves in southern provinces.
China Lactose-Free Dairy Market Segmentation
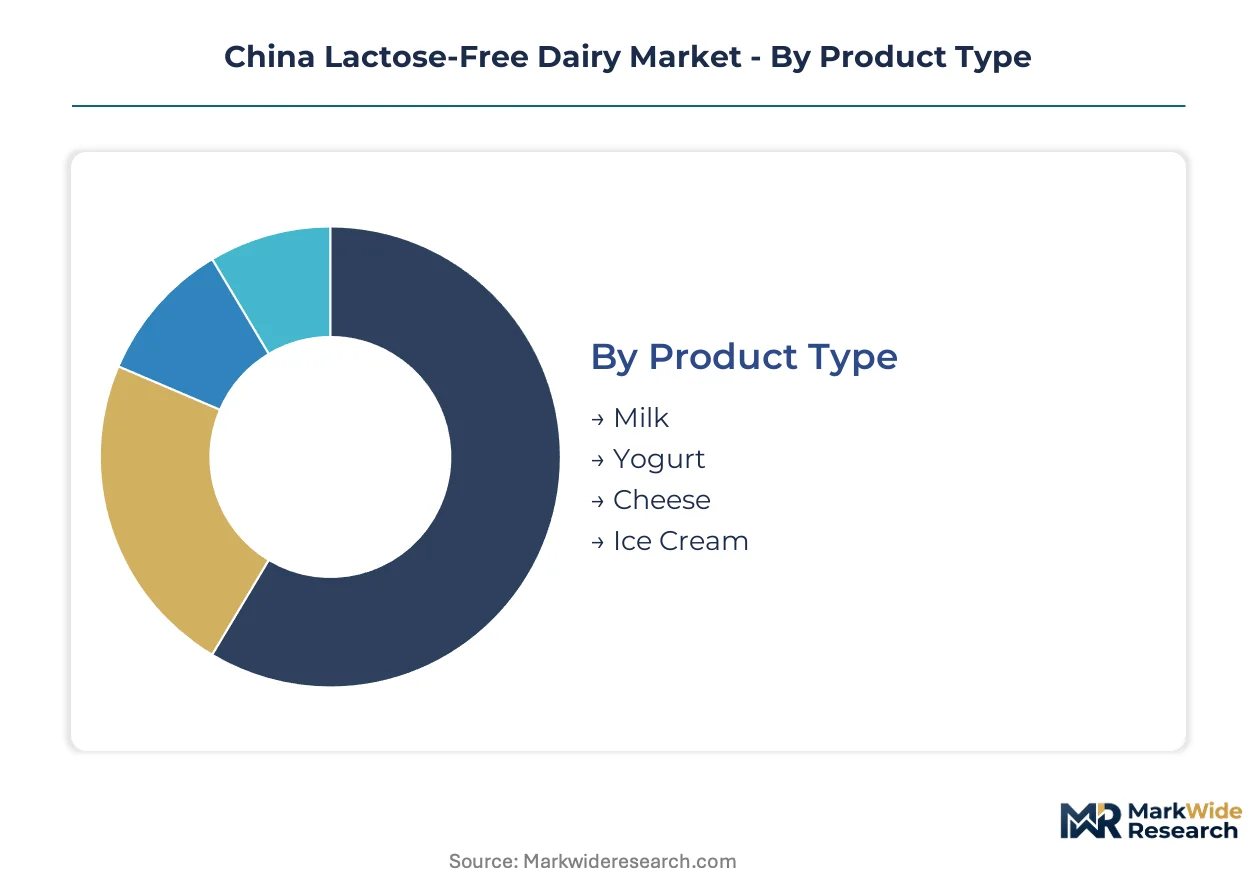
Segmentation in China's lactose-free dairy market reveals how enzymatic hydrolysis technology, cold-chain logistics maturity, and regulatory labeling requirements reshape product positioning across consumption occasions and purchase channels. Understanding these divides exposes where margin pools concentrate versus where volume scales.
Product Type:
Customization intensity spans from commodity fluid milk requiring minimal formulation variance to pediatric-targeted yogurts demanding precise probiotic strain selection and hydrolysis degree calibration.
- Milk:Fluid milk undergoes ultra-high-temperature treatment combined with beta-galactosidase enzymatic hydrolysis, converting lactose to glucose and galactose for sweetness without added sugars. Daily consumption habits in Shanghai and Beijing households drive replenishment subscription models, with freshness windows compressing below 72 hours from production to delivery.
- Yogurt:Probiotic-lactose-free hybrid formats merge enzymatic hydrolysis with live culture stabilization, commanding shelf space in health food stores and premium convenience channels. Gut-health positioning opens margin pools in functional dairy segments where protein density and digestive tolerance converge as purchase drivers.
- Cheese:Hard and soft cheese varieties utilize lactose-reduced milk bases, targeting diagnosed intolerance consumers seeking calcium-dense alternatives to conventional dairy.
- Ice Cream:Frozen dessert applications leverage hydrolyzed lactose sweetness profiles to reduce added sugar content while maintaining texture stability through cold-chain distribution.
Leading the category by volume: Milk. Expanding most quickly: Yogurt.
Distribution Channel:
Channel economics diverge sharply between asset-heavy cold-chain home delivery and traditional retail foot traffic, with platform algorithms collapsing discovery friction for diagnosed consumers.
- Supermarkets:Brick-and-mortar retail maintains visibility for first-time purchasers comparing nutritional labels, though foot traffic erodes as subscription models capture replenishment occasions.
- Online Retail:E-commerce platforms deploy live-streaming commerce and algorithmic targeting to self-identified lactose-intolerant shoppers, converting awareness into replenishment subscriptions within single sessions. Cold-chain logistics networks enable same-day or next-day delivery to urban households.
- Convenience Stores:Shelf-stable lactose-free formats penetrate 24-hour retail channels in Guangzhou and southern provinces where refrigerated infrastructure remains uneven.
- Health Food Stores:Athletes and fitness-oriented consumers seek protein-dense, gut-friendly recovery options in specialized retail environments where staff expertise guides hydrolysis completeness verification.
Volume concentrates in: Online Retail. Steepest expansion trajectory: Online Retail.
End User:
User segments stratify by symptom severity, nutritional requirement intensity, and willingness to pay premium pricing for enzymatically treated alternatives.
- Health-Conscious Consumers:Self-diagnosed intolerance drives preventive consumption patterns, with these shoppers prioritizing digestive wellness and clean-label positioning over clinical verification.
- Children:Pediatric formulations face strictest SAMR labeling interpretation, as NHC dietary guidelines explicitly recognize lactose-free dairy as alternative calcium sources for developing intolerance populations. Hospital and clinic recommendation patterns steer diagnosed patients toward enzymatically treated products.
- Adults:Han Chinese lactase non-persistence affects over ninety percent of the majority ethnic population, creating structurally guaranteed demand that expands with urban household formation rates.
- Athletes:Protein-dense, gut-friendly recovery positioning targets fitness enthusiasts in health food store channels where hydrolysis completeness and rapid absorption claims differentiate premium offerings.
Dominating by population addressable: Adults. Gaining share fastest: Children.
Packaging Type:
Packaging selection balances shelf-life extension, cold-chain thermal performance, and consumer convenience across consumption occasions from on-the-go to home pantry storage.
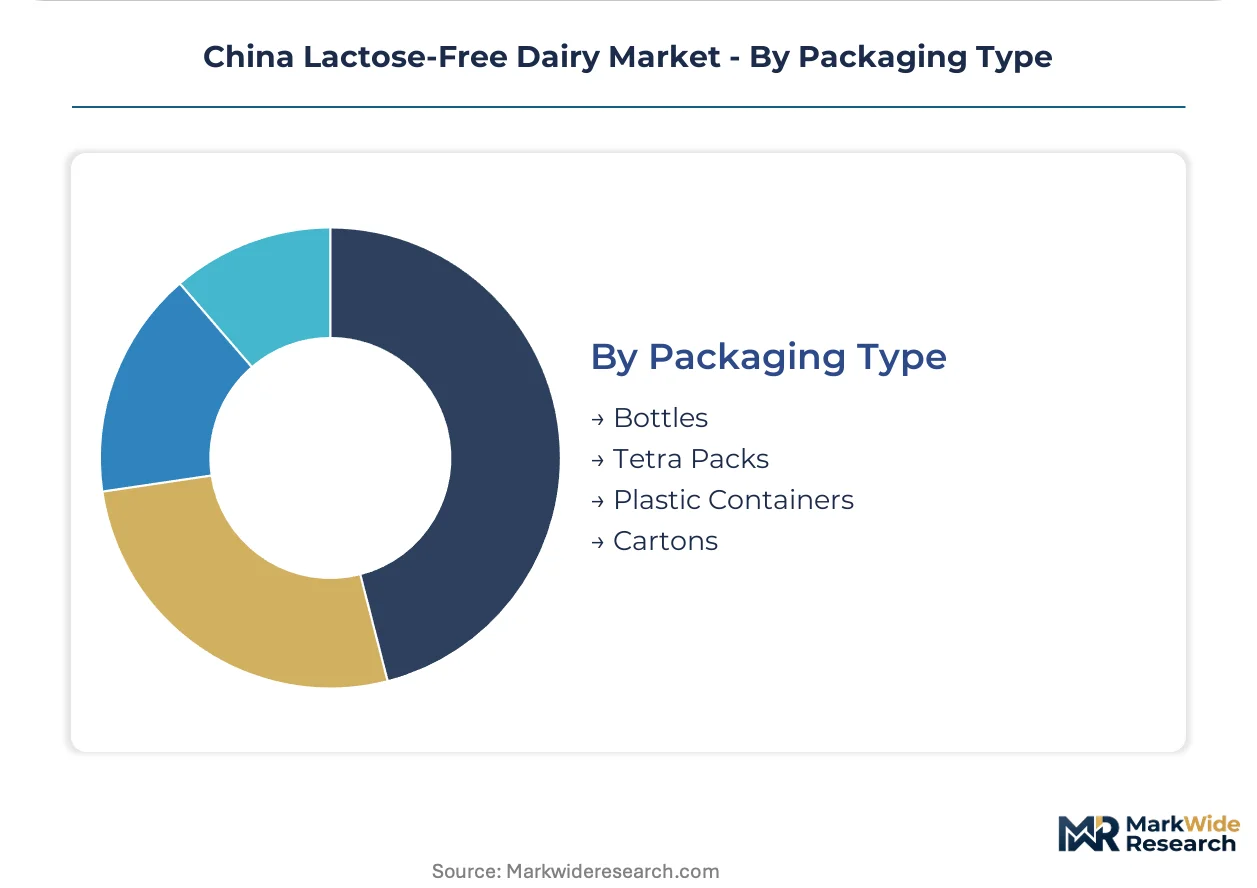
- Bottles:PET and HDPE bottles dominate home-delivery channels where reusability and recycling infrastructure align with urban household sustainability preferences.
- Tetra Packs:Aseptic carton formats enable ambient distribution for UHT-treated lactose-free milk, reducing cold-chain dependency in second-tier city expansion.
- Plastic Containers:Multi-serve tubs accommodate yogurt and soft cheese formats targeting family consumption and bulk purchasing behaviors.
- Cartons:Gable-top cartons maintain presence in traditional supermarket dairy aisles where shelf-facing competition demands recognizable conventional dairy parallels.
Primary volume carrier: Tetra Packs. Climbing the fastest: Bottles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors lactose-free dairy demand through dense urban household formation and subscription-model adoption. Cold-chain logistics networks radiate from this hub toward Beijing-Tianjin-Hebei and Pearl River Delta clusters. Provincial penetration gaps persist in western and central provinces.
Beijing-Tianjin-Hebei
Pediatric formulations and hospital recommendation patterns concentrate demand in this northern corridor. NHC dietary guidelines explicitly recognize lactose-free dairy as alternative calcium sources, steering clinic prescriptions toward enzymatically treated products. Beijing households lead subscription adoption, with Tianjin serving as a secondary logistics node for Hebei province expansion.
Shanghai-Yangtze River Delta
Live-streaming commerce algorithms target self-identified lactose-intolerant shoppers in this eastern cluster, collapsing discovery friction within single sessions. SAMR enforces GB 19645 and GB 25190 labeling standards that mandate clear lactose-free claims and prohibit misleading nutritional equivalence statements. Zhejiang and Jiangsu provinces follow Shanghai's consumption patterns as cold-chain reliability improves.
Guangdong-Pearl River Delta
Cross-border e-commerce bonded warehouses in Guangzhou and Shenzhen filter international brand access through BIS-relevant import standards. Shelf-stable formats penetrate convenience store channels where refrigerated infrastructure remains uneven across southern provinces. Hong Kong-influenced consumer preferences accelerate premium yogurt adoption with gut-health positioning.
Sichuan-Chongqing
Second-tier city underpenetration manifests in lactose-free dairy penetration rates below one-third of Shanghai levels. Provincial health commissions coordinate with NHC guidance to expand clinic recommendation networks. Chengdu serves as the western logistics hub for enzymatically treated milk distribution into surrounding provinces.
Shandong Peninsula
Dairy processing infrastructure concentrates in this northern coastal region, with Qingdao and Jinan hosting enzymatic hydrolysis production lines. GB standard revision uncertainty from SAMR threatens to recategorize lactose-free products, forcing compliance investments before regulatory clarity emerges. Local processors balance domestic supply with cross-border e-commerce export potential.
China Lactose-Free Dairy Market Competitive Landscape
Capital-heavy producers compete with asset-light designers in a structure where cold-chain logistics operators and enzymatic technology specialists occupy distinct value-capture positions. The market exhibits tiered consolidation around national dairy conglomerates with integrated distribution networks, mid-scale regional processors, and international specialty brands accessing through bonded channels. Strategic archetypes separate cold-chain dominators, enzymatic R&D specialists, and pediatric formulation premium-positioners. Competitive moves concentrate on home-delivery channel expansion and probiotic-lactose-free hybrid product development.
Among domestic dairy conglomerates, Inner Mongolia Yili Industrial Group Co. Ltd and Mengniu Dairy Company Limited occupy positions exemplifying cold-chain logistics dominance and enzymatic technology intensity respectively. Nestlé S.A. represents the international specialty archetype, anchoring pediatric formulation segments that command premium shelf placement. These three entities illustrate how scale, technology, and positioning specialization stratify competitive advantage in this market.
| Leading Market Players |
|---|
| Inner Mongolia Yili Industrial Group Co. Ltd |
| Mengniu Dairy Company Limited |
| Danone S.A. |
| Hebei Yangyuan Zhihui Beverage Co. Ltd |
| Vitasoy International Holdings Ltd |
| Junlebao Dairy Group |
| Bright Food Group Co. Ltd |
| Nestlé S.A. |
| China Modern Dairy Holdings Limited |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals gate qualified supply access and premium-tier pricing power, forcing processors to invest in renewable-powered cold-chain infrastructure before earning shelf placement in Shanghai and Beijing subscription channels. Buyers without verified low-carbon enzymatic production lines face exclusion from pediatric formulation segments where SAMR labeling scrutiny converges with parental willingness to pay.
Pricing Analysis
Outcome-based pricing anchors pediatric lactose-free formulations, where hydrolysis completeness certificates and NHC dietary guideline alignment command per-unit premiums over standard fluid milk. Three-tier pricing structure across premium, standard, and economy levels separates probiotic-hybrid yogurts from commodity UHT milk and private-label alternatives. Cost compression in economy tiers is intensifying because plant-based oat and soy milk alternatives capture price-sensitive households. Health-conscious urban adults exhibit lowest price sensitivity, while provincial families in second-tier cities prioritize unit economics over enzymatic certification.
Supply Chain Analysis
Regional distribution centers in Shanghai and Beijing anchor hub-and-spoke patterns radiating toward Guangzhou and Chengdu, with freshness windows below 72 hours dictating warehouse placement. Beta-galactosidase enzyme supply concentrates in Germany, Japan, and Denmark, exposing Chinese processors to forex volatility and single-source vulnerability from European specialty chemical producers. Distribution runs through bonded warehouses in Guangzhou and Shenzhen for cross-border e-commerce, filtering international brand access through BIS-relevant import standards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: cold-chain technician scarcity props pricing power for incumbents with certified training pipelines, while enzyme import dependency limits rapid capacity scaling.
For Market Incumbents: Extend cold-chain logistics networks into Chengdu, Hangzhou, and Wuhan before mid-tier processors secure regional distribution partnerships, locking out competitors through freshness-window advantages. Backward integration into beta-galactosidase enzyme sourcing—through joint ventures with European or Japanese specialty chemical producers—reduces forex exposure and secures input cost stability against supply volatility. For New Entrants and Emerging Players: Live-streaming commerce channels offer the lowest customer acquisition cost for self-diagnosed lactose-intolerant shoppers in second-tier cities, collapsing discovery friction without brick-and-mortar capex. Target pediatric formulations in Beijing-Tianjin-Hebei, where hospital recommendation patterns and NHC dietary guideline alignment create referral-driven demand with lower marketing spend than consumer education in saturated Shanghai. For Investors and Strategic Acquirers: SAMR's publication of revised GB functional food classification rules is the leading indicator that regulatory clarity will trigger consolidation, rewarding early positions in compliant processors. Mid-scale regional dairies with enzymatic hydrolysis certifications and established cross-border e-commerce bonded warehouse access represent prime acquisition archetypes. Watch for cold-chain infrastructure capex announcements from Inner Mongolia and Shandong processors as signals of capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Network Extension | Inner Mongolia Yili's refrigerated fleet expansion into Sichuan secures freshness-window dominance in underpenetrated western provinces. |
| Enzymatic R&D Partnership | Mengniu's beta-galactosidase process refinements reduce enzyme consumption per liter, improving margin capture in fluid milk. |
| Pediatric Formulation Certification | Nestlé's SAMR-aligned labeling investments capture premium shelf placement through hospital and clinic recommendation networks. |
| Cross-Border E-Commerce Bonded Warehouse Establishment | Guangzhou free trade zone infrastructure filters international brand access, creating regulatory moats for early entrants. |
| Probiotic-Lactose-Free Hybrid Launch | Beijing and Guangzhou manufacturers merge enzymatic hydrolysis with live culture stabilization, opening health food store margin pools. |
Research Methodology
Multi-period observation of enzymatic hydrolysis patent filings, cold-chain logistics capex disclosures, and SAMR regulatory publication timelines anchored the trend analysis, supplemented by interviews with dairy processing technologists, pediatric nutritionists at Beijing and Shanghai hospitals, e-commerce platform category managers, and cold-chain logistics operators. Secondary validation drew from SAMR GB standard revision notices, NHC dietary guideline publications, China Customs import data, and dairy processor SEC filings. Bottom-up volume modeling across product segments triangulated against top-down market sizing from macro consumption trends.
Segment-weighting approaches distributed value across milk, yogurt, cheese, and ice cream categories according to enzymatic treatment intensity, cold-chain dependency, and distribution channel margin structures. Modeled dimensions included product type, distribution channel, end-user segment, and packaging format across the projection horizon. CAGRs were derived from urban household formation rates, diagnosed lactose intolerance prevalence, and subscription-model adoption curves. Forecast inputs incorporated enzyme cost volatility indices and cold-chain infrastructure investment pipelines.
Inputs from SAMR regulatory filings and NHC guideline publications were available through the study window; gaps in real-time cold-chain fleet utilization data introduce uncertainty bands around second-tier city penetration assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
United States Casein and Caseinate Market
Dairy Products
Organic Milk Powder Market
Dairy Products
Savory Dairy Products Market
Dairy Products
Non-Fat Milk Market
Dairy Products
Mozzarella Cheese Market
Dairy Products
Dairy Blends Market
Dairy Products
Europe Dairy Based Beverages Market
Dairy Products
Condensed Milk Market
Dairy Products
United States Camel Dairy Market
Dairy Products
South America Yogurt Market
Dairy Products
Fat-Rich Dairy Products Market
Dairy Products
Cheddar Cheese Market
Dairy Products
Kefir Market
Dairy Products
Condensed Whey Market
Dairy Products
Processed Cheese Market
Dairy Products
Europe Drinkable Yogurt Market