
 United Kingdom Dairy Alternatives Market | 2026-2036
United Kingdom Dairy Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Dairy Alternatives Market Insights
Precision fermentation is narrowing the cost gap between dairy proteins and their plant-based counterparts, forcing incumbent reformulation strategies. Oatly Group AB leverages its vertically integrated malting infrastructure to secure raw material consistency across Nordic and British supply lines. Alpro sustains dominant shelf presence through deep partnerships with Tesco, Sainsbury's, and Waitrose. Arla Foods amba navigates its dual portfolio by positioning its JÖRĐ brand distinctly from conventional dairy operations.
United Kingdom dairy alternatives comprise formulated beverages and food products derived from legumes, cereals, nuts, or seeds, processed through enzymatic hydrolysis, homogenization, and ultra-high temperature treatment to achieve functional parity with cow's milk in foaming, emulsification, and nutritional profiles. These products serve industrial food manufacturing, foodservice preparation, and direct retail consumption where lactose intolerance, vegan dietary patterns, or environmental motivations drive substitution. Oat milk leads volume share due to superior barista functionality and lower water intensity than almond cultivation. Tetra Pak packaging dominates ambient distribution channels, though glass jar formats command premium positioning in specialty retail. Online retail captures the fastest growth trajectory as subscription models and direct-to-consumer platforms reduce intermediary costs for emerging brands.
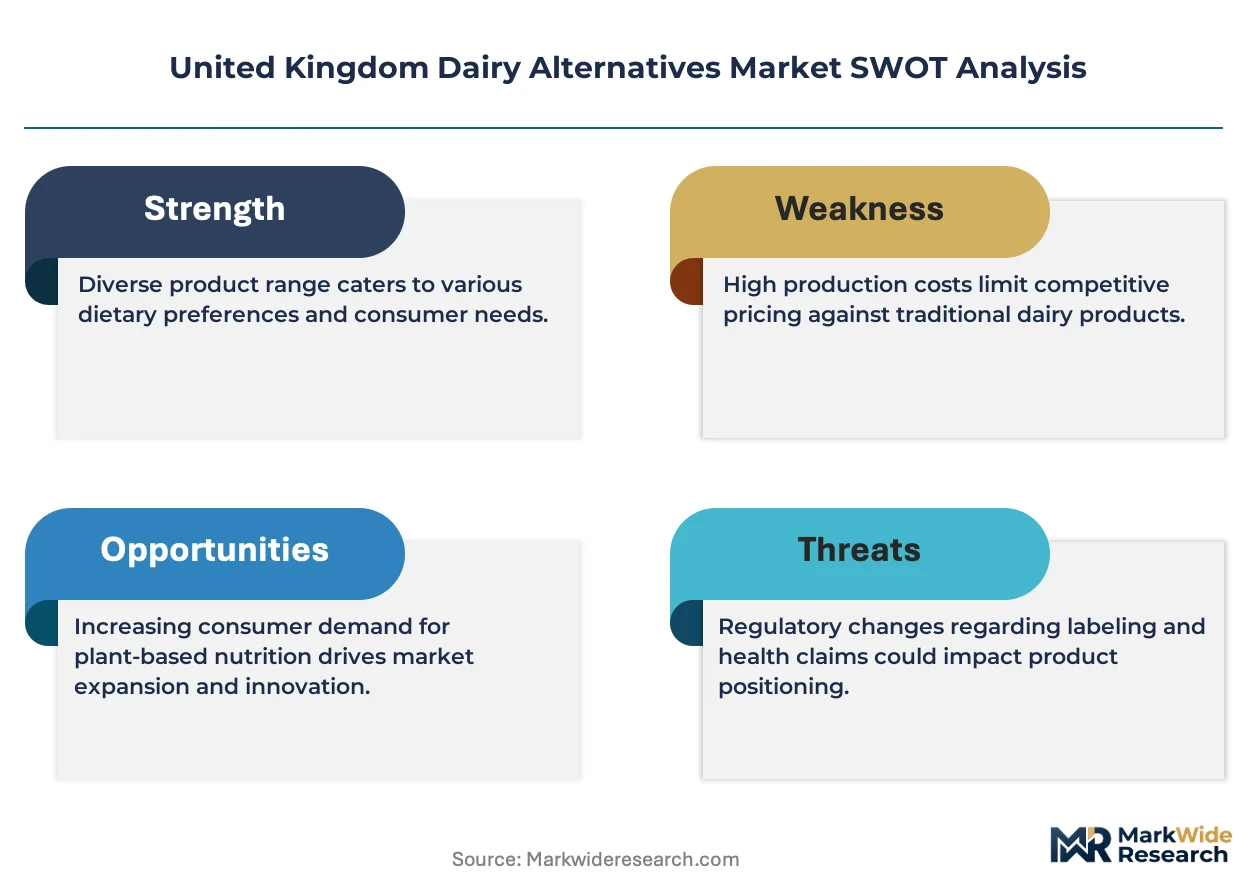
UK Food Standards Agency mandates govern novel protein safety assessments, while Trading Standards enforce compositional standards preventing misleading dairy nomenclature on plant-based labels. EU-derived retained law, including allergen labelling requirements, continues shaping reformulation decisions despite post-Brexit regulatory divergence discussions. The Advertising Standards Authority polices environmental claims, constraining how brands communicate carbon footprint advantages. Stakeholders must monitor whether precision fermentation-derived ingredients trigger novel food consultations, as regulatory classification will determine speed-to-market for next-generation products.
Market Dynamics
Precision fermentation is compressing protein production economics and forcing incumbent plant-based brands to accelerate reformulation cycles or cede barista-grade positioning to lab-cultured alternatives.
Growth Catalysts
- Trading Standards compositional enforcement:The UK's tightened dairy nomenclature rules prevent misleading plant-based labeling, building consumer trust in certified alternatives and reducing purchase hesitation at retail.
- Foodservice oat milk penetration:British café chains now specify oat-based barista blends as default milk options, normalizing premium pricing and expanding habitual consumption beyond home use.
- Greater London urban density:Concentrated populations of lactose-intolerant and environmentally motivated consumers in the capital generate repeat purchase velocity that subsidizes national distribution infrastructure.
Market Restraints
- Oat raw material concentration:Nordic malting infrastructure dominates supply, exposing UK formulators to currency volatility and shipping disruptions across the North Sea corridor.
- Almond water intensity:California drought cycles inflate input costs and attract sustainability scrutiny from the Advertising Standards Authority, constraining brand messaging flexibility.
- Novel food consultation timelines:UK Food Standards Agency safety assessments for precision fermentation proteins extend 18-24 months, delaying next-generation product launches against faster-moving competitors.
Strategic Opportunities
- South East commuter corridor:Rail-linked towns between London and Brighton show underpenetrated convenience retail coverage for ambient long-life formats.
- Subscription direct-to-consumer:Emerging brands bypass Tesco and Sainsbury's slotting fees through refrigerated delivery models, capturing full margin and customer data.
- EU-derived retained law divergence:Post-Brexit regulatory flexibility may permit faster approval pathways for enzymatic processing innovations than remain available in continental markets.
Industry Challenges
- Food technologist scarcity:Formulation expertise spanning enzymatic hydrolysis and UHT stability commands premium salaries, constraining mid-tier brand R&D bandwidth.
- Tetra Pak format lock-in:Ambient distribution infrastructure requires capital-intensive aseptic filling lines that disadvantage glass jar entrants seeking premium positioning.
- Allergen cross-contamination protocols:FSA-mandated separation procedures for nut and cereal processing lines extend facility certification timelines and inflate manufacturing overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Dairy Alternatives Market |
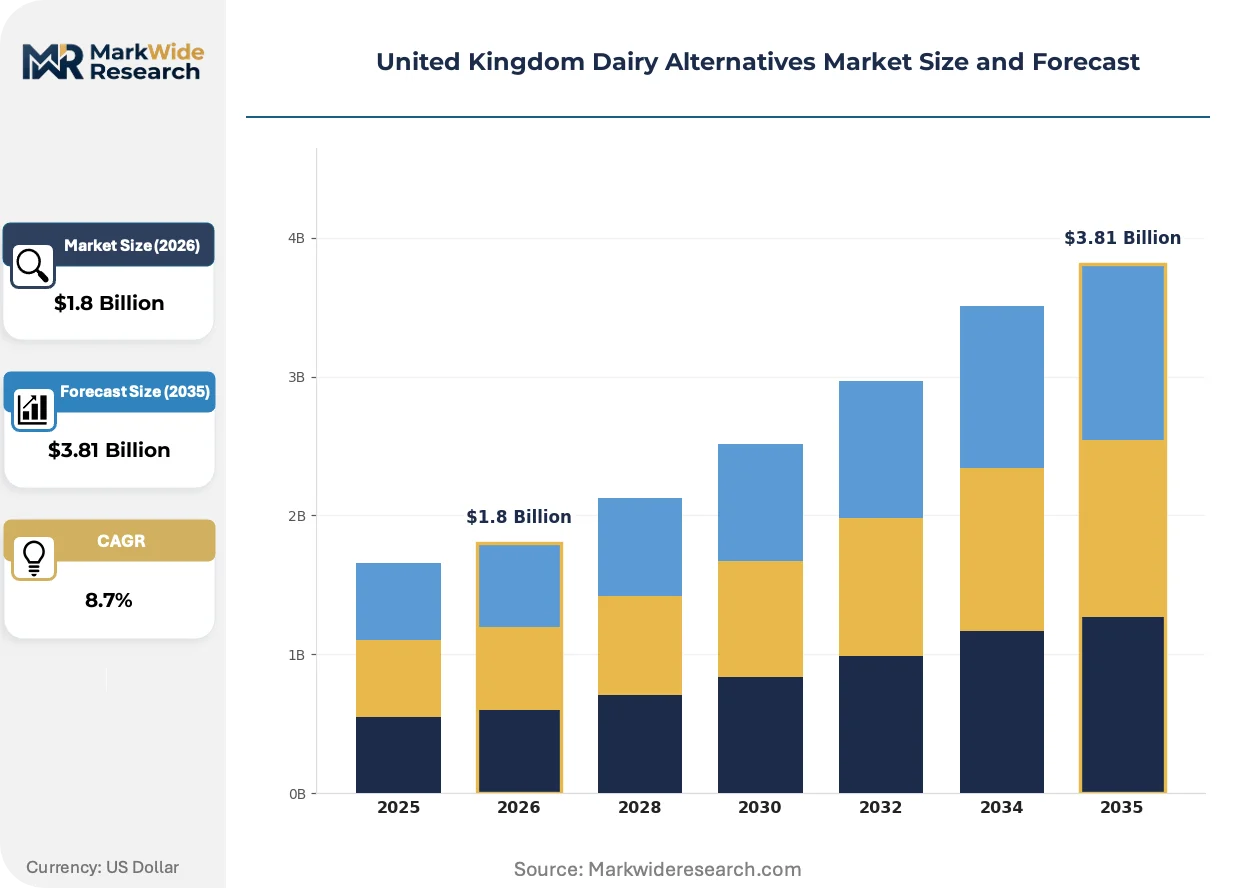
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Milk, Almond Milk, Oat Milk, Coconut Milk Packaging Type: Plastic Bottles, Tetra Paks, Glass Jars, Cartons End User: Retail Consumers, Foodservice, Cafés, Restaurants Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Convenience Stores |
| Companies Covered | Alpro, Oatly Group AB, Plenish, Coconut Collaborative Ltd, Blue Diamond Growers, Danone SA, Arla Foods amba, Rude Health, Minor Figures, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Dairy Alternatives Market Trends and Innovations
Hybrid production models are dissolving the boundary between plant-based and fermentation-derived proteins, forcing supply chain investments that favor scale players with captive bioreactor capacity.
Fermentation-derived whey protein is hybridizing with oat base stocks to achieve functional parity with cow's milk in foaming and emulsification. Specialty coffee roasters in Manchester and Bristol are piloting these blends for latte art competitions. The technology is hybridizing cost structures by reducing the enzyme load required for texture modification, compressing margins for pure plant-based formulators.
UK Food Standards Agency novel food consultations are extending safety assessment timelines for precision fermentation ingredients. This regulatory friction is redirecting R&D investment toward enzymatic hydrolysis improvements rather than protein engineering breakthroughs. Ambient beverage categories face the tightest approval bottlenecks, pushing some entrants toward chilled distribution with shorter regulatory pathways.
Subscription purchasing is displacing intermittent supermarket restocking among urban professionals under 35. Direct-to-consumer platforms capture purchase data that enables predictive flavor rotation, while traditional retail loses visibility into consumption velocity. This behavioral shift concentrates fastest in Greater London postcodes with same-day delivery coverage, forcing heritage brands to build proprietary logistics or surrender customer relationships to platform intermediaries.
United Kingdom Dairy Alternatives Market Segmentation
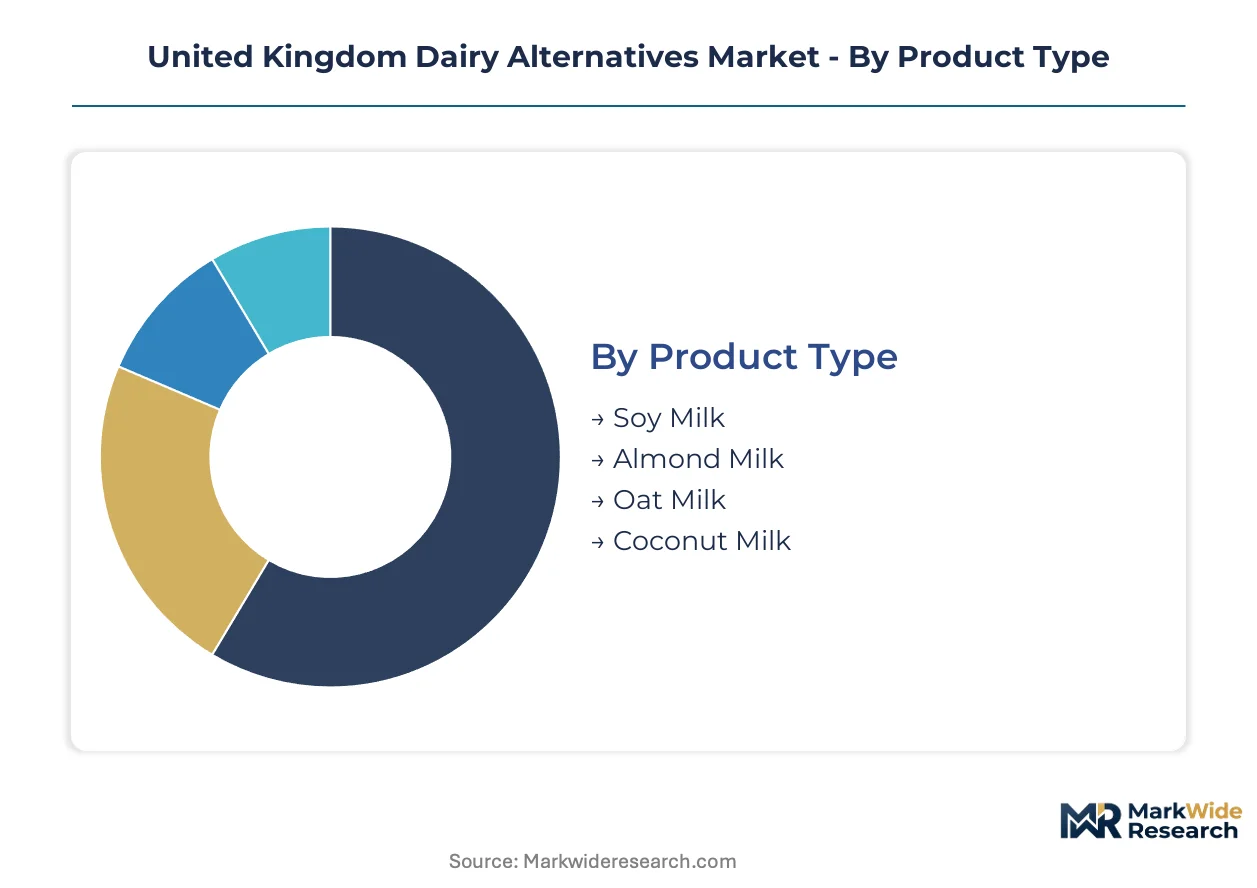
Segmentation in the United Kingdom dairy alternatives market reveals how formulation chemistry, packaging physics, and channel economics create distinct competitive battlegrounds. Each dimension carries different margin profiles and regulatory exposure, forcing portfolio decisions that trade volume scale against premium positioning.
Product Type:
After-sales intensity varies sharply across plant bases, with oat and almond requiring sustained barista training support while soy and coconut demand less ongoing technical engagement.
- Oat Milk:Enzymatically hydrolyzed oat base achieves superior foaming stability through controlled beta-glucan breakdown. British café chains in Manchester and Bristol specify oat as default milk, driving repeat purchase velocity that subsidizes national distribution infrastructure.
- Almond Milk:Blanched California almonds undergo homogenization with stabilizer systems to prevent fat separation. Greater London health-conscious consumers favor this segment despite Advertising Standards Authority scrutiny of water-usage claims.
- Soy Milk:Heat-treated soy protein isolate delivers complete amino acid profiles with established supply chains from European crushing facilities.
- Coconut Milk:High-fat coconut cream emulsions serve industrial food manufacturing and South Asian cuisine restaurants in Birmingham and Leicester.
By volume, oat milk leads. By growth pace, oat milk is also ahead as foodservice penetration accelerates.
Packaging Type:
Cost tier separation runs through material science and shelf-life engineering, with aseptic formats commanding manufacturing scale advantages that glass cannot replicate.
- Tetra Paks:Multi-layer aseptic cartons with aluminum barrier layers enable 12-month ambient stability without refrigeration. Tesco and Sainsbury's slotting fees favor this format for core grocery placement.
- Plastic Bottles:HDPE and PET formats suit chilled distribution with shorter shelf lives, capturing convenience store impulse purchases along the South East commuter corridor.
- Glass Jars:Premium positioning in specialty retail commands price multiples but faces Tetra Pak infrastructure lock-in at scale.
- Cartons:Non-aseptic gable-top formats serve fresh chilled segments with lower capital barriers for emerging entrants.
Tetra Pak dominates absolute volume. Glass jars expand most quickly in subscription direct-to-consumer channels.
End User:
Application-driven formulation splits between retail consistency and foodservice performance, with barista-grade specifications demanding higher protein and fat tolerances.
- Foodservice:Concentrated liquid formats with extended steam stability specifications serve high-throughput café operations. Pret A Manger and Costa Coffee procurement contracts specify oat-based barista blends with documented foam retention metrics.
- Cafés:Independent specialty coffee roasters in Bristol and Manchester pilot hybrid fermentation-plant blends for latte art competitions, testing next-generation protein functionality.
- Retail Consumers:Home consumption favors ambient long-life formats with flavor rotation strategies driven by subscription platform data.
- Restaurants:Bulk bag-in-box formats for kitchen sauce and dessert applications prioritize cost efficiency over foaming performance.
Foodservice captures volume leadership. Cafés show the steepest expansion trajectory as independent operators experiment with precision fermentation hybrids.
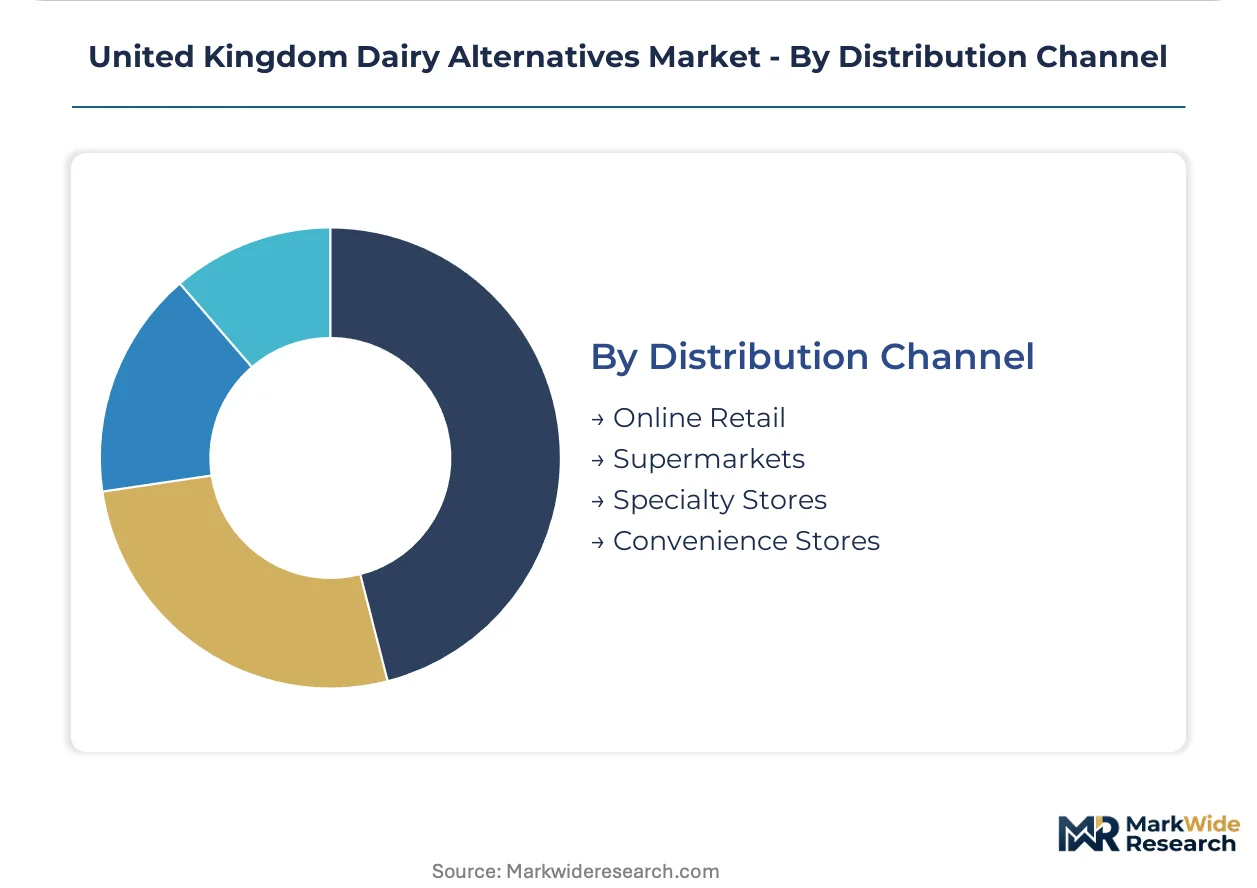
Distribution Channel:
Customer type stratification separates habitual replenishment from discovery-driven trial, with channel choice determining margin capture and data ownership.
- Online Retail:Subscription models and direct-to-consumer platforms reduce intermediary costs for emerging brands while capturing full customer data for predictive flavor rotation.
- Supermarkets:Tesco, Sainsbury's, and Waitrose control mass-market access through slotting fee structures that favor established suppliers with marketing development funds.
- Specialty Stores:Planet Organic and independent health food retailers provide premium positioning for glass jar formats and novel ingredient introductions.
- Convenience Stores:Rail-linked towns between London and Brighton show underpenetrated coverage for ambient long-life formats targeting commuter grab-and-go occasions.
Supermarkets retain volume dominance. Online retail is gaining share fastest among urban professionals under 35 in Greater London postcodes with same-day delivery coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nordic malting operations export enzyme-stabilized oat bases through North Sea shipping lanes to British formulators, while Irish dairy cooperatives repurpose processing infrastructure for plant-based contract manufacturing.
Greater London and the South East
Urban professionals under 35 drive subscription platform adoption for oat and almond variants. The UK Food Standards Agency enforces allergen labelling protocols that tighten ingredient disclosure requirements. Pret A Manger and Costa Coffee procurement contracts in the capital specify barista-grade oat blends with documented foam retention metrics.
Midlands
Industrial food manufacturing clusters demand bulk bag-in-box formats for sauce and dessert applications. Trading Standards compositional enforcement prevents misleading dairy nomenclature on plant-based labels. Birmingham and Leicester processing facilities serve South Asian cuisine restaurants with high-fat coconut cream emulsions.
North England
Specialty coffee roasters in Manchester pilot hybrid fermentation-plant blends for latte art competitions. EU-derived retained law continues shaping reformulation decisions despite post-Brexit regulatory divergence discussions. Independent café operators test next-generation protein functionality with precision fermentation hybrids.
Scotland
Chilled distribution networks target convenience retail coverage in underpenetrated commuter corridors. The Advertising Standards Authority polices environmental claims, constraining carbon footprint messaging. Edinburgh and Glasgow ambient long-life formats capture rail-linked grab-and-go occasions.
Wales
Rural health-conscious consumers favor glass jar premium positioning in specialty retail channels. Novel food consultation timelines at the UK Food Standards Agency extend safety assessments for precision fermentation proteins. Cardiff-based subscription models reduce intermediary costs for emerging brands entering the market.
United Kingdom Dairy Alternatives Market Competitive Landscape
Channel-controlling players compete with product-specialist players for shelf placement and foodservice procurement contracts. The market structure tiers between scale-driven multinationals with captive malting infrastructure and agile entrants leveraging direct-to-consumer platforms. Three archetypes dominate: vertically integrated oat processors, dairy incumbents with dual portfolios, and subscription-native challengers. Competitive moves concentrate on securing raw material consistency through Nordic supply partnerships and building proprietary logistics to bypass supermarket slotting fees.
Within the vertically integrated tier, Oatly Group AB and Arla Foods amba occupy distinct strategic positions. Oatly exemplifies the Nordic-origin processor with captive malting infrastructure securing raw material consistency across British supply lines. Arla represents the dairy incumbent navigating dual portfolio complexity by positioning plant-based operations distinctly from conventional milk processing. Among specialist challengers, Alpro anchors mass-market shelf presence through deep partnerships with dominant British supermarket chains. These three players illustrate how scale, origin, and channel strategy separate winners in procurement negotiations.
| Leading Market Players |
|---|
| Alpro |
| Oatly Group AB |
| Plenish |
| Coconut Collaborative Ltd |
| Blue Diamond Growers |
| Danone SA |
| Arla Foods amba |
| Rude Health |
| Minor Figures |
| Others |
Pricing and Supply Chain Analysis
Nordic oat malting infrastructure concentration exposes British formulators to currency volatility and North Sea shipping disruptions, compressing margins for ambient carton producers while amplifying premium spreads for glass jar specialists with captive supply arrangements.
Pricing Analysis
The technology-generation pricing gap separates enzymatically hydrolyzed oat bases from emerging precision fermentation hybrids and legacy soy isolates. Three-tier pricing structure across premium, standard, and economy levels stratifies by barista functionality certification and raw material provenance. Cost compression in the standard tier is intensifying because Nordic currency swings inflate landed oat base costs. Foodservice procurement teams show the least price sensitivity due to foam retention specifications, while retail private-label buyers drive aggressive negotiation.
Supply Chain Analysis
Tariff exposure between Sweden and the United Kingdom dominates supply chain risk calculus for oat-dependent formulators. Raw material sourcing draws from Swedish malting operations, Spanish almond crushing facilities, and Dutch soy protein isolate refiners. Enzyme stabilizers, aseptic carton laminates, and cold-chain logistics capacity constitute critical input dependencies. Single-source vulnerability concentrates in Nordic oat base supply. Distribution runs through Tesco and Sainsbury's centralized grocery replenishment systems for ambient formats, with chilled networks serving convenience retail corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise spanning enzymatic hydrolysis and UHT stability commands premium salaries that constrain mid-tier R&D bandwidth, creating acquisition opportunities for players with captive technical talent pipelines.
For Market Incumbents: Pre-empt precision fermentation entrants by locking exclusive oat supply contracts with Nordic malting cooperatives before novel food consultations accelerate. Accelerate in-house production of enzyme systems to reduce formulation cost exposure. Defend barista-grade positioning through foam retention certification investments that emerging lab-cultured alternatives cannot yet match. For New Entrants and Emerging Players: Establish a beachhead in the South East commuter corridor rail-linked towns between London and Brighton where ambient long-life convenience coverage remains underdeveloped. Target subscription direct-to-consumer platforms capturing urban professionals under 35 in Greater London postcodes with same-day delivery infrastructure. Bypass supermarket slotting fees through refrigerated delivery models that capture full margin and customer data ownership. For Investors and Strategic Acquirers: UK Food Standards Agency novel food consultation timelines reshapes the acquisition landscape by extending safety assessment periods for precision fermentation targets. Five-to-ten year viability favors vertically integrated oat processors with captive Nordic supply over pure technology plays awaiting regulatory clearance. Watch for enzymatic processing innovation approvals as the inflection signal indicating regulatory pathway divergence from continental markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Oat Malting | Secures raw material consistency against currency volatility and shipping disruption across North Sea corridors. |
| Direct-to-Consumer Subscription Launch | Captures full margin and customer data while bypassing Tesco and Sainsbury's slotting fee structures. |
| Barista Functionality Certification Investment | Defends premium positioning against precision fermentation alternatives through documented foam retention metrics. |
| Hybrid Fermentation-Plant Blend Development | Combines oat base stocks with precision fermentation proteins to achieve functional parity in specialty coffee applications. |
| South East Commuter Corridor Expansion | Targets underpenetrated rail-linked convenience retail between London and Brighton for ambient format penetration. |
Research Methodology
A standing panel of food technologists, café chain procurement directors, supermarket category buyers, and Trading Standards enforcement officers provided ongoing calibration against operating reality. Primary interviews with oat base formulators, enzyme suppliers, and aseptic packaging engineers combined with secondary validation from UK Food Standards Agency consultation documents, Nielsen retail audit data, and customs import records. Bottom-up volume modeling triangulated against top-down category spend estimates.
Scenario-bracketing framed demand projections across regulatory approval timelines, foodservice penetration rates, and subscription adoption curves. Segmentation dimensions modeled include plant base chemistry, packaging physics, distribution channel economics, and regional consumption patterns across the projection horizon. CAGRs derived from historical velocity trends adjusted for structural shifts in foodservice default milk specifications and precision fermentation cost compression trajectories. Forecast inputs incorporated oat futures pricing volatility and novel food consultation duration assumptions.
Stress conditions across Nordic currency swings, North Sea shipping disruption frequency, and UK Food Standards Agency approval timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about enzymatic processing innovation adoption and post-Brexit regulatory divergence pathways. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
A2 Ice Cream Market
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
Almond Drink Market
Dairy Alternatives
Australia Dairy Alternatives Market
Dairy Alternatives
Coconut Milk Market
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
Asia-Pacific Oat Milk Market
Dairy Alternatives
Oat Milk Market
Dairy Alternatives
Global Milk Replacers Market
Dairy Alternatives
Non-Dairy Creamer Market
Dairy Alternatives
Dry Yogurt Market
Dairy Alternatives
Hemp Milk Market
Dairy Alternatives
Middle East Dairy Alternatives Market
Dairy Alternatives
Vegan Coffee Creamer Market
Dairy Alternatives
Clarified Butter Market
Dairy Alternatives
United States Non-Dairy Milk Market