
 Banana Milk Market | 2026-2036
Banana Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Banana Milk Market Outlook
The banana milk category is recalibrating around a stark split between premium functional formulations and commodity-flavored dairy drinks. Binggrae Co., Ltd. leverages its decades-long brand equity in Korean convenience channels to sustain dominant shelf presence across Asia-Pacific retail networks. Maeil Dairy Industry Co., Ltd. differentiates through fortified protein positioning and extended organic certification coverage. Danone SA competes via its global R&D infrastructure and controlled distribution in European health-food segments.
Banana milk denotes a dairy or plant-based beverage incorporating banana puree, natural or artificial banana flavoring, and typically 2-4% milk fat content, produced through ultra-high-temperature processing or cold aseptic filling to achieve 6-12 month ambient shelf stability. The product serves as a palatable calcium and potassium delivery vehicle targeting children and post-workout recovery occasions. Organic and fortified product types command disproportionate margin pools as consumers trade up for additive-free and protein-enriched variants. Tetra Packs dominate ambient distribution economics while bottles anchor chilled premium positioning in supermarket dairy cases.
FDA nutrition labeling requirements and EFSA health claim frameworks shape permissible fortification levels and front-of-pack messaging across North American and European markets. South Korea's Ministry of Food and Drug Safety enforces strict dairy additive standards that constrain formulation flexibility for imported brands. Stakeholders must monitor evolving plant-based labeling disputes and sugar taxation proposals that threaten conventional flavored milk profitability in key export corridors.
Market Dynamics
Clean-label mandates from EFSA and FDA are compressing formulation flexibility while South Korean convenience retail density pulls global flavor innovation toward banana milk variants with shorter ingredient decks and extended ambient stability.
Growth Catalysts
- Protein fortification protocols:Post-workout recovery segments in specialty retail are pulling high-protein banana milk SKUs into premium chilled dairy cases, expanding margin pools beyond conventional flavored milk positioning.
- EFSA clean-label frameworks:Additive-free certification requirements are accelerating manufacturer migration toward natural banana puree bases and eliminating artificial flavor declarations across European export corridors.
- South Korean convenience culture:Dense CU and GS25 store networks are normalizing banana-flavored dairy as a default grab-and-go beverage, creating template demand patterns across Southeast Asian urban retail.
Market Restraints
- Banana puree supply concentration:Ecuador and Costa Rica dominate Cavendish concentrate exports, exposing processors to climate-driven harvest volatility and freight cost spikes from Pacific port congestion.
- MFDS additive strictures:South Korea's Ministry of Food and Drug Safety enforces dairy stabilizer limits that constrain imported brands from replicating home-market formulations without costly reformulation runs.
- Oat milk substitution threat:Barista-grade oat bases are capturing café contract slots and home-barista segments that banana milk historically accessed through flavored latte applications.
Strategic Opportunities
- Vietnam and Indonesia convenience expansion:Underpenetrated chilled dairy infrastructure in Ho Chi Minh City and Jakarta convenience chains offers first-mover positioning for ambient-stable banana milk in Tetra Pak formats.
- EU Green Deal packaging incentives:Bio-based barrier material subsidies are enabling cost-competitive transitions from conventional polyethylene-lined cartons to fiber-based alternatives with carbon footprint claims.
- Microfiltration-UHT convergence:Cold aseptic filling combined with extended-shelf-life membrane processing is opening refrigerated distribution bypass for premium banana milk without cold-chain capital intensity.
Industry Challenges
- Clean-label R&D talent scarcity:Formulation chemists capable of delivering 90-day ambient stability without synthetic stabilizers command premium compensation and extended recruitment cycles in Seoul and Rotterdam hubs.
- Dual certification timeline compression:Parallel organic and non-GMO verification processes for banana sourcing and dairy base supply are extending new product introduction cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banana Milk Market |
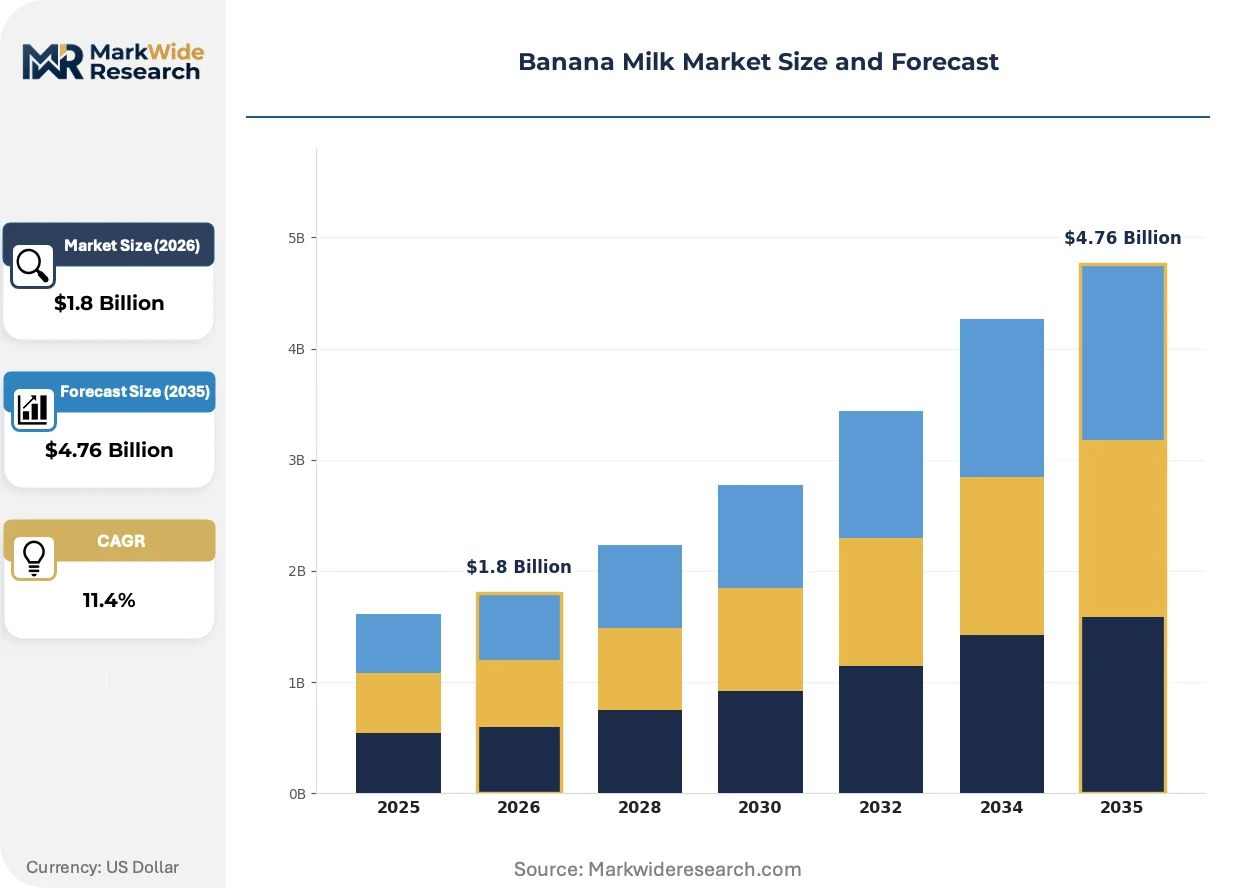
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Flavored, fortified Distribution Channel: Online, Supermarkets, Health Stores, Convenience Stores End User: Children, Athletes, Health Enthusiasts, General Consumers Packaging Type: Bottles, Tetra Packs, Cans, Pouches |
| Companies Covered | Lotte Chilsung Beverage Co., Ltd., Banana Wave, Binggrae Co., Ltd., Morinaga Milk Industry Co., Ltd., Namyang Dairy Products Co., Ltd., Maeil Dairy Industry Co., Ltd., Danone SA, Yili Group, Seoul Milk Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banana Milk Market Strategic Shifts
Processing technology and regulatory disclosure requirements are compressing traditional formulation advantages while consumer search behavior shifts discovery toward digital channels and functional ingredient claims.
High-pressure processing is absorbing the role of thermal sterilization in premium banana milk production, preserving volatile aromatic compounds that UHT protocols degrade. Health-food retailers in Germany and the Netherlands are prioritizing HPP-treated SKUs for refrigerated sets, compressing shelf space for conventional heat-treated alternatives. The technology is absorbing margin pressure from shorter distribution windows by commanding 40-60 percent price premiums in organic channels.
EFSA front-of-pack nutritional profiling schemes are mandating simplified sugar disclosure and restricting implied health claims on flavored dairy beverages. Manufacturers are reformulating toward reduced-sugar banana milk bases or deploying portion-controlled packaging to retain permissible marketing language. European private-label suppliers are most exposed, lacking R&D bandwidth to pivot formulations ahead of enforcement deadlines.
Direct-to-gym subscription models are fragmenting traditional retail procurement for post-workout banana milk, with fitness chains and boutique studios negotiating captive supply agreements that bypass supermarket slotting fees. Seoul-based CrossFit affiliates and London boutique cycling studios are piloting white-labeled protein-fortified variants with exclusive flavor profiles. This channel rotation is most visible in metropolitan clusters where convenience density and fitness penetration overlap.
Banana Milk Market Segmentation
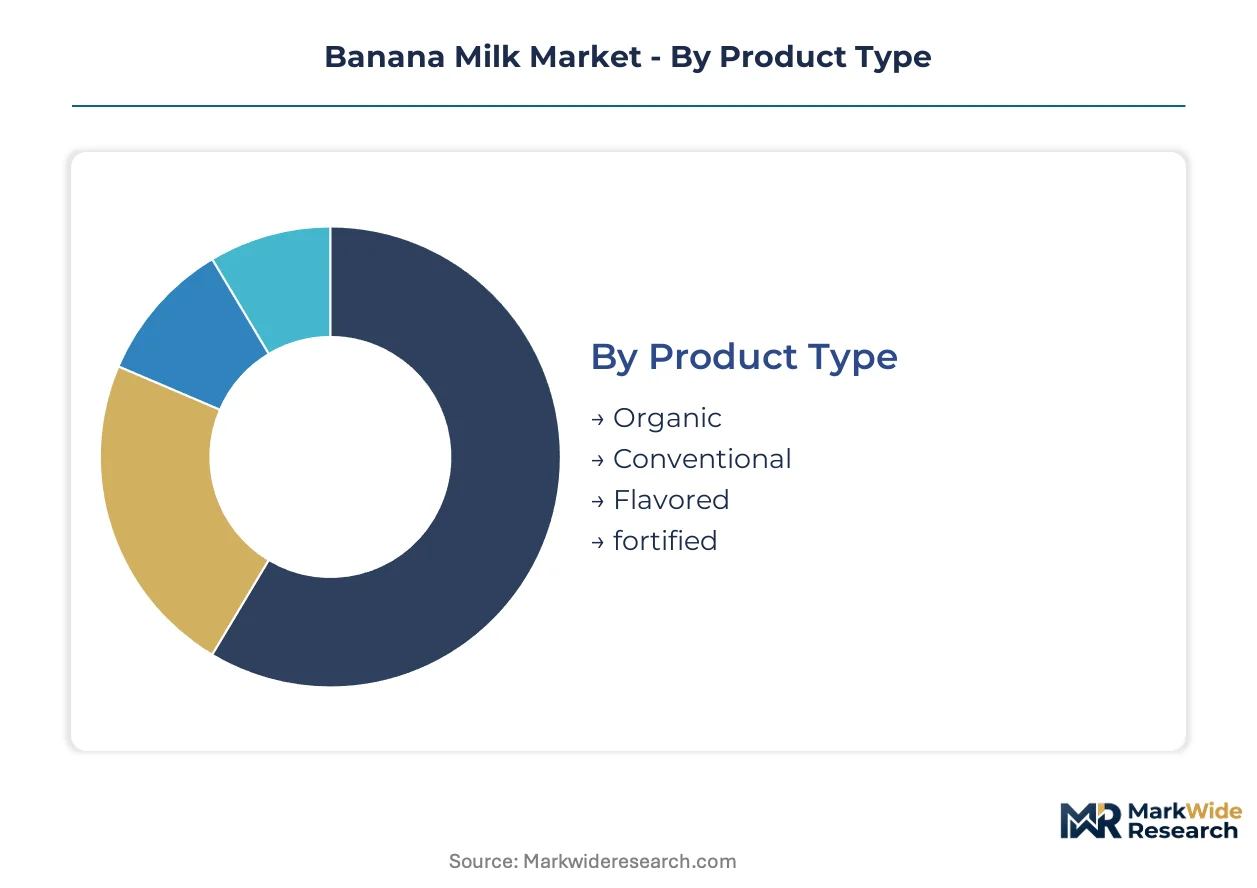
Banana milk manufacturers allocate capital unevenly across product tiers, with premium positioning demanding cold-chain infrastructure while ambient-stable formats minimize fixed asset requirements. Segmentation choices directly determine margin architecture and regulatory exposure in this bifurcated category.
Product Type:
Capital intensity varies sharply across this dimension, with organic certification requiring multi-year soil conversion investments and fortification protocols demanding specialized blending equipment.
- Organic:Dairy base sourcing must demonstrate three-year pasture conversion and zero synthetic pesticide residues in banana puree supply chains. EFSA organic logo eligibility commands shelf space premiums in German and Dutch health-food retail, though certification timelines extend new product launches by eight to fourteen months.
- Fortified:Protein, vitamin D, and calcium enrichment protocols require precision dosing systems and third-party potency verification. Post-workout recovery positioning in Seoul CrossFit affiliates and London boutique cycling studios is pulling high-protein SKUs into captive supply agreements that bypass conventional retail slotting fees.
- Conventional:Standard UHT processing with artificial flavoring and synthetic stabilizers dominates volume production in Vietnamese and Indonesian convenience chains.
- Flavored:Chocolate, strawberry, and vanilla banana milk variants target children through portion-controlled pouch formats in South Korean CU and GS25 networks.
Conventional absorbs the bulk of installed capacity; fortified is expanding most quickly.
Distribution Channel:
Channel selection determines working capital intensity, with direct-to-consumer models requiring inventory risk absorption while third-party retail minimizes logistics overhead.
- Convenience Stores:Dense urban networks in Seoul, Ho Chi Minh City, and Jakarta normalize banana milk as default grab-and-go beverages. CU and GS25 chains in South Korea anchor category visibility and drive flavor innovation templates across Southeast Asian retail.
- Health Stores:Refrigerated premium positioning in Edeka, Albert Heijn, and Planet Organic locations prioritizes HPP-treated and additive-free variants. Clean-label certification requirements compress formulation flexibility while commanding forty to sixty percent price premiums over conventional alternatives.
- Supermarkets:Chilled dairy cases in Tesco, Carrefour, and E-Mart host standard UHT and ESL formats with front-of-pack nutritional profiling compliance.
- Online:Direct-to-gym subscription models and Amazon Fresh fulfillment are fragmenting traditional procurement patterns for protein-fortified variants.
Convenience stores capture the highest transaction velocity; health stores deliver the steepest expansion trajectory.
End User:
User-centric formulation drives R&D allocation, with pediatric palatability requirements diverging sharply from adult functional demands.
- Health Enthusiasts:Protein-fortified banana milk with reduced sugar bases targets post-workout recovery occasions. Fitness chain captive supply agreements in metropolitan Seoul and London clusters are rotating procurement away from supermarket dominance.
- Children:Calcium and potassium delivery vehicles with portion-controlled packaging address parental nutritional concerns. South Korean school lunch programs and Japanese kindergarten contracts sustain stable demand pools.
- Athletes:Electrolyte-enriched variants with specific sodium-potassium ratios compete with sports drink incumbents in specialty retail.
- General Consumers:Commodity-flavored dairy drinks serve impulse purchase occasions in ambient-stable Tetra Pak formats.
General consumers represent the largest addressable base; health enthusiasts are gaining share fastest.
Packaging Type:
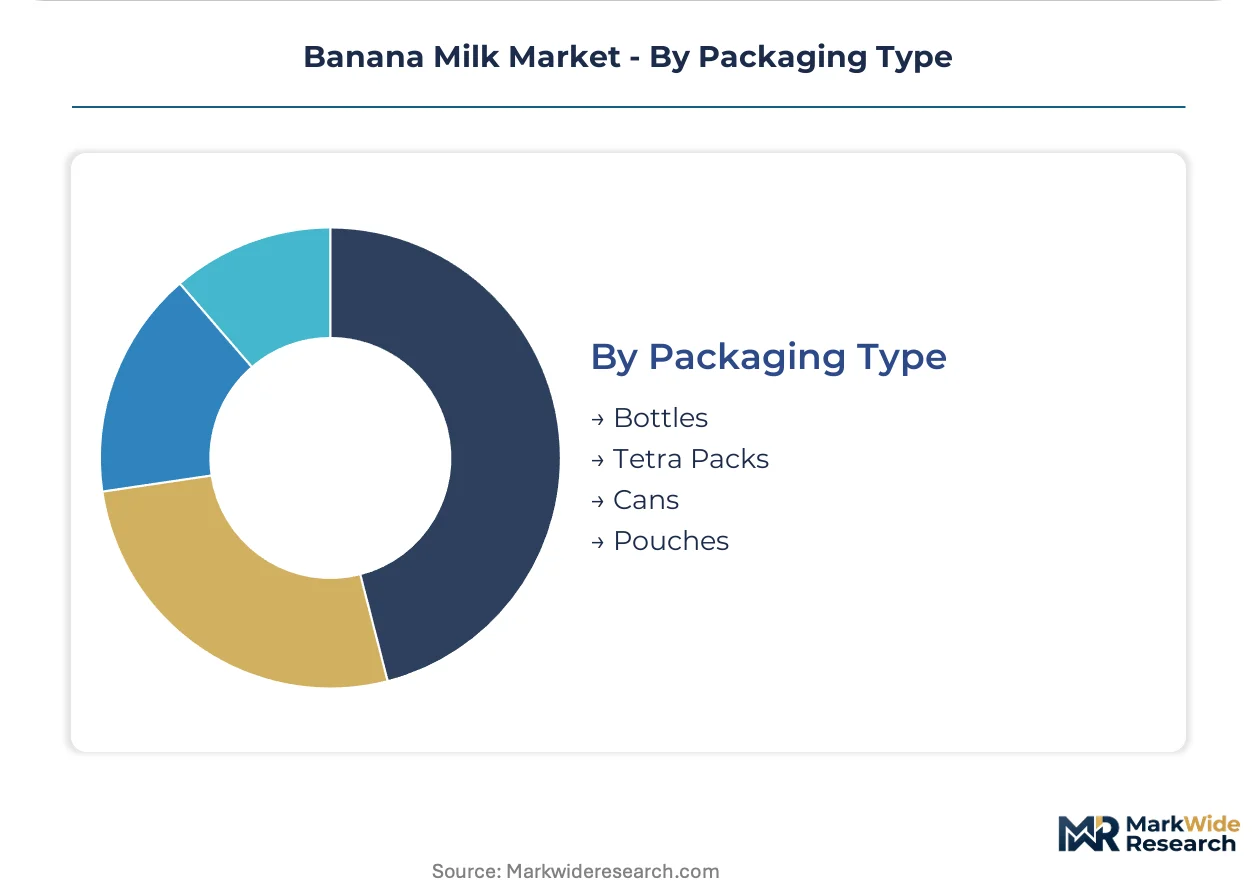
Packaging technology selection governs shelf-life extension and carbon footprint claims, with fiber-based alternatives absorbing R&D investment under EU Green Deal incentives.
- Tetra Packs:Aseptic carton technology enables six to twelve month ambient stability without cold-chain dependency. Indonesian and Vietnamese convenience expansion favors this format for underpenetrated chilled dairy infrastructure.
- Bottles:PET and HDPE containers anchor chilled premium positioning in supermarket dairy cases with shorter distribution windows. High-pressure processing compatibility preserves volatile aromatic compounds degraded by UHT protocols.
- Pouches:Flexible packaging with resealable spouts targets children and on-the-go consumption in Asian urban retail.
- Cans:Aluminum formats serve vending machine distribution and outdoor recreation segments with durability requirements.
Tetra Packs dominate current production volume; bottles are climbing the fastest on HPP premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors banana milk demand through dense CU and GS25 convenience networks that normalize flavored dairy as default grab-and-go consumption. This metropolitan template now propagates across Southeast Asian urban retail corridors.
South Korea
Seoul Capital Area convenience chains drive category visibility through ambient-stable Tetra Pak formats in CU, GS25, and 7-Eleven networks. MFDS dairy additive standards constrain imported brands from replicating home-market formulations without costly reformulation. Busan-Ulsan manufacturing clusters supply UHT processing infrastructure for export-grade production.
United States
Post-workout recovery segments in specialty retail pull high-protein banana milk SKUs into premium chilled dairy cases. FDA nutrition labeling requirements shape permissible fortification levels and front-of-pack messaging across North American distribution. California and New York Metro health-food retailers prioritize HPP-treated variants for refrigerated sets.
Germany
EFSA clean-label frameworks accelerate manufacturer migration toward natural banana puree bases and additive-free certification. Edeka and Albert Heijn refrigerated premium positioning commands forty to sixty percent price premiums for organic variants. Bavaria and North Rhine-Westphalia processing hubs concentrate aseptic filling capacity for European export corridors.
Vietnam
Underpenetrated chilled dairy infrastructure in Ho Chi Minh City convenience chains offers first-mover positioning for ambient-stable formats. Tetra Pak distribution economics bypass cold-chain capital intensity in tropical retail environments. Local processors are piloting banana-flavored dairy in urban convenience networks modeled on Korean templates.
Indonesia
Jakarta convenience expansion favors six-to-twelve month ambient stability without refrigeration dependency. Domestic dairy processors are reformulating toward shorter ingredient declarations to meet emerging clean-label preferences. Java-based manufacturing corridors supply UHT infrastructure for archipelago distribution.
Banana Milk Market Competitive Environment
Capital-heavy dairy processors compete with asset-light beverage designers for shelf space in convenience and health-food channels. The vendor base concentrates around three strategic archetypes: legacy Korean dairy conglomerates with decades-long convenience store equity, European multinationals leveraging global R&D infrastructure for fortified positioning, and regional Asian processors capturing cost-sensitive volume tiers. Dominant competitive moves include backward integration into banana puree supply chains and geographic licensing partnerships for formulation adaptation to local regulator requirements.
Among Korean dairy conglomerates, Binggrae Co., Ltd. and Maeil Dairy Industry Co., Ltd. occupy positions sustained by convenience channel density and fortified protein differentiation respectively. Danone SA represents the multinational archetype with controlled distribution in European health-food segments. These three exemplify the split between regional heritage positioning and global functional R&D investment that defines competitive dynamics across the category.
| Leading Market Players |
|---|
| Lotte Chilsung Beverage Co., Ltd. |
| Banana Wave |
| Binggrae Co., Ltd. |
| Morinaga Milk Industry Co., Ltd. |
| Namyang Dairy Products Co., Ltd. |
| Maeil Dairy Industry Co., Ltd. |
| Danone SA |
| Yili Group |
| Seoul Milk Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
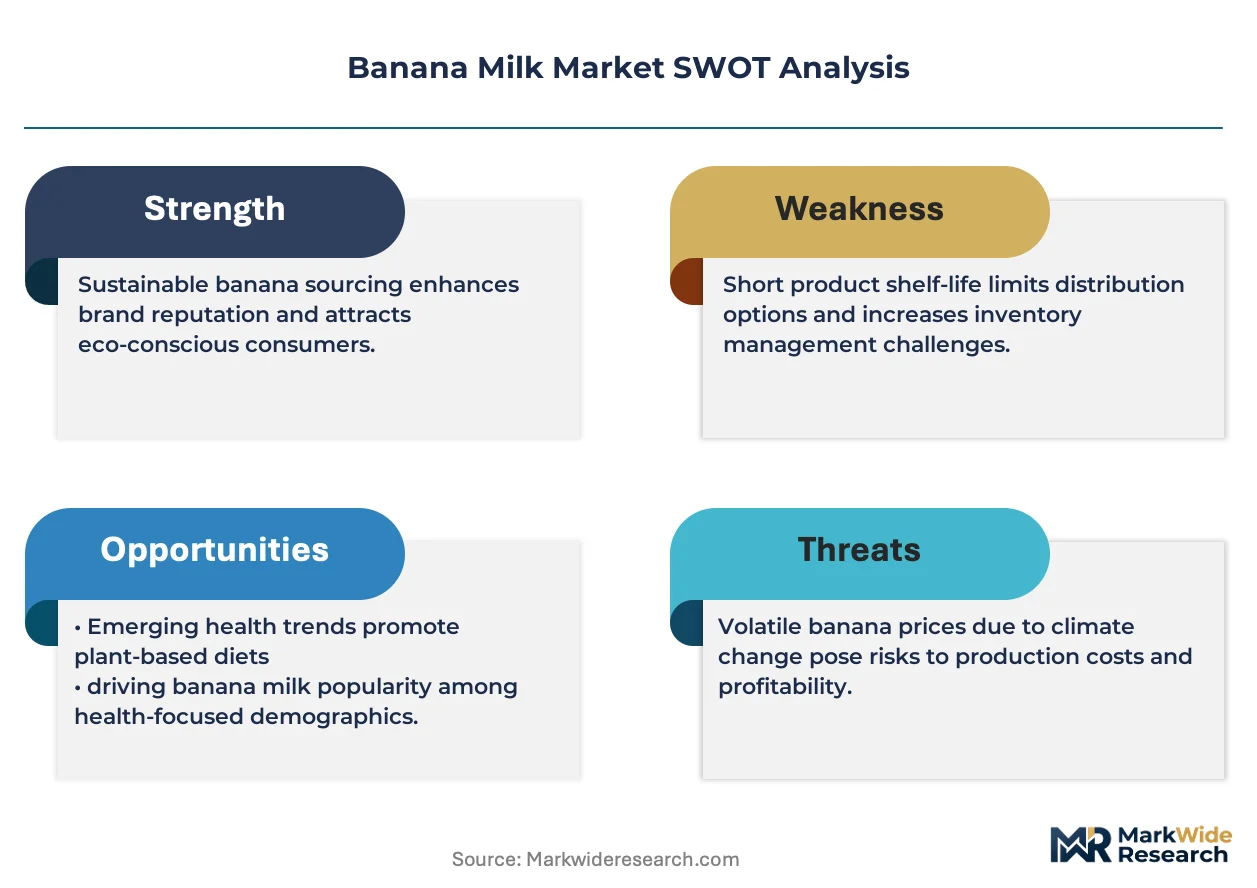
Cavendish banana puree concentrate from Ecuador and Costa Rica feeds directly into three-tier pricing stratification across premium organic, fortified functional, and conventional commodity tiers. Freight cost spikes from Pacific port congestion compress margins on ambient-stable Tetra Pak formats while cold-chain HPP-treated bottles capture forty to sixty percent shelf price premiums in German and Dutch health-food retail.
Pricing Analysis
Post-workout recovery yield anchors value-based pricing for protein-fortified banana milk SKUs in Seoul CrossFit affiliates and London boutique cycling studios. Certification grade and cold-chain dependency drive price differentiation, with organic EFSA-logo eligibility and HPP processing commanding steep premiums over conventional UHT alternatives. Pricing pressure stems from oat milk substitution in café contract slots, eroding historical flavored-latte positioning. Health enthusiasts exhibit lowest price sensitivity; Vietnamese and Indonesian convenience chains show highest elasticity on ambient-stable formats.
Supply Chain Analysis
Single-source vulnerability sits with Ecuador and Costa Rica for Cavendish concentrate exports, exposing processors to climate-driven harvest volatility. The supply chain draws from Pacific port corridors, UHT processing infrastructure in Busan-Ulsan, and aseptic filling capacity in Bavaria and North Rhine-Westphalia. Tariff exposure on banana puree imports threatens conventional tier profitability. Distribution runs through dense CU and GS25 convenience networks in Seoul, with Tetra Pak formats bypassing cold-chain requirements in Southeast Asian urban retail expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cavendish puree supply concentration props pricing power for processors with captive sourcing arrangements, constraining volume expansion for brands without backward integration into Ecuadorian or Costa Rican supply bases.
For Market Incumbents: To counter oat milk substitution in café and home-barista segments, secure exclusive banana puree offtake agreements with Ecuadorian processors and accelerate HPP capacity addition in Rotterdam or Seoul to defend premium positioning in European health-food retail. For New Entrants and Emerging Players: Enter via underpenetrated Ho Chi Minh City and Jakarta convenience chains with ambient-stable Tetra Pak formats, leveraging Korean flavor innovation templates without cold-chain capital intensity. White-label protein-fortified variants for direct-to-gym subscription models offer fastest route to revenue. For Investors and Strategic Acquirers: MFDS reformulation waivers for imported brands is the leading indicator that Korean market access is tightening, signaling long-term viability for domestic processors with established regulatory compliance infrastructure. Acquisition targets should show captive banana puree sourcing and dual organic-non-GMO certification coverage.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Banana Puree Supply | Captive sourcing from Ecuador and Costa Rica insulates processors from climate-driven harvest volatility and freight spikes. |
| HPP Capacity Expansion | Cold aseptic filling in Rotterdam or Seoul preserves aromatic compounds degraded by UHT protocols for health-food retail. |
| Direct-to-Gym Subscription Launch | CrossFit affiliates and boutique cycling studios in metropolitan Seoul and London bypass supermarket slotting fees. |
| EU Green Deal Packaging Transition | Bio-based barrier materials enable carbon footprint claims in Edeka and Albert Heijn refrigerated sets. |
| Vietnam-Indonesia Convenience Expansion | Tetra Pak distribution economics exploit underpenetrated chilled dairy infrastructure in Ho Chi Minh City and Jakarta. |
Study Parameters
Document review covered MFDS additive standards, EFSA clean-label frameworks, FDA nutrition labeling requirements, and trade flow data on Cavendish concentrate exports, complemented by interviews with dairy processing executives, convenience chain category buyers in Seoul and Jakarta, formulation chemists in Rotterdam, and banana puree procurement leads at Ecuadorian exporters. Secondary validation drew from customs records, refrigerated retail audit data, and UHT processing capacity disclosures. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Cross-referencing historical protein-fortified dairy adoption curves against panel input from health-food retailers and fitness chain operators shaped the projection methodology across the analysis window. Segmentation dimensions modeled include product type tier, distribution channel infrastructure, end-user occasion, and packaging technology compatibility. CAGRs derived from elasticity-adjusted volume trajectories and price-premium capture rates in organic and fortified tiers. Forecast inputs incorporated MFDS regulatory timeline uncertainty and EU Green Deal packaging subsidy uptake curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained Pacific port congestion or accelerated sugar taxation proposals in European export corridors. Deviation in clean-label R&D talent availability in Seoul and Rotterdam would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Oat Drinks Market
Dairy Alternatives
Middle East and Africa Dairy Alternatives Market
Dairy Alternatives
Cashew Milk Market
Dairy Alternatives
Vegan Condensed Milk Market
Dairy Alternatives
Plant Milk Market
Dairy Alternatives
North America Non-Dairy Yogurt Market
Dairy Alternatives
North America Non-Dairy Ice Cream Market
Dairy Alternatives
A2 Lactose-free Milk Market
Dairy Alternatives
Europe Non-Dairy Milk Market
Dairy Alternatives
Breast Milk Substitutes Market
Dairy Alternatives
Savory Yogurt Market
Dairy Alternatives
US Lactose-Free Dairy Market
Dairy Alternatives
Asia-Pacific Sour Milk Drinks Market
Dairy Alternatives
North America Drinkable Yogurt Market
Dairy Alternatives
Cultured Dairy Blends Market
Dairy Alternatives
A2 Ice Cream Market