
 Global Vegan Sour Cream Market | 2026-2036
Global Vegan Sour Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vegan Sour Cream Market Foresight
Premium organic certification is collapsing the gap between artisan vegan sour cream and conventional dairy equivalents. Forager Project leverages its California supply base to dominate West Coast retail placement. Kite Hill specializes in almond-fermented cultures that sustain higher price points in specialty channels. Tofutti Brands anchors the mass-market tier through decades-long diner and institutional relationships.
Vegan sour cream denotes a cultured, high-fat emulsion derived from plant lipoproteins—typically achieving 12–16% fat content through homogenization of coconut, cashew, or oat cream bases with lactic acid bacteria. The product serves as a functional topping, binding agent, and flavor carrier across cold-prepared and cooked applications. Coconut-based formulations lead volume due to superior mouthfeel replication, though oat-based variants represent the fastest-growing segment as Nordic suppliers scale enzymatic lipid modification. Application concentration in dips and sauces captures the deepest margin pools, while baking adoption remains nascent but structurally significant for long-term volume expansion.
FDA allergen labeling mandates, EU EFSA novel food assessments, and Health Canada plant-based dairy identity standards collectively shape formulation thresholds and cross-border market access. The EU Green Deal's farm-to-fork sustainability targets are accelerating ingredient traceability requirements that favor vertically integrated cashew processors over commodity traders. Stakeholders must monitor fermentation IP filings and regional clean-label enforcement intensity to anticipate which base ingredient will command the next supply contract cycle.
Market Dynamics
Fermentation IP consolidation and enzymatic lipid modification are restructuring competitive moats in vegan sour cream, as vertically integrated ingredient processors lock up supply contracts ahead of clean-label enforcement waves.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Mandatory ingredient traceability is redirecting procurement toward captive cashew processors with certified supply chains, compressing spot-market dependence.
- Foodservice channel expansion:North American quick-service chains are standardizing coconut-based formulations across cold-prep lines, creating volume anchors for contract manufacturers.
- Enzymatic lipid modification:Nordic suppliers are scaling oat cream bases with improved mouthfeel profiles, opening formulation flexibility beyond tropical oil dependence.
Market Restraints
- Cashew price volatility:West African and Indian raw nut supply interruptions transmit directly to margin compression for clean-label positioned brands.
- FDA allergen labeling mandates:Cross-contact documentation requirements for coconut and almond bases extend product development timelines and limit co-manufacturing options.
- Cultured dairy taste replication:Lactic acid bacteria strain selection remains empirically driven, with fermentation off-notes persisting in oat-based variants at commercial scale.
Strategic Opportunities
- German retail penetration:Discounter channel slotting for private-label vegan sour cream remains underdeveloped relative to milk and yogurt analogues.
- Baking application development:Heat-stable emulsion formulations for cake and pastry segments represent untapped volume pools beyond cold-prep dominance.
- Health Canada plant-based dairy identity standards:Proposed protein minimums for "dairy alternative" labeling could advantage cashew and soy bases over lower-protein coconut formulations.
Industry Challenges
- Fermentation microbiology talent scarcity:Industrial strain development and scale-up expertise concentrates with a handful of European culture houses, creating hiring bottlenecks.
- Organic certification timeline compression:Three-year transition requirements for ingredient suppliers are mismatching product launch schedules with retailer sustainability commitments.
- Co-packer allergen segregation:Shared facility protocols for coconut, cashew, and oat lines require dedicated production windows that constrain throughput flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vegan Sour Cream Market |
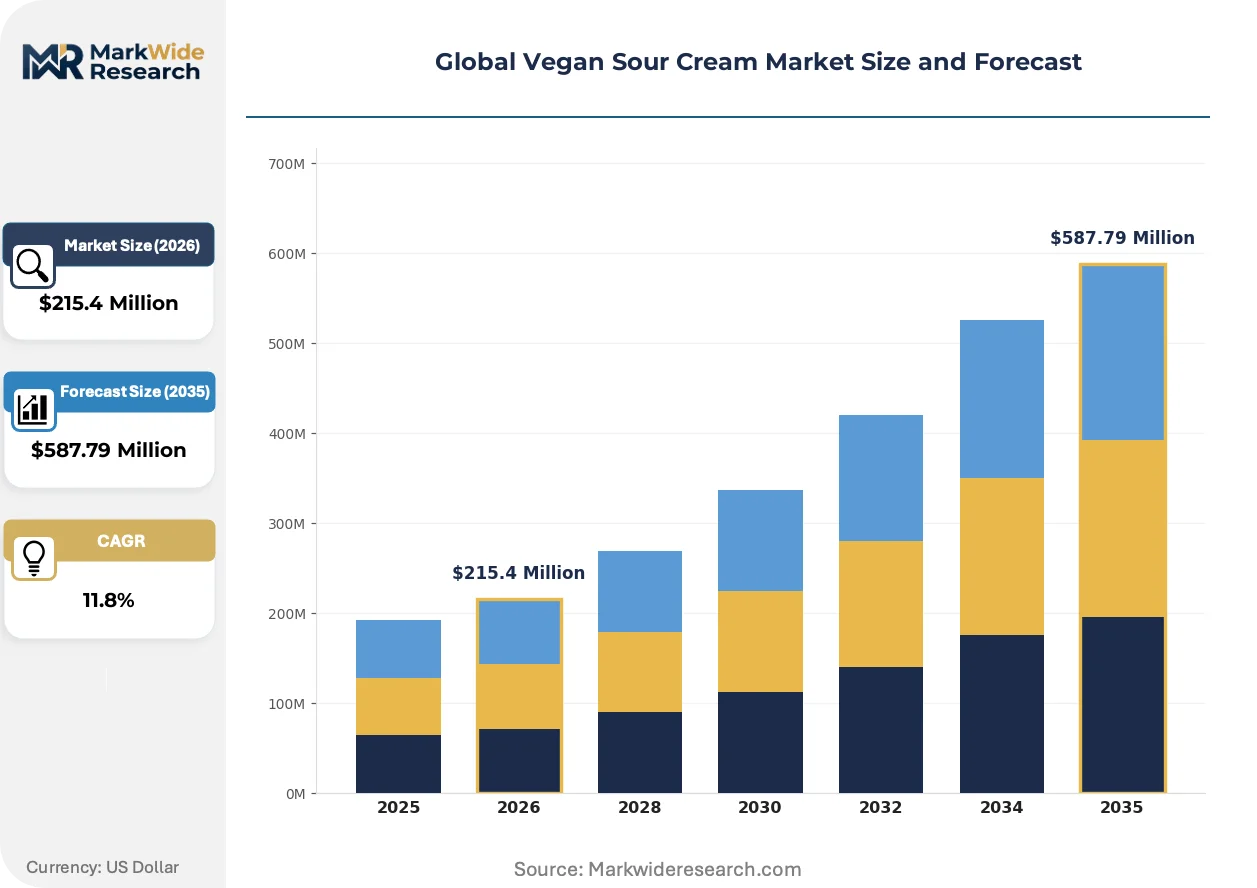
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $587.79 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut-Based, Soy-Based, Almond-Based, Cashew-Based, Oat-Based Flavor Profile: Original, Garlic & Herb, Spicy Jalapeno, Smoky Chipotle, Sweet Onion Application: Salads, Sandwiches, Dips, Baking, Sauces Customer Type: Retail Consumers, Foodservice Providers, Health Food Stores, Specialty Grocers |
| Companies Covered | The Kroger Co., Kite Hill, WayFare Health Foods, Tofutti Brands, Inc, Good Karma Foods, Inc., Forager Project, LLC, The Dairy Free Co., Follow Your Heart, DAIYA FOODS INC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vegan Sour Cream Market Shifts & Advancements
Precision fermentation and enzymatic processing are collapsing the functional gap between plant-derived and animal-derived cultured creams, redefining what constitutes premium positioning in refrigerated dairy alternatives.
Precision fermentation of dairy-identical proteins is decomposing the traditional trade-off between clean-label positioning and functional performance in high-heat applications. Bakery manufacturers in the United States are piloting these ingredients for sour cream-based cake formulations where thermal stability failures have historically limited plant-based penetration. The technology is decomposing the category boundary between "alternative" and "equivalent" by delivering identical protein functionality without allergen cross-contact liabilities.
REACH regulation updates on novel food enzymes are accelerating documentation burdens for European suppliers deploying lipid modification biocatalysts. EFSA assessment backlogs for new fermentation-derived ingredients are extending time-to-market by 18-24 months relative to GRAS pathways in North America. German and Dutch ingredient houses are responding by pre-submitting strain characterization dossiers ahead of commercial scale commitments.
Direct-to-foodservice distribution is displacing traditional broker-mediated placement for mid-sized vegan sour cream brands with specialized fermentation capabilities. United Kingdom contract caterers and institutional buyers are establishing direct supply relationships to secure allocation of limited organic-certified production runs. This channel compression is most visible in London and Manchester metropolitan procurement clusters where sustainability mandates outpace retail shelf development.
Global Vegan Sour Cream Market Segmentation
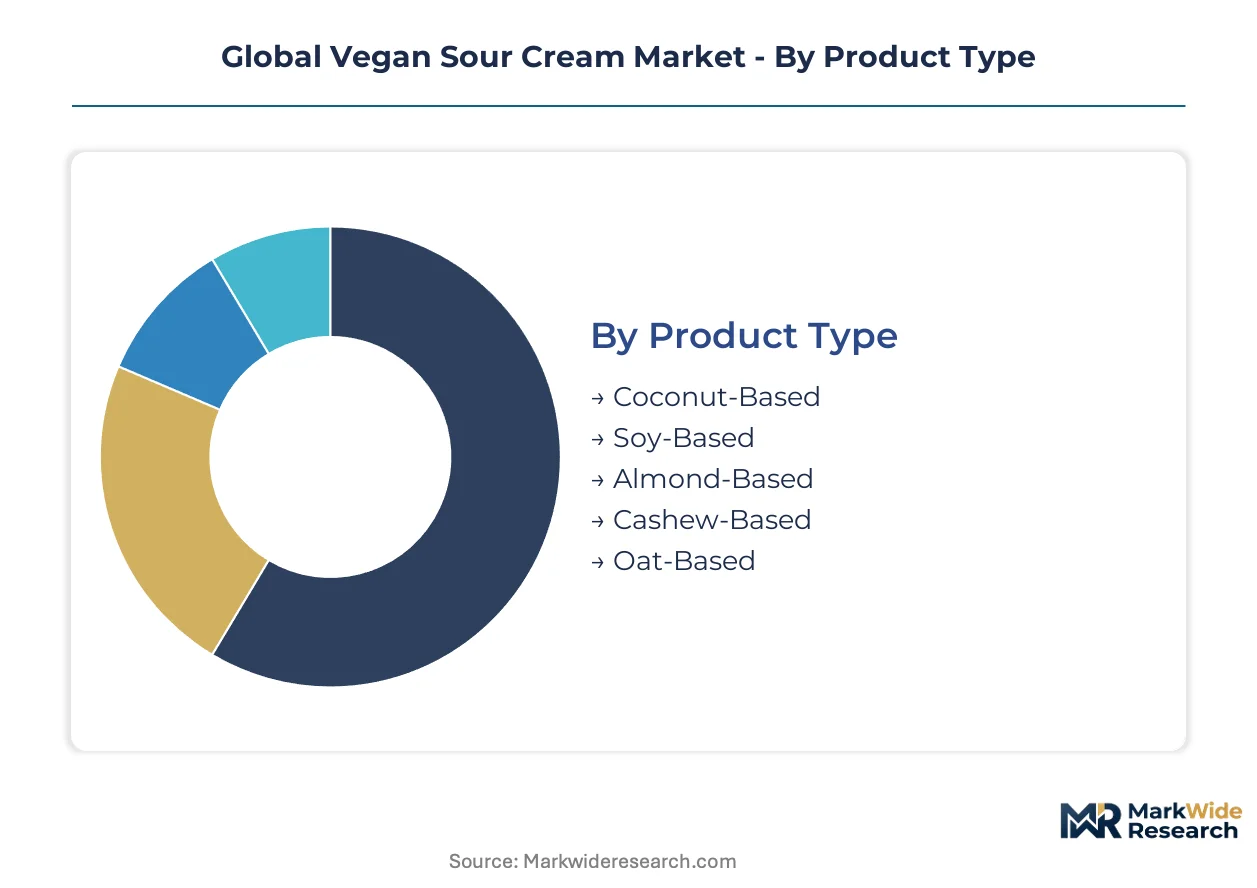
Segmentation in vegan sour cream reveals how base ingredient sourcing constraints, fermentation scalability, and channel-specific margin structures fragment commercial opportunity. Manufacturers must align formulation investments with the geographic and application concentration patterns that govern contract volumes.
Product Type:
Coconut and cashew bases anchor export-heavy supply chains from Southeast Asia and West Africa, while oat and soy variants concentrate in domestic European and North American production clusters.
- Coconut-Based:High-saturated-fat emulsions deliver superior cold mouthfeel replication through homogenized cream centrifugation. United States quick-service chains standardize this base for volume procurement, though tropical oil dependence exposes margins to shipping rate volatility and FDA allergen documentation burdens.
- Oat-Based:Enzymatic lipid modification by Nordic suppliers enables improved viscosity without coconut's saturated fat load. German and Dutch retail channels concentrate demand here as EU Green Deal traceability requirements favor domestically processed grain bases over imported nut oils.
- Soy-Based:Protein-rich fermented emulsions with established culture compatibility and lower raw material costs.
- Almond-Based:Premium-positioned variants leveraging California supply proximity for West Coast United States distribution.
- Cashew-Based:Clean-label preferred base with creamy texture but constrained by West African and Indian supply interruptions.
Coconut-based formulations command the established base. The steepest expansion runs through oat-based alternatives.
Flavor Profile:
Flavor development costs stratify sharply between commodity original formulations and specialty seasoned variants requiring additional fermentation stabilization and ingredient traceability documentation.
- Original:Unflavored cultured base serving as ingredient input for foodservice manufacturers and retail private-label programs. United States institutional buyers specify this segment for cost-controlled procurement in K-12 and healthcare feeding operations where customization occurs downstream.
- Garlic & Herb:Seasoned retail SKUs commanding shelf-ready premium positioning through dried herb inclusion and modified fermentation protocols. United Kingdom specialty grocers and health food stores concentrate demand here, with EFSA novel food assessments for certain herb extracts extending European time-to-market.
- Spicy Jalapeno:Heat-stable capsicum emulsions targeting Southwest United States and Mexican-influenced cuisine applications.
- Smoky Chipotle:Smoke-flavored variants with concentrated adoption in barbecue-centric United States regional markets.
- Sweet Onion:Caramelized allium profiles for dip-specific applications in North American retail.
Original unflavored bases dominate foodservice contract volumes. Value-added seasoned variants are gaining share fastest in European specialty retail.
Application:
Cold-prepared applications sustain higher margins and simpler emulsion stability requirements than thermally stressed baking and sauce applications.
- Dips:Cold-service emulsions with highest margin capture through premium positioning and flavor differentiation. United States and United Kingdom retail channels concentrate demand, with direct-to-foodservice distribution displacing traditional broker placement for organic-certified production runs.
- Baking:Heat-stable formulations requiring modified starch or precision fermentation protein integration to prevent thermal breakdown. United States bakery manufacturers pilot these applications where historical plant-based penetration failures have limited category expansion.
- Salads:Dressing and topping applications with established vegan penetration in European foodservice.
- Sandwiches:Spread functionality targeting deli and grab-and-go retail segments.
- Sauces:Cooked applications with emulsion stability challenges similar to baking but lower temperature thresholds.
Dip applications command the established base. Baking represents the steepest expansion trajectory as heat-stable formulations mature.
Customer Type:
Channel concentration patterns reveal divergent procurement logics between price-sensitive institutional volume buyers and sustainability-mandated specialty retailers.
- Foodservice Providers:Contract-manufactured volume procurement with standardized coconut-based specifications and extended payment terms. North American quick-service chains anchor this segment through system-wide menu integration, creating allocation competition for limited organic-certified production.
- Specialty Grocers:Curated SKU selection emphasizing clean-label positioning, regional sourcing narratives, and direct supplier relationships. United Kingdom and German metropolitan clusters concentrate demand here as sustainability mandates outpace conventional retail shelf development.
- Retail Consumers:Supermarket and mass-market purchasers with price-driven selection behavior.
- Health Food Stores:Allergen-free and organic-certified positioning with highest per-unit margins but constrained volumes.
Foodservice providers command the established base. Specialty grocers are climbing the fastest as sustainability procurement mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingredient sourcing for vegan sour cream concentrates in tropical and temperate zones with established lipid processing infrastructure. FDA allergen mandates, EU EFSA novel food pathways, and Health Canada plant-based identity standards create divergent compliance burdens across export corridors. Urban foodservice clusters in four countries anchor demand absorption.
United States
Quick-service chains in Chicago and Dallas-Fort Worth standardize coconut-based formulations across cold-prep lines, creating volume anchors for contract manufacturers. FDA allergen labeling mandates extend product development timelines for cross-contact documentation. California's Central Valley supplies almond bases to West Coast specialty grocers with direct-to-retail distribution bypassing traditional brokers.
Germany
Discounter channel slotting for private-label vegan sour cream remains underdeveloped relative to milk and yogurt analogues, presenting white-space opportunity. EU Green Deal farm-to-fork targets mandate ingredient traceability that redirects procurement toward vertically integrated cashew processors. Berlin and Hamburg metropolitan procurement clusters drive sustainability-mandated specialty retail expansion faster than conventional shelf development.
United Kingdom
Contract caterers in London and Manchester establish direct supply relationships to secure allocation of limited organic-certified production runs. EFSA novel food assessments for fermentation-derived ingredients extend time-to-market by 18-24 months relative to GRAS pathways. Health food stores in metropolitan clusters concentrate demand for allergen-free positioning with highest per-unit margins.
Canada
Health Canada plant-based dairy identity standards propose protein minimums for "dairy alternative" labeling that could advantage cashew and soy bases. Toronto and Vancouver foodservice providers pilot heat-stable emulsion formulations for baking applications where historical plant-based penetration failures have limited category expansion. Prairie oat processing infrastructure supports domestic enzymatic lipid modification scaling.
Netherlands
Dutch ingredient houses pre-submit strain characterization dossiers to EFSA ahead of commercial scale commitments to circumvent assessment backlogs. Rotterdam and Amsterdam distribution hubs coordinate Nordic oat cream base imports with improved viscosity profiles. REACH regulation updates on novel food enzymes accelerate documentation burdens for lipid modification biocatalyst deployment.
Global Vegan Sour Cream Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with fermentation IP holders commanding premium positioning while mass-market brands anchor volume through institutional relationships. The vendor base stratifies across three tiers: precision fermentation specialists, clean-label organic processors, and legacy dairy-alternative manufacturers with decades-long foodservice contracts. Two dominant competitive moves reshape positioning: direct-to-foodservice distribution compression and backward integration into captive cashew supply chains.
Within the clean-label organic tier, Forager Project and Kite Hill exemplify West Coast concentration strategies leveraging California supply proximity for specialty channel placement. Tofutti Brands occupies a position at the mass-market tier, anchoring decades-long diner and institutional relationships that sustain volume despite compressed margins. These three players represent distinct archetypes—organic regional specialist, almond-fermentation premium positioned, and legacy institutional supplier—rather than competing directly for identical procurement decisions.
| Leading Market Players |
|---|
| The Kroger Co. |
| Kite Hill |
| WayFare Health Foods |
| Tofutti Brands, Inc |
| Good Karma Foods, Inc. |
| Forager Project, LLC |
| The Dairy Free Co. |
| Follow Your Heart |
| DAIYA FOODS INC. |
| Others |
Supply & Pricing Matrix
EU Green Deal farm-to-fork traceability mandates gate both supplier qualification timelines and organic certification premiums simultaneously, compressing spot-market flexibility while expanding price spreads between certified and conventional tiers. This regulatory scaffolding forces manufacturers to pre-commit to captive supply relationships that lock in cost structures years ahead of shelf placement.
Pricing Analysis
FDA allergen labeling mandates dictate the pricing tier structure across the Global Vegan Sour Cream Market by extending product development timelines and limiting co-manufacturing options. Three-tier pricing structure across premium organic, standard clean-label, and economy mass-market levels stratifies around certification depth and fermentation IP control. Cost compression in the mass-market tier is intensifying because quick-service chains squeeze contract manufacturers on volume terms. Institutional buyers in United States K-12 and healthcare feeding operations exhibit highest price sensitivity, while United Kingdom specialty grocers and German metropolitan procurement clusters absorb premiums for traceable supply chains.
Supply Chain Analysis
West African and Indian cashew processing chokepoints expose margin structures to raw nut supply interruptions that transmit directly to clean-label positioned brands. Coconut cream concentrates in Indonesia and Philippines, oat bases in Nordic countries, and cashew derivatives in West Africa and India anchor geographic supply concentration. Raw material dependencies span tropical nut oils, enzymatically modified grain lipids, and lactic acid bacteria cultures from European culture houses. Single-source vulnerability in West African cashew supply creates procurement risk that favors backward integration. Distribution runs through direct-to-foodservice channels displacing traditional broker mediation in London, Manchester, and Berlin metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation of dairy-identical proteins threatens to collapse the functional differentiation that currently sustains plant-based premium positioning, forcing incumbents to defend against equivalence rather than inferiority.
For Market Incumbents: Secure fermentation IP portfolios and captive cashew supply contracts ahead of clean-label enforcement waves tightening across European markets. Anchor volume through long-term quick-service chain agreements that create allocation competition for limited organic-certified production. Defend against precision fermentation substitutes by emphasizing allergen-free positioning that dairy-identical proteins cannot replicate. For New Entrants and Emerging Players: Differentiate on enzymatic lipid modification capabilities for oat-based formulations that bypass tropical oil dependence and align with EU Green Deal traceability preferences. Target German discounter channel slotting for private-label vegan sour cream, which remains underdeveloped relative to milk and yogurt analogues. Pursue direct supply relationships with United Kingdom contract caterers establishing sustainability-mandated procurement clusters. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation protein integration and enzymatic processing infrastructure, favoring scaled players with culture house partnerships. Mid-term viability through the next decade rests on identifying acquisition targets with established EFSA pre-submission dossiers and Nordic oat cream base supply relationships. Monitor EFSA assessment backlog resolution as the critical signal for timing market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation IP Acquisition | Locks up lactic acid bacteria strain development expertise concentrated with European culture houses. |
| Backward Integration into Cashew Processing | Captures West African and Indian supply chains ahead of EU Green Deal traceability enforcement. |
| Direct-to-Foodservice Distribution Buildout | Bypasses broker mediation to secure allocation with London and Manchester sustainability-mandated buyers. |
| Enzymatic Lipid Modification Scale-Up | Enables oat-based viscosity profiles that reduce tropical oil dependence and shipping rate exposure. |
| EFSA Pre-Submission Dossier Filing | Circumvents 18-24 month assessment backlogs for novel fermentation-derived ingredients in European markets. |
Research Methodology
Desk research of regulatory filings, customs and trade data, and retail audit databases preceded structured interviews with fermentation technology directors, contract manufacturing procurement leads, foodservice category managers, and European culture house technical specialists. Primary fieldwork validated base ingredient sourcing patterns and enzymatic processing scale-up timelines against secondary trade flow analysis. Bottom-up volume modeling triangulated against top-down category expenditure estimates.
Variance decomposition across product type, flavor profile, application, and customer type segmentation dimensions anchored the analytical framework over the projection horizon. CAGRs derived from modeled volume trajectories incorporating fermentation capacity expansion schedules and regulatory pathway timelines. Forecast inputs included EFSA assessment backlog resolution rates and quick-service chain menu integration commitments.
Material uncertainties — cashew price volatility, REACH regulation updates on novel food enzymes, and Health Canada protein minimum finalization — sit outside the modeled envelope. Forecasts reflect documented assumptions about fermentation scalability and clean-label enforcement intensity. Practitioners should keep alternative scenarios live as precision fermentation cost curves and EU traceability mandate implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Dairy-Free Ice Creams Market
Dairy Alternatives
Clarified Butter Market
Dairy Alternatives
Dairy Alternatives Market
Dairy Alternatives
Non-Dairy Cheese Market
Dairy Alternatives
On-The-Go Yoghurt Market
Dairy Alternatives
Vegan Condensed Milk Market
Dairy Alternatives
United Kingdom Dairy Alternatives Market
Dairy Alternatives
South America Dairy Alternatives Market
Dairy Alternatives
United States Dairy Alternatives Market
Dairy Alternatives
Asia-Pacific Dairy Alternatives Market
Dairy Alternatives
Germany Non-Dairy Milk Market
Dairy Alternatives
Vegan Cheese Market
Dairy Alternatives
North America Drinkable Yogurt Market
Dairy Alternatives
North America Non-Dairy Milk Market
Dairy Alternatives
A2 Ice Cream Market
Dairy Alternatives
Dry Cream Substitute Market