
 Global Soy Desserts Market | 2026-2036
Global Soy Desserts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Soy Desserts Market Outlook
Precision fermentation is narrowing the cost gap between soy protein isolates and conventional dairy proteins, enabling broader commercial viability. Danone S.A. leverages its refrigerated supply chain infrastructure to dominate European retail distribution. The Hain Celestial Group, Inc. specializes in organic-certified soy pudding formulations that command premium shelf placement. Alpro anchors the Benelux and UK markets through dedicated plant-based manufacturing facilities.
Soy desserts comprise frozen, refrigerated, and shelf-stable formulations derived from processed soybeans, typically containing 3-8% protein content and functional stabilizers to mimic dairy mouthfeel. Manufacturers employ enzymatic hydrolysis or extrusion to modify soy protein texture for custard and ice cream applications. Soy yogurt leads product type segments due to established cold-chain infrastructure and breakfast occasion penetration. Online retailers represent the fastest-growing distribution channel as direct-to-consumer subscription models reduce intermediary margins. Health food stores sustain the highest per-unit pricing power through curated specialty assortments.
The FDA governs soy dessert labeling under Federal Food, Drug, and Cosmetic Act standards, while the EMA's nutrition and health claims regulation shapes European product positioning. China's SAMR enforces GB standards for plant-based food safety and additive limits. Japan's METI promotes soy protein utilization through functional food certification pathways. Stakeholders must monitor evolving protein content thresholds and cross-border allergen disclosure requirements that determine market access eligibility.
Market Dynamics
Precision fermentation is compressing the cost structure for soy protein isolates while fitness-driven demand for high-protein alternatives accelerates formulation innovation across frozen, refrigerated, and shelf-stable categories.
Growth Catalysts
- Protein Fortification Mandates:Japan's METI functional food certification pathways incentivize manufacturers to develop soy-based desserts with elevated protein claims targeting athletic consumers.
- Enzymatic Hydrolysis Advancement:Texture modification technologies enable soy custard and ice cream applications to achieve dairy-comparable mouthfeel without compromising nutritional density.
- German Retail Network Density:Established cold-chain infrastructure in Germany supports refrigerated soy yogurt penetration into mainstream breakfast occasions.
Market Restraints
- Input Cost Volatility:Non-GMO soybean premiums fluctuate with Brazilian and Argentinian harvest cycles, squeezing margin stability for organic-certified pudding lines.
- Supply Concentration Risk:European soy protein isolate production clusters in Benelux processing facilities, creating single-point vulnerability for continent-wide formulation supply.
- Allergen Disclosure Friction:Cross-border soy allergen labeling requirements under FDA and EMA frameworks impose compliance complexity for multi-market exporters.
Strategic Opportunities
- Direct-to-Consumer Subscription Models:Online retailers bypass traditional intermediary margins, enabling margin capture for specialized soy dessert assortments.
- China SAMR Plant-Based Standards:China's national food safety regulator creates regulatory clarity for additive limits, opening formulation pathways for export-oriented manufacturers.
- Precision Fermentation Convergence:Integration of microbial protein production with traditional soy processing collapses cost differentials against conventional dairy proteins.
Industry Challenges
- Refrigerated Supply Chain Capex:Cold-chain infrastructure requirements for soy yogurt distribution demand capital deployment that mid-scale entrants struggle to fund.
- Functional Stabilizer Sourcing:Securing consistent hydrocolloid supply for texture mimicry in custard applications faces lead-time volatility from Asian suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Soy Desserts Market |
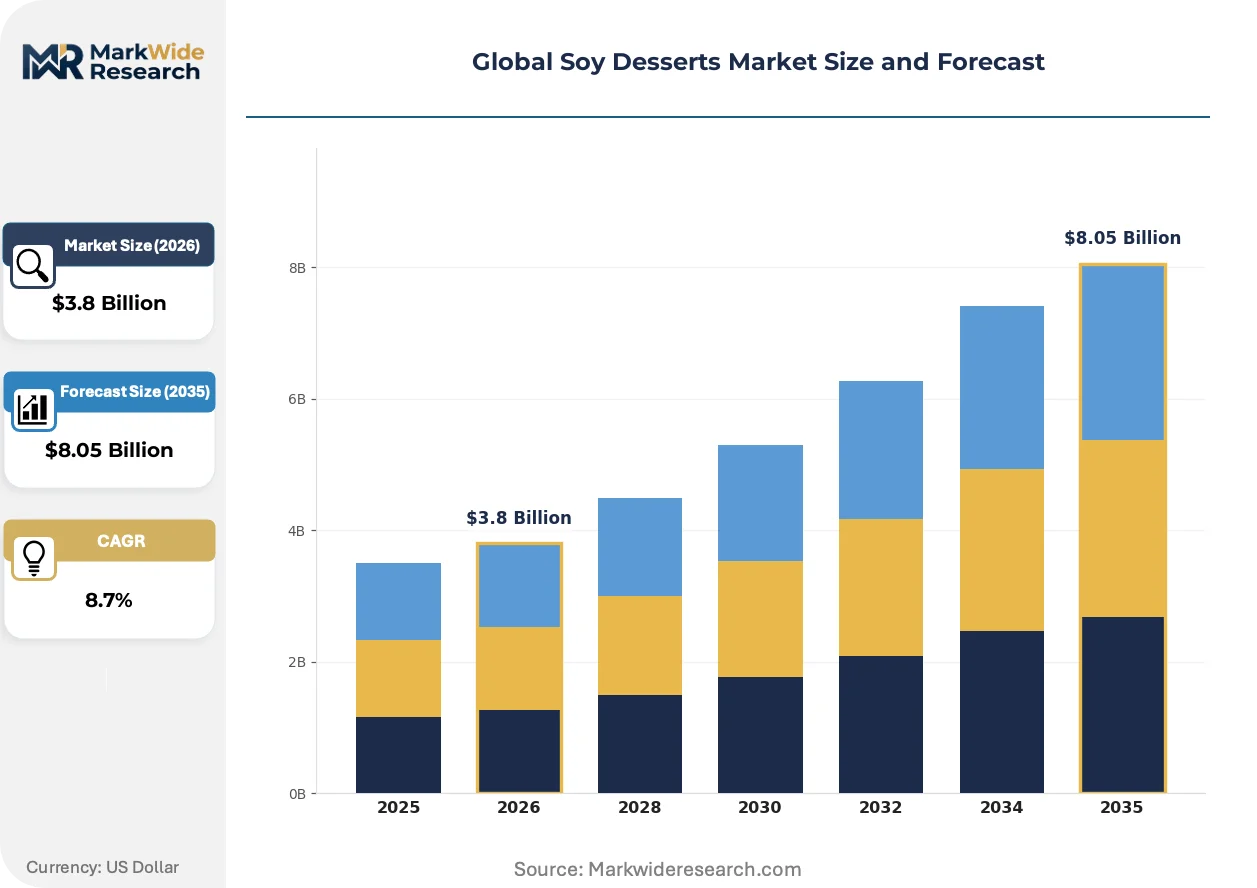
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Ice Cream, Soy Pudding, Soy Yogurt, Soy Custard End User: Health-Conscious Consumers, Vegans, Lactose Intolerant Individuals, Fitness Enthusiasts Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Stores Packaging Type: Glass Jars, Plastic Cups, Tetra Packs, Bulk Packaging |
| Companies Covered | The Hershey Company, Danone S.A., The Hain Celestial Group, Inc., AFC American Food Company, ADM, NOW Foods, Kerry Group plc, Alpro, Trader Joe's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Soy Desserts Market Strategic Shifts
Formulation science and distribution architecture are undergoing parallel transformation as protein functionality advances and channel economics restructure access patterns for plant-based desserts.
Precision fermentation platforms are collapsing the cost gap between soy isolates and animal-derived proteins. Fitness enthusiasts and athletic nutrition buyers are adopting these reformulated products at accelerating velocity. This cost compression enables price parity positioning against conventional dairy desserts in mass retail.
REACH chemical safety standards and the EU Green Deal sustainability frameworks are reshaping stabilizer and additive approval pathways for European soy dessert manufacturers. Industrial consequence includes reformulation cycles to eliminate palm-derived emulsifiers and synthetic hydrocolloids. Premium organic pudding lines in Germany and France are responding fastest, securing early shelf-space advantages.
Subscription-based replenishment models are displacing conventional grocery replenishment for specialized soy dessert assortments. Direct-to-consumer channels capture margin previously allocated to distributor and retailer intermediaries. This behavioral shift concentrates in urban UK and German markets where cold-chain logistics density supports reliable home delivery.
Global Soy Desserts Market Segmentation
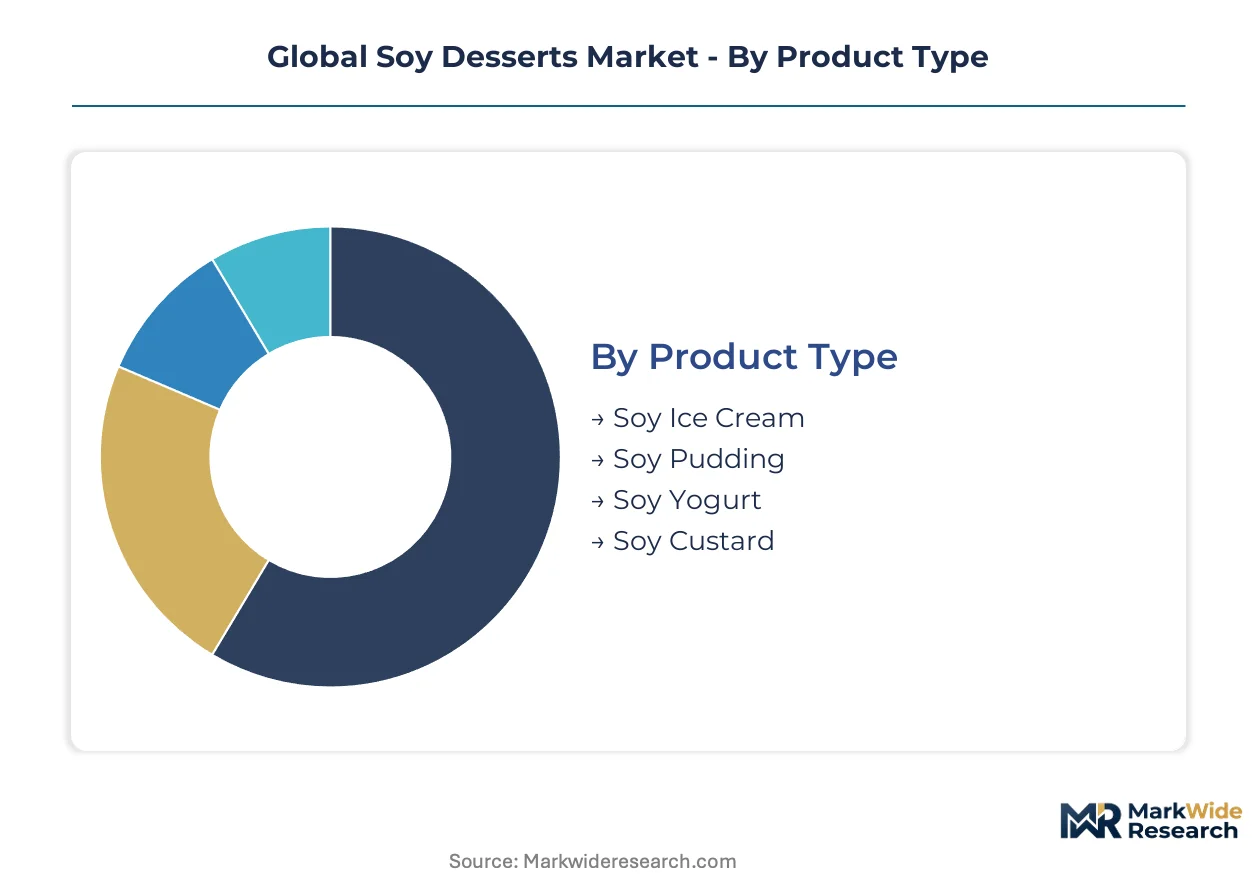
Soy dessert manufacturers align formulation architecture and distribution investments against distinct consumption occasions and buyer motivations. Segmentation clarity determines cold-chain deployment, protein fortification levels, and packaging format selection across frozen, refrigerated, and ambient categories.
Product Type:
Formulation complexity spans frozen indulgence through probiotic breakfast applications, each demanding specific protein modification and stabilizer systems.
- Soy Yogurt:Fermented formulations with live cultures achieve 3-4% protein content through enzymatic hydrolysis of soy milk base. Breakfast occasion penetration in Germany and the UK drives refrigerated distribution density, with Danone and Alpro leveraging established dairy cold-chain infrastructure for mainstream retail placement.
- Soy Ice Cream:High-fat frozen desserts require extrusion-textured soy protein isolates combined with palm-free emulsifier systems under REACH compliance. Fitness enthusiasts in urban UK markets adopt protein-fortified variants as post-workout recovery formats, compressing price premiums against dairy alternatives.
- Soy Pudding:Shelf-stable custard-style formulations employ UHT processing and modified starch stabilizers for ambient distribution. The Hain Celestial Group commands premium organic-certified positioning through health food store channels.
- Soy Custard:Refrigerated dessert cups with egg-replacer functionality target lactose-intolerant consumers seeking traditional dessert textures. Japanese METI functional food certification pathways support elevated protein claim positioning for athletic nutrition segments.
Established volume favors soy yogurt; emerging adoption favors soy ice cream.
End User:
Buyer archetypes diverge sharply on protein threshold requirements, ethical positioning tolerance, and price sensitivity.
- Fitness Enthusiasts:Athletic nutrition buyers prioritize protein density above taste mimicry, accepting texture trade-offs for 6-8% protein content. Japan's functional food certification and German sports nutrition retail networks concentrate demand for performance-positioned formats.
- Lactose Intolerant Individuals:Medical necessity drives purchase with lower price elasticity and sustained loyalty to verified dairy-free supply chains. China's SAMR allergen disclosure standards and FDA labeling requirements shape product access and trust architecture.
- Health-Conscious Consumers:Wellness-oriented buyers respond to organic certification and clean-label stabilizer systems, paying shelf-space premiums in curated retail environments.
- Vegans:Ethical alignment demands exclude all animal derivatives including bone-char filtered sugars and dairy-crossover manufacturing facilities, limiting supplier qualification pools.
Volume concentration sits with lactose-intolerant households; margin expansion sits with fitness-oriented buyers.
Distribution Channel:
Channel economics determine margin capture, temperature control investment, and customer relationship depth.
- Online Retailers:Direct-to-consumer subscription models bypass distributor and retailer margin layers, enabling specialized assortment curation for urban German and UK markets with reliable cold-chain logistics density.
- Supermarkets:Mass retail placement demands price parity positioning and refrigerated section negotiation against incumbent dairy desserts, favoring manufacturers with scale economies.
- Health Food Stores:Curated specialty assortments sustain highest per-unit pricing power through organic certification and clean-label differentiation, though volume throughput remains constrained.
- Specialty Stores:Asian grocery and vegan boutique channels serve diaspora communities and ethical early adopters with import-dependent supply chains facing customs clearance friction.
Margin architecture favors health food stores; volume scaling favors supermarket penetration.
Packaging Type:
Material selection balances sustainability positioning, shelf-life extension, and cold-chain thermal performance.
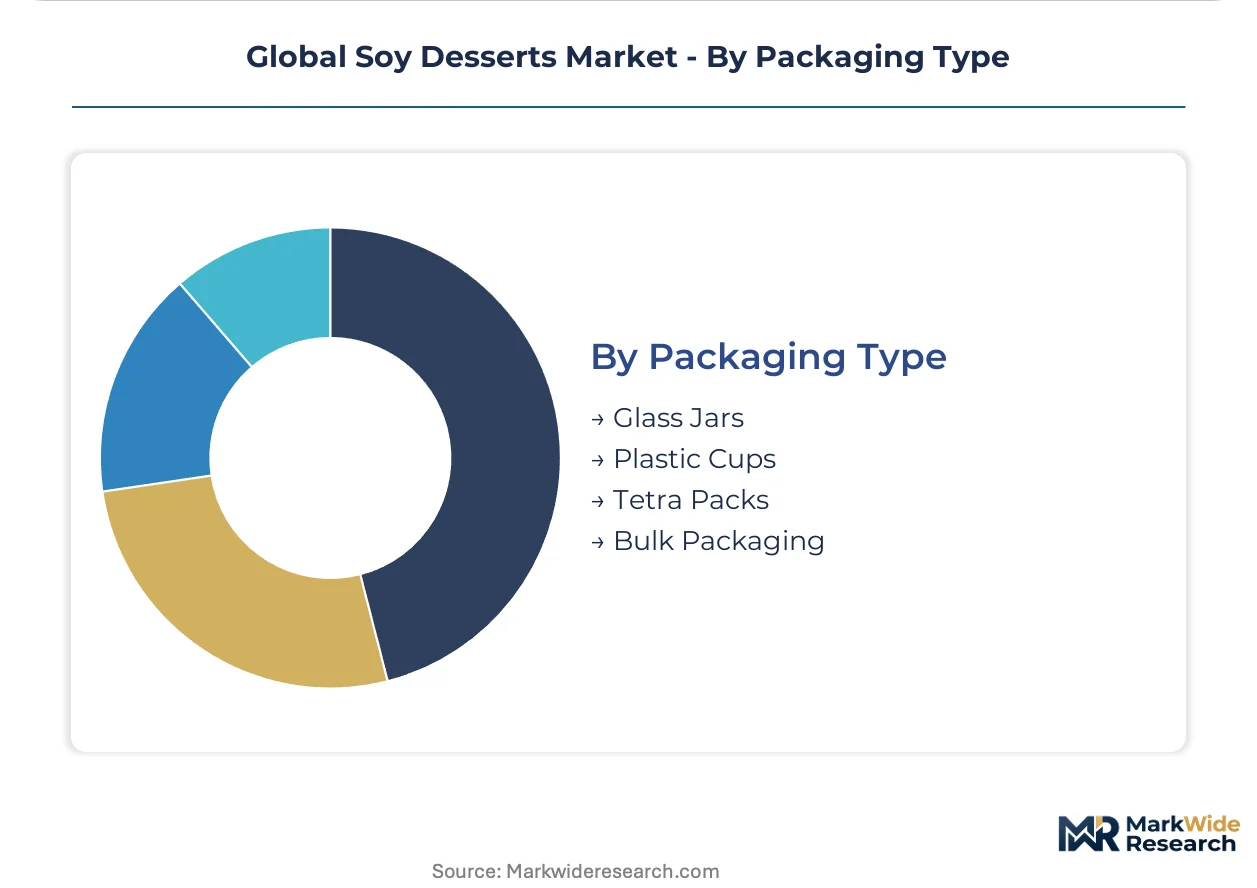
- Plastic Cups:Polypropylene single-serve formats dominate refrigerated soy yogurt with lightweight logistics and transparent product visibility, though EU Green Deal frameworks are forcing rPET and bio-based material transitions.
- Tetra Packs:Aseptic carton systems enable ambient distribution of soy pudding with extended shelf life, reducing refrigeration capex for manufacturers targeting emerging market expansion.
- Glass Jars:Premium organic lines leverage recyclable positioning and premium shelf aesthetics, though weight and breakage rates elevate logistics costs and limit e-commerce viability.
- Bulk Packaging:Foodservice and ingredient supply formats serve commercial bakery and food manufacturing customers with tote and drum configurations, bypassing retail margin structures entirely.
Sustainability compliance favors glass and carton innovation; cost efficiency favors plastic and bulk formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness enthusiasts and lactose-intolerant households concentrate demand in Germany, Japan, and the United States, where cold-chain infrastructure and functional food certification pathways enable premium soy dessert positioning. Regulatory frameworks in China and the UK are reshaping formulation standards and distribution economics.
United States
FDA labeling requirements for plant-based dairy alternatives are forcing reformulation cycles among refrigerated soy yogurt manufacturers. The agency's updated standards under the Federal Food, Drug, and Cosmetic Act mandate protein content disclosure and allergen prominence. Greater Boston and the Pacific Northwest host the densest health food store networks, where organic-certified pudding lines command shelf-space premiums.
Germany
Alpro and Danone have built continent-leading retail penetration for soy yogurt through dedicated plant-based manufacturing facilities in the Benelux corridor. REACH chemical safety standards and the EU Green Deal are eliminating palm-derived emulsifiers from frozen dessert formulations. Bavaria's cold-chain logistics density supports reliable home delivery subscription models for urban fitness enthusiasts.
Japan
METI functional food certification pathways incentivize elevated protein claims targeting athletic nutrition buyers. The ministry's soy protein utilization programs accelerate adoption of 6-8% protein fortified custards. Kanto region manufacturers cluster around Tokyo's sports nutrition retail networks, where post-workout recovery formats compress price premiums against dairy alternatives.
China
SAMR enforcement of GB standards for plant-based food safety creates regulatory clarity for additive limits in soy pudding exports. The national food safety regulator's additive thresholds are opening formulation pathways for international manufacturers targeting urban health-conscious consumers. Yangtze River Delta processing facilities concentrate soy protein isolate production for continent-wide supply.
United Kingdom
Alpro anchors market presence through dedicated manufacturing infrastructure serving breakfast occasion penetration. EMA nutrition and health claims regulation shapes product positioning for probiotic soy yogurt lines. London and Southeast England sustain the highest direct-to-consumer subscription velocity, where online retailers bypass traditional intermediary margins.
Global Soy Desserts Market Competitive Environment
Channel-controlling players compete with product-specialist players across refrigerated, frozen, and shelf-stable categories. Danone S.A. leverages scale economies in European retail distribution while The Hain Celestial Group, Inc. occupies premium organic positioning. Three archetypes dominate: multinational dairy conglomerates with plant-based extensions, pure-play organic specialists, and private-label retailers. Competitive moves concentrate on refrigerated supply chain partnerships and precision fermentation technology licensing.
Among multinational dairy conglomerates with plant-based extensions, Danone S.A. exemplifies channel-control strategy through refrigerated infrastructure deployment. The Hain Celestial Group, Inc. represents the organic-certified specialist archetype commanding health food store premiums. Alpro occupies a position bridging mass retail penetration and dedicated plant-based manufacturing commitment.
| Leading Market Players |
|---|
| The Hershey Company |
| Danone S.A. |
| The Hain Celestial Group, Inc. |
| AFC American Food Company |
| ADM |
| NOW Foods |
| Kerry Group plc |
| Alpro |
| Trader Joe's |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta processing clusters in China concentrate soy protein isolate capacity, translating upstream fermentation scale into downstream pricing leverage for export-oriented pudding manufacturers targeting European health food channels.
Pricing Analysis
Cost-plus contracts indexed to Brazilian non-GMO soybean futures dominate procurement between Argentinian crushing facilities and European organic-certified pudding lines. Three-tier pricing structure across premium organic, standard refrigerated, and economy shelf-stable levels tracks certification grade and cold-chain investment intensity. Price erosion runs through standard-tier soy yogurt as Danone and Alpro deploy scale economies in German mass retail. Fitness enthusiasts show lowest price sensitivity, accepting protein fortification premiums that lactose-intolerant households resist.
Supply Chain Analysis
Upstream feedstock flows from Brazil, Argentina, and the United States into Benelux extrusion facilities, creating geographic concentration at both origin and processing nodes. Soy protein isolates, palm-free emulsifier systems, and modified starch stabilizers constitute critical input dependencies. Single-source vulnerability sits with hydrocolloid supply from Asian suppliers facing REACH compliance reformulation cycles. Distribution runs through refrigerated logistics partnerships for yogurt, ambient carton networks for pudding, and direct-to-consumer cold-chain subscriptions in urban UK and German markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation adoption sits as an early-cycle expansion story. Protein cost compression accelerates formulation parity against dairy alternatives, widening addressable demand beyond vegan niches into mainstream breakfast and recovery occasions.
For Market Incumbents: Harden refrigerated supply chain partnerships against precision fermentation entrants achieving dairy-comparable taste profiles. Secure backward integration into non-GMO soybean origination to buffer Brazilian harvest volatility squeezing organic pudding margins. Prioritize METI functional food certification investment in Japan before athletic nutrition positioning saturates. For New Entrants and Emerging Players: Pursue white-space penetration in Chinese SAMR-compliant soy pudding exports, where regulatory clarity on additive limits remains underexploited by Western manufacturers. Target UK direct-to-consumer subscription velocity with specialized probiotic assortments bypassing supermarket slotting fee barriers. Anchor go-to-market strategy through health food store curation before scaling into mass retail negotiation. For Investors and Strategic Acquirers: Long-term, this sits as a functional food infrastructure play because cold-chain density and fermentation technology licensing determine margin capture more than brand equity alone. Acquisition targets should cluster around precision fermentation platforms with soy-dairy hybrid protein capabilities. Watch Japan's functional food certification queue depth as the signal for athletic nutrition segment maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Licensing | Microbial protein production collapses cost differentials against conventional dairy isolates. |
| Refrigerated Distribution Partnership | Cold-chain density in Germany and UK determines breakfast occasion penetration velocity. |
| Organic Certification Investment | EU Green Deal compliance secures premium shelf placement in health food channels. |
| Direct-to-Consumer Subscription Launch | Bypassing retailer margin layers captures value in urban fitness enthusiast segments. |
| Functional Food Regulatory Pathway | METI certification enables elevated protein claims targeting athletic nutrition buyers. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with plant-based R&D directors, refrigerated logistics operators, health food store category buyers, and METI certification consultants; and secondary validation against FDA labeling guidance documents, EMA nutrition claim registers, SAMR GB standard filings, and trade flow data from Brazilian and Argentinian customs authorities. Bottom-up volume triangulation against top-down value estimates anchored forecast reliability.
Forecast inputs considered product type segmentation across frozen, refrigerated, and shelf-stable formats; end-user archetypes spanning fitness enthusiasts, lactose-intolerant households, and ethical vegans; and distribution channel economics including supermarket slotting structures and subscription margin capture. CAGRs derived from elasticity modeling against protein price parity thresholds and cold-chain infrastructure deployment rates across the analysis window. Precision fermentation cost curves and METI certification queue dynamics supplied industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates or EU energy costs for refrigerated logistics would shift the trajectory. Forecasts reflect documented assumptions on protein functionality advancement and regulatory harmonization timelines. Cross-checking against Nielsen retail audit data for soy yogurt velocity in German supermarkets is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Yogurt Alternative Market
Dairy Alternatives
Protein Ice Cream Market
Dairy Alternatives
A2 Milk Powder Market
Dairy Alternatives
Global Milk Replacers Market
Dairy Alternatives
North America Non-Dairy Milk Market
Dairy Alternatives
Walnut Milk Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
Coconut Cream Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
Non-Dairy Creamer Market
Dairy Alternatives
Savory Yogurt Foods Market
Dairy Alternatives
Non-Dairy Ice Cream Market
Dairy Alternatives
Coconut Milk Products Market
Dairy Alternatives
Europe Non-Dairy Milk Market
Dairy Alternatives
Hempseed Milk Market
Dairy Alternatives
United States Oat Milk Market