
 Lactose Free Dairy Products Market | 2026-2036
Lactose Free Dairy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Lactose Free Dairy Products Market Outlook
The EU Green Deal is rebalancing dairy investment toward low-lactose processing infrastructure across member states. Nestlé S.A. leverages its enzymatic filtration capabilities to anchor premium positioning in European retail. Danone S.A. specializes in fermented lactose-free yogurt formats that sustain margins in competitive French and German markets. Arla Foods controls cooperative milk sourcing that extends its cost advantage in Scandinavian lactose-free milk production.
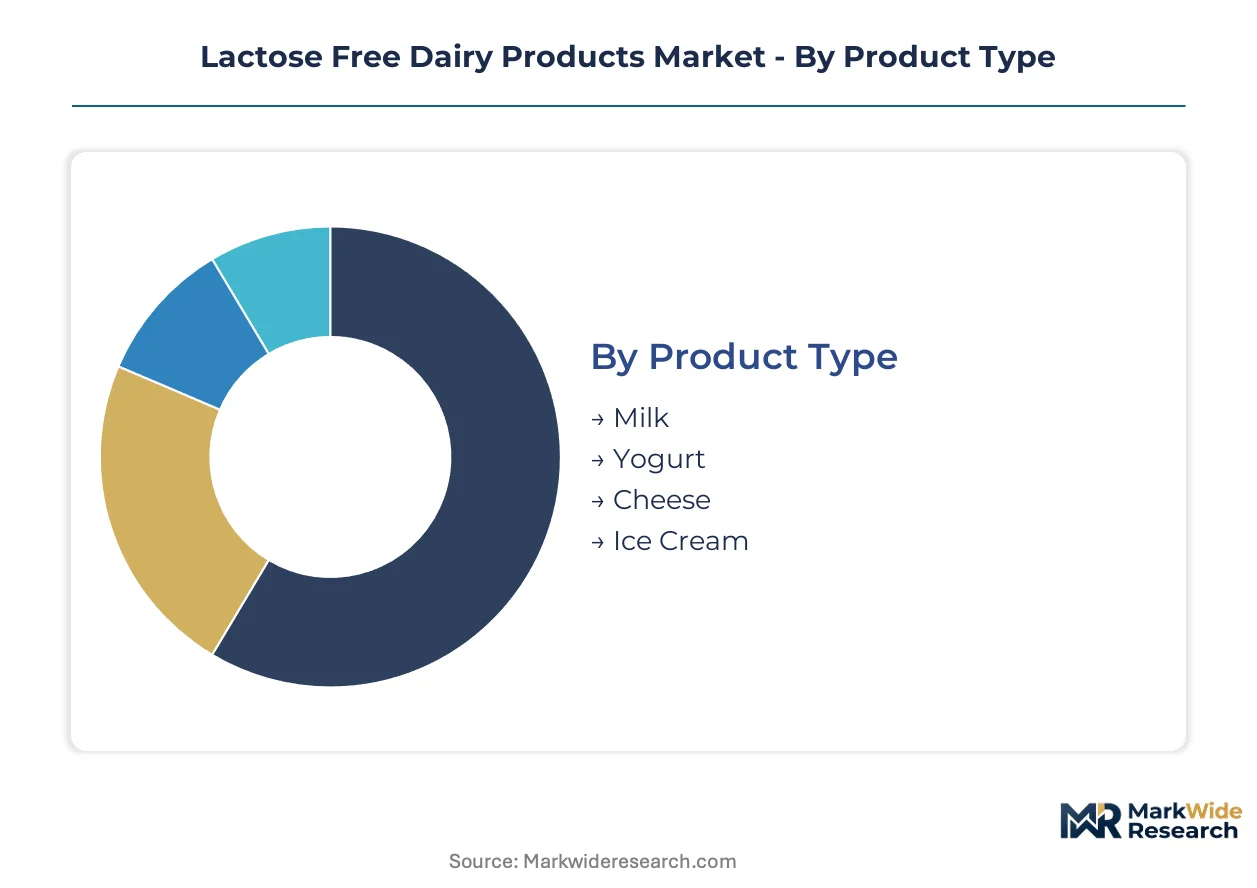
Lactose free dairy products are conventional dairy items treated with lactase enzyme to hydrolyze lactose into glucose and galactose, yielding sweetness equivalent to roughly 30% added sugar reduction while maintaining protein and calcium profiles. Milk dominates volume as the entry category for newly diagnosed intolerance consumers, while yogurt captures higher margins through probiotic positioning and premium pricing in health-focused retail channels. Ice cream represents the fastest-growing product type as formulation advances eliminate crystallization defects that previously limited sensory acceptance.
EFSA governs health claim substantiation for lactose-free labeling across Europe, while FDA enforces allergen disclosure thresholds that shape product formulation in the United States. BIS certification requirements in India create compliance barriers for imported specialized dairy, redirecting investment toward domestic enzymatic processing partnerships. Stakeholders must monitor evolving enzyme supplier consolidation and regional dairy quota adjustments that will determine cost-competitive positioning in the next planning cycle.
Market Dynamics
Enzymatic hydrolysis technology is compressing production costs while EU Green Deal funding redirects dairy infrastructure toward low-lactose processing capacity. This structural shift is redrawing competitive positioning between legacy fluid milk processors and specialized enzyme suppliers.
Growth Catalysts
- EU Green Deal subsidies:Member state dairy cooperatives are accessing transition financing to retrofit existing plants with lactase filtration systems, accelerating capacity expansion in Germany and France.
- Food service menu expansion:North American restaurant chains are adding dedicated lactose-free sections as intolerance diagnosis rates climb among 25-45 year-old consumers.
- Enzyme supplier consolidation:Novozymes and DSM-Firmenich are integrating downstream into dairy partnerships, securing captive demand for their lactase portfolios.
Market Restraints
- Fresh milk input cost volatility:Scandinavian dairy quotas and New Zealand weather patterns create raw material price swings that squeeze processor margins.
- EFSA health claim substantiation:The European regulator's strict evidentiary requirements for lactose-free labeling delay product launches by 18-24 months.
- Plant-based milk substitution:Oat and almond alternatives are capturing price-sensitive consumers in urban Australian and US coastal markets.
Strategic Opportunities
- Indian domestic processing partnerships:BIS certification barriers for imports are forcing multinationals to joint-venture with local enzymatic processors in Maharashtra and Gujarat.
- Probiotic yogurt convergence:Fermentation technology combined with lactase treatment is opening premium positioning in German and French pharmacy retail channels.
- Direct-to-subscription delivery:Specialized e-commerce platforms are bypassing conventional grocery slotting fees to reach diagnosed intolerance households in Sydney and Melbourne.
Industry Challenges
- Enzyme optimization expertise scarcity:Food technologists with simultaneous dairy chemistry and bioprocessing credentials command premium compensation in Copenhagen and Rotterdam hiring markets.
- Legacy system integration friction:Retrofitting continuous-flow lactase reactors into batch-oriented cheese plants requires custom engineering that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactose Free Dairy Products Market |
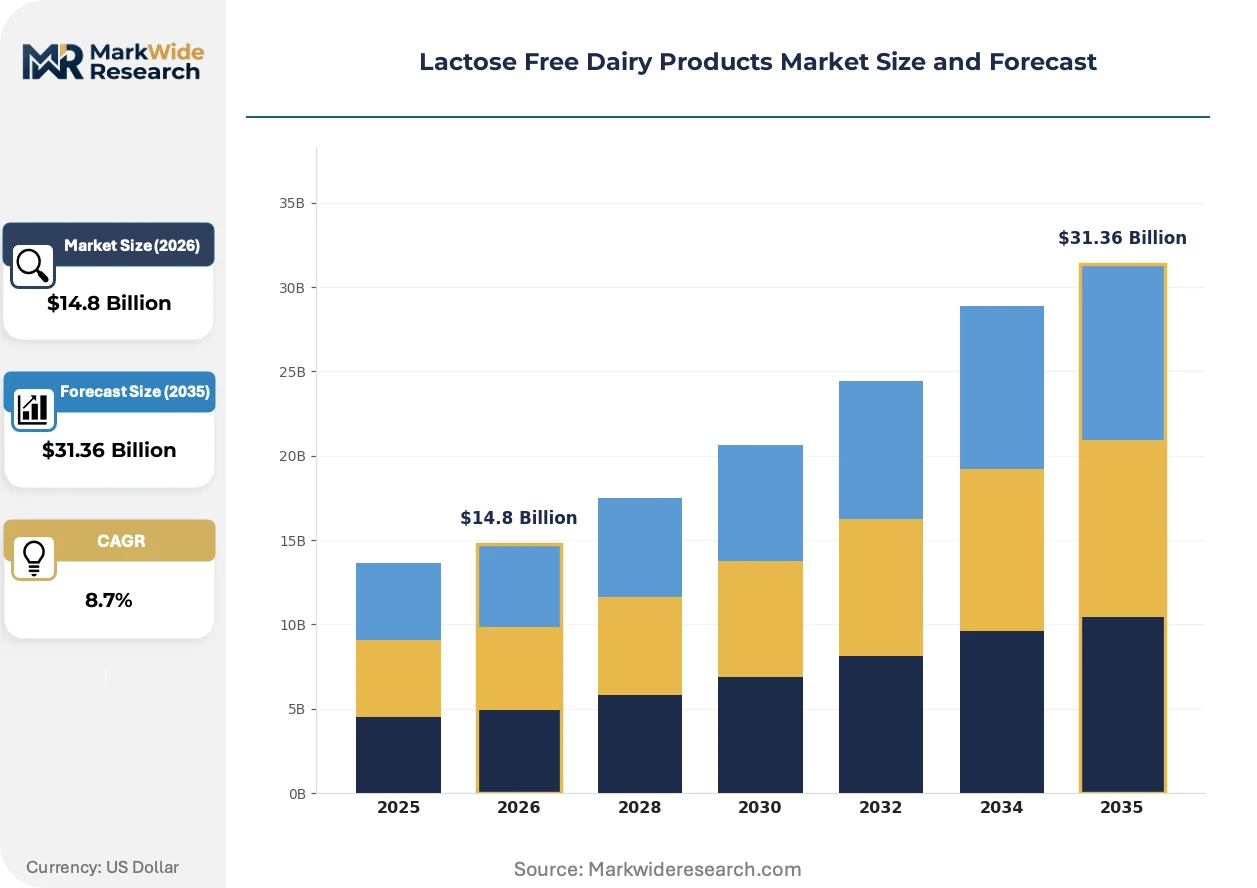
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Yogurt, Cheese, Ice Cream Form: Liquid, Powdered, Pouch, Spoonable End User: Households, Food Service, Retailers, Institutions Distribution Channel: Online, Supermarket, Convenience Store, Wholesaler |
| Companies Covered | Nestlé S.A., Danone S.A., Arla Foods, The Coca-Cola Company, Fonterra Co-operative Group, Saputo Inc., Organic Valley, Valio Ltd., General Mills Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactose Free Dairy Products Market Strategic Shifts
Continuous enzymatic processing is displacing batch hydrolysis across European dairy infrastructure. This shift is compressing unit economics while enabling real-time quality monitoring that reduces sweetness variation in finished products.
Immobilized enzyme reactor technology is absorbing capital investment from Danish and Dutch dairy cooperatives seeking throughput gains. Arla Foods and FrieslandCampina are piloting fixed-bed lactase systems that cut enzyme consumption by half. The technology is absorbing market share from traditional stirred-tank processes by eliminating filtration steps and reducing water usage.
EFSA's updated guidance on lactose-free health claims is tightening evidentiary standards for European processors. The regulation now requires clinical tolerance studies rather than analytical lactose threshold testing. German and French yogurt manufacturers are responding by funding proprietary digestion trials to secure premium positioning.
Subscription-based replenishment models are displacing conventional grocery purchasing among diagnosed intolerance consumers in the United States. Direct-to-consumer platforms are capturing recurring revenue from households managing irritable bowel syndrome and Crohn's disease. This channel shift is most visible in California and New York metro areas where specialized nutrition e-commerce penetration exceeds national averages.
Lactose Free Dairy Products Market Segmentation
Consumer diagnosis patterns and enzymatic processing economics create divergent growth trajectories across product formats. Each segment category reflects distinct upgrade cycles—from household pantry rotation to food service equipment retrofitting—that reshape competitive priorities for processors and retailers.
Product Type:
Upgrade cycles vary sharply by category, with fluid milk replacement driving household trial and premium formats capturing margin expansion.
- Milk:Fluid lactose-free milk undergoes enzymatic hydrolysis to reduce lactose below 0.1% while preserving calcium and protein matrices. First-line demand concentrates among newly diagnosed intolerance consumers in Germany and the United States, where pharmacy-channel referrals accelerate trial rates. Shelf-stable UHT variants extend reach into Australian rural markets with limited cold-chain infrastructure.
- Ice Cream:Advanced cryoprotectant formulations now prevent lactose-hydrolyzed base crystallization, eliminating the sandy texture that previously limited acceptance. Premium positioning in French and Italian gelateria chains captures margin premiums from dessert-focused dining occasions. The segment climbs fastest as sensory parity with conventional ice cream achieves mainstream validation.
- Yogurt:Fermented lactose-free yogurts combine probiotic cultures with enzymatic treatment for dual-functional positioning in German pharmacy retail.
- Cheese:Aged hard cheeses naturally low in lactose compete with enzymatically treated soft varieties for sandwich and cooking applications.
Milk sits at the top of the volume ranking, with ice cream climbing the fastest.
Form:
Cost tier differentiation separates industrial-scale processing from premium convenience positioning.
- Liquid:Refrigerated cartons dominate household replenishment cycles in Scandinavian markets with established cold-chain density. Extended shelf-life variants reduce distribution frequency for remote Australian communities.
- Powdered:Spray-dried lactose-free milk powders serve food manufacturing and export markets where water weight elimination cuts logistics expenditure. Demand concentrates in Indian domestic processing partnerships requiring BIS-compliant intermediate inputs for reconstitution.
- Pouch:Flexible single-serve packaging captures on-the-go consumption in Japanese convenience retail channels.
- Spoonable:Cup-format yogurts and puddings target premium snacking occasions in French urban supermarkets.
Liquid form leads volume throughput, with powdered gaining share fastest in industrial applications.
End User:
Application-specific formulation requirements drive divergence between household taste optimization and food service operational efficiency.
- Households:Direct consumption purchases prioritize sensory familiarity and nutritional equivalence to conventional dairy. Subscription replenishment models in California and New York metro areas bypass conventional grocery slotting fees to capture recurring revenue from diagnosed intolerance households managing irritable bowel syndrome and Crohn's disease.
- Food Service:Restaurant and café operators require bulk-format stability and consistent frothing performance for coffee applications. North American chain expansion of dedicated lactose-free menu sections responds to climbing diagnosis rates among 25-45 year-old consumers.
- Retailers:Private-label sourcing demands cost-competitive enzymatic processing with flexible packaging formats.
- Institutions:Hospital and school nutrition programs require analytical certification of lactose thresholds below clinical reaction thresholds.
Households anchor volume demand, with food service expanding most quickly through menu diversification.
Distribution Channel:
Customer type stratification separates convenience-driven impulse from planned replenishment behaviors.
- Supermarket:Dedicated lactose-free dairy aisles in German and Australian retail chains drive category visibility and cross-selling to adjacent free-from segments. Planogram placement adjacent to conventional dairy reduces stigma while capturing comparison shoppers.
- Online:Direct-to-consumer platforms leverage subscription algorithms to predict replenishment timing for chronic condition management. Specialized nutrition e-commerce penetration exceeds national averages in Sydney and Melbourne metro areas.
- Convenience Store:Single-serve emergency purchases capture travelers and urban workers with unexpected intolerance symptoms.
- Wholesaler:Food service distributors aggregate demand for bulk lactose-free mozzarella and cream in Italian restaurant supply chains.
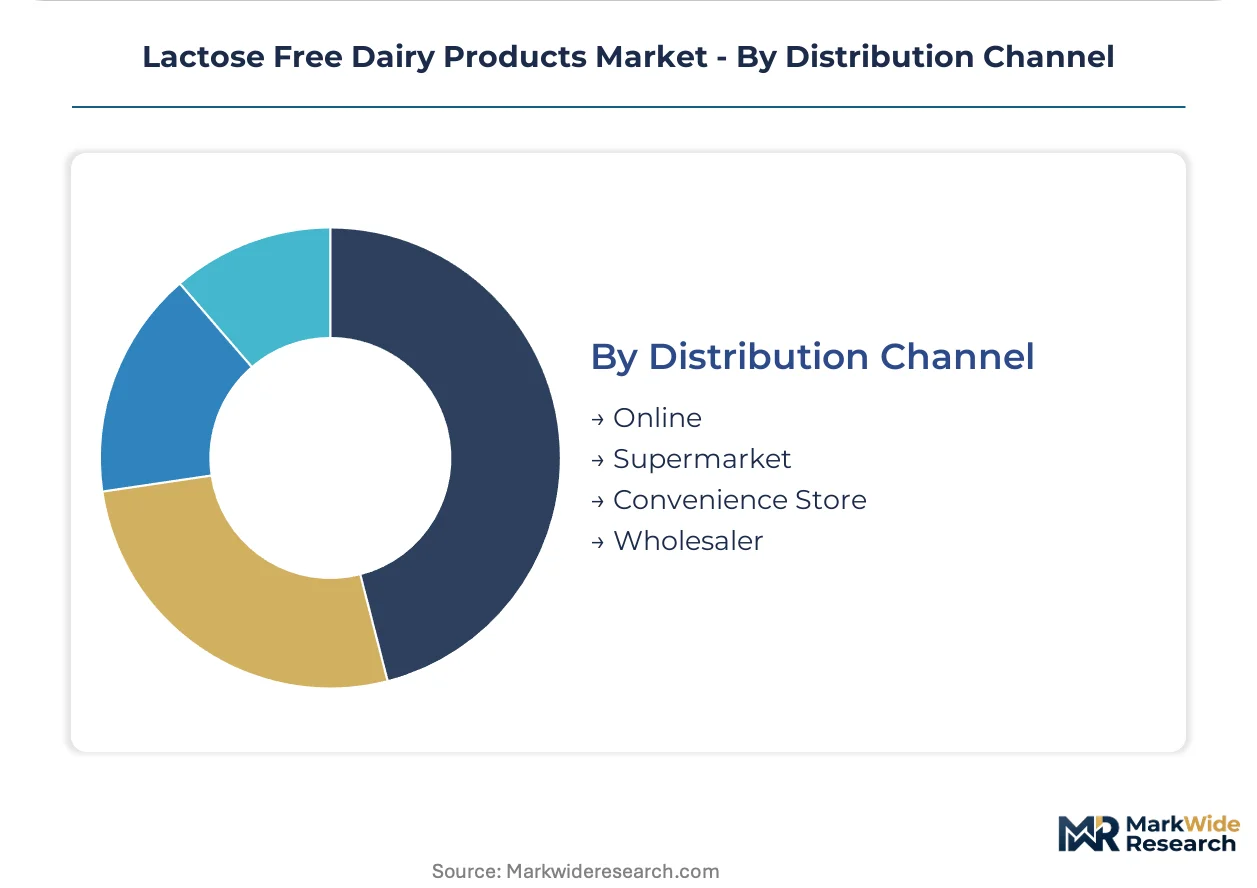
Supermarket channels dominate absolute volume, with online posting the steepest expansion trajectory through subscription conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The lactose-free dairy industry traces its commercial origins to Scandinavian cooperative systems in the 1980s, where enzymatic hydrolysis first achieved industrial scale. Swedish and Finnish dairy processors pioneered the lactase treatment protocols that now dominate global production standards.
United States
Pharmacy-channel diagnosis referrals accelerate household trial rates among newly intolerant consumers. FDA allergen disclosure thresholds shape formulation decisions for cross-border labeling compliance. California and New York metro areas host specialized nutrition e-commerce platforms that capture recurring subscription revenue from IBS and Crohn's disease households.
Germany
Retail penetration of dedicated lactose-free dairy aisles reaches deepest concentration in German supermarket chains. EU Green Deal transition financing retrofits existing plants with lactase filtration systems across Bavarian and North Rhine-Westphalian processing clusters. Frankfurt and Munich anchor pharmacy-retail convergence for probiotic yogurt positioning.
Australia
Shelf-stable UHT variants extend distribution into rural markets with limited cold-chain infrastructure. TGA labeling requirements align with EFSA standards for lactose threshold certification. Sydney and Melbourne direct-to-consumer platforms bypass conventional grocery slotting fees through subscription algorithms.
France
Fermented lactose-free yogurt formats sustain margin premiums in competitive pharmacy retail channels. ANSM and EFSA dual oversight tightens health claim substantiation timelines. Parisian and Lyonnaise gelateria chains drive premium ice cream adoption through advanced cryoprotectant formulations.
India
BIS certification barriers redirect multinational investment toward domestic enzymatic processing partnerships. FSSAI standards govern reconstituted milk powder inputs for lactose-free manufacturing. Maharashtra and Gujarat joint-ventures concentrate spray-dried powder production for industrial food manufacturing applications.
Lactose Free Dairy Products Market Competitive Environment
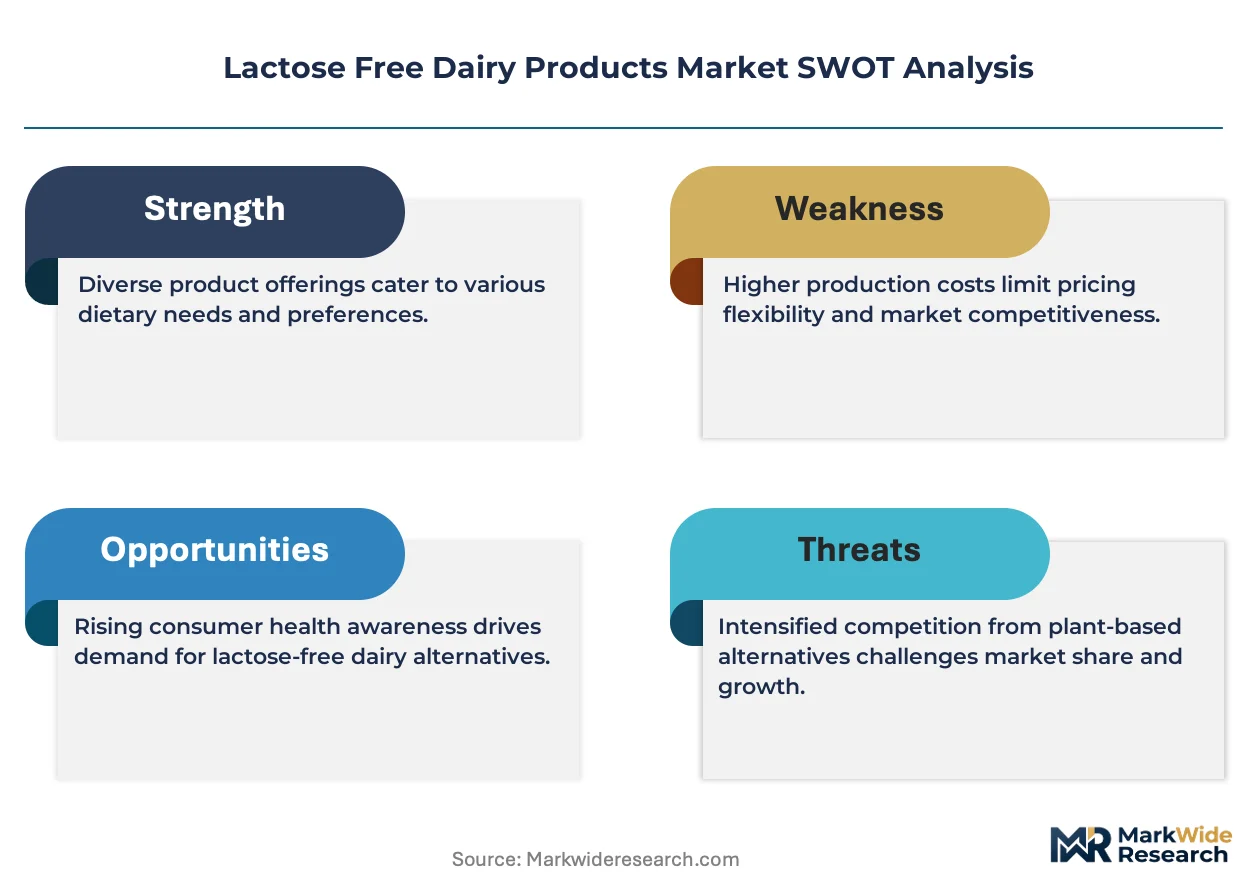
Premium-margin players sit above commodity-margin players across enzymatic processing sophistication and branded pharmacy-channel positioning. The vendor base clusters around three strategic archetypes: multinational dairy conglomerates with captive enzyme supply, cooperative systems with backward-integrated milk sourcing, and specialized enzyme suppliers integrating downstream into dairy partnerships. Dominant competitive moves include EU Green Deal-funded capacity retrofits and subscription-based direct-to-consumer channel bypass of conventional retail slotting.
Within the cooperative archetype, Arla Foods and Fonterra Co-operative Group exemplify milk-sourcing integration that compresses input cost volatility. Among publicly traded multinationals, Nestlé S.A. and Danone S.A. occupy positions spanning enzymatic filtration capabilities and fermented yogurt specialization. Valio Ltd. represents the Nordic-origin technical specialist segment that pioneered industrial-scale lactase treatment protocols.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Danone S.A. |
| Arla Foods |
| The Coca-Cola Company |
| Fonterra Co-operative Group |
| Saputo Inc. |
| Organic Valley |
| Valio Ltd. |
| General Mills Inc. |
| Others |
Value Chain & Pricing Dynamics
Global dairy commodity indices cascade through enzymatic processing tiers into three distinct price bands. Scandinavian cooperative sourcing anchors premium positioning while spot milk procurement in New Zealand and Germany feeds standard-tier production, with economy variants drawing from Indian domestic powder reconstitution partnerships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmacy-channel certified products from retail grocery lines and food service bulk formats. Price differentiation rests on lactose threshold certification grade and cold-chain delivery infrastructure investment. Pricing pressure stems from plant-based milk substitution in Australian and US coastal urban markets. Food service buyers exhibit highest price sensitivity due to operational cost compression, while subscription-direct households managing chronic conditions accept premium positioning.
Supply Chain Analysis
Direct-to-subscription platforms handle diagnosed intolerance household demand in California and New York metro areas. Supply concentrates in Denmark, Germany, and New Zealand for raw milk inputs, with enzymatic processing clusters in the Netherlands and France. The chain draws from lactase enzyme suppliers, fresh milk cooperatives, and cryoprotectant additive manufacturers. Single-source vulnerability in Novozymes and DSM-Firmenich enzyme supply creates concentration risk. Distribution runs through supermarket dedicated-aisle placement, online subscription algorithms, and food service wholesale aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic hydrolysis cost compression and probiotic yogurt premium-tier expansion create margin expansion runway for positioned players. Subscription-channel bypass of grocery slotting fees accelerates cash conversion for early movers.
For Market Incumbents: Deepen backward integration into captive lactase enzyme supply or secure long-term offtake agreements with Novozymes and DSM-Firmenich to defend against supplier consolidation pressure. Expand continuous-flow reactor retrofit capacity in Bavarian and North Rhine-Westphalian processing clusters to capture EU Green Deal transition financing before allocation windows close. For New Entrants and Emerging Players: Pharmacy retail distributors in Frankfurt, Munich, and Paris present the most penetrable channel for probiotic yogurt convergence products. Target direct-to-subscription platform partnerships in Sydney and Melbourne where specialized nutrition e-commerce penetration exceeds national benchmarks. Lead with irritable bowel syndrome and Crohn's disease household segmentation to secure recurring revenue anchoring. For Investors and Strategic Acquirers: Consolidation pressure builds where enzyme optimization expertise scarcity in Copenhagen and Rotterdam hiring markets constrains scaling for mid-tier processors. Five-to-ten year viability favors cooperative systems with backward-integrated milk sourcing or multinationals with captive filtration capabilities. Watch for EFSA health claim substantiation timeline compression as inflection signal for premium positioning access.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Enzyme Reactor Retrofit | EU Green Deal financing accelerates throughput gains in German and Dutch dairy cooperatives. |
| Direct-to-Subscription Launch | California and New York metro platforms bypass conventional grocery slotting fee structures. |
| Probiotic Yogurt Convergence | German pharmacy retail channels sustain margin premiums through dual-functional positioning. |
| Domestic Processing Partnership | Maharashtra and Gujarat joint-ventures overcome BIS certification barriers for multinational entry. |
| Immobilized Enzyme Technology Pilot | Arla Foods and FrieslandCampina cut lactase consumption by half in fixed-bed systems. |
Study Parameters
Bottom-up household and food service demand modeling reconciled against top-down enzymatic processing capacity tracking forms the analytical core of this study. Primary interviews with dairy cooperative procurement directors, enzyme supplier technical account managers, pharmacy retail category buyers, food service chain menu development leads, and regulatory affairs specialists at EFSA and FDA informed demand assumptions. Secondary validation drew from EU dairy production statistics, FDA allergen disclosure filings, BIS certification registries, and Australian TGA labeling guidance documents.
Historical trendline analysis of enzymatic processing adoption rates and lactose-free product penetration curves established baseline growth parameters across the projection horizon. The analytical framework models volume and value outputs through product type, form, end user, and distribution channel segmentation dimensions, with regional regulatory cluster overlays for Europe, North America, and Asia-Pacific. CAGRs derive from elasticity-adjusted demand curves incorporating diagnosis rate trajectories and food service menu expansion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal funding allocation shifts, enzyme supplier merger integration execution, and plant-based milk substitution acceleration in urban coastal markets. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Germany Casein and Caseinates Market
Dairy Products
Low Fat Cheese Market
Dairy Products
India Milk Protein Market
Dairy Products
Qatar Dairy Products Market
Dairy Products
United States Camel Dairy Market
Dairy Products
Evaporated Milk Market
Dairy Products
Goat Milk Market
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
Non-GMO Yogurt Market
Dairy Products
Argentina Whey Protein Market
Dairy Products
Drinkable Yogurt Market
Dairy Products
Reduced Lactose Whey Market
Dairy Products
Citrus Yogurt Market
Dairy Products
Ready-To-Use Cheese Market
Dairy Products
Mexico Whey Protein Market
Dairy Products
Lactic Butter Market