
 Lactose Market | 2026-2036
Lactose Market Size, Share, and Industry Trends Forecast 2026-2036
Lactose Market Analysis
Capital-intensity divergence between membrane filtration-equipped whey processors and conventional crystallization operators is bifurcating competitive economics in lactose production. FrieslandCampina leverages integrated dairy streams across Dutch and German facilities to sustain cost advantages in pharmaceutical-grade output. MEGGLE GmbH & Co. KG anchors its position through specialized milling and sieving capabilities for inhalation-grade specifications. Hilmar Cheese Company dominates whey sourcing from California's Central Valley cheese production, extending volume security that smaller fractionation rivals cannot replicate.
Lactose is a disaccharide carbohydrate extracted from whey permeate through crystallization, refining, and drying processes, yielding products with specified particle size distributions and residual protein content below defined thresholds for pharmaceutical compliance. It functions primarily as a filler-binder in tablet formulation, a carrier in dry powder inhalers, and a standardizing agent in food applications. Pharmaceutical end users command premium positioning due to stringent purity requirements, while food and beverage applications occupy higher volume but compressed margin tiers. Lactose monohydrate leads product type demand because of its established compatibility with direct compression tableting, whereas spray-dried lactose represents the fastest-expanding category as inhalation drug delivery grows.
FDA pharmaceutical excipient guidelines, EMA monograph standards, and REACH chemical registration requirements collectively determine market access and pricing stratification across supplier tiers. These frameworks enforce residual protein limits, microbial specifications, and traceability documentation that smaller whey processors struggle to satisfy. Stakeholders must monitor evolving pharmacopeial harmonization between USP-NF and EP standards, as divergence in particle size acceptance criteria could fragment supplier qualification pools and reshape sourcing strategies for multinational drug manufacturers.
Market Dynamics
Pharmaceutical-grade specification tightening is fragmenting supplier qualification pools, as membrane filtration investments separate capital-rich whey processors from crystallization-only operators unable to meet residual protein thresholds.
Growth Catalysts
- Inhalation-grade lactose demand:Dry powder inhaler formulation expansion in respiratory therapeutics is pulling specialized particle-size production capacity.
- REACH registration compliance:European chemical safety documentation requirements are filtering out non-compliant whey processors and consolidating qualified supplier bases.
- India pharmaceutical manufacturing:Domestic tablet binder and nutraceutical filler demand is accelerating import substitution for pharmaceutical-grade supply.
Market Restraints
- Whey permeate input volatility:Cheese production cyclicality in California and the Netherlands concentrates raw material risk with limited geographic diversification.
- Membrane filtration capex barriers:Ultrafiltration and nanofiltration equipment investments exceed crystallization-only facility upgrade paths, freezing mid-tier processor expansion.
- Lactose intolerance substitution:Galacto-oligosaccharides and maltodextrin displacement in food applications compresses standard-grade pricing power.
Strategic Opportunities
- Direct compression tableting expansion:Lactose monohydrate compatibility with high-speed pharmaceutical manufacturing lines opens formulation partnerships with generic drug producers.
- CDSCO pharmaceutical excipient harmonization:India's alignment with USP-NF and EP standards creates regulatory runway for domestic qualification of export-grade production.
- Spray-dried lactose inhalation carriers:Particle engineering for pulmonary drug delivery represents uncontracted capacity for specialized milling investments.
Industry Challenges
- Pharmacopeial auditor scarcity:Qualified validation personnel for USP-NF and EP dual certification are concentrated with incumbent European suppliers.
- Batch traceability system integration:Legacy whey processing facilities face ERP reconfiguration costs to meet pharmaceutical documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactose Market |
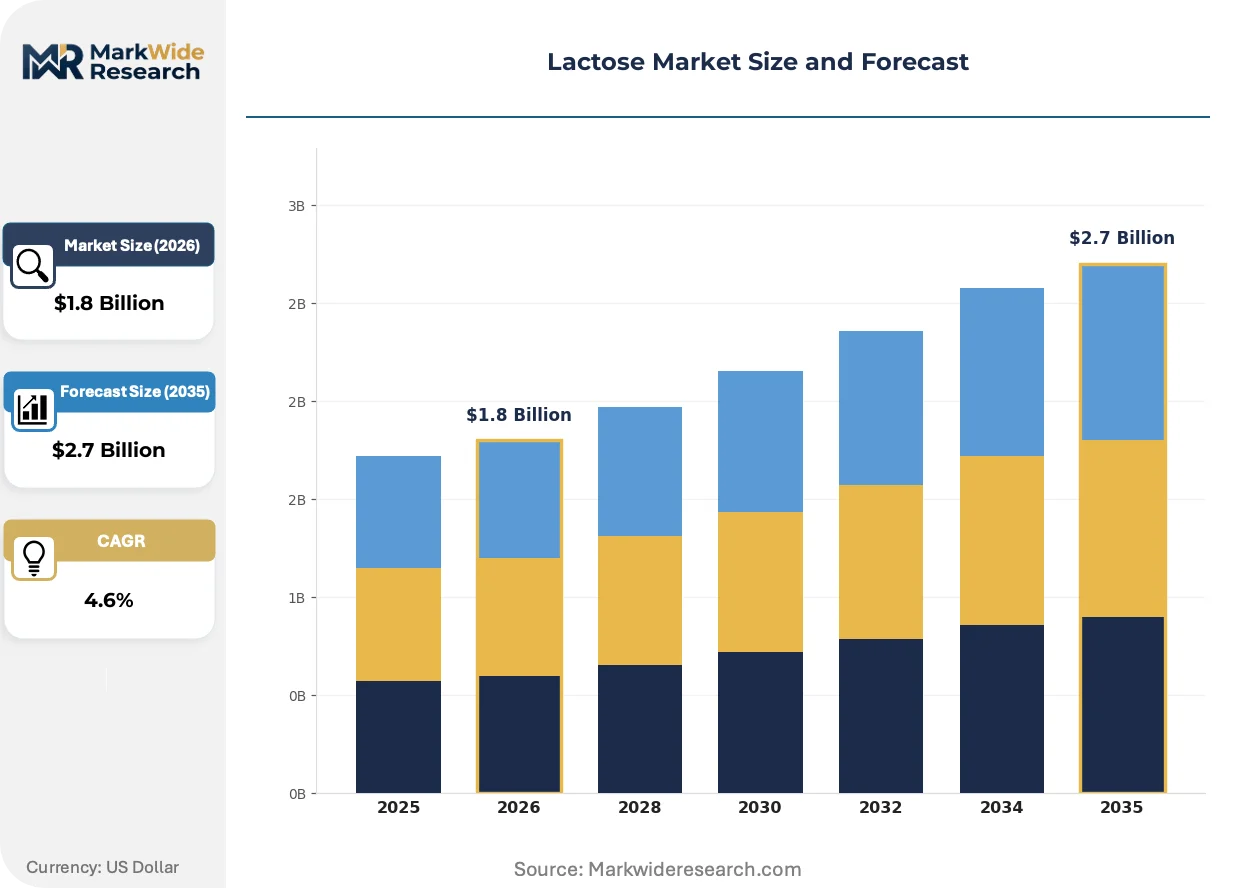
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lactose Monohydrate, Anhydrous Lactose, Crystalline Lactose, Spray-dried Lactose End User: Pharmaceuticals, Food & Beverage, Nutraceuticals, Animal Feed Application: Tablet Binders, Sweeteners, Fillers, Dairy Products Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | FrieslandCampina, Fonterra, Lactalis, Arla Foods, Glanbia, MEGGLE GmbH & Co. KG, Hilmar Cheese Company, DFE Pharma, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactose Market Emerging Trajectories
Particle engineering and regulatory documentation automation are reconfiguring competitive advantage away from volume scale toward specification precision and audit readiness.
Membrane filtration is decomposing the traditional crystallization monopoly in pharmaceutical-grade production. Inhalation drug manufacturers are specifying sub-10-micron particle distributions that conventional evaporative crystallization cannot reproducibly achieve. This technical divergence is decomposing unified pricing tiers into equipment-stratified supply categories.
EMA monograph revisions for residual protein and microbial specifications are compressing grandfathered supplier windows. European drug manufacturers must re-qualify excipient sources against tightened acceptance criteria by the implementation deadline. Inhalation-grade lactose contracts face the steepest re-qualification burdens due to pulmonary safety sensitivity.
Buyer consolidation among contract development and manufacturing organizations is compressing supplier negotiation leverage. Large pharmaceutical outsourcing platforms are unbundling excipient sourcing from formulation services and establishing direct lactose processor relationships. This disintermediation is most advanced in North American generic drug manufacturing clusters.
Lactose Market Segmentation
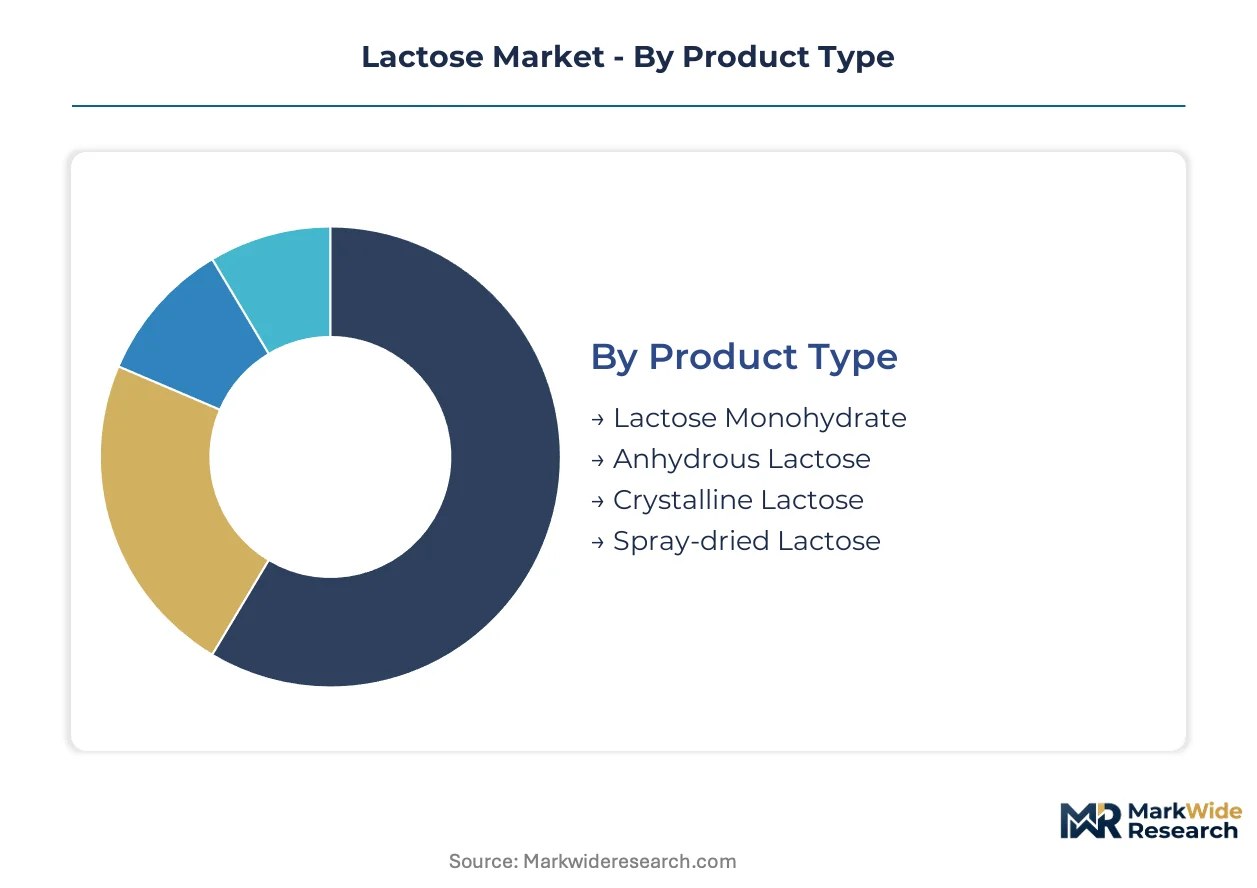
Segmentation in the lactose market tracks divergent purity requirements between pharmaceutical excipients and food-grade applications. Specification tiers determine equipment investment thresholds, with membrane filtration separating qualified pharmaceutical suppliers from commodity crystallization operators.
Product Type:
Domestic pharmaceutical manufacturing in India and the United States drives concentrated demand for two product types, while export-oriented European processors supply specialized inhalation grades globally.
- Lactose Monohydrate:This crystalline form contains one water molecule per lactose molecule, delivering predictable compression characteristics for direct tableting operations. Indian generic drug manufacturers and United States contract development organizations specify monohydrate for high-speed production lines, with residual protein thresholds below 0.1% determining supplier qualification status.
- Spray-dried Lactose:Engineered through atomization and rapid drying to produce spherical particles with controlled porosity. Pulmonary drug delivery expansion in Germany and Switzerland pulls specialized capacity for sub-10-micron distributions, with EMA inhalation-grade documentation requirements filtering supplier pools.
- Anhydrous Lactose:Dehydrated crystalline form with moisture content below 1%, specified for moisture-sensitive active pharmaceutical ingredients.
- Crystalline Lactose:Standard evaporative crystallization output serving food standardization and animal feed compounding with lower purity thresholds.
Lactose monohydrate holds the largest share; momentum sits with spray-dried lactose.
End User:
Margin stratification separates pharmaceutical excipients commanding certification premiums from volume-driven food applications facing substitution pressure.
- Pharmaceuticals:Tablet binders, capsule fillers, and inhalation carriers requiring USP-NF and EP dual certification. FDA pharmaceutical excipient guidelines and EMA monograph compliance create documentation barriers that consolidate procurement with qualified European and North American processors.
- Food & Beverage:Standardization agent for dairy products and confectionery, facing displacement from galacto-oligosaccharides in lactose-intolerant consumer segments. German and Dutch dairy processors represent anchor volume demand.
- Nutraceuticals:Protein powder carrier and prebiotic formulation base, with Indian domestic manufacturers scaling import substitution for pharmaceutical-grade supply.
- Animal Feed:Whey permeate derivative for calf nutrition and pet food formulations, sourced through commodity crystallization channels without pharmaceutical documentation overhead.
Pharmaceuticals capture the highest margin tier; nutraceuticals are climbing fastest.
Application:
Equipment specificity divides applications between pharmaceutical unit operations demanding particle engineering and commodity food processing accepting broader specifications.
- Tablet Binders:Direct compression compatibility requires specified particle size distributions and flow properties. United States generic drug clusters and Indian formulation facilities specify lactose monohydrate for high-throughput rotary tablet presses.
- Fillers:Bulking agent for capsules and sachets, with inhalation-grade specifications requiring specialized milling and sieving capabilities concentrated among German and Swiss suppliers.
- Sweeteners:Dairy and confectionery applications with FSSAI and FDA food additive compliance, facing price compression from maltodextrin alternatives.
- Dairy Products:Standardization of protein and solids content in milk powder and whey protein concentrates.
Tablet binders dominate volume; fillers show steepest specification tightening.
Distribution Channel:
Channel selection correlates with batch size and documentation requirements, with pharmaceutical procurement bypassing traditional wholesale structures.
- Wholesalers:Primary channel for food-grade and feed-grade lactose, with Rotterdam and Chicago distribution hubs serving dairy processors and compound feed manufacturers.
- Specialty Stores:Nutraceutical and sports nutrition retail, with Mumbai and Bangalore outlets serving domestic Indian demand.
- Online Retail:Direct procurement platforms for small-batch pharmaceutical researchers and specialty food formulators.
- Supermarkets:Consumer-packaged lactose for home brewing and specialty cooking applications.
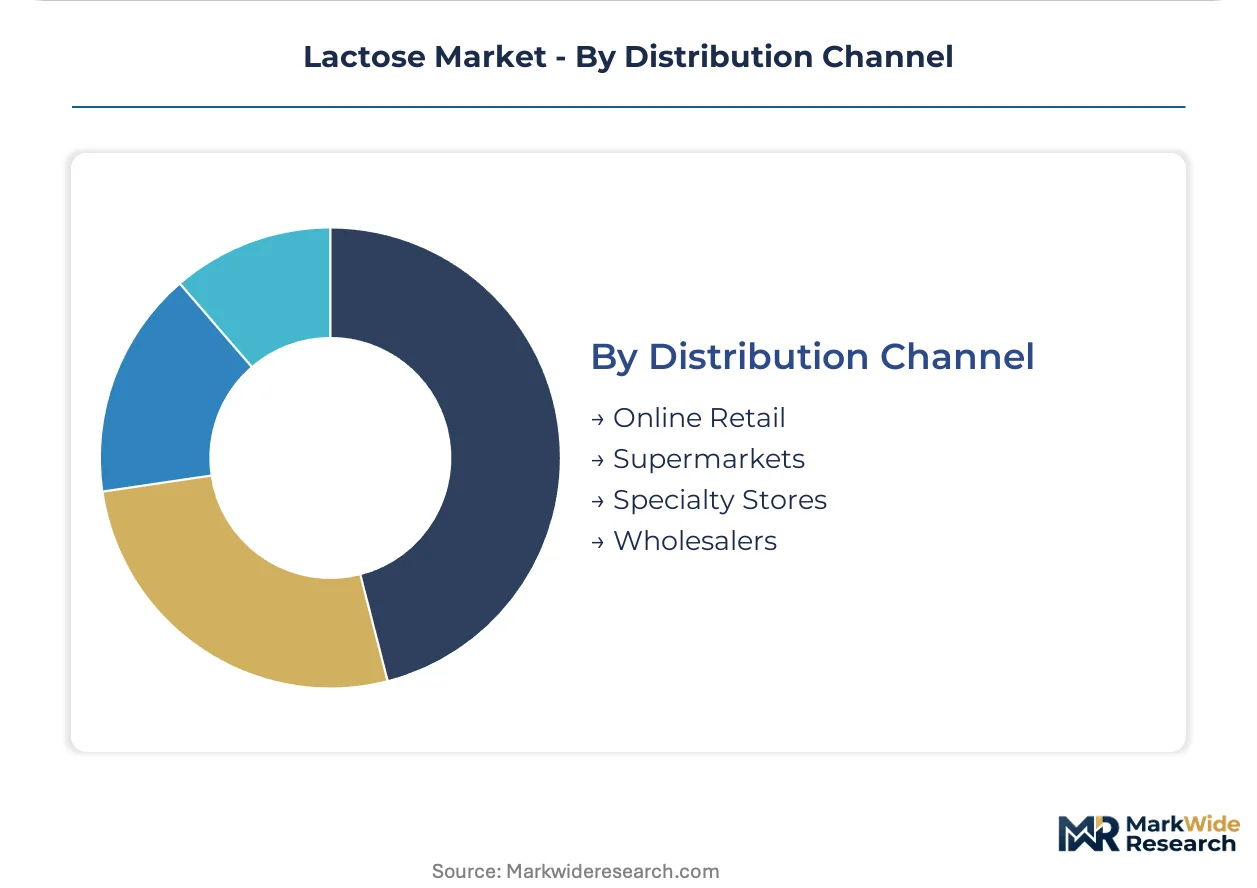
Wholesalers maintain volume leadership; direct processor relationships are displacing traditional channel structures in pharmaceutical procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and the United States absorb pharmaceutical-grade lactose at premium tolerances, while European food processors remain the most price-sensitive volume purchasers. This elasticity divergence fragments regional sourcing strategies. The Netherlands and Germany leverage membrane filtration infrastructure to capture margin-rich pharmaceutical contracts.
United States
Generic drug manufacturers in New Jersey and North Carolina drive concentrated demand for lactose monohydrate tablet binders. FDA pharmaceutical excipient guidelines enforce residual protein thresholds below 0.1% for supplier qualification. California's Central Valley cheese production anchors whey permeate supply for Hilmar Cheese Company's fractionation operations.
Germany
Inhalation-grade lactose specifications from pulmonary drug manufacturers in Munich and Frankfurt pull specialized particle engineering capacity. EMA monograph revisions for residual protein and microbial limits compress grandfathered supplier windows. Bavarian milling and sieging specialists concentrate spray-dried production for sub-10-micron distribution requirements.
India
Domestic pharmaceutical manufacturing in Maharashtra and Gujarat accelerates import substitution for pharmaceutical-grade excipients. CDSCO alignment with USP-NF and EP standards creates regulatory runway for export-grade production qualification. Mumbai and Bangalore formulation facilities scale direct compression tableting for generic drug exports.
Netherlands
Integrated dairy processors leverage whey stream consolidation across Dutch and German border facilities. REACH registration compliance filters non-compliant whey processors from qualified supplier pools. Rotterdam distribution hubs serve European pharmaceutical procurement with membrane filtration-equipped output.
Switzerland
Pulmonary drug delivery specialists in Basel specify inhalation-grade lactose with stringent particle size distributions. Swissmedic pharmaceutical excipient requirements reinforce documentation barriers for non-European suppliers. The Basel-Lörrach biopharma corridor concentrates dry powder inhaler formulation demand.
Lactose Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive positioning across specification tiers. Membrane filtration-equipped processors command pharmaceutical-grade premiums while crystallization-only operators compete on food-grade volume. Three archetypes dominate: integrated dairy conglomerates with whey stream control, specialized pharmaceutical excipient processors with milling capabilities, and regional cheese manufacturers with captive whey supply. Consolidation through backward integration into whey sourcing and capacity expansion into spray-dried inhalation grades represent the dominant competitive moves.
Within the integrated dairy tier, FrieslandCampina and Fonterra exemplify cost advantages through whey stream consolidation across multi-facility networks. MEGGLE GmbH & Co. KG occupies a position among specialized German processors with dedicated pharmaceutical milling capabilities. These three anchors illustrate the technology-cost bifurcation: scale-driven integration versus specification-precision specialization.
| Leading Market Players |
|---|
| FrieslandCampina |
| Fonterra |
| Lactalis |
| Arla Foods |
| Glanbia |
| MEGGLE GmbH & Co. KG |
| Hilmar Cheese Company |
| DFE Pharma |
| Kerry Group |
| Others |
Supply Flow & Price Mechanics
Ninety-day pharmaceutical excipient qualification timelines concentrate pricing power with membrane filtration-equipped processors in the Netherlands and Germany, while crystallization-only operators in commodity tiers face margin compression from whey permeate cost volatility. This lead-time stratification separates inhalation-grade premium capture from food-grade spot market exposure.
Pricing Analysis
After-sales documentation and audit support contracts drive lifetime value for pharmaceutical-grade suppliers. Three-tier pricing structure across pharmaceutical, nutraceutical, and food-grade levels anchors contract structures, with certification grade and volume scale as primary price differentiation drivers. Cost compression in standard-grade tiers is intensifying because galacto-oligosaccharide substitution erodes pricing power. Food and beverage manufacturers show highest price sensitivity; pulmonary drug developers accept premium positioning for EMA-compliant inhalation grades.
Supply Chain Analysis
The Netherlands and Germany anchor pharmaceutical-grade lactose production through membrane filtration infrastructure, while the United States and India scale crystallization capacity for domestic tablet binder demand. Whey permeate from cheese production, specialized milling equipment, and EMA documentation capabilities constitute critical input dependencies. Single-source vulnerability concentrates in California Central Valley whey sourcing for fractionation operations. Distribution runs through direct processor relationships with pharmaceutical CDMOs, bypassing traditional wholesale structures for certified excipient procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern excipient procurement as CDMO consolidation unbundles formulation services from raw material sourcing, creating direct supplier relationships that bypass traditional distribution layers.
For Market Incumbents: Consolidate membrane filtration capacity in the Netherlands and Germany to defend pharmaceutical-grade margins against emerging Indian processors scaling USP-NF qualification. Backward integration into whey sourcing secures raw material leverage against California supply concentration risk. EMA monograph revision deadlines compress grandfathered supplier windows, accelerating qualification barriers. For New Entrants and Emerging Players: Inhalation-grade particle engineering capacity gaps in India and the United States present white-space entry points where European incumbents under-serve domestic pulmonary drug developers. CDSCO harmonization with USP-NF standards creates regulatory runway for export-grade production qualification. Partner with Mumbai and Bangalore generic drug clusters for direct compression tableting formulation trials. For Investors and Strategic Acquirers: Long-term, this sits as a specification-precision play because membrane filtration capex barriers and pharmacopeial auditor scarcity protect incumbent returns against commodity competition. Target specialized milling and sieving capabilities with existing EMA inhalation-grade documentation. Watch CDSCO implementation timelines for Indian domestic qualification acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | EMA-compliant residual protein thresholds separate qualified pharmaceutical suppliers from crystallization-only competitors. |
| Backward Integration into Whey Sourcing | California Central Valley cheese production concentration creates captive supply advantages for fractionation operators. |
| Spray-Dried Inhalation Grade Development | Sub-10-micron particle engineering captures pulmonary drug delivery expansion in Germany and Switzerland. |
| CDSCO Regulatory Harmonization Investment | USP-NF and EP alignment creates export-grade production qualification runway for Indian domestic manufacturers. |
| Direct Processor-CDMO Relationship Formation | Buyer consolidation among North American generic drug clusters disintermediates traditional excipient distribution channels. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across pharmaceutical formulation facilities, whey processing plants, and regulatory affairs departments. Primary interviews with tablet production managers, excipient procurement leads at CDMOs, membrane filtration equipment specialists, and EMA compliance officers combined with secondary validation from FDA pharmaceutical excipient guidelines, EMA monograph revisions, USP-NF standards documentation, and CDSCO regulatory circulars. Bottom-up capacity modeling and top-down demand triangulation anchored value estimates.
Across the analysis window, segmentation dimensions included product type grade tier, end-use application, particle size specification band, and regional regulatory cluster. CAGRs derived from installed capacity expansion schedules, pharmaceutical manufacturing growth indices, and inhalation drug delivery pipeline assessments. Whey permeate supply forecasts and pharmacopeial harmonization timelines informed trajectory sensitivity.
Forecasts assume regulatory continuity in FDA, EMA, and CDSCO regimes; material policy shifts in residual protein thresholds or REACH registration requirements would require re-modeling. Recalibration cycles align with material shifts in pharmacopeial standard harmonization and CDSCO implementation deadlines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
North America Yogurt Market
Dairy Products
United States Casein Market
Dairy Products
Organic Milk Protein Market
Dairy Products
Yogurt and Probiotic Drink Market
Dairy Products
Europe Flavored Milk Market
Dairy Products
North America Organic Dairy Market
Dairy Products
Paneer Market
Dairy Products
Germany Dairy Market
Dairy Products
Fermented Milk Products Market
Dairy Products
Saudi Arabia Dairy Products Market
Dairy Products
Global Goat Cheese Market
Dairy Products
Milk Protein Concentrate Market
Dairy Products
Low-Calorie Butter Market
Dairy Products
Global Fresh Milk Market
Dairy Products
Drinkable Yogurt Market
Dairy Products
Skim Milk Powder Market