
 Coconut Yogurt Market | 2026-2036
Coconut Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Yogurt Market Insights
Asset-light contract manufacturing and third-party co-packing is rewriting competitive entry economics in coconut yogurt, allowing challenger brands to scale without capital-heavy dairy infrastructure. COYO leverages Australian coconut sourcing to anchor its premium positioning. The Coconut Collaborative competes through dedicated organic supply chains across British and European retail. Danone extends its plant-based R&D infrastructure from oat and almond into cultured coconut lines.
Coconut yogurt is a fermented food product manufactured from coconut milk through bacterial culture fermentation, typically achieving protein content of one to three grams per serving and a pH below 4.6 for shelf stability and food safety. Its primary commercial purpose is to serve as a dairy-free alternative in breakfast, snacking, and ingredient applications for lactose-intolerant consumers and plant-based diets. The flavored segment leads volume as vanilla, berry, and tropical variants drive repeat purchase frequency in mainstream retail. Organic certification commands price premiums in health food stores and specialty channels. Bulk packaging for food service and restaurant end users represents the fastest-growing consumption pool as commercial kitchens reformulate menus around allergen-free ingredients.
FDA nutrition labeling rules and EU organic regulations under EFSA and the EU Green Deal framework shape ingredient transparency requirements and restrict synthetic additive use in coconut yogurt positioned as natural or clean-label. USDA organic standards and state-level cottage food laws in the United States create fragmented compliance obligations for interstate distribution. Health Canada and Food Standards Australia New Zealand impose additional allergen and fortification disclosure mandates that affect import eligibility. Stakeholders must monitor evolving probiotic health claim restrictions across jurisdictions to determine which markets justify dedicated formulation investments versus standardized global recipes.
Market Dynamics
Contract manufacturing networks are compressing capital barriers for coconut yogurt entrants, enabling challenger brands to bypass dairy infrastructure investments and scale through third-party fermentation capacity.
Growth Catalysts
- EU Green Deal organic mandates:EFSA disclosure requirements under the EU Green Deal framework are accelerating clean-label formulation investments, pulling synthetic-additive-free coconut yogurt into mainstream European retail.
- Food service bulk adoption:Commercial kitchens across the United States are reformulating allergen-free menu lines, creating dedicated procurement slots for food-service-packaged cultured coconut products.
- Australian coconut sourcing clusters:Queensland and Northern Territory supply basins are anchoring premium positioning through provenance-linked ingredient storytelling in export markets.
Market Restraints
- Coconut cream input volatility:Philippine and Indonesian copra supply fluctuations transmit directly into coconut milk concentrate pricing, compressing margin predictability for mid-tier brands.
- Probiotic health claim restrictions:FDA substantiation requirements for live culture benefit claims create formulation lock-in, preventing flexible strain rotation that could reduce production costs.
- Dairy yogurt substitution threat:Lactose-free dairy lines and A2 milk yogurts are reclaiming price-sensitive consumers who previously exited conventional dairy.
Strategic Opportunities
- German retail organic penetration:REWE and EDEKA shelf expansion for certified organic plant-based dairy alternatives is outpacing supply, creating first-mover positioning for compliant entrants.
- Probiotic-functional convergence:Synbiotic formulations combining coconut fermentation substrates with targeted prebiotic fibers are opening clinical-nutrition channel access beyond conventional grocery.
- Direct-to-subscription channel innovation:Refrigerated last-mile logistics partnerships with specialized cold-chain couriers are collapsing traditional distributor markups for recurring household delivery.
Industry Challenges
- Fermentation technologist scarcity:Industrial microbiology talent capable of scaling non-dairy cultures lacks pipeline depth, extending R&D timelines for proprietary strain development.
- Multi-jurisdiction certification timelines:USDA organic, EU organic, and BioGro New Zealand approvals require sequential rather than parallel review, delaying unified global recipe launches.
- Cold-chain integration complexity:Legacy dairy distributor networks resist onboarding plant-based SKUs with shorter shelf lives and distinct temperature sensitivity profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Yogurt Market |
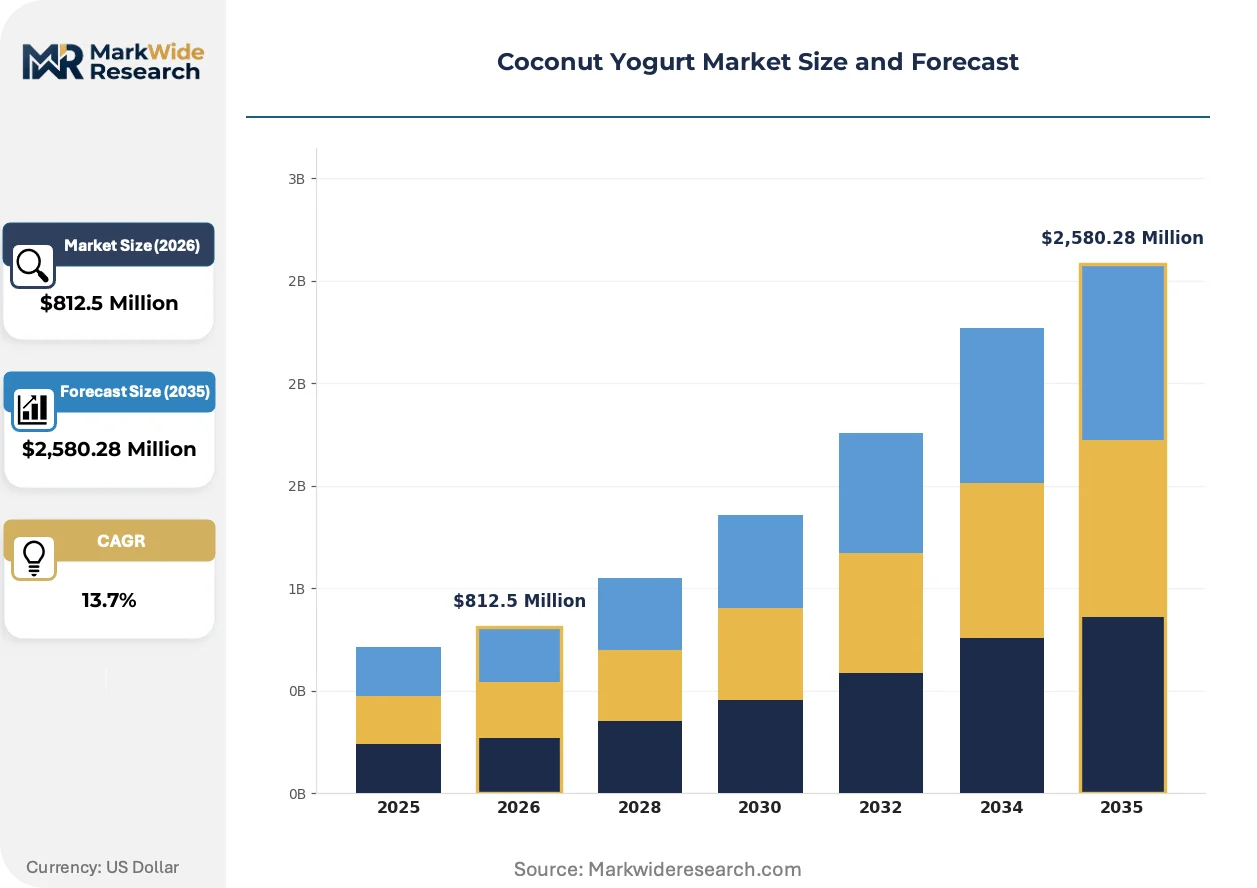
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $2,580.28 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain, Flavored, Organic, Non-Dairy Packaging Type: Jar, Cup, Pouch, Bulk Distribution Channel: Online, Supermarket, Health Food Store, Specialty Store End User: Retail Consumers, Food Service, Health Enthusiasts, Restaurants |
| Companies Covered | Danone, Chobani LLC, The Coconut Collaborative, COYO, So Delicious Dairy Free, Alpro, Kite Hill, Forager Project, Lavva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Yogurt Market Trends and Innovations
Precision fermentation and substrate engineering are rewriting cost curves for cultured coconut products, while regulatory disclosure mandates and channel fragmentation are reshaping how brands build consumer trust.
High-pressure processing technology is collapsing thermal pasteurization requirements for coconut yogurt, preserving live probiotic counts without refrigeration-dependent supply chains. Food service operators and direct-to-consumer brands are adopting HPP-equipped co-packers at accelerating rates. This compression is enabling ambient-stable product formats that penetrate convenience retail previously closed to chilled dairy alternatives.
EFSA nutrient profiling and health claim substantiation rules under the EU Green Deal are tightening probiotic efficacy documentation requirements for organic-positioned coconut yogurt. Manufacturers must now commission clinical trials or withdraw specific strain benefit claims from packaging. German and French markets are experiencing the fastest compliance adaptation, with reformulated labels appearing ahead of enforcement deadlines.
Buyer concentration among plant-based retail specialists is fragmenting procurement authority previously held by conventional grocery distributors. Independent natural products chains and online wellness platforms are disintermediating legacy food broker networks, demanding exclusive SKUs and shorter production runs. Australia and the United States show the most pronounced channel bifurcation, with divergent packaging and certification requirements for each path.
Coconut Yogurt Market Segmentation
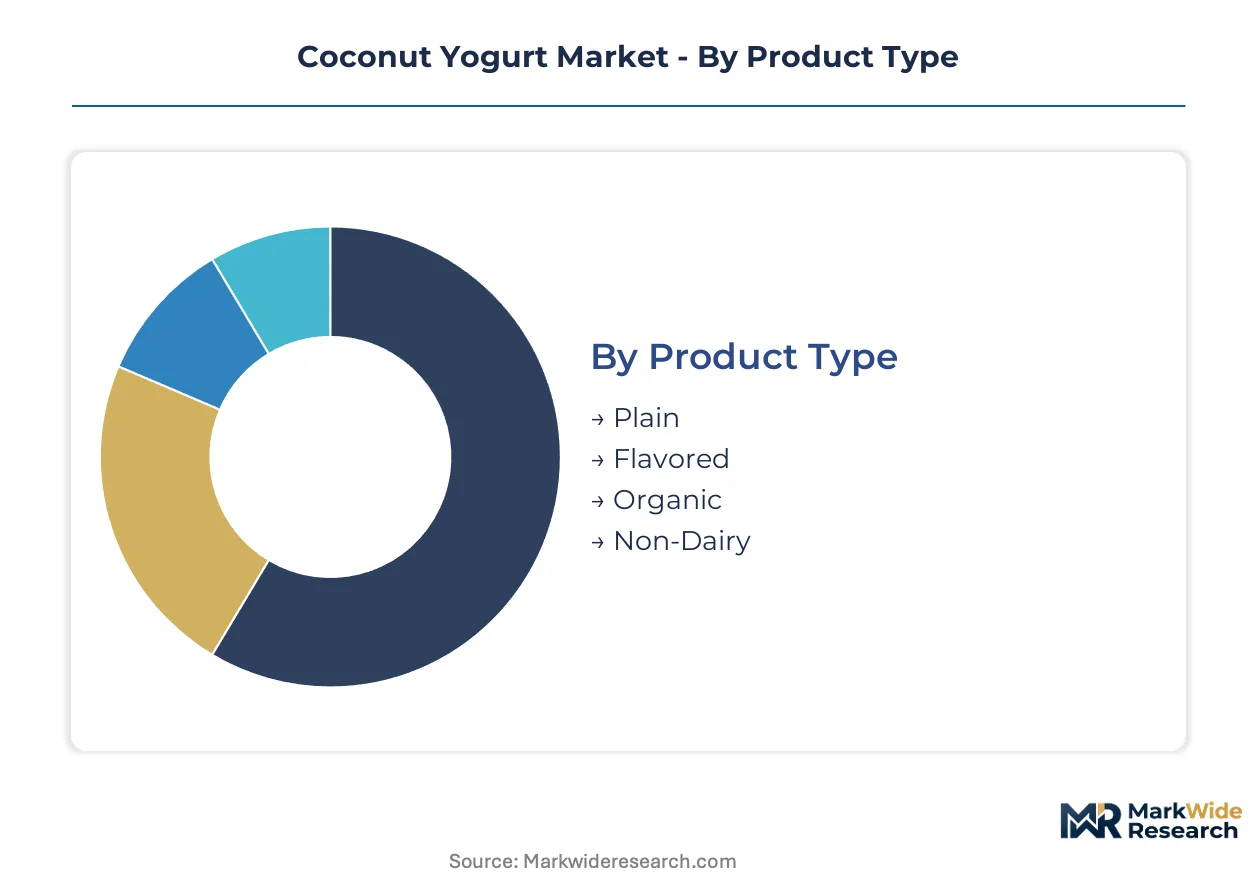
Coconut yogurt segmentation reveals how formulation choices, packaging formats, and channel strategies align with distinct consumer missions—from daily breakfast substitution to professional kitchen ingredient sourcing. Understanding these divides clarifies where margin pools concentrate and where challenger brands can displace incumbent dairy alternatives.
Product Type:
Plain coconut yogurt serves minimalist recipe applications and clean-label purists, while flavored variants address impulse-driven snacking occasions with sensory differentiation.
- Plain:Unsweetened formulations with minimal ingredient lists dominate home cooking and smoothie base applications. Demand concentrates among health enthusiasts in Germany and Australia seeking fermentation-forward, low-sugar alternatives to dairy yogurt.
- Flavored:Vanilla, berry, and tropical variants incorporate natural flavor systems and modest sweetener loads to drive repeat purchase frequency. United States mainstream retail chains allocate disproportionate shelf space to these SKUs, though EFSA disclosure requirements under the EU Green Deal are tightening additive scrutiny for European-positioned lines.
- Organic:Certified formulations command price premiums in specialty channels through provenance-linked ingredient storytelling.
- Non-Dairy:Explicit allergen-free positioning targets lactose-intolerant consumers and strict plant-based diet adherents.
The dominant share belongs to Flavored, while Organic is closing the gap fastest.
Packaging Type:
Format selection traces directly to consumption occasion and channel economics, with single-serve portability competing against bulk value for high-volume users.
- Jar:Glass and premium plastic jars support premium positioning and reuse value in home pantry environments. Australian brands leverage jar formats for export markets where visual premiumness justifies freight costs.
- Cup:Lightweight single-serve cups dominate grab-and-go breakfast and office snacking occasions. United States convenience retail and school foodservice programs drive volume concentration, though shorter shelf lives strain distributor economics.
- Pouch:Flexible formats reduce material costs and shipping weight for direct-to-consumer subscription channels.
- Bulk:Food-service-scale packaging captures commercial kitchen reformulation demand as restaurants build allergen-free menu lines.
Cup formats still anchor the installed base, yet Bulk packaging is expanding most quickly as food service procurement accelerates.
Distribution Channel:
Channel fragmentation reflects divergent shopper missions—stock-up pantry loading versus immediate consumption versus curated wellness discovery.
- Online:Direct-to-consumer and third-party marketplace sales enable subscription mechanics and cold-chain last-mile partnerships. Specialized refrigerated couriers in the United States and Australia are collapsing traditional distributor markups for recurring household delivery.
- Supermarket:Conventional grocery placement requires slotting fee investments and velocity guarantees that favor scaled players with dairy distributor relationships.
- Health Food Store:Independent natural products chains demand exclusive SKUs and shorter production runs, fragmenting procurement authority.
- Specialty Store:Curated wellness platforms and plant-based retail specialists disintermediate legacy food broker networks.
Supermarket penetration remains deepest, though Online is climbing the fastest as refrigerated logistics mature.
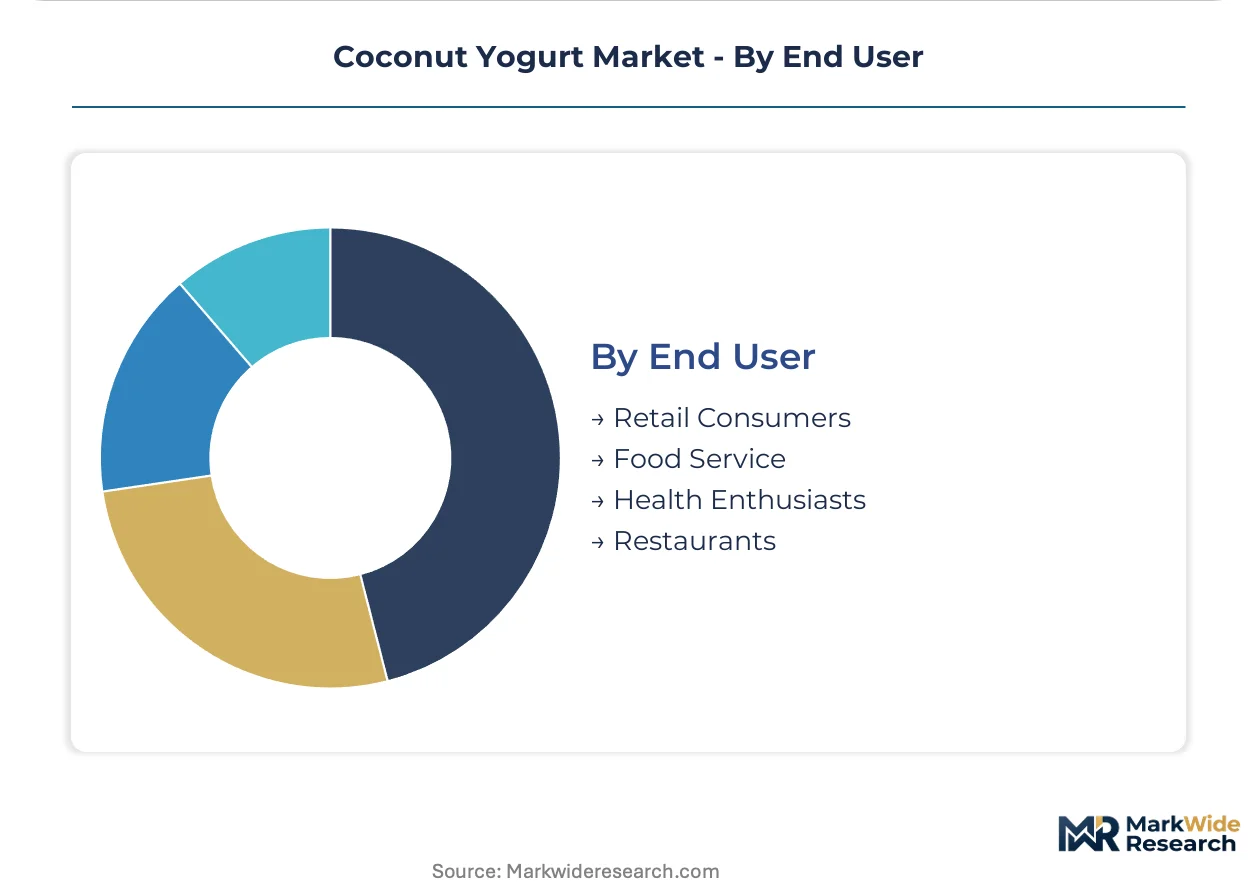
End User:
User type segmentation separates household consumption from commercial ingredient demand, with divergent quality specifications and procurement authority structures.
- Retail Consumers:Household purchasers prioritize taste familiarity, label simplicity, and price accessibility for routine breakfast and snacking occasions. German REWE and EDEKA expansion for certified organic plant-based alternatives is outpacing supply, creating first-mover positioning for compliant entrants.
- Food Service:Commercial kitchens and institutional feeders seek consistent supply, food-safety documentation, and reformulation flexibility for allergen-free menu lines. United States contract foodservice operators are establishing dedicated procurement slots for bulk-packaged cultured coconut products.
- Health Enthusiasts:Performance-oriented consumers target specific probiotic strains and macronutrient profiles.
- Restaurants:Chef-driven establishments value culinary versatility and premium provenance for menu differentiation.
Retail Consumers retain the volume base, yet Food Service is gaining share fastest as commercial kitchen adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium shelf space in German retail chains commands price multiples unavailable to identical formulations in Southeast Asian markets, creating a structural pricing-power asymmetry that shapes manufacturer location decisions and export investment priorities.
United States
Mainstream retail chains allocate disproportionate shelf space to flavored coconut yogurt SKUs, with vanilla and berry variants driving repeat purchase frequency. FDA nutrition labeling rules and probiotic health claim substantiation requirements create formulation lock-in for live culture benefits. California-based contract manufacturers and cold-chain logistics specialists anchor West Coast distribution networks serving direct-to-consumer subscription channels.
Germany
REWE and EDEKA expansion for certified organic plant-based dairy alternatives is outpacing supply, creating first-mover positioning for compliant entrants. EFSA disclosure requirements under the EU Green Deal framework accelerate clean-label formulation investments and restrict synthetic additive use. Bavarian and North Rhine-Westphalian retail clusters concentrate procurement authority for organic-positioned cultured coconut products.
Australia
Queensland and Northern Territory coconut supply basins anchor premium positioning through provenance-linked ingredient storytelling in export markets. Food Standards Australia New Zealand impose allergen and fortification disclosure mandates that affect import eligibility for competing products. Sydney and Melbourne metropolitan areas host specialized refrigerated couriers collapsing traditional distributor markups for recurring household delivery.
United Kingdom
The Coconut Collaborative leverages dedicated organic supply chains across British retail to compete on certification credibility. EU organic regulations under EFSA and the EU Green Deal framework shape ingredient transparency requirements for cross-channel trade. London and Southeast England health food store clusters demand exclusive SKUs and shorter production runs, fragmenting procurement authority previously held by conventional grocery distributors.
Canada
Health Canada disclosure mandates for allergen and fortification labeling affect import eligibility and domestic formulation decisions. Cottage food laws and provincial dairy regulations create fragmented compliance obligations for interstate distribution. Ontario and Quebec retail chains are expanding shelf space for cultured coconut products as consumers shift toward dairy-free alternatives.
Coconut Yogurt Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying fermentation capacity and coconut milk concentrate to brands lacking captive production. The vendor base spans multinational food conglomerates with plant-based R&D infrastructure, dedicated organic specialists with provenance-linked supply chains, and challenger brands scaling through asset-light contract manufacturing. Two strategic archetypes dominate: diversified dairy-alternative platforms extending from oat and almond into cultured coconut lines, and pure-play coconut specialists leveraging Australian or Southeast Asian sourcing clusters. Competitive moves concentrate on M&A-driven portfolio diversification into adjacent plant-based categories and geographic expansion through refrigerated logistics partnerships.
Within the diversified platform tier, Danone extends its plant-based R&D infrastructure from oat and almond into cultured coconut lines, exemplifying multinational scale advantages in formulation science and retail negotiation. COYO anchors the premium specialist archetype through Australian coconut sourcing and provenance-linked positioning in export markets. The Coconut Collaborative occupies a position within the dedicated organic supply chain segment, competing across British and European retail through certification credibility and exclusive retail relationships. These three represent distinct strategic postures rather than direct peer competition.
| Leading Market Players |
|---|
| Danone |
| Chobani LLC |
| The Coconut Collaborative |
| COYO |
| So Delicious Dairy Free |
| Alpro |
| Kite Hill |
| Forager Project |
| Lavva |
| Others |
Pricing and Supply Chain Analysis
Contract manufacturing overcapacity in Southeast Asian fermentation facilities is compressing unit economics for coconut yogurt brands, enabling challenger entrants to negotiate favorable co-packing terms while incumbent dairy-alternative platforms absorb margin pressure through captive production networks.
Pricing Analysis
The customization-premium spread in coconut yogurt separates standard retail SKUs from configured-to-order food service formats, with bulk procurement contracts commanding 15-25% discounts against single-serve cup equivalents. Three-tier pricing structure across organic-certified premium, conventional standard, and private-label economy levels reflects certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from Philippine and Indonesian copra supply fluctuations transmitting directly into coconut milk concentrate costs. Food service operators exhibit lowest price sensitivity due to menu reformulation lock-in, while mainstream retail consumers in price-comparison channels drive hardest bargain hunting.
Supply Chain Analysis
Extended payment terms from Australian and Thai coconut milk concentrate suppliers are becoming standard procurement practice, with 60-90 day windows replacing historical 30-day cycles to preserve processor working capital. Geographic supply concentrates in the Philippines, Indonesia, and Sri Lanka for copra crushing, with Australian Queensland clusters anchoring premium provenance positioning. Raw material dependencies rest on coconut cream concentrate, live probiotic cultures, and specialized fermentation substrates. Single-source vulnerability in Philippine copra supply creates structural risk exposure. Distribution runs through refrigerated dairy networks for retail, with direct-to-consumer cold-chain partnerships emerging as parallel channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coconut yogurt market fragmentation creates niche occupation opportunities as channel bifurcation between conventional grocery and wellness-specialist retail splinters procurement authority across multiple buyer archetypes.
For Market Incumbents: Entrench shelf position through exclusive SKU development with REWE and EDEKA in Germany, while backward integration into Queensland coconut sourcing clusters defends premium positioning against contract-manufactured challengers. FDA probiotic health claim substantiation requirements create formulation lock-in advantages that emerging players cannot easily replicate. For New Entrants and Emerging Players: German retail organic penetration gaps represent the most penetrable white-space target, with REWE and EDEKA shelf expansion outpacing certified supply. Direct-to-consumer subscription channels through specialized refrigerated couriers offer lowest competitive density entry path, collapsing traditional distributor markups for recurring household delivery. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription operators with cold-chain logistics partnerships, suggesting superior cash-flow quality versus conventional retail-dependent brands. Acquisition target archetype: asset-light contract manufacturing brands with German organic certification pipeline and food service bulk contract backlog. Signal to watch: FDA probiotic claim enforcement actions as margin compression indicator for formulation-locked incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Pipeline Investment | EU Green Deal EFSA disclosure requirements are accelerating clean-label compliance as table stakes for German retail placement. |
| Direct-to-Consumer Channel Launch | Refrigerated last-mile partnerships with specialized cold-chain couriers collapse distributor markups for recurring household delivery. |
| Food Service Bulk Format Development | Commercial kitchen reformulation demand for allergen-free menu lines creates fastest-growing consumption pool in United States contract foodservice. |
| Queensland Sourcing Cluster Integration | Australian provenance-linked ingredient storytelling anchors premium export positioning against Southeast Asian commodity supply. |
| Synbiotic Formulation R&D | Prebiotic fiber convergence with coconut fermentation substrates opens clinical-nutrition channel access beyond conventional grocery. |
Research Methodology
A standing panel of brand managers at plant-based retail specialists, category buyers at REWE and EDEKA, contract manufacturing operations directors, and cold-chain logistics specialists provided ongoing calibration throughout the study period. Primary interview intelligence combined with secondary validation from FDA 10-K filings, EFSA regulatory submissions, Nielsen retail audit data, and Australian Bureau of Agricultural and Resource Economics trade statistics. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning product type, packaging format, distribution channel, and end-user mission. CAGRs derived from historical trajectory analysis and forward-looking elasticity estimates incorporating copra supply volatility and refrigerated logistics penetration curves. Forecast inputs included Queensland coconut harvest projections and German organic retail shelf expansion rates.
Practitioners should monitor FDA probiotic claim enforcement patterns and EU Green Deal implementation timelines for early signals of regulatory revision pressure. Forecasts reflect assumptions about sustained consumer shift toward dairy-free alternatives and stable cold-chain infrastructure investment. Macroeconomic commodity price spikes, regulatory claim restriction tightening, or refrigerated logistics disruption would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Cashew Milk Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
Oat Drinks Market
Dairy Alternatives
China Dairy Alternatives Market
Dairy Alternatives
Japan Dairy Alternatives Market
Dairy Alternatives
Flax Milk Market
Dairy Alternatives
Coconut Milk Products Market
Dairy Alternatives
Vegan Cheese Alternatives Market
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
Vegan Coffee Creamer Market
Dairy Alternatives
Germany Non-Dairy Milk Market
Dairy Alternatives
Non-Dairy Ice Cream Market
Dairy Alternatives
Coconut Milk and Cream Market
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
Asia-Pacific Sour Milk Drinks Market
Dairy Alternatives
Banana Milk Market