
 Europe Non-Dairy Milk Market | 2026-2036
Europe Non-Dairy Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Non-Dairy Milk Market Insights
The split between premium barista-grade formulations and private-label commodity cartons is realigning how processors allocate capacity and margin. Oatly Group AB leverages its Scandinavian manufacturing base to sustain supply contracts with specialty coffee chains across Northern Europe. Danone SA anchors its position through Alpro's controlled distribution in French and Belgian supermarkets, while Valsoia SpA competes on Italian heritage positioning in Mediterranean markets.
Europe non-dairy milk comprises aqueous extracts of oilseeds, cereals, or nuts, formulated to achieve protein content between 0.5% and 3.5% and fat profiles mimicking semi-skimmed bovine milk for direct consumption or foodservice use. Oat milk leads volume growth due to its lower environmental water footprint and superior foaming stability in espresso applications. Almond milk occupies mature shelf-stable segments where margin pools have compressed, while soy milk retains dominance in food manufacturer ingredient channels despite consumer allergen concerns.
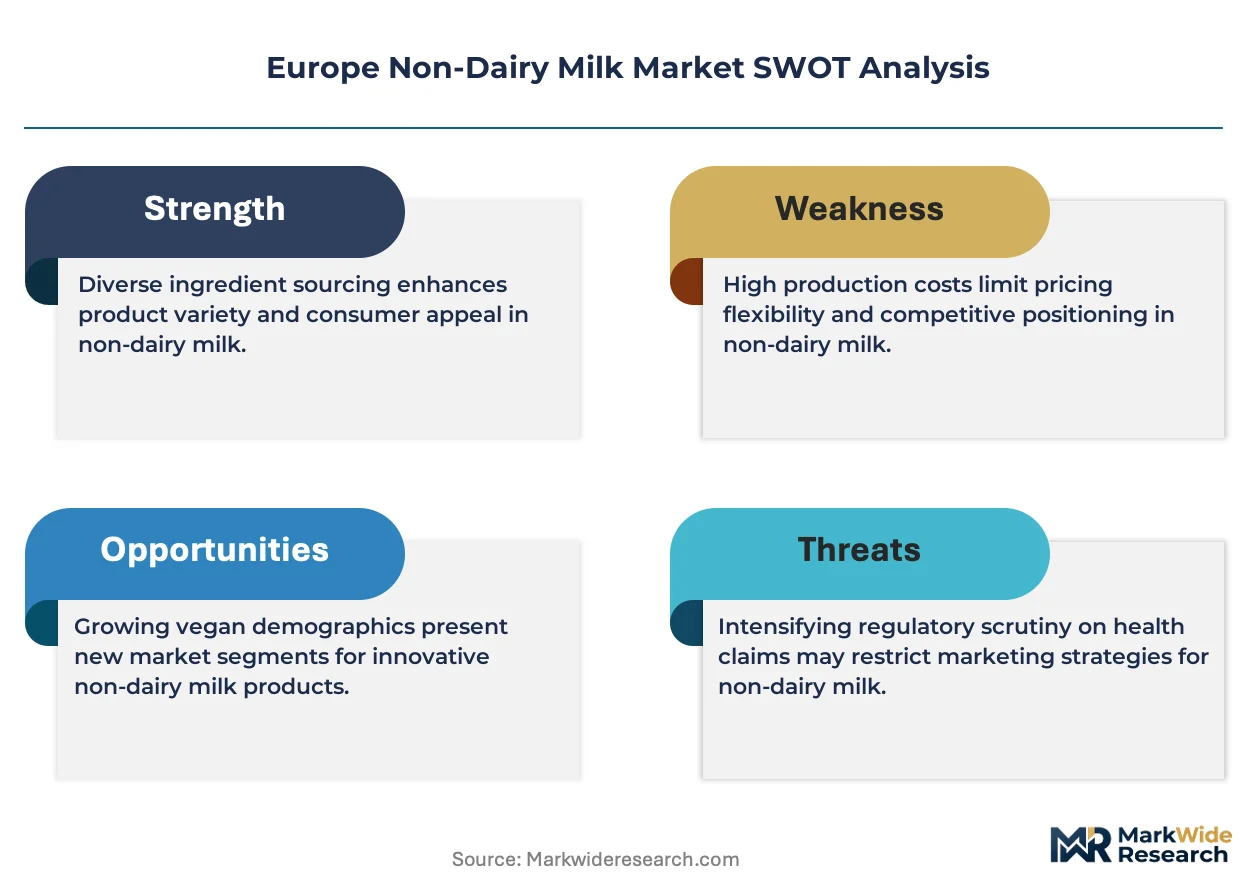
EMA food-contact material rules, EFSA novel food authorization pathways, and EU Green Deal agricultural emissions targets collectively determine which feedstocks gain formulation preference and labeling legitimacy. REACH chemical safety standards further constrain industrial solvent use in protein extraction processes. Stakeholders must monitor how EFSA revises protein quality scoring methodologies and whether national health claims in France and Germany diverge from harmonized EU positions.
Market Dynamics
Barista-grade oat milk procurement is electrifying capacity allocation across European processing plants, as specialty coffee chains in Berlin, Munich, and Paris now specify foaming stability parameters that commodity formulations cannot meet. This demand compression is forcing processors to choose between premium line investments and private-label volume defense.
Growth Catalysts
- EU Green Deal agricultural emissions targets:Feedstock sourcing from low-carbon cereal cultivation is gaining preferential access to French and German retail shelf space. Processors documenting supply chain emissions receive faster listing approvals.
- Specialty coffee channel expansion:Artisan cafés in Italy and Spain are specifying oat milk with protein content above 2.5% for latte art applications. This specification is pulling formulation upgrades across Southern European supply contracts.
- F-Gas Regulation compliance:Refrigerated distribution networks are retrofitting with natural refrigerants, reducing energy costs for chilled non-dairy milk logistics. Cold chain operators in the Netherlands and Belgium report operational savings that support extended shelf-space commitments.
Market Restraints
- Oat protein concentrate supply concentration:Scandinavian milling cooperatives control over 60% of European enzymatic processing capacity for barista-grade formulations. This geographic concentration creates procurement bottlenecks during harvest volatility.
- Almond milk margin compression:California drought cycles and water pricing volatility have destabilized input costs for shelf-stable almond formulations. Private-label buyers are absorbing margin erosion that branded players cannot sustain.
- REACH solvent restrictions:Protein extraction processes using hexane face phase-out timelines under revised chemical safety standards. Alternative aqueous extraction methods require capital retrofits that smaller processors cannot finance.
Strategic Opportunities
- Eastern European retail underpenetration:Polish and Romanian supermarket chains maintain minimal refrigerated non-dairy shelf space compared to Western European norms. First-mover processors securing direct store delivery contracts are capturing category creation economics.
- Food manufacturer ingredient channels:Plant-based yogurt and ice cream producers require standardized oat protein isolates with neutral flavor profiles. Ingredient-grade supply contracts offer volume stability absent from retail volatility.
- CSRD supply chain disclosure requirements:Mandatory emissions reporting is creating competitive differentiation for processors with verified low-carbon feedstock sourcing. Early compliance is translating into preferred supplier status with sustainability-focused retail buyers.
Industry Challenges
- Enzymatic process engineering talent scarcity:European universities produce limited graduates with combined food chemistry and industrial biotechnology training. Processors in Germany and France are competing for the same specialized workforce.
- EFSA novel food authorization timelines:Emerging protein sources from fava bean and chickpea extracts face 18-24 month safety evaluation periods. Product pipeline delays are compressing innovation-to-shelf cycles.
- Cold chain integration complexity:Refrigerated distribution networks designed for dairy products require temperature and humidity recalibration for plant-based formulations with different spoilage profiles. Logistics operators resist single-SKU infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Non-Dairy Milk Market |
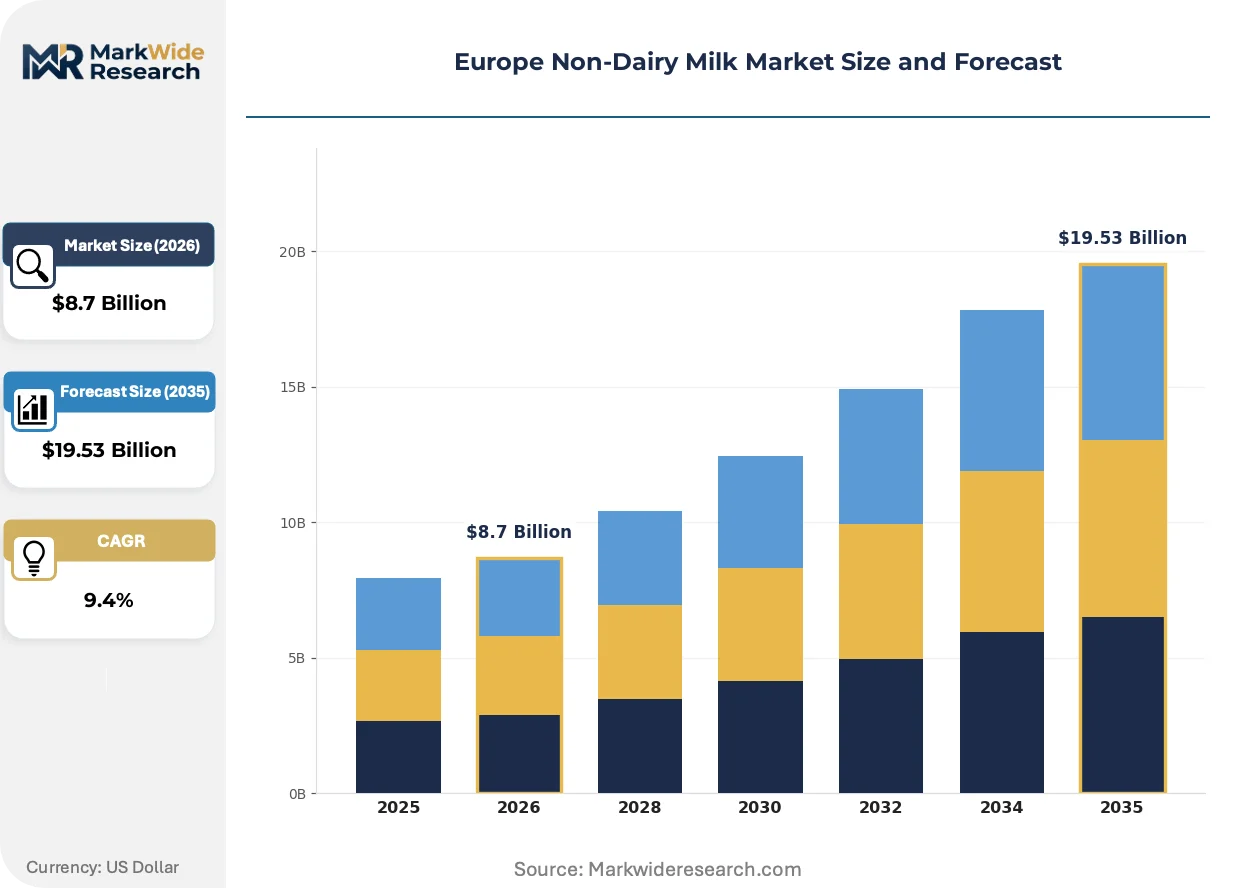
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Coconut Milk Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Convenience Stores End User: Households, Cafés, Restaurants, Food Manufacturers Packaging Type: Cartons, Bottles, Tetra Packs, Pouches |
| Companies Covered | Calidad Pascual SAU, The Hain Celestial Group Inc, Danone SA, Valsoia SpA, Nestlé SA, Oatly Group AB, Califia Farms LLC, Blue Diamond Growers, Alpro, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Non-Dairy Milk Market Trends and Innovations
Formulation science and regulatory disclosure requirements are converging to reshape how European processors compete on provenance transparency and functional performance. The segment is moving beyond commodity substitution toward ingredient-grade specialization.
High-pressure processing technology is electrifying clean-label shelf-stable production, eliminating thermal degradation of oat volatile compounds while achieving 12-month ambient stability. German and Dutch processors are adopting HPP lines originally deployed for cold-pressed juices, repurposing equipment for non-dairy milk sterilization. This technology is compressing the traditional trade-off between extended shelf life and flavor integrity that has constrained oat milk distribution reach.
EFSA protein quality scoring methodology revisions are forcing reformulation investments across soy and pea protein blends, as the regulator evaluates digestibility-corrected amino acid scores more stringently. Processors relying on historical protein content claims face label revision costs and potential health claim disqualification. The French and German markets are experiencing the most immediate compliance pressure, as national health authorities historically permitted broader protein positioning than harmonized EU standards now allow.
Direct-to-foodservice distribution models are displacing traditional wholesale intermediation in urban core markets, with processors establishing captive delivery fleets for specialty coffee accounts in London, Amsterdam, and Copenhagen. This channel restructuring is compressing distributor margins while capturing demand signals that inform production scheduling. The Benelux region exhibits the most advanced disintermediation, where processor-owned refrigerated vans now handle 40% of foodservice volume in metropolitan zones.
Europe Non-Dairy Milk Market Segmentation
European processors allocate capacity between commodity volume plays and premium functional specifications. The split between barista-grade formulations and private-label cartons determines margin capture across each segment axis.
Product Type:
Volume concentration diverges sharply from premium positioning across feedstock categories.
- Oat Milk:Enzymatically processed formulations achieve protein content between 2.5% and 3.5% with superior foaming stability for espresso applications. Specialty coffee chains in Berlin, Munich, and Paris now specify these parameters as procurement minimums, pulling capacity upgrades across Scandinavian and German processing plants.
- Almond Milk:Shelf-stable formulations dominate mature retail segments where California drought cycles have compressed input cost stability. Private-label buyers absorb margin erosion that branded players cannot sustain, particularly in French and Spanish supermarkets.
- Soy Milk:Retains dominance in food manufacturer ingredient channels despite consumer allergen concerns, supplying standardized protein bases for plant-based yogurt production.
- Coconut Milk:Concentrated in Mediterranean markets where Italian and Spanish consumers favor fat profiles for direct consumption and dessert applications.
Mature deployment sits with almond milk in ambient retail. Newer deployment is concentrated in oat milk barista-grade extraction capacity.
Distribution Channel:
Channel structure determines cold chain requirements and margin capture mechanics.
- Supermarkets:Refrigerated shelf space expansion in Germany and France outpaces Southern European markets, with Berlin and Munich retail networks leading allocation growth. EFSA labeling compliance and EU Green Deal emissions documentation accelerate listing approvals for processors with verified low-carbon feedstock sourcing.
- Online Retail:Direct-to-consumer subscription models concentrate in Benelux urban corridors, capturing demand signals that inform production scheduling for ambient-stable formulations.
- Health Food Stores:Curated premium positioning in French and Belgian independent retail supports smaller-batch organic and clean-label variants.
- Convenience Stores:Minimal penetration outside Nordic markets where chilled grab-and-go consumption patterns are established.
Supermarket refrigerated networks anchor current volume. Online retail channels are climbing the fastest for ambient-stable direct delivery.
End User:
Application specifications fragment procurement requirements across consumption contexts.
- Cafés:Artisan coffee shops specify foaming stability and protein thresholds that commodity formulations cannot meet, driving processor investment in enzymatic extraction capacity.
- Food Manufacturers:Plant-based yogurt and ice cream producers require standardized oat protein isolates with neutral flavor profiles, offering volume stability absent from retail volatility.
- Households:Direct consumption demand concentrates in German and French retail with preference for refrigerated freshness indicators.
- Restaurants:Foodservice procurement lags café channel sophistication, accepting broader specification ranges for cooking applications.
Food manufacturer supply contracts represent entrenched volume. Café channel specifications are expanding most quickly for premium extraction investment.
Packaging Type:
Packaging selection balances shelf-life extension against clean-label positioning and cold chain economics.
- Cartons:Dominant format for refrigerated oat milk in German and French supermarkets, with fiber-based structures gaining preference under EU Green Deal circular economy targets.
- Tetra Packs:Ambient-stable distribution enables reach into Eastern European markets with underdeveloped refrigerated networks, particularly Polish and Romanian retail expansion.
- Bottles:Premium positioning in health food and specialty channels supports higher price points for visual differentiation.
- Pouches:Limited adoption constrained by recycling infrastructure gaps and consumer familiarity barriers.
Tetra Pack ambient distribution anchors geographic expansion. Carton formats are gaining share fastest for refrigerated premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin and Munich retail networks are expanding refrigerated non-dairy shelf space faster than Southern European markets, anchoring Germany's position as the continent's demand nucleus. Specialty coffee chains across these cities now specify barista-grade oat milk parameters that processors must meet to secure procurement contracts.
Germany
Artisan café density in Berlin and Munich drives specification pressure on foaming stability and protein content above 2.5%. The EU Green Deal agricultural emissions documentation accelerates listing approvals for processors with verified low-carbon feedstock sourcing. Bavarian and North Rhine-Westphalia processing clusters are retrofitting enzymatic extraction capacity to meet these procurement minimums.
France
Parisian specialty coffee accounts specify oat milk performance parameters that commodity formulations cannot satisfy, pulling premium line investments from processors. EFSA protein quality scoring methodology revisions are forcing reformulation investments across soy and pea protein blends. Île-de-France and Auvergne-Rhône-Alpes distribution networks are capturing demand signals through direct-to-foodservice delivery models.
Italy
Mediterranean consumer preference for coconut milk fat profiles in direct consumption and dessert applications sustains distinct formulation demand. Artisan cafés in Milan and Rome are accelerating oat milk procurement with protein thresholds for latte art applications. Lombardy and Piedmont retail networks maintain curated premium positioning for smaller-batch organic variants.
Netherlands
Benelux urban corridors exhibit the most advanced distribution disintermediation, with processor-owned refrigerated vans handling metropolitan foodservice volume. The F-Gas Regulation compliance is reducing energy costs for chilled non-dairy milk logistics through natural refrigerant retrofits. Randstad cold chain operators report operational savings that support extended shelf-space commitments.
Poland
Supermarket chains maintain minimal refrigerated non-dairy shelf space compared to Western European norms, creating category creation economics for first-mover processors. Tetra Pack ambient distribution enables reach into underdeveloped refrigerated networks. Warsaw and Kraków direct store delivery contracts are capturing volume growth absent from retail volatility.
Europe Non-Dairy Milk Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation specification tiers, with barista-grade extraction capacity commanding procurement priority from specialty coffee chains. Scandinavian milling cooperatives control enzymatic processing capacity for high-performance oat milk, creating geographic concentration that shapes competitive access. Three archetypes dominate: controlled-distribution multinationals with supermarket anchor contracts, specialist processors with foodservice captive delivery fleets, and private-label volume defenders absorbing margin compression in ambient retail. Dominant competitive moves include strategic partnerships with specialty coffee chains and backward integration into low-carbon feedstock sourcing.
Within the controlled-distribution archetype, Danone SA and Valsoia SpA occupy positions anchored by supermarket network penetration. Among Scandinavian-based specialists, Oatly Group AB exemplifies the foodservice-focused model with direct delivery fleet deployment. These three companies represent the structural split between mass retail volume capture and premium channel specification mastery that defines European competitive positioning.
| Leading Market Players |
|---|
| Calidad Pascual SAU |
| The Hain Celestial Group Inc |
| Danone SA |
| Valsoia SpA |
| Nestlé SA |
| Oatly Group AB |
| Califia Farms LLC |
| Blue Diamond Growers |
| Alpro |
| Others |
Pricing and Supply Chain Analysis
Barista-grade versus private-label commodity bifurcation splits procurement economics across European processing capacity, with foaming stability specifications commanding premium positioning while ambient almond formulations absorb margin compression. This tier divergence concentrates pricing power with Scandinavian enzymatic processors and forces German and French retailers to allocate shelf space through EU Green Deal emissions documentation rather than volume alone.
Pricing Analysis
Value-based pricing anchors on functional performance outcomes—specifically latte art yield and espresso foam retention metrics that artisan cafés in Berlin and Paris now mandate. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein content thresholds and enzymatic processing depth, with branded barista formulations capturing margin pools unavailable to private-label commodity cartons. Pricing pressure stems from California drought-driven almond input volatility, compressing shelf-stable segment returns. Private-label buyers exhibit highest price sensitivity, absorbing margin erosion that forces branded players toward premium specification defense.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Belgium anchor hub-and-spoke patterns for chilled non-dairy logistics, with Randstad cold chain operators retrofitting natural refrigerant infrastructure under F-Gas Regulation compliance. Geographic supply concentration centers on Scandinavian milling cooperatives for enzymatic oat processing, German and Dutch plants for high-pressure sterilization capacity, and Spanish and Italian facilities for Mediterranean coconut formulations. Raw material dependencies include Nordic cereal cultivation, California almond orchards, and Southeast Asian coconut plantations. Single-source vulnerability sits with Scandinavian enzymatic capacity controlling over sixty percent of barista-grade extraction. Distribution runs through processor-owned refrigerated fleets displacing traditional wholesale intermediation in Benelux metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as REACH solvent restrictions and CSRD disclosure mandates force capital requirements beyond smaller processor reach, eliminating fragmented capacity across Southern and Eastern Europe.
For Market Incumbents: Anticipate margin compression in ambient almond segments by accelerating backward integration into low-carbon Nordic cereal sourcing that secures preferential retail listing under EU Green Deal frameworks. Defend barista-grade positioning through captive enzymatic capacity expansion in Bavarian and North Rhine-Westphalia clusters, locking specialty coffee procurement contracts ahead of Scandinavian competitor expansion. For New Entrants and Emerging Players: Direct-to-foodservice subscription platforms offer white-space penetration in Polish and Romanian markets where refrigerated retail infrastructure remains underdeveloped. Tetra Pack ambient distribution partnerships with Warsaw and Kraków supermarket chains bypass cold chain investment barriers. Target ingredient-grade oat protein isolate supply contracts with plant-based yogurt manufacturers seeking volume stability absent retail volatility. For Investors and Strategic Acquirers: Exit pathways concentrate in foodservice-focused specialists with direct delivery fleet infrastructure and verified low-carbon feedstock sourcing documentation. Long-term viability favors processors with enzymatic process engineering capabilities and CSRD-compliant supply chain transparency across the analysis window. Monitor EFSA novel food authorization timelines for fava bean and chickpea protein sources as inflection indicators for formulation diversification viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Feedstock Sourcing | EU Green Deal emissions documentation accelerates retail listing approvals for verified processors in Germany and France. |
| Enzymatic Extraction Capacity Expansion | Bavarian and North Rhine-Westphalia plant retrofits capture specialty coffee procurement contracts specifying protein thresholds above 2.5%. |
| Direct-to-Foodservice Fleet Deployment | Processor-owned refrigerated vans in Benelux metropolitan zones disintermediate traditional wholesale margins and capture demand signals. |
| High-Pressure Processing Line Adoption | German and Dutch equipment repurposing from cold-pressed juice applications achieves 12-month ambient stability without thermal flavor degradation. |
| Ingredient-Grade Supply Contract Diversification | Standardized oat protein isolate agreements with plant-based yogurt manufacturers offer volume stability insulated from retail channel volatility. |
Research Methodology
Multi-period observation of refrigerated shelf space allocation, enzymatic processing capacity utilization, and specialty coffee procurement specifications anchored the trend analysis, supplemented by interviews with plant-based category buyers at German and French supermarket chains, procurement directors at Scandinavian milling cooperatives, sustainability officers at Dutch cold chain operators, and formulation scientists at Italian and Spanish processors. Secondary validation drew from EFSA novel food authorization databases, EU Green Deal agricultural emissions reporting frameworks, REACH chemical safety regulatory filings, and Benelux retail audit data. Bottom-up volume modeling triangulated against top-down category spend estimates across the projection horizon.
Input-output matrix framing structured the analytical approach, mapping feedstock cultivation yields through enzymatic processing conversion rates to finished product distribution economics across supermarket, foodservice, and food manufacturer channels. Segmentation dimensions modeled included product type tier, distribution channel cold chain requirements, end-user application specifications, and packaging format shelf-life parameters. CAGRs derived from trend extrapolation of specialty coffee channel expansion rates and EFSA regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated F-Gas Regulation retrofit timelines and CSRD supply chain disclosure implementation phases.
The model holds under sustained EU Green Deal agricultural emissions enforcement and stable Nordic cereal harvest conditions; deviation in REACH solvent restriction phase-out schedules or California drought intensity would shift capacity allocation assumptions and pricing tier viability. Forecasts reflect documented assumption sets around specialty coffee channel growth and enzymatic process engineering talent availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
North America Dairy Alternative Market
Dairy Alternatives
Dairy-Free Spreads Market
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
Buttermilk Market
Dairy Alternatives
North America Non-Dairy Milk Market
Dairy Alternatives
Japan Dairy Alternatives Market
Dairy Alternatives
India Dairy Alternatives Market
Dairy Alternatives
Europe Non-Dairy Cheese Market
Dairy Alternatives
Coconut Milk Powder Market
Dairy Alternatives
Cheese Alternative Market
Dairy Alternatives
Breast Milk Substitutes Market
Dairy Alternatives
Oat Drinks Market
Dairy Alternatives
Pea Milk Market
Dairy Alternatives
On-The-Go Yoghurt Market
Dairy Alternatives
Non-Dairy Creamer Powder Market
Dairy Alternatives
Global Milk Replacers Market