
 Cashew Milk Market | 2026-2036
Cashew Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Cashew Milk Market Intelligence
Multi-source cashew procurement is realigning competitive economics across the Cashew Milk Market. Califia Farms leverages vertical integration into Vietnamese and Indian cashew processing to secure raw material consistency. So Delicious Dairy Free anchors its position through R&D intensity in enzymatic milling technology that improves mouthfeel without emulsifiers.
Cashew milk is an aqueous emulsion produced by blending soaked cashew nuts with water, typically containing 2-4% fat and 1% protein, then homogenized and ultra-high-temperature processed for shelf stability; it serves as a dairy substitute in beverages, cooking, and barista applications where foamability and neutral flavor profile matter. Unsweetened and organic variants dominate volume as health-conscious consumers reject added sugars, while fortified formulations with calcium and vitamin D capture the highest margin pools by commanding price premiums in pharmacy and health-store channels. Tetra Pak packaging leads ambient distribution for e-commerce fulfillment, though refrigerated cartons sustain stronger velocities in conventional grocery.
FDA food labeling standards and USDA Organic certification govern ingredient disclosure and processing claims in the United States, while the FDA's evolving stance on plant-based dairy terminology shapes permissible marketing language. Stakeholders must monitor pending FDA guidance on nutrient fortification equivalency claims, as this regulatory signal will determine whether fortified cashew milk can carry direct nutritional parity messaging against conventional dairy in retail environments.
Market Dynamics
Clean-label certification requirements from USDA Organic and Non-GMO Project verification are reshaping formulation economics, forcing processors to eliminate synthetic emulsifiers and invest in enzymatic milling infrastructure that preserves mouthfeel without additive dependence.
Growth Catalysts
- USDA Organic certification mandates:Retailers in the United States now require organic verification for shelf placement in conventional dairy aisles, pulling processors toward certified supply chains.
- Coffee shop menu reformulation:Specialty beverage chains are replacing oat milk with cashew alternatives to differentiate flavor profiles and reduce commodity cost volatility in plant-based offerings.
- Enzymatic milling technology:Advanced hydrolysis processes reduce particle size without high-pressure homogenization, cutting energy input by half while improving suspension stability.
Market Restraints
- Raw cashew price volatility:Vietnamese and Indian processing concentration exposes buyers to monsoon-driven crop failures and currency fluctuation risks.
- Protein content limitation:Cashew milk's 1% protein concentration falls below FDA nutritional equivalency thresholds for direct dairy replacement claims in school nutrition programs.
- Oat milk substitution threat:Established oat processing infrastructure and lower input costs sustain competitive pressure in barista-grade applications.
Strategic Opportunities
- Fortified pharmacy channel expansion:Calcium and vitamin D enriched formulations command premium positioning in health-store and clinical retail environments where nutritional density drives purchase decisions.
- E-commerce ambient distribution:Tetra Pak shelf-stable formats enable direct-to-consumer fulfillment without cold-chain infrastructure, opening rural and secondary market access.
- Indian domestic market development:Rising lactose intolerance diagnosis rates and established cashew processing infrastructure create localized production advantages for regional brands.
Industry Challenges
- Clean-label reformulation timelines:Removing carrageenan and synthetic vitamins while maintaining 12-month shelf stability requires 18-24 month R&D cycles that delay product launches.
- Barista foam stability certification:Third-party performance validation for latte art and microfoam texture lacks standardized testing protocols, forcing individual chain-specific qualification processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cashew Milk Market |
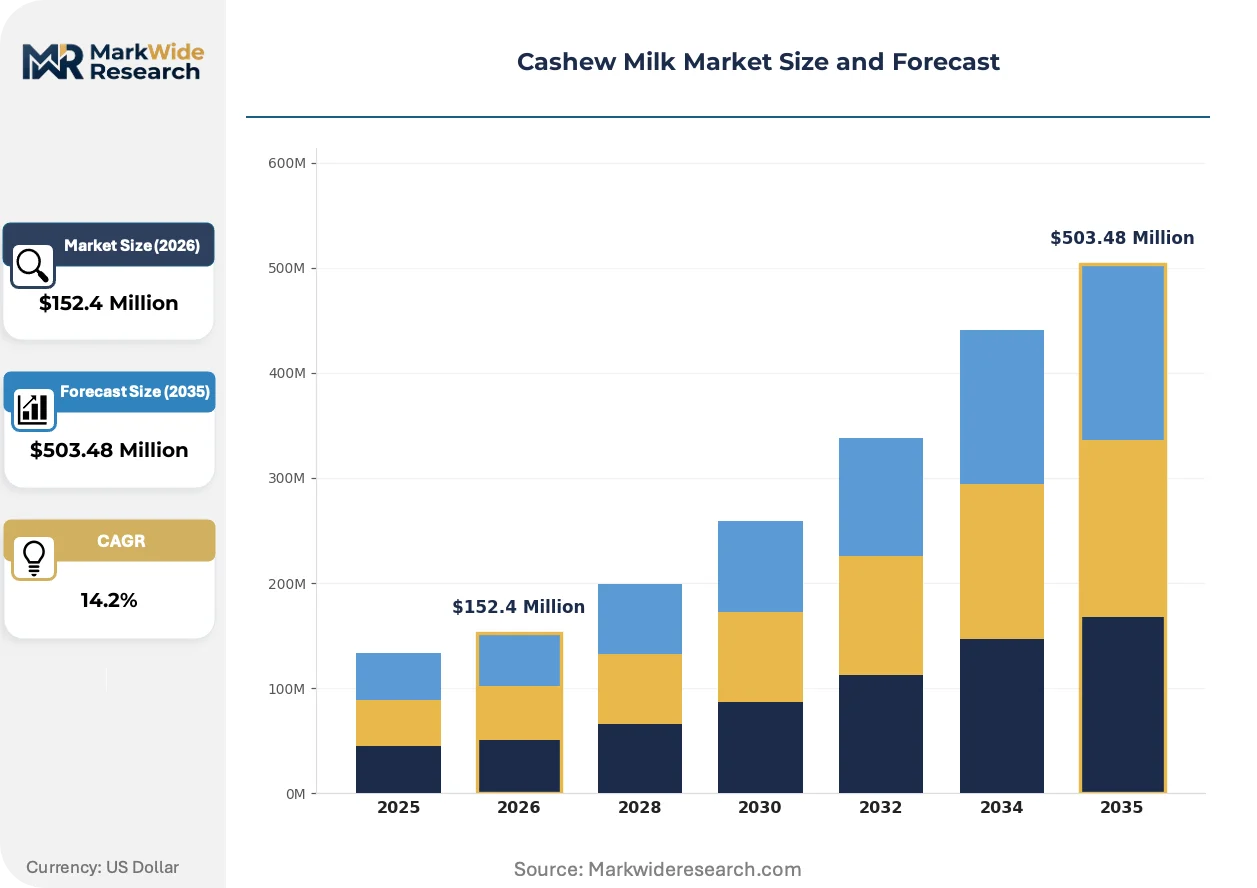
| Market Size in 2026 | $152.4 Million |
| Market Size in 2035 | $503.48 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unsweetened, Flavored, Organic, Fortified, Blended Application: Beverages, Cooking Ingredient, Bakery, Dairy Alternatives, Smoothies Packaging Type: Carton, Bottle, Tetra Pak, Pouch, Glass Jar Customer Type: Retail Consumers, Foodservice Providers, Health Stores, Specialty Stores, E-commerce |
| Companies Covered | Califia Farms, So Delicious Dairy Free, Danone (Silk), Edward & Sons Trading Co., Pacific Foods, Elmhurst Milked Direct, Hain Celestial Group, MALK Organics, Forager Project, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cashew Milk Market Strategic Shifts & Innovations
Formulation science and packaging engineering are converging to solve the tension between clean-label purity and functional performance that has constrained cashew milk's expansion beyond niche health channels.
High-pressure processing (HPP) is electrifying ambient shelf-life extension without thermal degradation of flavor compounds. Beverage manufacturers in the United States are adopting HPP lines at twice the pace of conventional UHT retort systems. This non-thermal sterilization method is electrifying premium positioning by preserving volatile aromatic molecules that UHT destroys, enabling price premiums in specialty retail.
EU Green Deal packaging mandates are forcing material transitions across European distribution networks. The F-Gas Regulation's phase-down of hydrofluorocarbon blowing agents for insulation is accelerating investment in aseptic carton barrier technologies that eliminate aluminum layers. German and French retailers are responding by sourcing fiber-based cap solutions and plant-derived barrier coatings that maintain oxygen exclusion without petroleum inputs.
Switching behavior in foodservice procurement is compressing supplier qualification cycles from annual to quarterly reviews. Restaurant groups and coffee chains are unbundling beverage sourcing from broadline distribution contracts, creating direct relationships with plant-based milk specialists. This disintermediation is most visible in United States coastal metropolitan markets where independent café density supports dedicated refrigerated logistics networks.
Cashew Milk Market Segmentation
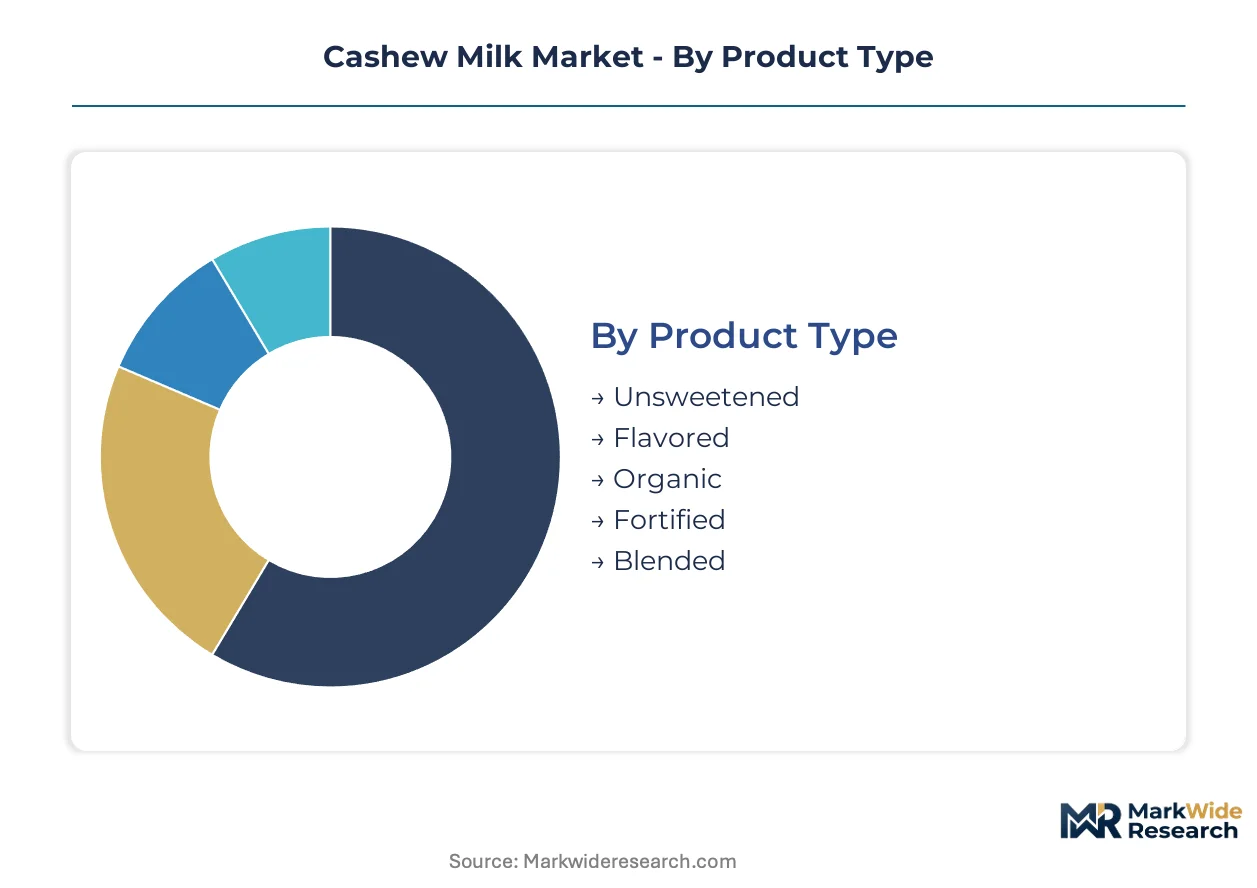
Cashew milk buyers fragment across health motivation, functional need, and channel access. Understanding these fault lines exposes where formulation investment and distribution spending yield disproportionate returns.
Product Type:
Purchase motivation splits between purity-seeking rejection of additives and targeted nutritional supplementation.
- Unsweetened:Zero-added-sugar formulations containing 2-4% cashew fat and no sweeteners command the highest household penetration in conventional grocery refrigerated sets. United States retail consumers seeking clean-label credentials drive volume here, though price compression from private-label entrants is narrowing margins.
- Fortified:Calcium and vitamin D enrichment at 30% daily value per serving captures pharmacy and health-store channels where nutritional density justifies 40-60% price premiums over base formulations. Clinical retail environments in the United States favor these SKUs for lactose-intolerant patient recommendations.
- Organic:USDA Organic certification with Non-GMO Project verification satisfies retailer mandate requirements for conventional dairy aisle placement.
- Flavored:Vanilla and chocolate variants target younger demographics and transitionary dairy consumers.
- Blended:Cashew-oat or cashew-almond combinations leverage complementary protein and foamability profiles.
Volume sits with Unsweetened; growth tilts toward Fortified.
Application:
Functional requirements diverge sharply between beverage consumption and heat-stable cooking applications.
- Beverages:Direct consumption and coffee preparation demand neutral flavor profiles and reliable foamability for latte art performance. Specialty coffee chains in the United States are expanding cashew milk menu placement as oat-fatigue drives differentiation.
- Cooking Ingredient:Sauces, soups, and curries require heat stability without protein separation. Foodservice procurement in Indian metropolitan markets favors locally processed cashew milk for traditional cuisine adaptation.
- Dairy Alternatives:Cereal accompaniment and standalone drinking positionings target retail consumers.
- Bakery:Moisture retention and fat replacement functions in vegan baking applications.
- Smoothies:Creamy texture contribution in blended beverage formulations.
Volume concentrates in Beverages; expansion accelerates fastest in Cooking Ingredient.
Packaging Type:
Cold-chain availability and shelf-life requirements determine format selection across distribution channels.
- Tetra Pak:Aseptic carton technology enables 12-month ambient shelf stability without refrigeration. E-commerce fulfillment networks in the United States rely on this format for direct-to-consumer shipping economics.
- Carton:Gable-top refrigerated cartons sustain the highest retail velocity in conventional grocery dairy cases.
- Bottle:PET and HDPE formats serve foodservice fountain and grab-and-go convenience.
- Pouch:Flexible packaging for bulk foodservice and institutional supply.
- Glass Jar:Premium positioning in specialty retail and farmers market channels.
Volume sits with Carton; growth tilts toward Tetra Pak.
Customer Type:
Procurement sophistication ranges from mass-market price sensitivity to clinical-grade nutritional specification.
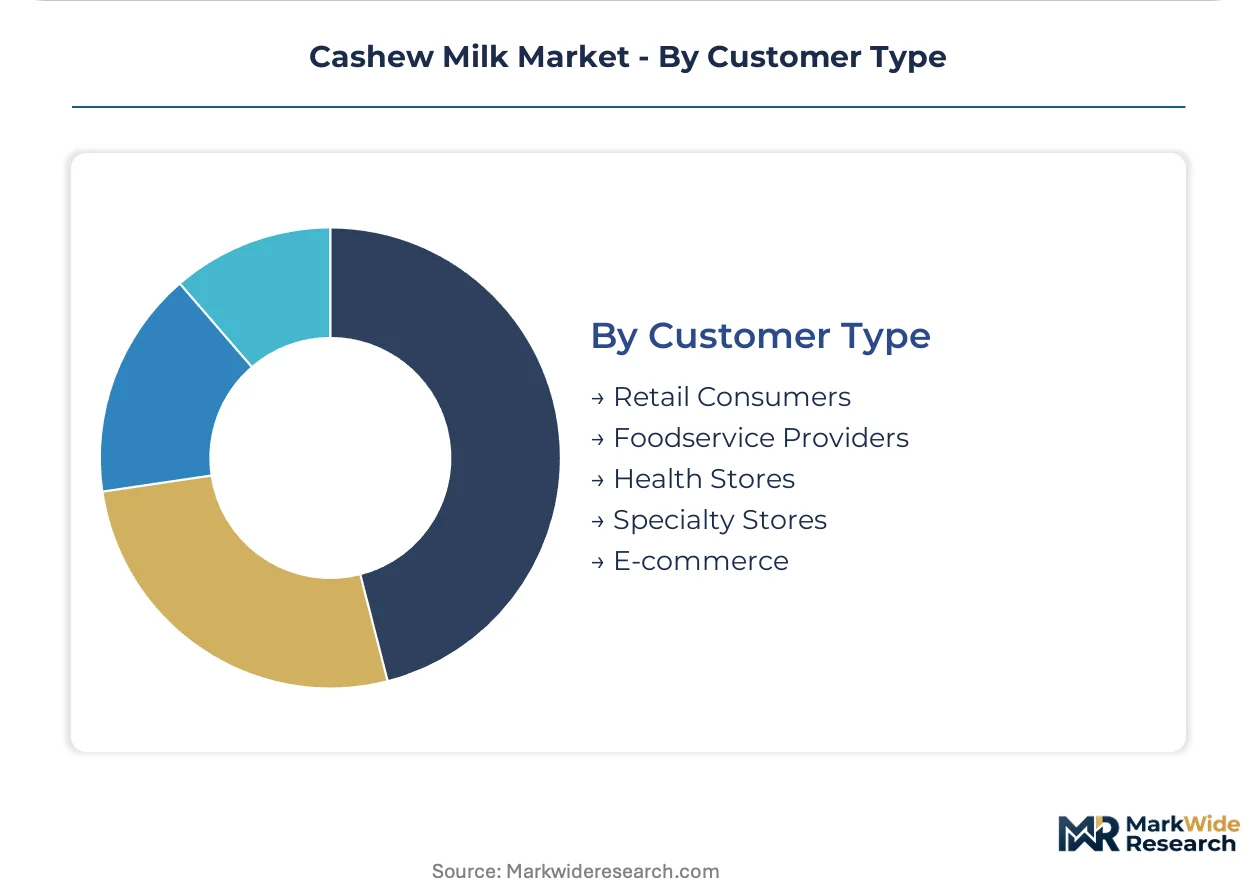
- Retail Consumers:Mass-market shoppers purchasing through conventional grocery and supermarket channels. United States refrigerated plant-based milk sets now dominate dairy aisle placement, with cashew milk gaining shelf space as almond milk saturates.
- Health Stores:Pharmacy and clinical retail environments where registered dietitians influence purchase decisions. Fortified formulations with documented bioavailability studies command preferential positioning here.
- Foodservice Providers:Restaurant groups and coffee chains conducting quarterly supplier qualification reviews. United States coastal metropolitan markets support dedicated refrigerated logistics networks for direct plant-based milk specialist relationships.
- Specialty Stores:Natural food cooperatives and independent grocers with localized assortment strategies.
- E-commerce:Direct-to-consumer subscription and ambient shelf-stable fulfillment.
Volume concentrates in Retail Consumers; expansion accelerates fastest in Foodservice Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese and Indian cashew processing clusters anchor raw material flows for cashew milk manufacturing worldwide. FDA food labeling standards and USDA Organic certification govern ingredient disclosure and processing claims in the United States. The EU Green Deal's packaging mandates and F-Gas Regulation phase-down reshape distribution economics across European markets.
United States
Refrigerated plant-based milk sets now dominate conventional dairy aisles in United States grocery channels. FDA's evolving stance on plant-based dairy terminology shapes permissible marketing language for cashew milk producers. Califia Farms leverages vertical integration into Vietnamese and Indian cashew processing to secure raw material consistency for its manufacturing operations.
Germany
EU Green Deal packaging mandates force material transitions across German distribution networks. The F-Gas Regulation's phase-down of hydrofluorocarbon blowing agents accelerates investment in aseptic carton barrier technologies that eliminate aluminum layers. German retailers source fiber-based cap solutions and plant-derived barrier coatings that maintain oxygen exclusion without petroleum inputs.
India
Rising lactose intolerance diagnosis rates and established cashew processing infrastructure create localized production advantages for regional brands. FSSAI food safety standards govern ingredient disclosure and nutritional labeling requirements for domestic cashew milk products. Maharashtra and Gujarat processing clusters concentrate raw cashew shelling and kernel preparation capacity for both export and emerging domestic plant-based milk manufacturing.
Vietnam
Monsoon-driven crop failures and currency fluctuation risks expose Vietnamese cashew processing concentration to raw material price volatility. The country's national food safety regulator oversees processing standards for export-oriented cashew kernel production. Binh Phuoc and Dong Nai provinces host the densest concentration of mechanized cashew shelling facilities supplying global plant-based milk manufacturers.
France
ANSM and DGCCRF oversight of food labeling claims shapes how cashew milk products communicate nutritional equivalency against conventional dairy. EFSA guidance on nutrient fortification bioavailability influences formulation decisions for calcium and vitamin D enriched variants. Paris metropolitan retail channels drive premium positioning for organic and clean-label certified cashew milk SKUs.
Cashew Milk Market Key Industry Players
Global majors compete with regional champions across certification standards and distribution channel access. The vendor base splits between multinational dairy alternatives portfolios and single-category plant-based specialists. Three strategic archetypes dominate: vertically integrated processors controlling upstream cashew supply, R&D-intensive clean-label formulators, and foodservice-focused barista-grade developers. Competitive moves concentrate on enzymatic milling technology licensing and direct procurement relationships with coffee chains.
Among North American clean-label specialists, Califia Farms, So Delicious Dairy Free, and Elmhurst Milked Direct exemplify contrasting approaches to formulation architecture. Califia Farms occupies a position as a vertically integrated operator with upstream control over Vietnamese and Indian processing assets. So Delicious Dairy Free anchors the R&D-intensive tier through investment in enzymatic milling infrastructure. Elmhurst Milked Direct represents the minimalist-ingredient archetype with simplified formulation protocols. Danone's Silk portfolio sits within the multinational dairy alternatives tier, leveraging broadline distribution scale against specialist positioning.
| Leading Market Players |
|---|
| Califia Farms |
| So Delicious Dairy Free |
| Danone (Silk) |
| Edward & Sons Trading Co. |
| Pacific Foods |
| Elmhurst Milked Direct |
| Hain Celestial Group |
| MALK Organics |
| Forager Project |
| Others |
Cost & Logistics Intelligence
Backward integration into Vietnamese and Indian cashew processing anchors supply security and pricing power for processors seeking to buffer raw material volatility. Captive control over kernel preparation insulates against monsoon-driven crop failures and currency fluctuation risks that otherwise transmit directly to finished goods margins.
Pricing Analysis
Certification-bundling with USDA Organic verification commands shelf placement premiums in United States conventional dairy aisles, while unbundled base formulations compete on price in private-label channels. Three-tier pricing structure across premium, standard, and economy levels separates fortified pharmacy-grade SKUs from mass-market refrigerated cartons and foodservice bulk formats. Cost compression in economy tiers is intensifying because private-label entrants replicate clean-label formulations without R&D overhead. Foodservice providers exhibit highest price sensitivity due to quarterly supplier qualification cycles, while health-store channels accept premium positioning for clinically recommended fortified variants.
Supply Chain Analysis
Regional distribution centers in United States coastal metropolitan markets enable dedicated refrigerated logistics for direct foodservice relationships. Raw cashew sourcing concentrates in Vietnam, India, and Ivory Coast processing clusters that shell and kernelize nuts for global plant-based milk manufacturing. Manufacturing draws from enzymatic milling equipment, aseptic carton barrier materials, and cold-chain infrastructure as critical inputs. Single-source vulnerability in Vietnamese crop exposure creates structural risk from monsoon pattern disruption. Distribution runs through Tetra Pak ambient networks for e-commerce fulfillment and refrigerated carton systems for conventional grocery velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cashew Milk Market sits in a technology-transition phase as enzymatic milling displaces high-pressure homogenization for clean-label mouthfeel achievement. This substitution is reshaping capital deployment toward hydrolysis infrastructure and away from legacy thermal processing lines.
For Market Incumbents: To counter oat milk's established barista-grade infrastructure and lower input costs, processors should anchor capacity addition in Vietnamese and Indian processing clusters to secure kernel supply consistency. Certification investment in USDA Organic and Non-GMO Project verification preserves conventional dairy aisle placement against retailer mandate tightening.
For New Entrants and Emerging Players: Coffee shop procurement teams represent the most penetrable channel partner type for specialty beverage chains unbundling plant-based milk sourcing from broadline distribution. White-space targets include Indian domestic market development leveraging localized processing infrastructure and pharmacy channel fortified formulations with documented bioavailability studies. Direct relationships with coastal metropolitan café networks bypass incumbent distribution chokepoints.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational dairy alternatives portfolios seeking clean-label certification assets and foodservice channel access. Long-term viability hinges on enzymatic milling technology licensing revenue streams and direct coffee chain procurement relationships. The signal to watch is FDA guidance on nutrient fortification equivalency claims that would unlock school nutrition program access.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Milling Technology Licensing | Enables clean-label mouthfeel without carrageenan dependence, satisfying USDA Organic requirements. |
| Backward Integration into Cashew Processing | Secures kernel supply consistency from Vietnamese and Indian shelling clusters against monsoon volatility. |
| Fortified Pharmacy Channel Expansion | Captures 40-60% price premiums in health-store environments where clinical recommendation drives purchase. |
| Tetra Pak Ambient Distribution Buildout | Opens e-commerce fulfillment economics without cold-chain infrastructure for rural market access. |
| Direct Coffee Chain Procurement Relationships | Bypasses broadline distribution markups in United States coastal metropolitan markets with dedicated logistics. |
Research Approach
Multi-period observation of enzymatic milling adoption rates, clean-label certification penetration, and coffee chain menu placement anchored the trend analysis, supplemented by interviews with plant-based milk R&D directors, foodservice procurement managers at specialty beverage chains, USDA Organic certification auditors, Tetra Pak packaging engineers, and pharmacy channel buyers. Secondary validation drew from FDA food labeling guidance documents, USDA Organic certification databases, FSSAI food safety standards, EU Green Deal packaging mandate texts, and customs records of cashew kernel trade flows. Bottom-up volume modeling across product type, application, packaging format, and customer type segments was triangulated against top-down market sizing from processor capacity disclosures.
Input-output matrices mapped cashew kernel supply from Vietnamese and Indian processing clusters through enzymatic milling infrastructure to finished goods distribution across refrigerated carton and Tetra Pak formats. Segmentation dimensions modeled included product type (unsweetened, fortified, organic, flavored, blended), application (beverages, cooking ingredient, dairy alternatives, bakery, smoothies), packaging type, and customer type across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating oat milk substitution effects and clean-label certification mandate diffusion. Forecast inputs included coffee chain menu reformulation velocity and FDA nutrient fortification guidance timeline.
Several conditions sit outside the modeled scope, including abrupt FDA terminology rulings on plant-based dairy labeling, severe monsoon disruption in Vietnamese growing regions, and breakthrough oat milk foamability improvements. Forecasts reflect documented assumptions about enzymatic milling cost curves and certification adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Non-Dairy Yogurt Market
Dairy Alternatives
Legumes Plant-Based Milk Market
Dairy Alternatives
Dairy Alternatives Market
Dairy Alternatives
North America Non-Dairy Milk Market
Dairy Alternatives
United Kingdom Dairy Alternatives Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
Almond Milk Market
Dairy Alternatives
Cheese Alternative Market
Dairy Alternatives
US Lactose-Free Dairy Market
Dairy Alternatives
Vegan Cheese Market
Dairy Alternatives
Non-Dairy Creamer Powder Market
Dairy Alternatives
Germany Non-Dairy Milk Market
Dairy Alternatives
Global Soy Desserts Market
Dairy Alternatives
On-The-Go Yoghurt Market
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
Coconut Yogurt Market