
 Lactose and Derivative Market | 2026-2036
Lactose and Derivative Market Size, Share, and Industry Trends Forecast 2026-2036
Lactose and Derivative Market Foresight
Precision crystallization and spray-drying advances are reshaping how pharmaceutical-grade lactose achieves particle-size consistency for inhalation-grade applications. Fonterra Co-operative Group leverages its New Zealand dairy base to sustain long-haul supply contracts into Asian pharmaceutical markets. FrieslandCampina anchors European lactose derivative production through dedicated infant nutrition and excipient lines. MEGGLE Group specializes in inhalation-grade lactose, occupying a narrow but defensible position in respiratory drug delivery.
Lactose and derivatives comprise milk sugar and its chemically or enzymatically modified forms, typically refined to purity levels exceeding 99% for pharmaceutical applications through crystallization, washing, and drying sequences. These materials serve primarily as excipients, bulking agents, and prebiotic substrates across drug manufacturing, food formulation, and animal nutrition. Pharmaceutical-grade powder dominates value capture due to stringent endotoxin and microbial limits that command price premiums over food-grade alternatives. Galactooligosaccharides represent the fastest-expanding product type as gut-health positioning drives infant formula and functional food incorporation. Food and beverages remains the largest end-use industry by volume, though pharmaceuticals generates superior margins per kilogram.
FDA enforces Current Good Manufacturing Practice standards for pharmaceutical excipients that effectively bar non-validated lactose suppliers from US drug supply chains. EMA's revised Excipient Risk Assessment Guidelines and REACH registration requirements for novel derivatives shape European product development priorities. India's CDSCO has tightened import testing protocols for lactose used in domestic generic tablet production. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP monographs, as divergence in residual protein limits could force parallel production lines or exclude suppliers from select markets.
Market Dynamics
Pharmaceutical-grade lactose supply is tightening as FDA and EMA purity mandates force manufacturers to segregate production lines, creating dedicated capacity bottlenecks that favor established excipient specialists over diversified dairy processors.
Growth Catalysts
- Inhalation-grade specifications:Respiratory drug delivery platforms require particle-size distributions below 10 microns, pulling investment toward precision crystallization infrastructure.
- EMA Excipient Risk Assessment Guidelines:Mandatory quality risk documentation for novel formulations is elevating certified lactose suppliers in European generic drug supply chains.
- Galactooligosaccharide prebiotic positioning:Infant nutrition manufacturers are reformulating around gut-health claims, expanding enzymatic derivative demand.
Market Restraints
- Whey permeate input volatility:Dairy commodity price swings transmit directly to lactose base costs, compressing margin predictability for non-integrated processors.
- German production cluster concentration:MEGGLE Group and DFE Pharma anchor European pharmaceutical-grade supply, creating geographic single-point vulnerability.
- Cellulose excipient substitution:Microcrystalline cellulose and starch derivatives are capturing tablet binder applications where lactose functionality is non-critical.
Strategic Opportunities
- India CDSCO import protocol tightening:Domestic generic manufacturers face testing delays, creating openings for validated Indian lactose producers with in-country certification.
- Continuous manufacturing integration:Direct compression tableting lines require excipient flow properties that spray-dried lactose grades uniquely satisfy.
- Biologics buffer applications:High-purity lactose derivatives are penetrating monoclonal antibody formulation as stabilizing excipients.
Industry Challenges
- Pharmacopeial harmonization gaps:Residual protein limits diverge between USP, EP, and JP monographs, forcing parallel inventory management.
- Endotoxin testing capacity:Pharmaceutical-grade certification requires LAL or rFC assay infrastructure that smaller dairy processors lack.
Report Scope
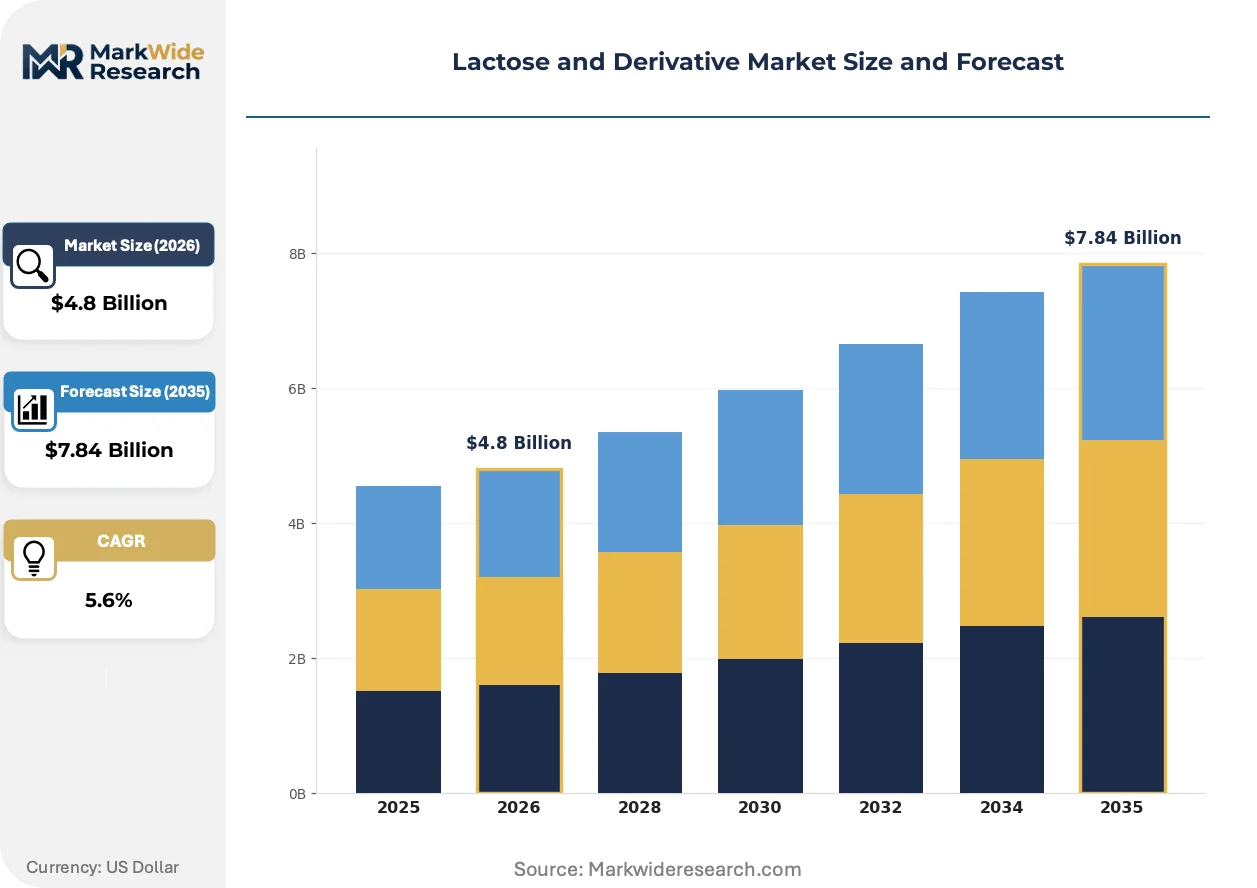
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactose and Derivative Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lactose Monohydrate, Lactose Anhydrous, Lactulose, Galactooligosaccharides End Use Industry: Pharmaceuticals, Food & Beverages, Animal Feed, Nutraceuticals Grade: Food Grade, Pharmaceutical Grade, Industrial Grade, Feed Grade Form: Powder, Granules, Crystals, Liquid |
| Companies Covered | Fonterra Co-operative Group, Koninklijke FrieslandCampina, Arla Foods, Glanbia plc, MEGGLE Group, DMK Deutsches Milchkontor, Hilmar Cheese Company, DFE Pharma, MILEI GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactose and Derivative Market Shifts & Advancements
Excipient functionality requirements are diverging as respiratory delivery systems and continuous manufacturing impose particle-engineering specifications that legacy crystallization methods cannot satisfy.
Particle engineering through spray-drying and controlled crystallization is migrating from batch pharmaceutical production toward integrated continuous manufacturing lines. Inhalation drug developers at mid-scale biotechnology firms are adopting these grades fastest, compressing the timeline between excipient qualification and commercial supply agreements.
REACH registration requirements for novel lactose derivatives are reshaping European product development priorities. ECHA substance evaluation protocols now demand extended toxicity datasets for enzymatically modified oligosaccharides, delaying launch timelines for galactooligosaccharide innovators and favoring established monograph-grade suppliers.
Specification-driven supplier consolidation is compressing approved vendor lists at multinational pharmaceutical manufacturers. Quality audit burdens are pushing procurement teams toward dual-source strategies with pre-qualified excipient specialists, most visible in German and Swiss generic drug manufacturing clusters where regulatory inspection intensity remains highest.
Lactose and Derivative Market Segmentation
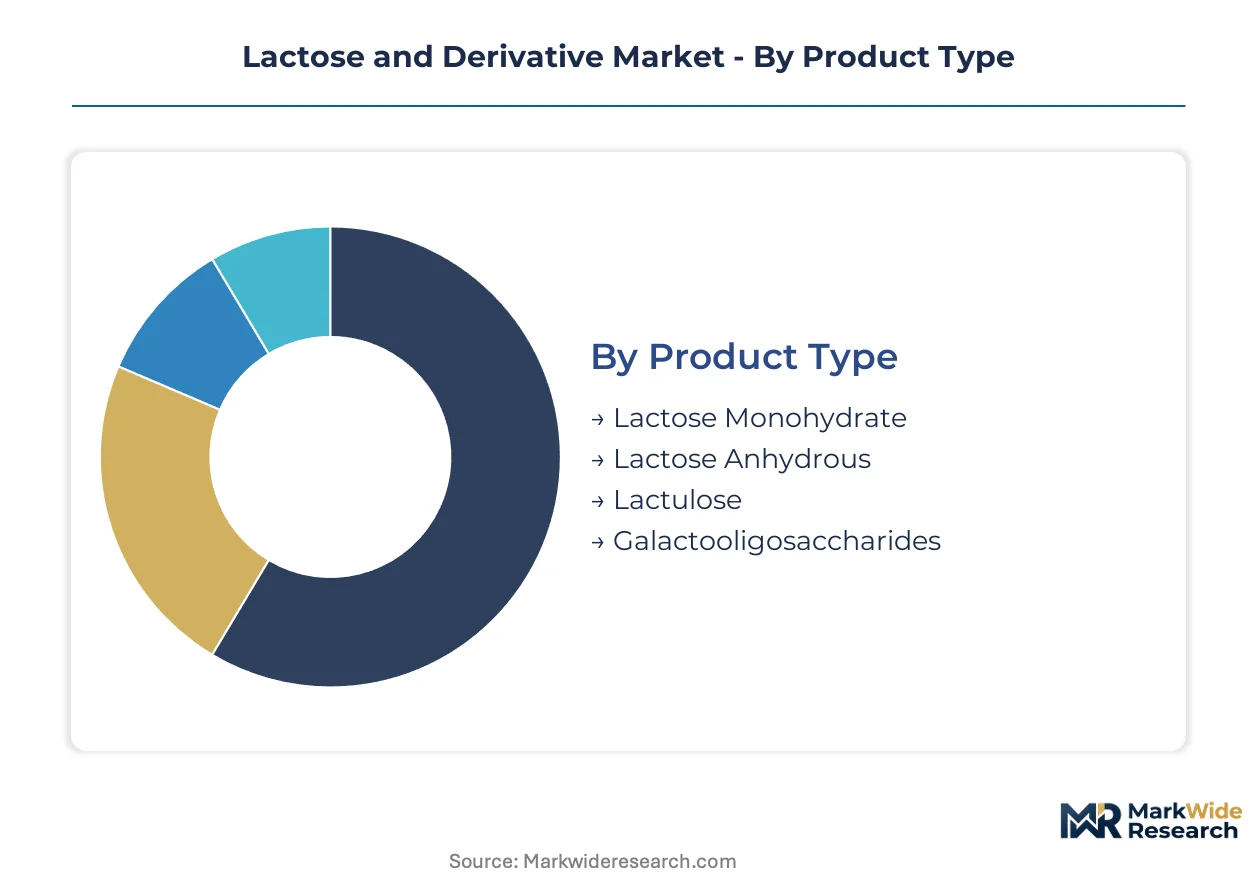
Segmentation in the lactose and derivative market separates commodity-grade bulk supply from high-margin pharmaceutical excipients. Grade certification and particle engineering specifications determine supplier eligibility for regulated drug supply chains. Each dimension captures distinct margin structures and technical barriers.
Product Type:
Application requirements dictate which chemical form of lactose or its derivatives enters specific supply chains.
- Lactose Monohydrate:Crystalline form containing one water molecule per lactose unit, stable under standard humidity conditions. Tablet manufacturers in Germany and Switzerland specify this grade for direct compression formulations where flowability and compressibility are critical.
- Galactooligosaccharides:Enzymatically derived prebiotic oligosaccharides with 2-8 galactose units linked to terminal glucose. Infant formula producers in the Netherlands and New Zealand are reformulating around gut-health positioning, pulling enzymatic production capacity from traditional lactose refining.
- Lactose Anhydrous:Water-free crystalline form with superior thermal stability for moisture-sensitive active pharmaceutical ingredients.
- Lactulose:Synthetic disaccharide of galactose and fructose used in laxative and hepatic encephalopathy therapeutics.
Lactose monohydrate commands the established base. The steepest expansion runs through galactooligosaccharides.
End Use Industry:
Customer type determines purity thresholds, regulatory burden, and pricing power across the value chain.
- Pharmaceuticals:Excipient applications demand endotoxin limits below 10 EU/g and microbial counts controlled to pharmacopeial standards. FDA Current Good Manufacturing Practice enforcement and EMA Excipient Risk Assessment Guidelines have elevated certified suppliers while excluding commodity dairy processors from drug supply chains.
- Food & Beverages:Largest volume consumption channel spanning confectionery, bakery, and dairy applications where lactose functions as a browning agent, flavor carrier, and texture modifier. European and North American processors dominate procurement.
- Nutraceuticals:Sports nutrition and dietary supplement formulations requiring intermediate purity between food and pharmaceutical grades.
- Animal Feed:Whey permeate derivatives for calf milk replacers and pet food palatability enhancement.
Food and beverages anchors volume throughput. Pharmaceuticals generates the highest margin per kilogram.
Grade:
Certification tier creates the primary commercial partition between commodity and specialty supply.
- Pharmaceutical Grade:Refined to purity exceeding 99% with validated endotoxin, microbial, and residual protein testing. Dedicated production lines in Germany and India serve generic drug manufacturers facing CDSCO import protocol tightening and USP-EP-JP pharmacopeial harmonization pressures.
- Food Grade:Standard purity for human consumption with FSSAI, EFSA, or FDA food safety compliance. Commodity pricing tracks dairy input volatility.
- Feed Grade:Lower purity specifications for animal nutrition applications.
- Industrial Grade:Technical applications in adhesives, fermentation substrates, and chemical synthesis.
Food grade maintains volume leadership. Pharmaceutical grade captures value expansion.
Form:
Physical presentation determines handling characteristics and end-use compatibility.
- Powder:Spray-dried or milled particulate with controlled particle-size distribution for tableting and dry blending. Inhalation-grade specifications below 10 microns require precision crystallization infrastructure concentrated among German and Swiss excipient specialists.
- Granules:Agglomerated particles for improved flow properties in high-speed tableting operations.
- Crystals:Purified crystalline lactose for specific dissolution profile requirements.
- Liquid:Aqueous solutions or suspensions for wet granulation and liquid dosage forms.
Powder dominates current formulation preferences. Granules are gaining share fastest in continuous manufacturing integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand dairy processors ship pharmaceutical-grade lactose across Asia-Pacific supply chains, with German and Swiss clusters dominating European respiratory drug excipient demand.
Germany
MEGGLE Group and DFE Pharma anchor specialized inhalation-grade lactose production for European generic drug manufacturers. EMA Excipient Risk Assessment Guidelines mandate quality risk documentation that elevates certified suppliers over commodity processors. The Bavarian pharmaceutical corridor concentrates spray-drying and precision crystallization infrastructure serving Swiss and German drug makers.
United States
FDA Current Good Manufacturing Practice enforcement bars non-validated lactose suppliers from domestic drug supply chains, tightening excipient certification requirements. Hilmar Cheese Company maintains pharmaceutical-grade production lines for tablet binder applications across North American generic manufacturers. California and Wisconsin dairy processing regions supply whey permeate feedstock to certified excipient refiners.
India
CDSCO import testing protocol tightening creates validation bottlenecks for domestic generic tablet producers sourcing pharmaceutical-grade lactose. Domestic manufacturers with in-country certification capture procurement shifts from delayed imports. Maharashtra and Gujarat pharmaceutical manufacturing clusters drive excipient demand for export-oriented generic drug production.
New Zealand
Fonterra Co-operative Group leverages integrated dairy base to sustain long-haul supply contracts into Asian pharmaceutical markets. The country's national food safety regulator maintains export certification alignment with USP and EP pharmacopeial standards. Canterbury and Waikato dairy regions supply whey permeate to pharmaceutical-grade refining operations.
Netherlands
FrieslandCampina operates dedicated infant nutrition and excipient production lines serving European galactooligosaccharide demand. EFSA prebiotic health claim regulations shape enzymatic derivative development priorities for gut-health positioned formulations. The Randstad dairy processing cluster concentrates lactose derivative refining capacity for continental drug and food manufacturers.
Lactose and Derivative Market Competitive Landscape
On the supply side, the industry is consolidating around pharmaceutical-grade certification barriers that exclude commodity dairy processors from drug supply chains. Three archetypes dominate: integrated dairy cooperatives with captive whey streams, specialized excipient houses with dedicated pharmaceutical lines, and regional whey processors serving food-grade bulk markets. Competitive moves center on capacity segregation for regulatory compliance and backward integration into whey permeate sourcing.
Within the specialized excipient tier, MEGGLE Group and DFE Pharma exemplify the narrow but defensible positioning in inhalation-grade lactose for respiratory drug delivery. Among integrated dairy cooperatives, Fonterra Co-operative Group and Koninklijke FrieslandCampina occupy positions spanning pharmaceutical, infant nutrition, and food-grade derivative production. These named entities anchor archetype representation rather than specific competitive actions.
| Leading Market Players |
|---|
| Fonterra Co-operative Group |
| Koninklijke FrieslandCampina |
| Arla Foods |
| Glanbia plc |
| MEGGLE Group |
| DMK Deutsches Milchkontor |
| Hilmar Cheese Company |
| DFE Pharma |
| MILEI GmbH |
| Others |
Supply & Pricing Matrix
Regulatory chokepoint concentration in German pharmaceutical-grade certification determines both the 40-60% price spread between inhalation-grade and food-grade lactose and the geographic clustering of dedicated production lines. FDA and EMA purity mandates force manufacturers to segregate capacity, creating supply scarcity that sustains premium tiers while excluding commodity dairy processors from drug supply chains.
Pricing Analysis
Processing-technology pricing gaps separate spray-dried inhalation-grade specifications from standard crystalline food-grade output. Three-tier pricing structure across pharmaceutical, food, and feed certification levels reflects endotoxin testing burdens and dedicated line requirements. Cost compression in pharmaceutical-grade tiers is intensifying because EMA Excipient Risk Assessment Guidelines extend quality documentation obligations. Generic drug manufacturers in India exhibit highest price sensitivity due to CDSCO import testing delays, while respiratory drug developers in Switzerland show lowest sensitivity given particle-engineering specifications.
Supply Chain Analysis
Tariff exposure between New Zealand and Asian pharmaceutical markets dominates supply chain risk planning for long-haul lactose contracts. Production gravity centers on Germany, New Zealand, and the Netherlands, with whey permeate feedstock drawing from Canterbury, Bavarian, and Randstad dairy clusters. Single-source vulnerability concentrates in German inhalation-grade specialists MEGGLE Group and DFE Pharma. Distribution runs through validated excipient distributors serving pharmaceutical manufacturers with pharmacopeial certification documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade lactose sits at an early-cycle expansion story as continuous manufacturing adoption and biologics buffer applications create new excipient demand vectors beyond traditional tablet binding.
For Market Incumbents: Entrench certification advantages by expanding dedicated pharmaceutical line capacity in India ahead of CDSCO domestic validation requirements. Deepen upstream control over whey permeate supply through cooperative agreements with Canterbury and Wisconsin dairy processors to offset input volatility from commodity dairy markets. For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical-grade production by securing in-country certification ahead of import protocol tightening. Target domestic generic manufacturers facing validation bottlenecks with spray-dried lactose grades optimized for direct compression tableting, leveraging local regulatory alignment as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors specialized excipient houses with validated pharmaceutical lines over diversified dairy cooperatives. Acquisition targets should display dual-source relationships with multinational drug manufacturers and endotoxin testing infrastructure. Watch for EMA-REACH harmonization announcements as the signal indicating accelerated consolidation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical Line Segregation | FDA and EMA mandates force dedicated capacity investments that exclude commodity processors from drug supply chains. |
| Backward Integration into Whey Permeate | Fonterra and FrieslandCampina anchor cost control through captive dairy base supply to refining operations. |
| Inhalation-Grade Particle Engineering | Precision crystallization infrastructure below 10-micron specifications commands premium positioning in respiratory drug delivery. |
| Indian Domestic Certification | CDSCO protocol tightening creates first-mover advantage for validated in-country producers serving generic manufacturers. |
| Continuous Manufacturing Integration | Spray-dried lactose grades with optimized flow properties capture direct compression tableting line demand. |
Research Methodology
Cross-validation between excipient procurement managers at German and Swiss generic drug manufacturers and regulatory affairs specialists at CDSCO anchors the qualitative findings. Primary interviews with pharmaceutical-grade lactose plant managers, downstream tablet formulation scientists, and infant nutrition R&D directors combined with secondary validation from FDA Current Good Manufacturing Practice guidance documents, EMA Excipient Risk Assessment Guidelines, USP-EP-JP pharmacopeial monographs, and dairy commodity trade data. Bottom-up capacity modeling and top-down pharmaceutical excipient demand estimation provided triangulation.
Calibration against historical pharmaceutical-grade lactose price spreads and certified supplier capacity additions shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include grade tier, end-use industry, particle-size specification, and regional regulatory cluster. CAGRs derived from pharmaceutical excipient volume trajectories and infant nutrition prebiotic incorporation rates, with sensitivity testing around whey permeate input cost volatility and EMA-REACH registration timelines for novel derivatives.
Sensitivities concentrate around pharmacopeial harmonization gaps between USP, EP, and JP residual protein limits and endotoxin testing capacity expansion at smaller dairy processors. Forecasts reflect assumptions about regulatory enforcement intensity and continuous manufacturing adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Colombia Dairy Market
Dairy Products
Skimmed Milk Powder Market
Dairy Products
India Dairy Market
Dairy Products
Dairy Products Market
Dairy Products
Asia-Pacific Cow Milk Minerals Market
Dairy Products
Reduced Fat Cheeses Market
Dairy Products
Germany Casein and Caseinates Market
Dairy Products
Reduced Lactose Whey Market
Dairy Products
Africa Dairy Protein Market
Dairy Products
Kefir Market
Dairy Products
Emmental Cheese Market
Dairy Products
South America Yogurt Market
Dairy Products
United States Dairy Market
Dairy Products
United States Casein Market
Dairy Products
Recombined Milk Products Market
Dairy Products
Fermented Milk Products Market