
 Japan Neodymium Iron Boron Magnet Market | 2026-2036
Japan Neodymium Iron Boron Magnet Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Neodymium Iron Boron Magnet Market Intelligence
Direct sales channels serving tier-one automotive suppliers is fragmenting as OEMs diversify magnet sourcing beyond traditional keiretsu networks. Hitachi Metals, Ltd. leverages its proprietary grain boundary diffusion technology to sustain premium positioning in high-coercivity grades. TDK Corporation anchors volume supply for consumer electronics with vertically controlled powder metallurgy operations. Shin-Etsu Chemical Co., Ltd. competes through rare earth raw material integration from upstream mining partnerships.
Neodymium Iron Boron magnets consist of an Nd2Fe14B tetragonal crystalline structure manufactured through powder metallurgy sintering or polymer bonding, delivering maximum energy products exceeding 400 kJ/m³ for compact high-torque applications. Sintered magnets dominate industrial and automotive demand due to superior magnetic flux density, while bonded magnets serve miniaturized consumer electronics where complex geometries outweigh peak field strength. The OEM end user segment concentrates procurement volumes for automotive traction motors, whereas aftermarket suppliers occupy fragmented repair and replacement demand with lower technical barriers.
METI enforces national rare earth stockpile requirements under the Act on Promotion of Recycling of Small Waste Electrical and Electronic Equipment, while JIS standards govern dimensional tolerances and corrosion resistance testing for magnet assemblies. PMDA oversight extends to medical device applications where biocompatible magnet coatings require validated manufacturing processes. Stakeholders must monitor METI's evolving critical mineral subsidy criteria and JIS revision cycles to anticipate qualification timelines for next-generation magnet grades.
Market Dynamics
Automotive OEMs in Japan are decoupling from traditional keiretsu magnet supply arrangements as domestic EV traction motor procurement scales beyond historic keiretsu capacity. METI's revised rare earth stockpiling mandates and recycling targets are forcing tier-one suppliers to requalify their entire magnet sourcing base.
Growth Catalysts
- EV Traction Motor Demand:Domestic automotive OEMs are expanding orders for high-coercivity sintered magnets as battery electric vehicle production lines activate across Kanto and Chubu manufacturing corridors.
- METI Stockpiling Mandates:The Act on Promotion of Recycling of Small Waste Electrical and Electronic Equipment tightens compliance timelines for rare earth recovery, accelerating investment in domestic magnet recycling infrastructure.
- Grain Boundary Diffusion:Proprietary heavy rare earth reduction technologies enable automotive-grade magnetic performance with lower dysprosium and terbium content, easing supply chain exposure to Chinese heavy rare earth concentration.
Market Restraints
- Raw Material Concentration:Neodymium and praseodymium oxide supply remains concentrated in Chinese separation and refining capacity, exposing Japanese magnet fabricators to export quota volatility and price transmission.
- Heavy Rare Earth Dependency:Dysprosium and terbium essential for high-temperature automotive grades lack economically viable alternative deposits outside Chinese ionic clay mining districts.
- JIS Certification Friction:Revised JIS dimensional tolerance and corrosion resistance testing protocols extend qualification timelines for next-generation magnet grades, freezing supplier switching decisions.
Strategic Opportunities
- Urban Mining Infrastructure:METI subsidy criteria for critical mineral recovery create white space for industrial-scale magnet dismantling and rare earth separation facilities in Osaka-Kobe industrial zones.
- Medical Device Convergence:PMDA biocompatibility pathways for implantable magnet assemblies open premium pricing tiers for coated sintered magnets in surgical robotics and drug delivery systems.
- Direct OEM Procurement:Tier-one automotive suppliers are establishing direct magnet purchasing relationships with fabricators, bypassing traditional trading house intermediaries and capturing margin compression.
Industry Challenges
- Metallurgical Talent Scarcity:Powder metallurgy sintering expertise and grain boundary diffusion process engineering skills are concentrating at a handful of legacy fabricators, constraining capacity expansion.
- Dual Certification Burden:Simultaneous JIS standard compliance and automotive OEM proprietary validation protocols extend new supplier qualification to 18-24 month cycles.
- Legacy Equipment Integration:Bonded magnet injection molding lines require substantial retooling to handle next-generation polymer compounds with elevated magnetic powder loading ratios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Neodymium Iron Boron Magnet Market |
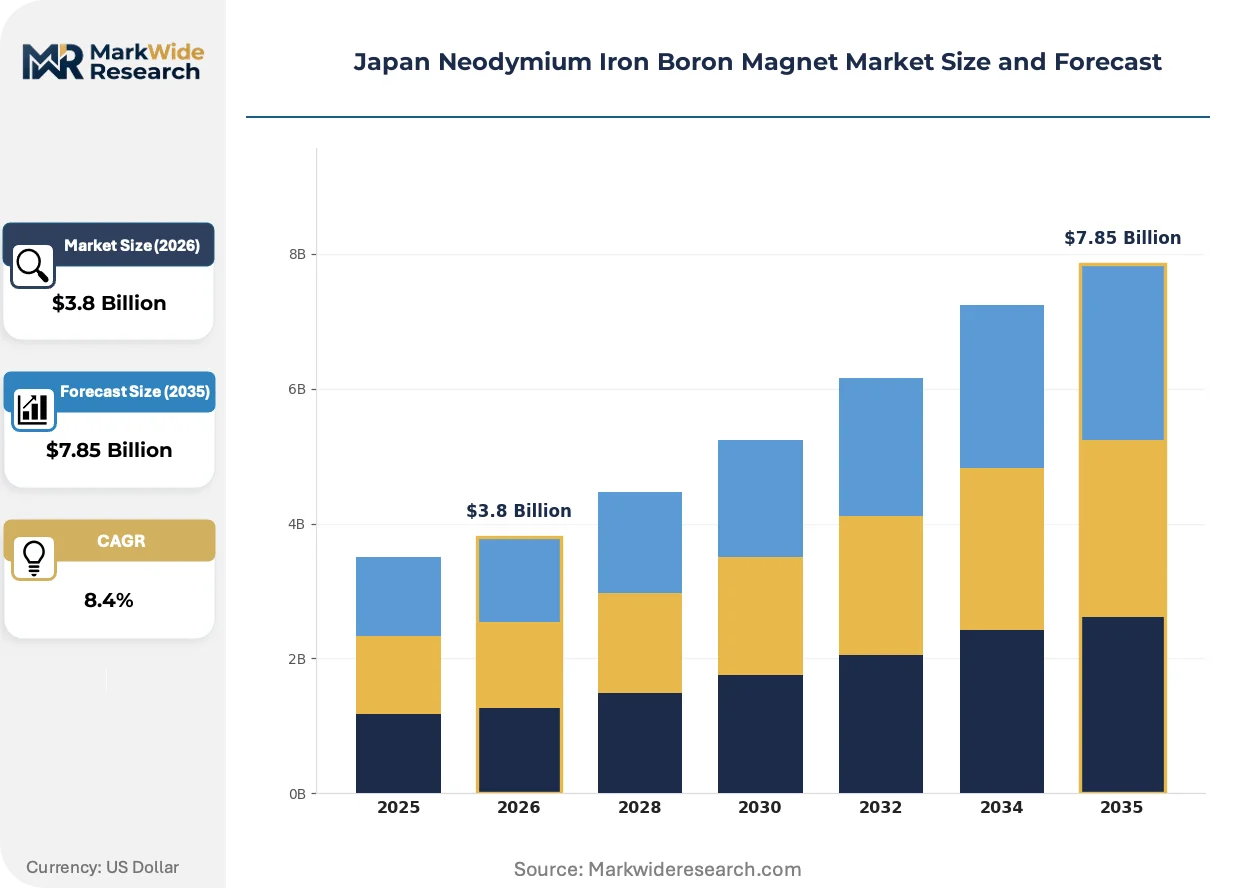
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bonded Magnets, Sintered Magnets, Milled Magnets, Others Application: Consumer Electronics, Automotive, Renewable Energy, Industrial Equipment End User: OEMs, Aftermarket Suppliers, Research Institutes, Defense Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Daido Steel Co., Ltd., Mitsubishi Materials Corporation, Hitachi Metals, Ltd., NEOMAX Co., Ltd., Sumitomo Special Metals Co., Ltd., TDK Corporation, Toshiba Materials Co., Ltd., Nippon Denko Co., Ltd., Shin-Etsu Chemical Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Neodymium Iron Boron Magnet Market Strategic Shifts & Innovations
Magnet fabrication technology in Japan is pivoting toward heavy rare earth minimization as automotive OEMs demand cost stability alongside thermal performance. Regulatory pressure on supply chain provenance is accelerating domestic recycling and alternative sourcing investments.
Grain boundary diffusion technology is migrating from niche aerospace applications into mainstream automotive traction motor supply. Hitachi Metals and TDK Corporation have operationalized production-scale GBD lines that reduce dysprosium content by 40-50% while maintaining 200°C coercivity ratings. Toyota Motor Corporation and Nissan Motor Company have qualified GBD-based magnet assemblies for 2026-2028 EV platform launches, compressing the adoption timeline from laboratory to volume production to under five years.
METI's revised rare earth stockpile requirements under the Act on Promotion of Recycling of Small Waste Electrical and Electronic Equipment now mandate 60-day minimum inventory coverage for designated critical minerals. Magnet fabricators must document upstream provenance through separation and mining stages to qualify for national subsidy programs. Tier-one automotive suppliers in the Kanto corridor are most affected, with several establishing dedicated compliance teams to manage JIS standard alignment alongside METI reporting obligations.
Automotive OEM procurement departments are consolidating magnet supplier panels from twelve-plus vendors to four-to-six strategic partners, compressing switching cycles and demanding multi-year price commitments. Trading houses that historically intermediated rare earth oxide and magnet transactions are losing share to direct OEM-fabricator contracts. This concentration is most visible in Toyota Motor Corporation's supplier base, where magnet procurement has centralized through a single designated tier-one with captive sintering capacity.
Japan Neodymium Iron Boron Magnet Market Segmentation
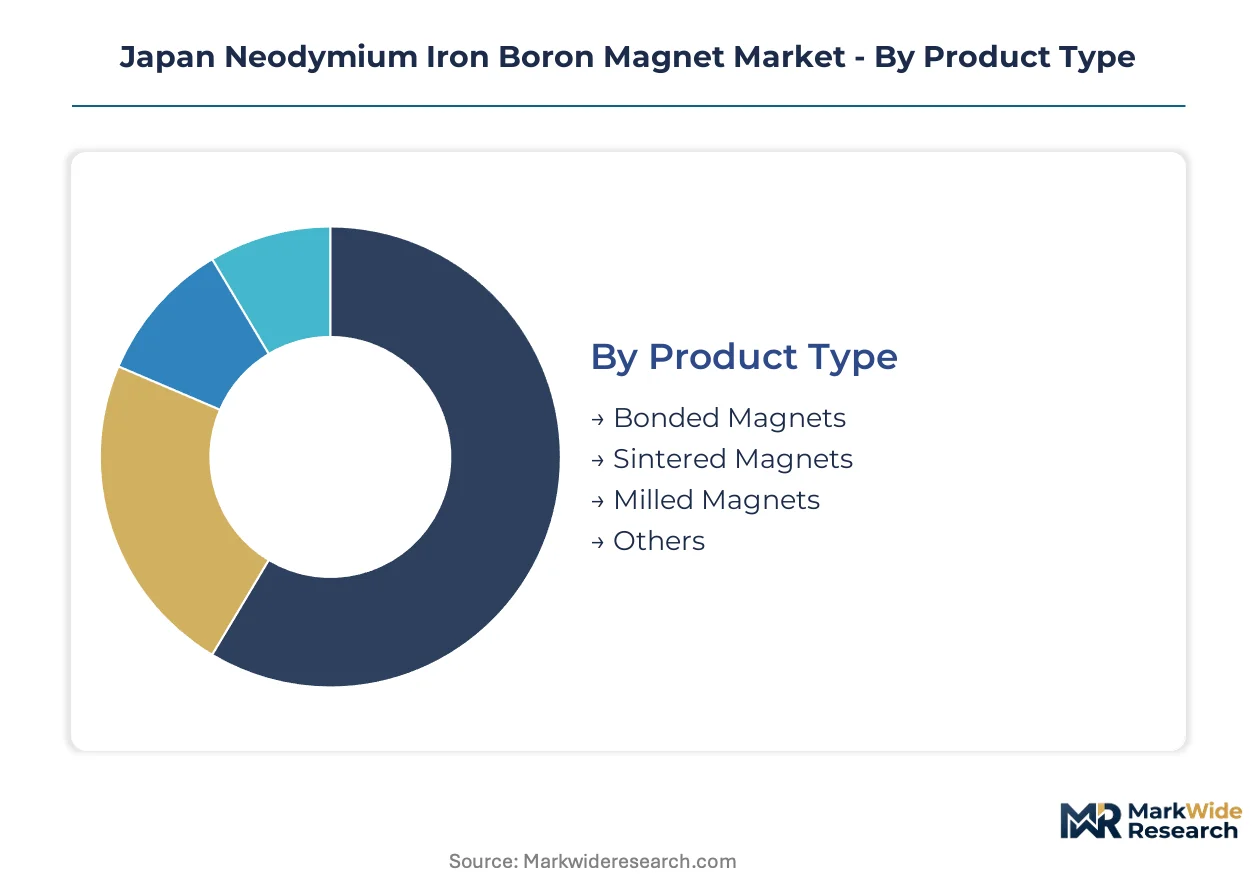
Segmentation in Japan's magnet market reveals divergent procurement cycles across product grades and end-use verticals. Automotive OEMs impose 18-24 month qualification timelines that freeze supplier relationships, while consumer electronics buyers rotate bonded magnet contracts quarterly based on spot pricing.
Product Type:
Sintered magnets turn over slowest due to embedded qualification investments, whereas bonded magnets refresh fastest through injection molding flexibility.
- Sintered Magnets:Powder metallurgy consolidation of Nd2Fe14B crystalline structures yields maximum energy products exceeding 400 kJ/m³. Automotive traction motor procurement in Kanto manufacturing corridors concentrates here, with METI stockpiling mandates forcing fabricators to document upstream provenance through mining stages.
- Bonded Magnets:Polymer matrix encapsulation of magnetic powder enables complex geometries for miniaturized applications. Consumer electronics assembly lines in Osaka-Kobe industrial zones rotate bonded magnet suppliers fastest, driven by quarterly cost-down targets and polymer compound innovation cycles.
- Milled Magnets:Precision-machined sintered blanks serve niche industrial automation requiring tight dimensional tolerances under JIS standards.
- Others:Emerging additive-manufactured magnet prototypes and experimental thin-film depositions occupy pre-commercial research phases.
Sintered magnets anchor the volume base while bonded magnets gain share at the steepest rate.
Application:
Cost tier stratification separates premium thermal-grade automotive demand from price-sensitive consumer electronics procurement.
- Automotive:Traction motor assemblies require heavy rare earth-doped sintered grades maintaining 200°C coercivity ratings. Toyota Motor Corporation and Nissan Motor Company have qualified grain boundary diffusion-based magnet assemblies for forthcoming EV platform launches, compressing adoption timelines.
- Consumer Electronics:Miniaturized bonded magnet configurations prioritize complex geometries over peak field strength. Smartphone and wearable device manufacturers in Tokyo-Yokohama electronics clusters drive the fastest contract rotation cycles.
- Renewable Energy:Direct-drive wind turbine generators demand large-diameter sintered rings with corrosion-resistant coatings for offshore installations.
- Industrial Equipment:Servo motors and magnetic couplings in Chubu manufacturing belts utilize standard-grade sintered magnets with JIS-certified dimensional tolerances.
Automotive applications command the highest margin tier while consumer electronics contracts expand most quickly.
End User:
Customer type determines procurement sophistication, with OEMs demanding multi-year price commitments and aftermarket suppliers accepting spot-market flexibility.
- OEMs:Tier-one automotive suppliers are consolidating magnet supplier panels from twelve-plus vendors to four-to-six strategic partners. Direct OEM-fabricator contracts are displacing traditional trading house intermediaries, compressing switching cycles and capturing margin compression.
- Aftermarket Suppliers:Fragmented repair and replacement demand operates with lower technical barriers and minimal qualification overhead.
- Research Institutes:National laboratories and university consortia pilot next-generation grain boundary diffusion variants and heavy rare earth reduction formulations.
- Defense:Specialized high-reliability grades for aerospace and naval applications operate under classified procurement protocols with extended vendor vetting.
OEMs anchor procurement volume concentration while research institutes climb the fastest as METI subsidy criteria accelerate domestic innovation investment.
Distribution Channel:
Supply chain configuration separates direct relationships with fabrication expertise from arms-length trading house transactions.
- Direct Sales:Fabricators with captive sintering capacity engage automotive OEM procurement departments through multi-year framework agreements. Hitachi Metals and TDK Corporation leverage proprietary grain boundary diffusion technology to sustain premium positioning through direct channels.
- Distributors:Regional trading houses serving smaller industrial equipment manufacturers maintain inventory positions for standard-grade bonded and sintered magnets.
- Online Retail:E-commerce platforms capture prototype quantities and research-grade samples with minimal order minimums.
- Wholesalers:Bulk commodity trading of rare earth oxides and unmagnetized blanks supplies downstream fabricators.
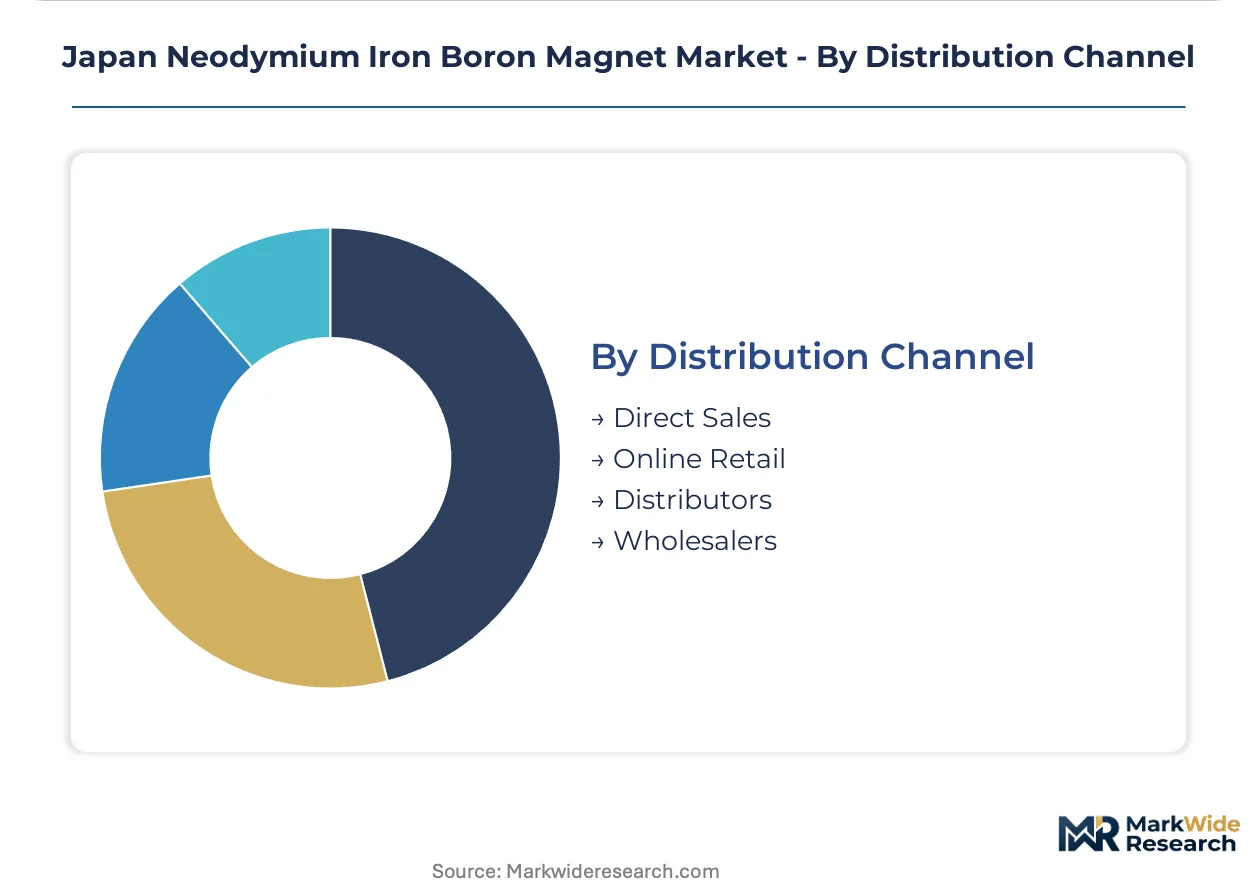
Direct sales channels dominate value capture while online retail expands most quickly for low-volume research and prototyping demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Yokohama anchors magnet logistics for the Kanto industrial corridor, handling rare earth oxide imports and finished magnet exports through dedicated bulk terminals. Containerized magnet shipments move through Tokyo Bay feeder networks to automotive assembly plants in adjacent prefectures.
Kanto/Tokyo
Automotive OEM traction motor procurement concentrates here, with Toyota Motor Corporation and Nissan Motor Company headquarters driving qualification cycles for grain boundary diffusion magnet assemblies. METI enforces 60-day rare earth stockpile minimums through the Act on Promotion of Recycling of Small Waste Electrical and Electronic Equipment. The Keihin industrial belt spanning Tokyo, Kanagawa, and Saitama prefectures hosts tier-one magnet fabricators supplying direct-drive EV platforms.
Kansai/Osaka
Consumer electronics bonded magnet demand rotates fastest in this corridor, with smartphone and wearable device manufacturers compressing supplier contracts to quarterly cycles. JIS dimensional tolerance standards govern precision-machined magnet blanks serving industrial automation. The Osaka-Kobe manufacturing zone attracts METI subsidy applications for urban mining infrastructure targeting end-of-life magnet recovery.
Chubu/Nagoya
Industrial equipment servo motor procurement dominates regional magnet consumption, with magnetic coupling applications in automotive parts manufacturing. PMDA biocompatibility pathways for implantable magnet assemblies open premium pricing tiers for coated sintered grades. The Nagoya-Toyota City corridor maintains captive sintering capacity for just-in-time automotive supply chains.
Kyushu
Renewable energy direct-drive wind turbine generator demand drives large-diameter sintered ring procurement for offshore installations. Heavy rare earth dependency for high-temperature grades exposes fabricators to Chinese ionic clay supply concentration. The Kitakyushu industrial zone hosts corrosion-resistant coating facilities for marine-grade magnet assemblies.
Tohoku
Research institutes and national laboratories pilot next-generation heavy rare earth reduction formulations under METI innovation subsidies. Defense-aerospace magnet applications operate under classified procurement protocols with extended vendor vetting. The Sendai technology corridor connects university consortia to tier-one fabricators for prototype-to-production scaling.
Japan Neodymium Iron Boron Magnet Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream controlling magnetic powder metallurgy and grain boundary diffusion processes. The vendor base concentrates among legacy fabricators with captive sintering capacity, while trading houses lose intermediary share to direct OEM procurement. Three archetypes dominate: vertically integrated rare earth-to-magnet producers, technology-licensed powder specialists, and automotive-captive tier-one suppliers. Competitive moves center on multi-year framework agreements locking in volume commitments and backward integration into rare earth separation partnerships.
Among Japan-based fabricators, Hitachi Metals, Ltd., TDK Corporation, and Shin-Etsu Chemical Co., Ltd. occupy distinct positioning tiers. Hitachi Metals exemplifies the technology-differentiated archetype through proprietary process control. TDK Corporation anchors volume supply relationships with consumer electronics clusters. Shin-Etsu Chemical represents upstream-integrated positioning through mining partnerships. Each occupies a strategic position without direct overlap in core customer segments.
| Leading Market Players |
|---|
| Daido Steel Co., Ltd. |
| Mitsubishi Materials Corporation |
| Hitachi Metals, Ltd. |
| NEOMAX Co., Ltd. |
| Sumitomo Special Metals Co., Ltd. |
| TDK Corporation |
| Toshiba Materials Co., Ltd. |
| Nippon Denko Co., Ltd. |
| Shin-Etsu Chemical Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Underutilized heavy rare earth separation capacity in Chinese ionic clay mining districts is compressing dysprosium and terbium oxide premiums, forcing Japanese magnet fabricators to absorb cost volatility through contract renegotiations with automotive OEMs while METI stockpiling mandates lock in minimum inventory carrying costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates grain boundary diffusion-enabled automotive grades from conventional sintered magnets and bonded consumer electronics variants. Price differentiation hinges on JIS corrosion resistance certification tier and quarterly volume commitments exceeding ten-ton lots. Pricing pressure stems from OEM consolidation of supplier panels from twelve-plus vendors to four-to-six strategic partners. Consumer electronics buyers in Osaka-Kobe clusters exhibit highest price sensitivity through quarterly contract rotation, whereas automotive traction motor procurement locks in multi-year frameworks with lowest sensitivity.
Supply Chain Analysis
Chinese export quota volatility for neodymium and praseodymium oxide dominates supply chain risk exposure for Japanese fabricators. Raw material sourcing draws from Chinese separation and refining capacity, Malaysian light rare earth deposits, and Australian hard rock mining operations. Heavy rare earth dependency rests on Chinese ionic clay districts for dysprosium and terbium feedstocks. Distribution runs through direct OEM-fabricator framework agreements displacing traditional trading house intermediaries, with Port of Yokohama handling bulk oxide imports and containerized finished magnet exports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Japan Neodymium Iron Boron Magnet Market is entering a cyclical recovery phase as domestic EV traction motor procurement scales beyond historic keiretsu capacity, with automotive OEM platform launches driving volume commitments through the projection horizon.
For Market Incumbents: Pre-empt supplier panel consolidation by securing multi-year framework agreements with Toyota Motor Corporation and Nissan Motor Company before qualification cycles freeze switching decisions. Deepen backward integration into rare earth separation partnerships to reduce exposure to Chinese oxide export quota volatility. Invest in grain boundary diffusion capacity expansion to defend premium positioning against technology-licensed powder specialists.
For New Entrants and Emerging Players: Establish a beachhead in medical device magnet assemblies where PMDA biocompatibility pathways create qualification barriers protecting niche premium tiers. Target urban mining infrastructure development in Osaka-Kobe industrial zones under METI subsidy criteria for critical mineral recovery. Pursue joint development agreements with national laboratories in Tohoku to access prototype-to-production scaling pathways.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated rare earth-to-magnet producers with captive sintering capacity and established JIS certification credentials. Five-to-ten year viability favors fabricators demonstrating operational grain boundary diffusion lines and direct OEM procurement relationships. Monitor METI critical mineral subsidy disbursement velocity as the inflection signal for domestic recycling infrastructure investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Grain Boundary Diffusion Scale-Up | Reduces dysprosium content by 40-50% while maintaining 200°C coercivity ratings for automotive traction motors. |
| Urban Mining Infrastructure Development | Captures METI subsidies for end-of-life magnet dismantling and rare earth separation in Osaka-Kobe zones. |
| Direct OEM Procurement Relationships | Bypasses trading house intermediaries to capture margin compression in consolidated supplier panels. |
| JIS Certification Investment | Accelerates qualification timelines for next-generation magnet grades amid revised dimensional tolerance protocols. |
| Heavy Rare Earth Reduction R&D | Mitigates supply chain exposure to Chinese ionic clay concentration through proprietary formulation development. |
Research Approach
Operator-level perspectives from magnet fabrication plant managers, tier-one automotive supplier procurement leads, rare earth trading house executives, and METI critical minerals policy officers anchored the qualitative base. Primary interviews combined with secondary validation from customs trade data, JIS standard revision filings, SEC 10-K disclosures by listed fabricators, and METI subsidy program documentation. Bottom-up demand modeling across sintered and bonded magnet product types triangulated against top-down supply capacity assessments.
Scenario-bracketing framed volume and value outputs across the analysis window through sensitivity testing of EV adoption trajectories and rare earth oxide price bands. Segmentation dimensions modeled include product type, application vertical, end-user category, and distribution channel structure. CAGRs derived from regression analysis of historical procurement volumes against automotive production forecasts and consumer electronics shipment data. Industry-specific inputs incorporated grain boundary diffusion adoption curves and METI stockpiling compliance cost burdens.
Sensitivities concentrate around Chinese rare earth export policy shifts, automotive OEM platform launch delays, and JIS certification timeline extensions. Forecasts reflect assumptions regarding keiretsu decoupling velocity and urban mining infrastructure buildout rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Copper Magnet Wire Market
Magnetic Materials
Amorphous Soft Magnetic Materials Market
Magnetic Materials
Magnetite Nanoparticles Market
Magnetic Materials
Magnetic Carbon Nanofoam Market
Magnetic Materials
Magnet Market
Magnetic Materials
North America Ferrite Magnet Market
Magnetic Materials
North America Samarium Cobalt Magnets Market
Magnetic Materials
Global Non Grain-Oriented Electrical Steel Market
Magnetic Materials
Sintered Magnet Market
Magnetic Materials
Global Soft Magnetic Alloys Market
Magnetic Materials
Magnetic Material Magnetization and Testing Equipment Market
Magnetic Materials
Europe Ferrite Magnet Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
Magnetostrictive Materials Market
Magnetic Materials
Samarium Cobalt Magnets Market
Magnetic Materials
Global Neodymium Magnet Market