
 Copper Magnet Wire Market | 2026-2036
Copper Magnet Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Magnet Wire Market Intelligence
The gap between premium high-temperature insulation grades and commodity enamelled stock is consolidating around thermal class ratings and conductor purity specifications. Tongling Jingda Special Electromagnetic Wire Co., Ltd leverages captive copper refining and enamel coating integration to dominate mid-voltage motor supply in Asia. Hitachi Metals Ltd sustains leadership in ultra-fine magnet wire for precision electronics through proprietary in-house reduction mills. Sumitomo Electric Industries, Ltd. anchors its position with polyimide enamel formulations serving aerospace and defense coil requirements.
Copper magnet wire consists of high-purity electrolytic copper drawn to precise diameters and coated with synthetic enamel or polymer insulation, typically rated from Class F at 155°C through Class H at 180°C and above, serving as the conductive core in electromagnetic coils that convert electrical to mechanical energy. Enamelled copper wire occupies the largest volume share across electric motor windings where slot fill efficiency determines power density, while polymer insulated wire commands premium positioning in high-voltage traction motors requiring multi-layer extruded barriers. Tri-filar wire configurations are gaining structural importance in compact transformer designs where interleaved windings reduce leakage inductance.
China's GB standards and NMPA oversight enforce conductor purity and insulation thickness minimums for domestic supply, while the EU F-Gas Regulation and REACH framework restrict certain solvent-based enamel chemistries in European manufacturing. The US NHTSA and EPA coordinate efficiency mandates that indirectly tighten magnet wire specifications for automotive traction motors and charging infrastructure. Stakeholders must monitor divergence between regional thermal class certification requirements as export compliance costs reshape competitive access across major motor manufacturing hubs.
Market Dynamics
Slot fill efficiency mandates in electric vehicle traction motors are compressing insulation thickness tolerances and thermal class requirements, forcing wire producers to synchronize enamel coating precision with stator winding automation.
Growth Catalysts
- Dual carbon goals:China's NMPA enforcement of GB standards for conductor purity and energy efficiency is accelerating domestic plant upgrades and export-grade capacity expansion.
- High-temperature motor windings:Class H and above insulation ratings are penetrating industrial motor rebuilds as power density requirements intensify in Germany's manufacturing sector.
- Tri-filar configurations:Interleaved winding architectures are gaining structural importance in compact transformer designs where leakage inductance reduction determines performance.
Market Restraints
- Electrolytic copper volatility:Cathode price swings transmit directly into magnet wire cost structures, compressing margin buffers for enamel coaters without captive refining.
- Solvent-based enamel restrictions:The EU F-Gas Regulation and REACH framework are eliminating certain polyester-imide chemistries, forcing reformulation investments.
- Aluminum substitution in low-duty motors:Cost-sensitive appliance manufacturers are migrating stator windings to aluminum magnet wire in thermal classes below 155°C.
Strategic Opportunities
- India's PLI scheme for EV components:Domestic stator manufacturing incentives are creating localized demand for Class F and H enamelled copper supply.
- Polyimide-polyetherimide hybrid enamels:Aerospace coil specifications are opening premium positioning for wire producers with multi-layer extrusion capabilities.
- Direct-to-winder distribution:Motor OEMs are bypassing traditional wire distributors for mill-direct procurement with just-in-time coating schedules.
Industry Challenges
- Slot fill automation integration:Stator winding robotics require magnet wire with enhanced lubricity and consistent elongation, demanding coating chemistry adjustments.
- Thermal class certification timelines:IEC and NEMA testing protocols for new insulation systems extend qualification cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Magnet Wire Market |
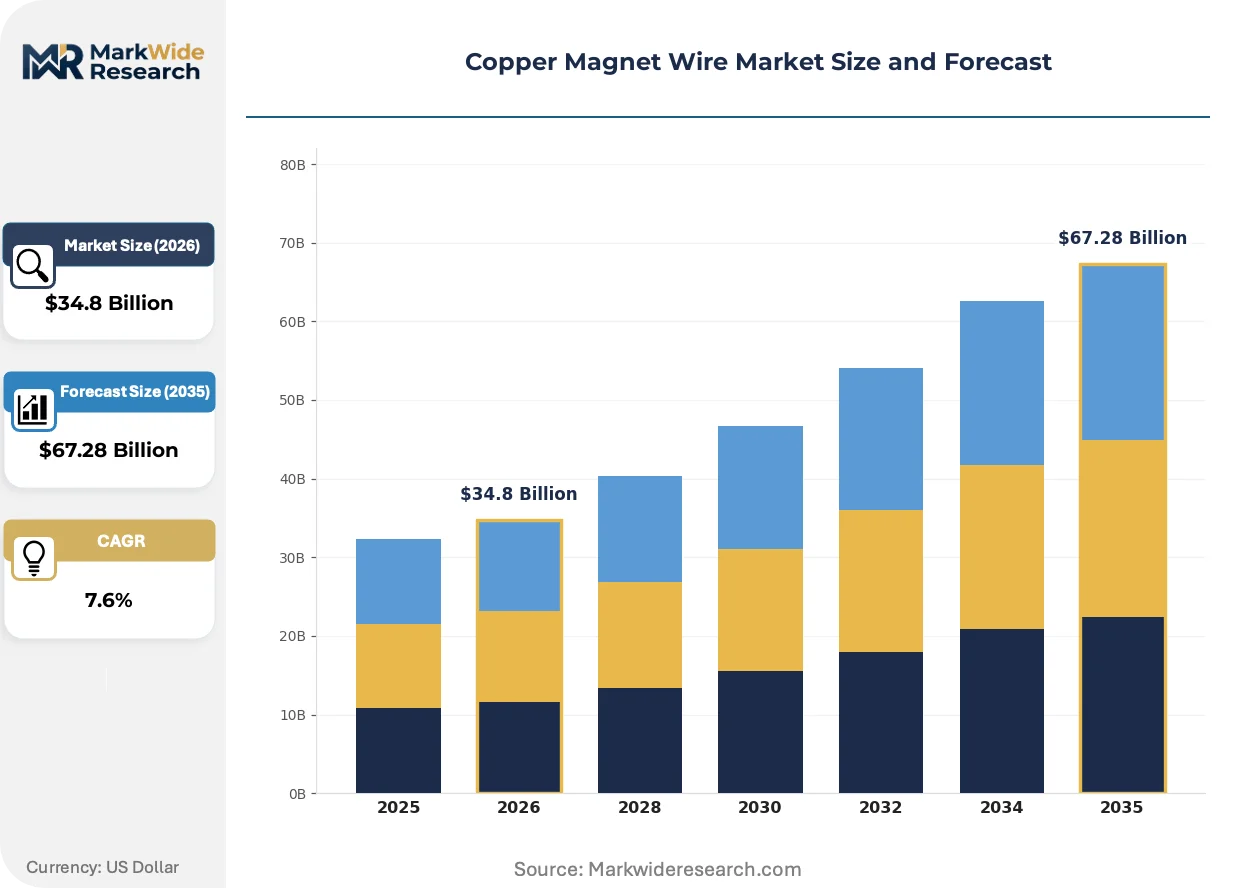
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $67.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enamelled Copper Wire, Ribbon Wire, Polymer Insulated Wire, Tri-Filar Wire, Hemp Insulated Wire Technology: Class F Insulation, Class H Insulation, Polyurethane Enamel, Polyimide Enamel, Polyester Enamel Application: Electric Motors, Transformers, Relays, Generators, Inductors End User: Electrical Equipment Makers, Appliance Manufactures, Telecom Equipment Providers, Automotive Tier-1 Suppliers, Consumer Electronics Brands |
| Companies Covered | Tongling Jingda Special Electromagnetic Wire Co., Ltd, Hitachi Metals Ltd, Sumitomo Electric Industries, Ltd., TE Connectivity, Fujikura Ltd, LS Cable & System Ltd., Rea Magnet Wire Company Inc., Altana AG, Superior Essex Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Magnet Wire Market Strategic Shifts & Innovations
Material science advances in polymer insulation and conductor processing are redefining performance benchmarks across thermal classes, while regulatory chemistry restrictions and procurement model compression reshape competitive access.
Polyimide enamel formulations with enhanced corona resistance are converging with 800V traction motor architectures, enabling thinner insulation layers without dielectric breakdown. EV powertrain engineers at German and Chinese OEMs are specifying these grades for hairpin winding applications. The technology is converging with slot fill targets above 70%, compressing the viable supplier base to coaters with precision tension control.
REACH Annex XVII restrictions on certain isocyanate-based enamel hardeners are eliminating legacy coating lines across European manufacturing. Wire producers in Germany and Italy are retrofitting solvent recovery systems or migrating to waterborne polyester-imide alternatives. The regulatory pressure falls heaviest on mid-voltage industrial motor suppliers serving EU export markets.
Specification consolidation by tier-one automotive suppliers is compressing the approved vendor list for traction motor wire. Stator manufacturers are consolidating procurement around coaters with integrated copper rod production and in-house enamel formulation. This concentration is most visible in China's Yangtze River Delta EV manufacturing clusters, where mill-direct contracts now dominate high-volume Class H supply.
Copper Magnet Wire Market Segmentation
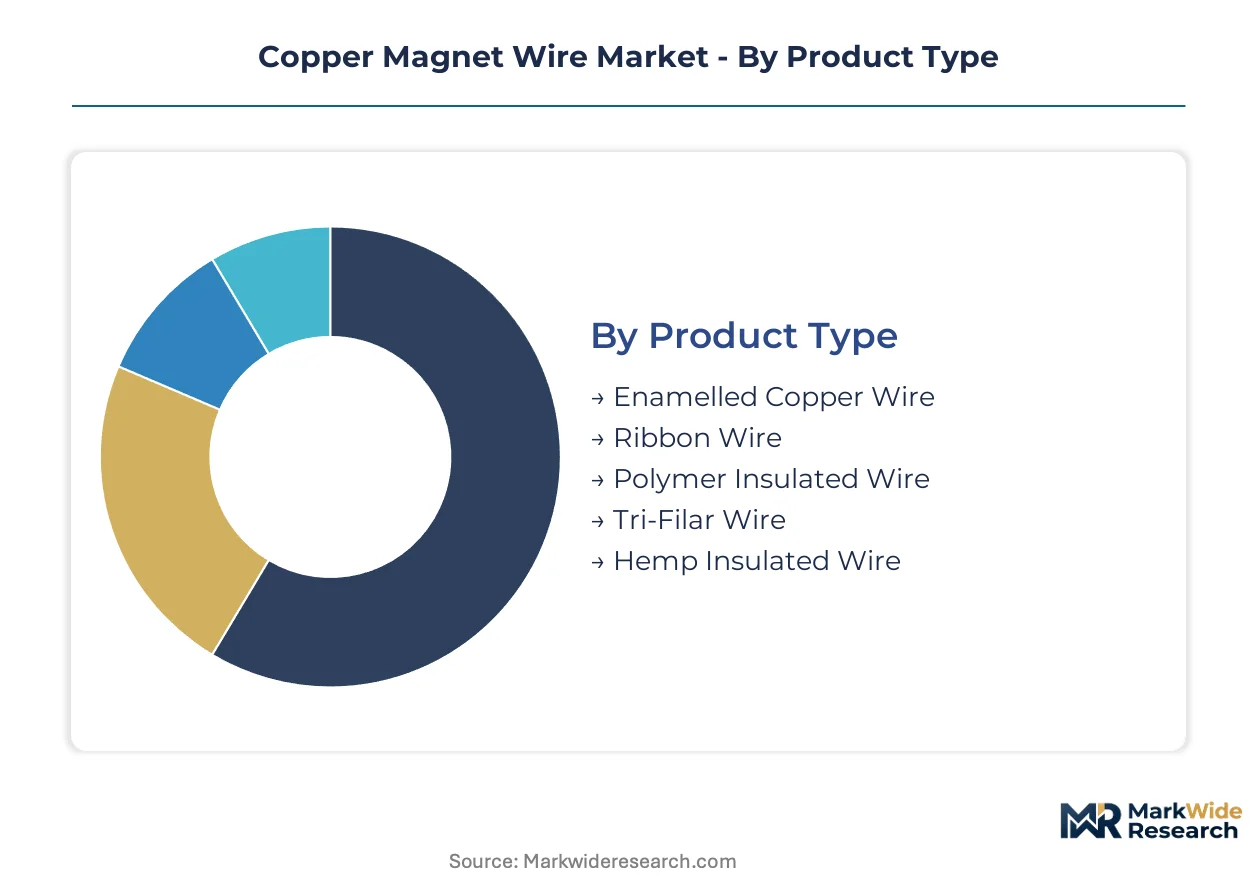
Segmentation in copper magnet wire markets tracks the tension between commodity enamelled stock for volume motor applications and precision-engineered insulation systems for power-dense EV traction architectures. Wire producers configure coating lines, thermal class certifications, and distribution channels around these structural divides.
Product Type:
Standalone wire products serve discrete procurement channels, while embedded configurations integrate directly into stator and transformer manufacturing lines.
- Enamelled Copper Wire:High-purity electrolytic copper drawn to precise diameters and coated with synthetic enamel insulation, typically rated Class F through Class H. Demand concentrates in China's Yangtze River Delta EV stator clusters where slot fill efficiency above 70% compresses insulation thickness tolerances.
- Polymer Insulated Wire:Multi-layer extruded polymer barriers over copper conductors, commanding premium positioning in 800V traction motors requiring enhanced dielectric strength. Procurement by German automotive OEMs for hairpin winding applications is accelerating qualification cycles for coaters with precision tension control.
- Ribbon Wire:Rectangular cross-section conductors maximizing slot fill in compact motor designs.
- Tri-Filar Wire:Interleaved winding configurations reducing leakage inductance in compact transformers.
- Hemp Insulated Wire:Legacy natural fiber insulation retaining niche applications in heritage equipment rebuilds.
Enamelled copper wire leads volumes today; polymer insulated wire is gaining share fastest.
Technology:
Cost tier stratification separates commodity enamel chemistries from aerospace-grade polyimide formulations requiring extended qualification timelines.
- Class H Insulation:180°C thermal rating with enhanced thermal endurance for high-power density motors. Germany's industrial motor rebuild sector is standardizing on these grades as power density mandates intensify.
- Polyimide Enamel:Aromatic polymer formulations delivering superior corona resistance and thermal stability. Aerospace coil specifications in the US and EU are opening premium positioning for coaters with multi-layer extrusion capabilities.
- Class F Insulation:155°C rating dominating mid-voltage industrial motor applications.
- Polyurethane Enamel:Self-bonding properties enabling precision coil winding in electronics.
- Polyester Enamel:Cost-effective base chemistry facing REACH-driven reformulation pressure in European manufacturing.
Class F insulation retains the broadest installed base; polyimide enamel is climbing the fastest.
Application:
Application segmentation maps directly to customer technical requirements, from slot fill efficiency in rotating machines to frequency response in magnetic components.
- Electric Motors:Stator and rotor windings where conductor purity and insulation thickness determine power density. China's NMPA enforcement of GB standards is accelerating domestic plant upgrades for EV traction motor supply.
- Transformers:Core and coil assemblies requiring interleaved winding architectures for leakage inductance control. Demand from India's distribution infrastructure expansion is creating localized supply requirements.
- Relays:Electromechanical switching coils prioritizing space efficiency.
- Generators:Field and armature windings in power generation equipment.
- Inductors:Frequency-selective magnetic components in power electronics.
Electric motors anchor current demand; transformer applications show steepest expansion trajectory.
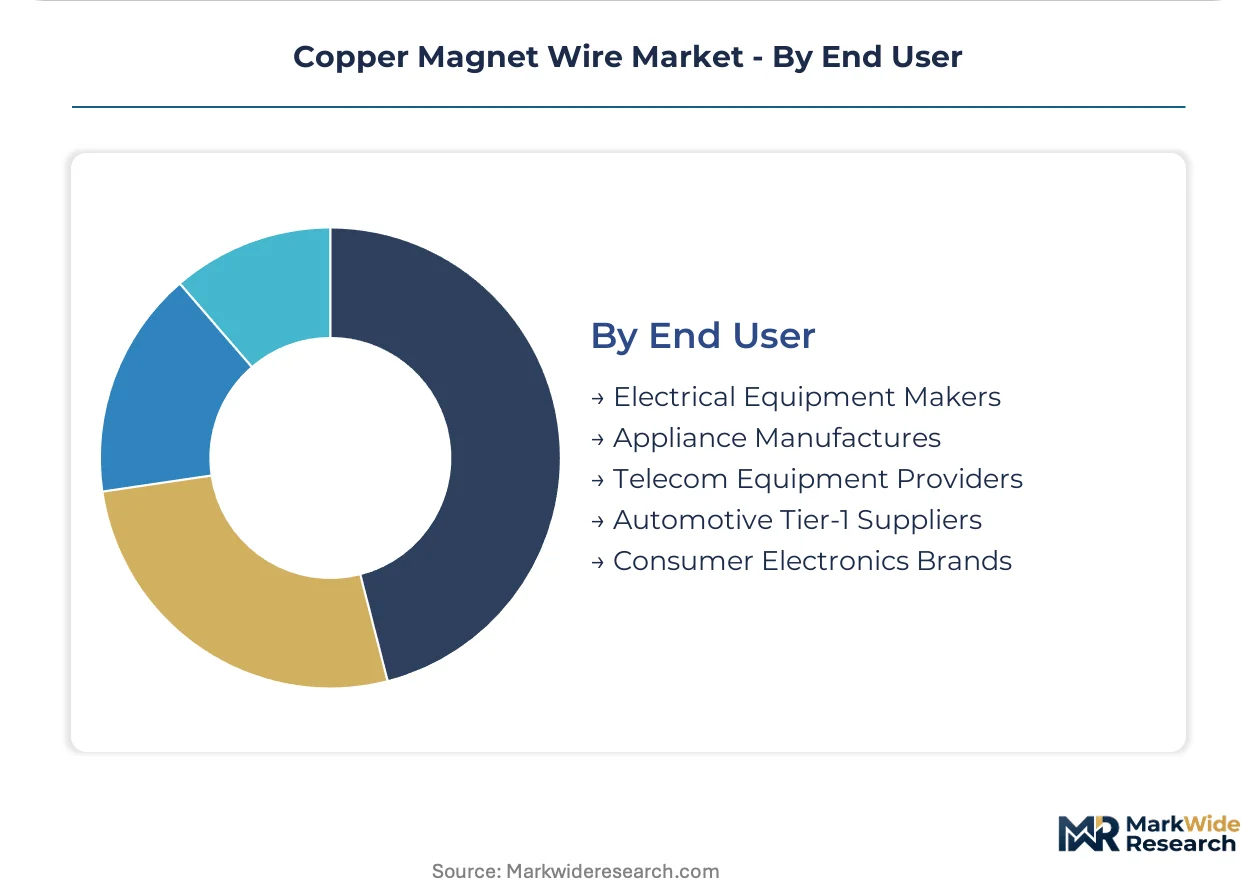
End User:
Customer type determines procurement model, from mill-direct contracts with automotive tier-ones to distributor-mediated supply for fragmented appliance manufacturing.
- Automotive Tier-1 Suppliers:Stator manufacturers consolidating procurement around coaters with integrated copper rod production and in-house enamel formulation. Specification consolidation is compressing approved vendor lists across German and Chinese EV manufacturing clusters.
- Electrical Equipment Makers:Industrial motor OEMs procuring Class H wire for rebuild programs and new equipment. Germany's manufacturing sector is driving standardization on high-temperature insulation grades.
- Appliance Manufacturers:Cost-sensitive producers migrating low-duty motor windings to aluminum substitution below 155°C thermal classes.
- Telecom Equipment Providers:Precision inductor and transformer requirements for network infrastructure.
- Consumer Electronics Brands:Ultra-fine magnet wire specifications for compact coil applications.
Electrical equipment makers represent the largest procurement volume; automotive tier-1 suppliers are expanding their share most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's EV stator manufacturing clusters outpace Germany's industrial motor rebuild sector in magnet wire procurement velocity, while India's component localization incentives reshape supply chain geography across Asia.
China
Dual carbon goals and NMPA enforcement of GB standards accelerate domestic plant upgrades for conductor purity and energy efficiency. MIIT coordination with SAMR tightens insulation thickness minimums for export-grade capacity. Yangtze River Delta EV manufacturing clusters concentrate mill-direct procurement contracts for high-volume Class H enamelled supply.
Germany
Industrial motor rebuild programs standardize on Class H insulation ratings as power density mandates intensify across manufacturing. EU F-Gas Regulation and REACH framework eliminate certain polyester-imide chemistries, forcing reformulation investments. Bavaria's automotive tier-one suppliers compress approved vendor lists around coaters with integrated copper rod production.
United States
NHTSA and EPA efficiency mandates tighten magnet wire specifications for automotive traction motors and charging infrastructure. Aerospace coil specifications in defense and commercial aviation open premium positioning for multi-layer extrusion capabilities. Southeast industrial corridors attract stator winding automation investments requiring enhanced lubricity wire grades.
India
PLI scheme incentives for EV components create localized demand for Class F and H enamelled copper supply. CEA distribution infrastructure expansion drives transformer winding requirements with interleaved architectures. Gujarat and Tamil Nadu manufacturing zones concentrate domestic stator production capacity for automotive tier-one procurement.
Japan
METI industrial efficiency programs sustain precision electronics demand for ultra-fine magnet wire specifications. JIS standards certification maintains qualification barriers for export-oriented coil suppliers. Kansai and Chubu manufacturing belts anchor polyimide enamel formulation capabilities serving aerospace and defense requirements.
Copper Magnet Wire Market Key Industry Players
Top-tier vendors anchor integrated copper refining and enamel coating operations, while mid-tier coaters without captive metal supply face margin compression from cathode price volatility. The vendor base stratifies around thermal class certification depth, precision tension control capabilities, and geographic proximity to EV stator clusters. Three archetypes dominate: backward-integrated Asian metal producers, European specialty enamel formulators, and North American distribution-anchored coaters. Competitive moves concentrate on mill-direct contract consolidation and solvent recovery system retrofitting for REACH compliance.
Within the integrated-production archetype, Tongling Jingda Special Electromagnetic Wire Co., Ltd and Sumitomo Electric Industries, Ltd. occupy positions exemplifying captive copper refining paired with in-house enamel formulation. Hitachi Metals Ltd. represents the precision-specialist tier, with company nomenclature indicating Japanese origin and ultra-fine wire positioning.
| Leading Market Players |
|---|
| Tongling Jingda Special Electromagnetic Wire Co., Ltd |
| Hitachi Metals Ltd |
| Sumitomo Electric Industries, Ltd. |
| TE Connectivity |
| Fujikura Ltd |
| LS Cable & System Ltd. |
| Rea Magnet Wire Company Inc. |
| Altana AG |
| Superior Essex Inc. |
| Others |
Cost & Logistics Intelligence
Captive copper refining paired with in-house enamel coating anchors supply position and pricing power for integrated producers serving China's Yangtze River Delta EV clusters, while coaters without upstream metal control face margin compression from cathode price volatility transmitted through spot market exposure.
Pricing Analysis
Capacity additions in China's Jiangsu and Zhejiang provinces are reshaping price floors for Class H enamelled wire as domestic producers expand high-temperature coating lines. Three-tier pricing structure across aerospace-grade polyimide, automotive Class H, and industrial Class F levels separates coaters by thermal class certification depth and conductor purity. Cost compression in mid-voltage industrial segments is intensifying because REACH-driven reformulation investments in European manufacturing are eliminating legacy polyester-imide chemistries. Appliance manufacturers below 155°C thermal classes exhibit highest price sensitivity, while aerospace coil specifications show lowest sensitivity due to qualification barriers and performance requirements.
Supply Chain Analysis
Regional distribution centers in Germany's Bavaria and China's Shanghai corridor operate hub-and-spoke patterns for mill-direct automotive procurement. Manufacturing concentrates in China, Germany, and Japan, with each anchoring distinct thermal class specializations. Raw material flows draw from electrolytic copper cathode, polyimide resin formulations, and solvent-based enamel chemistries. Single-source vulnerability runs through polyimide resin supply concentrated among specialty chemical producers. Distribution runs through direct-to-winder contracts bypassing traditional wire distributors for just-in-time coating schedules synchronized with stator winding automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
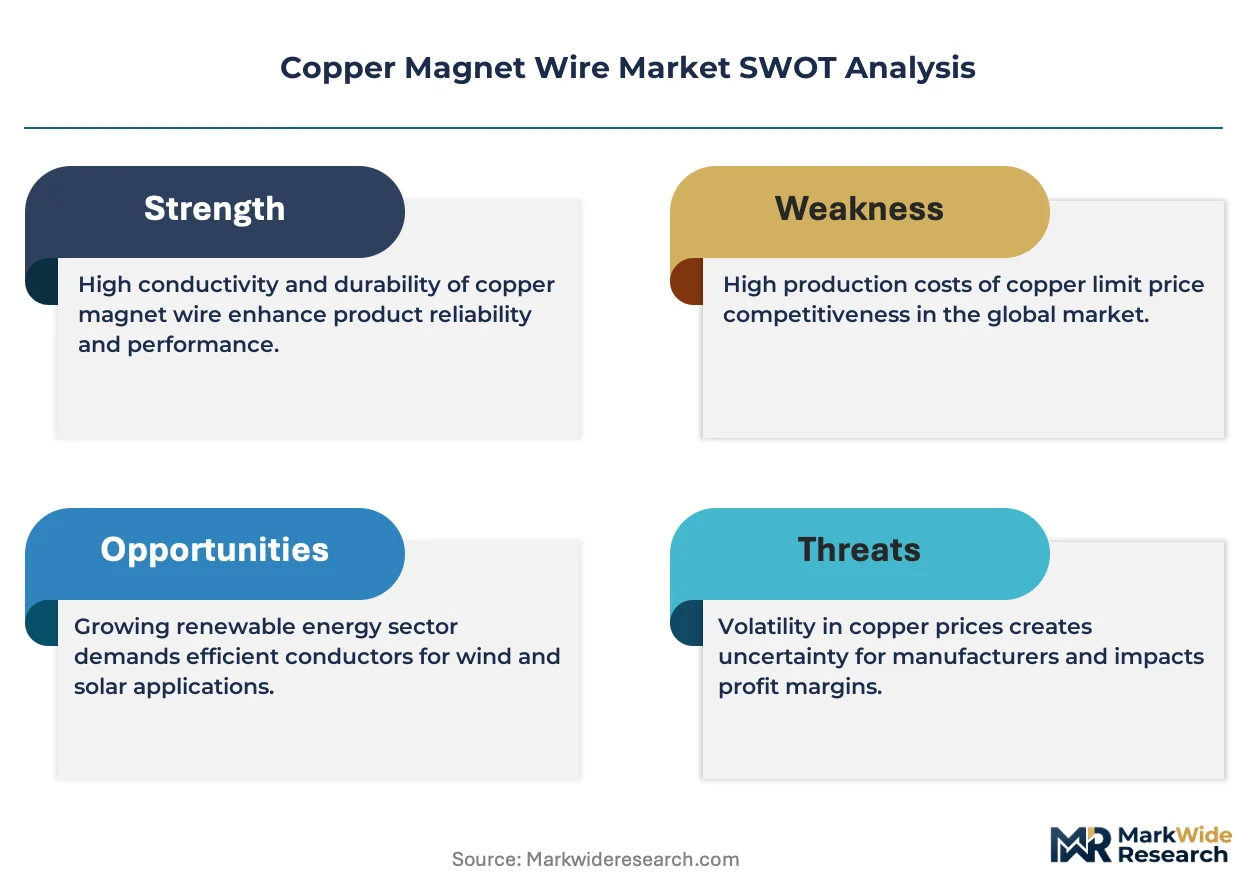
Margin expansion opportunities concentrate in premium thermal class migration and solvent recovery system retrofits that lower compliance costs, as aluminum substitution pressure at the economy tier compresses returns for undifferentiated coaters.
For Market Incumbents: Extend polyimide enamel formulation capabilities to capture aerospace and 800V traction motor premiums, while retrofitting solvent recovery systems to defend position against REACH-driven elimination of legacy coating lines in European manufacturing. Backward integration into captive copper rod production anchors supply security against cathode price volatility. For New Entrants and Emerging Players: The price-point gap between premium polyimide formulations and commodity Class F enamel creates entry space for hybrid polyester-imide alternatives with enhanced thermal performance. India's PLI scheme for EV components offers the most penetrable geography, with Gujarat and Tamil Nadu manufacturing zones concentrating domestic stator production. A mill-direct distribution model with just-in-time coating schedules aligns with automotive tier-one procurement consolidation. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier European coaters with REACH compliance investments already deployed because regulatory barriers protect acquired cash flows from new entrant competition. Target archetypes: German and Italian enamel formulators with solvent recovery systems and existing automotive qualifications. Watch for aluminum substitution acceleration in appliance motors as signal of economy-tier demand destruction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Rod Production | Captive cathode supply insulates margin from LME volatility for Yangtze Delta coaters. |
| Solvent Recovery System Retrofit | REACH compliance protects EU market access for polyester-imide coating lines. |
| Polyimide-Polyetherimide Hybrid Formulation | Multi-layer extrusion capabilities open aerospace coil specifications with 18-24 month qualification cycles. |
| Direct-to-Winder Distribution Model | Mill-direct contracts bypass traditional distributors for automotive tier-one procurement consolidation. |
| India PLI Scheme Localization | Gujarat and Tamil Nadu manufacturing zones capture domestic stator demand from EV component incentives. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with magnet wire plant managers, automotive tier-one procurement leads, enamel formulation chemists, and stator winding automation engineers with secondary validation against customs trade data, SEC filings from publicly listed wire producers, MIIT capacity disclosures, and IEC thermal class certification registries. Bottom-up segment sizing triangulated against top-down market construction.
Segment-weighting approaches distributed value and volume across product type, thermal class technology, application, and end-user dimensions, with regional production cluster intensity applied as a cross-cutting modifier. CAGRs derived from elasticity modeling against EV powertrain penetration rates and industrial motor rebuild cycles. Forecast inputs incorporated NMPA enforcement timelines for GB standard upgrades and REACH Annex XVII restriction phase-in schedules.
Caveats apply where electrolytic copper price volatility, regulatory reformulation timelines, or aluminum substitution acceleration could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Global Non-Oriented Electrical Steel Market
Magnetic Materials
High Performance Magnet Market
Magnetic Materials
High Performance Permanent Magnet Market
Magnetic Materials
Magnetic Plastics Market
Magnetic Materials
Magnetic Filter Market
Magnetic Materials
Europe Magnet Wire Market
Magnetic Materials
Global Soft Magnetic Alloys Market
Magnetic Materials
Ferromanganese Market
Magnetic Materials
North America Samarium Cobalt Magnets Market
Magnetic Materials
Iron Oxide Market
Magnetic Materials
North America Magnet Market
Magnetic Materials
Global Magnetic Beads Market
Magnetic Materials
Europe Copper Magnetic Wire Market
Magnetic Materials
Gadolinium Market
Magnetic Materials
Global Bonded Magnet Market
Magnetic Materials
North America Magnet Wire Market