
 North America Samarium Cobalt Magnets Market | 2026-2036
North America Samarium Cobalt Magnets Market Size, Share, and Industry Trends Forecast 2026-2036
North America Samarium Cobalt Magnets Market Intelligence
The US Inflation Reduction Act is broadening demand for domestically sourced rare-earth magnets across defense and clean-energy supply chains. Bunting Magnetics leverages vertical integration in sintered magnet production to secure long-term aerospace contracts. Arnold Magnetic Technologies anchors its position through specialized high-temperature grades for satellite propulsion systems. Electron Energy Corporation differentiates via in-house powder metallurgy capabilities that reduce reliance on overseas samarium feedstock.
Samarium cobalt magnets are intermetallic compounds of samarium and cobalt, typically SmCo5 or Sm2Co17, manufactured through powder metallurgy and sintering to achieve maximum energy products of 16-32 MGOe and operating temperatures exceeding 300°C. These properties make them indispensable for aerospace actuators, missile guidance systems, and downhole drilling equipment where neodymium alternatives demagnetize. Sintered products command the largest share of value owing to their superior magnetic performance and established qualification pathways with defense primes. Aerospace applications are expanding fastest as hypersonic weapons programs and satellite constellation deployments accelerate procurement cycles for radiation-hardened magnetic assemblies.
The US Department of Defense drives demand through DFARS-compliant sourcing mandates and the Defense Production Act Title III program for critical minerals. Canada's PMRA and Health Canada regulate occupational exposure limits in magnet manufacturing facilities, while Mexico's environmental standards under SEMARNOT govern rare-earth processing waste streams. Stakeholders must monitor how Buy American content thresholds evolve under pending defense authorization amendments and whether domestic sintering capacity expands ahead of projected aerospace procurement waves.
Market Dynamics
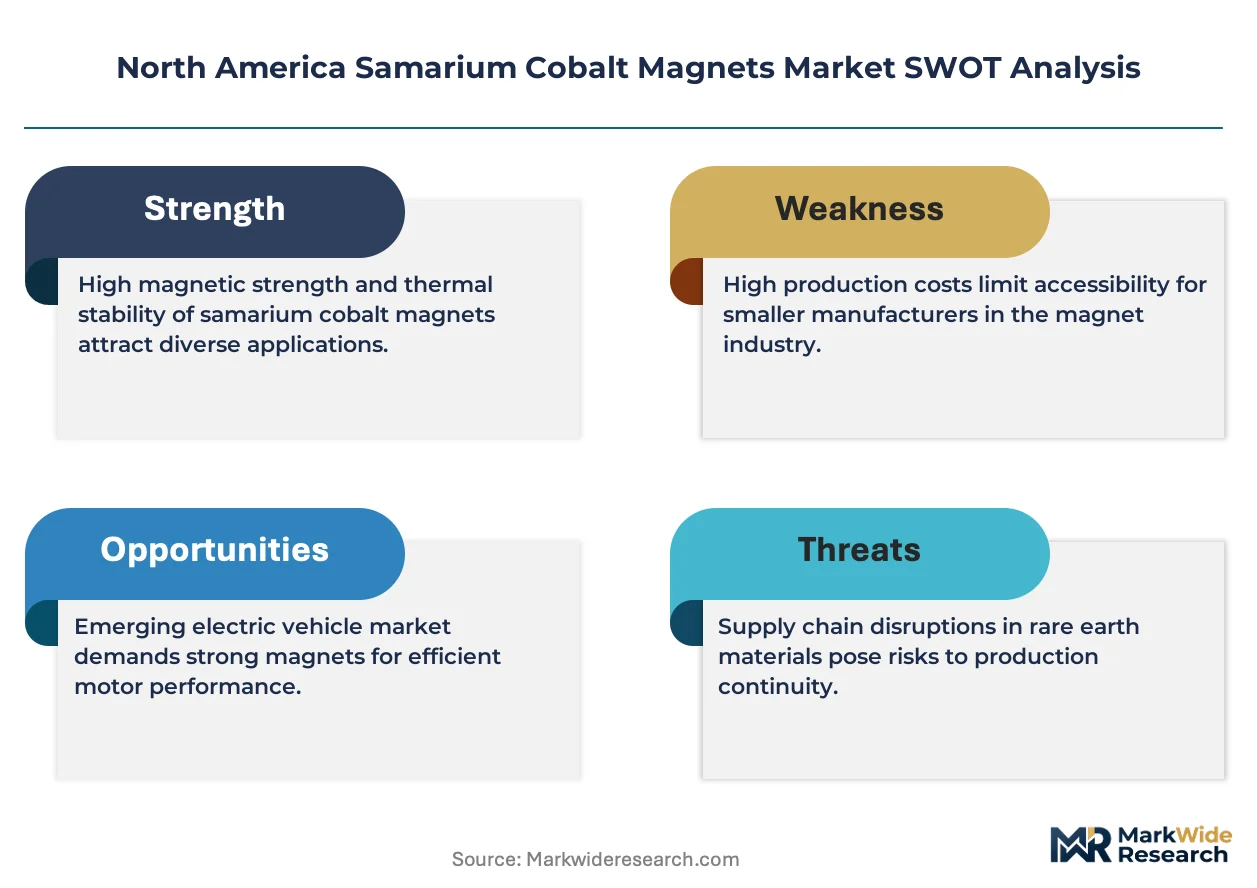
Defense procurement mandates under the US Defense Production Act Title III program are restructuring rare-earth magnet supply chains, compelling domestic sintering capacity expansion ahead of aerospace qualification cycles.
Growth Catalysts
- DFARS-compliant sourcing mandates:Pentagon acquisition rules now require domestic or allied-nation rare-earth processing, redirecting defense contractor magnet procurement toward North American suppliers.
- Hypersonic weapons programs:Next-generation missile guidance systems demand Sm2Co17 grades that withstand 300°C+ operating temperatures where neodymium alternatives fail.
- Southwestern US manufacturing clusters:SpaceX, Raytheon, and Northrop Grumman facilities in Arizona, New Mexico, and Texas are co-locating magnet qualification laboratories with sintering operations.
Market Restraints
- Samarium feedstock concentration:Over 80% of global samarium oxide refining occurs in China, creating single-source vulnerability for North American magnet manufacturers.
- Neodymium-iron-boron substitution pressure:NIB magnets offer 35-52 MGOe energy products at one-third the cobalt content cost, capturing cost-sensitive industrial motor applications.
- EPA hazardous waste rules:Powder metallurgy operations generate cobalt-containing particulates subject to RCRA Subtitle C disposal requirements, elevating compliance costs for sintering facilities.
Strategic Opportunities
- US Inflation Reduction Act tax credits:Clean energy manufacturing incentives extend to permanent magnet production for wind turbine generators and electric vehicle traction motors.
- Additive manufacturing convergence:Binder jet printing of SmCo powders enables near-net-shape magnet geometries for satellite miniaturization, reducing machining waste.
- Mexican maquiladora expansion:SEMARNOT environmental permits for rare-earth processing are attracting magnet assembly operations to Baja California aerospace corridors.
Industry Challenges
- Powder metallurgy talent scarcity:Specialized sintering technicians with aerospace NADCAP certification command premium wages, constraining production ramp rates.
- DoD qualification timelines:MIL-STD-981 magnet testing protocols require 18-24 months for new grade approval, freezing supplier switching during procurement cycles.
- Legacy ERP integration:Defense primes operate SAP environments that resist real-time magnet traceability data feeds from tier-two sintering suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Samarium Cobalt Magnets Market |
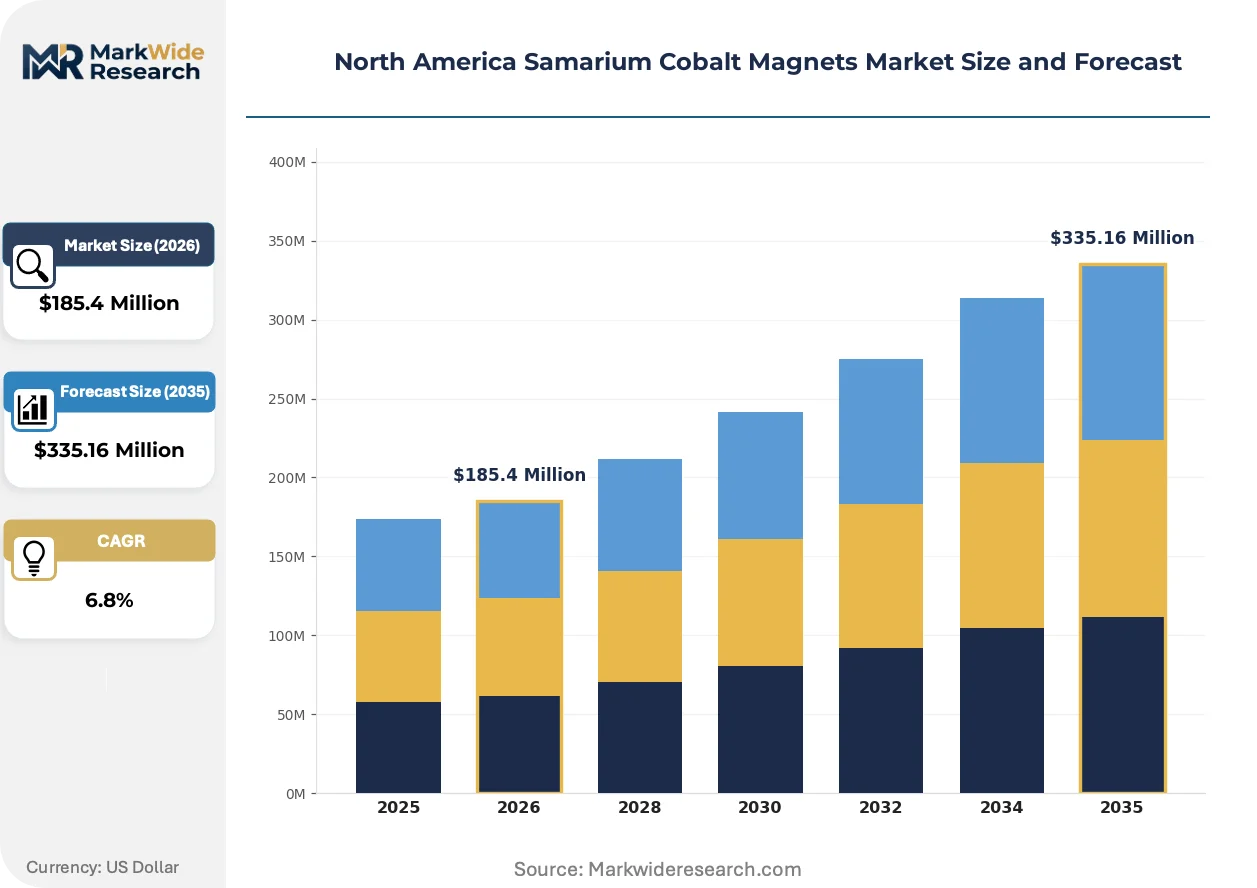
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $335.16 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isotropic, Anisotropic, Bonded, Sintered Application: Aerospace, Automotive, Robotics, Medical Devices End User: Industrial, Consumer Electronics, Defense, Telecommunications Technology: Permanent Magnets, Magnetic Sensors, Magnetic Assemblies, Electromagnetic Devices |
| Companies Covered | Bunting Magnetics, Magnetic Component Engineering, Arnold Magnetic Technologies, Dexter Magnetic Technologies, MASTER MAGNETICS, Adams Magnetic Products, Integrated Magnetics, Viona Magnetics, Electron Energy Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Samarium Cobalt Magnets Market Strategic Shifts & Innovations
Magnet manufacturing is pivoting toward radiation-hardened assemblies as satellite constellation deployments accelerate, while regulatory pressure on rare-earth supply chains intensifies qualification requirements for defense applications.
Hot isostatic pressing of Sm2Co17 compacts is automating density uniformity control in aerospace-grade magnet production. Lockheed Martin and Boeing satellite divisions are qualifying HIP-processed magnets for geostationary orbit propulsion systems. The technology is automating rejection-rate reduction in radiation-hardened magnetic assemblies, compressing supplier qualification cycles from 36 to 24 months.
The US Inflation Reduction Act domestic content bonuses are restructuring magnet procurement economics for clean-energy OEMs. Wind turbine and EV motor manufacturers must demonstrate 40% North American rare-earth processing to capture full tax credits. Offshore wind developers in the Atlantic corridor are accelerating supplier audits of sintering operations in Pennsylvania and Ohio to meet 2026 bonus phase-in deadlines.
Defense primes are consolidating magnet vendor lists from 12-15 qualified suppliers to 4-6 strategic partners with captive powder metallurgy capabilities. Raytheon Missiles & Defense and Northrop Grumman Space Systems are executing multi-year offtake agreements that embed quality engineers at sintering facilities. This concentration is most visible in the southwestern United States, where on-site technical collaboration is replacing arm's-length purchasing for hypersonic and satellite programs.
North America Samarium Cobalt Magnets Market Segmentation
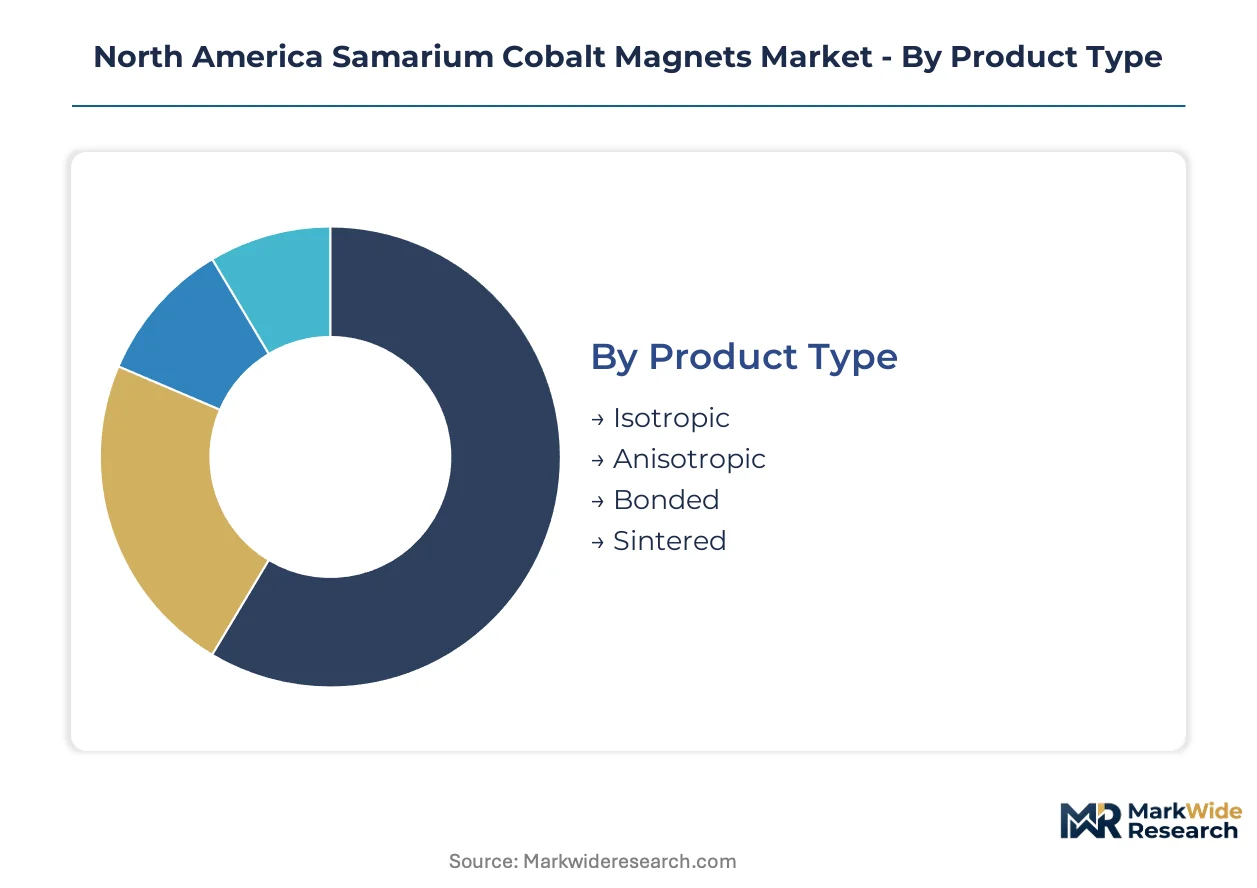
Samarium cobalt magnets fragment across performance grades and manufacturing methods that dictate thermal tolerance, energy density, and qualification pathways. Aerospace and defense procurement rules favor specific product types, while end-user concentration shapes regional sintering capacity investments.
Product Type:
Sintered magnets command premium pricing through superior magnetic performance, while bonded alternatives serve cost-sensitive applications where dimensional flexibility outweighs energy density requirements.
- Sintered:Powder metallurgy compaction achieves 26-32 MGOe energy products and 300°C+ operating temperatures. Pentagon hypersonic weapons programs in New Mexico and Texas mandate sintered Sm2Co17 grades for missile guidance systems where thermal stability is non-negotiable.
- Anisotropic:Magnetic field alignment during pressing yields directional flux properties critical for high-performance motors. Southwestern US satellite propulsion manufacturers in Arizona prioritize anisotropic grades for reaction wheel assemblies requiring precise torque control.
- Isotropic:Uniform magnetic properties suit simple geometries and cost-constrained industrial sensors.
- Bonded:Polymer-bonded powders enable complex shapes with 10-18 MGOe performance for medical device miniaturization.
Mature deployment sits with Sintered. Newer deployment is concentrated in Bonded.
Application:
Defense procurement timelines stretch 18-24 months for aerospace qualification, while automotive traction motor demand channels investment toward high-volume sintering automation.
- Aerospace:Radiation-hardened magnetic assemblies for geostationary orbit propulsion withstand 300°C operational extremes. Lockheed Martin satellite divisions in Colorado and California specify aerospace-grade SmCo for station-keeping thrusters where neodymium demagnetization risks mission failure.
- Defense:DFARS-compliant sourcing mandates redirect missile guidance magnet procurement toward domestic sintering operations. Raytheon Missiles & Defense facilities in Arizona execute multi-year offtake agreements embedding quality engineers at supplier plants.
- Automotive:Traction motor designers balance cobalt cost volatility against thermal performance requirements.
- Robotics:Precision actuators in surgical and industrial automation favor compact SmCo geometries.
- Medical Devices:MRI-compatible surgical tools and implantable sensors leverage corrosion-resistant SmCo properties.
Established procurement dominates Defense. Steepest expansion trajectory appears in Aerospace.
End User:
Defense primes consolidate vendor lists from 12-15 qualified suppliers to 4-6 strategic partners with captive powder metallurgy capabilities, concentrating purchasing power among sintering operations with NADCAP certification.
- Defense:Pentagon Title III critical minerals funding expands domestic rare-earth magnet supply chains. Northrop Grumman Space Systems in California co-locates magnet qualification laboratories with southwestern US sintering facilities to compress 36-month qualification cycles.
- Industrial:Downhole drilling equipment manufacturers in Texas specify SmCo for 200°C+ geothermal exploration environments where standard magnets fail.
- Telecommunications:Satellite constellation ground stations require temperature-stable microwave components.
- Consumer Electronics:Premium audio transducers and miniature motors represent niche volume.
Procurement concentration sits with Defense. Emerging demand is concentrating in Industrial.
Technology:
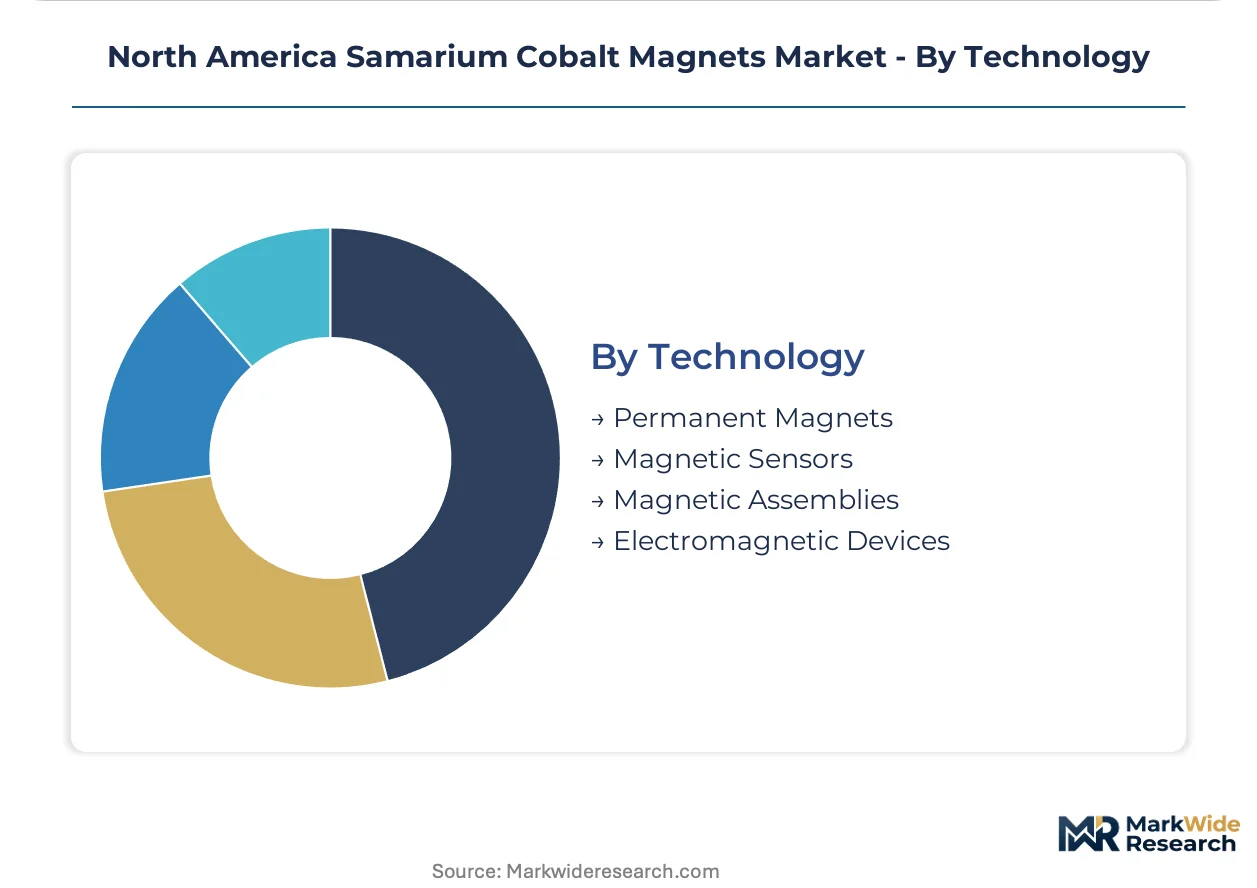
Permanent magnet architectures absorb 80%+ of samarium cobalt consumption, while magnetic sensor integration expands in satellite attitude determination systems requiring radiation tolerance.
- Permanent Magnets:Intermetallic SmCo5 and Sm2Co17 compounds deliver maximum energy products for high-temperature motor applications. SpaceX Starship Raptor engine actuators in Texas specify permanent magnet assemblies qualified to MIL-STD-981 protocols.
- Magnetic Assemblies:Pre-engineered rotor and stator subsystems reduce OEM integration burden for satellite manufacturers.
- Magnetic Sensors:Hall-effect and fluxgate devices leverage temperature-stable SmCo bias magnets.
- Electromagnetic Devices:Specialized couplings and clutches serve oilfield and aerospace auxiliary systems.
Volume concentration sits with Permanent Magnets. Technology migration is accelerating in Magnetic Assemblies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Albuquerque-Tucson-El Paso corridor anchors North American samarium cobalt magnet activity, with defense and space manufacturing clusters driving procurement concentration across the southwestern United States.
United States
Hypersonic weapons programs and satellite constellation deployments accelerate demand for Sm2Co17 grades. The Defense Production Act Title III program channels federal investment into domestic rare-earth processing infrastructure. Arizona, New Mexico, and Texas host co-located magnet qualification laboratories with sintering operations serving Raytheon and Northrop Grumman facilities.
Canada
Downhole drilling equipment manufacturers specify SmCo for geothermal exploration above 200°C. Health Canada and PMRA enforce occupational exposure limits in powder metallurgy facilities. Ontario's industrial corridor near Toronto concentrates magnet assembly operations for oilfield service companies exporting to US shale basins.
Mexico
SEMARNOT environmental permits attract rare-earth processing investment to Baja California aerospace corridors. Maquiladora operations near Tijuana assemble magnetic components for satellite ground systems. The northern border states deepen supplier relationships with southwestern US defense primes seeking tariff-advantaged production.
North America Samarium Cobalt Magnets Market Key Industry Players
The competitive structure tilts toward vertically integrated specialists with captive powder metallurgy capabilities. Three to four strategic partners dominate defense prime vendor lists, displacing fragmented tier-two suppliers. Archetypes separate into integrated sintering operations, specialized magnetic assemblers, and rare-earth feedstock processors. Capacity expansion and multi-year offtake agreements constitute the dominant competitive moves, with quality engineer embedment at supplier facilities replacing arm's-length purchasing.
Among US-based integrated producers, Bunting Magnetics, Arnold Magnetic Technologies, and Electron Energy Corporation exemplify the vertically integrated archetype. These companies occupy positions where in-house powder metallurgy capabilities reduce reliance on overseas samarium feedstock. Their geographic concentration in the southwestern United States aligns with defense and space manufacturing clusters. The competitive dynamic rewards operations with NADCAP certification and MIL-STD-981 qualification pathways, creating barriers for smaller magnetic assemblers lacking captive sintering capacity.
| Leading Market Players |
|---|
| Bunting Magnetics |
| Magnetic Component Engineering |
| Arnold Magnetic Technologies |
| Dexter Magnetic Technologies |
| MASTER MAGNETICS |
| Adams Magnetic Products |
| Integrated Magnetics |
| Viona Magnetics |
| Electron Energy Corporation |
| Others |
Cost & Logistics Intelligence
Defense prime consolidation of vendor lists from 12-15 suppliers to 4-6 strategic partners compels sintering operations to absorb qualification cost burdens upfront, compressing margins on initial contracts while securing multi-year pricing power through embedded quality engineer arrangements.
Pricing Analysis
Aerospace-grade Sm2Co17 magnets command value-based pricing anchored to mission-critical uptime guarantees for satellite propulsion systems where demagnetization risks mission failure. Three-tier pricing structure across aerospace-qualified, industrial-grade, and bonded alternatives separates NADCAP-certified sintered products from standard offerings. Pricing pressure stems from neodymium-iron-boron substitution in cost-sensitive industrial motor applications. Automotive traction motor designers exhibit highest price sensitivity; defense primes with DFARS mandates show lowest sensitivity due to thermal performance non-negotiability.
Supply Chain Analysis
Regional distribution centers in Arizona, New Mexico, and Texas operate hub-and-spoke patterns feeding southwestern US defense and space manufacturing clusters. Samarium oxide refining concentrates in China, with downstream magnet manufacturing anchored in the United States and Mexico. Raw material dependencies span samarium feedstock, cobalt metal, and specialized sintering equipment. Single-source vulnerability in Chinese rare-earth processing creates structural risk exposure. Distribution runs through direct supplier embedment at prime facilities, replacing traditional arm's-length procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive powder metallurgy capabilities determine qualification access and pricing power across defense procurement cycles.
For Market Incumbents: Deploy NADCAP certification expansion to lock out non-integrated magnetic assemblers from hypersonic weapons program qualification pipelines. Consolidate southwestern US sintering capacity through selective acquisition of tier-two operations lacking captive powder metallurgy. Neodymium substitution pressure in industrial segments threatens margin stability in non-aerospace grades. For New Entrants and Emerging Players: The gap between aerospace-premium and industrial-economy pricing creates entry space for Mexican maquiladora operations serving satellite ground system assembly with tariff-advantaged production. Target Baja California aerospace corridors where SEMARNOT environmental permits attract rare-earth processing investment. Pursue binder jet printing qualifications for near-net-shape SmCo geometries to bypass traditional sintering capital requirements. For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with in-house samarium feedstock processing ahead of Defense Production Act Title III funding disbursements. Five-to-ten year viability hinges on securing DFARS-compliant supply chain status before qualification cycle freezes. Monitor Buy American content threshold amendments as the inflection signal for domestic capacity valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Samarium Processing | In-house rare-earth oxide refining reduces Chinese supply exposure for Pentagon-compliant magnet production. |
| NADCAP Certification Investment | Aerospace prime vendor consolidation favors suppliers with embedded quality systems at sintering facilities. |
| Hot Isostatic Pressing Automation | Lockheed Martin satellite divisions qualify HIP-processed magnets for geostationary orbit propulsion systems. |
| Mexican Maquiladora Expansion | SEMARNOT permits in Baja California enable tariff-advantaged assembly for southwestern US defense corridors. |
| Additive Manufacturing Qualification | Binder jet printing of SmCo powders serves satellite miniaturization demands with reduced machining waste. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with powder metallurgy technicians, aerospace procurement officers, defense prime quality engineers, and rare-earth processing specialists. Secondary validation drew from EPA hazardous waste documentation, DFARS compliance databases, and SEC filings from magnet manufacturers. Bottom-up segment sizing triangulated against top-down rare-earth consumption estimates across the analysis window.
Granularity-level modeling operated at product type, application, and end-user dimensions, with additional disaggregation by NADCAP certification status and MIL-STD-981 qualification tier. CAGRs derived from regression analysis of historical procurement volumes against defense authorization trajectories and clean energy tax credit phase-in schedules. Forecast inputs incorporated hypersonic weapons program acceleration curves and satellite constellation deployment timelines.
Inputs from defense contractor procurement databases and rare-earth trade statistics were available through the study window; gaps in classified program budget allocations introduce uncertainty bands around aerospace segment projections. Forecasts reflect documented assumptions regarding Inflation Reduction Act bonus phase-in adherence and Defense Production Act funding continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Magnetostrictive Materials Market
Magnetic Materials
Copper Magnet Wire Market
Magnetic Materials
Iron Oxide Market
Magnetic Materials
Samarium Cobalt Magnets Market
Magnetic Materials
High Performance Magnet Market
Magnetic Materials
Magnetic Materials Market
Magnetic Materials
Amorphous Soft Magnetic Materials Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
Magnetorheological Fluid Market
Magnetic Materials
Magnetic Material Magnetization and Testing Equipment Market
Magnetic Materials
North America Ferrite Magnet Market
Magnetic Materials
Global Magnetic Beads Market
Magnetic Materials
Rare Earth Magnet Market
Magnetic Materials
Global Soft Magnetic Alloys Market
Magnetic Materials
Plastic Bonded Magnet Market
Magnetic Materials
Sintered Magnet Market