
 Neodymium Market | 2026-2036
Neodymium Market Size, Share, and Industry Trends Forecast 2026-2036
Neodymium Market Intelligence
Australian and North American capacity expansion is rewriting the established supply chain geography for neodymium and its associated oxides. Lynas Rare Earths leverages its integrated mine-to-magnet strategy to secure non-Chinese supply chains for global customers. In the United States, MP Materials operates the Mountain Pass facility, anchoring domestic production of critical rare earth elements. China Northern Rare Earth Group maintains significant scale advantages through its vast domestic processing infrastructure and state support.
Neodymium is a rare earth metal, atomic number 60, prized for its use in creating the strongest type of permanent magnets. These magnets, typically a Nd2Fe14B alloy, provide exceptionally high magnetic field strength relative to their mass. Within product types, neodymium magnets command the largest market share due to their indispensability in high-efficiency motors. The automotive and renewable energy end-user segments represent the fastest-growing areas, driven by electric vehicle and wind turbine applications.
Mining and processing operations are governed by stringent environmental standards set by bodies like the US EPA and China's MEE. Trade policies and critical minerals initiatives, such as the EU's Critical Raw Materials Act and Japan's Economic Security Promotion Act, directly influence sourcing strategies. These regulations shape investment decisions and the development of alternative supply routes. Navigating the geopolitical landscape of rare earth supply chains remains the central strategic challenge for downstream consumers.
Market Dynamics
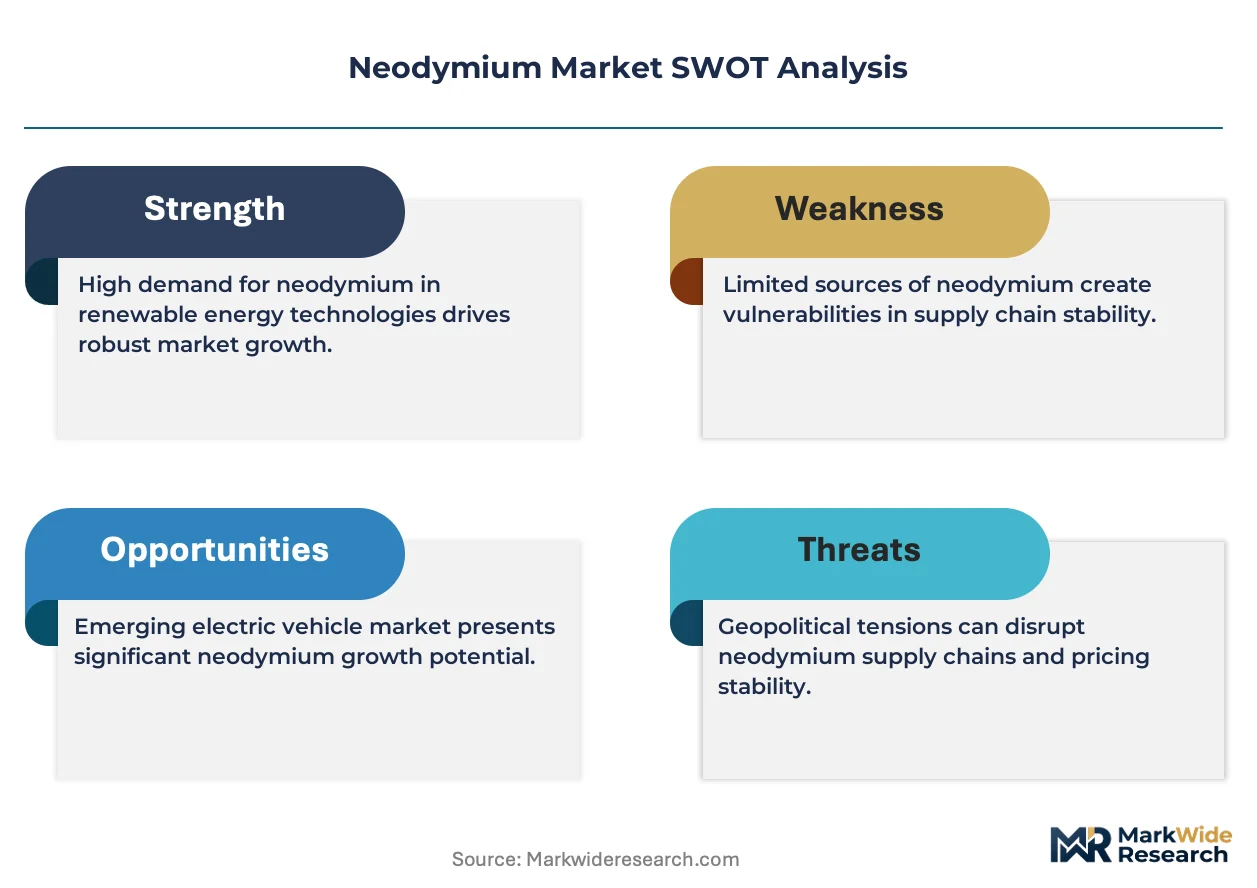
The market's central dynamic is the geopolitical and commercial tension between highly concentrated processing capacity in China and escalating demand from strategic industries. This supply-demand imbalance is intensified by global decarbonization policies mandating electric vehicles and wind power, creating structural price volatility and supply security concerns for downstream users.
Growth Catalysts
- EU Green Deal:Mandates for renewable energy directly increase the need for neodymium magnets in the gearboxes of large-scale offshore wind turbines.
- Electric Vehicle Motors:The automotive industry's global transition to electric vehicles depends on NdFeB magnets to build high-efficiency, high-torque powertrain motors.
- Supply Chain Security Policies:National initiatives, such as the US Inflation Reduction Act, provide financial incentives for developing non-Chinese rare earth supply chains.
Market Restraints
- Geographic Concentration:Overwhelming reliance on Chinese processing infrastructure creates significant supply chain risk and price volatility for global consumers.
- Environmental Compliance Costs:Stringent standards from bodies like the US EPA for mining and processing increase project costs and development timelines for new entrants.
- Substitution Research:Persistent R&D into ferrite or other non-rare earth magnets poses a long-term threat, particularly in price-sensitive applications.
Strategic Opportunities
- Secondary Sourcing:Developing urban mining and advanced recycling technologies to recover neodymium from end-of-life electronics and EV motors creates a circular supply.
- Emerging Applications:Use in high-performance robotics, drones, and factory automation systems presents a new vector for consumption beyond established end-user segments.
- New Production Geographies:Exploration and development of rare earth deposits in Australia, Canada, and parts of Africa offer diversification away from traditional sources.
Industry Challenges
- Capital Intensity:The immense upfront capital investment required to construct new mines and sophisticated solvent extraction processing plants is a major barrier to entry.
- Specialized Talent Scarcity:A global shortage of metallurgists and chemical engineers with expertise in complex rare earth separation presents an operational bottleneck for new projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neodymium Market |
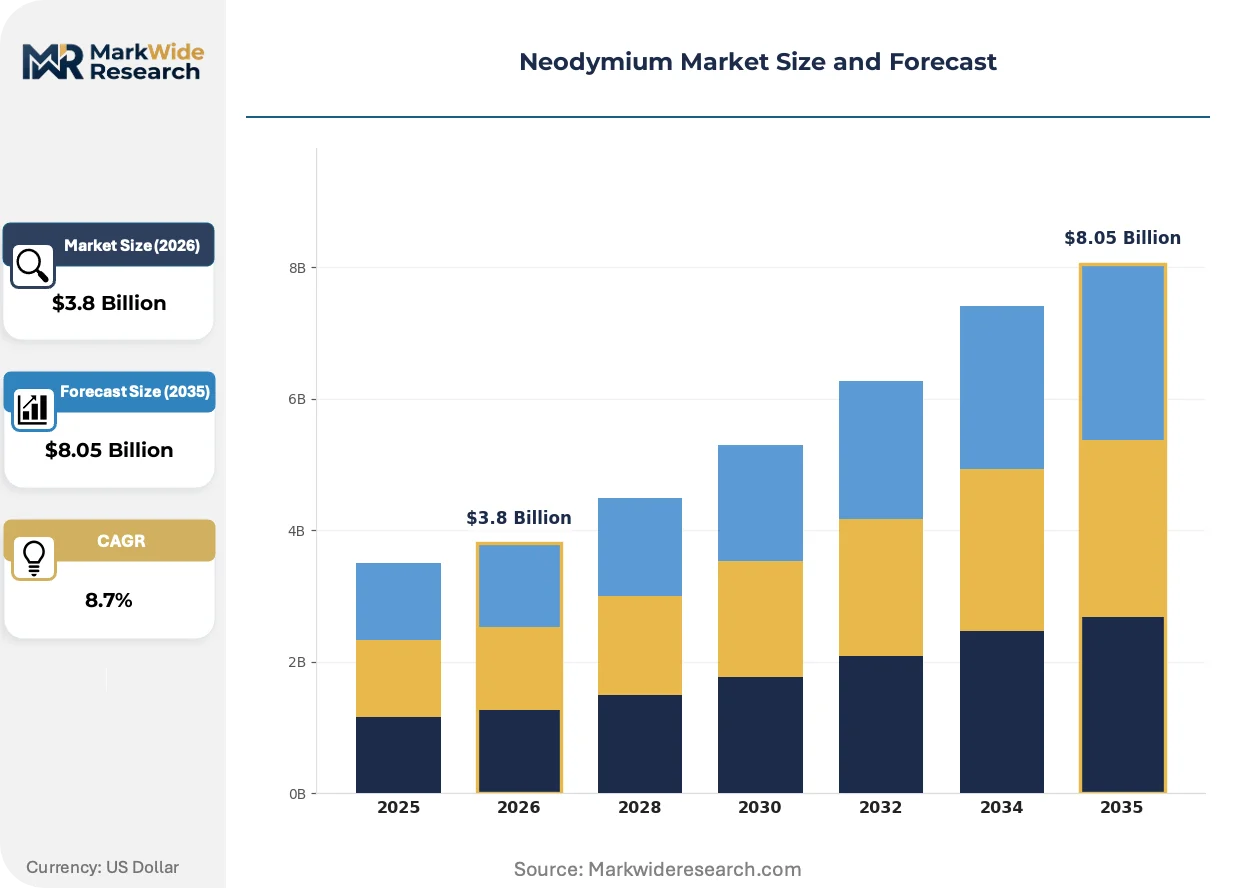
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neodymium Magnets, Neodymium Oxide, Neodymium Fluoride, Neodymium Metal Application: Electric Vehicles, Wind Turbines, Electronics, Healthcare Devices End User: Aerospace, Automotive, Telecommunications, Renewable Energy Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Shenghe Resources Holding, MP Materials, China Northern Rare Earth Group, Neo Performance Materials, Iluka Resources Limited, China Rare Earth Resources and Technology, Lynas Rare Earths, Arafura Rare Earths, Qiandong Rare Earth Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neodymium Market Strategic Shifts & Innovations
Market evolution is defined by a dual focus on technological innovation to mitigate material dependence and geopolitical maneuvering to secure resilient supply chains for critical applications. These forces are compelling a re-evaluation of both material science and procurement strategy across the value chain.
Material simulation software provides a platform for designing motors and magnets with optimized or reduced neodymium content. Automotive and aerospace engineers are adopting these tools to accelerate design validation before creating physical prototypes. This software-first approach is virtualizing aspects of materials science, compressing R&D timelines for developing magnets with lower rare earth dependency.
The European Union's Critical Raw Materials Act establishes targets for domestic processing and recycling of materials like neodymium. This policy directly pressures downstream industries to diversify sourcing and invest in European-based supply chain capabilities. Automotive manufacturers are the most affected segment, now actively pursuing offtake agreements with producers outside of Asia to ensure compliance.
Large-volume consumers are moving away from transactional spot-market buys toward long-term, direct offtake agreements with producers. This behavioral change is disintermediating traditional distributors for strategic accounts in the electric vehicle and wind turbine sectors. The trend is most pronounced in North America and Europe, where OEMs seek to de-risk multi-year production plans by securing future material inputs.
Neodymium Market Segmentation
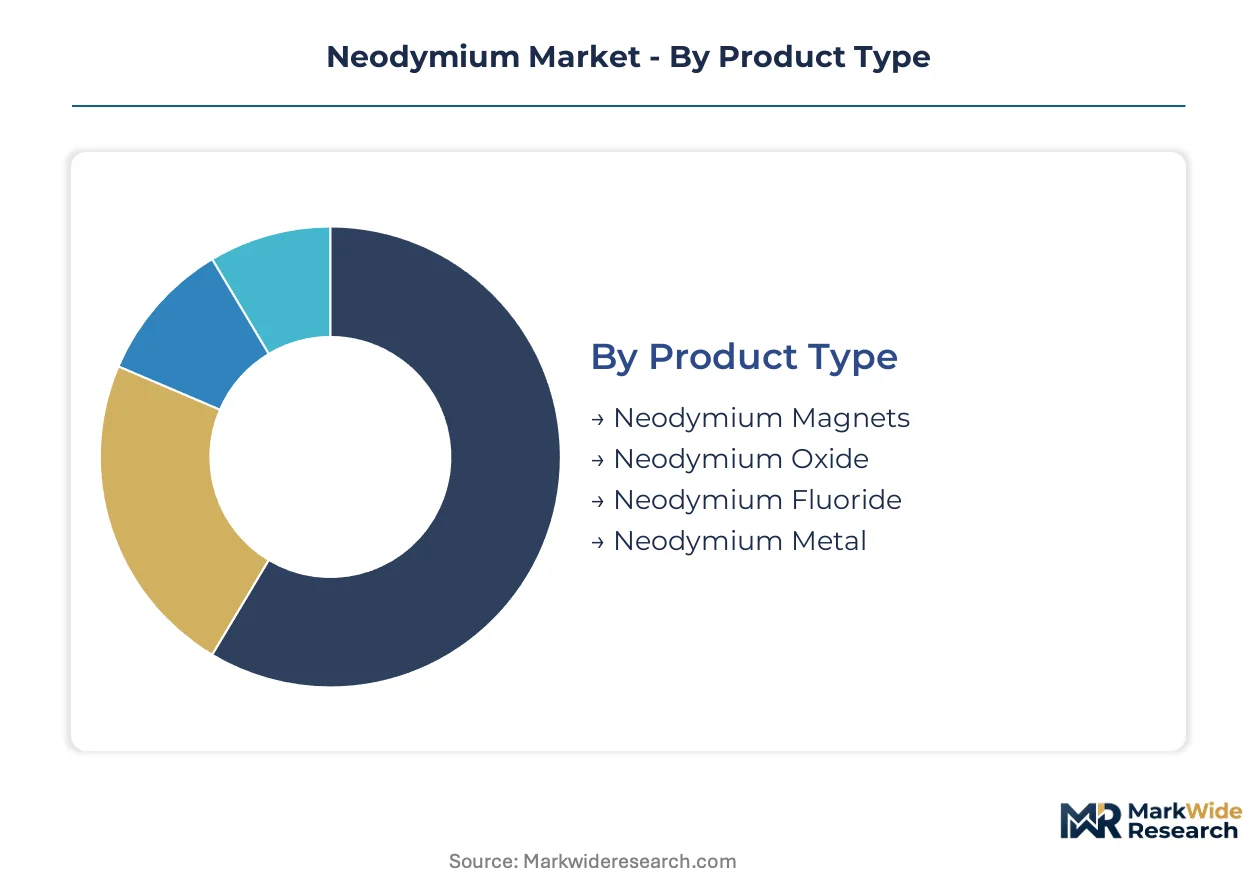
The Neodymium Market segmentation provides a granular view of its diverse product forms, critical applications, and end-user industries. Understanding these segments clarifies the value chain dynamics and strategic procurement decisions for this essential rare earth element. This detailed breakdown highlights areas of significant demand and supply chain emphasis.
Product Type:
The neodymium market's product type segmentation highlights the diverse forms of the element utilized across its applications, from raw materials to finished magnetic components.
- Neodymium Magnets:These permanent magnets, typically Nd2Fe14B alloy, offer exceptionally high magnetic field strength. Demand concentrates in electric vehicle motors, propelled by the global transition to high-efficiency powertrains.
- Neodymium Oxide:This refined rare earth compound serves as a critical intermediate product, often purified to high percentages. Demand concentrates in magnet manufacturing facilities, particularly in China's processing hubs for integrated supply chains.
- Neodymium Fluoride:Specialized applications include use in optical fibers and as a fluxing agent in various metallurgical processes.
- Neodymium Metal:The purified metallic form is primarily converted into neodymium-iron-boron alloys for permanent magnet production.
The dominant share belongs to Neodymium Magnets, while Neodymium Oxide is closing the gap fastest.
Application:
Different applications drive demand for neodymium, reflecting distinct industrial requirements and the performance needs of specific product categories.
- Electric Vehicles:These applications require NdFeB magnets for high-efficiency, high-torque powertrain motors. Demand concentrates in major automotive manufacturing regions, propelled by global decarbonization policies.
- Wind Turbines:Large NdFeB magnets are indispensable in direct-drive and geared generators for wind power. Demand concentrates in offshore wind farm development, especially across the EU, driven by renewable energy mandates.
- Electronics:Neodymium finds use in hard disk drives, high-fidelity headphones, and compact smartphone speakers.
- Healthcare Devices:This segment incorporates neodymium in MRI machines and specialized medical diagnostic instruments.
Electric Vehicles and Wind Turbines collectively drive significant expansion in neodymium consumption.
End User:
End-user industries for neodymium vary by their maturity and investment cycles in magnet-reliant technologies, dictating procurement patterns.
- Automotive:This sector integrates neodymium magnets into electric vehicle powertrains and auxiliary systems. Demand concentrates in regions with aggressive EV adoption targets, such as China and Germany.
- Renewable Energy:This industry employs neodymium in large-scale wind turbine generators for electricity production. Demand concentrates in countries investing heavily in green infrastructure, including the United States and Denmark.
- Aerospace:Neodymium magnets are utilized in actuators, sensors, and specialized motors for advanced aircraft systems.
- Telecommunications:This segment incorporates neodymium in fiber optic components and high-frequency communication devices.
The Automotive and Renewable Energy sectors collectively define the strategic importance of neodymium in global industrial transitions.
Distribution Channel:
The distribution channels for neodymium reflect varied procurement strategies and supply chain structures across the market.
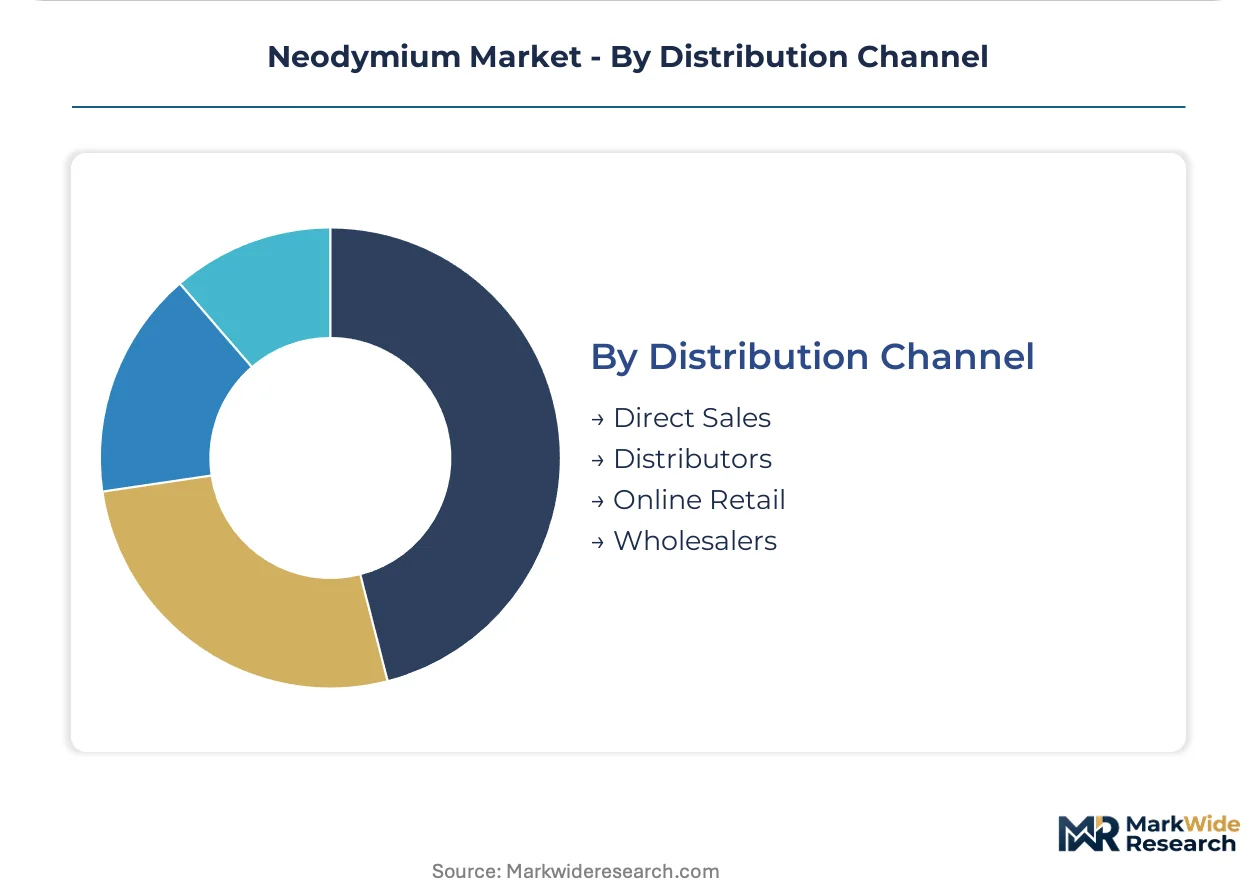
- Direct Sales:Involves direct contracts between producers and large-volume consumers, often major OEMs. Procurement is shifting towards long-term offtake agreements, particularly for strategic supply security.
- Distributors:These intermediaries manage inventory and logistics for smaller or diverse industrial customers. Supply chain security policies influence distributors to diversify sourcing away from single-country reliance.
- Online Retail:This channel caters to niche applications and smaller-scale buyers requiring specific magnet sizes or forms.
- Wholesalers:They purchase large quantities from producers and resell to industrial buyers or smaller distributors.
Direct Sales channels are gaining prominence as strategic customers seek secure, long-term supply arrangements with producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Major global shipping ports facilitate the intricate movement of neodymium raw materials and finished magnets across continents. This logistical infrastructure underwrites the market's global supply chain dynamics, connecting diverse mining operations to specialized processing hubs. End-user industries depend on these efficient routes for critical material inputs.
China
China's vast domestic processing infrastructure drives global neodymium supply, fueling its electric vehicle and wind turbine manufacturing sectors. The nation's dual carbon goals actively stimulate demand for high-performance magnets in green technologies. Baotou, a major industrial cluster in Inner Mongolia, serves as a primary hub for rare earth mining and separation operations.
United States
The United States' automotive industry increasingly demands neodymium magnets for its expanding electric vehicle production. The US Inflation Reduction Act provides financial incentives for developing non-Chinese rare earth supply chains. California's Mountain Pass facility anchors domestic production, reducing reliance on external processing capacity.
Germany
Germany's robust automotive sector requires significant neodymium for its high-efficiency electric vehicle powertrains. The EU Green Deal mandates for renewable energy also drive demand for magnets in wind turbine generators. Manufacturing centers in Bavaria focus on advanced magnet applications and motor design.
Australia
Australia's rich rare earth deposits serve as a crucial source for primary neodymium raw materials. The nation's critical minerals initiatives support the expansion of mining and initial processing capabilities. Western Australia, home to Lynas Rare Earths, develops integrated mine-to-refinement pathways for global customers.
Japan
Japan's advanced electronics and automotive industries sustain consistent demand for neodymium magnets in high-performance applications. The Economic Security Promotion Act encourages diversification of critical raw material sourcing. Industrial regions around Tokyo concentrate on magnet manufacturing and advanced materials research.
Neodymium Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the neodymium market. The industry exhibits a tiered structure, with upstream raw material extraction and midstream processing showing concentration, while downstream magnet manufacturing is more fragmented. Strategic archetypes include integrated rare earth miners, specialized processing firms, and advanced magnet producers. Capacity expansion and strategic partnerships, particularly long-term offtake agreements, represent dominant competitive moves.
At the scale-driven end, China Northern Rare Earth Group, a major Chinese entity, exemplifies the state-supported enterprises dominating domestic processing capacity. Lynas Rare Earths, an Australian-based company, represents the integrated non-Chinese supply chain players focused on securing alternative sources. MP Materials, a US-based corporation, anchors domestic production of critical rare earth elements, highlighting efforts to build resilient national supply chains. These entities collectively shape the global supply dynamics of neodymium.
| Leading Market Players |
|---|
| Shenghe Resources Holding |
| MP Materials |
| China Northern Rare Earth Group |
| Neo Performance Materials |
| Iluka Resources Limited |
| China Rare Earth Resources and Technology |
| Lynas Rare Earths |
| Arafura Rare Earths |
| Qiandong Rare Earth Group |
| Others |
Cost & Logistics Intelligence
Baotou's vast processing infrastructure dictates global neodymium supply, directly influencing downstream pricing power for magnet manufacturers and end-users. Geopolitical tensions and strategic mineral policies further complicate the market's pricing and supply dynamics. This interplay creates structural price volatility, particularly for non-Chinese customers.
Pricing Analysis
Contract-based long-term offtake agreements define pricing for major strategic buyers in the neodymium market. Price differentiation stems from the purity of neodymium oxide grades and the volume scale of procurement. Pricing pressure is intensifying due to escalating demand from electric vehicle and wind turbine sectors, coupled with supply chain security policies. Automotive and renewable energy sectors exhibit lower price sensitivity compared to the electronics segment, which often seeks cost-optimized solutions.
Supply Chain Analysis
Geopolitical tension between concentrated processing in China and escalating demand from strategic industries dominates the neodymium supply chain. Geographic supply concentration centers on China for processing, while Australia and the United States serve as crucial raw material sources. The market relies heavily on neodymium oxide and NdFeB magnets as key component dependencies. Single-source vulnerability from China's processing dominance remains the primary structural risk. Direct sales channels are gaining prominence for large-volume OEMs, while distributors cater to smaller industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Neodymium Market presents a defensive-moat story, primarily justified by the high capital intensity and complex regulatory entrenchment required for new project development.
For Market Incumbents: Entrench existing market positions by accelerating capacity expansion in non-Chinese geographies, particularly in North America and Australia. Secure long-term offtake agreements with major automotive and renewable energy OEMs to de-risk future demand against geopolitical supply disruptions. Invest in advanced processing technologies to improve efficiency and reduce environmental compliance costs, countering potential substitution research.
For New Entrants and Emerging Players: Urban mining and advanced recycling technologies represent the most penetrable entry point for new participants. Explore and develop rare earth deposits in emerging geographies like Canada and parts of Africa, diversifying away from traditional sources. Focus on developing circular supply chain solutions and specialized magnet applications for high-performance robotics and drones as a go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated rare earth miners with established non-Chinese processing capabilities for long-term viability. These entities provide essential materials for the global decarbonization transition, ensuring sustained demand over the next decade. The commissioning and successful ramp-up of new non-Chinese processing plants will serve as a critical signal to watch for inflection points.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand non-Chinese processing capacity | Reduces single-country dependency and enhances global supply resilience. |
| Secure long-term offtake agreements | De-risks future material supply for major electric vehicle manufacturers. |
| Invest in advanced recycling technologies | Creates a circular economy for neodymium from end-of-life products. |
| Diversify raw material sourcing geographies | Mitigates geopolitical risks associated with concentrated rare earth deposits. |
| Integrate mine-to-magnet value chain | Ensures greater control over quality, cost, and supply security for customers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory documents, industry reports, and company filings to ensure data accuracy. Primary interviews included metallurgists, EV powertrain engineers, wind turbine manufacturers, and rare earth traders. Secondary data sources comprised US EPA reports, China MEE guidelines, EU Critical Raw Materials Act documents, and company annual filings, with bottom-up market sizing triangulated against top-down validation.
Forecast inputs considered volume and value projections across the analysis window, modeling segmentation dimensions including product type, application, end-user, distribution channel, and regional production clusters. Compound annual growth rates were derived from historical growth patterns and projected policy impacts, with industry-specific inputs such as EV production targets and wind turbine deployment rates informing the model.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or energy transition investment would shift the trajectory. Forecasts reflect assumptions documented through the modeling period. Geopolitical trade tensions and technological breakthroughs in substitution represent key risk factors that could revise projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
US Copper Scrap Market
Metals
Carbon Steel Market
Metals
Chrome Metal Powder Market
Metals
Copper Clad Aluminum Wire Market
Metals
Stainless Steel Sheet Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
Armour Steel Plate Market
Metals
Silver Powder and Flakes Market
Metals
Ultrafine Tungsten Wire for Medical Applications Market
Metals
Grain Oriented Electrical Steel Market
Metals
Aluminum Ingots Market
Metals
High Purity Base Metals Market
Metals
GCC Metal Forging Market
Metals
Bismuth Oxide Market
Metals
High-End Copper Foil Market
Metals
United States Aluminum Extrusion Market